
 North America Smart Airport Market | 2026-2036
North America Smart Airport Market Size, Share, and Industry Trends Forecast 2026-2036
North America Smart Airport Market Analytics
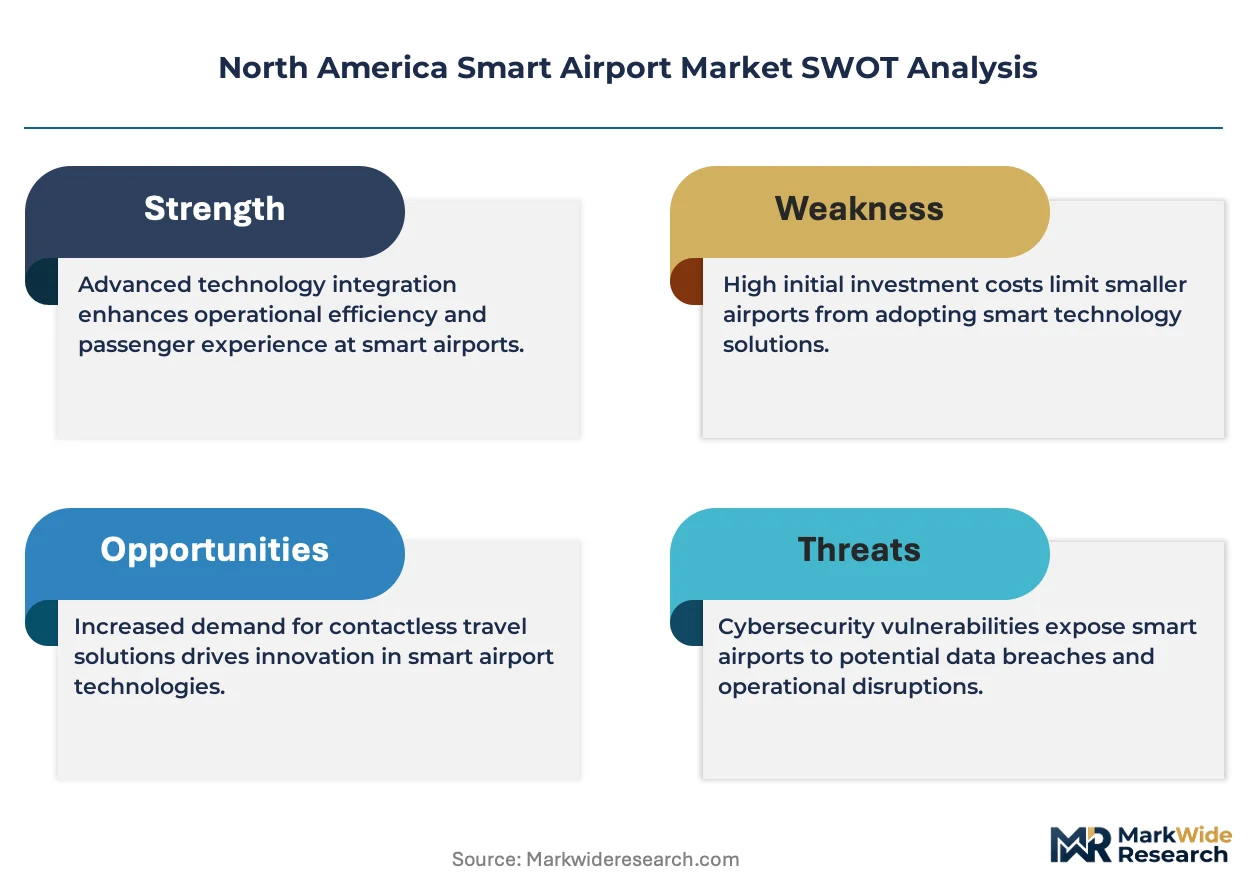
FAA Part 139 certification upgrades with embedded cybersecurity Annexes is reorganizing the vendor landscape for airfield systems integration. Honeywell International Inc. sustains dominance in building management systems across major US hub airports through captive supply of fire safety and HVAC controls. Siemens AG competes aggressively on digital twin platforms for baggage handling, leveraging its Munich-engineered simulation software adapted for North American apron layouts. Thales Group anchors its position in passenger analytics through biometric gate deployments at Canadian Tier-1 airports.
A smart airport denotes a digitally instrumented aviation facility where IoT sensor networks, biometric identity platforms, and AI analytics engines converge to automate passenger processing, optimize gate utilization, and predict equipment failures before operational disruption. These systems typically operate on sub-100 millisecond latency requirements for real-time baggage tracking and facial recognition boarding. IoT Solutions and Biometrics within the Technology dimension capture the steepest procurement curves, as airports replace legacy RFID with computer-vision baggage handling and touchless passenger corridors. Airport Operations and Passenger Experience applications now absorb the majority of system integration budgets, while Security Management retains mature, replacement-driven spending patterns with thinner margins.
The FAA's NextGen Advisory Committee and Transport Canada's Digital Aviation Strategy jointly enforce interoperability standards that determine which vendors qualify for federal infrastructure grants. FAA cybersecurity directives issued under 49 U.S.C. § 44701 and Canada's Transport Act amendments impose continuous monitoring obligations on connected airfield equipment, effectively filtering out non-compliant hardware suppliers. Stakeholders must track how pending NIST framework updates for critical infrastructure ripple into airport procurement specifications before committing to multi-year platform investments.
Market Dynamics
FAA cybersecurity mandates under 49 U.S.C. § 44701 and Transport Canada's equivalent airfield digitization rules are compressing vendor qualification timelines while filtering out non-compliant hardware suppliers from federal infrastructure grants.
Growth Catalysts
- NextGen Modernization Mandate:FAA directives require biometric boarding infrastructure and AI-driven baggage tracking at Category X airports, accelerating procurement cycles for computer-vision systems.
- Sun Belt Terminal Expansion:Concurrent digitization programs at Dallas-Fort Worth, Atlanta, and Phoenix airports concentrate demand for IoT sensor networks and gate optimization platforms.
- Transport Canada Digital Aviation Framework:Federal interoperability standards for connected airfield equipment unlock infrastructure funding for vendors meeting continuous monitoring obligations.
Market Restraints
- Cybersecurity Compliance Burden:NIST framework updates for critical infrastructure impose recurring certification costs on legacy system integrators, raising total cost of ownership for mid-tier airports.
- Semiconductor Supply Concentration:IoT sensor and edge computing hardware depends on concentrated Asian foundry capacity, exposing North American deployments to lead-time volatility.
- Legacy System Interoperability:Existing RFID baggage infrastructure lacks API compatibility with computer-vision platforms, forcing expensive middleware development or full replacement.
Strategic Opportunities
- Canadian Tier-2 Airport Modernization:Vancouver, Calgary, and Montreal secondary terminals remain underpenetrated for biometric passenger corridors, offering first-mover positioning for integrated platform vendors.
- Digital Twin Convergence:Munich-engineered simulation software adapted for North American apron layouts enables predictive maintenance contracts that bundle hardware with recurring analytics revenue.
- Outcome-Based Service Contracts:US hub airports are piloting availability-based pricing for baggage handling systems, shifting vendor compensation from capital expenditure to operational performance metrics.
Industry Challenges
- Airfield Systems Integration Talent Gap:FAA Part 139 certification upgrades with embedded cybersecurity annexes require specialized expertise in both aviation safety and industrial IoT security, constraining deployment velocity.
- Sub-100 Millisecond Latency Engineering:Real-time facial recognition boarding and baggage tracking demand edge computing architectures that few systems integrators can architect at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Smart Airport Market |
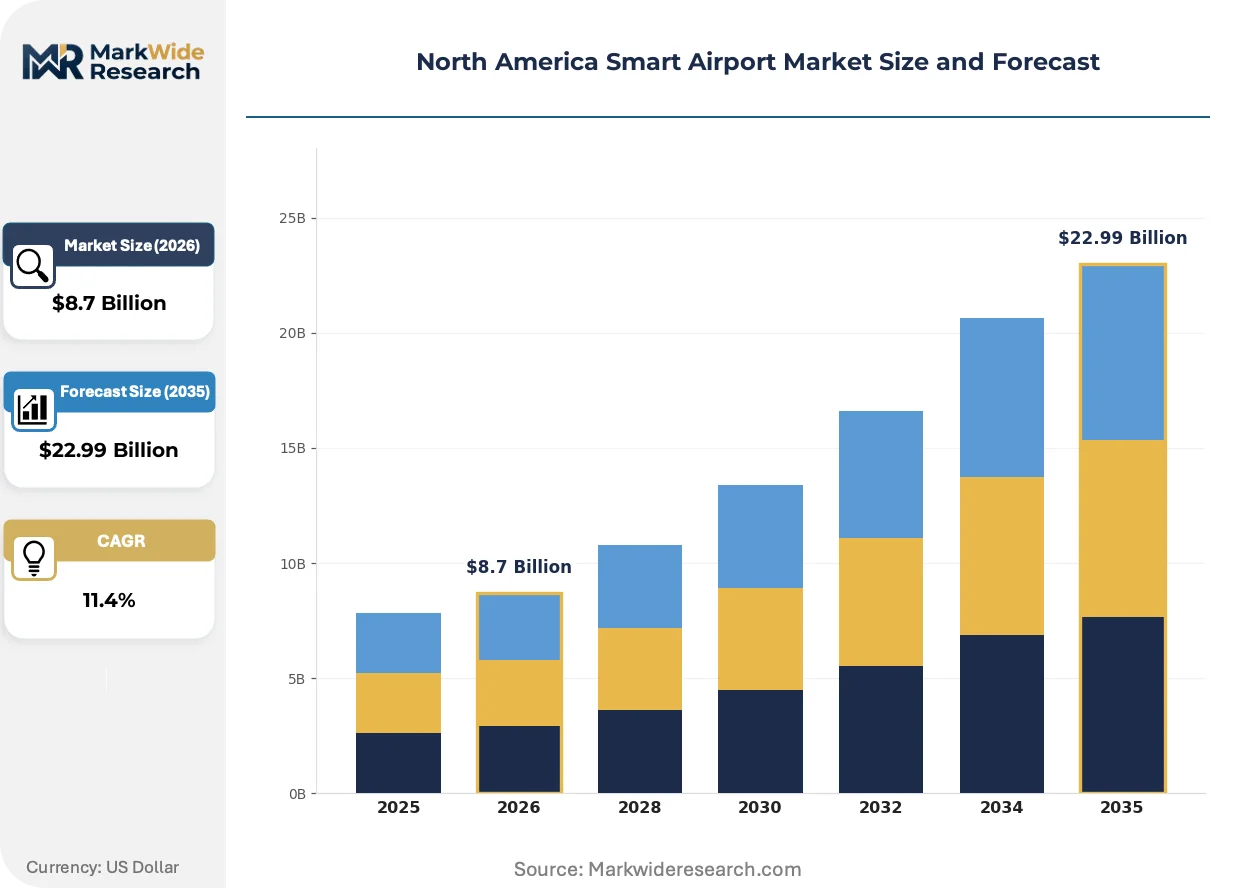
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT Solutions, Biometrics, AI Analytics, Cloud Computing Application: Security Management, Baggage Tracking, Passenger Experience, Airport Operations End User: Airlines, Airport Authorities, Ground Handling, Passengers Service Type: Consulting Services, System Integration, Support Services, Managed Services |
| Companies Covered | Cisco Systems Inc., Honeywell International Inc., IBM Corporation, Siemens AG, Thales Group, Amadeus IT Group, Raytheon Technologies Corporation, SITA, Sabre Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Smart Airport Market Evolving Landscape
Computer-vision baggage handling is fragmenting established technology hierarchies while regulatory pressure compresses procurement timelines and buyer behavior shifts toward performance-based contracting.
Computer-vision baggage handling platforms replace legacy RFID tracking with camera-based object recognition and neural network classification. US Category X airports and Canadian Tier-1 facilities are deploying these systems at accelerated pace due to touchless passenger corridor mandates. The technology is fragmenting the incumbent systems integration market by enabling specialized AI vendors to bypass traditional baggage handling OEMs through direct airport contracts.
Transport Canada's Digital Aviation Strategy amendments impose continuous monitoring obligations on connected airfield equipment, mirroring FAA cybersecurity directives under 49 U.S.C. § 44701. These rules disqualify hardware lacking real-time telemetry and automated patch management from federal infrastructure grants. Biometric gate deployments and IoT sensor networks face the steepest compliance burdens, forcing vendors to reengineer product architectures for auditability.
US hub airports are unbundling after-sales service from capital equipment purchases, replacing traditional maintenance contracts with availability-based performance agreements. This restructuring compresses switching cycles and transfers operational risk to vendors. Dallas-Fort Worth and Phoenix have piloted these models for baggage handling systems, with procurement teams evaluating total cost of ownership over seven-year horizons rather than upfront capital expenditure.
North America Smart Airport Market Segmentation
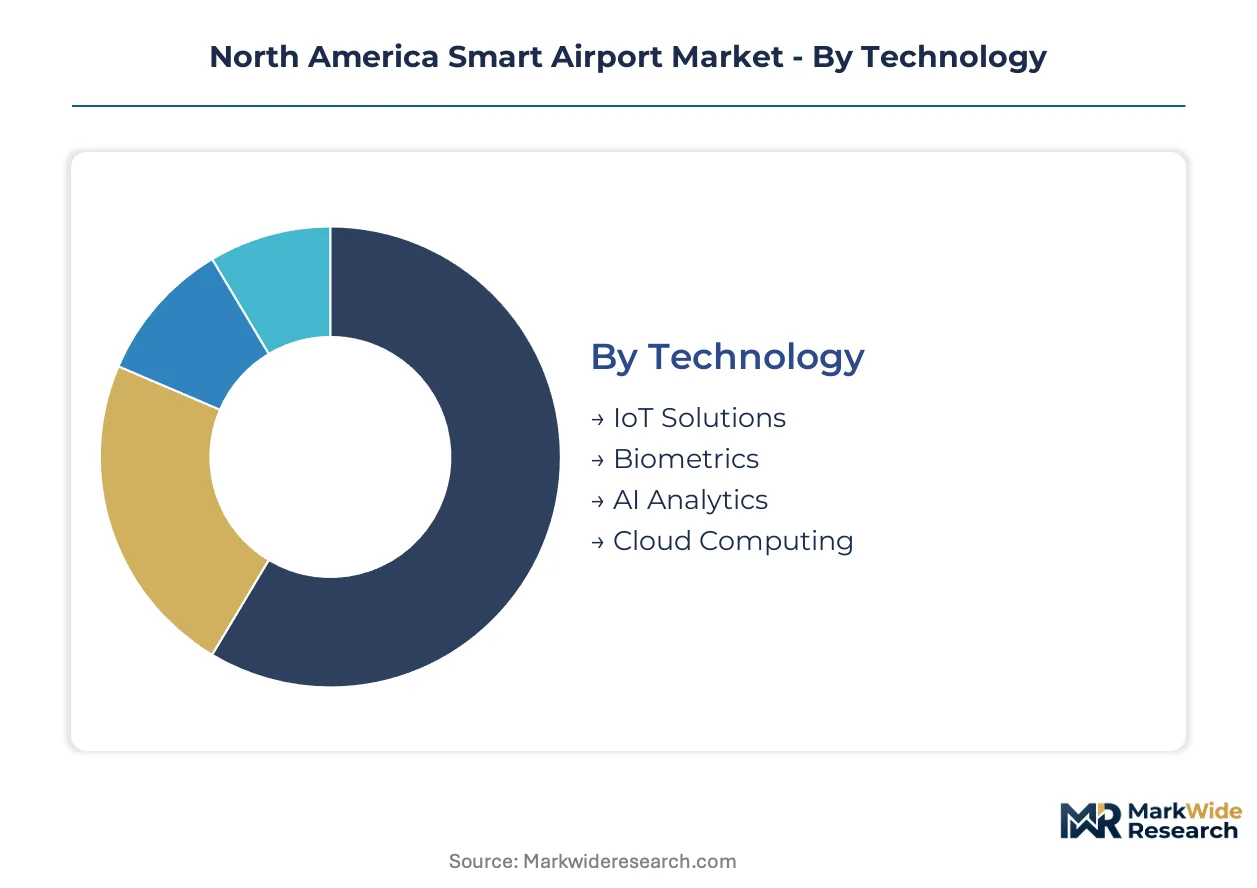
Smart airport procurement flows through distinct technology and service channels, each shaped by FAA certification requirements and Transport Canada interoperability mandates. Understanding how segments map to federal funding eligibility and vendor qualification pathways reveals where procurement budgets concentrate.
Technology:
IoT sensor networks and biometric platforms move through systems integrators holding FAA Part 139 cybersecurity annexes, while AI analytics and cloud infrastructure increasingly route through direct vendor-airport contracts.
- IoT Solutions:Distributed sensor networks for gate utilization, environmental monitoring, and equipment health tracking operate on sub-100 millisecond latency architectures. Demand clusters at Dallas-Fort Worth, Atlanta, and Phoenix terminals where concurrent digitization programs require unified sensor deployments for baggage handling and passenger flow optimization.
- Biometrics:Facial recognition boarding gates and touchless identity verification platforms integrate with existing security infrastructure. Canadian Tier-1 airports and US Category X facilities drive procurement as Transport Canada's Digital Aviation Strategy and FAA NextGen mandates compress deployment timelines.
- AI Analytics:Predictive maintenance engines and passenger flow optimization algorithms process telemetry from connected airfield equipment.
- Cloud Computing:Edge-to-cloud data pipelines enable centralized monitoring of distributed airport systems.
By volume, IoT Solutions leads technology procurement. By growth pace, Biometrics is expanding most quickly.
Application:
Airport Operations and Passenger Experience applications absorb the majority of integration budgets, while Security Management retains mature replacement-driven spending with thinner margins.
- Airport Operations:Gate optimization platforms, apron management systems, and predictive maintenance for ground support equipment automate resource allocation. Sun Belt corridor airports concentrate demand as Dallas-Fort Worth and Phoenix run concurrent terminal digitization programs requiring unified operational command centers.
- Passenger Experience:Touchless corridors, wayfinding systems, and personalized retail platforms reduce processing friction. US hub airports and Canadian Tier-1 facilities prioritize these investments as biometric boarding mandates reshape terminal design specifications.
- Security Management:Perimeter surveillance, access control, and threat detection systems operate on established procurement cycles.
- Baggage Tracking:Computer-vision and RFID-integrated baggage handling replaces legacy tracking infrastructure.
Airport Operations captures the largest share of current budgets. Passenger Experience is climbing the fastest as touchless mandates expand.
End User:
Airport Authorities control capital expenditure decisions for infrastructure, while Airlines and Ground Handling operators influence operational technology specifications through performance-based contracting pilots.
- Airport Authorities:Public and quasi-public entities owning terminal infrastructure and airfield systems determine procurement scope for biometric gates, IoT networks, and building management platforms. FAA infrastructure grants and Transport Canada funding eligibility filter vendor selection toward compliant hardware suppliers.
- Airlines:Carrier-specific investments in check-in automation, lounge digitization, and crew management systems concentrate at hub operations. Major US network carriers drive standardization demands that ripple through airport technology specifications.
- Ground Handling:Third-party service providers procure equipment tracking and workforce management systems.
- Passengers:End-user demand manifests indirectly through satisfaction metrics driving airport authority investment priorities.
Airport Authorities dominate capital procurement. Airlines are gaining influence fastest through outcome-based service contracts.
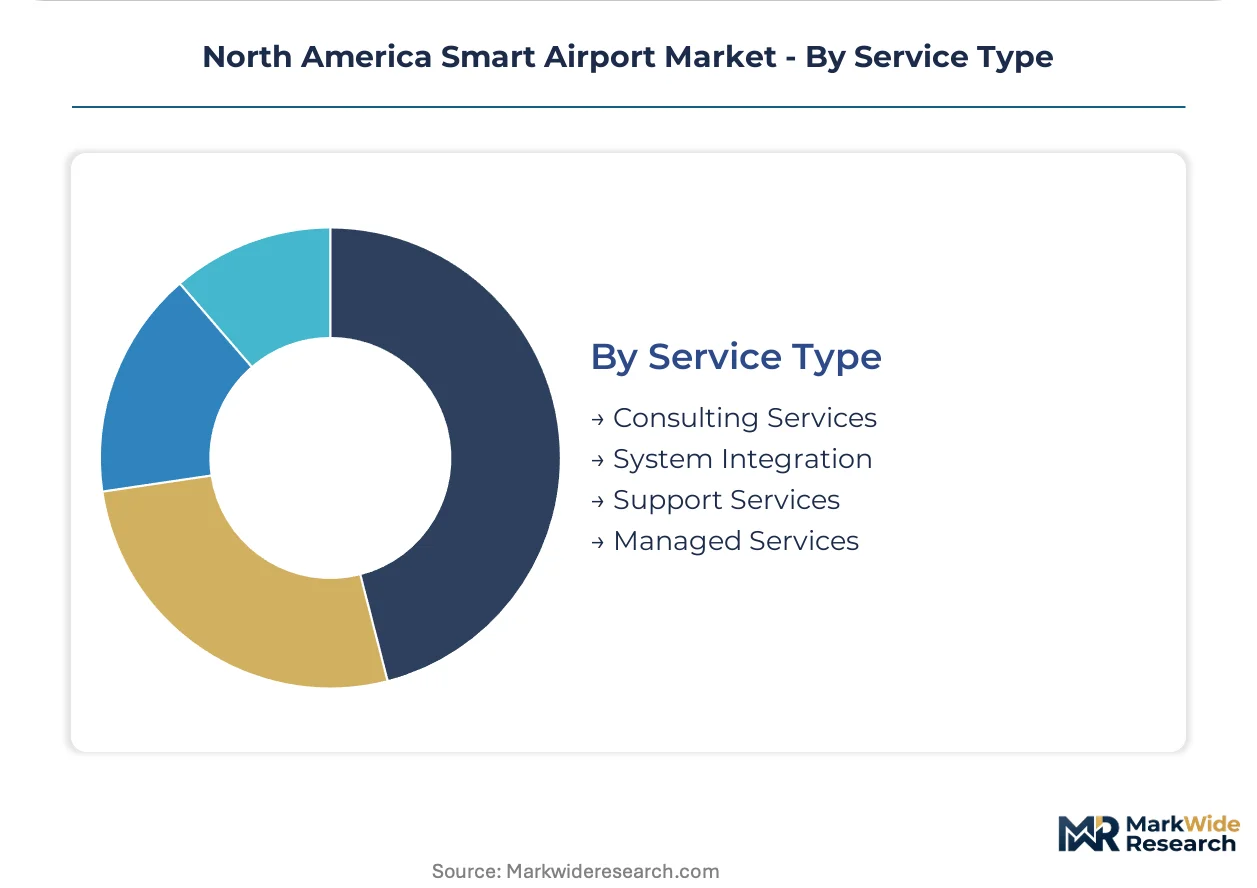
Service Type:
System Integration commands premium pricing for FAA Part 139 certified deployments, while Managed Services contracts are expanding as airports shift from capital expenditure to availability-based operational expenditure models.
- System Integration:Design, deployment, and certification of connected airfield equipment requires specialized expertise bridging aviation safety and industrial IoT security. Vendor qualification timelines compress under FAA cybersecurity directives, filtering out non-compliant integrators from federal infrastructure grants.
- Managed Services:Availability-based contracts for baggage handling, passenger processing, and building systems transfer operational risk to vendors. Dallas-Fort Worth and Phoenix have piloted these models, with procurement teams evaluating seven-year total cost of ownership.
- Consulting Services:Digital transformation planning and regulatory compliance advisory support pre-procurement phases.
- Support Services:Maintenance, training, and software update contracts for deployed systems.
System Integration leads by current contract value. Managed Services shows the steepest expansion trajectory as performance-based pricing gains adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA infrastructure grants and Transport Canada digitization frameworks channel procurement toward compliant vendors across the continent. Federal interoperability mandates compress deployment timelines while filtering non-certified suppliers from funding eligibility.
United States
Category X airports drive biometric boarding and AI baggage tracking procurement under FAA NextGen directives. The FAA's 49 U.S.C. § 44701 cybersecurity annexes disqualify hardware lacking continuous monitoring capabilities from federal grants. Dallas-Fort Worth and Phoenix anchor Sun Belt demand through concurrent terminal digitization programs.
Canada
Tier-1 airports deploy facial recognition gates as Transport Canada's Digital Aviation Strategy mandates touchless passenger corridors. The Transport Act amendments impose real-time telemetry requirements on connected airfield equipment. Vancouver, Calgary, and Montreal secondary terminals remain underpenetrated for integrated biometric platforms.
Mexico
Hub airport modernization accelerates as bilateral aviation agreements align Mexican certification with FAA cybersecurity standards. The Secretariat of Infrastructure, Communications and Transportation channels federal funding toward IoT sensor networks at Mexico City and Cancun terminals. Northern border state airports concentrate procurement for cross-border passenger processing integration.
North America Smart Airport Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with captive aviation divisions. Market structure concentrates around vendors holding FAA Part 139 cybersecurity certifications and Transport Canada interoperability qualifications. Two strategic archetypes dominate: building management specialists leveraging fire safety and HVAC control relationships, and digital platform vendors bundling simulation software with predictive maintenance contracts. Competitive moves center on outcome-based service contracting and direct airport relationships that bypass traditional systems integrators.
Within the certified systems integrator tier, Honeywell International Inc. and Siemens AG exemplify divergent positioning strategies. Honeywell occupies a position anchored in building management systems across major US hub airports through captive supply relationships in fire safety and environmental controls. Siemens represents the digital twin convergence archetype, adapting Munich-engineered simulation platforms for North American apron layouts. Thales Group sits within the passenger analytics specialization, anchoring biometric gate deployments at Canadian Tier-1 facilities.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| Honeywell International Inc. |
| IBM Corporation |
| Siemens AG |
| Thales Group |
| Amadeus IT Group |
| Raytheon Technologies Corporation |
| SITA |
| Sabre Corporation |
| Others |
Value Network & Pricing Analysis
FAA Part 139 certification upgrades with embedded cybersecurity annexes gate both vendor qualification and price differentiation, compressing procurement timelines while stratifying contract values across certified and non-certified supplier tiers. This regulatory filter concentrates pricing power with systems integrators holding dual aviation safety and industrial IoT security credentials.
Pricing Analysis
Cost-plus contracts with semiconductor indexation dominate IoT sensor and edge computing procurement, shielding vendors from raw material volatility while transferring margin risk to airport authorities. Price differentiation rests on FAA cybersecurity certification tier and after-sales service bundling, with Tier-1 integrators commanding premiums for continuous monitoring compliance. Cost compression in mid-tier system integration is intensifying because legacy RFID baggage infrastructure requires expensive middleware development. Canadian Tier-2 airports exhibit highest price sensitivity due to constrained infrastructure budgets, while US Category X hubs prioritize performance guarantees over upfront capital expenditure.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for edge computing chipsets, while China dominates rare earth magnet production for sensor motor assemblies. North American smart airport deployments draw from concentrated Asian foundry capacity for GPU accelerators, CMOS image sensors, and lithium-ion power cells. Single-source vulnerability in advanced node semiconductors exposes procurement timelines to geopolitical disruption. Distribution runs through FAA-certified systems integrators holding Transport Canada interoperability qualifications, with direct vendor-airport contracting expanding for AI analytics platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Deployable expertise in sub-100 millisecond latency engineering and FAA Part 139 cybersecurity certification constrains market entry, creating scarcity premiums for qualified integrators. This capability gap shapes competitive dynamics across vendor tiers and acquisition targeting.
For Market Incumbents: Compound certification advantages by embedding continuous monitoring telemetry into legacy building management installations, defending against specialized AI vendors bypassing traditional baggage handling OEMs. Deepen backward integration into edge computing hardware to secure semiconductor allocation priority. Prioritize outcome-based service contracts at Dallas-Fort Worth and Phoenix to lock in seven-year revenue visibility. For New Entrants and Emerging Players: Transport Canada's Digital Aviation Strategy fast-track certification offers entry into Vancouver, Calgary, and Montreal secondary terminals where biometric passenger corridors remain underpenetrated. Target Canadian Tier-2 airport authorities with bundled IoT sensor and biometric gate platforms priced on availability-based metrics. Leverage direct airport relationships to circumvent established systems integrator channels. For Investors and Strategic Acquirers: Pending NIST framework updates for critical infrastructure reshape the acquisition landscape by elevating compliance costs for non-certified hardware suppliers. Five-to-ten year viability favors platforms combining Munich-engineered simulation software with predictive maintenance revenue streams. Monitor FAA infrastructure grant disbursement velocity as inflection indicator for vendor consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Investment | FAA Part 139 annex compliance unlocks federal infrastructure grant eligibility. |
| Digital Twin Platform Integration | Munich-engineered simulation software enables predictive maintenance contracting. |
| Outcome-Based Service Contracting | Availability-based pricing at Sun Belt airports transfers operational risk to vendors. |
| Canadian Tier-2 Geographic Expansion | Secondary terminal digitization programs offer first-mover positioning. |
| Edge Computing Hardware Backward Integration | In-house production of sub-100 millisecond latency architectures secures supply. |
Research Methodology
The analysis maps IoT sensor networks, biometric platforms, AI analytics engines, and cloud infrastructure deployments, each validated through airport authority procurement officers, systems integration engineers, FAA certification consultants, and airline operations executives. Primary fieldwork combined with secondary validation from SEC filings, FAA NextGen program disclosures, Transport Canada regulatory amendments, and airport capital expenditure budgets. Bottom-up deployment tracking and top-down federal funding allocation triangulate market sizing across technology and application segments.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models technology type, application function, end-user archetype, and service delivery mode, with CAGRs derived from deployment velocity at named facilities. Forecast inputs include semiconductor lead-time indices, federal infrastructure grant authorization cycles, and biometric mandate implementation schedules.
Underlying assumptions cover regulatory compliance continuity, foundry capacity allocation stability, and federal funding authorization levels, with deviation risk concentrated in cybersecurity directive amendments and geopolitical semiconductor trade restrictions. Recalibration cycles align with material shifts in FAA procurement specifications and Transport Canada interoperability mandate updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Technologies
Middle-East and Africa Airport Ground Handling Systems Market
Airport Technologies
Airport RFID System Market
Airport Technologies
Airport Cargo Community Digital Collaboration Platforms Market
Airport Technologies
Asia-Pacific Smart Airport Market
Airport Technologies
Global Remote Towers Market
Airport Technologies
Middle-East and Africa Smart Airport Market
Airport Technologies
Airport Airside Service Market
Airport Technologies
Smart Baggage Handling System Market
Airport Technologies
Global Airport Baggage Handling System Market
Airport Technologies
North America Airport Baggage Handling Systems Market
Airport Technologies
Middle-East and Africa Airport Baggage Handling Systems Market
Airport Technologies
Smart Airport 3.0 Market
Airport Technologies
Commercial Airport Radar Systems Market
Airport Technologies
America Airport Ground Handling Systems Market
Airport Technologies
Airport Smart Lighting Market
Airport Technologies
Europe Airport Ground Handling Systems Market