
 Airport Ground Handling Market | 2026-2036
Airport Ground Handling Market Size, Share, and Industry Trends Forecast 2026-2036
Airport Ground Handling Market Analysis
Asset-light leasing models for ground support equipment fleets is rewriting competitive entry barriers across the sector. Menzies Aviation plc leverages its global station network to sustain long-term airline contracts across five continents. Swissport International AG anchors its position through integrated cargo and passenger service bundles at major European hubs. dnata differentiates via in-house training academies that control labor quality and regulatory compliance costs.
Airport ground handling encompasses the complete suite of aircraft turnaround services performed between landing and departure, including baggage conveyance, aircraft towing, passenger boarding bridge operation, and cargo loading within strict slot-time windows of 25-90 minutes depending on aircraft class. The primary commercial purpose is to minimize aircraft on-ground time while ensuring safety compliance and passenger service continuity. Baggage handling commands the largest service revenue pool due to high labor intensity and equipment dependency, while cargo operations represent the fastest-expanding segment driven by e-commerce air freight volumes. Pushback tractors and belt loaders dominate equipment procurement budgets, though ground power units are gaining share as airports electrify apron operations to meet emissions targets.
The FAA mandates specific ground handling safety protocols under 14 CFR Part 139 for US commercial airports, while the EU Green Deal and F-Gas Regulation are accelerating diesel-to-electric equipment replacement mandates across European apron zones. EASA's oversight of ground handling service provider certification under Regulation 965/2012 shapes market access by requiring standardized training and operational audits. Stakeholders must monitor how evolving carbon border adjustments and local airport slot regulations reshape the economics of centralized versus decentralized ground handling contracts.
Market Dynamics
Electrification mandates under the EU Green Deal and parallel emissions frameworks are compressing equipment replacement cycles while reconfiguring capital deployment across apron operations worldwide.
Growth Catalysts
- E-commerce air freight expansion:Parcel volumes through express carriers are forcing hub airports to expand dedicated cargo handling capacity and cold-chain infrastructure.
- EU F-Gas Regulation:Diesel ground power unit phaseouts are creating replacement demand for electric alternatives across European apron zones.
- India airport privatization:Greenfield developments at Navi Mumbai and Jewar are accelerating third-party ground handler contract awards.
Market Restraints
- Lithium battery supply concentration:Cathode material processing dependence on China is inflating electric GSE procurement costs and extending delivery timelines.
- Specialized technician scarcity:FAA-certified airframe mechanics command premium wages, constraining labor pool expansion for integrated ground handling providers.
- Slot allocation rigidity:IATA Worldwide Slot Guidelines limit operational flexibility at congested hubs, compressing turnaround windows below equipment optimization thresholds.
Strategic Opportunities
- Saudi Arabia giga-project aviation:NEOM and Red Sea International Airport developments are greenfield opportunities for full-service ground handling contracts without incumbent displacement costs.
- Predictive maintenance analytics:IoT sensor integration with fleet management platforms is enabling outcome-based service pricing for equipment leasing.
- Hydrogen fuel cell GSE:Zero-emission alternatives are gaining traction for pushback tractors where battery weight compromises operational range.
Industry Challenges
- EASA Regulation 965/2012 audit cycles:Certification maintenance requires continuous training documentation and operational standardization across multi-station networks.
- Legacy fleet integration:Mixed diesel-electric equipment pools complicate maintenance scheduling and spare parts inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airport Ground Handling Market |
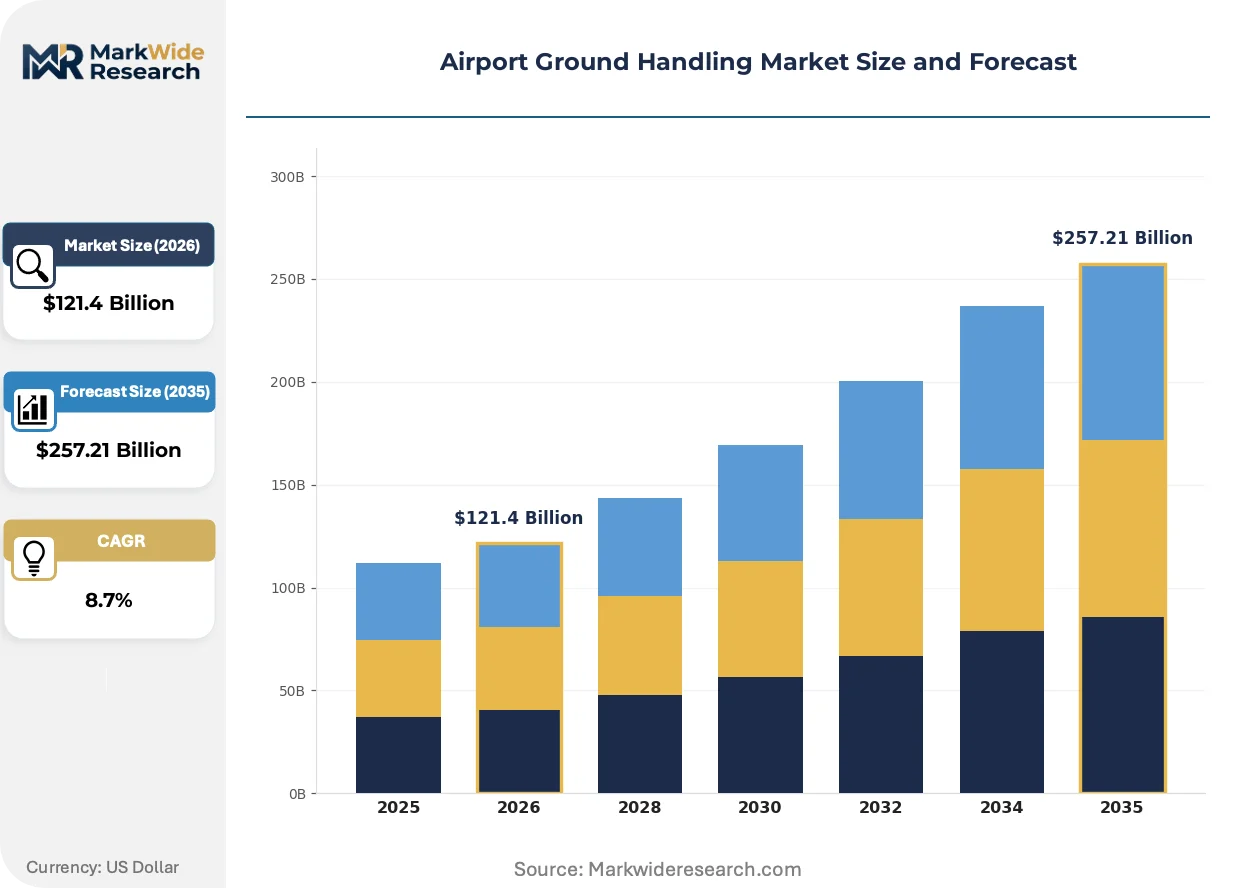
| Market Size in 2026 | $121.4 Billion |
| Market Size in 2035 | $257.21 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Baggage Handling, Aircraft Maintenance, Passenger Services, Cargo Operations Equipment Type: Pushback Tractors, Belt Loaders, Tugs, Ground Power Units End User: Airlines, Ground Service Providers, Airports, Freight Forwarders Operational Capacity: Low-Cost Carriers, Full-Service Carriers, Charter Airlines, Regional Operators |
| Companies Covered | Menzies Aviation plc, Çelebi Havacılık Holding A.Ş., Swissport International AG, TAV Havalimanları Holding A.Ş., Singapore Airport Terminal Services Limited, dnata, Aviapartner Group NV, Groundforce Handling Portugal, Worldwide Flight Services (WFS), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airport Ground Handling Market Emerging Trajectories
Automation and electrification are converging to redefine aircraft turnaround economics, with regulatory pressure accelerating technology adoption timelines beyond typical capital planning horizons.
Autonomous baggage tractors are migrating from pilot programs to operational deployment at major hubs. Dubai International Airport and Changi Airport have both integrated driverless baggage dollies into active apron zones. This technology is migrating from novelty demonstrations to standard procurement specifications in Asian hub RFPs, compressing labor cost structures for overnight sort operations.
The EU Green Deal's 55% emissions reduction target for 2030 is mandating diesel-to-electric conversion timelines for all ground support equipment categories. National implementation through airport operating licenses is binding ground handlers to fleet electrification commitments. German hub operators face the most compressed compliance windows, with Frankfurt and Munich airports requiring full electric GSE penetration by 2028.
Airline procurement departments are unbundling integrated ground handling contracts into discrete service modules. Full-service carriers now separately tender baggage, cargo, and passenger services at major stations. This pattern is most visible in India, where Air India and IndiGo have fragmented contracts across multiple specialized providers at Delhi and Mumbai to optimize unit economics.
Airport Ground Handling Market Segmentation
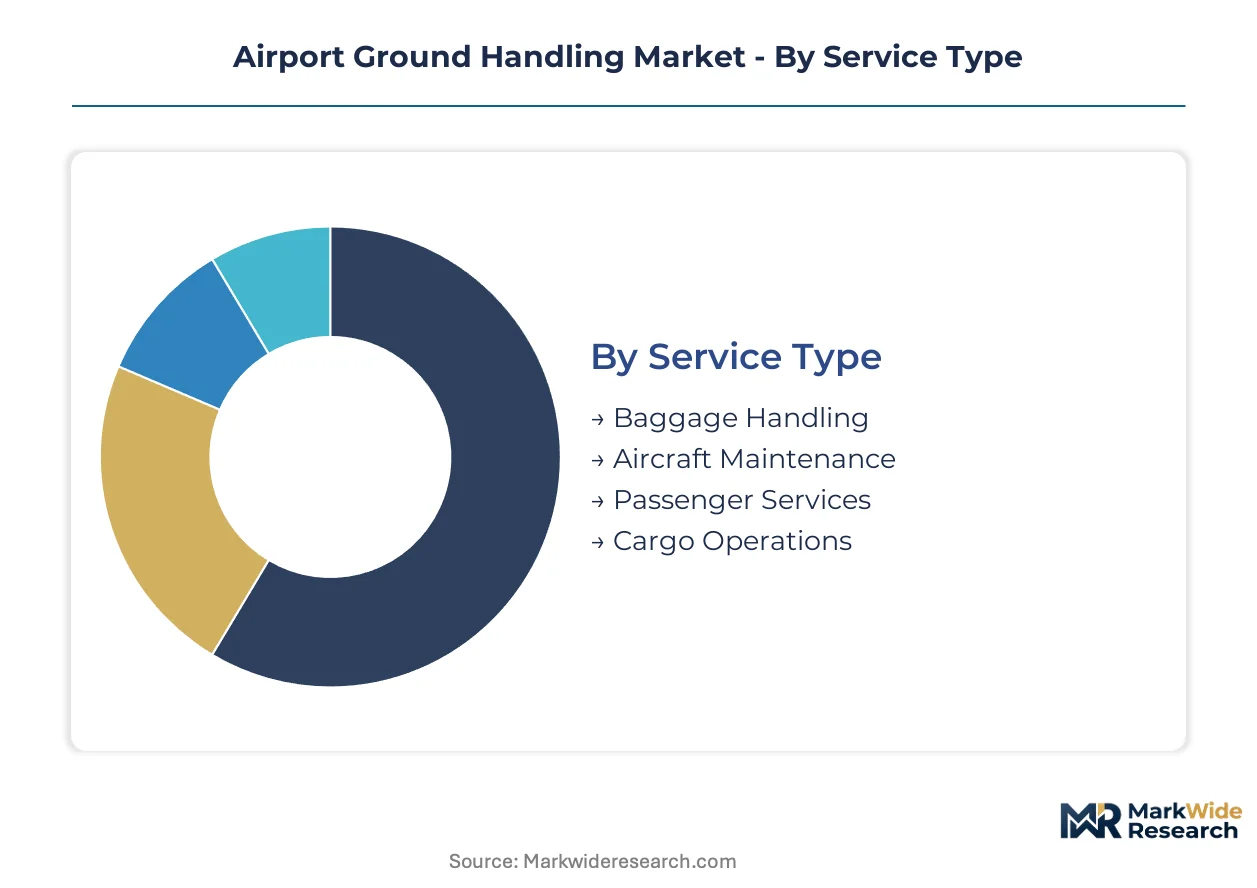
Ground handling contracts vary sharply by operational intensity and regulatory exposure. Service providers configure staffing, equipment, and certification levels around distinct commercial aviation models.
Service Type:
The use-case spectrum spans labor-intensive passenger touchpoints through capital-heavy cargo infrastructure, each demanding different workforce skill profiles and equipment portfolios.
- Baggage Handling:Conveyor systems and sortation automation dominate capital allocation. Demand concentrates at Dubai International and Hartsfield-Jackson Atlanta, where hub-and-spoke networks generate massive transfer volumes and sub-20-minute connection windows.
- Cargo Operations:Cold-chain infrastructure and express parcel sortation define capability requirements. E-commerce volumes through Shenzhen and Memphis are forcing dedicated freighter stand expansion and perishable handling certifications.
- Aircraft Maintenance:Line maintenance services performed during turnaround windows require FAA-certified airframe mechanics. Overnight checks at maintenance bases generate recurring revenue streams independent of flight schedules.
- Passenger Services:Check-in counters, gate management, and boarding bridge operation carry high labor intensity but lower equipment dependency. Contract margins compress at stations where airlines retain direct control of premium cabin services.
The dominant share belongs to Baggage Handling, while Cargo Operations is closing the gap fastest.
Equipment Type:
Procurement budgets track electrification mandates and apron congestion severity, with diesel replacement cycles accelerating under emissions frameworks.
- Ground Power Units:Electric alternatives are displacing diesel models under EU F-Gas Regulation phaseouts. Frankfurt and Munich airports require full electric penetration, binding ground handlers to fleet conversion commitments.
- Pushback Tractors:Hydrogen fuel cell variants are gaining traction where battery weight compromises operational range for widebody aircraft. Saudi Arabia's NEOM development specifies zero-emission ground support equipment from inception.
- Belt Loaders:Narrow-body compatibility and containerized cargo adaptation drive specification diversity. Leasing models dominate procurement as handlers prioritize fleet flexibility over ownership.
- Tugs:Baggage and cargo dollies require standardized coupling systems across mixed airline fleets. Autonomous variants are migrating from pilot programs to operational deployment at Singapore Changi.
Ground Power Units command the largest procurement volumes currently, with Pushback Tractors seeing the steepest technology transition.
End User:
Contract structures diverge between asset-heavy airport operators and specialized third-party providers competing on unit economics.
- Ground Service Providers:Integrated handlers like Menzies Aviation and Swissport bundle passenger, cargo, and ramp services across multi-station networks. Long-term airline contracts anchor revenue predictability.
- Airlines:Full-service carriers are expanding outsourced ground operations at hub airports while retaining direct control at home bases. Air India and IndiGo have fragmented contracts across multiple providers at Delhi and Mumbai.
- Airports:Privatized operators at Navi Mumbai and Jewar are accelerating third-party handler contract awards through concession agreements.
- Freight Forwarders:Express integrators demand dedicated cargo handling capacity with customs pre-clearance capabilities at major hubs.
Ground Service Providers hold the established position, though Airlines are fragmenting procurement fastest.
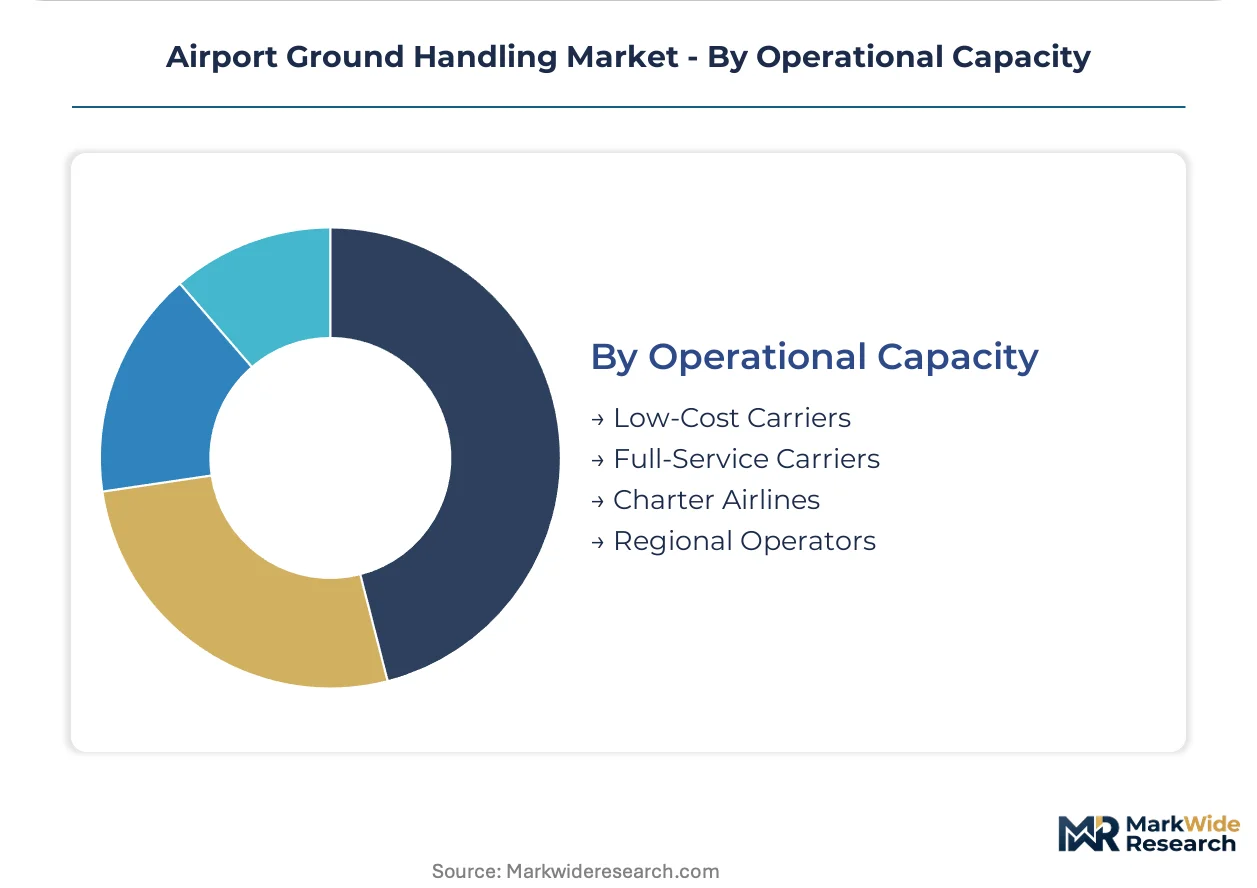
Operational Capacity:
Turnaround economics vary dramatically by aircraft utilization intensity and service tier expectations.
- Full-Service Carriers:Complex catering, premium cabin services, and interline baggage handling extend ground time requirements. Hub operations at London Heathrow and Paris Charles de Gaulle demand synchronized multi-vendor coordination.
- Low-Cost Carriers:25-minute turnaround targets compress all service windows and eliminate non-essential touchpoints. Stand-remote boarding and minimal catering reduce equipment dependency.
- Regional Operators:Turboprop fleets require specialized ground power and smaller belt loader configurations. Frequency-driven schedules at secondary airports generate stable but lower-yield contracts.
- Charter Airlines:Irregular operations and seasonal peaks demand flexible staffing models and short-term equipment leases.
Full-Service Carriers generate the highest contract values, while Low-Cost Carriers are expanding ground handling outsourcing most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's emissions mandates are compressing equipment replacement cycles across European apron zones while India's airport privatization wave accelerates third-party ground handler contract awards at greenfield developments.
Germany
Frankfurt and Munich airports require full electric ground support equipment penetration by 2028 under national implementation of EU F-Gas Regulation phaseouts. The Luftfahrt-Bundesamt enforces standardized training documentation for ground handling certification maintenance. Lufthansa Group's hub operations at Frankfurt anchor integrated multi-vendor coordination demand for synchronized turnaround services.
United States
E-commerce air freight expansion through Memphis and Louisville is forcing dedicated cargo handling capacity investments from express integrators. The FAA mandates specific ground handling safety protocols under 14 CFR Part 139 for commercial airports nationwide. Delta Air Lines and United Airlines retain direct ground operations control at Atlanta and Chicago O'Hare while expanding outsourcing at secondary stations.
India
Greenfield airport developments at Navi Mumbai and Jewar are accelerating third-party ground handler contract awards through concession agreements. The Airports Authority of India privatization framework binds new operators to service-level commitments for passenger and cargo throughput. Delhi and Mumbai hub operations fragment contracts across multiple specialized providers as Air India and IndiGo optimize unit economics.
Saudi Arabia
NEOM and Red Sea International Airport developments represent greenfield opportunities for full-service ground handling contracts without incumbent displacement costs. The General Authority of Civil Aviation aligns giga-project aviation infrastructure with zero-emission ground support equipment specifications from inception. Riyadh's King Khalid International Airport expansion concentrates demand for integrated passenger and cargo service bundles.
Singapore
Changi Airport's integration of autonomous baggage dollies into active apron zones is migrating driverless technology from pilot programs to standard procurement specifications. The Civil Aviation Authority of Singapore oversees ground handling service provider licensing under performance-based regulatory frameworks. The airport-city industrial cluster anchors Southeast Asian hub demand for cold-chain cargo infrastructure and express parcel sortation capacity.
Airport Ground Handling Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a market structure consolidating around multi-station network operators and regional equipment providers. Three archetypes dominate: integrated global handlers bundling passenger, cargo and ramp services; specialized cargo operators building cold-chain infrastructure at express hubs; and equipment-focused lessors deploying asset-light fleet models. Competitive moves concentrate on M&A for station network expansion and strategic partnerships for electrified equipment procurement.
Among integrated global handlers, Menzies Aviation plc, Swissport International AG and dnata occupy positions representing the multi-continent contract archetype. Menzies leverages its station network across five continents for long-term airline contract anchoring. Swissport exemplifies the European hub concentration model through integrated cargo and passenger service bundles. dnata sits within the training-controlled quality tier via in-house academy infrastructure managing labor compliance costs. These three structures illustrate how scale, geographic clustering and workforce certification differentiate competitive positioning across apron service markets.
| Leading Market Players |
|---|
| Menzies Aviation plc |
| Çelebi Havacılık Holding A.Ş. |
| Swissport International AG |
| TAV Havalimanları Holding A.Ş. |
| Singapore Airport Terminal Services Limited |
| dnata |
| Aviapartner Group NV |
| Groundforce Handling Portugal |
| Worldwide Flight Services (WFS) |
| Others |
Supply Flow & Price Mechanics
Lithium battery supply concentration in China determines both equipment procurement tier spreads and ground support equipment fleet configuration across apron operations worldwide. Cathode material processing bottlenecks inflate electric GSE delivery timelines and compress margin structures for handlers pursuing EU Green Deal compliance.
Pricing Analysis
Certification level under EASA Regulation 965/2012 creates the primary spread between premium and standard service tiers. Three-tier pricing structure across premium, standard, and economy levels reflects audit documentation depth and multi-station network coverage. Cost compression in the standard tier is intensifying because airlines unbundle integrated contracts into discrete service modules. Low-cost carriers exhibit highest price sensitivity due to 25-minute turnaround targets, while full-service carriers at hub airports tolerate premium pricing for synchronized multi-vendor coordination.
Supply Chain Analysis
Ground support equipment manufacturing concentrates in Germany, China, and the United States for pushback tractors and belt loaders. Fleet procurement draws from lithium-ion battery cells, high-strength steel chassis, and electric drivetrain components. Single-source vulnerability for cathode material processing creates procurement risk for European handlers facing 2028 electrification deadlines. Distribution runs through airport operating license mandates that bind ground handlers to fleet conversion commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified airframe mechanic scarcity constrains labor pool expansion for integrated ground handling providers pursuing line maintenance service growth. This capability gap separates handlers with in-house training academies from competitors dependent on external certification pipelines.
For Market Incumbents: Build regulatory compliance documentation as a moat against audit cycle disruptions under EASA Regulation 965/2012. Invest in captive training academy infrastructure to control labor quality and reduce certification maintenance costs. Acquire specialized cargo operators at express hubs to capture e-commerce air freight expansion. Expand electric GSE leasing portfolios to capture asset-light demand from airlines fragmenting procurement. For New Entrants and Emerging Players: Greenfield airport developments in Saudi Arabia represent the most penetrable entry point without incumbent displacement costs. Target hydrogen fuel cell pushback tractor deployment at NEOM and Red Sea International Airport where zero-emission specifications apply from inception. Pursue predictive maintenance analytics partnerships with IoT sensor providers to enable outcome-based service pricing for equipment leasing contracts. For Investors and Strategic Acquirers: EU F-Gas Regulation phaseout deadlines reshape the acquisition landscape toward electric GSE fleet operators with established airport concession relationships. Long-term viability centers on handlers with multi-station networks spanning 3+ continents and documented training standardization. Target acquisition archetype: integrated providers with cold-chain cargo certifications at express hubs. Monitor lithium battery supply chain diversification announcements as inflection indicator for procurement cost normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Training Academy Expansion | In-house EASA certification control reduces compliance costs and anchors airline contract renewals. |
| Electric Fleet Conversion | Frankfurt and Munich airport mandates bind handlers to 2028 full electrification commitments. |
| Cargo Infrastructure Buildout | Express parcel sortation capacity at Shenzhen and Memphis captures e-commerce volume growth. |
| Autonomous Equipment Deployment | Driverless baggage dollies at Changi Airport compress labor costs for overnight operations. |
| Greenfield Hub Concession Bidding | Navi Mumbai and Jewar privatization awards long-term third-party handler contracts without displacement. |
Methodological Framework
A spread of perspectives from ground handling operations directors, airline procurement managers, airport concession planners, and EASA certification auditors converged on the working assumptions. Primary interviews with apron equipment maintenance heads and cargo terminal managers combined with secondary validation from FAA 14 CFR Part 139 filings, EU Green Deal implementation documents, airport operating license records, and IATA slot allocation databases. Bottom-up station-level revenue modeling and top-down regional market sizing provided triangulation across the analysis window.
Demand-supply balance framing anchored the forecast framework across service type, equipment category, and operational capacity segments. Modeled dimensions included baggage handling automation intensity, cargo cold-chain infrastructure tier, and aircraft turnaround window compression. CAGRs derived from equipment replacement cycle acceleration under emissions mandates and greenfield airport development pipelines. Forecast inputs incorporated lithium battery procurement cost trajectories and certified technician wage inflation patterns.
Practitioners should monitor EU carbon border adjustment announcements and local airport slot regulation changes for early signals of centralized versus decentralized contract economics. Forecasts reflect assumptions on electrification technology adoption curves and privatization concession award timelines. Quarterly review of cathode material supply diversification indicators and EASA audit documentation standardization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Operations
Business Jet Ground Handling Services Market
Airport Operations
Africa Airport Operations Market
Airport Operations
Europe Offshore Helicopter Services Market
Airport Operations
France Airport Operations Market
Airport Operations
Middle East Airport Ground and Cargo Handling Services Market
Airport Operations
South Korea Airport Operations Market
Airport Operations
Airport Terminal Operations Market
Airport Operations
Europe Airport Operations Market
Airport Operations
Airport Operations Market
Airport Operations
UK Airport Operations Market
Airport Operations
Global Airside Services Market
Airport Operations
Global Non-Aeronautical Market
Airport Operations
Aircraft Ground Handling System Market
Airport Operations
Airport Ground and Cargo Handling Services Market
Airport Operations
Middle East Airport Operations Market
Airport Operations
Canada Airport Operations Market