
 Middle-East and Africa Smart Airport Market | 2026-2036
Middle-East and Africa Smart Airport Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Smart Airport Market Foresight
Gulf-based airport infrastructure investment is decoupling from traditional construction cycles as digital overlay spending accelerates. SITA leverages its longstanding air transport IT heritage to anchor passenger processing contracts across the region's busiest hubs. Honeywell International Inc. competes through building automation and security analytics integration, while Huawei Technologies Co., Ltd. extends its telecommunications infrastructure dominance into airport-specific IoT and smart lighting deployments.
The Middle-East and Africa Smart Airport encompasses digitally integrated airport ecosystems combining biometric identification hardware, sensor networks, and real-time data analytics platforms to optimize passenger throughput, asset tracking, and energy management. Biometric Systems now command disproportionate capital allocation as facial recognition gates and touchless identity verification become operational requirements rather than premium upgrades. IoT Solutions and Security Analytics represent the fastest-expanding application layers, whereas Integration Services capture concentrated margin pools due to the complexity of retrofitting legacy infrastructure with interoperable digital systems.
Saudi Arabia's General Authority of Civil Aviation and South Africa's Civil Aviation Authority enforce divergent certification pathways that fragment vendor compliance costs across the region. The UAE's GCAA mandates align more closely with EU aviation security frameworks, creating regulatory arbitrage opportunities for technology providers already certified under EASA-equivalent standards. Stakeholders must monitor how national data localization requirements intersect with cloud-based airport management platforms, as this tension will determine which service architectures gain procurement preference across African and Middle Eastern jurisdictions.
Market Dynamics
Biometric passenger processing mandates from the International Civil Aviation Organization are compressing deployment timelines across Middle Eastern and African hubs, forcing capital reallocation from physical infrastructure expansion toward digital overlay systems that retrofit existing terminals.
Growth Catalysts
- ICAO TRIP Framework Compliance:Aviation security mandates from the International Civil Aviation Organization's Traveler Identification Programme are accelerating procurement of facial recognition gates and automated border control systems across Saudi Arabia and the United Arab Emirates.
- Mega-Hub Expansion Cycles:Dubai International Airport and King Abdulaziz International Airport are setting deployment benchmarks for biometric passenger processing that neighboring markets emulate through competitive infrastructure positioning.
- Touchless Identity Verification:Post-pandemic operational requirements have elevated contactless biometric authentication from premium upgrade to baseline procurement specification across the region's busiest terminals.
Market Restraints
- Legacy Infrastructure Retrofit Costs:Interoperability requirements between decades-old baggage handling systems and new IoT sensor networks inflate integration budgets beyond original digital transformation projections.
- Vendor Concentration in Critical Components:Biometric algorithm licensing remains concentrated among a narrow set of specialized providers, creating supply vulnerability for airport operators pursuing multi-vendor strategies.
- Data Localization Compliance Friction:Divergent national requirements across Saudi Arabia's General Authority of Civil Aviation and South Africa's Civil Aviation Authority fragment cloud architecture standardization for airport management platforms.
Strategic Opportunities
- Underpenetrated African Secondary Hubs:Nigeria's Murtala Muhammed International Airport and Kenya's Jomo Kenyatta International Airport present first-mover positioning for integrated biometric-IoT deployments before regulatory mandates harden.
- Energy Analytics Convergence:Smart lighting systems are converging with building automation platforms to create unified energy management dashboards that reduce operational expenditure for desert-climate cooling loads.
- UAE-GCCA Regulatory Arbitrage:The Emirates' General Civil Aviation Authority alignment with EASA-equivalent standards creates certification pathway advantages for European-heritage technology providers entering the broader region.
Industry Challenges
- Interoperability Engineering Talent Scarcity:Airport operators face acute shortages of systems architects capable of bridging proprietary legacy protocols with open-standard IoT frameworks without operational downtime.
- Multi-Jurisdiction Certification Timelines:Biometric system vendors must navigate sequential approval processes across Saudi Arabia's General Authority of Civil Aviation and South Africa's Civil Aviation Authority, extending revenue recognition cycles.
- Sensor Network Cybersecurity Integration:Real-time data analytics platforms require hardened edge computing architectures that most regional airport IT departments lack internal capability to architect and maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Smart Airport Market |
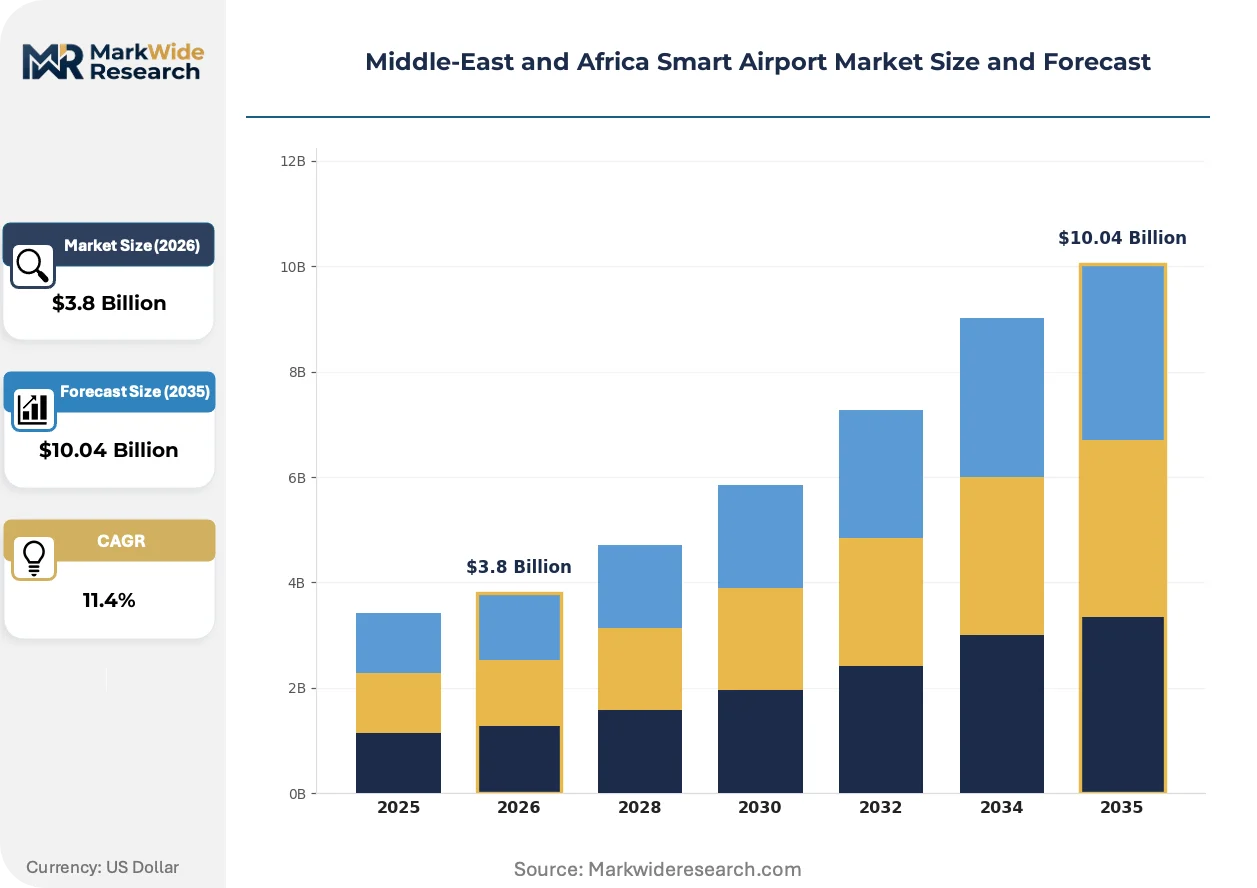
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT Solutions, Biometric Systems, Security Analytics, Smart Lighting End User: Airlines, Airport Operators, Government Agencies, Ground Handlers Application: Passenger Processing, Security Management, Baggage Handling, Information Management Service Type: Consulting Services, Integration Services, Support Services, Maintenance Services |
| Companies Covered | SITA, Honeywell International Inc., IBM, Amadeus IT Group, S.A., Siemens AG, Cisco Systems, Inc., Indra Sistemas, S.A., Thales Group, Huawei Technologies Co., Ltd., Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Smart Airport Market Shifts & Advancements
Digital twin architectures are displacing static simulation models across Middle Eastern hub operations, enabling real-time scenario testing for passenger flow optimization before physical reconfiguration commitments.
Computer vision analytics for baggage tracking is converging with automated guided vehicle fleets to create closed-loop asset management systems. Dubai International Airport and Hamad International Airport are piloting these integrated deployments during 2024 operational windows. The structural consequence is compression of ground handling labor intensity while improving mishandled baggage recovery rates.
Saudi Arabia's General Authority of Civil Aviation has issued biometric data retention specifications that exceed baseline ICAO requirements. This regulatory divergence is fragmenting vendor compliance roadmaps, as systems architected for UAE deployment require architectural modification for Saudi certification. African operators are deferring procurement decisions pending clarity on whether GACA or GCAA frameworks will dominate regional standardization.
Airport operators are consolidating vendor relationships around integrated service contracts that bundle hardware, software, and decade-long maintenance obligations. The traditional discrete procurement of point solutions from competing specialists is yielding to single-accountability structures. This pattern is most pronounced in the United Arab Emirates, where Dubai Aviation Engineering Projects has mandated unified responsibility clauses for its terminal expansion portfolios.
Middle-East and Africa Smart Airport Market Segmentation
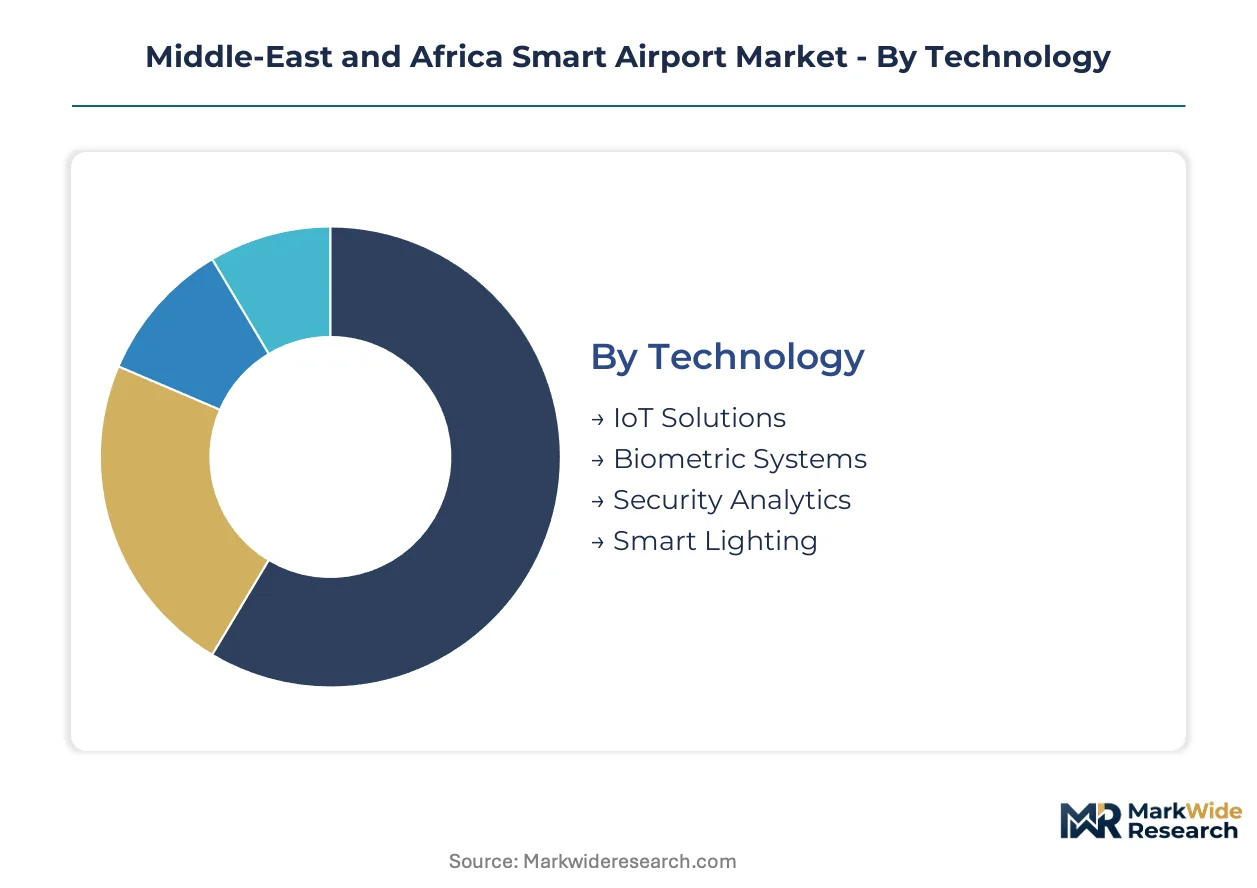
Procurement patterns across Middle-East and Africa smart airports diverge sharply by technology maturity and regulatory readiness. Upgrade cycles for legacy terminals versus greenfield mega-hub deployments create distinct demand profiles that vendors must navigate simultaneously.
Technology:
Retrofit intensity varies dramatically by terminal vintage, with newer Gulf infrastructure favoring integrated platform deployments while African secondary airports prioritize modular, expandable architectures.
- Biometric Systems:Facial recognition gates and automated border control units process passenger identity verification through ICAO-compliant document readers. Dubai International Airport and King Abdulaziz International Airport anchor regional demand as neighboring emirates accelerate competitive procurement. Touchless authentication mandates have compressed sales cycles from premium upgrade to baseline specification.
- IoT Solutions:Sensor networks for environmental monitoring, asset tracking, and predictive maintenance integrate with building management platforms through edge computing architectures. Saudi Arabia's General Authority of Civil Aviation and UAE's GCAA diverge on data localization requirements, fragmenting cloud deployment standards across the region.
- Security Analytics:Real-time video analytics and threat detection algorithms screen passenger behavior patterns and baggage anomalies.
- Smart Lighting:LED retrofit programs with automated daylight harvesting reduce cooling loads in desert-climate terminals.
Volume placements concentrate in Biometric Systems; the faster expansion belongs to IoT Solutions.
End User:
Budget authority fragmentation shapes procurement complexity, with each stakeholder class operating distinct capital allocation timelines and technical specification priorities.
- Airport Operators:Terminal owners and concession holders fund passenger-facing digital infrastructure including biometric gates, wayfinding systems, and retail analytics platforms. Mega-hub expansions in the UAE and Saudi Arabia concentrate capital deployment, while African operators defer commitments pending regulatory harmonization.
- Government Agencies:National aviation authorities and border control departments mandate security system specifications and fund sovereign checkpoint infrastructure. Saudi Arabia's General Authority of Civil Aviation enforces biometric data retention requirements that exceed baseline ICAO frameworks, forcing architectural modifications for multinational vendors.
- Airlines:Carriers invest in self-service check-in, baggage tracking, and loyalty integration at their hub operations.
- Ground Handlers:Ramp operators procure asset tracking and workforce management systems for tarmac efficiency.
Capital commitment scale favors Airport Operators; regulatory specification power resides with Government Agencies.
Application:
Operational pain point severity determines deployment sequencing, with passenger throughput bottlenecks commanding priority over back-of-house optimization.
- Passenger Processing:End-to-end biometric corridors eliminate document presentation at multiple checkpoints, compressing connection times and reducing terminal congestion. Dubai International Airport's Terminal 3 and Hamad International Airport serve as reference architectures that neighboring markets emulate through competitive infrastructure positioning.
- Security Management:Integrated threat detection combines video analytics, access control, and perimeter monitoring into unified command centers. Divergent certification pathways between Saudi Arabia's General Authority of Civil Aviation and South Africa's Civil Aviation Authority fragment vendor compliance roadmaps.
- Baggage Handling:RFID tracking and automated guided vehicle fleets reduce mishandled baggage rates.
- Information Management:Flight information displays and mobile passenger applications integrate real-time operational data.
Deployment maturity peaks in Passenger Processing; Security Management climbs the fastest as regulatory mandates harden.
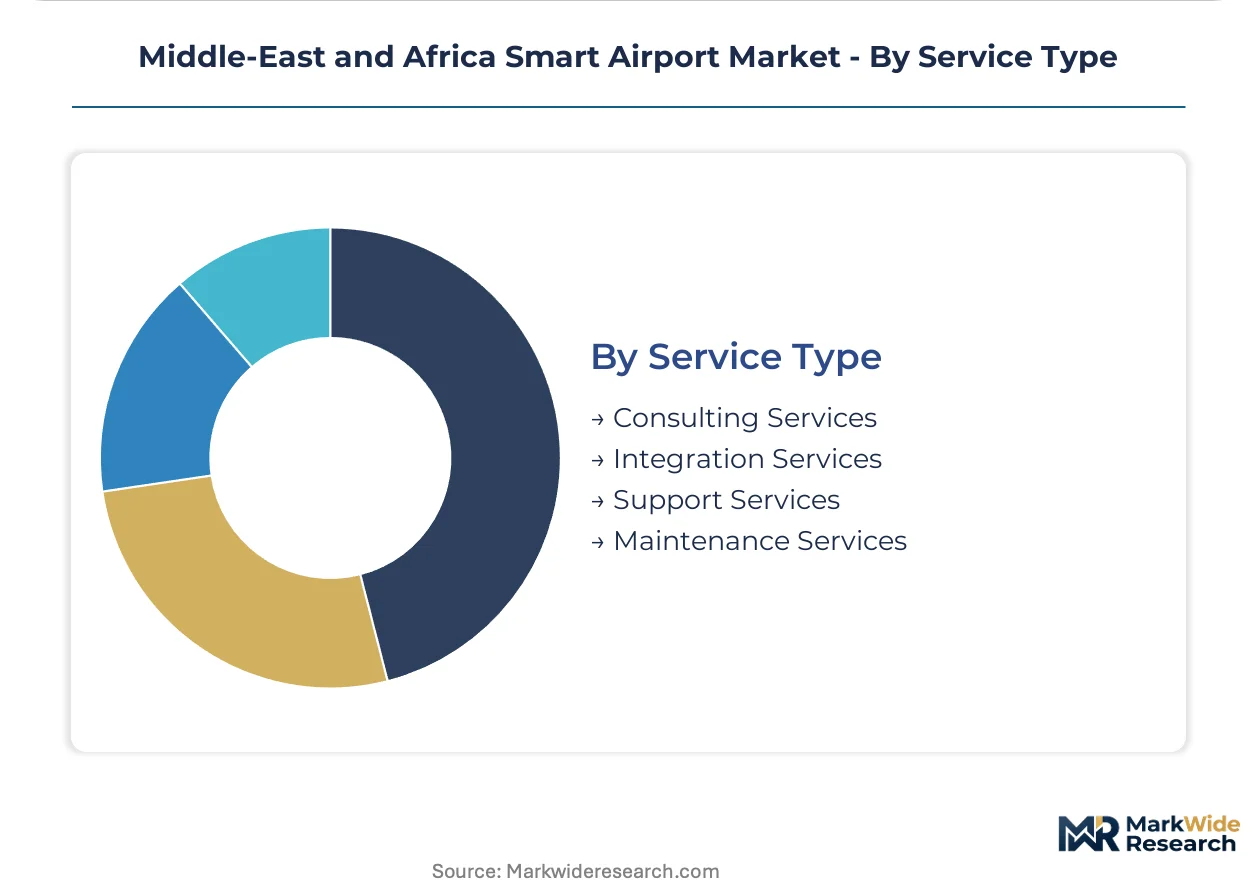
Service Type:
Contract structure evolution favors bundled accountability over discrete procurement, with decade-long maintenance obligations becoming standard in Gulf mega-hub awards.
- Integration Services:Systems architects bridge proprietary legacy protocols with open-standard IoT frameworks, ensuring interoperability between decades-old baggage handling infrastructure and new sensor networks. Scarce engineering talent inflates project timelines and concentrates margin capture among specialized providers.
- Maintenance Services:Long-term operational support contracts cover biometric hardware calibration, software updates, and cybersecurity patching. Dubai Aviation Engineering Projects mandates unified responsibility clauses that bundle hardware, software, and maintenance under single-vendor accountability.
- Consulting Services:Digital transformation strategy and regulatory compliance advisory precede capital deployment.
- Support Services:Help desk and field engineering response for operational incident resolution.
Revenue concentration sits with Integration Services; contract duration extension favors Maintenance Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petroleum-derived capital reserves from the Arabian Peninsula anchor procurement capacity for biometric and IoT infrastructure across the Middle-East and Africa smart airport landscape.
United Arab Emirates
Dubai International Airport and Abu Dhabi International Airport drive concentrated demand for facial recognition gates and automated border control systems. The General Civil Aviation Authority mandates alignment with EASA-equivalent security frameworks, creating certification arbitrage for European-heritage technology providers. Dubai Aviation Engineering Projects bundles hardware, software, and maintenance under unified vendor accountability clauses for its terminal expansion portfolios.
Saudi Arabia
King Abdulaziz International Airport and King Khalid International Airport anchor mega-hub expansion cycles that neighboring markets emulate through competitive infrastructure positioning. The General Authority of Civil Aviation enforces biometric data retention specifications exceeding baseline ICAO requirements, fragmenting vendor compliance roadmaps. Riyadh and Jeddah clusters concentrate capital deployment for integrated passenger processing corridors.
South Africa
O.R. Tambo International Airport and Cape Town International Airport face deferred procurement timelines pending regulatory harmonization between GACA and GCAA frameworks. The Civil Aviation Authority maintains divergent certification pathways that inflate integration costs for multinational vendors. Johannesburg and Pretoria industrial zones concentrate maintenance and integration service capabilities for legacy terminal retrofit projects.
Qatar
Hamad International Airport pilots computer vision analytics for baggage tracking converged with automated guided vehicle fleets during operational windows. The Qatar Civil Aviation Authority monitors Saudi and UAE regulatory developments before finalizing biometric mandate specifications. Doha serves as reference architecture for passenger flow optimization that Gulf Cooperation Council neighbors benchmark against.
Egypt
Cairo International Airport pursues modular biometric-IoT deployments prioritizing expandable architectures over integrated platform investments. The Egyptian Civil Aviation Authority defers to regional standardization clarity before hardening procurement specifications. Cairo and Alexandria clusters concentrate government agency funding for sovereign checkpoint infrastructure rather than full terminal digitization.
Middle-East and Africa Smart Airport Market Competitive Landscape
Global majors compete with regional champions across integration complexity and regulatory certification dimensions. The vendor base stratifies into three tiers: heritage air-transport IT specialists, building automation conglomerates, and telecommunications infrastructure providers extending into airport-specific deployments. Dominant competitive moves include bundled service contracts spanning decade-long maintenance obligations and strategic positioning around data localization compliance architectures.
Within the heritage air-transport IT tier, SITA and Amadeus IT Group, S.A. occupy positions anchored by longstanding passenger processing system deployments. Huawei Technologies Co., Ltd. exemplifies the telecommunications-to-IoT extension archetype, leveraging infrastructure dominance into smart lighting and sensor network opportunities. These three entities represent distinct strategic vectors: legacy system integration, travel technology platforms, and communications infrastructure overlay respectively.
| Leading Market Players |
|---|
| SITA |
| Honeywell International Inc. |
| IBM |
| Amadeus IT Group, S.A. |
| Siemens AG |
| Cisco Systems, Inc. |
| Indra Sistemas, S.A. |
| Thales Group |
| Huawei Technologies Co., Ltd. |
| Others |
Supply & Pricing Matrix
Aviation-grade semiconductor price indices cascade through biometric hardware procurement tiers, compressing margins for system integrators while concentrating pricing power among algorithm licensors serving Dubai International Airport and King Abdulaziz International Airport retrofit programs.
Pricing Analysis
Warranty bundling separates decade-long maintenance obligations from hardware-only transactions across Gulf mega-hub awards. Three-tier pricing structure across premium, standard, and economy levels reflects ICAO TRIP certification grade and integration complexity. Pricing pressure stems from vendor consolidation around unified accountability contracts as Dubai Aviation Engineering Projects mandates single-source responsibility. Government agencies exhibit lowest price sensitivity due to sovereign security mandates, while African secondary airport operators defer procurement pending regulatory harmonization clarity.
Supply Chain Analysis
Freight cost volatility from East Asian component hubs inflates landed costs for facial recognition gate assemblies bound for Jeddah and Riyadh clusters. Manufacturing concentrates in China, South Korea, and Germany for biometric sensors, edge computing modules, and LED lighting systems. Supply chains draw from specialized semiconductor foundries, aviation-certified aluminum extrusions, and ICAO-compliant document readers. Single-source vulnerability persists in biometric algorithm licensing. Distribution runs through systems integrators holding GCAA and GACA certification credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from decade-long bundled service contracts is forcing discrete point-solution vendors toward acquisition or exit across the Middle-East and Africa smart airport landscape.
For Market Incumbents: Deploy certification stacking across Saudi Arabia's General Authority of Civil Aviation and UAE's GCAA frameworks to create compliance moats against European-heritage challengers. Deepen backward integration into edge computing hardware to capture margin pools currently flowing to semiconductor distributors. Anchor passenger processing contracts through SITA-style air-transport IT heritage while absorbing IoT sensor specialists to neutralize Huawei's telecommunications infrastructure extension threat. For New Entrants and Emerging Players: Computer vision analytics for baggage tracking convergence represents the most penetrable white-space wedge before Dubai International Airport and Hamad International Airport pilots harden procurement specifications. Target Nigeria's Murtala Muhammed International Airport and Kenya's Jomo Kenyatta International Airport with modular biometric-IoT architectures that defer full integration costs. Pursue ground handler asset tracking segments where regulatory mandates remain unformed and incumbent relationships are weakest. For Investors and Strategic Acquirers: Distressed-cycle entries favor integration service specialists with GACA-GCAA dual certification capabilities in South Africa's Johannesburg-Pretoria corridor. Long-term viability hinges on data localization compliance architecture ownership as cloud-based airport management platforms fragment across national jurisdictions. Monitor biometric data retention specification divergence between Saudi Arabia and UAE as the inflection signal determining which service architectures gain procurement preference.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Certification Stacking | Dual GACA-GCAA compliance creates vendor lock-in across Saudi and UAE hub expansions. |
| Edge Computing Hardware Integration | In-house sensor module production captures margin from semiconductor distributors serving retrofit programs. |
| Unified Accountability Contracting | Single-source responsibility clauses mandated by Dubai Aviation Engineering Projects eliminate discrete procurement. |
| African Secondary Hub Pre-positioning | First-mover deployments at Murtala Muhammed and Jomo Kenyatta establish reference architectures before mandates harden. |
| Data Localization Architecture Investment | Compliance-ready cloud platforms resolve tension between national sovereignty requirements and operational efficiency. |
Research Methodology
Document review covered ICAO TRIP implementation guidelines, GACA and GCAA regulatory filings, and airport operator procurement disclosures, complemented by interviews with airport IT directors, biometric systems integrators, and aviation authority certification officers. Secondary validation drew from SITA industry whitepapers, IATA operational statistics, and customs import records for biometric hardware categories. Bottom-up terminal deployment tracking and top-down regional infrastructure budget analysis were triangulated to anchor market sizing.
Installed base projections across biometric gates, IoT sensor networks, and integration service contracts were generated over the projection horizon through passenger throughput modeling, retrofit intensity scoring by terminal vintage, and regulatory mandate compliance timelines. Segmentation dimensions spanned technology maturity tier, end-user budget authority class, application operational priority, and service contract structure. CAGRs were derived from deployment pipeline aggregation and capital expenditure commitment tracking. Forecast inputs included ICAO compliance deadline schedules and mega-hub expansion phasing at Dubai International Airport and King Abdulaziz International Airport.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory harmonization failure between Saudi Arabia and UAE frameworks or prolonged African procurement deferrals. Forecasts reflect assumptions regarding biometric mandate enforcement consistency and cloud architecture standardization progress. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Technologies
Bird Detection System for Airports Market
Airport Technologies
Airport Airside Service Market
Airport Technologies
Airport Cargo Community Digital Collaboration Platforms Market
Airport Technologies
Smart Airport 4.0 Market
Airport Technologies
Asia-Pacific Smart Airport Market
Airport Technologies
North America Airport Baggage Handling Systems Market
Airport Technologies
America Airport Ground Handling Systems Market
Airport Technologies
Asia-Pacific Airport Baggage Handling Systems Market
Airport Technologies
Smart Airport 3.0 Market
Airport Technologies
Smart Baggage Handling System Market
Airport Technologies
Europe Airport Ground Handling Systems Market
Airport Technologies
Smart Airport 2.0 Market
Airport Technologies
Commercial Airport Radar Systems Market
Airport Technologies
Global Remote Towers Market
Airport Technologies
Airport Interactive Kiosk Market
Airport Technologies
Global Airport Baggage Handling System Market