
 Ground Support Equipment Market | 2026-2036
Ground Support Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Ground Support Equipment Market Intelligence
Multi-source procurement for electric tugs and ground power units is recalibrating how airport operators balance capital costs against fleet standardization. JBT Corporation leverages its installed base of passenger boarding bridges to cross-sell integrated electric ground power systems. TLD Group anchors the European market through its specialization in zero-emission baggage handling equipment with proprietary battery management architectures. Weihai Guangtai Airport Equipment Co., Ltd. competes aggressively on manufacturing scale, dominating domestic procurement cycles for China's expanding hub airports.
Ground support equipment encompasses mobile and fixed assets used to service aircraft between flights, including tow tractors rated for narrow-body and wide-body loads, 400 Hz ground power units delivering 90 kVA to 180 kVA, and deicing platforms operating at pressures exceeding 100 psi to remove frozen contaminants. The equipment ensures turnaround efficiency, regulatory compliance with airworthiness directives, and passenger safety during boarding and cargo transfer. Aircraft tugs and ground power units command the largest share of product-type revenue as fleet electrification retrofits accelerate replacement cycles across aging diesel inventories. Battery-powered technology within the propulsion category is expanding fastest, though hydraulic systems retain margin strength in heavy-lift cargo loaders where torque requirements exceed electric motor capacities.
FAA airworthiness directives and EPA Tier 4 emissions standards constrain diesel equipment eligibility in the United States, while EASA's CS-25 certification requirements and the EU Green Deal's airport decarbonization mandates reshape procurement specifications across European member states. China's GB standards for special motor vehicles and MIIT electric vehicle subsidies further bifurcate product development roadmaps between regions. Stakeholders must monitor how regulatory divergence between North American and European emissions frameworks affects platform standardization and aftermarket parts interoperability.
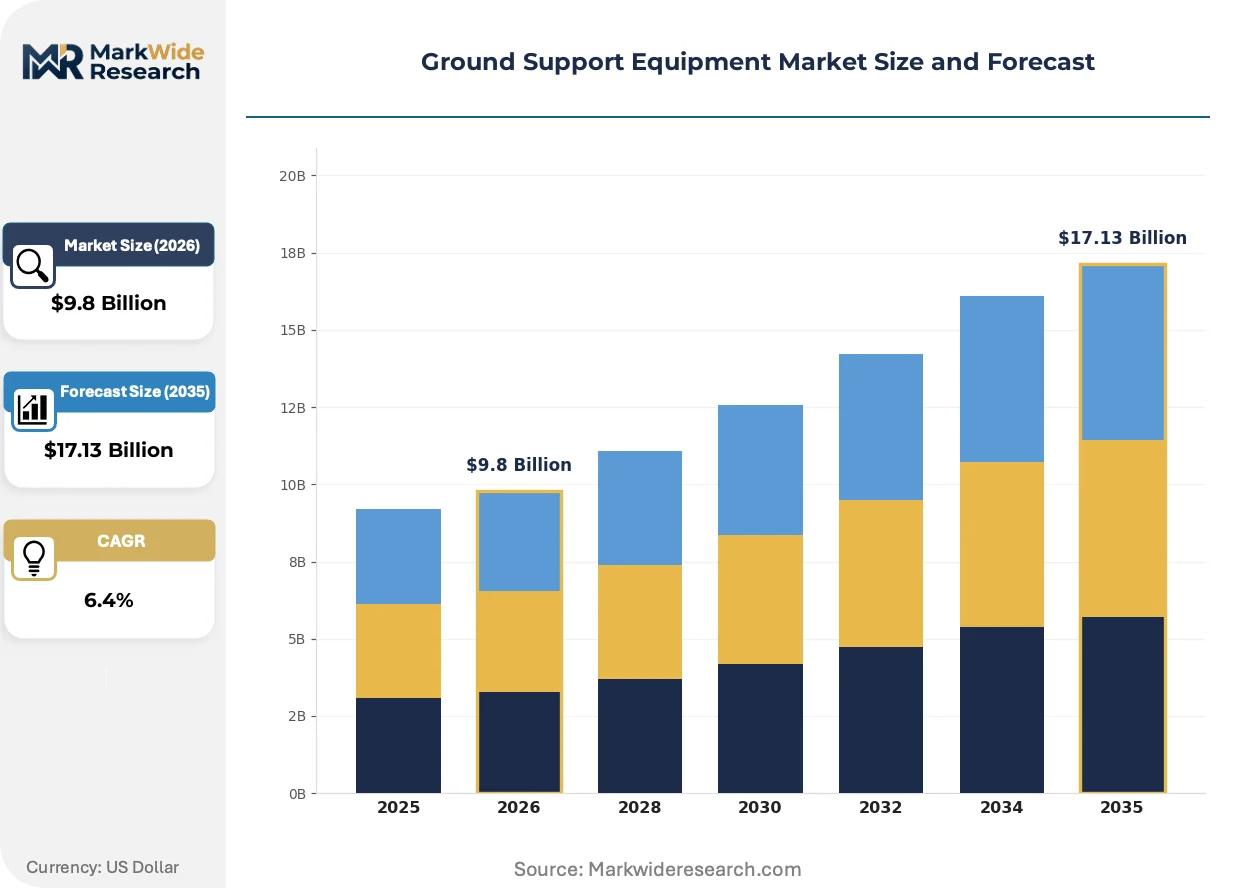
Market Dynamics
Electrification mandates from aviation regulators are compressing replacement cycles for diesel-powered tugs and ground power units, forcing airport operators to restructure capital deployment timelines and fleet standardization strategies.
Growth Catalysts
- FAA Emissions Standards:Updated EPA Tier 4 requirements for ground service vehicles are disqualifying legacy diesel equipment from US airport procurement, accelerating demand for battery-powered alternatives.
- Hub Airport Expansion:State-backed construction programs in China are generating concentrated orders for electric baggage tractors and cargo loaders at new terminal facilities.
- EU Green Deal Mandates:Airport decarbonization targets across European member states are binding ground handlers to zero-emission fleet commitments by specified deadlines.
Market Restraints
- Battery Supply Concentration:Cell manufacturing for heavy-duty ground support applications clusters in East Asian supply chains, exposing procurement to geopolitical disruption and input cost volatility.
- Technical Performance Ceilings:Electric motor torque output remains insufficient for wide-body aircraft pushback operations exceeding 400,000-pound rated loads, preserving diesel dominance in heavy-tug segments.
- Regulatory Divergence:Misaligned certification timelines between FAA airworthiness directives and EASA CS-25 requirements are fragmenting product development roadmaps and raising compliance costs.
Strategic Opportunities
- Retrofit Electrification Kits:Aftermarket battery conversion packages for existing diesel tugs represent untapped white space in North American and European installed bases.
- Autonomous Ground Operations:Convergence of LiDAR navigation systems with electric propulsion architectures enables unmanned baggage tractor deployments at tier-one hub airports.
- MIIT Subsidies:China's Ministry of Industry and Information Technology electric vehicle incentives extend to airport ground support equipment, reducing effective acquisition costs for domestic operators.
Industry Challenges
- Certification Bottlenecks:EASA CS-25 and FAA airworthiness directive approval timelines for novel battery architectures extend 18-24 months, delaying revenue recognition for new product introductions.
- Technician Reskilling:Maintenance workforces trained on hydraulic and diesel systems require retraining in high-voltage electrical safety and battery management diagnostics.
- Interoperability Friction:Proprietary charging connectors and battery management protocols from competing manufacturers prevent fleet standardization and inflate spare parts inventories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ground Support Equipment Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aircraft Tugs, Ground Power Units, Air Start Units, Baggage Carts, Deicing Equipment Technology: Hydraulic, Electric, Pneumatic, Diesel, Battery-Powered Application: Passenger Boarding, Cargo Handling, Aircraft Maintenance, Aircraft Refueling End User: Airlines, Airports, Maintenance Organizations, Cargo Operators |
| Companies Covered | Rheinmetall AG, China International Marine Containers (Group) Ltd., Textron Ground Support Equipment Inc., Cavotec SA, TCR Group, TLD Group, Weihai Guangtai Airport Equipment Co., Ltd., JBT Corporation, Oshkosh Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ground Support Equipment Market Strategic Shifts & Innovations
Solid-state battery chemistries and autonomous navigation systems are converging to redefine equipment specifications, while procurement models pivot from capital purchase toward performance-based fleet service agreements.
Solid-state lithium-metal cells are rewriting energy density benchmarks for ground support equipment, enabling 400 Hz power units to sustain 180 kVA output with 40% weight reduction versus conventional lithium-ion packs. Airport operators in the United Arab Emirates and Singapore are piloting these systems for wide-body aircraft servicing. The technology is compressing equipment footprint requirements and enabling mobile ground power architectures previously constrained by battery mass.
The EU Green Deal's airport decarbonization mandates are binding ground handlers to binding emission reduction trajectories with audited compliance reporting. Equipment lessors are restructuring contract terms to guarantee uptime metrics for electric fleets or absorb carbon penalty exposure. European hub operators at Frankfurt, Amsterdam Schiphol, and Paris Charles de Gaulle are now specifying zero-emission clauses in ground handling concession tenders.
Airport authorities are consolidating vendor relationships through multi-year fleet service agreements that transfer battery degradation risk and maintenance liability to OEMs or specialized lessors. Traditional equipment purchase with in-house maintenance is yielding to outcome-based contracts where operators pay per aircraft turnaround. This restructuring is most advanced at Middle Eastern mega-hubs and select North American network carrier facilities.
Ground Support Equipment Market Segmentation
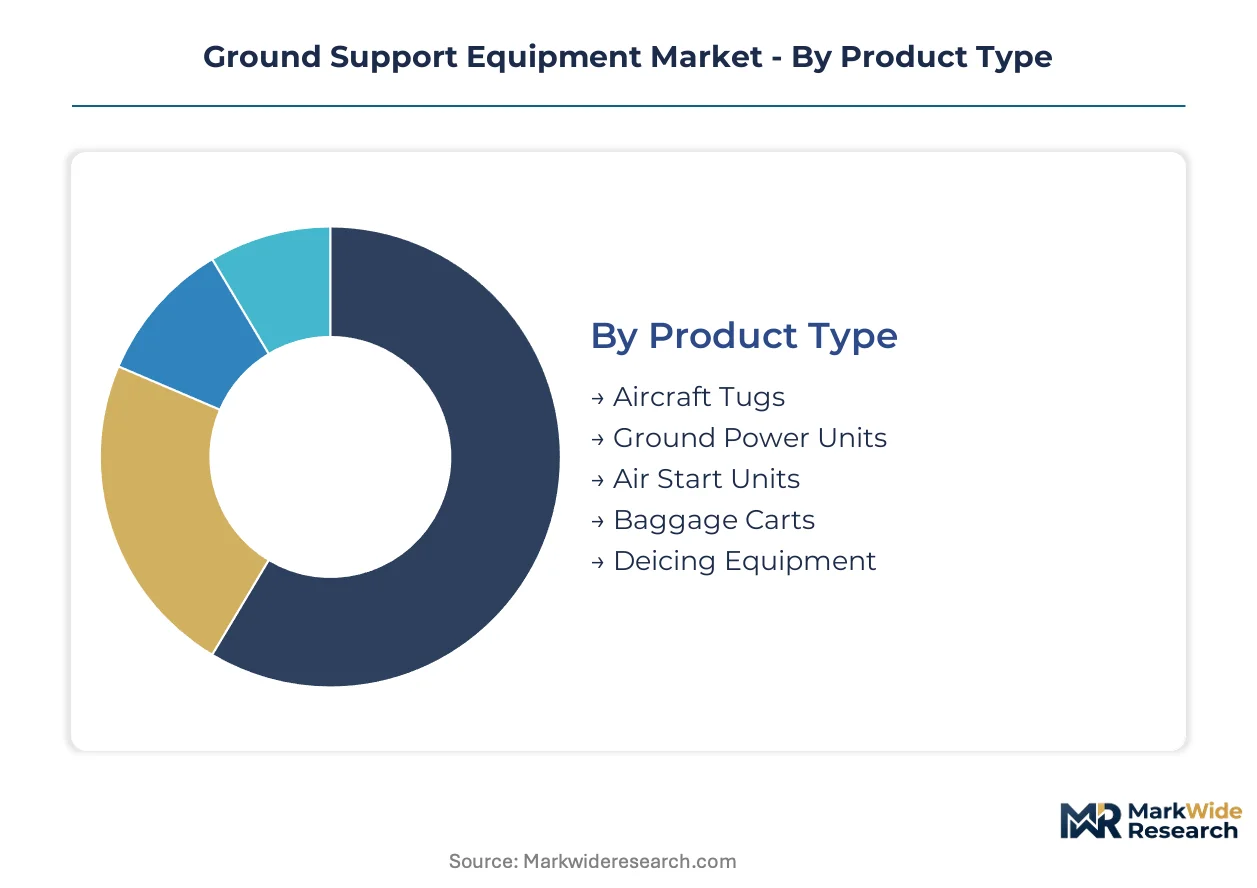
Ground support equipment procurement splits across four dimensions that reshape how OEMs allocate engineering resources and how operators structure fleet replacement cycles. Understanding these segment boundaries clarifies where electrification investments concentrate and which technology platforms retain residual demand.
Product Type:
Supply concentration for core mobile assets clusters around narrow-body pushback tractors and 90-180 kVA ground power systems, with specialized deicing platforms commanding premium margins due to lower manufacturing volumes.
- Aircraft Tugs:Rated for loads spanning 15,000-pound regional jets to 400,000-pound wide-body aircraft, these units dominate capital allocation at hub airports undergoing fleet electrification retrofits. Demand concentrates in China where state-backed airport construction programs require substantial volumes for new terminal capacity.
- Ground Power Units:400 Hz solid-state and rotary systems delivering 90 kVA to 180 kVA replace aircraft auxiliary power units during ground operations. The FAA's updated emissions standards for ground service vehicles are pushing manufacturers toward battery-powered architectures in the United States.
- Air Start Units:Pneumatic turbine starters providing compressed air for jet engine ignition, essential for aircraft types without onboard auxiliary power.
- Baggage Carts:Electric tractors and dollies handling unit load devices between terminal and aircraft, with zero-emission mandates reshaping European procurement specifications.
- Deicing Equipment:Mobile and fixed platforms operating at pressures exceeding 100 psi to remove frozen contaminants, requiring specialized high-capacity pumps and heated fluid systems.
Today's leader: Aircraft Tugs. Tomorrow's challenger: Ground Power Units.
Technology:
Cost tier stratification separates mature hydraulic and diesel platforms from emerging electric architectures, with battery-powered systems capturing premium pricing despite higher upfront acquisition costs.
- Battery-Powered:Lithium-ion and solid-state lithium-metal cells enabling zero-emission operation with 40% weight reduction versus conventional packs. Airport operators in the United Arab Emirates and Singapore are piloting these systems for wide-body aircraft servicing.
- Electric:Grid-connected or battery-electric motor drives for light-duty baggage handling and passenger boarding bridges, expanding fastest where regulatory mandates compress replacement timelines.
- Hydraulic:High-torque systems retaining margin strength in heavy-lift cargo loaders where electric motor output remains insufficient for rated loads.
- Diesel:EPA Tier 4-compliant and legacy engines facing procurement disqualification at US airports under updated FAA emissions standards.
- Pneumatic:Compressed air systems for specialized air start and braking applications, maintaining niche demand in retrofit-installed bases.
Battery-Powered architectures are climbing the fastest; Diesel retains residual share only where torque requirements exceed electric motor capacities.
Application:
Volume concentration tracks aircraft turnaround frequency, with passenger boarding and cargo handling commanding the largest equipment fleets per airport gate position.
- Passenger Boarding:Passenger boarding bridges, air stairs, and electric ground power integration ensuring regulatory compliance with airworthiness directives and passenger safety during embarkation.
- Cargo Handling:Heavy-lift loaders, transporters, and container dollies where hydraulic systems retain technical performance advantages for wide-body freight operations.
- Aircraft Maintenance:Maintenance platforms, engine hoists, and test equipment requiring EASA CS-25 certification alignment for European operator acceptance.
- Aircraft Refueling:Hydrant dispensers and mobile refuelers operating under strict fire safety and spill containment protocols.
Passenger Boarding generates the highest unit volumes; Cargo Handling sustains the steepest margin premiums.
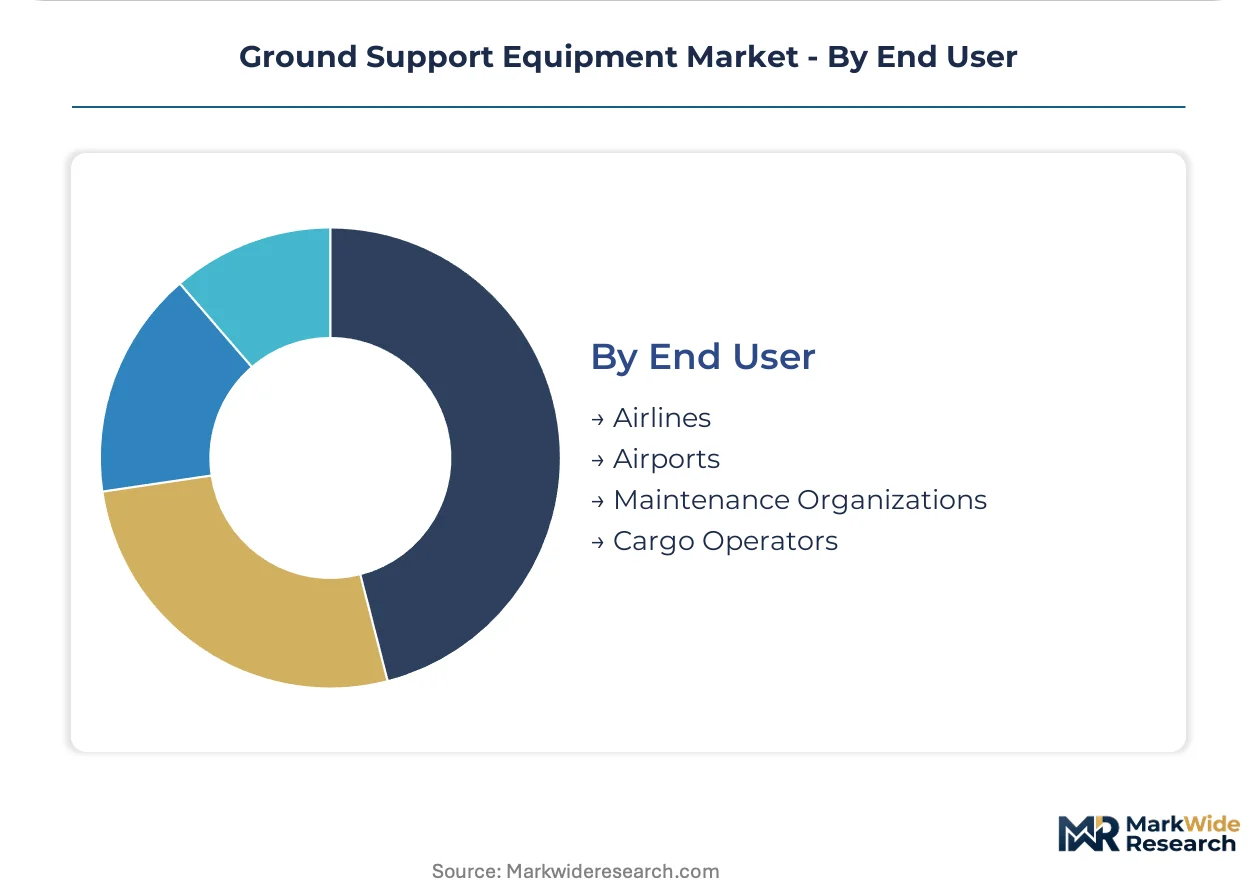
End User:
Customer type determines procurement authority structure, with airport authorities consolidating vendor relationships through multi-year fleet service agreements that transfer operational risk to OEMs.
- Airports:Terminal operators specifying zero-emission clauses in ground handling concession tenders at European hubs including Frankfurt, Amsterdam Schiphol, and Paris Charles de Gaulle.
- Airlines:Network carriers restructuring capital deployment timelines around fleet standardization strategies for hub-and-spoke operations.
- Cargo Operators:Express integrators and freight forwarders prioritizing turnaround efficiency over emission compliance in secondary markets.
- Maintenance Organizations:Third-party and in-house MRO providers requiring specialized platforms for airworthiness directive compliance and heavy maintenance checks.
Airports currently dominate procurement volume; Maintenance Organizations are expanding fastest as outsourced MRO contracts proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between EPA Tier 4 mandates and EU Green Deal decarbonization timelines is creating cost-of-compliance arbitrage, with manufacturers relocating final assembly to jurisdictions where certification burdens and emission thresholds impose lighter capital requirements.
United States
FAA airworthiness directives and EPA Tier 4 emissions standards are disqualifying legacy diesel tugs from airport procurement, forcing ground handlers to accelerate replacement cycles. The FAA's updated ground service vehicle regulations are compressing capital deployment timelines for fleet electrification. Dallas-Fort Worth International Airport and Atlanta Hartsfield-Jackson are consolidating vendor relationships through multi-year fleet service agreements that transfer battery degradation risk to OEMs.
China
State-backed airport construction programs are generating concentrated orders for electric baggage tractors and cargo loaders at new terminal facilities. MIIT electric vehicle subsidies extend to airport ground support equipment, reducing effective acquisition costs for domestic operators. Weihai Guangtai Airport Equipment Co., Ltd. dominates procurement cycles at Beijing Daxing and Chengdu Tianfu International Airport through manufacturing scale advantages.
Germany
EASA CS-25 certification requirements and the EU Green Deal's airport decarbonization mandates are binding ground handlers to zero-emission fleet commitments with audited compliance reporting. Frankfurt Airport and Munich Airport are specifying zero-emission clauses in ground handling concession tenders. Rheinmetall AG leverages defense-sector battery management expertise to cross-sell into commercial aviation ground power systems.
United Arab Emirates
Airport operators in Dubai and Abu Dhabi are expanding fleets of electric baggage tractors and ground power units to support new terminal capacity at Al Maktoum International and Zayed International Airport. The country's civil aviation regulator aligns with EASA frameworks while offering accelerated certification pathways for solid-state battery architectures. Emirates Flight Catering and dnata are piloting autonomous baggage tractor deployments with LiDAR navigation integration.
Singapore
Changi Airport Group is retrofitting existing gate positions with integrated electric ground power systems to meet 2030 sustainability targets under the national Green Plan. The Civil Aviation Authority of Singapore mandates emission disclosure for ground handling concessions, creating procurement preference for battery-powered equipment. SATS Ltd. and dnata Singapore are restructuring contracts to guarantee uptime metrics for electric fleets or absorb carbon penalty exposure.
Ground Support Equipment Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue solid-state battery architectures and autonomous navigation capabilities as differentiation vectors. The vendor base stratifies across three tiers: diversified industrial conglomerates with aviation divisions, specialized ground support equipment manufacturers with proprietary battery management systems, and regional fabricators competing on manufacturing scale and domestic procurement relationships. Dominant competitive moves include backward integration into battery cell supply chains and strategic partnerships with airport operators for outcome-based fleet service agreements.
Within the diversified industrial tier, Rheinmetall AG and Textron Ground Support Equipment Inc. exemplify players leveraging defense and aerospace manufacturing expertise to cross-sell into commercial aviation ground support. Among specialized manufacturers, TLD Group and JBT Corporation occupy positions defined by zero-emission product portfolios and installed base cross-selling opportunities. Weihai Guangtai Airport Equipment Co., Ltd. represents the scale-driven archetype, anchoring domestic procurement cycles through manufacturing cost advantages at China's expanding hub airports.
| Leading Market Players |
|---|
| Rheinmetall AG |
| China International Marine Containers (Group) Ltd. |
| Textron Ground Support Equipment Inc. |
| Cavotec SA |
| TCR Group |
| TLD Group |
| Weihai Guangtai Airport Equipment Co., Ltd. |
| JBT Corporation |
| Oshkosh Corporation |
| Others |
Cost & Logistics Intelligence
Backward integration into battery cell manufacturing anchors both supply security and margin control for ground support equipment OEMs facing volatile lithium-ion input costs. This upstream positioning allows manufacturers to buffer pricing power against East Asian cell supply concentration while airport operators absorb residual volatility through multi-year fleet service agreements.
Pricing Analysis
Distributor margins for ground support equipment compress as direct procurement from OEMs expands among airport authorities consolidating vendor relationships. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and after-sales service bundling, with EPA Tier 4-compliant electric architectures commanding premium positioning. Pricing pressure stems from MIIT subsidy eligibility in China reducing effective acquisition costs for domestic operators. Cargo operators in secondary markets exhibit highest price sensitivity, while Middle Eastern mega-hubs prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Regional distribution centers in Germany, the United Arab Emirates, and Singapore feed hub-and-spoke patterns serving airport clusters across their respective regions. Cell manufacturing for heavy-duty applications clusters in China, South Korea, and Japan, drawing from cobalt, lithium, and nickel feedstocks subject to commodity price volatility. Single-source vulnerability in solid-state electrolyte production poses structural risk as OEMs pivot toward next-generation battery architectures. Distribution runs through specialized aviation equipment lessors who bundle maintenance liability with equipment delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ground support equipment market functions as a stable compounder, with regulatory electrification mandates driving predictable replacement cycles across aging diesel installed bases.
For Market Incumbents: Deploy proprietary battery management architectures as the defensive lever against emerging solid-state specialists threatening technical differentiation. TLD Group and JBT Corporation should deepen captive supply of lithium-metal cells to secure input cost predictability, while accelerating EASA CS-25 certification pipelines to outpace regulatory divergence between European and North American frameworks. For New Entrants and Emerging Players: Ground handling concessionaires at European hubs represent the most penetrable channel partner type for autonomous navigation system integrators lacking established aviation relationships. White-space targets include retrofit electrification kits for North American diesel tug installed bases and solid-state ground power units for wide-body servicing at Middle Eastern mega-hubs. A go-to-market angle through outcome-based fleet service agreements bypasses capital procurement barriers at budget-constrained secondary airports. For Investors and Strategic Acquirers: Consolidation pressure builds where proprietary charging protocols fragment fleet interoperability and inflate spare parts inventories across multi-vendor airport operations. The five-to-ten-year viability window favors specialized manufacturers with captive battery architectures over diversified industrial conglomerates exposed to defense procurement cyclicality. Acquisition target archetypes include autonomous navigation software developers with LiDAR integration capabilities and regional service networks with maintenance technician reskilling infrastructure. The signal to watch is EASA-FAA regulatory harmonization timelines that would collapse fragmented product development roadmaps and reward scale players with unified certification platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Battery Integration | Enables 40% weight reduction for 180 kVA ground power units at Dubai and Singapore hubs. |
| Autonomous Navigation Deployment | LiDAR-enabled baggage tractors reduce labor costs at tier-one airports undergoing capacity expansion. |
| Retrofit Electrification Kits | Aftermarket conversion packages unlock North American diesel installed base replacement demand. |
| Fleet Service Agreement Restructuring | Outcome-based contracts transfer battery degradation risk from airport operators to OEMs. |
| Technician Reskilling Programs | High-voltage electrical safety certification addresses maintenance workforce transition gaps. |
Research Approach
Bottom-up airport operator procurement modeling reconciled against top-down OEM production tracking forms the analytical core of this study. Primary interviews with fleet managers at hub airports, ground handling concession directors, maintenance organization technical leads, and aviation authority certification officers combined with secondary validation from FAA airworthiness directive filings, EASA CS-25 certification databases, MIIT subsidy disclosure records, and airport construction procurement announcements. This dual-layer approach triangulates demand signals against supply-side capacity commitments.
Input-output matrices map equipment unit demand across product type, propulsion architecture, application, and end-user segments over the projection horizon. Modeled dimensions include aircraft size class, regulatory compliance tier, ground handling function, and customer procurement authority structure. CAGRs derive from regression analysis against airport passenger traffic forecasts and fleet electrification mandate timelines, with solid-state battery adoption curves and autonomous navigation penetration rates serving as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EASA-FAA regulatory harmonization delays and East Asian cell supply chain disruptions. Outputs reflect documented assumptions around electrification subsidy continuity and certification timeline stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Infrastructure
Airport Moving Walkways Market
Airport Infrastructure
Airport Passenger Boarding Bridge Market
Airport Infrastructure
Jet Bridge Market
Airport Infrastructure
Aviation Infrastructure Market
Airport Infrastructure
Aircraft Cargo Handling Equipment Market
Airport Infrastructure
North America Aviation Infrastructure Market
Airport Infrastructure
India Aviation Infrastructure Market
Airport Infrastructure
Asia-Pacific Aviation Infrastructure Market
Airport Infrastructure
Airport Kiosk Market
Airport Infrastructure
Airport Ground Support Equipment Market
Airport Infrastructure
Europe Airport Baggage Handling Systems Market
Airport Infrastructure
Aircraft Tow Tractors Market
Airport Infrastructure
South-East Asia Aviation Infrastructure Market
Airport Infrastructure
Passenger Boarding Bridge Market
Airport Infrastructure
GCC Aviation Infrastructure Market
Airport Infrastructure
Engineered Material Arresting System Market