
 Ground Handling Systems Market | 2026-2036
Ground Handling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Ground Handling Systems Market Analytics
Aluminum-intensive chassis construction is pivoting toward carbon-fiber-reinforced polymer composites in next-generation pushback tractors to cut tare weight and extend battery range. Menzies Aviation leverages its global station network to standardize electric ground support equipment procurement across continents. Swissport International AG anchors its competitive position through vertical integration into in-house technical training academies for ground handling crews. Weihai Guangtai Airport Equipment dominates manufacturing scale in the Asia-Pacific supply base for conventional diesel tugs.
Ground handling systems encompass the motorized, towed, and fixed infrastructure used to service aircraft during turnaround intervals, including tugs rated to 70-ton drawbar pull, 400 Hz solid-state ground power units, and belt loaders with 30-foot reach envelopes. These systems enable safe aircraft positioning, cargo transfer, passenger boarding, and auxiliary power substitution while jet engines remain shut down. Electric systems are capturing the fastest expansion as airports face Scope 1 emissions targets and jet fuel price volatility, though conventional systems still occupy the largest installed base due to capital inertia at regional airports. Ramp services generate the deepest margin pools because turnaround-time penalties directly link to airline on-time performance contracts.
The FAA mandates Part 139 airport certification standards that dictate ground equipment fire suppression and marking protocols, while the EU Green Deal's sustainable aviation fuel corridors pressure airports to electrify their entire ground fleets. ISO 6966 and IATA AHM 913 establish interoperability benchmarks for towbarless tractor couplings and ground power connectors that determine vendor market access. Stakeholders must weigh retrofit economics against fleet replacement timelines as battery energy density improvements and hydrogen fuel cell trials reshape total-cost-of-ownership calculations for ground support equipment procurement committees.
Market Dynamics
Electrification of airport ground fleets is compressing equipment replacement cycles as battery energy density improvements and hydrogen fuel cell trials reshape capital planning committees' total-cost-of-ownership calculations for pushback tractors and belt loaders.
Growth Catalysts
- EU F-Gas Regulation:This mandate accelerates fluorinated greenhouse gas phase-out in ground support equipment, forcing airports toward electric alternatives and expanding addressable market for zero-emission tugs.
- India airport privatization:Fleet expansion by domestic carriers intensifies ground handling capacity needs across privatized terminals, creating equipment procurement surges at Delhi, Mumbai, and Bangalore airports.
- Carbon-fiber-reinforced polymer composites:Next-generation pushback tractors adopt CFRP chassis construction to cut tare weight and extend battery range, enabling heavier aircraft handling with smaller powertrains.
Market Restraints
- Lithium supply concentration:Battery raw material sourcing clusters in limited geographies, exposing electric ground support equipment manufacturers to price volatility and geopolitical supply disruptions.
- Regional airport capital inertia:Smaller facilities delay fleet electrification due to upfront equipment costs and charging infrastructure requirements, slowing market penetration outside major hubs.
- Legacy diesel tug installed base:Functional conventional equipment at mid-tier airports extends replacement timelines, compressing near-term demand for electric alternatives despite regulatory pressure.
Strategic Opportunities
- Hydrogen fuel cell trials:Ground handling equipment manufacturers pilot fuel cell powertrains for heavy-duty tugs, opening white space beyond battery-electric limitations for ultra-heavy aircraft positioning.
- Scope 1 emissions targets:Airline sustainability commitments pressure airports to electrify entire ground fleets, creating bundled procurement opportunities across multiple equipment categories simultaneously.
- Technical training academies:In-house crew certification programs for electric ground support equipment operation and maintenance create recurring revenue streams and customer lock-in for service providers.
Industry Challenges
- ISO 6966 and IATA AHM 913 compliance:Towbarless tractor coupling and ground power connector interoperability benchmarks demand extensive testing, extending product development timelines and certification costs.
- Legacy system integration:Electric tugs must interface with existing aircraft towbar configurations and 400 Hz ground power infrastructure, complicating fleet transition planning for airport operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ground Handling Systems Market |
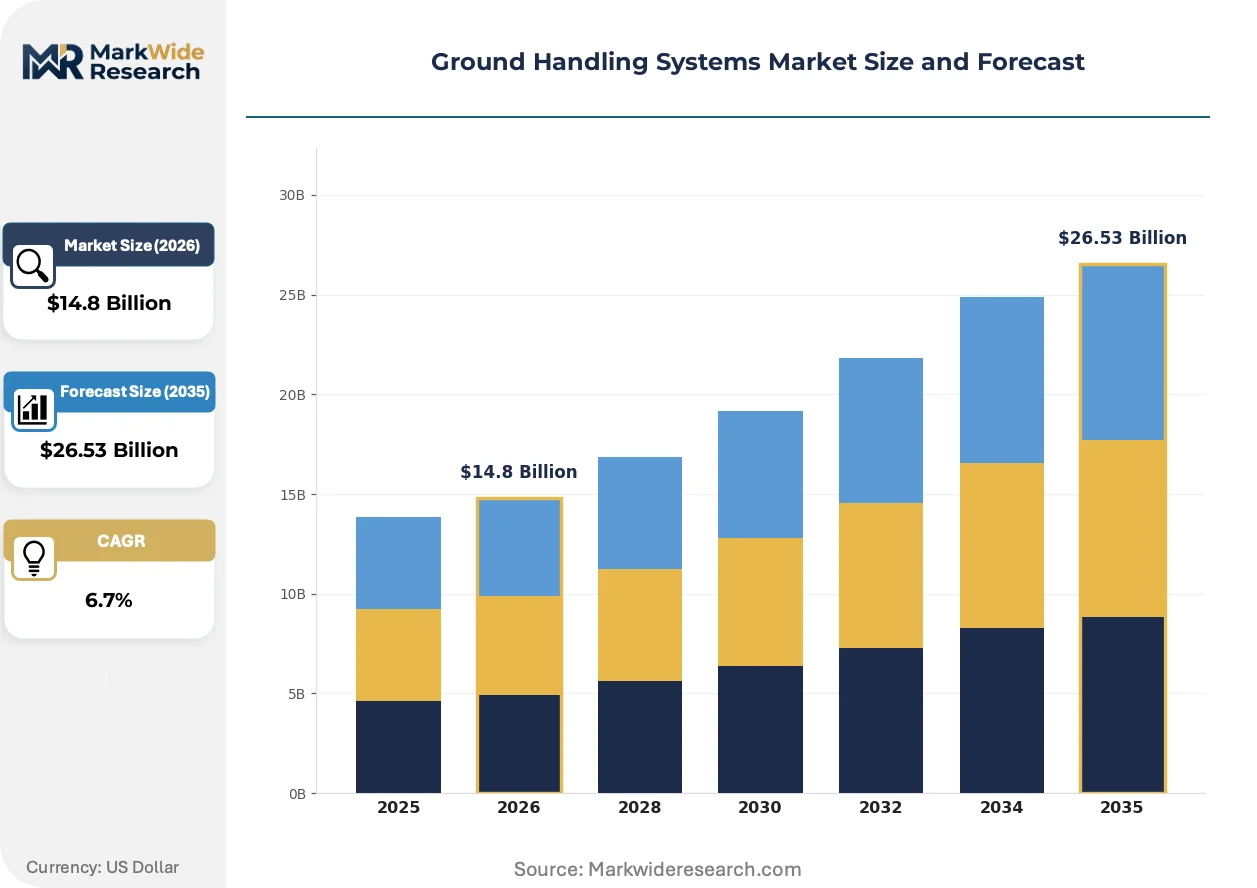
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aircraft Tugs, Baggage Tractors, Pushback Tractors, Ground Power Units Service Type: Ramp Services, Cargo Handling, Passenger Services, Aircraft Maintenance End User: Airlines, Airports, Ground Service Providers, Freight Operators Technology: Automated Systems, Conventional Systems, Electric Systems, Hybrid Systems |
| Companies Covered | Menzies Aviation, Oshkosh Corporation, Swissport International AG, China International Marine Containers, TCR Group, Dnata, Aviapartner, Weihai Guangtai Airport Equipment, Worldwide Flight Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ground Handling Systems Market Evolving Landscape
Ground handling equipment is undergoing material and powertrain transformation as weight reduction targets collide with electrification mandates, reshaping competitive positioning among chassis manufacturers and battery system suppliers.
Solid-state battery chemistry is integrating into next-generation electric tugs, replacing conventional lithium-ion packs to achieve higher energy density and faster charging intervals. Airport operators in Germany and the Netherlands are piloting these systems for narrow-body aircraft pushback operations. This integration is compressing turnaround time windows and enabling heavier aircraft handling without diesel backup systems.
The EU Green Deal's sustainable aviation fuel corridors pressure airports to demonstrate ground fleet decarbonization alongside jet fuel substitution. European hub operators respond by bundling electric ground support equipment procurement with renewable energy contracts. Belt loader and cargo loader segments face the steepest compliance timelines due to their high utilization rates.
Airline procurement committees now unbundle after-sales service contracts from equipment purchases, selecting specialized maintenance providers independent of original manufacturers. This fragmentation is visible across Middle Eastern mega-hub airports where long-term service agreements now span multiple vendor relationships. Third-party technical training providers capture margin pools previously held by equipment OEMs.
Ground Handling Systems Market Segmentation
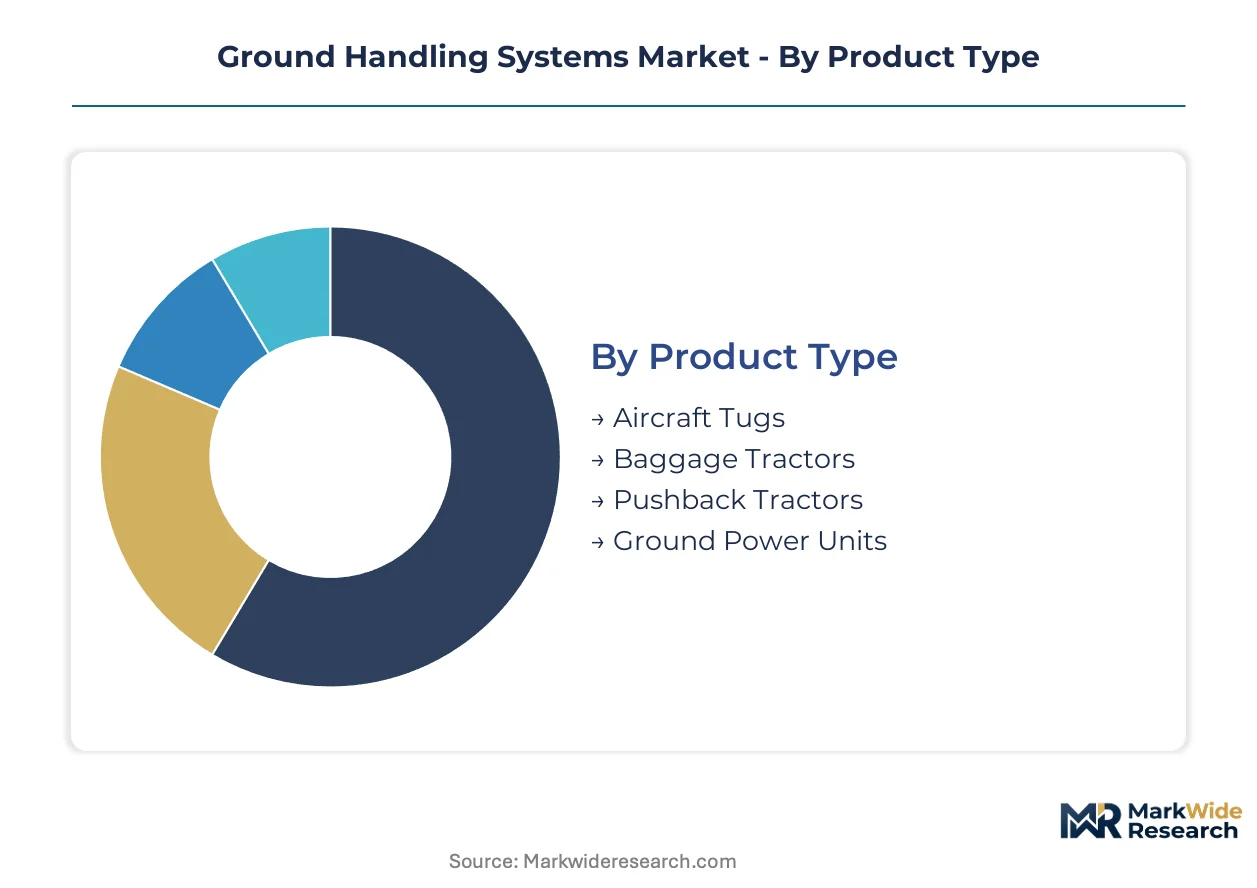
Ground handling equipment procurement committees segment purchases by duty cycle intensity and regulatory exposure, not just aircraft compatibility. Understanding these splits clarifies why electric powertrains penetrate baggage tractors faster than pushback tractors despite similar technical maturity.
Product Type:
Volume sales concentrate in lighter-duty equipment for narrow-body fleets, while premium pricing attaches to heavy-drawbar tractors serving wide-body positioning.
- Aircraft Tugs:General-purpose diesel and electric tractors rated to 35-ton drawbar pull handle narrow-body repositioning and short-haul fleet support. Demand clusters at Indian privatized airports where Indigo and SpiceJet expansion drives procurement surges for A320-family handling.
- Pushback Tractors:Heavy-duty units rated to 70-ton drawbar pull with towbarless couplings serve Boeing 777 and A350 positioning. European hub operators under EU F-Gas Regulation pressure pilot carbon-fiber chassis variants to extend battery range for these energy-intensive operations.
- Baggage Tractors:Low-speed utility vehicles with 5,000-pound cargo deck capacity shuttle luggage between terminal and aircraft.
- Ground Power Units:400 Hz solid-state and diesel rotary units substitute auxiliary power during engine-off turnaround intervals.
Mature deployment sits with Ground Power Units. Newer deployment is concentrated in Pushback Tractors.
Service Type:
Margin pools vary by contractual linkage to airline on-time performance penalties, with ramp-facing services commanding premium pricing over back-of-house functions.
- Ramp Services:Aircraft positioning, power provision, and cooling directly interface with turnaround-time guarantees in airline-ground handler contracts. Swissport and Menzies Aviation bundle electric equipment procurement across these services to meet Scope 1 emissions targets at London Heathrow and Amsterdam Schiphol.
- Cargo Handling:Belt loaders, cargo loaders, and container dollies face the steepest electrification timelines under EU Green Deal corridor mandates due to high utilization rates at express freight hubs.
- Passenger Services:Passenger boarding bridges, stairs, and buses operate at lower duty cycles with less regulatory pressure.
- Aircraft Maintenance:Hydraulic mules, nitrogen carts, and maintenance platforms serve hangar-based MRO operations with extended equipment lifecycles.
Revenue concentration pools in Ramp Services. Technology refresh is accelerating fastest in Cargo Handling.
End User:
Procurement authority splits between asset-owning airports and outsourced ground handlers, reshaping vendor sales cycles and service contract structures.
- Airlines:Legacy carriers with in-house ground operations at hub airports specify equipment interoperability standards. Lufthansa and Air France-KLM procurement committees unbundle maintenance contracts from equipment purchases, fragmenting vendor relationships.
- Ground Service Providers:Third-party handlers like Swissport International AG standardize electric fleet procurement across global station networks to achieve scale economies in training and spare parts.
- Airports:Municipal and privatized terminal operators specify fire suppression and marking protocols under FAA Part 139 or equivalent national certification standards.
- Freight Operators:Express carriers and integrators operate dedicated cargo ramps with specialized equipment configurations.
Consolidated purchasing sits with Ground Service Providers. Fragmented procurement characterizes Airline direct purchasing.
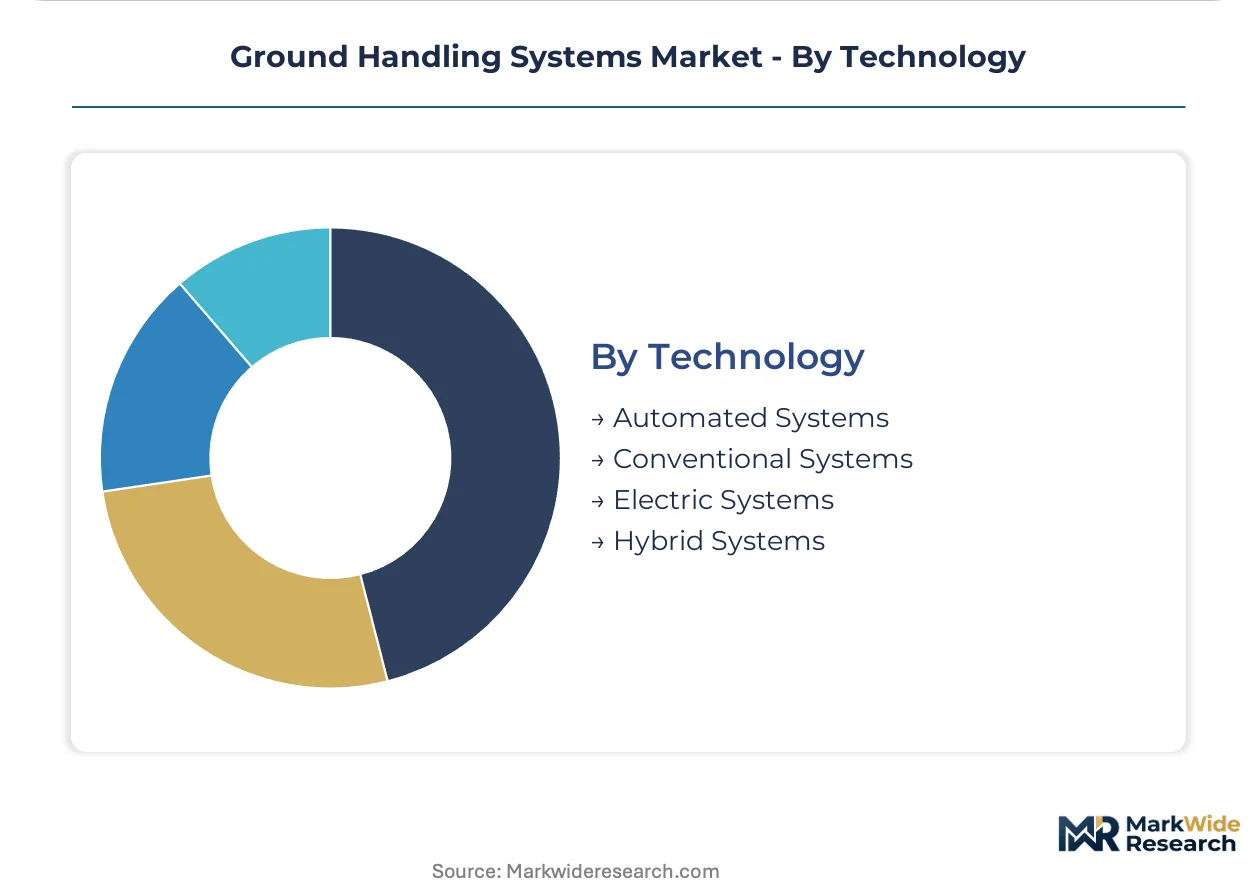
Technology:
Capital allocation shifts between retrofit economics and fleet replacement as battery energy density improvements and hydrogen trials reshape total-cost-of-ownership calculations.
- Electric Systems:Battery-electric tugs and belt loaders with lithium-ion or solid-state packs capture the steepest expansion trajectory as airports face Scope 1 emissions targets. German and Dutch hub operators pilot solid-state chemistry for narrow-body pushback to compress turnaround windows.
- Hybrid Systems:Diesel-electric powertrains with onboard generation serve as transition architecture for regional airports with charging infrastructure constraints.
- Conventional Systems:Diesel-powered equipment retains the largest installed base due to capital inertia at mid-tier airports.
- Automated Systems:Autonomous tugs with optical guidance and aircraft docking sensors remain in limited trial deployment.
Installed base dominance rests with Conventional Systems. Steepest expansion trajectory belongs to Electric Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in the United Arab Emirates concentrate ground handling procurement authority for Middle Eastern hub expansion. These zones attract fleet operators seeking tax-efficient equipment staging points for cross-regional deployment.
United States
FAA Part 139 certification standards mandate fire suppression and marking protocols for ground equipment at commercial airports. Major carriers at Dallas-Fort Worth and Atlanta Hartsfield-Jackson drive electric tug trials as Scope 1 emissions targets tighten. California airports lead hydrogen fuel cell pilot programs for heavy-duty pushback operations.
Germany
The EU F-Gas Regulation accelerates fluorinated greenhouse gas phase-out in ground support equipment, forcing Frankfurt and Munich airports toward electric alternatives. German hub operators pilot solid-state battery chemistry in narrow-body pushback tractors. The Rhine-Main region concentrates technical training academy investments for electric fleet certification.
India
Airport privatization at Delhi, Mumbai, and Bangalore intensifies ground handling capacity needs as Indigo and SpiceJet expand narrow-body fleets. The PLI scheme incentivizes domestic manufacturing of electric ground support equipment. Gujarat and Maharashtra industrial corridors attract assembly operations for battery-powered baggage tractors.
United Arab Emirates
Dubai South free zone and Abu Dhabi Khalifa Industrial Zone concentrate procurement authority for ground handling fleet standardization. The country's aviation regulator mandates interoperability benchmarks for towbarless tractor couplings. Dubai International Airport anchors hydrogen fuel cell trials for ultra-heavy aircraft positioning equipment.
Netherlands
Amsterdam Schiphol's EU Green Deal corridor commitments pressure full ground fleet electrification alongside sustainable aviation fuel adoption. Dutch airport operators bundle electric ground support equipment procurement with renewable energy contracts. The Randstad region hosts solid-state battery integration trials for 70-ton drawbar pull pushback tractors.
Ground Handling Systems Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated service providers capturing bundled procurement contracts while equipment fabricators compete on technical specifications. The vendor base concentrates around three strategic archetypes: global ground handling service providers with captive equipment fleets, specialized airport equipment manufacturers with regional manufacturing footprints, and diversified industrial conglomerates with aerospace divisions. Competitive moves center on fleet standardization across global station networks and backward integration into battery system supply.
Among global service providers, Menzies Aviation and Swissport International AG exemplify the fleet-standardization archetype through multi-continent equipment procurement coordination. Weihai Guangtai Airport Equipment Co., Ltd. anchors the Asia-Pacific manufacturing base for conventional diesel tug supply. These three entities represent distinct competitive positions: service-led consolidation, manufacturing scale, and regional supply concentration respectively.
| Leading Market Players |
|---|
| Menzies Aviation |
| Oshkosh Corporation |
| Swissport International AG |
| China International Marine Containers |
| TCR Group |
| Dnata |
| Aviapartner |
| Weihai Guangtai Airport Equipment |
| Worldwide Flight Services |
| Others |
Value Network & Pricing Analysis
The EU F-Gas Regulation gates qualified supply for zero-emission ground support equipment and premium-tier pricing access for electric tugs certified to ISO 6966 and IATA AHM 913 interoperability benchmarks. Buyers face bifurcated sourcing landscapes where F-Gas-compliant electric systems command structural premiums over conventional diesel alternatives.
Pricing Analysis
Short lead-time premiums attach to carbon-fiber-reinforced polymer chassis pushback tractors with solid-state battery packs, while spot inventory of conventional lithium-ion systems trades at modest discounts. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Cost compression in mid-tier electric baggage tractors is intensifying because battery cell oversupply from Asian manufacturers feeds price competition. Regional airport operators exhibit highest price sensitivity due to capital constraints, whereas European hub operators under EU Green Deal mandates demonstrate lowest sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with lithium carbonate and cobalt hydroxide processing concentrated in China, South Korea, and the Democratic Republic of Congo. Battery pack assembly draws from these geographies while carbon-fiber prepreg sourcing rests on Japanese and German specialty chemical producers. Tariff exposure on Chinese battery components threatens cost structures for European and North American equipment assemblers. Distribution runs through ground service provider fleet procurement committees and airport authority capital expenditure programs rather than aftermarket retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a consolidation play as EU F-Gas Regulation compliance costs and charging infrastructure investments force smaller regional equipment lessors into distressed exit scenarios.
For Market Incumbents: Deploy backward integration into solid-state battery cell supply to secure energy density advantages for 70-ton drawbar pull pushback tractors. Incumbents must standardize electric fleet configurations across global station networks before hydrogen fuel cell trials by Dubai International Airport and Amsterdam Schiphol establish alternative powertrain standards. Certification investment in IATA AHM 913 interoperability testing creates switching costs against emerging Asian manufacturers. For New Entrants and Emerging Players: Direct-to-ground-handler digital procurement platforms offer route-to-market bypassing incumbent OEM service bundling. New entrants should target Indian privatized airports at Delhi, Mumbai, and Bangalore where PLI scheme incentives for domestic electric ground support equipment manufacturing create white-space procurement surges. Narrow-body aircraft tug segments with A320-family compatibility requirements present lowest certification barriers. For Investors and Strategic Acquirers: Dubai International Airport's hydrogen fuel cell pilot program for ultra-heavy aircraft positioning is the leading indicator that powertrain technology inflection will reshape equipment residual values and leasing economics. Long-term viability over the next decade hinges on exposure to European hub electrification mandates rather than regional airport diesel replacement cycles. Acquisition targets should display captive technical training academy capabilities and multi-continent service contracts with Menzies Aviation or Swissport International AG network coverage.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Battery Integration | German and Dutch hub operators pilot this chemistry to compress narrow-body pushback turnaround windows without diesel backup. |
| Carbon-Fiber Chassis Adoption | European pushback tractor manufacturers leverage CFRP construction to extend battery range for heavy-drawbar operations under EU F-Gas pressure. |
| Technical Training Academy Expansion | Swissport International AG anchors competitive position through in-house crew certification programs for electric ground support equipment operation. |
| Hydrogen Fuel Cell Trials | Dubai International Airport pilots this powertrain for ultra-heavy aircraft positioning beyond battery-electric limitations. |
| Procurement Committee Unbundling | Lufthansa and Air France-KLM fragment vendor relationships by separating maintenance contracts from equipment purchases. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this ground handling systems analysis. Primary interviews with airport procurement directors, ground handling fleet managers, electric vehicle battery system engineers, and ground support equipment maintenance heads combined with IATA operational statistics, FAA Part 139 certification databases, EU F-Gas Regulation implementation reports, and Indian PLI scheme disclosure filings. Bottom-up equipment unit economics triangulated against top-down airport capital expenditure surveys.
Data-stream reconciliation across shipment volumes, installed base estimates, and replacement cycle assumptions structured the analytical framework. Segmentation dimensions modeled include product type, service category, end-user procurement authority, and powertrain technology across the analysis window. CAGRs derived from logistic diffusion curves for electric powertrain penetration and hydrogen fuel cell pilot program scaling assumptions. Industry-specific inputs incorporated EU Green Deal corridor compliance timelines and Indian airport privatization capex schedules.
The model holds under sustained EU F-Gas Regulation enforcement and lithium supply chain stability; deviation in battery raw material geopolitics or hydrogen infrastructure deployment would shift equipment replacement trajectories. Forecasts reflect documented assumptions regarding narrow-body fleet expansion rates and Scope 1 emissions target stringency. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Infrastructure
Airport Moving Walkways Market
Airport Infrastructure
Aviation Infrastructure Market
Airport Infrastructure
Airport Logistics Systems Market
Airport Infrastructure
North America Aviation Infrastructure Market
Airport Infrastructure
Airport Ground Support Equipment Market
Airport Infrastructure
Aircraft Catering Vehicle Market
Airport Infrastructure
Europe Airport Baggage Handling Systems Market
Airport Infrastructure
Asia-Pacific Aviation Infrastructure Market
Airport Infrastructure
Airport Services Market
Airport Infrastructure
Ground Support Equipment Market
Airport Infrastructure
Aircraft Tow Tractors Market
Airport Infrastructure
South-East Asia Aviation Infrastructure Market
Airport Infrastructure
Jet Bridge Market
Airport Infrastructure
Telescopic Masts Market
Airport Infrastructure
Global Green Airport Market
Airport Infrastructure
GCC Aviation Infrastructure Market