
 Middle-East and Africa Airport Ground Handling Systems Market | 2026-2036
Middle-East and Africa Airport Ground Handling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Airport Ground Handling Systems Market Foresight
ISO 9001 quality management certification is unwinding the competitive landscape for ground handling equipment suppliers across the Middle-East and Africa. Siemens AG leverages its automation portfolio to dominate intelligent baggage conveyor deployments in Dubai and Riyadh. Cavotec SA anchors its position through captive supply of advanced electrical ground power units for major hub airports. Alvest SAS specializes in towbarless aircraft tractors, competing on manufacturing scale against regional assemblers.
Middle-East and Africa airport ground handling systems encompass motorized and fixed infrastructure used to service aircraft during turnaround, including belt loaders with 500-kg payload capacity, cargo dollies rated for 15-tonne loads, and preconditioned air units delivering 110 tons per hour of cooled airflow. Baggage Handling systems command the largest installed base across the region's megahubs, though Automated Systems within the technology dimension represent the fastest-expanding margin pool as airports pursue tarmac digitization. Cargo Handling equipment attracts replacement demand from African freight gateways, while RFID Tracking integration is displacing legacy barcode systems for unit load device accountability.
The UAE's General Civil Aviation Authority and Saudi Arabia's General Authority of Civil Aviation enforce airside equipment certification standards that shape procurement specifications and operator training mandates. South Africa's Civil Aviation Authority applies SANS 10330 compliance for ground support equipment, restricting market access for uncertified imports. Stakeholders must monitor how Egypt's civil aviation regulator adapts its technical directives to accommodate electric ground handling fleets as Cairo and Alexandria airports modernize.
Market Dynamics
Fleet expansion among Gulf Cooperation Council full-service carriers is compressing aircraft turnaround windows from 45 minutes to under 30 minutes, forcing ground handling operators to replace legacy belt loaders and cargo dollies with higher-throughput automated alternatives.
Growth Catalysts
- Vision 2030 airport construction:Saudi Arabia's General Authority of Civil Aviation is greenlighting multiple greenfield airports, generating concentrated demand for electrical ground power units and preconditioned air systems.
- Baggage Handling System modernization:Megahubs in Dubai and Riyadh are retrofitting terminals with RFID-enabled conveyor networks to replace barcode-based unit load device tracking.
- ISO 9001 certification mandates:Quality management standards are filtering procurement eligibility, advantaging suppliers with documented automation portfolios over regional equipment assemblers.
Market Restraints
- Aluminum and steel input volatility:Cargo dollies rated for 15-tonne loads and aircraft tractors face margin pressure from fluctuating raw material costs passed through fixed-price municipal contracts.
- South African certification bottlenecks:SANS 10330 compliance requirements restrict market access for uncertified ground support equipment imports, limiting supplier diversity in African freight gateways.
- Lead-acid battery substitution threat:Electric ground handling fleets in Cairo and Alexandria airports confront charging infrastructure gaps that slow displacement of diesel-powered towbarless tractors.
Strategic Opportunities
- Egyptian aviation electrification:Cairo and Alexandria airport modernization programs are creating first-mover openings for advanced electrical ground power unit deployments as the country's civil aviation regulator adapts technical directives.
- RFID-barcode convergence:Unit load device accountability systems are integrating radio-frequency identification with legacy tracking infrastructure, opening retrofit contracts for mid-life baggage handling installations.
- Hub-and-spoke cargo consolidation:African freight gateways are consolidating volume through Addis Ababa and Nairobi, concentrating replacement demand for 500-kg payload belt loaders and specialized cargo dollies.
Industry Challenges
- GCAA-certified operator scarcity:The UAE's General Civil Aviation Authority mandates stricter ground safety certifications that outpace local training pipeline capacity, delaying equipment commissioning.
- Legacy system integration friction:Tarmac digitization initiatives confront interoperability gaps between new automated baggage conveyors and existing fixed infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Airport Ground Handling Systems Market |
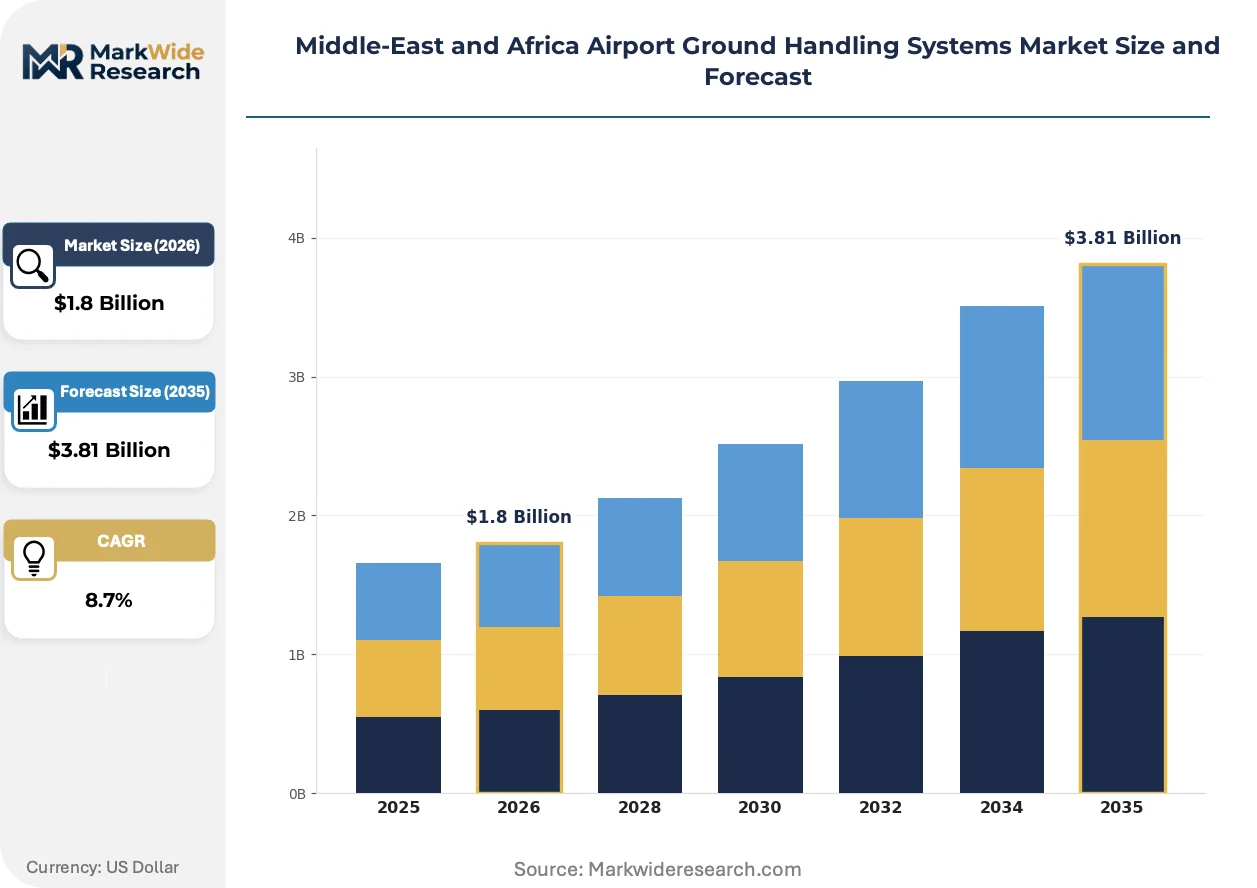
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Baggage Handling, Aircraft Services, Cargo Handling, Passenger Services Technology: Automated Systems, Electric Tugs, RFID Tracking, Mobile Applications End User: Airlines, Ground Handling Companies, Airports, Government Agencies Service Type: Ramp Services, Passenger Assistance, Cargo Management, Maintenance Services |
| Companies Covered | Siemens AG, Cavotec SA, Alvest SAS, Usimat-sermees, Ersel Banca Privata S p A, Tüm Hakları ERSEL TEKNOLOJİ San ve Ltd, DENGE - Ground Support Equipment Manufacturer (GSE), High Dam, excel handling sp z o o, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Airport Ground Handling Systems Market Shifts & Advancements
Automation architectures are fragmenting equipment procurement patterns across Middle-East and African airports, separating premium intelligent systems from standardized mechanical units. Three developments are compressing vendor margins while expanding service attach rates.
Intelligent baggage conveyor deployments are bifurcating the installed base across the region's megahubs. Dubai and Riyadh airports are adopting sensor-integrated belt systems with predictive maintenance capability, while secondary facilities retain mechanical conveyors. This technology split is enabling premium pricing for automation suppliers while compressing margins for regional assemblers locked into commodity equipment contracts.
Saudi Arabia's General Authority of Civil Aviation is tightening airside equipment certification standards ahead of Vision 2030 airport openings. The industrial consequence is a qualification backlog for electrical ground power units and preconditioned air systems. Full-service carriers operating expanded fleets are responding by pre-qualifying suppliers 18-24 months ahead of commissioning dates, front-loading procurement cycles.
Service contract unbundling is disrupting traditional equipment-plus-maintenance bundles in UAE and Saudi procurement. Ground handling operators are separating capital acquisition from lifecycle support, awarding multi-year service agreements to specialized maintenance providers. This pattern is most visible among Dubai-based hub operators managing mixed fleets of towbarless tractors and cargo dollies from multiple OEMs.
Middle-East and Africa Airport Ground Handling Systems Market Segmentation
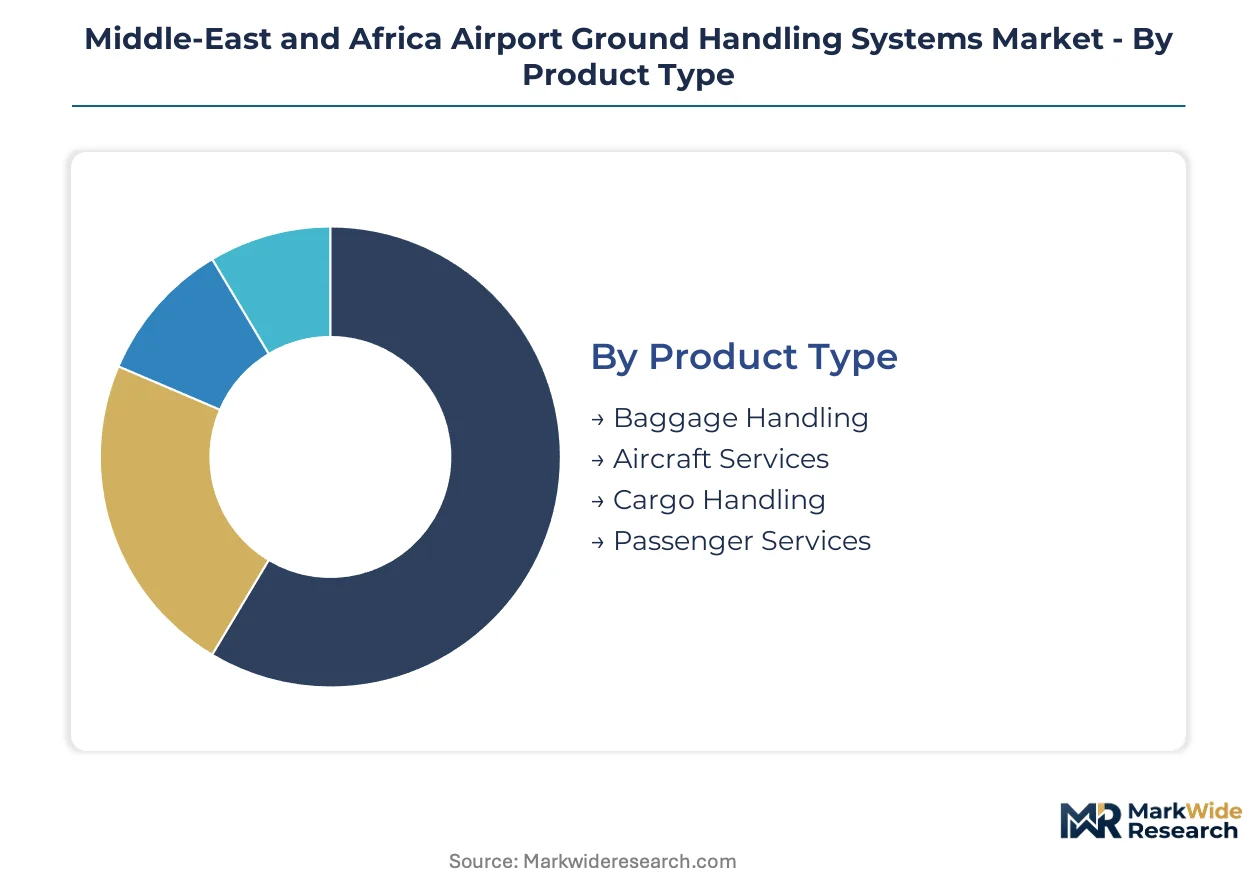
Segmentation in the Middle-East and Africa airport ground handling systems market reveals how procurement priorities diverge across regulatory environments. Equipment specifications in Saudi Arabia's Vision 2030 airports differ materially from South African SANS 10330 compliance requirements, creating distinct demand clusters.
Product Type:
GCAA and GACA certification standards filter eligibility differently across equipment categories, advantaging suppliers with documented quality management systems.
- Baggage Handling:Belt loaders with 500-kg payload capacity and RFID-enabled conveyor networks dominate installed bases across Dubai and Riyadh megahubs. Saudi Arabia's greenfield airport construction under Vision 2030 is generating concentrated demand for high-throughput automated alternatives as full-service carriers compress turnaround windows below 30 minutes.
- Aircraft Services:Preconditioned air units delivering 110 tons per hour of cooled airflow and electrical ground power units form the critical infrastructure for aircraft turnaround. UAE-based hub operators managing expanded Gulf Cooperation Council fleets are pre-qualifying suppliers 18-24 months ahead of commissioning dates.
- Cargo Handling:Cargo dollies rated for 15-tonne loads attract replacement demand from African freight gateways consolidating volume through Addis Ababa and Nairobi.
- Passenger Services:Fixed infrastructure for passenger boarding bridges and apron buses serves secondary facilities retaining mechanical systems while megahubs automate.
Baggage Handling handles the majority of throughput; Aircraft Services is expanding most quickly on share.
Technology:
Cost tier differentiation separates premium intelligent systems from standardized mechanical units across the region's airports.
- Automated Systems:Sensor-integrated baggage conveyors with predictive maintenance capability command premium pricing in Dubai and Riyadh. The technology split between megahubs and secondary facilities is compressing margins for regional assemblers locked into commodity equipment contracts.
- RFID Tracking:Radio-frequency identification systems are displacing legacy barcode infrastructure for unit load device accountability. Retrofit contracts are opening for mid-life baggage handling installations as operators pursue tarmac digitization.
- Electric Tugs:Towbarless aircraft tractors confront charging infrastructure gaps at Cairo and Alexandria airports that slow displacement of diesel-powered alternatives.
- Mobile Applications:Ground handling operators are separating capital acquisition from lifecycle support, awarding multi-year service agreements to specialized maintenance providers managing mixed fleets.
Automated Systems capture the premium tier; RFID Tracking is gaining share fastest as retrofit demand accelerates.
End User:
Customer type determines procurement scale and service contract structure across the Middle-East and Africa.
- Ground Handling Companies:Independent operators managing mixed fleets of towbarless tractors and cargo dollies from multiple OEMs are driving service contract unbundling in UAE and Saudi procurement.
- Airlines:Full-service carriers across the Gulf Cooperation Council are expanding fleet sizes and demanding faster turnaround protocols, forcing equipment replacement cycles.
- Airports:Municipal operators face margin pressure from fixed-price contracts as aluminum and steel input volatility affects cargo dolly manufacturing costs.
- Government Agencies:Aviation regulators in Egypt are adapting technical directives to accommodate electric ground handling fleets as Cairo and Alexandria modernize.
Ground Handling Companies drive the service revenue pool; Government Agencies are the emerging demand channel as electrification mandates spread.
Service Type:
Maturity gradients separate established ramp operations from digitizing cargo management functions.
- Ramp Services:Aircraft marshalling, pushback operations, and ground power connection form the core revenue base for established handlers across the region's megahubs.
- Cargo Management:Freight handling specialization is concentrating at African gateways as hub-and-spoke consolidation redirects volume through Addis Ababa and Nairobi.
- Passenger Assistance:Wheelchair services and unaccompanied minor handling retain labor-intensive profiles resistant to automation.
- Maintenance Services:Lifecycle support contracts are separating from capital acquisition as Dubai-based operators unbundle traditional equipment-plus-maintenance bundles.
Ramp Services anchors current revenue; Cargo Management shows the steepest expansion trajectory as African freight consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ground handling procurement concentrates among Gulf Cooperation Council megahubs and African freight consolidation nodes, with regulatory divergence creating distinct certification requirements across jurisdictions.
United Arab Emirates
Dubai International and Zayed International airports drive demand for automated baggage conveyors and electrical ground power units as Emirates and Etihad expand widebody fleets. The General Civil Aviation Authority enforces stricter ground safety certifications for equipment operators, extending supplier pre-qualification timelines. Abu Dhabi's hub modernization is retrofitting terminals with RFID-enabled tracking infrastructure.
Saudi Arabia
Vision 2030 greenfield airport construction at Riyadh and Jeddah is generating concentrated procurement of preconditioned air systems and towbarless tractors. The General Authority of Civil Aviation is tightening airside equipment certification standards ahead of new airport openings, forcing 18-24 month supplier qualification cycles. NEOM's northwest aviation cluster is specifying fully electric ground handling fleets.
South Africa
Johannesburg's OR Tambo International anchors African cargo consolidation, driving replacement demand for 15-tonne rated cargo dollies. The Civil Aviation Authority applies SANS 10330 compliance for ground support equipment, restricting market access for uncertified imports. Cape Town's secondary hub retains mechanical baggage systems while deferring automation investments.
Egypt
Cairo and Alexandria airport modernization programs are creating first-mover openings for electrical ground power unit deployments. The country's civil aviation regulator is adapting technical directives to accommodate electric ground handling fleets, though charging infrastructure gaps slow diesel displacement. Alexandria's Borg El Arab facility is piloting RFID-barcode hybrid tracking systems.
Turkey
Istanbul Airport's mega-hub operations demand high-throughput belt loaders and automated cargo dollies to serve Turkish Airlines' expanded fleet. The Directorate General of Civil Aviation harmonizes equipment certification with EU standards, facilitating cross-border supplier access. Ankara's cargo gateway is consolidating regional freight volume from Central Asian corridors.
Middle-East and Africa Airport Ground Handling Systems Market Competitive Landscape
Player mix skews toward European automation specialists and regional equipment assemblers competing on certification compliance rather than manufacturing scale. Siemens AG leverages its industrial automation portfolio to anchor intelligent system deployments, while Cavotec SA and Alvest SAS occupy distinct equipment niches. Market structure favors suppliers with documented ISO 9001 quality management systems over price-competitive regional fabricators. Dominant competitive moves include pre-qualification front-loading ahead of Saudi greenfield openings and service contract unbundling that separates capital acquisition from lifecycle maintenance.
Among European-headquartered specialists, Siemens AG, Cavotec SA, and Alvest SAS exemplify three distinct competitive archetypes. Siemens represents the automation-integrated conglomerate competing on intelligent system architectures. Cavotec occupies the captive electrical infrastructure position. Alvest anchors the towbarless tractor specialization segment. Regional assemblers including DENGE and High Dam compete on price for mechanical equipment contracts, though SANS 10330 and GCAA certification requirements constrain their addressable market. Usimat-sermees and Tüm Hakları ERSEL TEKNOLOJİ represent Turkey-based fabricators serving proximate Middle Eastern markets.
| Leading Market Players |
|---|
| Siemens AG |
| Cavotec SA |
| Alvest SAS |
| Usimat-sermees |
| Ersel Banca Privata S p A |
| Tüm Hakları ERSEL TEKNOLOJİ San ve Ltd |
| DENGE - Ground Support Equipment Manufacturer (GSE) |
| High Dam |
| excel handling sp z o o |
| Others |
Supply & Pricing Matrix
Fixed-price municipal contracts with aluminum and steel indexation lock in equipment procurement budgets for ground handling operators while exposing manufacturers to raw material volatility. This contract structure concentrates pricing power among integrated suppliers with captive metal sourcing, compressing margins for regional fabricators dependent on spot market purchases.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate procurement for cargo dollies and aircraft tractors across Gulf Cooperation Council airports. Price differentiation rests on ISO 9001 certification tier and after-sales service bundling, with GCAA-certified suppliers commanding 15-20% premiums over uncertified regional assemblers. Cost compression in mechanical equipment tiers is intensifying as Saudi greenfield projects consolidate volume among pre-qualified vendors. Municipal airport operators exhibit highest price sensitivity, while Emirates and Etihad prioritize turnaround reliability over unit cost.
Supply Chain Analysis
Strait of Hormuz transit underwrites component delivery schedules for electrical ground power units and preconditioned air systems destined for UAE and Saudi hubs. Manufacturing concentrates in Germany, Italy, and Turkey, with high-grade steel and aluminum castings drawn from European foundries. Single-source vulnerability persists for intelligent conveyor sensor modules sourced from a concentrated automation component base. Distribution runs through Dubai-based logistics hubs serving African freight gateways, with SANS 10330 certification bottlenecks restricting South African market access for uncertified imports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
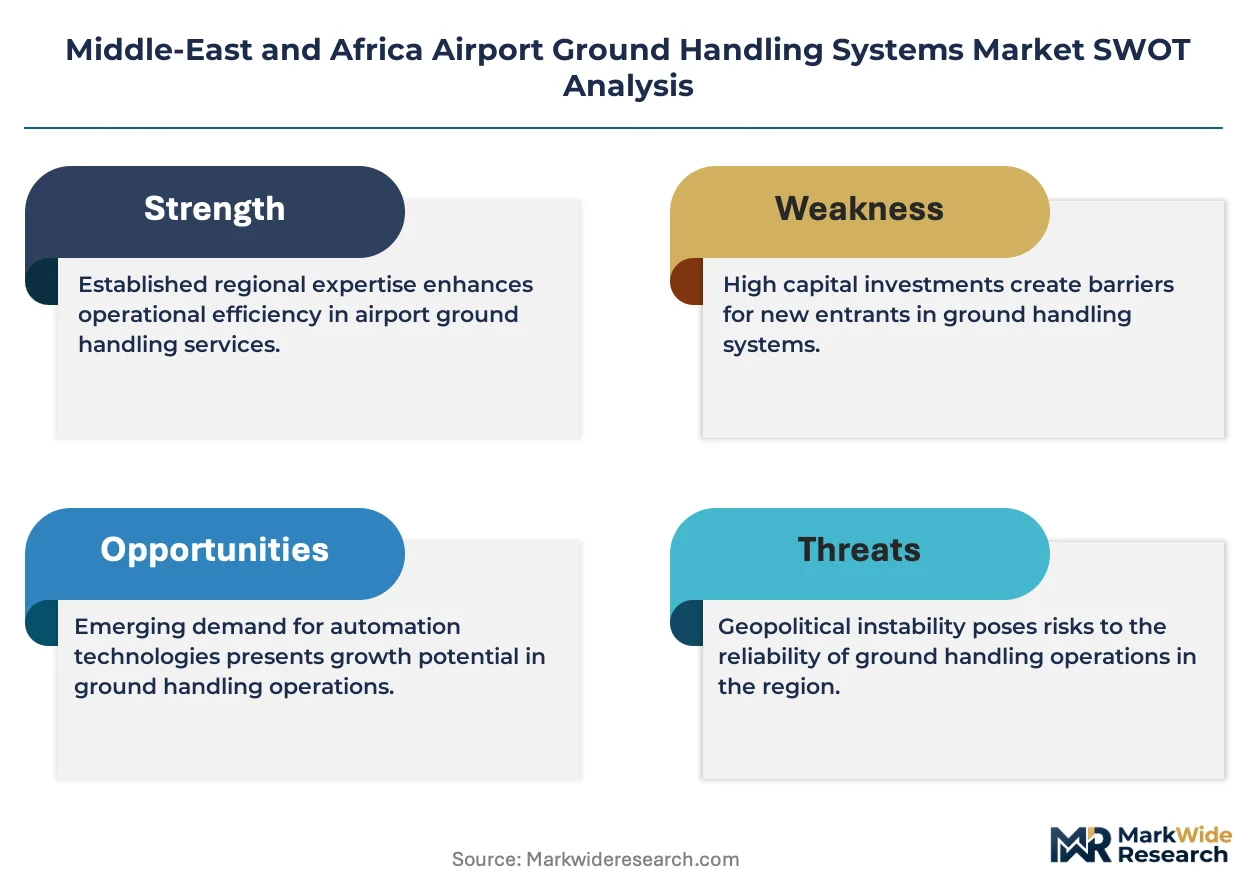
The acute shortage of GCAA-certified equipment operators across UAE airports constrains commissioning velocity and creates captive value for training-capable suppliers. This capability gap amplifies strategic importance for stakeholders positioned to close certification backlogs.
For Market Incumbents: Consolidate service contract portfolios by acquiring specialized maintenance providers managing mixed fleets of towbarless tractors and cargo dollies. Deepen backward integration into aluminum casting operations to offset LME volatility eroding margins on fixed-price municipal contracts. Pre-empt emerging competition from Chinese electric tug manufacturers by accelerating GCAA pre-qualification for next-generation battery-powered ground support equipment. For New Entrants and Emerging Players: Lifecycle support unbundling among Dubai-based hub operators creates white-space for independent maintenance providers capable of multi-OEM fleet management. Egyptian airport electrification programs offer the most penetrable geography, with Cairo and Alexandria modernization creating first-mover openings before technical directives fully crystallize. Pursue joint-venture structures with established European automation specialists to bypass 18-24 month GACA supplier qualification cycles. For Investors and Strategic Acquirers: ISO 9001-certified regional fabricators with documented automation portfolios represent the most defensible acquisition archetype in a market filtering procurement eligibility through quality management mandates. Long-term viability hinges on exposure to Saudi Vision 2030 greenfield construction rather than African replacement demand. Monitor Egypt's civil aviation regulator for electrification mandate signals that would re-rate electric ground power unit deployment timelines.| Strategic Initiative | Industry Significance |
|---|---|
| GCAA Certification Pre-Qualification | 18-24 month supplier qualification cycles ahead of Saudi greenfield openings lock in incumbent positions. |
| Backward Integration into Aluminum Casting | In-house foundry operations insulate margin pressure from LME volatility on fixed-price municipal contracts. |
| Service Contract Unbundling | Separating capital acquisition from lifecycle support creates recurring revenue pools for specialized maintenance providers. |
| RFID-Barcode Hybrid Retrofit | Mid-life baggage handling installations in Egypt and secondary UAE facilities open upgrade contract opportunities. |
| Electric Fleet Pilot Programs | NEOM's fully electric ground handling specifications establish reference architecture for regional electrification mandates. |
Research Methodology
A spread of perspectives from ground handling operations directors, GSE procurement managers, GCAA certification officers, and airline fleet planning executives converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through customs trade databases, General Authority of Civil Aviation technical directives, SANS 10330 compliance registries, and SEC filings from listed automation suppliers. Bottom-up equipment shipment tracking and top-down airport capital expenditure triangulation anchored volume estimates.
Segmentation dimensions modeled span product type (baggage handling, aircraft services, cargo handling, passenger services), technology tier (automated systems, RFID tracking, electric tugs, mobile applications), end-user category (ground handling companies, airlines, airports, government agencies), and service type (ramp services, cargo management, passenger assistance, maintenance services). CAGRs were derived from regression analysis against fleet expansion schedules and greenfield construction timelines across the projection horizon. Forecast inputs incorporated Gulf Cooperation Council carrier widebody delivery schedules and Vision 2030 airport commissioning dates.
Forecasts assume regulatory continuity in GCAA and GACA certification regimes; material policy shifts toward accelerated electrification mandates would require re-modeling deployment timelines for diesel displacement scenarios. Practitioners should keep alternative scenarios live as Egypt's civil aviation regulator adapts technical directives and charging infrastructure gaps at Cairo and Alexandria airports evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Technologies
Smart Airport 4.0 Market
Airport Technologies
Asia-Pacific Airport Baggage Handling Systems Market
Airport Technologies
Asia-Pacific Smart Airport Market
Airport Technologies
North America Airport Baggage Handling Systems Market
Airport Technologies
Aviation Beacons Technology Market
Airport Technologies
Bird Detection System for Airports Market
Airport Technologies
Airport Information Display System Market
Airport Technologies
Global Airport Baggage Handling System Market
Airport Technologies
Airport Interactive Kiosk Market
Airport Technologies
Airport Cargo Community Digital Collaboration Platforms Market
Airport Technologies
America Airport Ground Handling Systems Market
Airport Technologies
Middle-East and Africa Airport Baggage Handling Systems Market
Airport Technologies
Airport RFID System Market
Airport Technologies
North America Smart Airport Market
Airport Technologies
Advanced Airport Technologies Market
Airport Technologies
Commercial Airport Baggage Handling Systems Market