
 High-Value Healthcare Asset Tracking and Recovery Platforms Market | 2026-2036
High-Value Healthcare Asset Tracking and Recovery Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
High-Value Healthcare Asset Tracking and Recovery Platforms Market Insights
The market is restructuring around a widening capability gap between premium RTLS-integrated platforms and commodity barcode systems. Zebra Technologies leverages its hardware-software stack to dominate enterprise-grade deployments across integrated delivery networks. CenTrak sustains technology leadership through proprietary infrared and ultrasound fusion architectures that deliver sub-room accuracy. Securitas Healthcare competes by anchoring its offering in security-centric workflows that appeal to risk-sensitive hospital administrators.
High-value healthcare asset tracking and recovery platforms encompass sensor networks, location engines, and analytics software that continuously monitor medical equipment position, condition, and utilization status through RF signaling, cloud data processing, and mobile dashboards. These systems primarily reduce capital waste, prevent theft, and ensure regulatory traceability of devices subject to recall or maintenance protocols. Real-time location systems command the largest installed base but IoT sensors represent the fastest-expanding segment as battery efficiency and edge computing enable predictive maintenance applications. Equipment management anchors current revenue while asset utilization analytics emerges as the highest-margin growth vector as hospitals seek operational efficiency under reimbursement pressure.
FDA UDI requirements, EPA hazardous materials handling protocols, and HIPAA data security standards collectively shape platform architecture, mandating encrypted transmission, audit trails, and interoperability with electronic health records. The EU MDR and GDPR impose parallel compliance burdens on multinational health systems, accelerating demand for unified global deployments. Stakeholders must evaluate whether to consolidate vendors across geographies or accept integration complexity from regional specialists as regulatory divergence deepens.
Market Dynamics
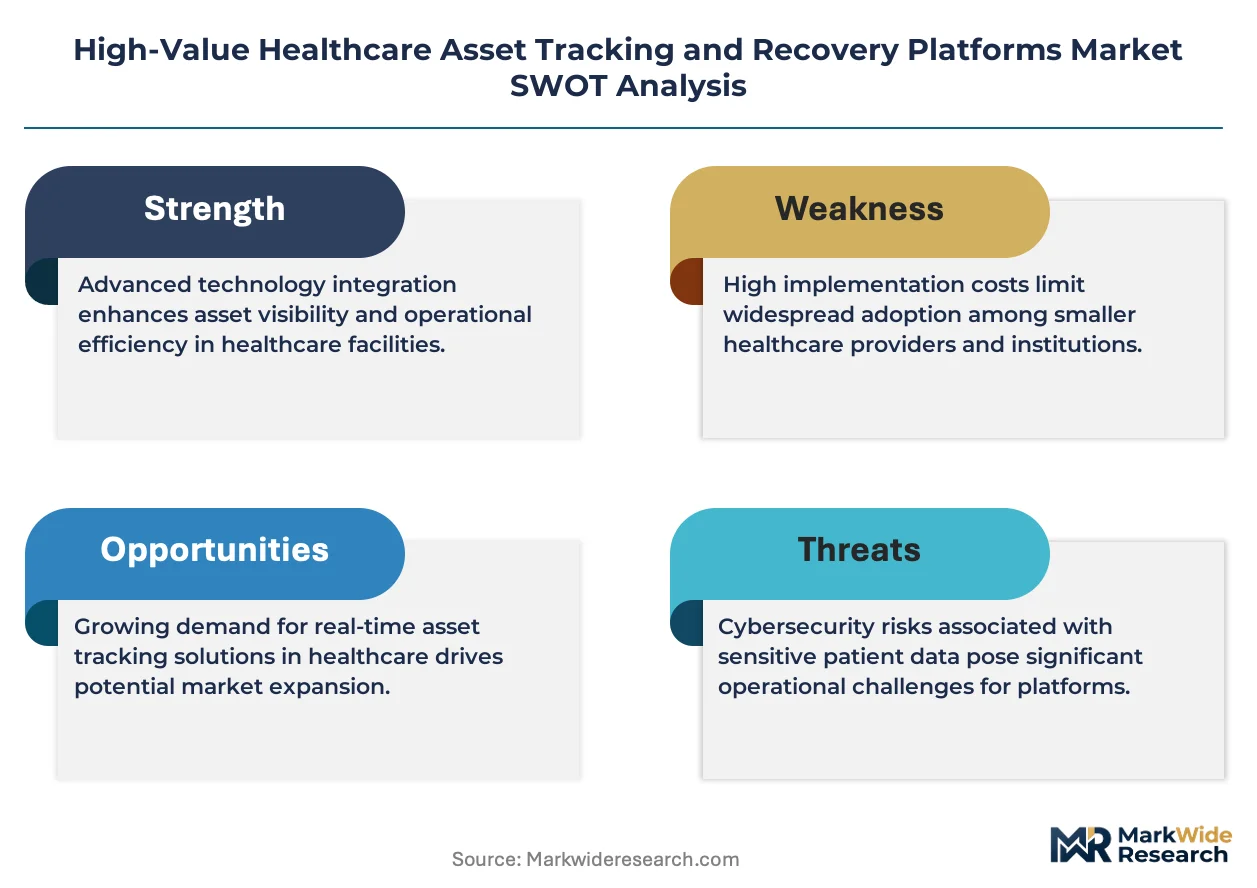
Health system consolidation is compressing procurement cycles and forcing asset tracking platforms to prove enterprise-scale ROI across multi-hospital networks before contract award.
Growth Catalysts
- FDA UDI Mandate:Device traceability requirements compel hospitals to deploy automated identification systems that link physical assets to electronic health records for recall management and adverse event tracking.
- IoT Sensor Miniaturization:Battery-efficient edge computing modules enable predictive maintenance applications that extend equipment lifespan and reduce capital replacement cycles in acute care settings.
- United States:Integrated delivery networks achieving economies of scale through centralized asset pools that require real-time visibility across dozens of facilities and thousands of mobile medical devices.
Market Restraints
- Semiconductor Supply Concentration:RF chip fabrication dependencies in East Asian foundries create lead time volatility for RTLS hardware manufacturers serving North American hospital systems.
- Legacy Infrastructure Inertia:Decades-old Wi-Fi architectures in aging hospital buildings obstruct seamless BLE mesh deployment without costly access point upgrades or cabling retrofits.
- GDPJ Compliance Burden:European data residency requirements impose architectural constraints on cloud-native platforms that fragment product roadmaps and inflate engineering overhead for multinational vendors.
Strategic Opportunities
- India:Hospital accreditation standards under NABH are mandating equipment accountability systems that create first-mover advantages for platforms adapted to price-sensitive purchasing environments.
- AI-RTLS Convergence:Machine learning inference at the edge transforms raw location data into utilization optimization recommendations that command premium pricing from efficiency-focused health systems.
- Subscription Revenue Models:Hardware-as-a-service arrangements reduce upfront capital barriers for mid-size community hospitals and generate predictable recurring revenue streams for platform vendors.
Industry Challenges
- Interoperability Engineering:Biomedical engineering teams lack expertise in HL7 FHIR integration protocols that connect asset tracking databases to computerized maintenance management systems.
- RF Spectrum Congestion:Dense medical device environments in urban tertiary centers experience signal interference that degrades location accuracy and triggers false alerts requiring manual verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Value Healthcare Asset Tracking and Recovery Platforms Market |
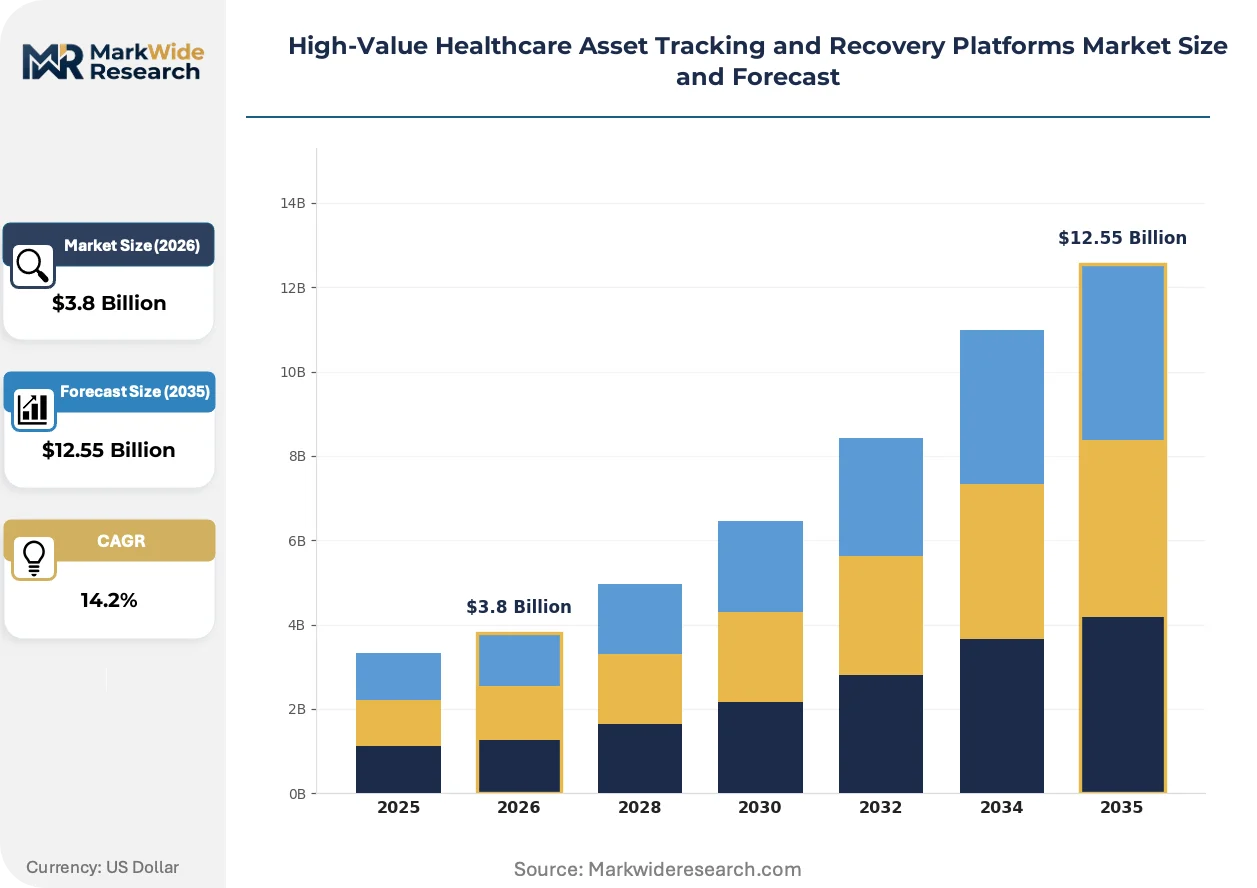
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Real-Time Location Systems, RFID Tracking, GPS Monitoring, Barcode Scanning, IoT Sensors Application: Equipment Management, Inventory Control, Asset Utilization, Theft Prevention, Maintenance Scheduling End User: Hospitals, Diagnostic Laboratories, Surgical Centers, Long-Term Care Facilities, Rehabilitation Clinics Deployment Model: Cloud-Based, On-Premises, Hybrid, Managed Services |
| Companies Covered | Zebra Technologies, CenTrak, Securitas Healthcare, Infor, AiRISTA Flow, Midmark RTLS, Kontakt.io, Sonitor Technologies, GE HealthCare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Value Healthcare Asset Tracking and Recovery Platforms Market Trends and Innovations
Platform architecture is pivoting from standalone location tracking toward integrated operational intelligence that embeds asset data directly into clinical workflow automation.
Ultra-wideband chipsets are unifying precision ranging with low-power consumption in a single silicon package. Academic medical centers in Germany and Switzerland are piloting sub-meter accuracy for surgical instrument tracking in hybrid operating rooms. This convergence is unifying previously separate capital budgets for RTLS infrastructure and surgical safety systems into single procurement decisions.
EU MDR Article 27 mandates unique device identification at the point of care for all implantable devices. Manufacturers must now maintain device history records accessible through machine-readable identifiers that hospital asset platforms must parse and synchronize. European health systems are responding by demanding multi-modal scanning capabilities that accommodate both legacy linear barcodes and modern data matrix formats.
Chief financial officers are consolidating vendor relationships and demanding outcome guarantees that tie subscription fees to measurable reductions in equipment rental expenses or shrinkage losses. Large IDNs in Texas and California are replacing transactional hardware purchases with performance-based contracts where vendors retain ownership risk. This restructuring is most visible in the United States where reimbursement compression has elevated capital efficiency to board-level priority.
High-Value Healthcare Asset Tracking and Recovery Platforms Market Segmentation
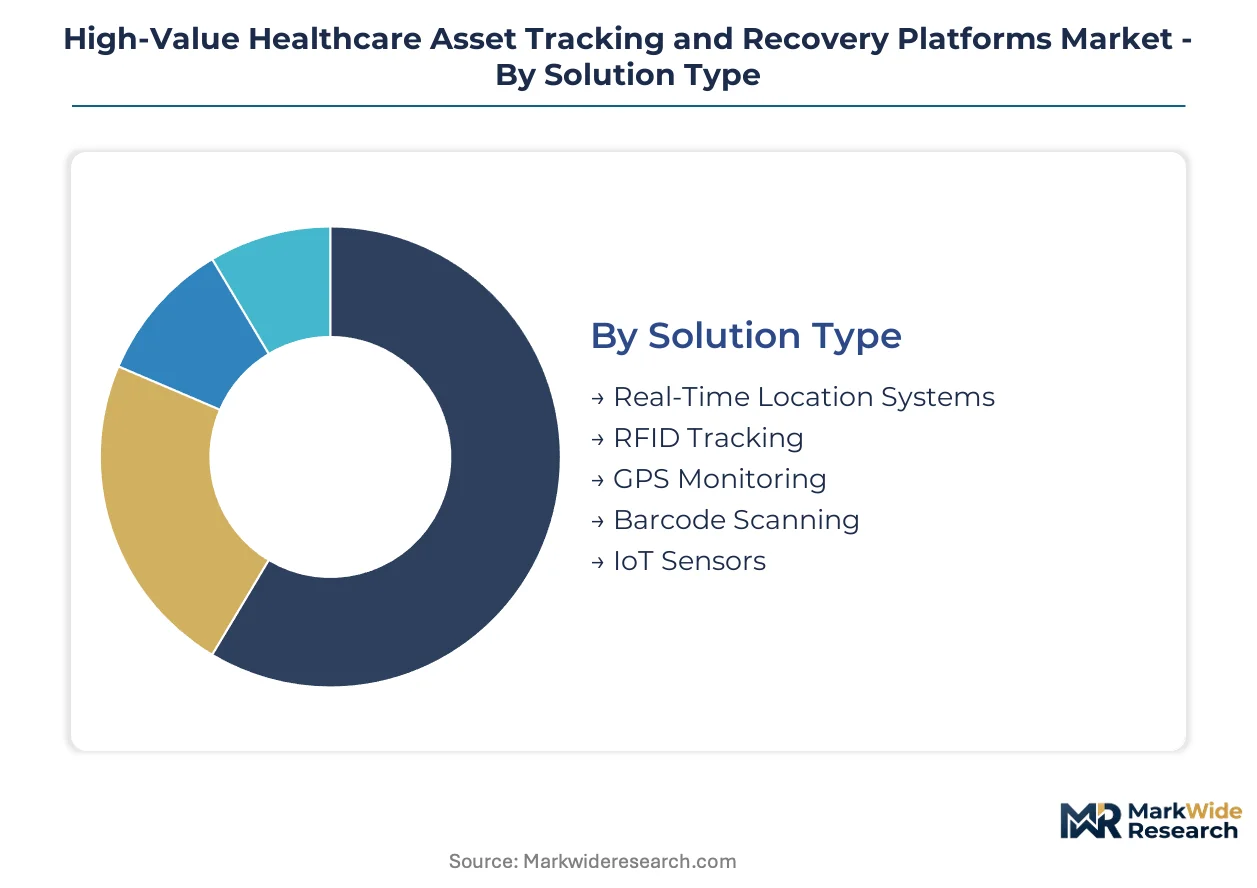
Asset tracking platforms fragment across technology maturity curves and organizational readiness, with procurement committees weighting capital intensity against integration complexity. Solution architecture and deployment flexibility determine contract value more than hardware specifications alone.
Solution Type:
Volume deployments cluster around legacy identification methods, while premium budgets flow toward sensor fusion architectures that unify location intelligence with predictive analytics.
- Real-Time Location Systems:Infrared-ultrasound and BLE mesh networks deliver sub-room accuracy for ventilators, infusion pumps, and wheelchairs. Demand concentrates in United States integrated delivery networks consolidating asset pools across dozens of facilities. FDA UDI traceability mandates accelerate replacement of passive tracking with active beacon infrastructure.
- IoT Sensors:Battery-efficient edge computing modules monitor equipment condition, temperature exposure, and vibration patterns. German academic medical centers pilot these for surgical instrument lifecycle management under EU MDR Article 27 compliance timelines. Predictive maintenance applications command premium pricing from capital-constrained hospital CFOs.
- RFID Tracking:Passive and active radio-frequency tags provide cost-effective inventory visibility for mid-size community hospitals.
- GPS Monitoring:Satellite-based tracking serves mobile assets and home healthcare equipment fleets requiring wide-area coverage.
- Barcode Scanning:Linear and data matrix codes persist as compliance minimums for implantable device documentation.
Mature deployment sits with Barcode Scanning. Newer deployment is concentrated in IoT Sensors.
Application:
Operational efficiency drives purchasing more than loss prevention, with health systems prioritizing utilization analytics that reduce rental expenses and capital replacement cycles.
- Equipment Management:Real-time location dashboards reduce time-to-find metrics for critical devices during code blue events. United States tertiary centers report measurable improvements in nurse workflow efficiency. Cloud-native platforms from Zebra Technologies and CenTrak dominate enterprise-scale deployments.
- Asset Utilization:Machine learning algorithms transform location data into par-level optimization and redistribution recommendations. Texas and California IDNs negotiate outcome-based contracts tying subscription fees to documented equipment rental reductions. This segment commands the highest margins as reimbursement compression elevates operational efficiency to board priority.
- Inventory Control:Automated replenishment triggers link consumption tracking to supply chain management systems.
- Theft Prevention:Geofencing alerts and exit monitoring secure high-value mobile equipment in urban medical centers.
- Maintenance Scheduling:Condition-based alerts extend equipment lifespan and ensure regulatory compliance with Joint Commission standards.
Procurement concentration favors Equipment Management. Steepest expansion trajectory belongs to Asset Utilization.
End User:
Facility scale and reimbursement model determine platform sophistication, with acute care hospitals outspending post-acute providers by an order of magnitude.
- Hospitals:Multi-campus health systems deploy enterprise RTLS across emergency departments, operating suites, and central sterile processing. United States consolidation creates procurement leverage for standardized platforms. FDA UDI and EPA hazardous materials protocols mandate encrypted audit trails.
- Surgical Centers:Ambulatory facilities prioritize instrument tracking and sterilization workflow integration. Swiss and German outpatient clinics pilot ultra-wideband precision for orthopedic and ophthalmic procedure sets.
- Diagnostic Laboratories:Specimen chain-of-custody tracking drives RFID and barcode investments.
- Long-Term Care Facilities:Wander management and resident safety applications dominate purchasing in skilled nursing environments.
- Rehabilitation Clinics:Therapy equipment utilization tracking supports operational efficiency in outpatient physical medicine.
Capital allocation peaks with Hospitals. Emerging demand concentrates in Surgical Centers.
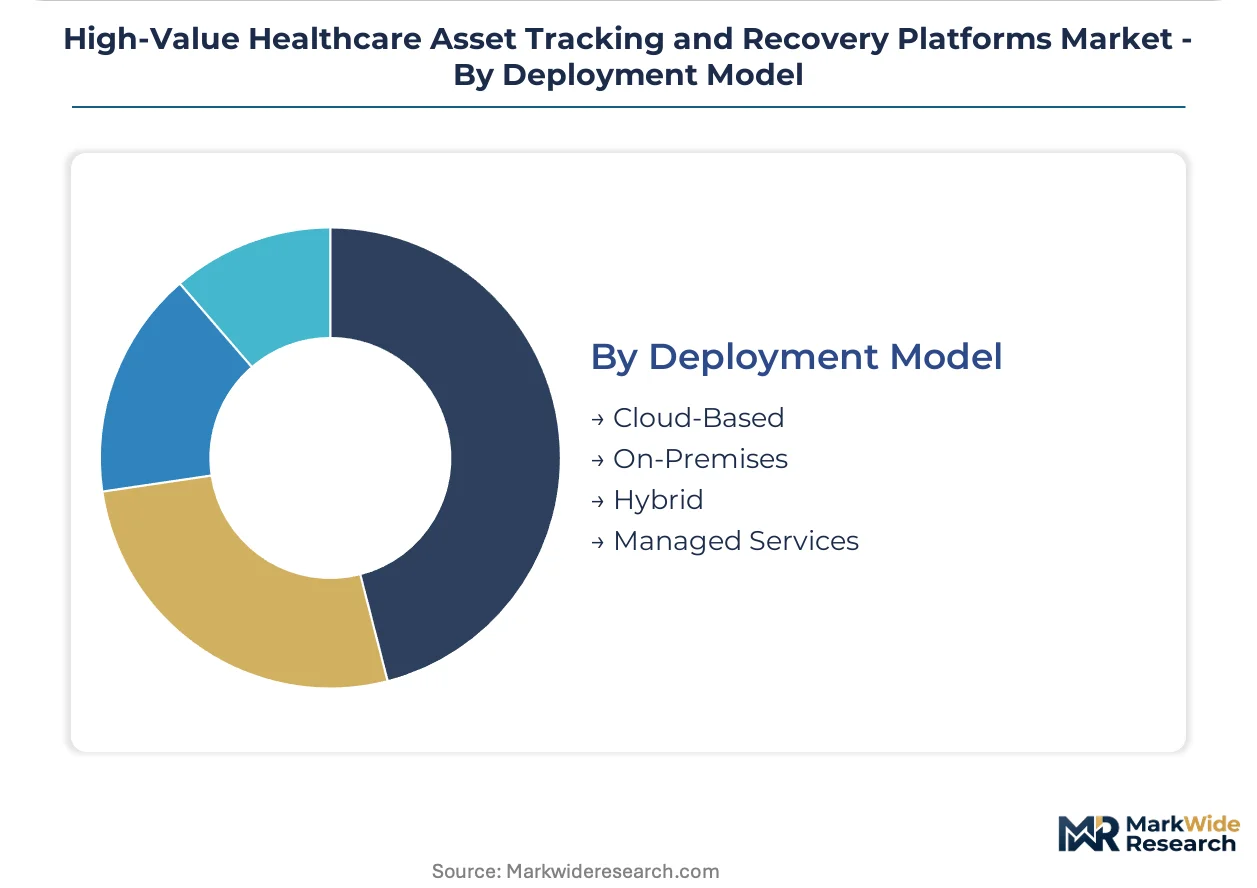
Deployment Model:
IT governance preferences and data residency requirements fragment architecture choices, with cloud-native platforms gaining share despite security committee skepticism.
- Cloud-Based:Multi-tenant SaaS architectures reduce upfront capital barriers and enable predictive analytics at scale. GDPR data residency requirements fragment European product roadmaps and inflate engineering overhead for multinational vendors.
- Hybrid:Edge processing with cloud aggregation balances latency-sensitive location engines against centralized analytics. United States IDNs favor this model for sensitive biomedical device data.
- On-Premises:Air-gapped installations persist in defense and intelligence-affiliated medical centers.
- Managed Services:Vendor-operated infrastructure transfers operational risk for mid-size hospitals lacking biomedical engineering depth.
Established preference remains with Hybrid. Cloud-Based architectures are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Longwood Medical Area anchors North American RTLS deployment density, with Massachusetts General Hospital and Brigham and Women's Hospital operating as reference sites for enterprise asset tracking validation.
United States
Integrated delivery networks in Texas and California negotiate outcome-based contracts tying platform fees to documented rental expense reductions. FDA UDI mandates compel automated identification systems linking physical assets to electronic health records. The Dallas-Fort Worth metroplex hosts concentrated pilot programs for ultra-wideband surgical instrument tracking.
Germany
Academic medical centers in Munich and Heidelberg pilot sub-meter precision systems for hybrid operating room workflows. EU MDR Article 27 mandates unique device identification at point of care for implantable devices. The Rhine-Main cluster around Frankfurt drives standardization demands for multi-modal scanning accommodating legacy barcodes and modern data matrix formats.
Switzerland
Swissmedic regulations enforce stringent device history record accessibility through machine-readable identifiers. Outpatient clinics in Zurich and Geneva deploy precision tracking for orthopedic and ophthalmic procedure sets. The Basel pharmaceutical corridor influences adjacent hospital procurement toward traceability-integrated platforms.
India
NABH accreditation standards mandate equipment accountability systems creating first-mover advantages for adapted platforms. CDSCO device registration requirements parallel international traceability protocols. The Delhi-NCR hospital cluster drives price-sensitive purchasing decisions favoring subscription-based deployment models.
United Kingdom
NHS England procurement frameworks prioritize interoperability with existing electronic health record infrastructure. MHRA post-Brexit device regulations maintain alignment with EU MDR traceability timelines. The Cambridge-Oxford-London golden triangle concentrates digital health innovation and early RTLS adoption.
High-Value Healthcare Asset Tracking and Recovery Platforms Market Competitive Landscape
Premium-margin players sit above commodity-margin players across solution architecture sophistication, with hardware-software integration capability determining contract value capture. The vendor base stratifies into enterprise-scale platform providers, specialized accuracy-technology developers, and security-centric workflow specialists. Two dominant competitive moves reshape positioning: strategic partnerships bridging RTLS infrastructure with electronic health record systems, and subscription revenue models transferring capital risk from hospital buyers to platform vendors.
Within the enterprise platform tier, Zebra Technologies and CenTrak occupy positions representing divergent technical approaches to location intelligence. Zebra Technologies exemplifies hardware-software stack consolidation across integrated delivery networks. CenTrak anchors the specialized accuracy segment through proprietary sensor fusion architectures. Securitas Healthcare sits within the security-centric workflow archetype, appealing to risk-sensitive hospital administrators seeking unified physical and asset protection systems.
| Leading Market Players |
|---|
| Zebra Technologies |
| CenTrak |
| Securitas Healthcare |
| Infor |
| AiRISTA Flow |
| Midmark RTLS |
| Kontakt.io |
| Sonitor Technologies |
| GE HealthCare |
| Others |
Pricing and Supply Chain Analysis
Ultra-wideband chipset miniaturization is compressing hardware costs while concentrating manufacturing capabilities in East Asian foundries, simultaneously enabling subscription pricing models and creating single-source dependencies for RF components. This dual transformation rewards vendors with captive supply relationships while pressuring margin structures for hardware-dependent competitors.
Pricing Analysis
Outcome-based contracts tying platform fees to measurable equipment rental reductions anchor premium pricing for enterprise-grade deployments. Pricing stratifies across sensor-fusion precision tiers, with infrared-ultrasound fusion commanding premiums over BLE mesh alternatives. Cost compression in commodity barcode segments is intensifying because mid-size community hospitals prioritize capital efficiency over accuracy specifications. Surgical centers and ambulatory facilities exhibit highest price sensitivity, while integrated delivery networks accept premium pricing for unified multi-campus deployments.
Supply Chain Analysis
FDA UDI and CE marking requirements for medical-grade RF devices create qualification barriers that filter component suppliers to certified semiconductor fabricators. RTLS hardware draws from Taiwan, South Korea, and Malaysia for RF chip fabrication, with battery modules sourced from Japan and China. Single-source vulnerability concentrates in BLE and UWB chipset supply where qualified alternative suppliers remain limited. Distribution runs through biomedical equipment distributors and direct hospital system contracts, with GPO procurement frameworks consolidating purchasing leverage for large IDNs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as platform vendors pursue captive control over sensor hardware to escape commodity margin compression in software-only offerings.
For Market Incumbents: To counter margin erosion from cloud-native entrants, Zebra Technologies and CenTrak should deepen backward integration into proprietary sensor manufacturing and expand edge computing R&D to differentiate inference capabilities. Securitas Healthcare must anchor security-centric workflows through deeper integration with hospital access control systems to defend against pure-play RTLS specialists expanding into physical security. For New Entrants and Emerging Players: Price-sensitive community hospitals in India and Southeast Asia represent the most penetrable buyer archetype for subscription-based managed service models that eliminate upfront capital barriers. AiRISTA Flow and Kontakt.io should target surgical center instrument tracking with simplified ultra-wideband deployments that require minimal IT infrastructure. Go-to-market success hinges on GPO partnership strategies that bypass lengthy individual hospital procurement cycles. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by electronic health record vendors seeking embedded location intelligence capabilities. Long-term viability favors platforms with demonstrated FHIR interoperability and recurring revenue concentration above hardware transactional exposure. Watch FDA UDI enforcement intensity and EU MDR implementation timelines as inflection indicators for replacement demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Hardware Backward Integration | Captive RF chipset supply insulates margins from foundry concentration risks in Taiwan and South Korea. |
| HL7 FHIR Interoperability Certification | Seamless EHR integration becomes table stakes for enterprise IDN procurement committees evaluating vendors. |
| Subscription Revenue Model Transition | Hardware-as-a-service arrangements reduce capital barriers for mid-size hospitals and generate predictable recurring streams. |
| Ultra-Wideband Precision Deployment | Sub-meter accuracy for surgical instrument tracking unifies previously separate capital budgets for RTLS and safety systems. |
| EU MDR Article 27 Compliance Pathway | Multi-modal scanning capabilities accommodating legacy barcodes and data matrix formats capture European replacement demand. |
Research Methodology
Document review covered FDA UDI guidance documents, EU MDR implementation timelines, and hospital procurement databases, complemented by interviews with biomedical engineering directors, health system CFOs, GPO contracts managers, and RTLS platform product strategists. Secondary validation drew from SEC filings of publicly traded vendors, CMS Medicare equipment utilization data, and GPO contract award disclosures. Bottom-up segmentation modeling triangulated against top-down health system capital expenditure patterns.
Historical deployment trajectories cross-referenced against expert panel assessments of regulatory enforcement intensity and technology adoption curves across the projection horizon. Segmentation dimensions modeled include solution type, application workflow, facility scale, and deployment architecture. CAGRs derived from equipment replacement cycle analysis, health system consolidation rates, and IoT sensor cost decline curves. Forecast inputs incorporated FDA inspection frequency data and EU MDR notified body certification timelines.
Revisions become necessary when semiconductor supply disruptions, regulatory enforcement delays, or health system merger activity materially diverge from baseline assumptions. Forecasts reflect documented assumptions about technology cost trajectories and reimbursement pressure intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Healthcare Claims Management Software Market
Healthcare IT
Pharmaceutical Quality Management Systems Market
Healthcare IT
Global Accountable Care Solutions Market
Healthcare IT
Global Cancer Registry Software Market
Healthcare IT
Healthcare AIDC Market
Healthcare IT
Wearable Biosensors Market
Healthcare IT
Healthcare IT Market
Healthcare IT
Healthcare IT Provider Market
Healthcare IT
US Healthcare IT Market
Healthcare IT
Healthcare Contact Center Solution Market
Healthcare IT
Americas Healthcare Human Resources (HR) Software Market
Healthcare IT
Global IT Spending in Healthcare Market
Healthcare IT
Cancer Patient Registry Software Market
Healthcare IT
Patient Registry Software Market
Healthcare IT
Healthcare IT Consulting Services Market
Healthcare IT
Clinical Communication and Collaboration Market