
 Glottic Cancer Treatment Market | 2026-2036
Glottic Cancer Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Glottic Cancer Treatment Market Foresight
North American biopharma manufacturing is consolidating around precision oncology capacity for head and neck malignancies. Novartis leverages its radioligand therapy infrastructure to anchor supply of targeted glottic interventions. Bristol-Myers Squibb competes through checkpoint inhibitor portfolios that sustain physician preference in recurrent disease settings. Merck & Co differentiates via pembrolizumab's established reimbursement in first-line squamous cell carcinoma of the head and neck.
Glottic cancer treatment encompasses multimodal management of malignant neoplasms arising from the true vocal cords, typically employing organ-preserving strategies that balance oncologic control with phonatory function through transoral laser microsurgery, intensity-modulated radiation therapy, and systemic agents targeting EGFR or PD-1 pathways. Surgery and radiation therapy remain the structural backbone of early-stage care, capturing stable margin pools where larynx preservation rates exceed 80 percent in T1-T2 disease. Immunotherapy represents the fastest-expanding treatment modality, with anti-PD-1 agents displacing platinum-doublet chemotherapy in recurrent and metastatic segments where survival endpoints have shifted meaningfully.
FDA oncology center of excellence reviews shape trial design and label expansion timelines for glottic cancer therapeutics, while EMA's Committee for Medicinal Products for Human Use coordinates centralized access across European member states. NMPA in China and PMDA in Japan maintain distinct local clinical data requirements that fragment regulatory submission strategies for multinational sponsors. Stakeholders must monitor biomarker-defined patient selection criteria and evolving health technology assessment methodologies as these will determine commercial access and pricing power across major markets.
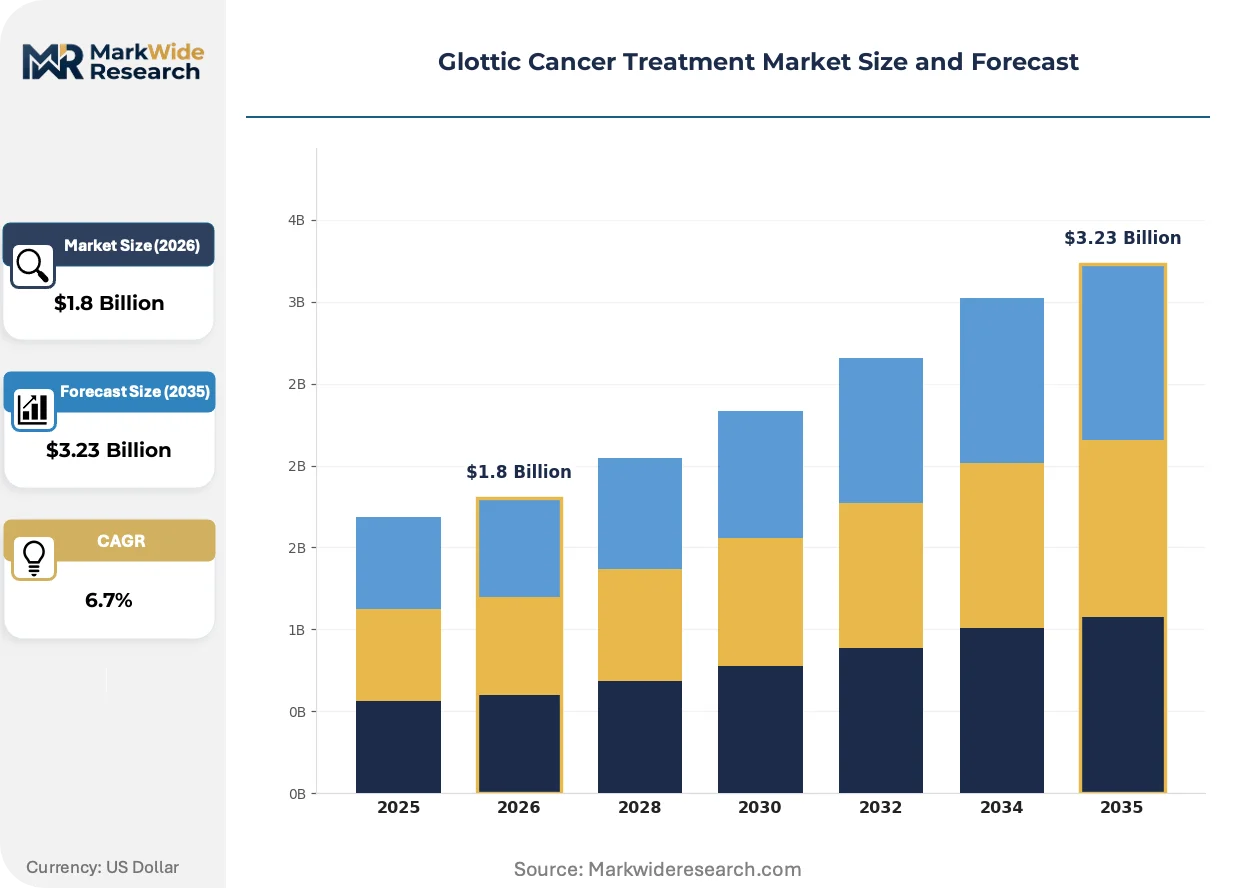
Market Dynamics
The larynx-preservation imperative is compressing surgical margins while expanding radiation and systemic therapy volumes, forcing reimbursement recalibration across major markets.
Growth Catalysts
- EMA Accelerated Assessment:The centralized European pathway compresses regulatory timelines for head and neck oncology biologics, pulling investment toward glottic-specific trials.
- Transoral Robotic Surgery:TORS platforms enable resection precision that preserves phonatory function in early-stage disease, expanding eligible patient pools beyond traditional laser microsurgery candidates.
- Japan's Specialized Cancer Center Clustering:Concentrated expertise in Tokyo and Osaka generates referral gravity that standardizes organ-preserving protocols across the national treatment network.
Market Restraints
- Platinum Supply Concentration:Cisplatin and carboplatin dependence for concurrent chemoradiation creates vulnerability to South African and Russian mining disruptions that propagate through oncology supply chains.
- Reimbursement Compression:Germany's G-BA health technology assessments impose outcome-based pricing ceilings that constrain margin expansion for novel immunotherapies in recurrent disease.
- Technical Limitation in Salvage Surgery:Post-radiation fibrosis and tissue necrosis elevate complication rates for surgical intervention after failed organ-preservation, restricting retreatment options.
Strategic Opportunities
- Biomarker-Defined Subpopulations:PD-L1 and TMB stratification enables targeted trial design that satisfies FDA's Project Orbis for simultaneous multi-regional approval.
- India's Underserved Tertiary Network:Radiation therapy capacity gaps in tier-2 cities create partnership openings for telemedicine-guided treatment planning and equipment leasing models.
- Radioligand-Convergence:Theranostic pairing of diagnostic PET tracers with targeted alpha-emitters is modularizing treatment sequences that bypass systemic chemotherapy toxicity.
Industry Challenges
- Laryngology-Oncology Coordination Gap:Voice rehabilitation specialists remain concentrated in academic centers, creating post-treatment care deserts that degrade functional outcomes.
- Legacy EHR Integration:Speech analysis tools for post-treatment monitoring require custom API development against entrenched hospital information systems that resist interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glottic Cancer Treatment Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Modality: Surgery, Radiation Therapy, Chemotherapy, Targeted Therapy, Immunotherapy Stage of Cancer: Early Stage, Locally Advanced, Recurrent, Metastatic End User: Oncology Clinics, Specialized Cancer Centers, Community Hospitals, Research Institutes Healthcare Setting: Inpatient Facilities, Outpatient Facilities, Ambulatory Surgical Centers, Palliative Care Units |
| Companies Covered | Novartis, Bristol-Myers Squibb, Merck & Co, Eli Lilly and Company, Pfizer Inc, Amgen, Roche, Cipla, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glottic Cancer Treatment Market Shifts & Advancements
Functional preservation metrics are displacing pure survival endpoints in trial design, while real-world evidence generation is compressing the gap between regulatory approval and clinical adoption.
Artificial intelligence-based voice analysis is modularizing post-treatment surveillance by enabling remote detection of recurrence through smartphone-captured vocal biomarkers. Community oncology practices in the United States are piloting these platforms to reduce specialist visit burden. The technology is compressing geographic barriers to specialist-level monitoring in rural catchment areas.
REACH regulation amendments are tightening disclosure requirements for cobalt-60 sourcing in radiation equipment, forcing European linear accelerator manufacturers to revalidate supply chain documentation. Treatment centers in Germany and France face extended procurement timelines as vendors reconfigure supplier audits. The policy is accelerating migration toward electronic brachytherapy alternatives that eliminate isotope dependence.
Consolidated purchasing by United States hospital networks is compressing vendor margins and unbundling service contracts from equipment leases. Integrated delivery networks in Texas and Florida now separate technical service agreements from capital acquisition, treating maintenance as competitive bid. The shift is most visible in radiation oncology where proton therapy centers face extended payback periods under volume-guarantee structures.
Glottic Cancer Treatment Market Segmentation
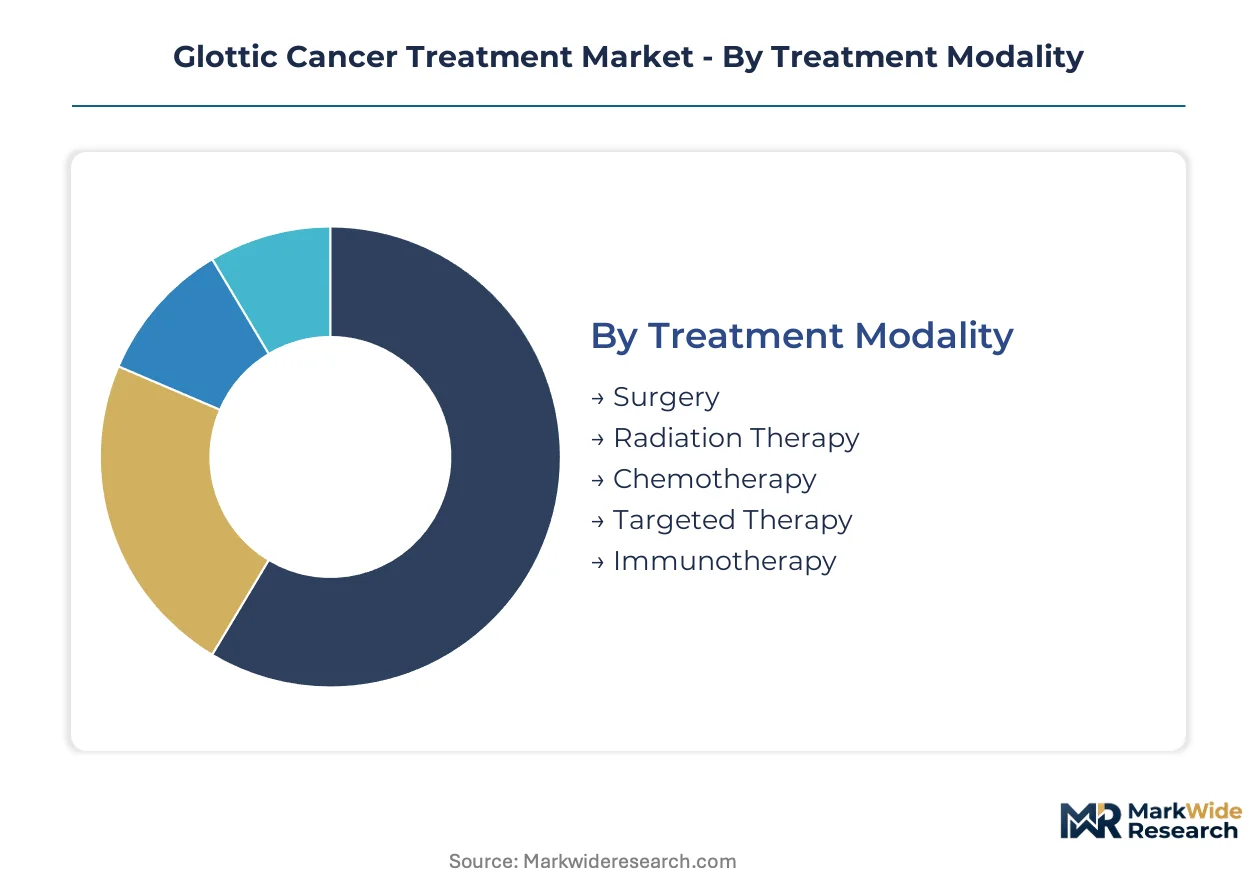
Glottic cancer treatment segmentation reveals how organ-preservation protocols redistribute patient volumes across modalities and care settings. Stage-specific pathways and reimbursement structures determine where value concentrates within the treatment continuum.
Treatment Modality:
Supply of advanced therapeutic platforms clusters in academic medical centers with laryngology subspecialty depth, concentrating margin capture where technical complexity is highest.
- Surgery:Transoral laser microsurgery and transoral robotic surgery (TORS) platforms enable precision resection of T1-T2 lesions with phonatory function preservation. Demand concentrates in specialized cancer centers across the United States, Germany, and Japan where fellowship-trained laryngologists anchor referral networks.
- Radiation Therapy:Intensity-modulated radiation therapy (IMRT) and proton therapy deliver dose-escalated treatment with parotid-sparing protocols. Volume is climbing fastest in community hospital settings where linear accelerator capacity has expanded under certificate-of-need reforms in select US states.
- Chemotherapy:Platinum-based concurrent chemoradiation remains the structural backbone for locally advanced disease, though supply vulnerability to mining disruptions constrains protocol stability.
- Targeted Therapy:EGFR inhibitors occupy a narrowing niche as immunotherapy displaces systemic options in recurrent settings, with prescribing concentrated in tertiary centers with molecular profiling capacity.
- Immunotherapy:Anti-PD-1 agents are expanding most quickly across all healthcare settings as first-line standards shift in recurrent and metastatic segments.
Today's leader: Surgery. Tomorrow's challenger: Immunotherapy.
Stage of Cancer:
Cost tier stratification separates curative-intent protocols with durable reimbursement from palliative segments where outcome-based pricing pressures concentrate.
- Early Stage:T1-T2N0 disease management relies on single-modality surgery or radiation with larynx preservation rates exceeding 80 percent. Patient volumes cluster in high-throughput centers where transoral platforms enable same-day discharge protocols.
- Locally Advanced:T3-T4 and node-positive disease requires multimodal chemoradiation with surgical salvage reserved for non-responders. Germany's G-BA assessments impose outcome-based pricing ceilings that constrain margin expansion for novel combination regimens.
- Recurrent:Salvage laryngectomy and re-irradiation protocols face technical limitations from post-treatment fibrosis, restricting retreatment options to specialized centers with microvascular reconstruction capability.
- Metastatic:Systemic therapy dominates with immunotherapy displacing platinum-doublet chemotherapy, though geographic access disparities persist between urban academic centers and community oncology practices.
Early stage commands volume. Locally advanced commands investment.
End User:
Customer type fragmentation reflects the coordination gap between laryngology, radiation oncology, and medical oncology in care pathway design.
- Oncology Clinics:Community-based practices are piloting AI-based voice surveillance platforms to reduce specialist visit burden and extend monitoring reach into rural catchment areas.
- Specialized Cancer Centers:Concentrated expertise in Tokyo, Osaka, Houston, and Boston generates referral gravity that standardizes organ-preserving protocols and anchors clinical trial enrollment.
- Community Hospitals:Radiation therapy capacity expansion under integrated delivery network purchasing contracts is compressing vendor margins and unbundling service agreements from equipment leases.
- Research Institutes:Biomarker-defined trial design for PD-L1 and TMB stratification satisfies FDA's Project Orbis for simultaneous multi-regional approval.
Specialized cancer centers set standards. Community hospitals scale access.
Healthcare Setting:
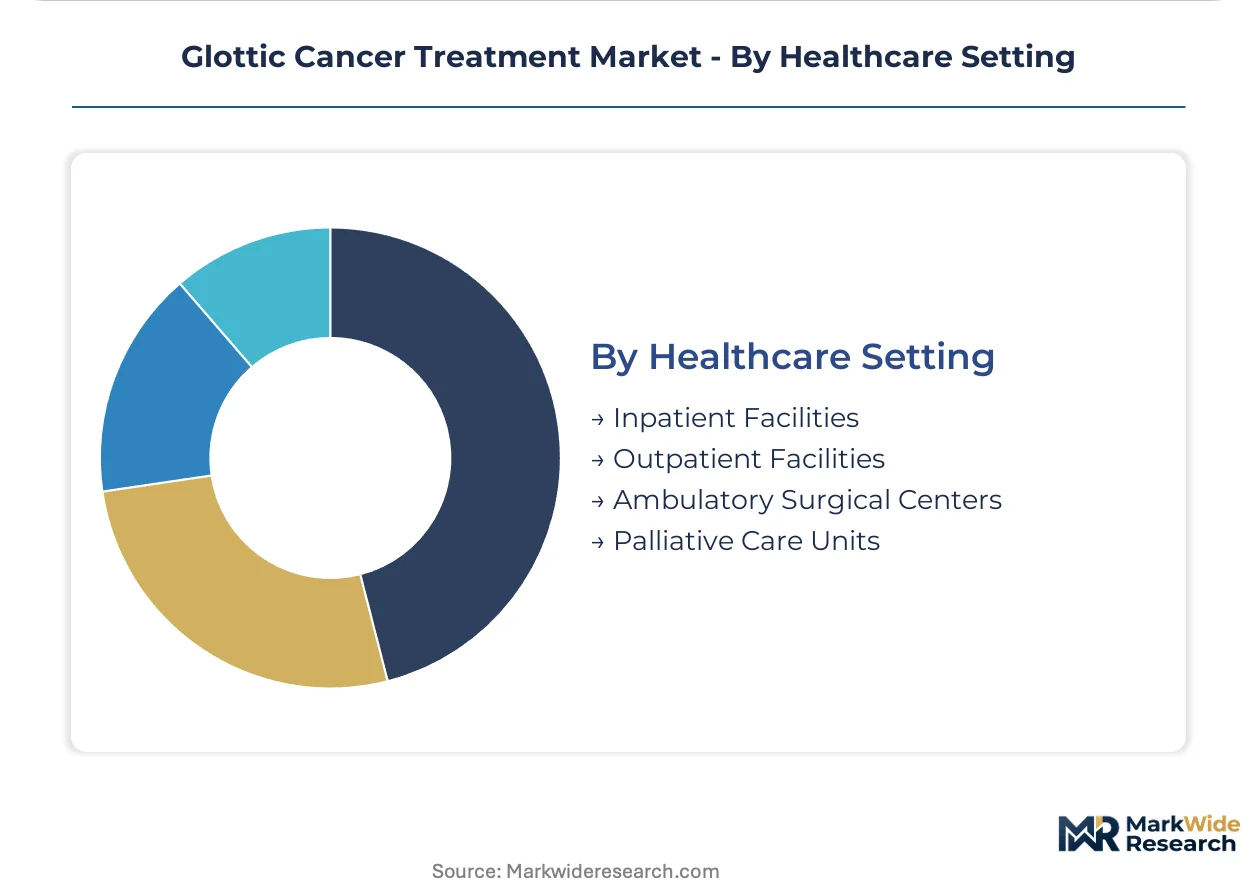
Volume migration toward outpatient and ambulatory settings reflects payer pressure to reduce inpatient costs for procedures with established safety profiles.
- Inpatient Facilities:Total laryngectomy and complex salvage surgery require microvascular flap reconstruction and intensive airway management, anchoring high-acuity margin pools.
- Outpatient Facilities:Transoral laser microsurgery and radiation therapy fractions are shifting to ambulatory platforms as reimbursement incentives align with shortened length-of-stay targets.
- Ambulatory Surgical Centers:TORS procedures for select T1-T2 lesions are migrating to freestanding facilities where facility fees and anesthesia costs concentrate value capture.
- Palliative Care Units:Voice rehabilitation and dysphagia management address functional outcomes in advanced disease, though specialist concentration in academic centers creates post-treatment care deserts.
Inpatient facilities retain complexity. Outpatient facilities capture volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where glottic cancer clinical trials concentrate, with sponsors migrating investment toward jurisdictions offering accelerated review pathways and differentiated reimbursement frameworks. Manufacturing capacity for precision oncology biologics is clustering in countries with established radioligand infrastructure and specialized cancer center density.
United States
FDA's Oncology Center of Excellence anchors the fastest regulatory timelines for head and neck biologics, pulling Phase III enrollment toward Houston and Boston academic clusters. The agency's Project Orbis framework enables simultaneous multi-regional submission that compresses approval windows for PD-1 pathway inhibitors. Specialized cancer centers in Texas and Florida generate referral gravity that standardizes organ-preserving protocols across integrated delivery networks.
Germany
G-BA health technology assessments impose outcome-based pricing ceilings that constrain margin expansion for novel immunotherapies in recurrent disease settings. EMA's centralized accelerated assessment pathway pulls sponsor investment toward Munich and Heidelberg trial sites. The country's linear accelerator manufacturing base faces extended procurement timelines under REACH cobalt-60 disclosure amendments, accelerating migration toward electronic brachytherapy alternatives.
Japan
PMDA maintains distinct local clinical data requirements that fragment regulatory submission strategies for multinational sponsors, though Sakigake designation offers expedited review for breakthrough therapies. Concentrated expertise in Tokyo and Osaka generates referral gravity that standardizes larynx-preserving protocols across the national treatment network. METI funding for proton therapy capacity expansion is redistributing patient volumes from academic centers to community hospital settings.
India
Radiation therapy capacity gaps in tier-2 cities create partnership openings for telemedicine-guided treatment planning and equipment leasing models. CDSCO's evolving oncology biologics pathway is attracting contract research organization investment toward Hyderabad and Bangalore. The country's platinum import dependence for concurrent chemoradiation creates supply vulnerability that domestic formulators are addressing through backward integration into active pharmaceutical ingredient production.
United Kingdom
NICE technology appraisals impose cost-effectiveness thresholds that delay patient access to checkpoint inhibitors compared to continental European markets. MHRA's post-Brexit recognition framework with FDA and Health Canada is repositioning London as a launchpad for multi-regional trial design. The NHS's concentrated purchasing power is consolidating radiation oncology service contracts around major academic centers in Manchester and Birmingham.
Glottic Cancer Treatment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue radioligand-convergence and AI-enabled surveillance platforms. The market structure consolidates around three archetypes: diversified oncology majors with checkpoint inhibitor portfolios, precision therapy specialists leveraging radioligand infrastructure, and emerging players in voice biomarker diagnostics. Strategic moves center on biomarker-defined trial design for regulatory differentiation and unbundling of radiation equipment service contracts from capital leases.
Among Swiss-based diversified majors, Novartis anchors the precision therapy tier through radioligand therapy infrastructure deployment. Bristol-Myers Squibb and Merck & Co represent competing positions in the checkpoint inhibitor segment, with each occupying distinct reimbursement footholds in head and neck oncology. These three entities exemplify how regulatory pathway expertise and manufacturing scale concentrate competitive advantage in this indication.
| Leading Market Players |
|---|
| Novartis |
| Bristol-Myers Squibb |
| Merck & Co |
| Eli Lilly and Company |
| Pfizer Inc |
| Amgen |
| Roche |
| Cipla |
| Sanofi |
| Others |
Supply & Pricing Matrix
REACH cobalt-60 disclosure amendments gate qualified radiation equipment supply and premium-tier pricing access for European treatment centers, forcing linear accelerator manufacturers to revalidate supplier audits while compressing procurement timelines for electronic brachytherapy alternatives.
Pricing Analysis
Distributor margins for radiation therapy equipment have compressed under consolidated purchasing by United States hospital networks. Three-tier pricing structure across premium, standard, and economy levels separates proton therapy centers from IMRT-capable community hospitals from basic linear accelerator installations. Pricing pressure stems from unbundled service contracts and volume-guarantee structures that extend equipment payback periods. Community hospitals exhibit highest price sensitivity, while specialized cancer centers prioritize phonatory function preservation metrics over capital cost.
Supply Chain Analysis
CE marking and FDA 510(k) clearance requirements gate entry for transoral robotic surgery platforms and radioligand therapy infrastructure. Manufacturing concentrates in the United States, Germany, and Japan where precision oncology capacity clusters. Platinum supply for concurrent chemoradiation draws from South African and Russian mining operations, creating single-source vulnerability for cisplatin and carboplatin formulation. Distribution runs through specialized cancer center procurement committees and integrated delivery network purchasing contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Glottic cancer treatment functions as a late-cycle quality story where reimbursement and functional preservation metrics now dominate investment decisions, with demand shifting toward larynx-preserving protocols that command premium pricing in specialized settings.
For Market Incumbents: To counter checkpoint inhibitor displacement in recurrent disease, Bristol-Myers Squibb and Merck & Co should deepen radioligand-convergence partnerships and anchor manufacturing scale in FDA's Project Orbis pathway for simultaneous multi-regional approval. Novartis must defend precision therapy positioning through theranostic pairing infrastructure that bypasses systemic chemotherapy toxicity.
For New Entrants and Emerging Players: Capture India's tier-2 radiation therapy capacity gaps through telemedicine-guided treatment planning partnerships and equipment leasing models that address platinum supply vulnerability. Voice biomarker diagnostic platforms offer the most penetrable entry point, with smartphone-captured surveillance reducing specialist visit burden in rural United States catchment areas.
For Investors and Strategic Acquirers: Roll-up economics work for AI-enabled voice surveillance platforms because post-treatment monitoring remains fragmented across academic and community settings with no dominant incumbent. Long-term viability hinges on FDA breakthrough device designation and CMS reimbursement coding. Watch for biomarker-defined trial enrollment velocity as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | PD-L1 and TMB stratification satisfies FDA's Project Orbis for multi-regional approval. |
| Regulatory Approval Pathway | EMA accelerated assessment compresses timelines for head and neck oncology biologics. |
| Manufacturing Scale-Up | Radioligand therapy infrastructure anchors supply of targeted glottic interventions. |
| Reimbursement Strategy | Pembrolizumab's established CMS coding secures first-line squamous cell carcinoma access. |
| Strategic Partnership | Telemedicine-guided planning partnerships address India's tier-2 radiation capacity gaps. |
Research Methodology
Direct dialogue with laryngology department heads, radiation oncology procurement managers, payer access specialists, and formulary directors grounded qualitative findings, cross-referenced against FDA oncology center of excellence filings, EMA accelerated assessment decisions, ClinicalTrials.gov enrollment data, and hospital GPO contract databases. Bottom-up and top-down triangulation validated segment-level volume estimates.
Top-down modeling anchored macro-level oncology spending trajectories while bottom-up patient-flow analysis tracked stage-specific treatment pathways across the projection horizon. Segmentation dimensions included treatment modality, cancer stage, end-user type, and healthcare setting, with CAGRs derived from enrollment velocity in biomarker-defined trials and radioligand therapy capacity expansion rates.
Underlying measurement precision varies by segment; immunotherapy and specialized cancer center revenue pools carry tighter precision than community hospital radiation volumes. Forecasts reflect assumptions regarding regulatory pathway timelines and reimbursement coding decisions. A model refresh is warranted upon material change in FDA's Project Orbis framework or EMA accelerated assessment criteria.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Cancer/Tumor Profiling Market
Oncology
North America Bone Metastasis Market
Oncology
Global Metastatic Melanoma Drugs Market
Oncology
Europe Tumor Ablation Market
Oncology
Thyroid Cancer Market
Oncology
Head and Neck Cancer Market
Oncology
Metastatic Breast Cancer Market
Oncology
Global Cancer Treatment Market
Oncology
Tumor Ablation Market
Oncology
Asia-Pacific Proton Therapy Market
Oncology
Asia-Pacific Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Global Oncology Clinical Trials Market
Oncology
Europe Proton Therapy Market
Oncology
Asia-Pacific Cancer Therapy Market
Oncology
Stomach Cancer Treatment Market
Oncology
Oncology Apoptosis Modulators Market