
 Global Emergency Department Information System Market | 2026-2036
Global Emergency Department Information System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Emergency Department Information System Market Foresight
Cloud-native architecture is fragmenting the traditional EDIS technology stack, forcing vendors to rebuild core platforms around microservices and API-first interoperability. Epic Systems Corporation anchors its position through deep integration with enterprise EHR ecosystems across major academic medical centers. Oracle Health leverages its cloud infrastructure to compete for health system contracts requiring scalable disaster recovery and multi-tenant deployment. MEDHOST specializes in community hospital configurations where capital constraints favor subscription pricing over perpetual licensing.
An Emergency Department Information System constitutes clinical workflow software engineered to manage patient throughput, triage protocols, documentation standards, and resource scheduling within acute care entry points, typically integrating HL7 FHIR interfaces for interoperability with ancillary systems. Cloud-Based Platforms represent the fastest-expanding product type as health systems prioritize remote accessibility and reduced IT overhead, while Integrated EHR Solutions sustain dominant share by embedding ED workflows within longitudinal patient records. On the application dimension, Triage Management commands concentrated vendor investment due to its direct impact on left-without-being-seen rates and liability exposure, whereas Reporting & Analytics emerges as a margin-rich layer as payers and regulators intensify performance transparency requirements.
FDA oversight of clinical decision support algorithms and HIPAA security rule enforcement by the Office for Civil Rights are elevating compliance costs for vendors seeking US market access, while ISO 13485 quality management expectations and IEC 62304 software lifecycle standards shape international competitive eligibility. The EU AI Act's risk classification framework for medical decision-support tools will further constrain deployment architectures for vendors serving European trauma centers and urgent care networks. Stakeholders must evaluate whether vendor roadmaps align with emerging interoperability mandates and evolving cybersecurity certification thresholds before committing to long-term platform contracts.
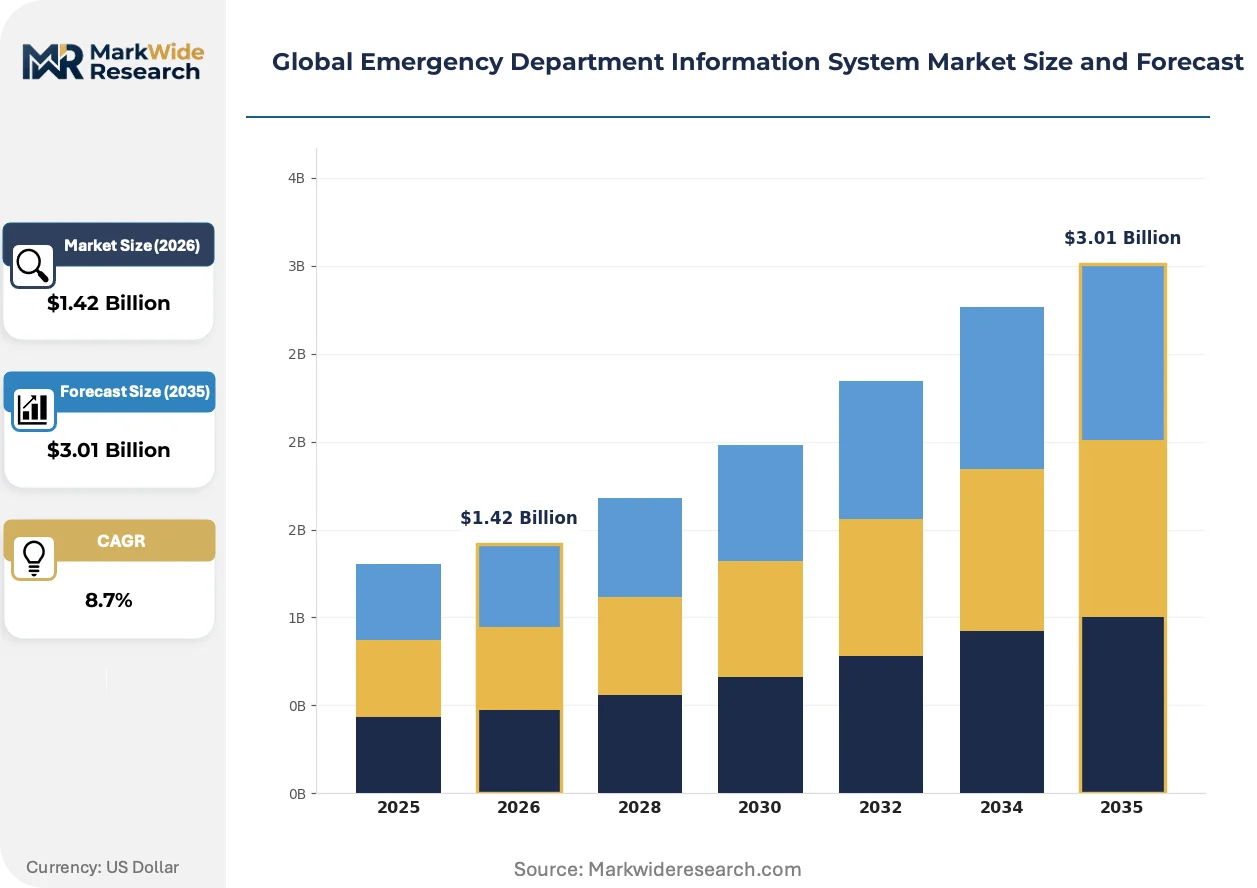
Market Dynamics
Cloud-native architecture is fragmenting the traditional Emergency Department Information System technology stack, forcing incumbent vendors to rebuild core platforms around microservices and API-first interoperability while health systems demand seamless EHR integration.
Growth Catalysts
- HIPAA Security Rule enforcement:The Office for Civil Rights is intensifying audits of emergency department data handling, compelling hospitals to upgrade to certified platforms with automated compliance monitoring.
- FHIR R4 adoption:Health systems are mandating HL7 FHIR interfaces for all new EDIS procurements to enable real-time data exchange with radiology, laboratory, and pharmacy systems.
- Academic medical center consolidation:Multi-facility networks in the United States are standardizing on single-vendor EDIS deployments to reduce interoperability friction across acquired hospitals.
Market Restraints
- Specialized clinical informatics talent scarcity:Emergency medicine workflow optimization requires hybrid clinical-technical expertise that commands premium compensation and extends implementation timelines.
- FDA 510(k) pathway complexity:Clinical decision support modules with diagnostic algorithms face elevated scrutiny under FDA guidance, delaying product launches by 12-18 months.
- Legacy on-premises infrastructure lock-in:Capital-constrained community hospitals retain depreciated server installations that resist cloud migration without substantial write-offs.
Strategic Opportunities
- Rural critical access hospitals:Federally qualified health centers in underserved United States regions lack modern triage systems and qualify for HRSA-funded technology modernization grants.
- Pediatric emergency department specialization:Age-specific triage protocols and weight-based dosing calculators represent an underdeveloped module category with distinct liability profiles.
- EU AI Act compliance services:European trauma centers will require risk classification documentation for algorithmic decision-support tools, creating advisory revenue streams for prepared vendors.
Industry Challenges
- EHR integration complexity:Epic, Cerner, and MEDITECH proprietary data models require vendor-specific connector development that fragments engineering resources.
- Cybersecurity certification timelines:HITRUST and SOC 2 Type II audits consume 9-14 months, delaying contract execution with security-conscious health systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Emergency Department Information System Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Systems, Integrated EHR Solutions, Cloud-Based Platforms, On-Premises Software Application: Patient Registration, Triage Management, Clinical Documentation, Resource Allocation, Reporting & Analytics End User: Emergency Clinics, Trauma Centers, Urgent Care Facilities, Specialty Hospitals Deployment: Cloud Deployment, Hosted Solutions, Hybrid Models, Local Server Installation |
| Companies Covered | Oracle Health, Epic Systems Corporation, MEDHOST, Medsphere Systems Corporation, EMIS Group, Evident Software, EPOWERdoc, T System, Veradigm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Emergency Department Information System Market Shifts & Advancements
Real-time predictive analytics and ambient clinical documentation are compressing documentation burden while regulators impose algorithmic transparency requirements on decision-support tools.
Natural language processing engines with ambient listening capabilities are capturing physician-patient encounters without keyboard interaction. Emergency departments in academic medical centers are piloting these tools to reduce documentation time per encounter. The technology is rendering obsolete traditional template-based charting that consumes 25-30% of physician shift time.
The EU AI Act's risk-based classification framework for medical decision-support software is imposing conformity assessment obligations on vendors serving European trauma centers. High-risk algorithms require notified body intervention and post-market surveillance systems. EDIS vendors with European deployments are restructuring product architectures to isolate risk-classified modules.
Subscription pricing with consumption-based tiers is displacing perpetual licensing in health system procurement. Community hospitals favor predictable operational expenditure over capital-intensive upfront purchases. This shift is most visible in United States markets where private equity-backed hospital operators prioritize cash flow predictability.
Global Emergency Department Information System Market Segmentation
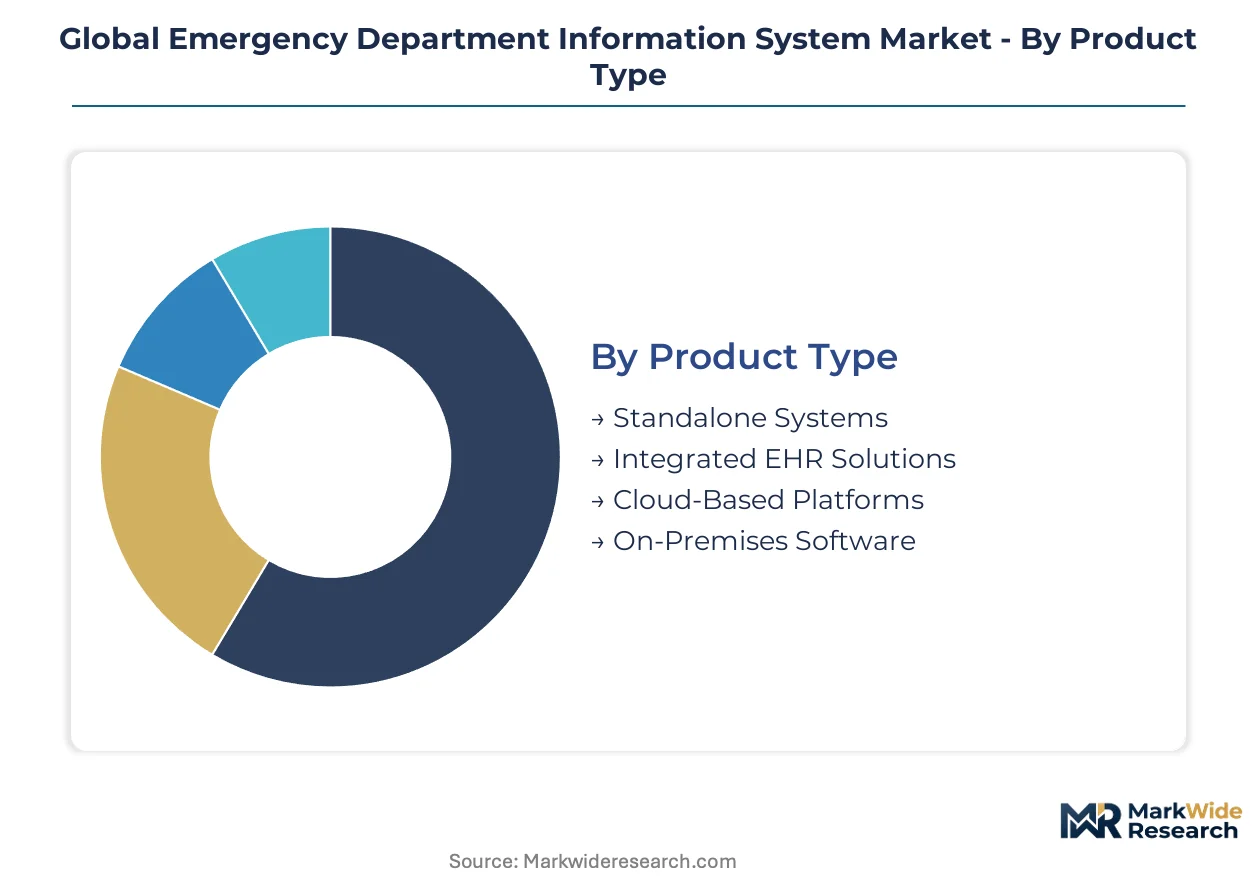
EDIS procurement cycles vary dramatically across product architectures and deployment models. Understanding which segments command premium investment versus rapid replacement helps vendors align R&D with actual purchasing rhythms.
Product Type:
Cloud-native platforms refresh on 3-5 year cycles as health systems chase interoperability mandates, while on-premises installations linger for 10-15 years due to capital depreciation schedules.
- Cloud-Based Platforms:Microservices architecture enables API-first integration with radiology and laboratory systems. United States academic medical centers prioritize these for disaster recovery scalability and multi-tenant management across consolidated networks.
- Integrated EHR Solutions:Embedded ED workflows within longitudinal patient records eliminate interface maintenance overhead. Epic Systems Corporation and Oracle Health dominate procurement at large health systems seeking unified data models.
- Standalone Systems:Best-of-breed triage and documentation modules serve specialty hospitals with unique workflow requirements.
- On-Premises Software:Perpetual licensing persists at capital-constrained community hospitals deferring cloud migration costs.
Integrated EHR Solutions dominate installed base. Cloud-Based Platforms is where expansion concentrates.
Application:
Revenue per module correlates directly with liability exposure reduction and regulatory reporting burden.
- Triage Management:Algorithmic acuity scoring with real-time capacity dashboards reduces left-without-being-seen rates. United States trauma centers invest heavily here due to malpractice liability concentration at intake decision points.
- Reporting & Analytics:Performance transparency layers extract premium pricing from payers and regulators demanding outcome metrics. Dashboards tracking door-to-provider times and admission conversion rates command subscription premiums.
- Clinical Documentation:Structured templates and ambient listening tools compress physician charting burden per encounter.
- Patient Registration:Insurance verification and demographic capture modules integrate with revenue cycle systems.
- Resource Allocation:Bed management and staffing optimization tools balance throughput against surge capacity.
Triage Management commands highest per-module pricing. Reporting & Analytics is gaining share fastest as value-based contracts proliferate.
End User:
Procurement authority and technical sophistication diverge sharply across acute care settings.
- Trauma Centers:Level I and II facilities require specialized mass casualty protocols and regional coordination capabilities. These sites mandate FDA-compliant clinical decision support for diagnostic algorithms under heightened regulatory scrutiny.
- Emergency Clinics:High-volume urban departments prioritize throughput optimization and rapid EHR integration. Cloud deployment dominates as IT staffing constraints favor vendor-managed infrastructure.
- Urgent Care Facilities:Retail health locations need lightweight triage systems with consumer-facing check-in workflows.
- Specialty Hospitals:Pediatric and psychiatric EDs demand age-specific protocols distinct from general acute care templates.
Emergency Clinics represent largest addressable volume. Trauma Centers is where margin expansion concentrates.
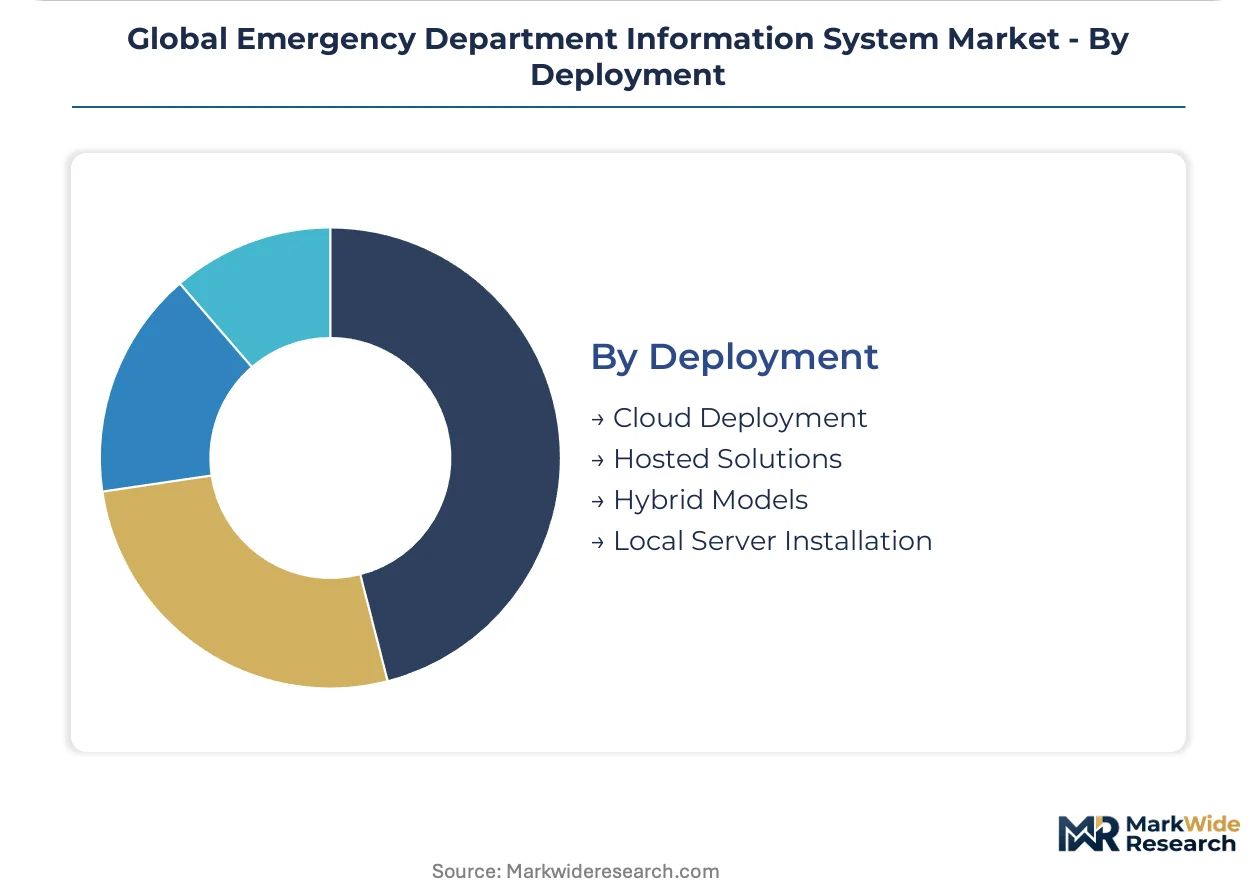
Deployment:
Operational expenditure preferences are displacing capital-intensive ownership models across health system tiers.
- Cloud Deployment:Subscription pricing with consumption-based tiers eliminates upfront licensing costs. Private equity-backed United States hospital operators favor predictable cash flow profiles over depreciated server assets.
- Hybrid Models:Sensitive patient data remains on local servers while analytics workloads shift to cloud infrastructure. This architecture satisfies HIPAA Security Rule requirements for controlled access while enabling scalable compute.
- Hosted Solutions:Vendor-managed private cloud instances serve mid-size health systems lacking internal cloud expertise.
- Local Server Installation:Fully on-premises deployments persist where connectivity reliability concerns or legacy integration requirements block migration.
Local Server Installation still anchors legacy installed base. Cloud Deployment is where new contract value concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net EDIS technology flows concentrate toward the United States, which imports specialized clinical decision support modules while exporting cloud-native platform architectures to English-speaking markets. Germany and the United Kingdom generate surplus intellectual property in FHIR interoperability standards. Japan and Australia remain net importers of emergency department workflow software.
United States
Academic medical center consolidation drives standardization across multi-facility networks, with health systems mandating single-vendor deployments to reduce interface friction. HIPAA Security Rule enforcement by the Office for Civil Rights compels hospitals to upgrade certified platforms with automated compliance monitoring. The Boston-Cambridge cluster anchors development of ambient clinical documentation tools, with Massachusetts General Hospital piloting NLP engines that capture physician-patient encounters without keyboard interaction.
Germany
University hospitals in Bavaria and Baden-Württemberg prioritize ISO 13485-certified platforms for trauma center accreditation, creating demand for quality-managed software lifecycles. The EU AI Act's risk classification framework imposes conformity assessment obligations on algorithmic decision-support tools deployed at Charité Berlin and Heidelberg University Hospital. The Rhine-Main metropolitan region concentrates vendor advisory services helping European trauma centers document risk classification for high-risk algorithms.
United Kingdom
NHS England's Federated Data Platform procurement mandates HL7 FHIR R4 interfaces for all emergency department systems, accelerating replacement of legacy installations. NHS Digital's cybersecurity standards require HITRUST certification for cloud deployments handling patient identifiable data. London's King's College Hospital and St Thomas' Hospital serve as reference sites for integrated EHR solutions embedding ED workflows within longitudinal patient records.
Japan
Metropolitan Tokyo emergency departments face capacity constraints that drive investment in predictive analytics for patient throughput optimization. The Ministry of Health, Labour and Welfare's reimbursement reforms tie emergency department efficiency metrics to hospital payment rates. Osaka University Hospital and Nagoya University Hospital anchor adoption of cloud-native platforms with multi-tenant management for regional hospital networks.
Australia
State health departments in New South Wales and Victoria consolidate procurement for emergency department information systems to achieve economies of scale across public hospital networks. The Australian Digital Health Agency's interoperability standards mandate FHIR interfaces for federal funding eligibility. Melbourne's Alfred Hospital and Royal Melbourne Hospital pilot pediatric emergency department specialization modules with age-specific triage protocols.
Global Emergency Department Information System Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: enterprise EHR-integrated platforms, cloud-native best-of-breed specialists, and community hospital subscription providers. Strategic archetypes include academic medical center anchors, private equity-backed consolidation plays, and regional workflow customization shops. Dominant competitive moves involve API-first interoperability certification and vertical integration into ambient clinical documentation technology.
Within the enterprise-integrated tier, Epic Systems Corporation and Oracle Health occupy positions defined by their anchoring relationships with major academic medical centers and health system consolidation plays. MEDHOST exemplifies the community hospital subscription model, with its positioning reflecting capital-constrained facility preferences for operational expenditure over perpetual licensing. These three companies collectively represent the spectrum of deployment architectures reshaping procurement patterns across United States health systems.
| Leading Market Players |
|---|
| Oracle Health |
| Epic Systems Corporation |
| MEDHOST |
| Medsphere Systems Corporation |
| EMIS Group |
| Evident Software |
| EPOWERdoc |
| T System |
| Veradigm |
| Others |
Supply & Pricing Matrix
Trans-Pacific fiber-optic latency corridors linking United States health systems to Singapore and Sydney data centers concentrate cloud-hosting costs, enabling Oracle Health and Epic Systems Corporation to extract subscription premiums from academic medical centers while forcing price compression on community hospital tiers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers command subscription premiums through HITRUST certification and FDA 510(k) compliance, while standard offerings compete on FHIR R4 interoperability. Price differentiation rests on certification grade and after-sales implementation support. Pricing pressure stems from private equity-backed hospital operators demanding consumption-based SaaS tiers. Community hospitals exhibit highest price sensitivity; academic medical centers prioritize compliance over cost.
Supply Chain Analysis
Contract manufacturing for EDIS hardware concentrates in Taiwan's server foundries and South Korea's memory fabrication facilities. Software development draws from engineering talent pools in India and Poland. Raw material dependencies include semiconductor-grade silicon, specialized medical-grade displays, and encrypted storage arrays. Single-source vulnerability runs through Taiwan's advanced node capacity. Distribution runs through vendor-managed private cloud instances and direct health system sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
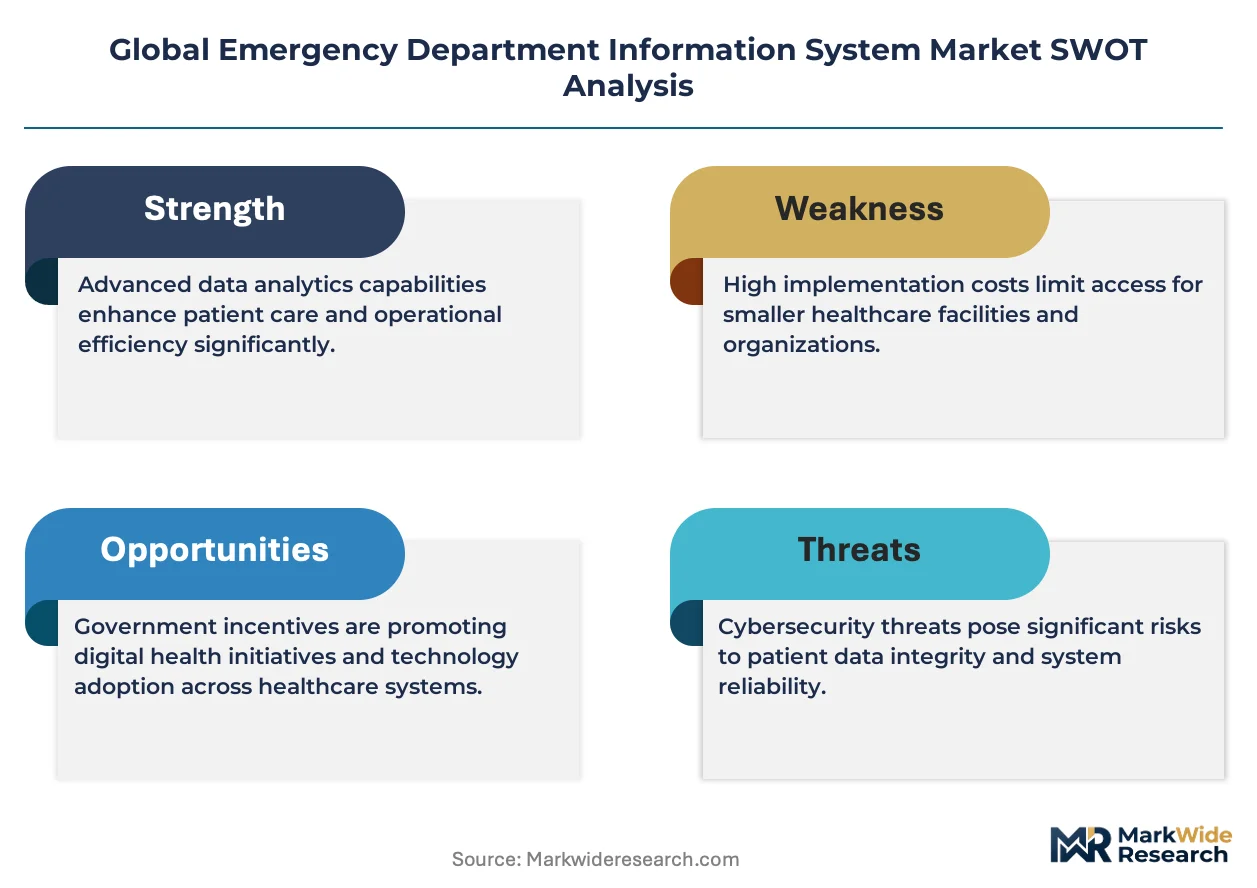
Cloud-native architecture disruption and EU AI Act risk classification mandates create a high-growth inflection where regulatory compliance becomes the primary competitive moat.
For Market Incumbents: Entrench platform stickiness through backward integration into ambient clinical documentation technology and captive API-first interoperability certification. Defend against best-of-breed triage specialists by embedding ED workflows deeper within longitudinal EHR records. Prioritize HITRUST and SOC 2 Type II certification investments to extend contract execution timelines as a barrier. For New Entrants and Emerging Players: Establish a beachhead in pediatric emergency department specialization where age-specific triage protocols remain underdeveloped. Target rural critical access hospitals eligible for HRSA-funded technology modernization grants. Deploy lightweight cloud-native triage modules with subscription pricing to bypass capital-intensive procurement cycles. For Investors and Strategic Acquirers: FDA clinical decision support algorithm guidance reshapes the acquisition landscape toward vendors with cleared diagnostic modules. Long-term viability centers on platforms with European trauma center deployments capable of EU AI Act conformity assessment. Monitor FDA 510(k) clearance velocity as the signal indicating which algorithmic decision-support architectures achieve sustainable market access.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Epic Systems Corporation's deep EHR embedding reduces interface friction across consolidated United States health systems. |
| Regulatory Certification Investment | HITRUST and SOC 2 Type II audits unlock contracts with security-conscious academic medical centers. |
| Geographic Expansion | European trauma center deployments require EU AI Act risk classification documentation and notified body relationships. |
| Acquisition of Specialist Firm | Pediatric ED workflow specialists offer distinct liability profiles and age-specific protocol libraries. |
| Strategic Partnership | Cloud infrastructure alliances with hyperscalers enable multi-tenant disaster recovery for consolidated hospital networks. |
Research Methodology
A spread of perspectives from emergency department physicians, hospital purchasing committee chairs, biomedical informatics directors, and GPO contracts managers converged on the working assumptions. Primary interviews with health system CTOs and EDIS implementation specialists combined with secondary validation against FDA 510(k) filings, hospital procurement databases, CMS Medicare reimbursement data, and HL7 FHIR adoption reports. Bottom-up vendor revenue triangulation against top-down health system IT spending analysis anchored volume estimates.
Demand-supply balance modeling across the projection horizon incorporated deployment architecture, health system size tier, integration complexity, and regional regulatory cluster as segmentation dimensions. CAGRs derived from S-curve adoption modeling and replacement cycle analysis. Forecast inputs included academic medical center consolidation velocity and cloud-native platform refresh rates.
Sensitivities concentrate around FDA enforcement discretion shifts and EU AI Act implementation timelines. Forecasts reflect documented assumptions on interoperability mandate adoption and cybersecurity certification thresholds. Quarterly review of 510(k) clearance backlogs and health system cloud migration announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Global Healthcare Revenue Cycle Management Market
Healthcare IT
Dental Implantology Software Market
Healthcare IT
Chiropractic Software Market
Healthcare IT
Veterinary Dental Software Market
Healthcare IT
Global Pharmacy Management System Market
Healthcare IT
Healthcare IT Consulting Services Market
Healthcare IT
Hospital Workforce Management Software Market
Healthcare IT
Americas Healthcare Human Resources (HR) Software Market
Healthcare IT
US Healthcare IT Market
Healthcare IT
Global Technology Spending on Core Administration in Healthcare Market
Healthcare IT
Healthcare Revenue Cycle Management (RCM) Software Market
Healthcare IT
Global Pharmacy Inventory Management Software Solutions and Cabinets Market
Healthcare IT
US Dental Clearing Houses Market
Healthcare IT
Global IT Spending in Healthcare Market
Healthcare IT
Global Back-End Revenue Cycle Management Market
Healthcare IT
Clinical Perinatal Software Market