
 Global Hospital Asset Tracking and Inventory Management Systems Market | 2026-2036
Global Hospital Asset Tracking and Inventory Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hospital Asset Tracking and Inventory Management Systems Market Foresight
The EU Medical Device Regulation is consolidating procurement standards across European hospital networks, forcing legacy asset tracking upgrades. Zebra Technologies leverages its RFID hardware portfolio to anchor enterprise deployments across integrated delivery networks. CenTrak competes on real-time location system accuracy in operating room environments. GE Healthcare extends its imaging equipment installed base into predictive maintenance contracts that bundle asset tracking software.
Hospital asset tracking and inventory management systems combine RFID tags, barcode scanners, BLE beacons, and software platforms to locate medical devices, monitor sterilization cycles, and automate reordering of consumables. These systems typically operate on 433 MHz or 2.4 GHz bands with location granularity ranging from room-level to sub-meter precision, depending on ultra-wideband or infrared augmentation. Hardware Devices dominate current revenue as hospitals retrofit existing equipment with RFID and BLE tags, while Cloud-based Platforms represent the fastest-expanding segment as IT departments shift capital expenditure to operational expenditure models. Integrated Systems command premium pricing by unifying previously siloed tracking, maintenance, and supply chain modules.
The FDA enforces unique device identification requirements that mandate track-and-trace capabilities for high-risk medical devices, directly expanding addressable demand for compliant software. EMA's MDR traceability provisions and Japan's METI-promoted JIS standards for healthcare IoT security create parallel compliance burdens that shape product roadmaps. Stakeholders must monitor how FDA UDI Phase 3 enforcement timelines and EU AI Act risk classifications for predictive inventory algorithms reshape vendor certification requirements.
Market Dynamics
Cloud migration is compressing hospital IT procurement cycles as multi-facility networks abandon perpetual licenses for subscription models, forcing vendors to restructure revenue recognition and customer success functions around recurring retention metrics.
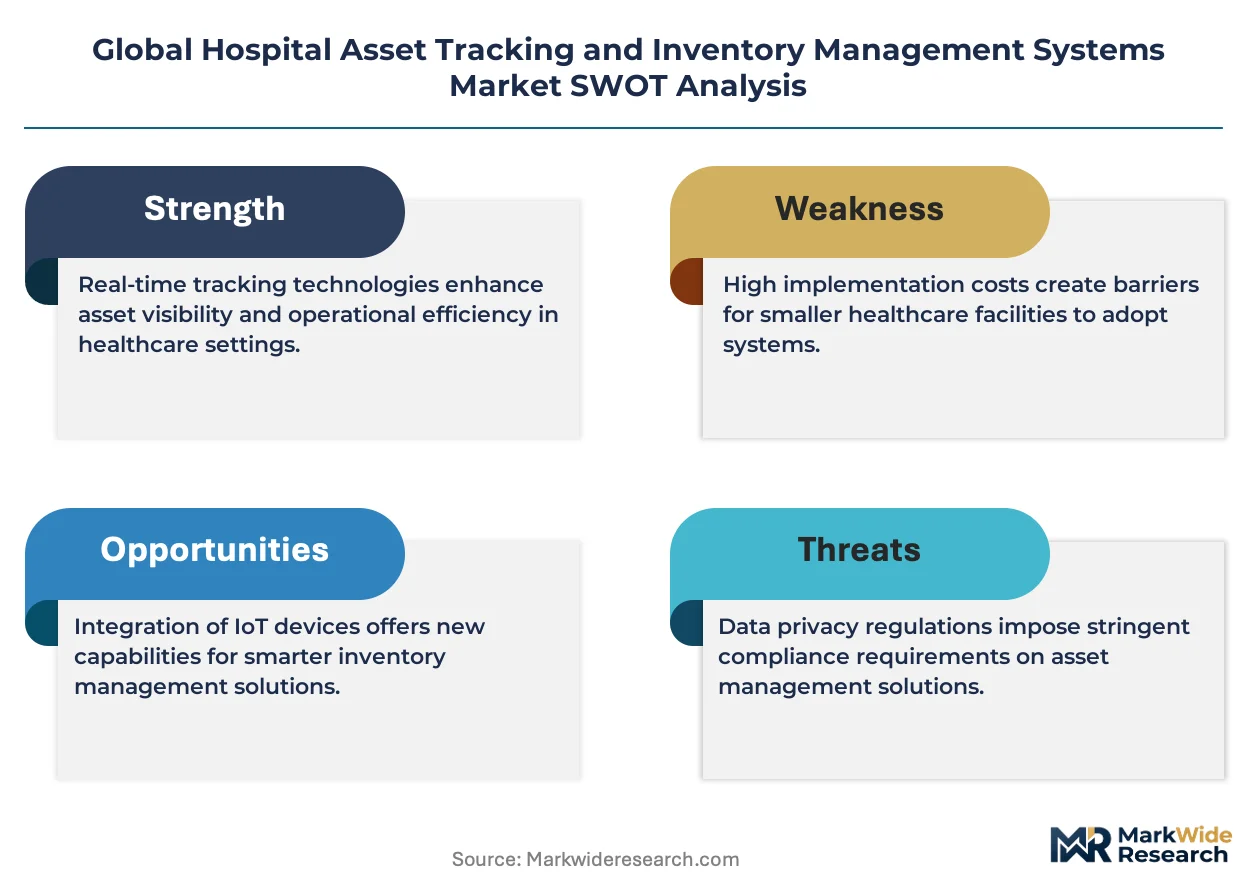
Growth Catalysts
- FDA UDI Phase 3 enforcement:The mandate for unique device identification on high-risk medical devices compels health systems to deploy track-and-trace software, directly expanding compliant platform demand.
- Workforce shortages in Germany, United Kingdom, and Japan:Hospital networks in these markets are automating inventory reconciliation to offset nursing and supply chain staffing gaps.
- BLE beacon density:Low-energy Bluetooth infrastructure is achieving room-level location granularity at one-third the hardware cost of ultra-wideband, accelerating retrofit adoption.
Market Restraints
- RFID tag cost volatility:Passive tag prices fluctuate with copper and aluminum futures, squeezing margins on high-volume consumables tracking deployments.
- Legacy EHR integration friction:Proprietary data formats in Cerner and Epic installations require expensive middleware development for real-time asset location feeds.
- Substitution by barcode-plus-vision systems:Computer vision cameras for surgical instrument counting are displacing RFID in sterile processing departments at lower total cost.
Strategic Opportunities
- India's hospital accreditation expansion:NABH standards are mandating asset traceability for tier-2 and tier-3 cities, creating first-mover advantage for cloud-native vendors.
- Predictive maintenance convergence:Machine learning algorithms fused with vibration sensors on infusion pumps enable failure prediction 48-72 hours before clinical impact.
- EU AI Act risk classification:Predictive inventory algorithms classified as high-risk systems will require conformity assessment, creating certification service revenue streams.
Industry Challenges
- RF engineer scarcity:Site survey and interference mitigation for 2.4 GHz deployments in steel-and-concrete hospital structures requires specialized talent concentrated among systems integrators.
- Multi-vendor interoperability:BLE, ultra-wideband, and infrared location feeds must normalize into single dashboards, demanding FHIR-compliant data architecture investments.
- Joint Commission audit preparation:Documentation of preventive maintenance intervals for tracked devices consumes clinical engineering hours that compete with urgent repair backlogs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hospital Asset Tracking and Inventory Management Systems Market |
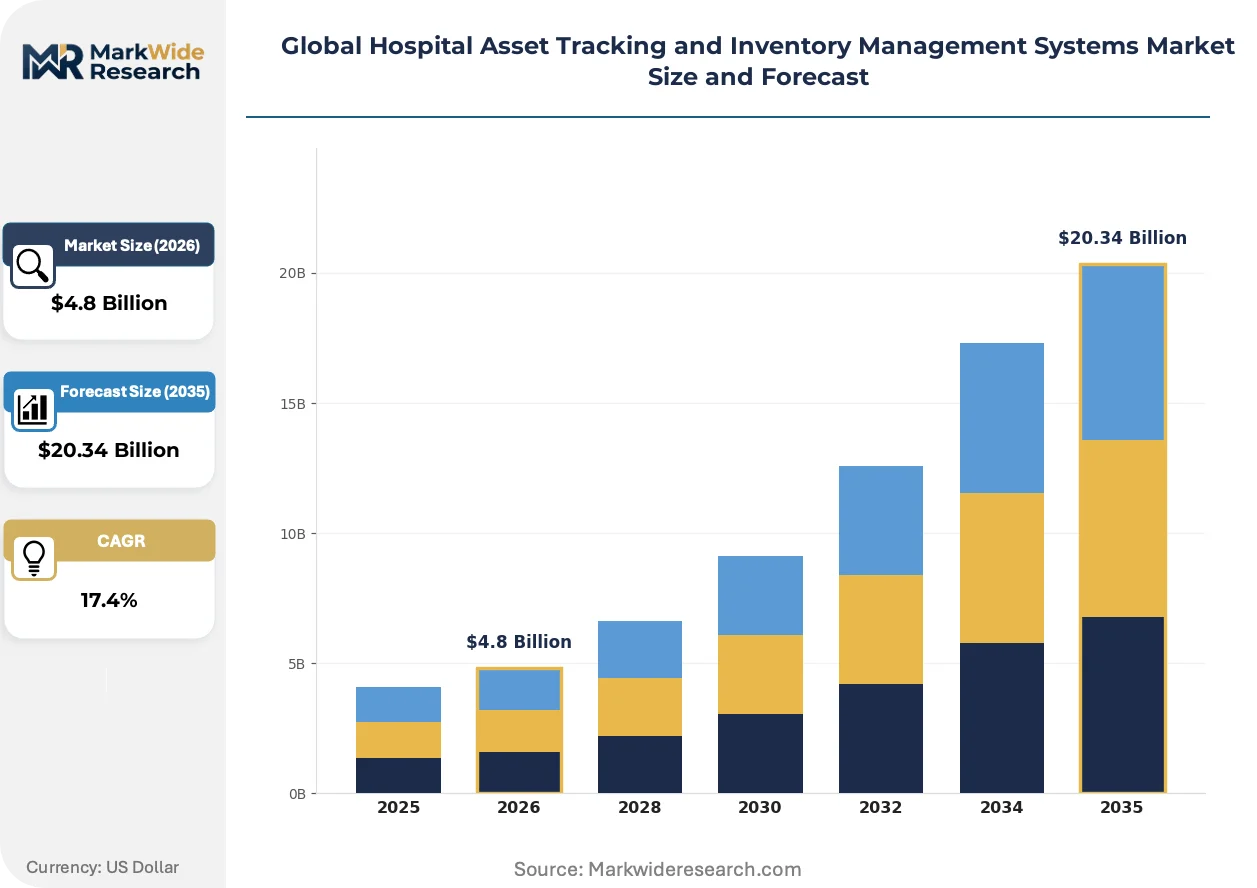
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $20.34 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Hardware Devices, Integrated Systems, Cloud-based Platforms Technology: RFID, Barcode, Bluetooth Low Energy, Wi-Fi, Ultra-wideband Application: Inventory Management, Asset Tracking, Equipment Maintenance, Supply Chain Optimization, Patient Flow Monitoring End User: Hospitals, Diagnostic Centers, Ambulatory Surgical Centers, Specialty Clinics |
| Companies Covered | Zebra Technologies, CenTrak, GE Healthcare, Ruya Compliance, Accruent, Philips Healthcare, Stanley Healthcare, FSI, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hospital Asset Tracking and Inventory Management Systems Market Shifts & Advancements
Artificial intelligence is embedding into inventory forecasting workflows, compressing the gap between consumption signal and replenishment action from days to hours.
Ultra-wideband is overtaking infrared augmentation for sub-meter precision in operating room environments. Academic medical centers in Switzerland and Australia are deploying UWB anchors at 1.5-meter spacing to track surgical instrument trays. This density is enabling real-time par-level automation that RFID room-level granularity cannot match.
EMA's MDR traceability provisions are forcing European hospital networks to consolidate previously siloed procurement databases. The regulation mandates device history records spanning manufacture to decommission. Integrated delivery networks in France and Germany are responding by unifying asset tracking, maintenance, and supply chain modules into single platforms rather than point solutions.
Subscription-based SaaS pricing is displacing perpetual license models among US integrated delivery networks. Hospital CFOs prefer operational expenditure treatment for IT investments under value-based care margin pressure. This preference is most visible in California and Texas, where multi-hospital systems are negotiating enterprise-wide platform contracts with usage-based tiering.
Global Hospital Asset Tracking and Inventory Management Systems Market Segmentation
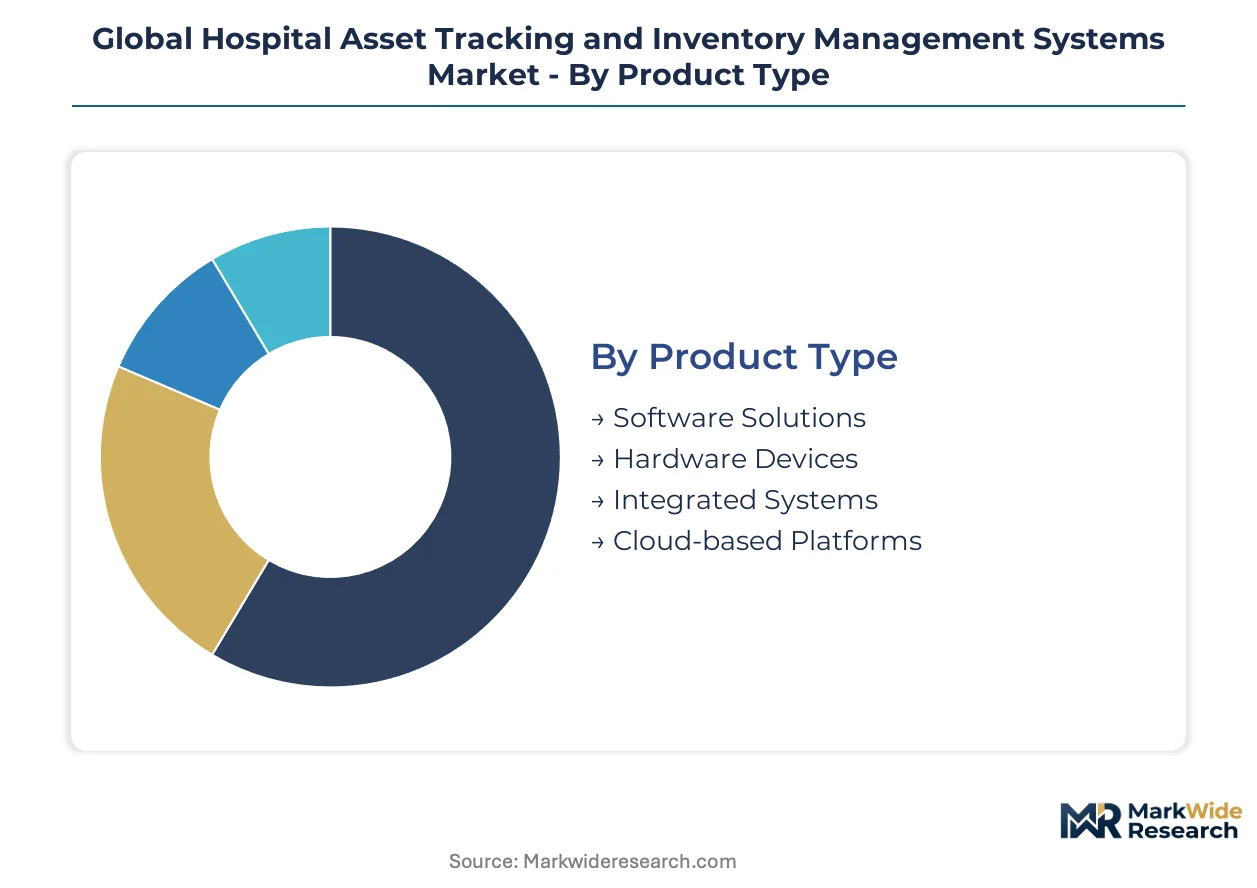
Hospital procurement committees evaluate asset tracking investments through multiple lenses simultaneously. Product architecture determines capital deployment patterns. Technology selection dictates infrastructure retrofit scope and ongoing operational complexity.
Product Type:
Hospital CFOs weight total cost of ownership against integration depth when selecting platform architecture.
- Hardware Devices:RFID readers, BLE gateways, and barcode scanners constitute the physical layer requiring site-specific installation. Demand concentrates in US academic medical centers expanding real-time location infrastructure to meet Joint Commission documentation requirements. Copper and aluminum commodity volatility squeezes margins on passive tag deployments.
- Cloud-based Platforms:Subscription delivery models shift IT expenditure from capital to operational budgets. Multi-hospital networks in Germany and the United Kingdom prioritize these solutions as workforce shortages intensify automation imperatives.
- Software Solutions:Perpetual license inventory management applications requiring on-premise server infrastructure.
- Integrated Systems:Unified platforms combining tracking, maintenance scheduling, and supply chain modules into single vendor relationships.
Hardware Devices lead on scale; Cloud-based Platforms lead on momentum.
Technology:
Radio frequency spectrum allocation and location precision requirements drive technology selection across clinical environments.
- RFID:Passive and active radio-frequency identification operates at 433 MHz or 2.4 GHz bands with room-level granularity. US health systems deploy RFID most intensively to satisfy FDA UDI Phase 3 track-and-trace mandates for high-risk medical devices.
- Ultra-wideband:Sub-meter precision location tracking using 6-8 GHz spectrum. Swiss and Australian academic centers deploy UWB anchor density at 1.5-meter spacing for surgical instrument tray tracking in operating rooms.
- Bluetooth Low Energy:Low-energy beacon infrastructure achieves room-level accuracy at reduced hardware cost versus UWB.
- Barcode:Linear and 2D optical scanning for consumable inventory reconciliation.
- Wi-Fi:Location services leveraging existing wireless infrastructure with reduced dedicated hardware requirements.
RFID dominates installed base; Ultra-wideband gains share fastest in precision-critical settings.
Application:
Clinical workflow integration determines solution complexity and stakeholder alignment requirements.
- Asset Tracking:Real-time location services for mobile medical equipment including infusion pumps, wheelchairs, and defibrillators. Demand concentrates in California and Texas multi-hospital systems negotiating enterprise platform contracts.
- Inventory Management:Automated par-level monitoring and reorder triggering for consumable supplies. Japanese hospital networks automate reconciliation to offset supply chain staffing gaps.
- Equipment Maintenance:Preventive maintenance interval tracking and work order generation.
- Supply Chain Optimization:Vendor-managed inventory and consignment tracking integration.
- Patient Flow Monitoring:Bed management and throughput optimization using location data.
Asset Tracking anchors revenue; Inventory Management shows steepest expansion trajectory.
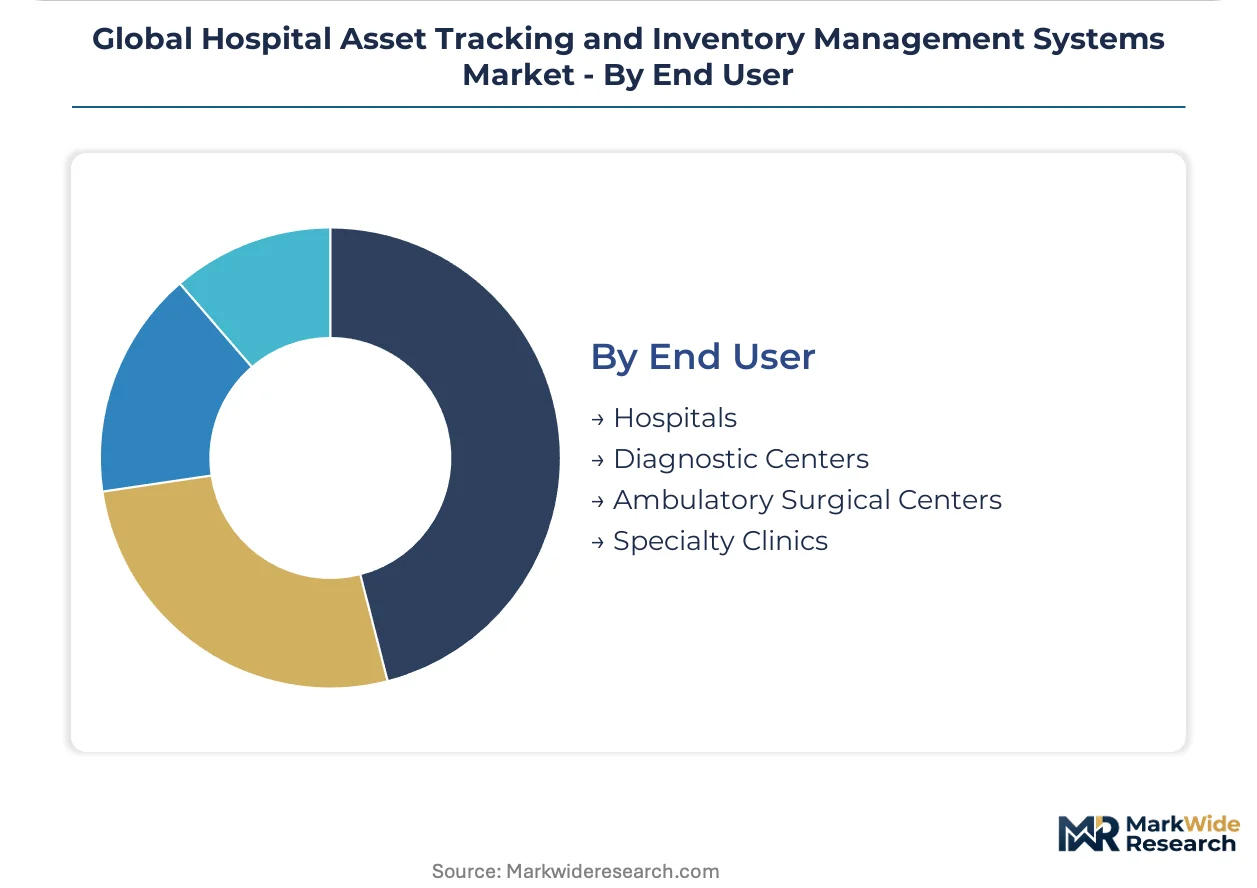
End User:
Facility scale and regulatory exposure shape procurement authority and solution sophistication.
- Hospitals:General acute care facilities with diverse equipment portfolios and complex compliance obligations. India's NABH accreditation expansion mandates asset traceability for tier-2 and tier-3 city hospitals.
- Ambulatory Surgical Centers:Focused procedure facilities with concentrated high-value instrument tracking needs. These centers prioritize lower total cost solutions given constrained capital budgets.
- Diagnostic Centers:Imaging and laboratory facilities with specialized equipment maintenance requirements.
- Specialty Clinics:Single-discipline practices with limited device variety and simpler inventory profiles.
Hospitals command platform economics; Ambulatory Surgical Centers drive volume at compressed price points.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinical engineering talent clusters in the United States, Germany, and Japan anchor the highest-density deployments of real-time location infrastructure. These markets concentrate regulatory expertise and hospital network scale that accelerate technology validation cycles.
United States
FDA UDI Phase 3 enforcement compels integrated delivery networks to deploy track-and-trace platforms across multi-facility footprints. Health systems in California and Texas negotiate enterprise-wide contracts that bundle asset tracking with predictive maintenance modules. The Joint Commission's audit documentation requirements drive RFID infrastructure expansion in academic medical centers concentrated in Boston and the Research Triangle.
Germany
Workforce shortages in nursing and supply chain functions accelerate cloud-based inventory automation among hospital networks in North Rhine-Westphalia and Bavaria. EMA MDR traceability provisions mandate device history records that consolidate previously siloed procurement databases. The country's university hospitals in Heidelberg and Berlin serve as validation sites for ultra-wideband surgical instrument tracking at sub-meter precision.
Japan
METI-promoted JIS standards for healthcare IoT security shape vendor certification requirements for asset tracking deployments. Hospital networks in Tokyo and Osaka automate inventory reconciliation to offset persistent staffing gaps in supply chain operations. The country's aging demographic intensifies demand for predictive maintenance algorithms that extend equipment lifecycle in capital-constrained facilities.
United Kingdom
NHS England's procurement consolidation drives cloud platform adoption among multi-hospital trusts seeking operational expenditure treatment for IT investments. Workforce automation imperatives concentrate in Greater London and the Midlands, where staffing ratios strain manual inventory reconciliation workflows. The country's medical device regulator enforces traceability standards that align with EU MDR provisions despite post-Brexit regulatory divergence.
India
NABH accreditation expansion mandates asset traceability for tier-2 and tier-3 city hospitals in Maharashtra, Karnataka, and Tamil Nadu. Cloud-native vendors target first-mover advantage in cities including Pune, Bengaluru, and Chennai, where private hospital chains expand bed capacity. The country's central pharmaceutical regulator enforces track-and-trace requirements that cascade into hospital procurement compliance obligations.
Global Hospital Asset Tracking and Inventory Management Systems Market Competitive Landscape
Capital-heavy hardware producers compete with asset-light software designers for procurement committee attention. The vendor base separates into infrastructure specialists supplying RFID readers and BLE gateways, platform developers delivering subscription-based inventory management, and integrated systems providers unifying tracking with maintenance scheduling. Market structure rewards scale in hardware manufacturing and recurring revenue retention in cloud delivery. Dominant competitive moves include strategic partnerships between hardware OEMs and electronic health record vendors, plus geographic expansion through systems integrator networks.
Among diversified industrial technology providers, Zebra Technologies occupies a position exemplifying hardware-centric market entry, while CenTrak represents specialists in real-time location system accuracy. GE Healthcare anchors the medical equipment OEM archetype that extends installed base relationships into predictive maintenance contracts. These three companies illustrate the strategic segmentation between infrastructure suppliers, precision tracking specialists, and integrated healthcare technology conglomerates that defines competitive positioning in this market.
| Leading Market Players |
|---|
| Zebra Technologies |
| CenTrak |
| GE Healthcare |
| Ruya Compliance |
| Accruent |
| Philips Healthcare |
| Stanley Healthcare |
| FSI |
| Siemens Healthineers |
| Others |
Supply & Pricing Matrix
EU MDR traceability mandates gate qualified supply access and premium-tier pricing power for vendors demonstrating device history record compliance across European hospital networks. Pricing stratifies across integrated system premiums, standalone platform subscriptions, and hardware-only transactions as procurement committees weigh total cost of ownership against regulatory risk mitigation.
Pricing Analysis
Bundled predictive maintenance contracts command pricing premiums against unbundled hardware transactions as GE Healthcare and Siemens Healthineers extend imaging equipment relationships into recurring service revenue. Price differentiation rests on FDA UDI certification tier and after-sales service bundling depth. Cost compression in passive RFID tag deployments intensifies because copper and aluminum commodity volatility squeezes high-volume consumables tracking margins. Ambulatory surgical centers exhibit acute price sensitivity while academic medical centers absorb premium positioning for sub-meter precision infrastructure.
Supply Chain Analysis
Freight cost inflation for BLE gateway and UWB anchor shipments from contract manufacturers in Taiwan, South Korea, and China compresses hardware vendor margins on trans-Pacific lanes. Semiconductor content draws from concentrated foundry capacity in Taiwan and South Korea, tethering RFID reader production to single-source vulnerability in advanced node availability. Distribution runs through systems integrator networks in the United States, Germany, and Japan that anchor clinical engineering talent clusters for site survey and interference mitigation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory enforcement into demand acceleration as FDA UDI Phase 3 timelines compel health system procurement committees toward compliant platform investments.
For Market Incumbents: Anticipate displacement pressure from computer vision-based surgical instrument counting systems in sterile processing departments by deepening predictive maintenance algorithm development and securing GPO contract exclusivity clauses. Certification investment in EU AI Act high-risk system conformity assessment creates defensive moats against cloud-native challengers.
For New Entrants and Emerging Players: AI-native inventory forecasting modules offer wedge positioning against legacy perpetual license vendors in India's tier-2 and tier-3 city hospital expansion. Cloud-native deployment targeting Maharashtra and Karnataka NABH accreditation mandates enables first-mover advantage with subscription pricing that shifts capital expenditure burden from constrained facility budgets.
For Investors and Strategic Acquirers: Roll-up economics work for regional systems integrators because hospital IT procurement cycle compression favors vendors with embedded clinical engineering talent for site survey and 2.4 GHz interference mitigation. Target acquisition profiles center on Swiss and Australian academic medical center validation relationships that accelerate UWB anchor density proof points. The signal to watch is EU AI Act enforcement timing for predictive inventory algorithm risk classification.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA UDI Compliance Pathway | Phase 3 enforcement timelines compel health system track-and-trace platform procurement across multi-facility networks. |
| Hospital System Partnership | Enterprise-wide contracts in California and Texas bundle asset tracking with predictive maintenance modules. |
| CE Marking Pathway | EMA MDR traceability provisions mandate device history records that consolidate siloed procurement databases. |
| Software Companion Development | FHIR-compliant data architecture investments normalize BLE, UWB, and infrared feeds into single dashboards. |
| Reimbursement Strategy | Value-based care margin pressure drives CFO preference for operational expenditure treatment of IT investments. |
Research Methodology
Multiple input streams — hospital procurement committee interviews, biomedical engineering director consultations, GPO contracts manager discussions, and clinical engineering talent surveys — were reconciled against secondary validation from FDA UDI guidance documents, EMA MDR implementation reports, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up equipment installation base modeling and top-down health system IT expenditure triangulation anchored volume and value estimates.
Data-stream reconciliation across product type, technology selection, application workflow, and end-user facility scale dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segment-level adoption curves weighted against regulatory enforcement timelines and workforce automation imperatives. Forecast inputs incorporated RFID tag commodity price volatility assumptions and cloud platform subscription retention metrics by hospital network scale tier.
The model holds under steady FDA UDI Phase 3 enforcement and EU MDR traceability implementation; deviation in regulatory delay or accelerated AI Act risk classification would shift vendor certification investment requirements and procurement cycle timing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Global Back-End Revenue Cycle Management Market
Healthcare IT
Global Dental Software Market
Healthcare IT
Non-Clinical Homecare Software Market
Healthcare IT
North America Long-Term Care Software Market
Healthcare IT
Europe Dental Software Market
Healthcare IT
US Practice Management Systems Market
Healthcare IT
Femtech Market
Healthcare IT
Global Personal Health Records Software Market
Healthcare IT
North America Internet of Medical Things (Iomt) Market
Healthcare IT
Clinical Healthcare IT Market
Healthcare IT
Medical Specimen Tracking System Market
Healthcare IT
Italy Dental Practice Management Software Market
Healthcare IT
Global Patient Flow Management Solutions Market
Healthcare IT
Healthcare Contact Center Solution Market
Healthcare IT
Healthcare Credentialing Software Market
Healthcare IT
Healthcare Ediscovery Market