
 Healthcare IT Outsourcing Market | 2026-2036
Healthcare IT Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare IT Outsourcing Market Intelligence
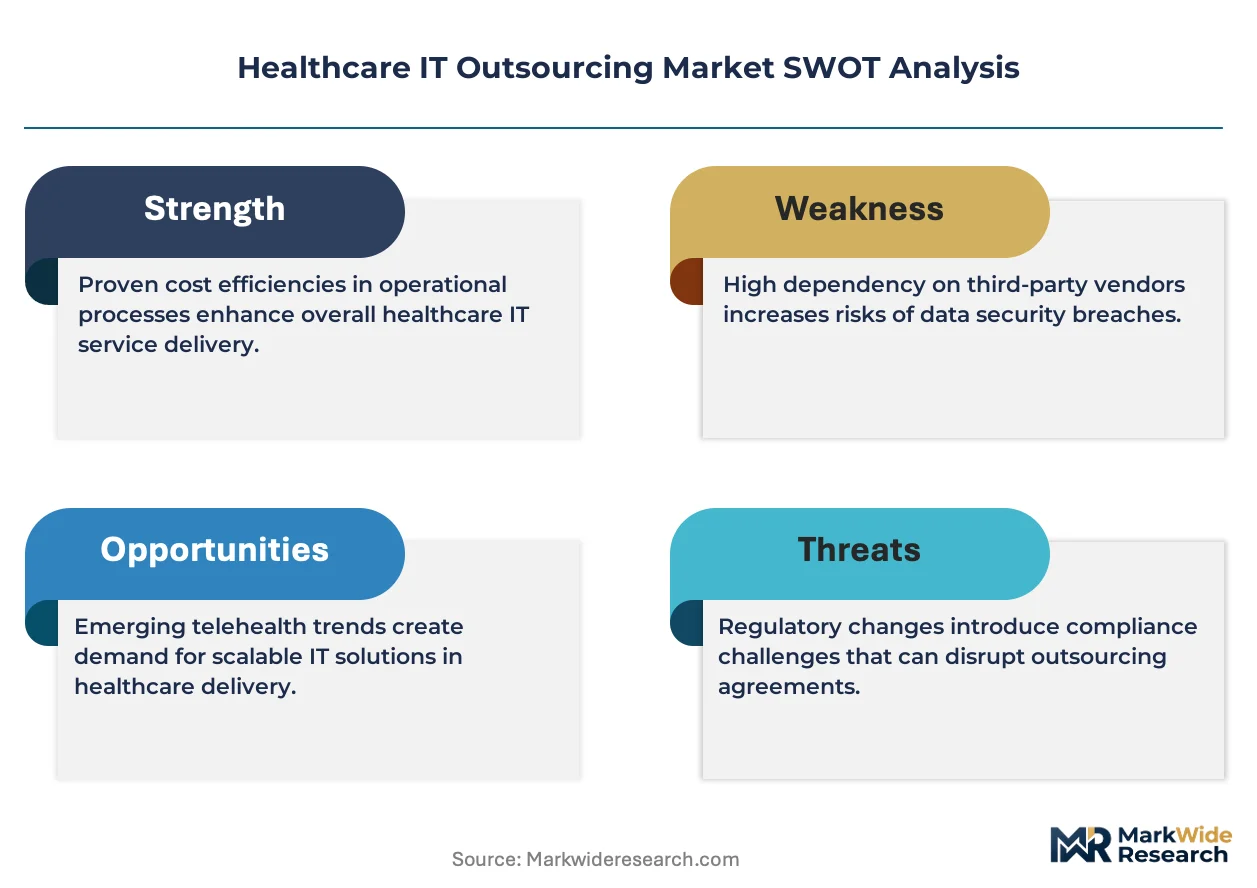
Integrated service bundling is consolidating buyer preferences across the Healthcare IT Outsourcing landscape, with hospitals favoring single-vendor contracts spanning infrastructure, application management, and analytics rather than fragmented point solutions. Accenture leverages its multi-cloud healthcare platform to anchor large health system transformations across North America. Cognizant sustains competitive positioning through deep Epic and Cerner integration expertise. Omega Healthcare dominates offshore medical coding and revenue cycle management from its India delivery centers.
Healthcare IT Outsourcing encompasses the contracted provision of information technology services—including cloud infrastructure management, electronic health record system maintenance, healthcare data analytics, and revenue cycle software administration—to healthcare provider organizations and life sciences entities. These arrangements typically operate under multi-year service level agreements specifying uptime thresholds, data security protocols, and regulatory compliance benchmarks, enabling providers to reduce capital expenditure on internal IT departments while accessing specialized technical talent. Infrastructure Management and Cloud Services represent mature, high-volume segments where margin compression intensifies competition among incumbent providers, while Data Analytics and Telehealth Platforms emerge as faster-expanding categories where differentiated algorithmic capabilities command pricing premiums. The Delivery Model dimension shows Hybrid arrangements gaining share as clients seek cost arbitrage from offshore labor combined with onshore regulatory proximity.
FDA oversight of software as a medical device intersects with HIPAA security rule enforcement by the US Department of Health and Human Services to create dual compliance burdens that outsourcing vendors must absorb. India's CDSCO data localization expectations and the EU's GDPR health data processing restrictions further fragment the regulatory landscape governing cross-border patient information flows. Stakeholders must evaluate vendor resilience against evolving cybersecurity disclosure mandates and emerging AI governance frameworks before committing to long-term outsourcing partnerships.
Market Dynamics
The 21st Century Cures Act interoperability mandates are forcing hospital systems to dismantle data silos and migrate toward API-first architectures, compressing vendor consolidation timelines and elevating specialized integration partners over generalist IT providers.
Growth Catalysts
- HIPAA compliance complexity:The US Department of Health and Human Services enforcement of security rule audits drives provider organizations toward vendors with certified compliance infrastructure rather than internal IT buildouts.
- Epic and Cerner integration depth:Health systems demand outsourced partners capable of managing multi-EHR environments without disrupting clinical workflows or revenue cycle continuity.
- India delivery center scale:Offshore medical coding and claims processing operations from Mumbai and Hyderabad capture cost arbitrage while maintaining turnaround time SLAs for US hospital clients.
Market Restraints
- Cybersecurity insurance cost inflation:Ransomware targeting healthcare IT infrastructure has tripled premium burdens for outsourcing vendors, compressing margins on fixed-price infrastructure management contracts.
- CDSCO data localization requirements:India's mandate for domestic storage of patient health records fragments cross-border service architectures and forces duplicate infrastructure investments.
- Legacy mainframe dependency:Payer organizations retain COBOL-based claims processing cores that resist cloud migration, trapping vendors in high-cost maintenance relationships with limited modernization pathways.
Strategic Opportunities
- AI governance frameworks:The EU AI Act's risk classification for healthcare algorithms creates first-mover advantage for vendors pre-certifying diagnostic and clinical decision-support tools.
- Rural health system penetration:Critical access hospitals in the US Mountain West and Great Plains regions remain underserved by enterprise outsourcing providers, presenting white-space for mid-tier specialists.
- Telehealth platform unbundling:Virtual care infrastructure is separating from EHR bundles, enabling standalone vendors to capture point solutions for remote patient monitoring and asynchronous consultation workflows.
Industry Challenges
- Epic-certified analyst scarcity:Health systems report 18-month backlogs for hiring certified technical staff, forcing vendors to absorb training costs or poach talent at premium wages.
- FDA software-as-medical-device validation timelines:Algorithm updates for clinical decision support require 90-180 day review cycles that conflict with agile development sprints and client delivery expectations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare IT Outsourcing Market |
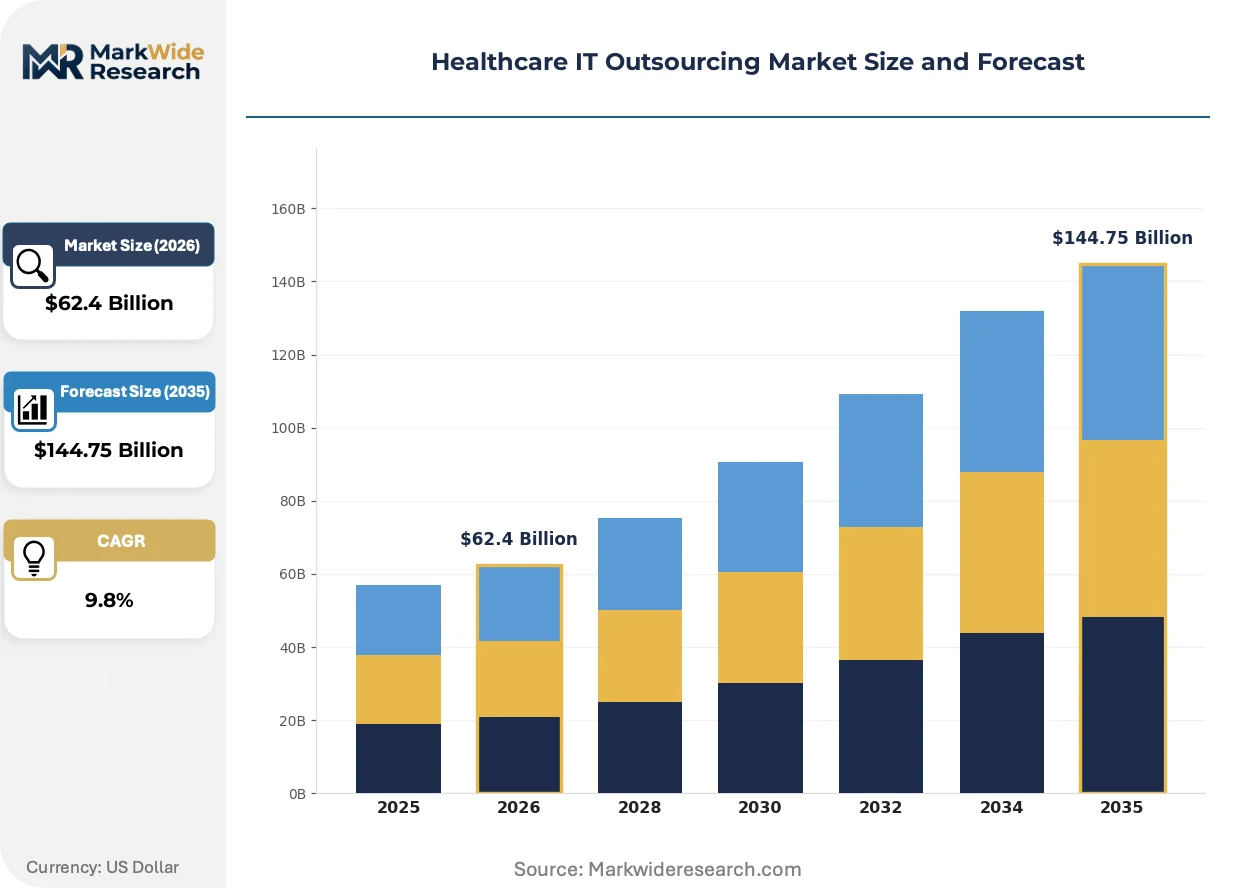
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $144.75 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
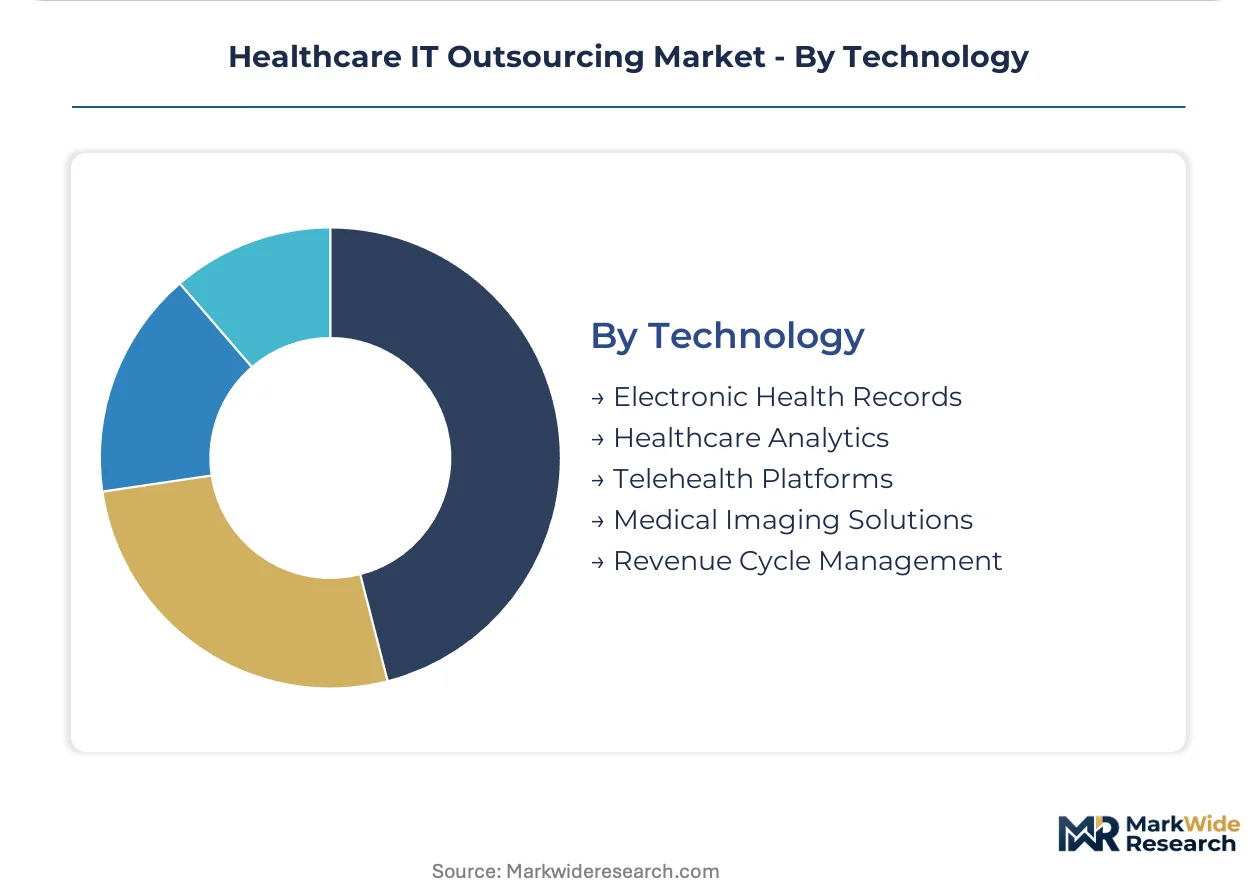
| Segmentation | Service Type: Application Development, Infrastructure Management, Data Analytics, Cloud Services, Technical Support Delivery Model: Onshore, Offshore, Nearshore, Hybrid End User: Hospitals, Diagnostic Centers, Ambulatory Care Facilities, Telemedicine Providers, Clinical Research Organizations Technology: Electronic Health Records, Healthcare Analytics, Telehealth Platforms, Medical Imaging Solutions, Revenue Cycle Management |
| Companies Covered | GE Healthcare, Conifer Health Solutions, Accenture, Firstsource Solutions, AGS Health, Cognizant, Omega Healthcare, GeBBS Healthcare Solutions, UST, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare IT Outsourcing Market Strategic Shifts & Innovations
Healthcare IT outsourcing is fragmenting from monolithic enterprise contracts toward composable service architectures. Vendors now compete on integration velocity rather than scale alone.
Microservices architecture is modularizing legacy EHR maintenance into discrete API-connected components. Large health systems in Texas and California are piloting containerized modules for patient scheduling and billing that swap vendors without full-platform replacement. This modularity is compressing switching costs and enabling multi-vendor strategies previously blocked by data lock-in.
The EU AI Act's high-risk system obligations are reshaping algorithm development workflows for clinical decision support. Vendors serving European life sciences clients must now maintain technical documentation, human oversight protocols, and conformity assessments before deployment. German hospital systems are demanding pre-certified AI modules, accelerating vendor specialization in regulatory-ready algorithmic tools.
Subscription-based infrastructure pricing is displacing capital-intensive data center ownership among community hospital networks. Colorado and Arizona health systems now prefer consumption-modeled cloud contracts that align IT expenditure with patient volume fluctuations. This shift favors vendors with granular usage metering and transparent cost allocation across clinical departments.
Healthcare IT Outsourcing Market Segmentation
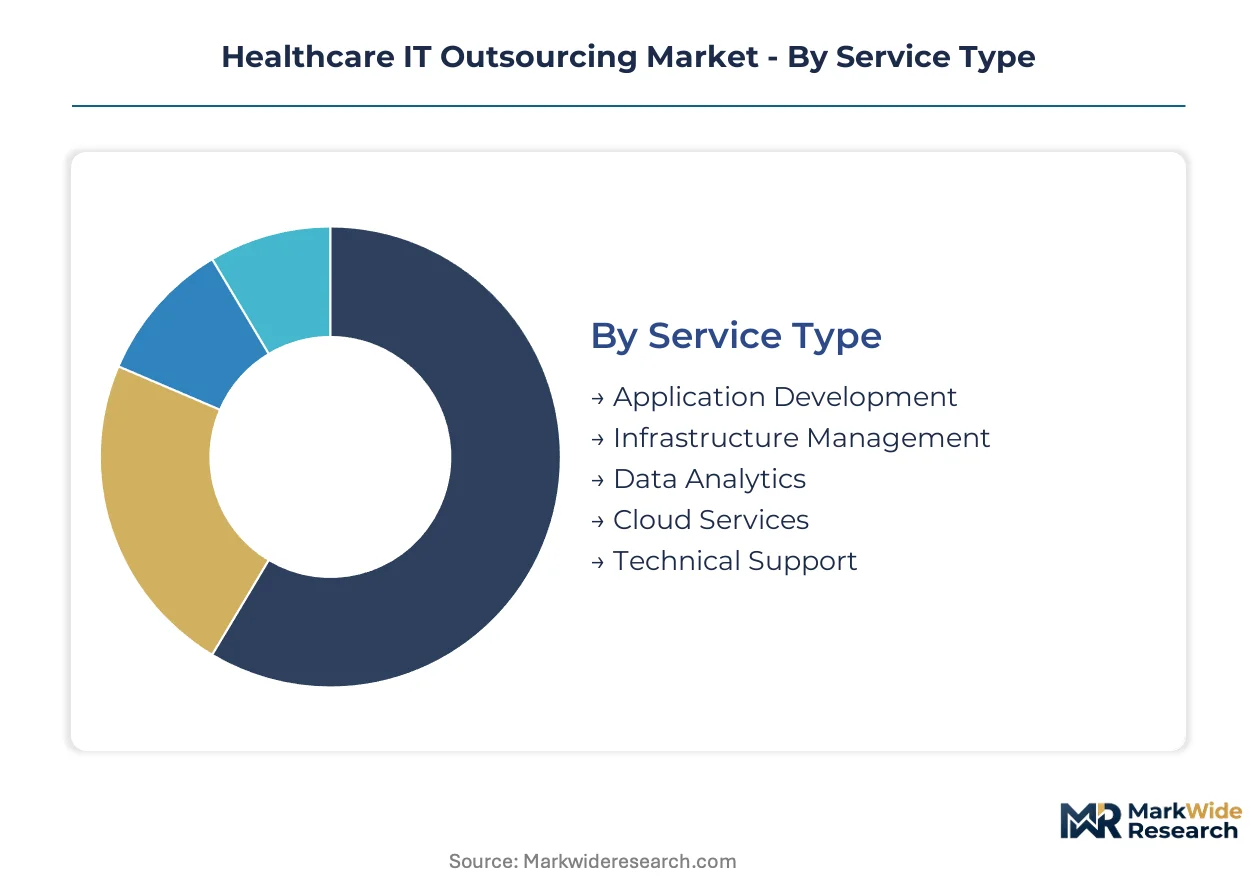
Healthcare IT outsourcing segmentation reveals how vendor specialization aligns with provider risk tolerance and technical complexity. Buyers select service tiers based on regulatory exposure, EHR dependency, and geographic delivery constraints.
Service Type:
Customization intensity varies sharply across this category, from standardized infrastructure maintenance to bespoke clinical application development.
- Infrastructure Management:Server provisioning, network operations, and data center uptime monitoring form the backbone of multi-year outsourcing contracts. US hospital systems in Texas and Florida concentrate demand here, driven by Epic and Cerner uptime SLAs that penalize downtime exceeding 99.9% thresholds.
- Cloud Services:Multi-tenant platforms for storage, compute, and disaster recovery replace capital-intensive on-premise ownership. Colorado and Arizona community hospitals favor consumption-based pricing that aligns IT expenditure with patient volume fluctuations.
- Data Analytics:Population health algorithms and operational dashboards transform claims and clinical data into actionable intelligence.
- Application Development:Custom modules for patient portals and revenue cycle workflows address health system-specific requirements.
- Technical Support:Tiered helpdesk operations resolve end-user incidents across clinical and administrative staff.
Most installed capacity flows through Infrastructure Management. Expansion is steepest in Cloud Services.
Delivery Model:
Cost tier positioning determines vendor selection, with labor arbitrage competing against regulatory proximity.
- Hybrid:Blended onshore-offshore teams combine US-based project management with India-based coding and testing resources. Mumbai and Hyderabad delivery centers capture medical claims processing volume while maintaining HIPAA-compliant data handling protocols.
- Offshore:Dedicated India and Philippines operations deliver medical coding, transcription, and back-office revenue cycle functions at 40-60% cost reduction versus domestic equivalents.
- Onshore:US-based delivery satisfies FDA software-as-medical-device validation requirements and state-level data residency mandates.
- Nearshore:Canada and Mexico facilities serve US clients requiring timezone alignment without full domestic cost burden.
Hybrid arrangements command the largest contract values. Nearshore is gaining share fastest among mid-tier health systems.
End User:
Application complexity and integration depth separate acute care hospitals from distributed outpatient networks.
- Hospitals:Integrated delivery networks outsource EHR maintenance, revenue cycle management, and cybersecurity operations across multi-facility footprints. Academic medical centers in California and Massachusetts demand Epic-certified technical staff for complex clinical workflow support.
- Telemedicine Providers:Virtual care platforms require scalable infrastructure for video consultation, remote patient monitoring, and asynchronous messaging. Standalone vendors unbundle from EHR bundles to capture point solutions for asynchronous consultation workflows.
- Diagnostic Centers:Imaging networks prioritize PACS integration and radiology workflow optimization.
- Ambulatory Care Facilities:Physician practices and urgent care chains seek lightweight EHR support without enterprise overhead.
- Clinical Research Organizations:Trial sponsors outsource data management, regulatory submission support, and pharmacovigilance systems.
Hospital systems generate the highest contract values. Telemedicine Providers are expanding most quickly.
Technology:
Maturity stage differentiates legacy EHR maintenance from emerging AI-enabled clinical decision support.
- Electronic Health Records:Epic and Cerner system administration, upgrade management, and interoperability configuration consume the largest outsourcing budgets. Health systems report 18-month backlogs for certified technical staff, forcing vendors to absorb training premiums.
- Healthcare Analytics:Predictive algorithms for readmission risk, sepsis detection, and resource optimization require specialized data science talent. German hospital systems demand pre-certified AI modules under EU AI Act high-risk system obligations.
- Revenue Cycle Management:Claims processing, denial management, and patient billing automation address payer complexity.
- Telehealth Platforms:Virtual care infrastructure separates from EHR bundles to enable standalone vendor selection.
- Medical Imaging Solutions:PACS, VNA, and AI-assisted radiology tools demand high-bandwidth storage and specialized clinical integration.
Electronic Health Records anchor current spending. Healthcare Analytics is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Healthcare IT Outsourcing industry traces its modern scale to the United States, where HIPAA compliance mandates and Epic-Cerner EHR proliferation first created specialized vendor demand in the early 2000s. That regulatory foundation spread outsourcing models to Canada, the United Kingdom, Germany, and India.
United States
Hospital systems in Texas and California dominate infrastructure outsourcing contracts, driven by Epic uptime SLAs penalizing downtime exceeding 99.9%. HIPAA security rule enforcement by the US Department of Health and Human Services accelerates vendor transitions. Academic medical centers in Massachusetts demand certified technical staff for complex clinical workflow support.
India
Mumbai and Hyderabad delivery centers capture offshore medical coding and claims processing volume at 40-60% cost reduction versus domestic equivalents. CDSCO data localization requirements fragment cross-border service architectures and force duplicate infrastructure investments. Bangalore-based development teams maintain HIPAA-compliant data handling protocols for US hospital clients.
Germany
Hospital systems demand pre-certified AI modules under EU AI Act high-risk system obligations for clinical decision support. EMA oversight intersects with GDPR health data processing restrictions to create dual compliance burdens for outsourcing vendors. Frankfurt and Munich clusters concentrate regulatory-ready algorithmic tool development.
United Kingdom
NHS digital transformation programs outsource EHR maintenance and cybersecurity operations to specialized vendors. GDPR health data processing restrictions govern cross-border patient information flows. London health systems pilot containerized modules for patient scheduling that enable multi-vendor strategies.
Philippines
Manila and Cebu delivery centers expand medical transcription and back-office revenue cycle functions for US payer organizations. Timezone alignment with North American clients supports real-time claims processing workflows. Vendor investments address cybersecurity insurance cost inflation compressing margins on fixed-price contracts.
Healthcare IT Outsourcing Market Key Industry Players
The competitive structure tilts toward integrated service bundling, with hospitals favoring single-vendor contracts spanning infrastructure, application management, and analytics. Market concentration remains moderate, with global consultancies, offshore specialists, and healthcare-focused boutiques occupying distinct tiers. Strategic archetypes include multi-cloud platform anchors, Epic-Cerner integration specialists, and offshore delivery scale players. Dominant competitive moves encompass M&A for EHR expertise acquisition and geographic expansion into underserved rural health systems.
Within the integration-specialist tier, Accenture leverages its multi-cloud healthcare platform to anchor large health system transformations, while Cognizant sustains competitive positioning through deep Epic and Cerner integration expertise. Omega Healthcare dominates offshore medical coding and revenue cycle management from its India delivery centers, representing the scale-driven offshore archetype.
| Leading Market Players |
|---|
| GE Healthcare |
| Conifer Health Solutions |
| Accenture |
| Firstsource Solutions |
| AGS Health |
| Cognizant |
| Omega Healthcare |
| GeBBS Healthcare Solutions |
| UST |
| Others |
Cost & Logistics Intelligence
Epic-certified analyst labor costs cascade through three distinct pricing tiers as health systems absorb training premiums and poaching-driven wage inflation. HIPAA-compliant infrastructure investments in India and the Philippines compress margins on fixed-price contracts while elevating subscription-based cloud pricing for US hospital clients.
Pricing Analysis
Consumption-modeled cloud contracts with granular usage metering now dominate infrastructure procurement across Colorado and Arizona community hospitals. Pricing stratifies across premium certified-staff tiers, standard hybrid delivery, and economy offshore-only levels, with differentiation driven by HIPAA audit readiness and Epic integration depth. Cost compression in the economy tier intensifies because cybersecurity insurance inflation triples vendor premium burdens. Critical access hospitals in the Mountain West exhibit highest price sensitivity, while academic medical centers in Massachusetts prioritize certified technical staff over cost minimization.
Supply Chain Analysis
FDA software-as-medical-device validation and HIPAA security rule certification gate vendor participation in US hospital procurement cycles. Talent supply concentrates in India, the Philippines, and select US metropolitan clusters, with Mumbai and Hyderabad delivery centers anchoring offshore medical coding volume. Raw material dependencies include cloud compute infrastructure, specialized health data storage, and certified EHR technical labor. Single-source vulnerability persists for Epic-certified analyst talent, where 18-month hiring backlogs constrain vendor scaling. Distribution runs through multi-year service level agreements specifying uptime thresholds and regulatory compliance benchmarks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate where vendors shift fixed-price infrastructure contracts toward subscription-based cloud pricing aligned with patient volume fluctuations. Automation of medical coding workflows and AI-assisted clinical decision support tools enable premium-tier repositioning.
For Market Incumbents: Lock in long-term Epic and Cerner integration partnerships before microservices architecture fragments vendor relationships. Acquire mid-tier specialists with pre-certified AI modules under EU AI Act obligations to preempt regulatory-ready algorithm competition. Vertical integration into offshore delivery centers in India mitigates CDSCO data localization cost duplication threatening margin compression. For New Entrants and Emerging Players: The premium-economy price-point gap in rural health system penetration creates white-space entry for mid-tier specialists with hybrid delivery models. Critical access hospitals in the Great Plains remain underserved by enterprise outsourcing providers. Telehealth platform unbundling from EHR bundles enables standalone vendor capture of remote patient monitoring point solutions. For Investors and Strategic Acquirers: Consolidation pressure builds where cybersecurity insurance inflation compresses margins on fixed-price contracts below sustainable thresholds. Acquisition target archetypes include offshore delivery scale players with HIPAA-compliant India infrastructure and AI governance pre-certification capabilities. Watch FDA software-as-medical-device validation timeline extensions as inflection indicator for vendor agility premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Epic-Cerner Integration Partnership | Deep EHR expertise anchors multi-year hospital system contracts against microservices fragmentation. |
| EU AI Act Pre-Certification | Regulatory-ready algorithmic tools command pricing premiums from German hospital systems. |
| Hybrid Delivery Expansion | Blended onshore-offshore teams balance HIPAA compliance proximity with India cost arbitrage. |
| Cybersecurity Insurance Optimization | Ransomware-targeted premium reduction restores margin viability on infrastructure contracts. |
| Rural Health System Penetration | Critical access hospital white-space in Mountain West regions escapes enterprise vendor saturation. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital CIOs, Epic-certified technical staff, revenue cycle operations directors, and offshore delivery center managers with secondary validation against CMS Medicare data, hospital procurement databases, GPO contracts, and HHS HIPAA enforcement records. Bottom-up service line estimates and top-down market sizing triangulated across infrastructure management, cloud services, data analytics, and application development segments.
Segment-weighting approaches distributed value across service type, delivery model, end user, and technology dimensions throughout the forecast period. CAGRs derived from historical trajectory analysis and forward-looking regulatory impact modeling incorporated 21st Century Cures Act interoperability mandate compliance costs and EU AI Act high-risk system obligation implementation timelines as healthcare-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for microservices-based EHR modularization would alter the outlook for vendor consolidation timelines and switching cost dynamics. Forecasts reflect assumptions regarding HIPAA enforcement intensity and cybersecurity insurance market stabilization. A model refresh is warranted upon material change in FDA software-as-medical-device validation timelines or CDSCO data localization enforcement scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
United States Pharmacy Management System Market
Healthcare IT
Ambulatory Surgical Centers IT Services Market
Healthcare IT
Global Emergency Department Information System Market
Healthcare IT
Global Pharma Knowledge Management Software Market
Healthcare IT
IP-Based Nurse Call System Market
Healthcare IT
Cognitive Assessment and Training in Healthcare Market
Healthcare IT
North America Long-Term Care Software Market
Healthcare IT
Americas Healthcare Human Resources (HR) Software Market
Healthcare IT
Global Orthopedic Software Market
Healthcare IT
Global Hospital Asset Tracking and Inventory Management Systems Market
Healthcare IT
Revenue Cycle Management (RCM) Market
Healthcare IT
Healthcare Business Collaboration Tools Market
Healthcare IT
US Long Term Care Software Market
Healthcare IT
Operating Room Management Software Market
Healthcare IT
Pharmaceutical Software Market
Healthcare IT
Operating Room Software Market