
 Europe Outpatient Software Market | 2026-2036
Europe Outpatient Software Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Outpatient Software Market Foresight
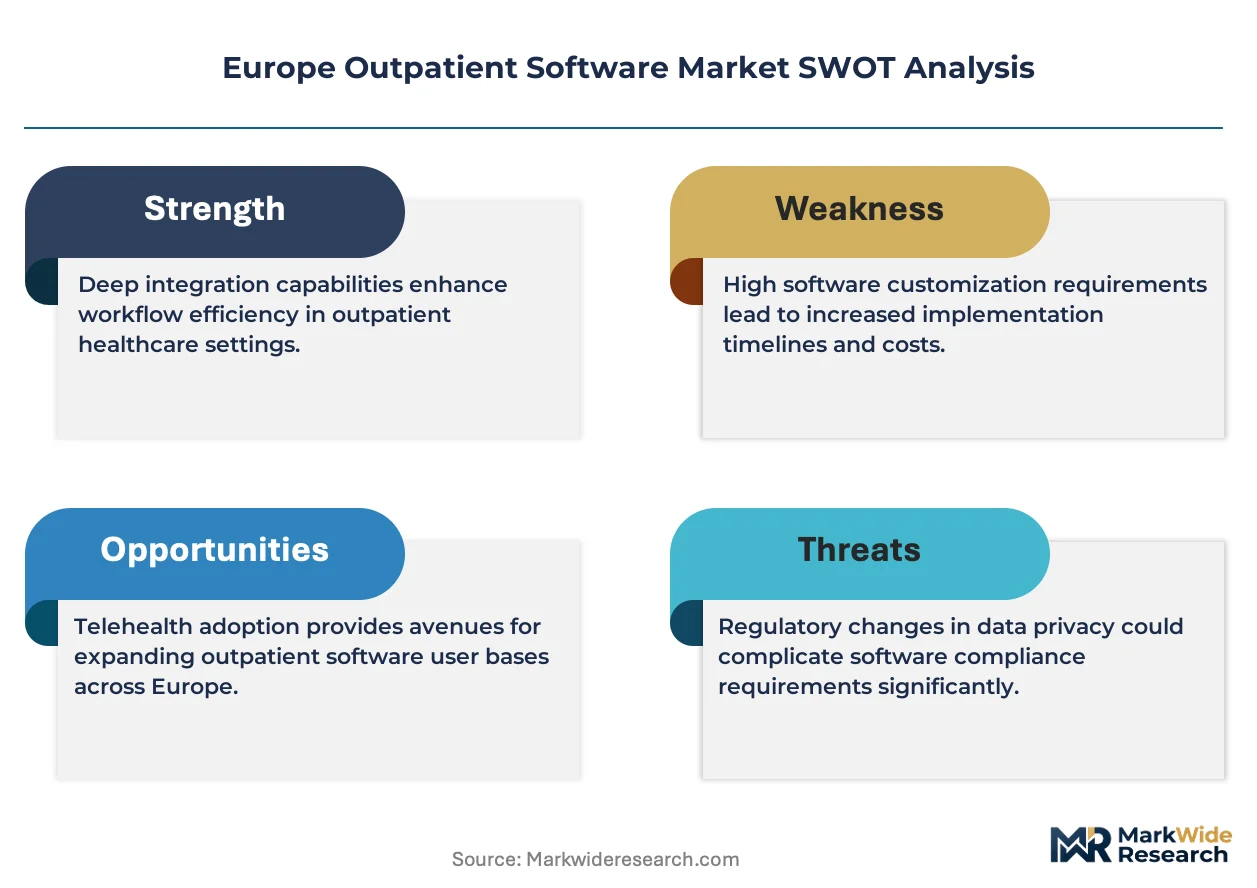
Legacy on-premise infrastructure is shifting toward cloud-native architectures as European healthcare providers seek elastic capacity and reduced capital expenditure. Epic Systems Corporation leverages its interoperability expertise to anchor large hospital network deployments across Northern Europe. Dedalus S.p.A. competes through deep specialization in country-specific reimbursement workflows, while CompuGroup Medical sustains broad geographic coverage via modular product tiers that adapt to national tariff structures.
Europe outpatient software encompasses clinical and administrative applications that manage patient flows, billing, scheduling, and care coordination outside inpatient settings, typically operating through HL7 FHIR interfaces and national health data exchange protocols to ensure continuity across fragmented provider networks. Cloud-based deployment leads absolute growth as NHS England and French regional health agencies mandate off-premise hosting for new procurements, while telehealth platforms represent the fastest-expanding technology segment driven by post-pandemic chronic care protocols. Billing software retains the deepest margin pool due to complex, country-specific reimbursement coding requirements that resist standardization.
EMA data governance guidelines, GDPR health data provisions, and the EU AI Act's risk-classification framework collectively reshape vendor development priorities and procurement eligibility across member states. National regulators in Germany, France, and Italy enforce divergent certification timelines that fragment product rollout schedules and elevate compliance costs for cross-border suppliers. Stakeholders must monitor evolving interoperability mandates under the European Health Data Space regulation to anticipate which connectivity standards will dominate procurement specifications.
Market Dynamics
The European Health Data Space regulation is forcing outpatient software vendors to rebuild data exchange architectures around federated consent models and cross-border interoperability protocols. This structural pressure is compressing product development cycles while elevating compliance costs for suppliers serving multiple member states.
Growth Catalysts
- GDPR health data provisions:Mandatory encryption and pseudonymization standards create replacement demand for legacy systems across German ambulatory networks.
- Telehealth platforms:Post-pandemic chronic care protocols in France and the United Kingdom are embedding remote monitoring into standard outpatient workflows.
- NHS England cloud mandates:Off-premise hosting requirements for new procurements are accelerating SaaS migration among independent general practitioners.
Market Restraints
- Country-specific reimbursement coding:Fragmented tariff structures across Germany, France, and Italy force vendors to maintain parallel billing modules, elevating development overhead.
- EMA data governance timelines:Divergent national certification schedules delay product rollouts and extend sales cycles for cross-border suppliers.
- Legacy HL7 v2 infrastructure:Deep installed bases in Southern European clinics resist FHIR migration, constraining addressable market expansion.
Strategic Opportunities
- Eastern European e-health strategies:Poland and Romania are directing EU recovery funds toward interoperable outpatient systems with accelerated procurement timelines.
- AI-assisted clinical decision support:The EU AI Act's risk-classification framework creates compliant product categories for vendors embedding diagnostic algorithms.
- Modular microservices architecture:API-first platforms enable smaller vendors to penetrate national health systems without full-stack replacement offerings.
Industry Challenges
- FHIR implementation expertise:Shortages of developers fluent in Fast Healthcare Interoperability Resources standards constrain deployment velocity for mid-sized vendors.
- Dual GDPR-EU AI Act compliance:Overlapping audit requirements for health data processing and algorithmic risk management extend certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Outpatient Software Market |
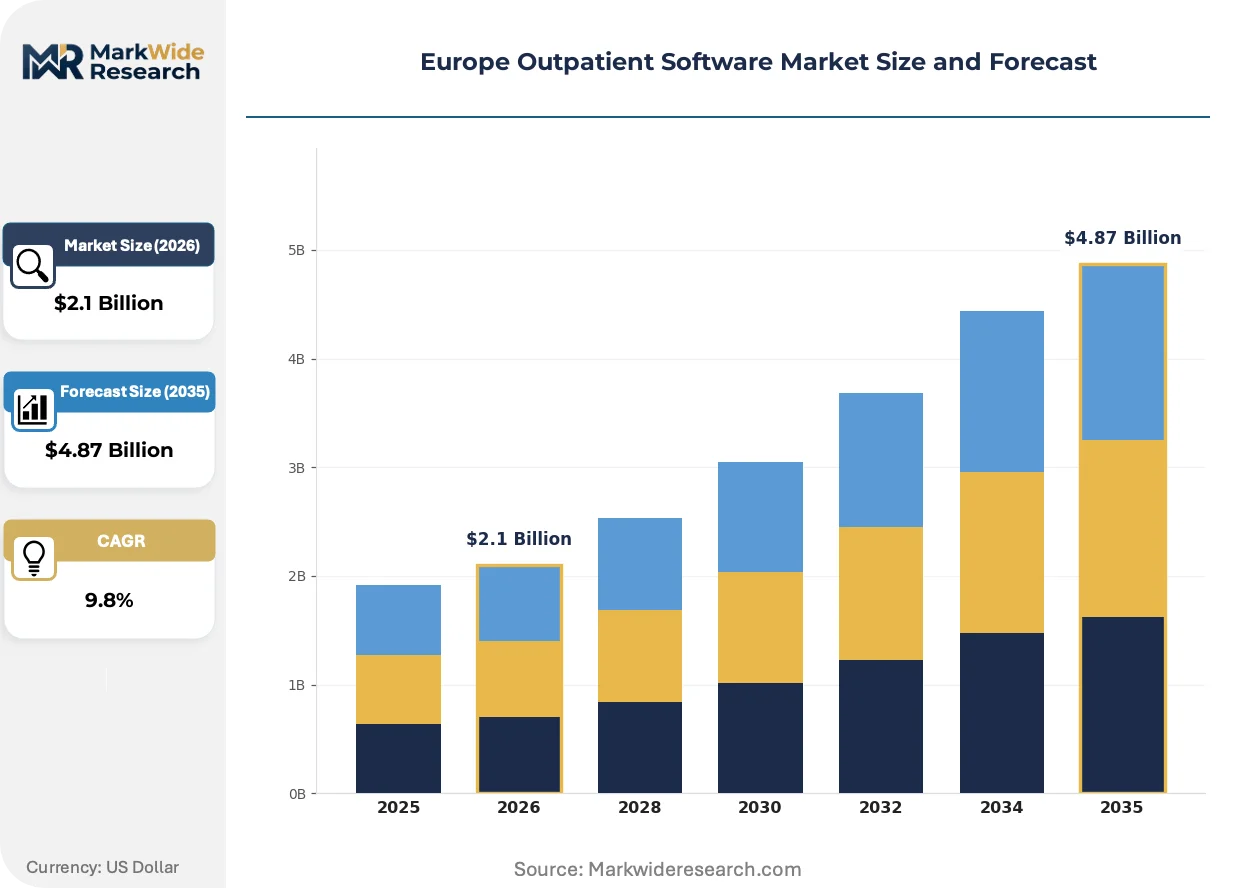
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.87 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scheduling Software, CRM Software, Billing Software, Reporting Software Deployment: On-premise, Cloud-based, Hybrid, Web-based End User: Clinics, Urgent Care Centers, Ambulatory Surgery Centers, Physician Practices Technology: AI-driven Solutions, IoT-enabled Systems, Telehealth Platforms, Interoperable Applications |
| Companies Covered | Cerner Corporation, Epic Systems Corporation, Dedalus S.p.A., CompuGroup Medical, Medical Information Technology, Inc., NEXUS AG, McKesson Corporation, Allscripts Healthcare Solutions, Inc., Oracle, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Outpatient Software Market Shifts & Advancements
Cloud-native architectures are displacing on-premise installations across European outpatient settings. Vendors are racing to embed AI-driven clinical workflows while navigating tightening data sovereignty requirements.
HL7 FHIR R4 interfaces are integrating patient record exchange across fragmented provider networks. French regional health agencies and NHS trusts are mandating these standards for new system procurements. This convergence is compressing vendor differentiation around connectivity depth rather than functional breadth.
The EU AI Act's risk-classification framework is reshaping development priorities for diagnostic software modules. High-risk applications now require conformity assessments before market entry. German outpatient networks are delaying AI procurement until vendor certification pathways stabilize.
Subscription-based licensing is displacing perpetual ownership models among independent physician practices. Italian and Spanish clinic associations are negotiating collective SaaS agreements to reduce per-seat costs. This shift concentrates purchasing power with regional buying consortia and compresses vendor margins on standardized modules.
Europe Outpatient Software Market Segmentation
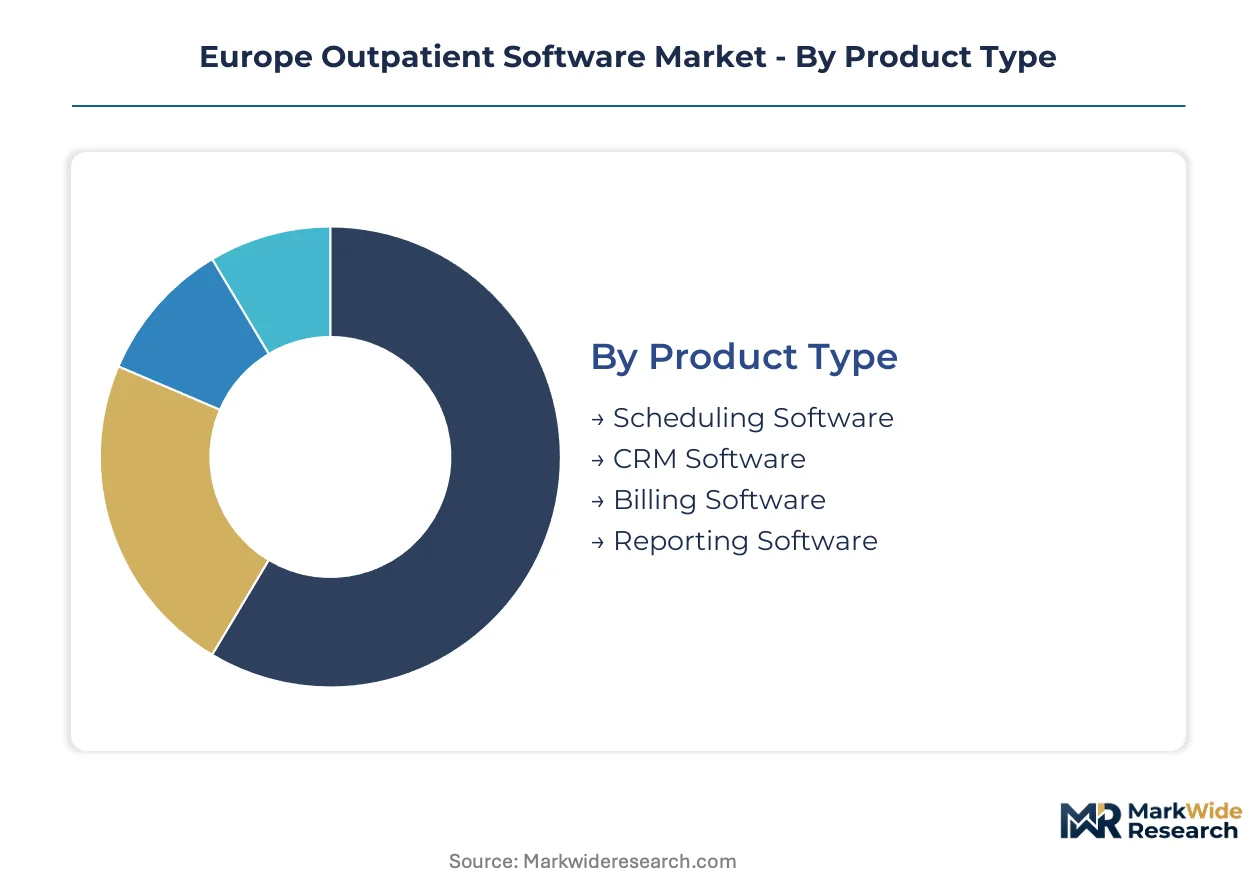
European outpatient software procurement varies sharply by provider scale and regulatory environment. Segmentation reveals where cloud mandates, reimbursement complexity, and interoperability standards concentrate commercial opportunity across product categories.
Product Type:
Customization intensity ranges from configurable workflow engines to rigid compliance modules that resist adaptation.
- Scheduling Software:Patient flow optimization tools integrate with national appointment booking systems. German ambulatory networks and NHS England trusts drive replacement demand as legacy systems fail GDPR encryption standards.
- Billing Software:Country-specific tariff coding engines manage reimbursement workflows across fragmented European structures. France and Italy maintain parallel billing modules due to divergent national classification systems, elevating vendor development overhead.
- CRM Software:Patient engagement platforms with consent management layers adapt to EMA data governance guidelines.
- Reporting Software:Analytics modules aggregate clinical and financial metrics for regional health agency compliance.
Leading the category by volume: Billing Software. Growing fastest: Scheduling Software.
Deployment:
Capital expenditure sensitivity and data sovereignty requirements shape infrastructure choices across provider tiers.
- Cloud-based:Elastic capacity platforms hosted on EU-certified data centers reduce upfront hardware investment. NHS England mandates off-premise hosting for new procurements, accelerating SaaS migration among independent general practitioners.
- Hybrid:Split architectures keep sensitive patient records on local servers while routing administrative functions to cloud instances. French regional health agencies favor this model for medium-sized clinic networks balancing compliance with cost control.
- On-premise:Legacy server installations persist in Southern European clinics with deep HL7 v2 infrastructure investments.
- Web-based:Browser-accessible lightweight deployments serve small physician practices with limited IT staffing.
Cloud-based deployments command the largest installed base. Hybrid architectures are expanding most quickly among mid-tier providers.
End User:
Procurement sophistication escalates from solo practices to multi-site networks with dedicated compliance officers.
- Ambulatory Surgery Centers:High-volume facilities require integrated scheduling, billing, and clinical documentation platforms. German and UK networks lead adoption of cloud-native systems with real-time inventory tracking for surgical supplies.
- Clinics:Multi-specialty outpatient facilities prioritize interoperable applications connecting to hospital networks. French regional health agencies direct procurement budgets toward HL7 FHIR-compliant systems.
- Urgent Care Centers:Rapid-turnaround facilities demand streamlined triage workflows and automated reporting for regulatory submission.
- Physician Practices:Solo and small-group providers favor subscription-based licensing with minimal configuration requirements.
Ambulatory Surgery Centers generate the highest per-site software expenditure. Clinics represent the broadest addressable base.
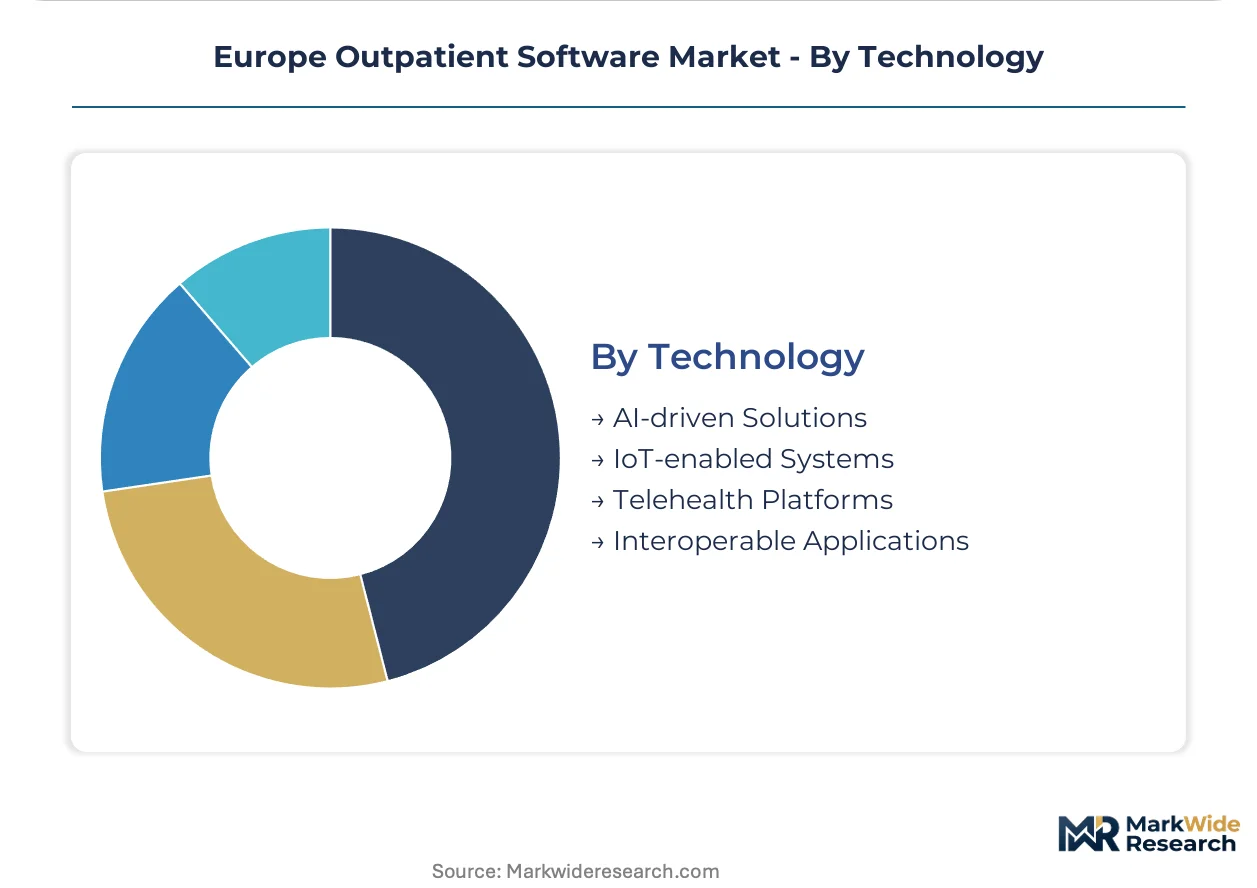
Technology:
Maturity gradients separate proven connectivity standards from emerging capabilities awaiting regulatory clarity.
- Telehealth Platforms:Remote consultation and monitoring systems embed into chronic care protocols. Post-pandemic reimbursement frameworks in France and the United Kingdom sustain demand for video consultation modules integrated with electronic health records.
- Interoperable Applications:HL7 FHIR R4-compliant systems exchange patient data across fragmented provider networks. NHS trusts and French regional agencies mandate these interfaces for new procurements, compressing vendor differentiation around connectivity depth.
- AI-driven Solutions:Diagnostic algorithms and clinical decision support tools face EU AI Act conformity assessment requirements. German outpatient networks delay procurement until certification pathways stabilize.
- IoT-enabled Systems:Connected device platforms stream biometric data from home monitoring equipment into outpatient workflows.
Interoperable Applications anchor current procurement specifications. Telehealth Platforms follow the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones and regional health clusters across Europe are concentrating outpatient software procurement budgets. Tax incentives for digital health infrastructure in Germany's MedTech hubs and France's regional health agencies accelerate vendor deployment timelines.
Germany
Baden-Württemberg and Bavaria host dense clusters of ambulatory surgery centers demanding integrated scheduling platforms. The BfArM digital health application approval process shapes vendor certification requirements. Berlin-Brandenburg networks lead cloud migration among multi-site physician practices seeking GDPR-compliant hosting.
United Kingdom
NHS England's cloud-first procurement mandates drive SaaS adoption across independent general practitioner networks. The Care Quality Commission's digital standards enforcement accelerates legacy system replacement in Greater London and the Midlands. Manchester and Birmingham health innovation zones concentrate pilot deployments of FHIR-compliant interoperability tools.
France
Île-de-France and Auvergne-Rhône-Alpes regional health agencies direct funding toward telehealth-integrated outpatient platforms. ANSM's medical device software classification timelines delay AI-assisted diagnostic module rollouts. Lyon and Paris clinic networks negotiate collective SaaS agreements compressing per-seat vendor margins.
Italy
Lombardy and Emilia-Romagna maintain parallel billing systems resisting cross-border standardization. The Agenas national digital health agency enforces divergent certification schedules from Northern European regulators. Milan and Bologna multi-specialty clinics prioritize hybrid cloud architectures balancing data sovereignty with cost control.
Europe Outpatient Software Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-stack vendors commanding large hospital networks while modular providers serve independent practices. The vendor base concentrates around three strategic tiers: interoperability-heavy platforms, country-specific reimbursement specialists, and API-first microservices providers. M&A activity targets FHIR implementation capabilities, while strategic partnerships address cross-border compliance fragmentation.
Within the full-stack tier, Epic Systems Corporation and Cerner Corporation anchor large network deployments across Northern European health systems. Dedalus S.p.A. and CompuGroup Medical occupy positions shaped by deep specialization in country-specific workflows, with the latter sustaining broad geographic coverage through modular product tiers. These four exemplify how scale and localization trade-offs define competitive positioning under divergent national regulatory frameworks.
| Leading Market Players |
|---|
| Cerner Corporation |
| Epic Systems Corporation |
| Dedalus S.p.A. |
| CompuGroup Medical |
| Medical Information Technology, Inc. |
| NEXUS AG |
| McKesson Corporation |
| Allscripts Healthcare Solutions, Inc. |
| Oracle |
| Others |
Supply & Pricing Matrix
Captive cloud infrastructure investments by Epic Systems Corporation and Cerner Corporation anchor both supply positioning and pricing power across NHS England and German hospital networks, creating tiered cost structures that independent practices cannot replicate.
Pricing Analysis
Volume concentrates in standardized SaaS tiers while margins pool in customized billing modules. Three-tier pricing structure across premium, standard, and economy levels stratifies by FHIR certification depth and GDPR audit completion. Cost compression in economy tiers stems from collective purchasing agreements by Italian and Spanish clinic associations. Independent physician practices exhibit highest price sensitivity, whereas ambulatory surgery centers absorb premium pricing for integrated inventory tracking.
Supply Chain Analysis
Dual-sourcing requirements mandated by French regional health agencies and NHS England trusts compel vendors to maintain qualified backup data centers across Germany, Ireland, and the Netherlands. Software development draws from specialized FHIR implementation labor pools in Poland and Romania, with cloud hosting resting on EU-certified infrastructure providers. Single-source vulnerability concentrates in legacy HL7 v2 integration specialists. Distribution runs through regional buying consortia that aggregate procurement for independent practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's risk-classification framework elevates compliance costs into a structural moat, privileging vendors with pre-certified diagnostic modules and documented conformity assessment pathways.
For Market Incumbents: Deploy modular microservices architecture to defend against API-first challengers penetrating national health systems. Consolidate FHIR implementation capabilities through targeted capability acquisition in Poland and Romania. Channel control through exclusive partnerships with regional buying consortia in Italy and Spain protects margin pools in standardized modules.
For New Entrants and Emerging Players: AI-assisted clinical decision support tools that navigate EU AI Act conformity assessments offer the most penetrable wedge. Target Eastern European e-health strategies in Poland and Romania directing EU recovery funds toward interoperable systems. Go-to-market through white-label partnerships with established regional distributors accelerates procurement qualification.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by full-stack vendors seeking FHIR expertise and country-specific reimbursement knowledge. Long-term viability favors platforms with demonstrated dual GDPR-EU AI Act compliance. Watch for stabilization of German BfArM digital health application approval timelines as the inflection signal for AI procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | HL7 FHIR R4 connectivity anchors procurement specifications across NHS England trusts. |
| Acquisition of Specialist Firm | Country-specific billing module expertise reduces development overhead for cross-border expansion. |
| Strategic Partnership | Regional buying consortia in France and Italy concentrate purchasing power and compress per-seat costs. |
| Geographic Expansion | Eastern European e-health strategies accelerate procurement timelines in Poland and Romania. |
| Product Launch | EU AI Act-compliant diagnostic modules unlock German outpatient networks delaying procurement. |
Research Methodology
Multi-period observation of cloud migration timelines, FHIR implementation rates, and procurement award patterns anchored the trend analysis, supplemented by interviews with hospital IT directors, ambulatory surgery center administrators, health system procurement officers, and EMA regulatory affairs specialists. Secondary validation drew from NHS Digital procurement databases, ANSM medical device software classifications, BfArM digital health application registers, and EU tenders electronic daily records. Bottom-up segment sizing triangulated against top-down health expenditure flows.
Input-output matrices mapped deployment model transitions, organization scale tiers, vertical specialization depth, and regional regulatory cluster variations across the projection horizon. CAGRs derived from fitted growth curves applied to segment-level baseline values, with cloud adoption elasticity and reimbursement complexity indices serving as software-specific forecast inputs.
Several conditions sit outside the modeled scope, including divergent national certification timelines beyond published EMA guidance and geopolitical disruptions to EU-certified data center operations. Forecasts reflect documented assumptions about interoperability mandate enforcement and EU AI Act implementation consistency. Deviation in European Health Data Space regulation rollout schedules would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Global Dermatology EMR Software Market
Healthcare IT
Global Hospital Asset Tracking and Inventory Management Systems Market
Healthcare IT
Medical Specimen Tracking System Market
Healthcare IT
Global Electronic Trial Master File (ETMF) Market
Healthcare IT
Digital Mhealth Solution Market
Healthcare IT
Senior Care Technologies Market
Healthcare IT
Dental Implantology Software Market
Healthcare IT
Healthcare Enterprise Software Market
Healthcare IT
Patient Referral Management Software Market
Healthcare IT
Healthcare Ediscovery Market
Healthcare IT
Healthcare Technology Management Market
Healthcare IT
Healthcare IT Services Market
Healthcare IT
Interactive Patient Care Systems Market
Healthcare IT
Asia-Pacific Dental Practice Management Software Market
Healthcare IT
Global Medical Practice Management Software Market
Healthcare IT
Asia Pacific Healthcare IT Market