
 Clinical Alarm Management Market | 2026-2036
Clinical Alarm Management Market Size, Share, and Industry Trends Forecast 2026-2036
Clinical Alarm Management Market Intelligence
Market Context
ECRI Institute hazard-class alarm specifications are reorganizing how health systems evaluate clinical alert platforms. Masimo leverages its pulse oximetry heritage to extend into hospital-wide alarm integration, while Koninklijke Philips N.V. anchors its position through bedside-to-cloud monitoring architectures. GE Healthcare competes on imaging-aligned alarm workflows, and Ascom Holding AG specializes in mobile caregiver alerting across European and North American installations.
Technical Definition and Segment Structure
Clinical alarm management encompasses the hardware, software, and protocols that prioritize, route, and suppress physiologic and technical alerts in acute care settings, typically processing heart rate, SpO2, respiratory rate, and blood pressure thresholds through centralized middleware. Alert management software captures the deepest margin pools as health systems seek algorithmic suppression of non-actionable alarms, while AI analytics represents the fastest-expanding technology tier as machine learning classifiers reduce alarm fatigue. Bedside alarms remain the highest-volume product category, though cloud-based solutions displace on-premises installations fastest among new hospital construction.
Regulatory Environment
The Joint Commission's National Patient Safety Goal on alarm management in the United States and the FDA's guidance on physiologic alarm systems shape product validation requirements and hospital accreditation incentives. IEC 60601-1-8 international alarm standards govern acoustic and visual signal specifications, creating compliance barriers for non-certified entrants. Stakeholders must monitor whether CMS reimbursement adjustments for alarm-related adverse events will accelerate replacement cycles in underinvested nursing facilities.
Market Dynamics
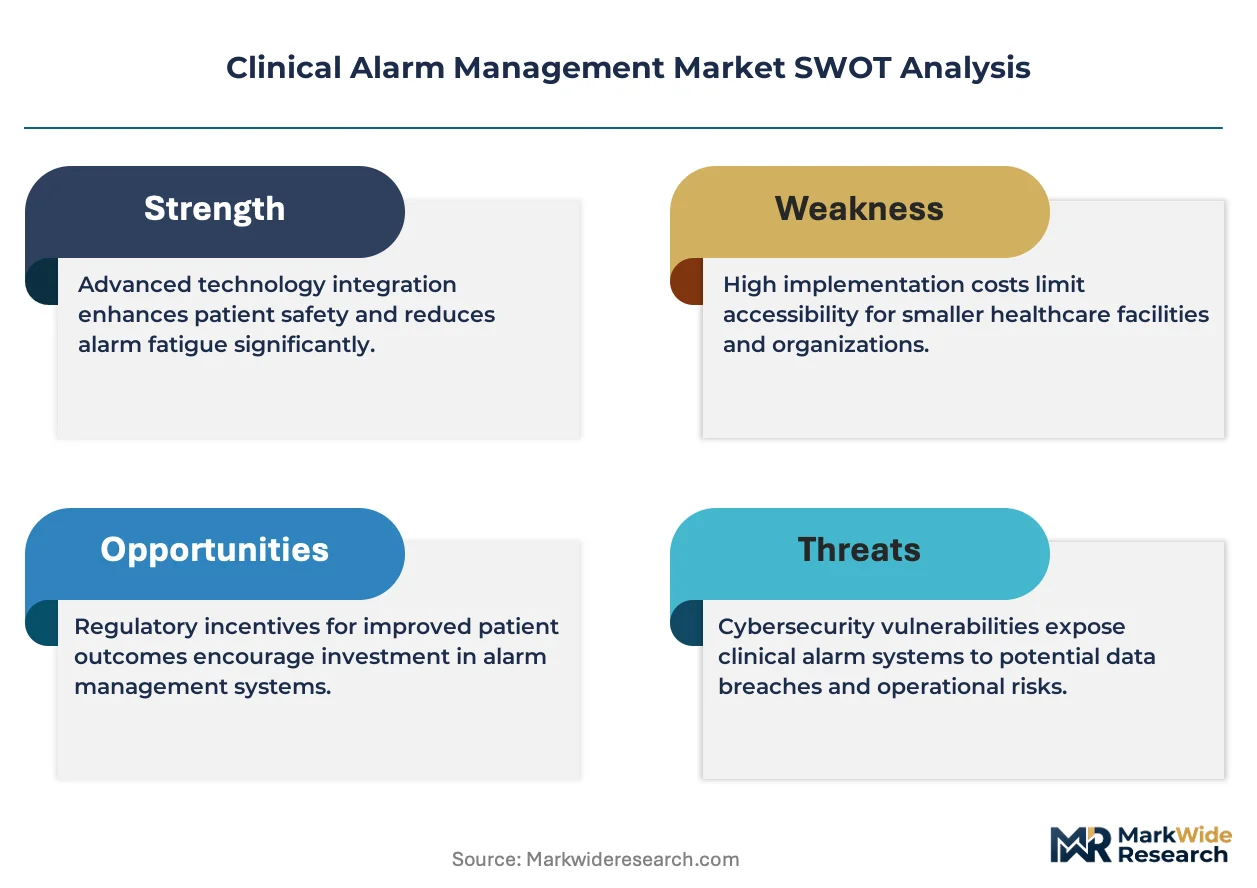
Algorithmic alarm suppression is compressing the value chain as hospitals demand middleware that filters non-actionable alerts before they reach caregivers, forcing vendors to integrate machine learning classifiers into legacy monitoring infrastructure.
Growth Catalysts
- Joint Commission NPSG.06.01.01:The United States accreditation mandate requires documented alarm management programs, compelling health systems to replace fragmented bedside alerting with centralized platforms.
- Perioperative monitoring densification:Ambulatory surgical centers are deploying multi-parameter alarm networks as procedure complexity migrates outside traditional hospitals.
- Cloud-native architectures:Software-as-a-service alarm analytics reduce capital expenditure barriers for mid-size community hospitals previously locked out of enterprise-tier solutions.
Market Restraints
- IEC 60601-1-8 acoustic compliance:International certification requirements for alarm signal harmonics create eighteen-month validation timelines that freeze product release cycles.
- Semiconductor foundry concentration:Taiwan-based fabrication dependence for sensor microcontrollers exposes hardware vendors to geopolitical supply interruptions.
- Legacy device protocol fragmentation:Proprietary data formats from installed bedside monitors resist middleware integration without costly gateway hardware.
Strategic Opportunities
- Skilled nursing facility underpenetration:Post-acute care settings in the United States lack alarm analytics infrastructure despite rising acuity admissions.
- FDA breakthrough device designation pathway:Expedited review for AI-enabled alarm prioritization algorithms accelerates commercialization timelines for predictive alerting systems.
- Edge-to-cloud convergence:Federated learning architectures enable alarm model training across hospital networks without centralizing protected health information.
Industry Challenges
- Biomedical informatics talent scarcity:Health systems struggle to recruit engineers capable of configuring alarm suppression rules that satisfy clinical governance committees.
- EHR interoperability certification:Meaningful Use Stage 3 compliance requirements demand multi-vendor integration testing that extends implementation timelines by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clinical Alarm Management Market |
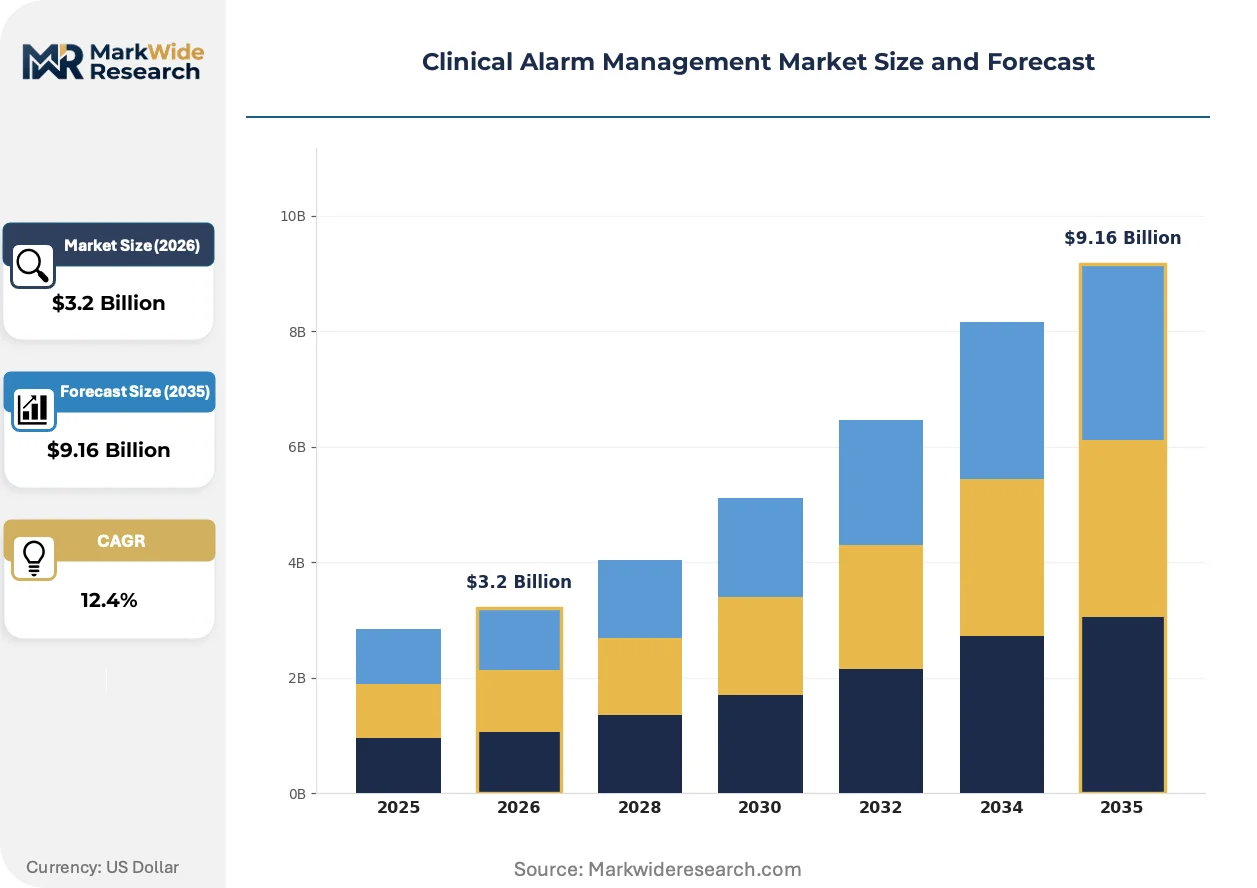
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $9.16 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bedside Alarms, Centralized Monitoring Systems, IT Solutions, Alert Management Software End User: Hospitals, Nursing Facilities, Home Healthcare, Ambulatory Surgical Centers Technology: Wireless Communication, Cloud-Based Solutions, Mobile Applications, AI Analytics Installation Type: On-Premises, Cloud-Based, Hybrid Systems, Standalone Solutions |
| Companies Covered | Masimo, Spok Inc., Koninklijke Philips N.V., Nihon Kohden Corporation, Baxter International Inc., GE Healthcare, Ascom Holding AG, Capsule Technologies, Inc., Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clinical Alarm Management Market Strategic Shifts & Innovations
Sensor fusion architectures are collapsing the distinction between physiologic monitoring and ambient clinical surveillance, enabling alarm systems to incorporate contextual patient state data beyond traditional vital signs.
Multimodal sensing arrays combining acoustic, visual, and pressure-sensitive inputs are miniaturizing into disposable adhesive patches. Post-anesthesia care units in the United States are piloting these platforms for continuous respiratory monitoring without wired connections. The technology is miniaturizing alarm infrastructure from centralized nursing stations toward patient-worn form factors that eliminate bedside hardware entirely.
The FDA's 2023 guidance on predetermined change control plans for machine learning-enabled medical devices is reshaping how vendors validate algorithm updates. Manufacturers must now submit locked algorithm modification protocols before commercialization, shifting development workflows toward modular, documentable software architectures. Intensive care unit alarm platforms face the steepest compliance burden as predictive models require continuous retraining on evolving patient populations.
Hospital procurement committees are unbundling alarm software licenses from hardware monitoring contracts that historically locked buyers into single-vendor ecosystems. Group purchasing organizations are negotiating standalone middleware agreements that interoperate across competing bedside device manufacturers. This pattern is most pronounced in United States integrated delivery networks consolidating multiple legacy hospitals under unified technology governance.
Clinical Alarm Management Market Segmentation
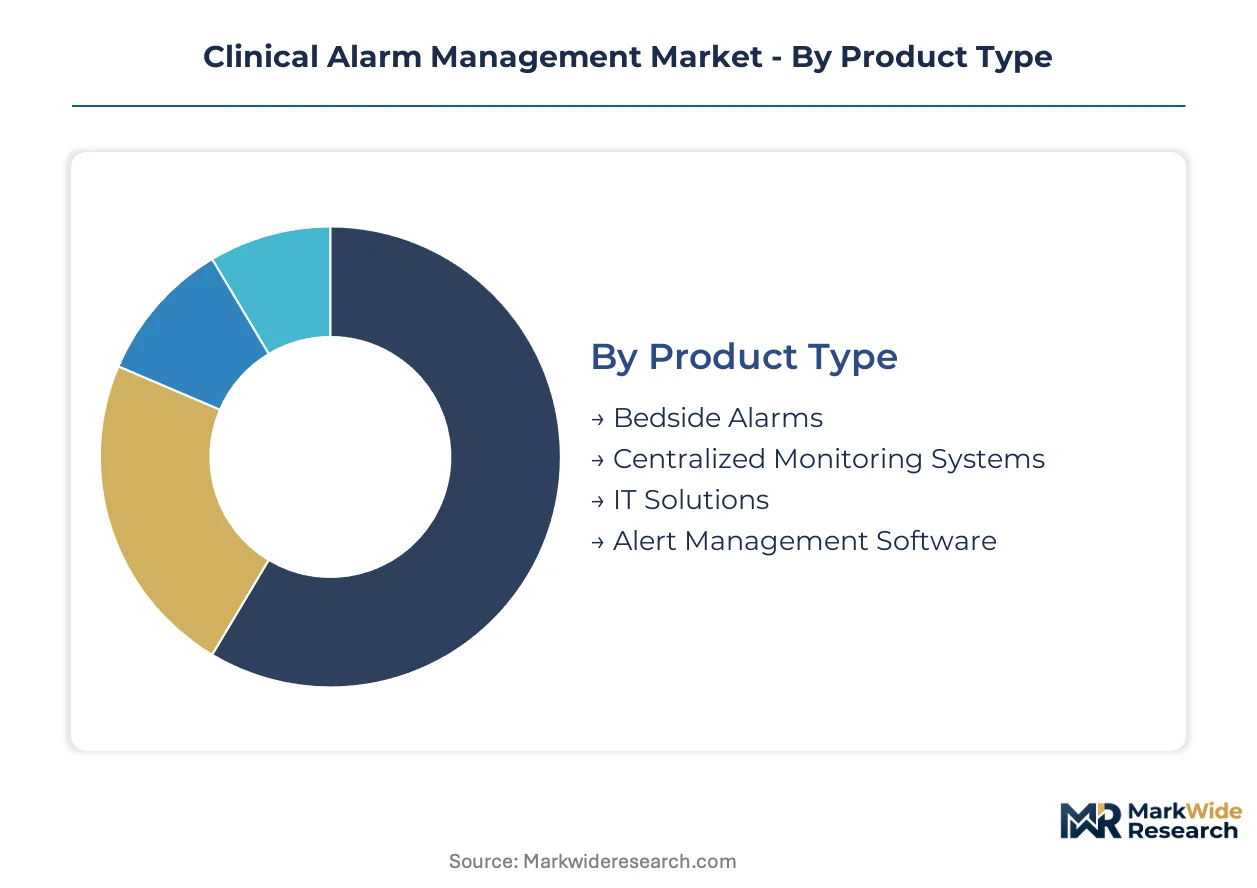
Clinical alarm management vendors configure product roadmaps around four distinct segmentation axes. Procurement patterns diverge sharply between enterprise health systems seeking centralized platforms and post-acute facilities prioritizing standalone affordability.
Product Type:
Domestic demand concentrates in bedside and centralized systems, while IT solutions and alert management software draw substantial export revenue from European and Asia-Pacific hospital networks.
- Bedside Alarms:These units process SpO2, heart rate, and respiratory thresholds at the point of care. United States health systems deploy them most densely in telemetry units, though alarm fatigue concerns are accelerating replacement cycles.
- Centralized Monitoring Systems:Middleware platforms aggregate alerts from multiple bedside devices onto unified nursing station displays. Demand clusters in United States integrated delivery networks consolidating acquired community hospitals under single governance structures.
- IT Solutions:Network infrastructure enabling alarm transmission across hospital floors.
- Alert Management Software:Algorithmic platforms suppressing non-actionable alerts before caregiver notification.
Bedside alarms command the established base. The steepest expansion runs through alert management software.
End User:
Cost tiers separate segments: hospitals absorb premium centralized platforms, while nursing facilities and home healthcare operate at lower price points with reduced feature depth.
- Hospitals:Acute care institutions deploy full-stack alarm ecosystems spanning emergency departments through step-down units. United States Joint Commission accreditation mandates drive replacement of fragmented legacy alerting.
- Nursing Facilities:Post-acute settings manage lower-acuity patient populations with simplified alarm parameters. Medicaid reimbursement constraints in United States skilled nursing facilities suppress investment in advanced analytics.
- Home Healthcare:Remote monitoring applications extending alarm reach beyond facility walls.
- Ambulatory Surgical Centers:Procedure-specific monitoring for same-day discharge protocols.
Hospitals anchor procurement volume. Home healthcare climbs the fastest as remote patient monitoring reimbursement expands.
Technology:
Maturity curves separate segments: wireless communication and mobile applications represent deployed infrastructure, while cloud-based solutions and AI analytics occupy earlier adoption phases.
- Wireless Communication:Wi-Fi and proprietary radio protocols transmit alarm signals without bedside tethering. United States hospitals prioritize 5 GHz spectrum allocation to reduce interference with medical telemetry.
- Cloud-Based Solutions:SaaS architectures host alarm analytics off-premises, eliminating capital expenditure barriers. Mid-size United States community hospitals adopt these fastest where IT staffing constraints limit on-premises management.
- Mobile Applications:Smartphone and pager integration routing alerts to roaming caregivers.
- AI Analytics:Machine learning classifiers distinguishing actionable from nuisance alarms.
Wireless communication underpins current installations. AI analytics gains share fastest as FDA breakthrough device pathways accelerate algorithm commercialization.
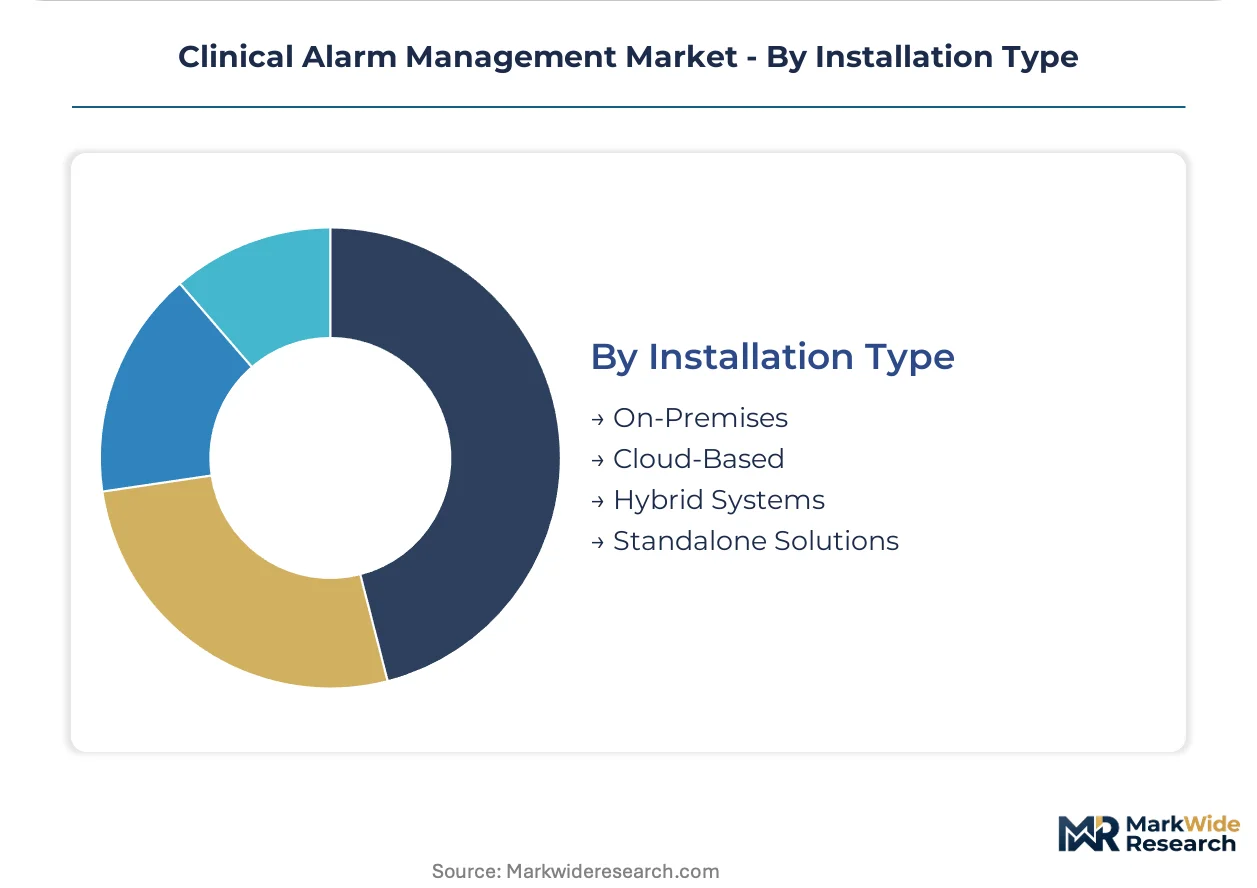
Installation Type:
Volume concentration favors on-premises deployments in existing facilities, though supply concentration in cloud infrastructure providers is reshaping new construction procurement.
- On-Premises:Local server installations maintaining alarm data within hospital firewalls. United States health systems with substantial legacy device investments favor this architecture for protocol compatibility.
- Cloud-Based:Fully hosted deployments eliminating hardware ownership. Greenfield United States hospital construction specifies these to reduce biomedical engineering headcount requirements.
- Hybrid Systems:Split architectures keeping sensitive data local while offloading analytics.
- Standalone Solutions:Self-contained alarm units without network integration.
On-premises systems retain the installed base. Cloud-based deployments expand most quickly among new hospital construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Concentration sits with the United States, where Joint Commission mandates and integrated health system consolidation drive centralized alarm platform procurement. Germany and Japan anchor European and Asian demand through aging infrastructure replacement and regulatory harmonization efforts. Emerging adoption clusters in India and Brazil reflect hospital digitization programs and private healthcare expansion.
United States
Joint Commission NPSG.06.01.01 mandates documented alarm management programs, compelling health system consolidation of fragmented bedside alerting. FDA guidance on physiologic alarm systems shapes product validation requirements for predictive analytics. The Cleveland Clinic and Mayo Clinic anchor enterprise-tier procurement, driving middleware standardization across multi-hospital networks.
Germany
Hospital digitization funding under the Hospital Future Act (KHZG) accelerates replacement of legacy monitoring infrastructure. IEC 60601-1-8 compliance requirements create certification barriers favoring established European vendors. The Rhine-Ruhr metropolitan region concentrates procurement activity, with university hospitals in Düsseldorf and Cologne piloting AI-enabled alarm suppression platforms.
Japan
Aging demographics and nursing workforce shortages intensify demand for automated alarm triage systems. PMDA regulatory pathways for software as a medical device streamline commercialization of cloud-native alarm analytics. The Keihin industrial corridor spanning Tokyo and Yokohama hosts dense concentrations of tertiary hospitals deploying integrated monitoring-to-alert workflows.
India
Private hospital chains in metro areas expand multi-parameter monitoring capacity as medical tourism and domestic health insurance penetration rise. CDSCO medical device rules increasingly align with international standards, reducing import friction for alarm management platforms. Bangalore and Hyderabad anchor technology adoption, with corporate hospital groups deploying centralized monitoring across expanding facility networks.
Brazil
ANVISA medical device registration requirements shape vendor market entry strategies for alarm management solutions. Private health plan expansion drives investment in hospital infrastructure outside the public SUS system. São Paulo state concentrates demand, with hospital networks in the capital and Campinas metropolitan area standardizing alarm platforms across acquired facilities.
Clinical Alarm Management Market Key Industry Players
Concentration sits with diversified medical technology conglomerates and specialized middleware vendors competing across overlapping territory. The vendor base spans pulse oximetry heritage players extending into hospital-wide integration, bedside monitoring incumbents defending installed base positions, and mobile alerting specialists capturing roaming caregiver notification workflows. Two strategic archetypes dominate: integrated monitoring-to-alert stack providers, and standalone software vendors unbundling analytics from hardware. Competitive moves center on strategic partnerships for EHR interoperability and algorithmic licensing agreements for AI-enabled suppression.
Within the integrated stack tier, Koninklijke Philips N.V. and GE Healthcare exemplify bedside-to-cloud architectures spanning monitoring hardware through centralized middleware. Masimo occupies a position extending pulse oximetry dominance into alarm integration, while Ascom Holding AG sits within the mobile alerting specialization vector. These named entities represent how heritage positioning in adjacent medical technology domains translates into alarm management market presence.
| Leading Market Players |
|---|
| Masimo |
| Spok Inc. |
| Koninklijke Philips N.V. |
| Nihon Kohden Corporation |
| Baxter International Inc. |
| GE Healthcare |
| Ascom Holding AG |
| Capsule Technologies, Inc. |
| Medtronic |
| Others |
Cost & Logistics Intelligence
Long-term capacity reservation contracts with Taiwan-based semiconductor foundries lock in sensor microcontroller supply and price visibility for alarm hardware vendors, insulating procurement committees from spot-market volatility while embedding IEC 60601-1-8 certification costs into multi-year agreements.
Pricing Analysis
Joint Commission NPSG.06.01.01 dictates the pricing tier structure across the United States market, separating enterprise health systems absorbing premium centralized platform costs from nursing facilities constrained by Medicaid reimbursement ceilings. Pricing stratifies across FDA-cleared AI analytics tiers, cloud-native SaaS subscriptions, and legacy bedside hardware bundles. Cost compression in standalone alarm units is intensifying because group purchasing organizations unbundle software licenses from hardware contracts. Community hospitals exhibit highest price sensitivity; integrated delivery networks demonstrate lowest sensitivity due to consolidated procurement leverage.
Supply Chain Analysis
Eighteen-month lead times for IEC 60601-1-8 acoustic certification create inventory buffers that strain working capital for middleware vendors. Hardware assembly concentrates in China, Malaysia, and Mexico, while sensor microcontrollers draw from Taiwan and South Korea. Supply chain risk centers on single-source vulnerability for FDA-validated algorithm training datasets. Distribution runs through group purchasing organizations and direct hospital system contracts, bypassing traditional medical device distributors for enterprise-tier deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI-enabled alarm suppression is disrupting legacy monitoring architectures, with FDA breakthrough device designations accelerating commercialization timelines for predictive analytics vendors.
For Market Incumbents: Shield installed base positions by deepening EHR interoperability certification investments that extend Meaningful Use Stage 3 compliance timelines for challengers. Acquire specialized middleware vendors with established Joint Commission documentation workflows to preempt standalone software entrants from penetrating integrated delivery networks. For New Entrants and Emerging Players: Differentiate on federated learning architectures that enable alarm model training without centralizing protected health information, addressing hospital system data governance constraints. Target skilled nursing facility underpenetration in United States post-acute markets where Medicaid reimbursement expansion creates addressable white space. Pursue software-as-a-service positioning to bypass capital expenditure barriers locking mid-size community hospitals out of enterprise-tier solutions. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native alarm analytics vendors with FDA-predetermined change control plans already submitted. Five-to-ten year viability favors platforms with established hospital system partnerships and algorithmic IP moats rather than hardware-dependent business models. Monitor CMS reimbursement adjustments for alarm-related adverse events as the signal indicating accelerated replacement cycles in underinvested nursing facilities.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Expedited review accelerates commercialization for AI-enabled alarm prioritization algorithms. |
| Hospital System Partnership | Cleveland Clinic and Mayo Clinic procurement patterns drive middleware standardization across networks. |
| CE Marking Pathway | IEC 60601-1-8 compliance creates certification barriers favoring established European vendors in Germany. |
| Software Companion Development | Mobile caregiver alerting applications capture roaming notification workflows beyond bedside hardware. |
| Reimbursement Strategy | CMS adjustments for alarm-related adverse events would unlock skilled nursing facility replacement demand. |
Research Approach
Operator-level perspectives from biomedical engineers, hospital purchasing committee chairs, GPO contracts managers, and alarm platform product directors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, Joint Commission accreditation records, CMS Medicare cost reports, and hospital procurement databases. Bottom-up unit economics triangulated against top-down health system IT spending benchmarks.
Sensitivity analysis tested forecast outputs against alternative scenarios for Joint Commission enforcement intensity and cloud migration adoption curves. Segmentation dimensions spanned product type, end-user facility class, deployment architecture, and regional regulatory cluster. CAGRs derived from logistic diffusion modeling of alarm fatigue reduction investments across the projection horizon. Algorithmic suppression adoption rates and EHR interoperability certification timelines served as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained FDA breakthrough device pathway velocity or accelerated cloud infrastructure buildout would require recalibration. Forecasts reflect documented assumptions regarding reimbursement policy continuity and semiconductor supply normalization. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Canada Patient Monitoring Devices Market
Patient Monitoring
Asia-Pacific Remote Patient Monitoring Systems Market
Patient Monitoring
Global Vital Sign Monitoring Market
Patient Monitoring
Patient Monitoring Pods Market
Patient Monitoring
Japan Patient Care Monitoring Equipment Market
Patient Monitoring
North America Self-Monitoring Blood Glucose Market
Patient Monitoring
Drowsiness Monitoring System Market
Patient Monitoring
Global Bed Monitoring System and Baby Monitoring System Market
Patient Monitoring
United States Cardiac Holter Monitor Market
Patient Monitoring
Global Heart Rate Monitor Market
Patient Monitoring
Telemonitoring Systems Market
Patient Monitoring
France Patient Monitoring Market
Patient Monitoring
Cardiac Rhythm Remote Monitoring Devices Market
Patient Monitoring
Global Arrhythmia Monitoring Devices Market
Patient Monitoring
Blood Pressure Monitors Market
Patient Monitoring
Middle East and Africa Remote Patient Monitoring Market