
 US Practice Management Systems Market | 2026-2036
US Practice Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
US Practice Management Systems Market Intelligence
Subscription-based interoperability modules are repositioning how US practice management vendors package core functionality. Epic Systems Corporation leverages its dominant hospital footprint to extend ambulatory practice tools downstream. Athenahealth, Inc. sustains a cloud-native architecture that reduces IT overhead for independent practices. Cerner Corporation (Oracle) anchors enterprise clients through backward integration into revenue cycle operations.
A practice management system technically integrates scheduling, billing, claims processing, and reporting functions into a unified administrative platform, typically supporting HL7 FHIR data exchange and ICD-10 coding compliance to streamline clinical business operations. Cloud-based deployment leads segment momentum as private practices abandon server maintenance burdens, while hybrid architectures retain traction among ambulatory surgical centers balancing data sovereignty with remote access needs. Technical support and integration services capture expanding margin pools as practices layer analytics tools atop legacy infrastructure.
The ONC Cures Act Final Rule and HIPAA security standards shape vendor certification requirements and data exchange protocols across US healthcare IT procurement. FDA oversight of clinical decision support modules embedded within practice platforms adds compliance complexity for developers. Stakeholders must monitor state-level Medicaid reimbursement rule changes that determine whether new practice management capabilities qualify for federal funding.
Market Dynamics
Cloud-native architectures are displacing on-premise installations across independent physician practices, while the ONC Cures Act Final Rule mandates interoperability standards that force vendors to reengineer certification pathways.
Growth Catalysts
- ONC Cures Act Final Rule:Federal interoperability mandates compel vendors to deploy HL7 FHIR data exchange capabilities, expanding addressable market for certified platforms.
- Independent physician practices:Small and mid-sized ambulatory groups are abandoning server maintenance burdens in favor of subscription-based SaaS deployment models.
- Texas, California, and Florida:Multi-location practice networks in these states concentrate procurement volumes and drive standardization across regional health systems.
Market Restraints
- HIPAA security compliance costs:Encryption, audit logging, and breach notification infrastructure impose recurring operational overhead that squeezes vendor margins.
- Legacy data migration complexity:Decades of unstructured patient records in proprietary formats create technical debt that slows cloud transition timelines.
- Interoperability implementation gaps:Incomplete FHIR adoption across competing platforms perpetuates data silos that undermine promised integration benefits.
Strategic Opportunities
- Rural health clinics:Federally qualified health centers in underserved counties remain underpenetrated by enterprise-grade practice management platforms.
- Revenue cycle analytics convergence:Artificial intelligence modules layered atop billing infrastructure are capturing expanding margin pools from denial management automation.
- Medicaid reimbursement rule changes:State-level policy adjustments determine whether new capabilities qualify for federal funding, creating procurement windows.
Industry Challenges
- HL7 FHIR implementation expertise:Shortage of engineers proficient in healthcare data standards creates bottlenecks in product development cycles.
- FDA clinical decision support oversight:Regulatory ambiguity around software-as-medical-device classification delays feature rollouts and expands legal exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Practice Management Systems Market |
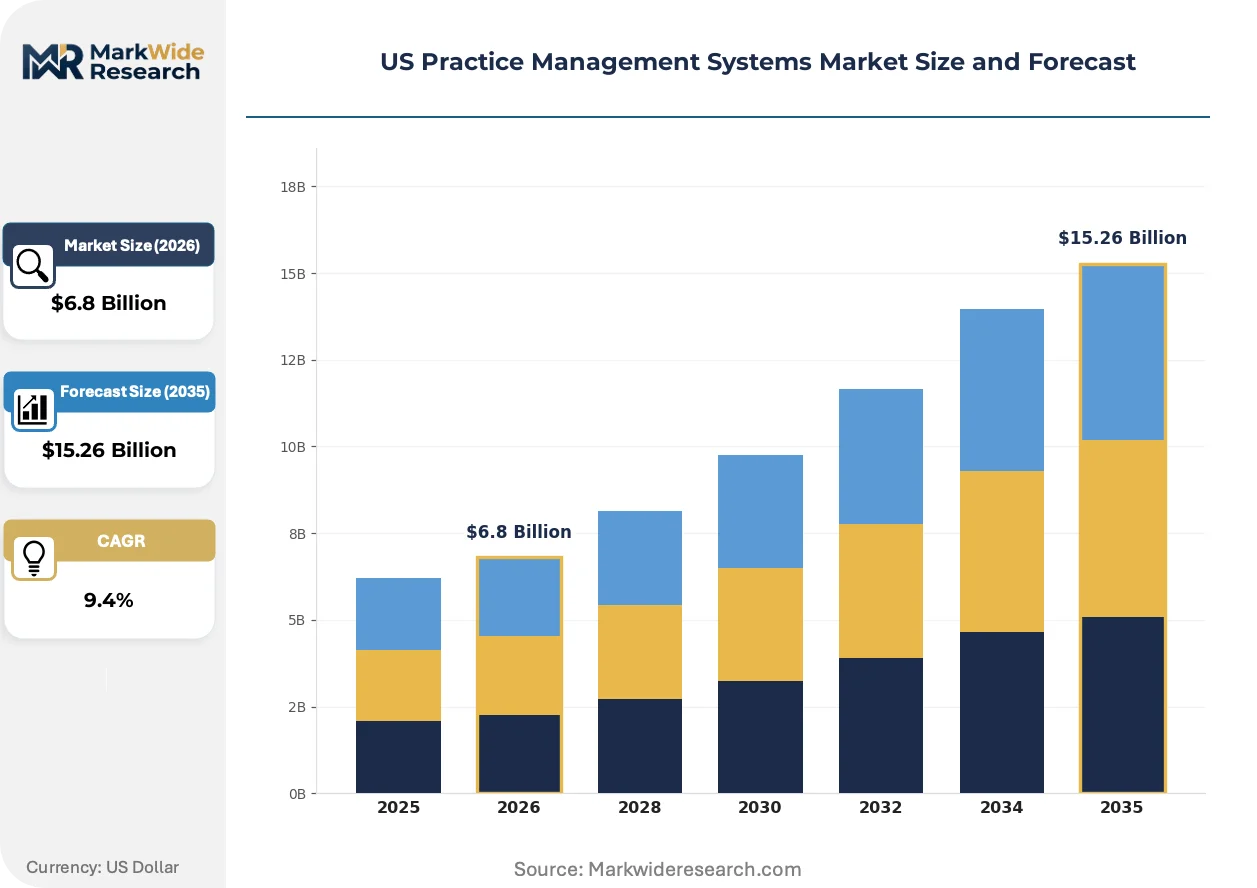
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Premise, Cloud-Based, Hybrid, Standalone End User: Hospitals, Clinics, Private Practices, Ambulatory Surgical Centers Deployment Model: Public Cloud, Private Cloud, Community Cloud, Multi-Tenant Service Type: Technical Support, Consulting Services, Customization, Integration |
| Companies Covered | Epic Systems Corporation, Athenahealth, Inc., eClinicalWorks, Cerner Corporation (Oracle), Henry Schein, Inc., Veradigm LLC (Allscripts Healthcare), McKesson Corporation, GE Healthcare, Greenway Health, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Practice Management Systems Market Strategic Shifts & Innovations
Artificial intelligence is embedding into administrative workflows, while regulatory pressure accelerates standardization and buyer expectations shift toward consumption-based pricing models.
Machine learning algorithms for claims scrubbing and denial prediction are integrating into core billing modules. Ambulatory surgical centers and multi-specialty groups are adopting these tools fastest. This capability compression is forcing standalone revenue cycle vendors to defend position through deeper EHR partnerships or acquisition.
The ONC Cures Act Final Rule mandates standardized APIs for patient data access. This policy compels vendors to expose longitudinal records to third-party applications. Independent practices in Texas and Florida are leveraging this portability to switch platforms with reduced data loss risk.
Subscription pricing with usage-based tiers is displacing perpetual license models. Small practices prefer predictable monthly costs over capital-intensive upfront purchases. California-based independent physician associations are negotiating group purchasing contracts that aggregate bargaining power across hundreds of member clinics.
US Practice Management Systems Market Segmentation
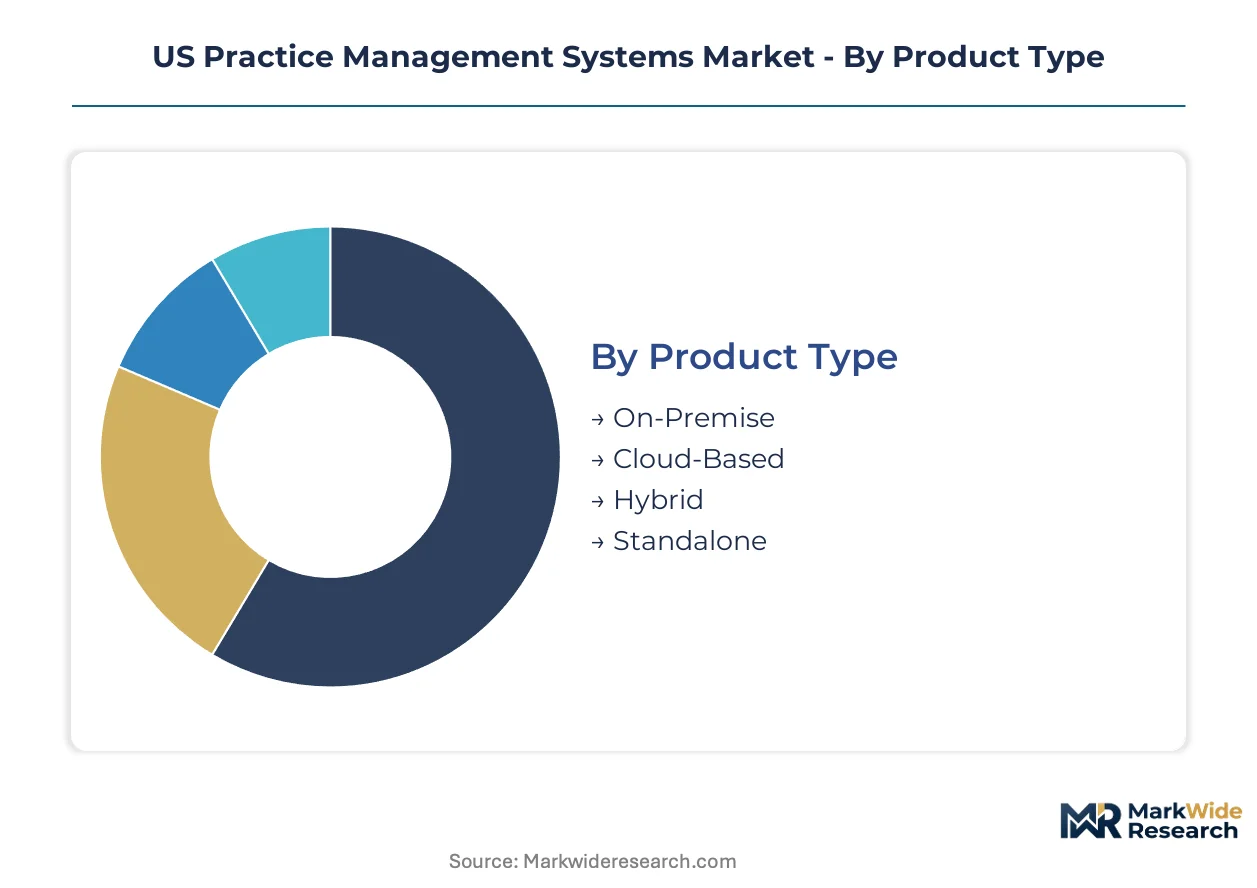
Segmentation in the US practice management systems market reveals how certification burdens, deployment complexity, and end-user scale reshape procurement patterns. Vendors must align product architecture with specific HIPAA compliance tiers and ONC certification pathways to capture share across diverging customer needs.
Product Type:
Cloud-based platforms carry lighter FDA oversight for clinical decision support modules, while on-premise systems face stricter state-level data sovereignty audits. Certification intensity varies directly with deployment architecture.
- On-Premise:Legacy server installations requiring dedicated IT staff and localized HIPAA audit trails. Demand concentrates in ambulatory surgical centers across Texas where data custody concerns override cloud migration incentives.
- Cloud-Based:Multi-tenant SaaS architectures with automated ONC certification updates and encrypted HL7 FHIR exchange. Independent physician practices in California and Florida are abandoning server maintenance burdens fastest.
- Hybrid:Split configurations preserving sensitive billing data on local servers while routing scheduling through cloud interfaces.
- Standalone:Modular point solutions for single-function replacement without full platform overhaul.
Leading the category by volume: Cloud-Based. Growing fastest: Hybrid.
End User:
Procurement scale and integration complexity separate hospital enterprise deals from clinic-level subscriptions, with reimbursement eligibility creating diverging capability requirements.
- Hospitals:Enterprise-wide deployments demanding Epic or Cerner backbone compatibility and revenue cycle integration. Multi-location networks in Florida concentrate procurement volumes.
- Clinics:Federally qualified health centers requiring Medicaid reimbursement rule alignment and sliding-scale billing modules. Texas rural counties show underpenetrated demand.
- Private Practices:Solo and small-group physicians prioritizing subscription predictability over capital expenditure.
- Ambulatory Surgical Centers:Procedure-focused workflows needing anesthesia scheduling and implant inventory tracking.
Highest procurement concentration: Hospitals. Steepest expansion trajectory: Clinics.
Deployment Model:
Cost tier and data isolation requirements drive selection, with public cloud dominating at the economy tier and private cloud anchoring premium deployments.
- Public Cloud:Shared infrastructure with standardized security patches and lowest per-seat pricing. Independent practices in California negotiate group purchasing contracts across hundreds of member clinics.
- Private Cloud:Dedicated single-tenant environments with custom encryption key management. Ambulatory surgical centers in Texas balance data sovereignty with remote access needs.
- Community Cloud:Collaborative infrastructure shared among affiliated practices within regional health systems.
- Multi-Tenant:Segregated logical partitions on common hardware enabling vendor operational efficiency.
Dominant by revenue: Public Cloud. Gaining share fastest: Private Cloud.
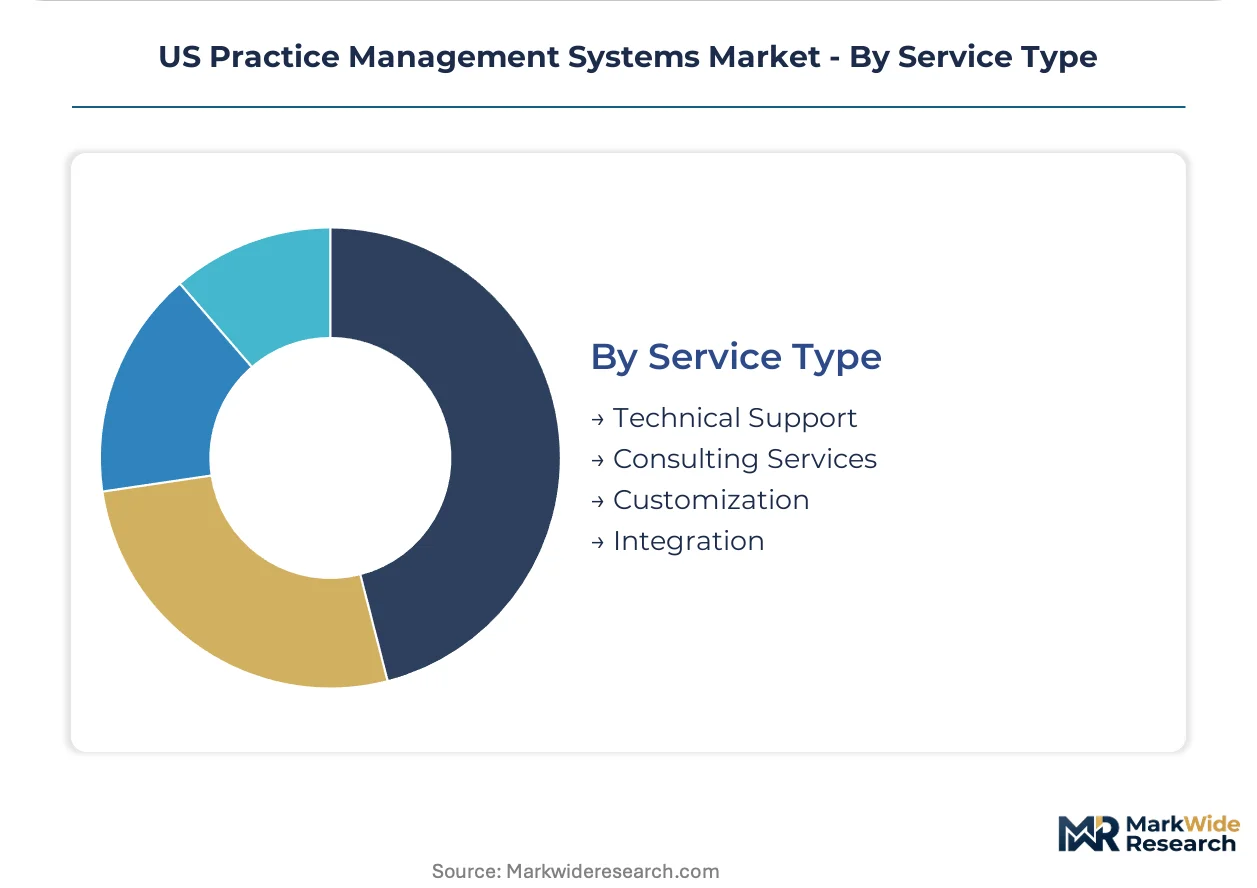
Service Type:
Margin pools concentrate in high-touch integration work, while technical support commoditizes and customization creates vendor lock-in.
- Technical Support:Tiered response SLAs with 24/7 coverage premiums. Standard offerings face pricing pressure as cloud-native platforms reduce failure rates.
- Consulting Services:Workflow optimization and change management for practice transitions. Florida multi-location networks drive standardization demand.
- Customization:Specialty-specific template development and reporting dashboard configuration.
- Integration:HL7 FHIR mapping and legacy EHR data migration. California practices layering analytics tools atop infrastructure expand margin pools.
Largest revenue contributor: Integration. Climbing the fastest: Consulting Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dallas-Fort Worth metroplex anchors US practice management procurement volumes through its dense concentration of multi-location physician networks and ambulatory surgical center chains.
Texas
Independent physician associations across Houston and Austin are consolidating purchasing power through group contracts for cloud-based scheduling platforms. The Texas Medical Board enforces strict data sovereignty requirements that slow cloud migration in rural counties. Federally qualified health centers in the Rio Grande Valley remain underpenetrated by enterprise-grade systems.
California
Silicon Valley-based health technology vendors are piloting AI-embedded billing modules with large independent practice associations in Los Angeles and San Francisco. The California Department of Justice actively enforces HIPAA breach notification standards through its medical privacy unit. Sacramento-area multi-specialty groups are standardizing on hybrid deployment models to balance compliance with innovation access.
Florida
Retirement corridor practices from Miami to Tampa are driving demand for Medicare-specific claims processing capabilities. The Florida Agency for Health Care Administration mandates Medicaid reimbursement system compatibility for state-funded clinic upgrades. Orlando-area ambulatory surgical centers are procuring anesthesia scheduling modules at accelerating rates.
New York
Manhattan-based academic medical centers are extending Epic Systems ambulatory tools into affiliated community practices across the five boroughs. The New York State Department of Health enforces ONC certification requirements through its health IT incentive programs. Buffalo and Rochester independent practices are negotiating collective SaaS contracts through regional IPA structures.
Illinois
Chicago health system networks are consolidating revenue cycle operations across suburban outpatient clinics. The Illinois Department of Healthcare and Family Services adjusts Medicaid reimbursement rules that determine practice management capability eligibility. Peoria and Springfield rural health clinics are accessing federal HRSA funding for platform modernization.
US Practice Management Systems Market Key Industry Players
Capital-heavy enterprise software producers compete with asset-light cloud-native designers across divergent customer segments. The vendor landscape organizes into three tiers: hospital-anchored platforms serving integrated delivery networks, ambulatory-focused specialists targeting independent practices, and modular point-solution providers filling workflow gaps. Dominant competitive moves include backward integration into revenue cycle operations and strategic partnerships with regional health information exchanges.
Within the hospital-anchored tier, Epic Systems Corporation and Cerner Corporation (Oracle) occupy positions defined by enterprise EHR backbone compatibility. Athenahealth, Inc. exemplifies the cloud-native archetype through its multi-tenant SaaS architecture. These three entities represent the structural poles around which competitive positioning organizes: scale-driven enterprise consolidation versus agile independent practice targeting.
| Leading Market Players |
|---|
| Epic Systems Corporation |
| Athenahealth, Inc. |
| eClinicalWorks |
| Cerner Corporation (Oracle) |
| Henry Schein, Inc. |
| Veradigm LLC (Allscripts Healthcare) |
| McKesson Corporation |
| GE Healthcare |
| Greenway Health |
| Others |
Cost & Logistics Intelligence
Backward integration into revenue cycle operations anchors both supply positioning and pricing power for dominant US practice management vendors. Epic Systems and Cerner leverage captive billing infrastructure to bundle subscription tiers that independent practices cannot replicate without heavy ONC certification investment. This structural moat protects margin pools even as cloud-native competitors force SaaS pricing compression at the mid-market edge.
Pricing Analysis
Cost-down pressure on enterprise tiers accelerates because hospital systems negotiate volume-based discounts across multi-location networks. Three-tier pricing structure across premium, standard, and economy levels separates ONC-certified platforms from uncertified modules and basic scheduling tools. Price differentiation traces to certification grade and after-sales integration support, with independent practices in California showing highest sensitivity to monthly subscription predictability while ambulatory surgical centers in Texas absorb premium private-cloud premiums for data sovereignty.
Supply Chain Analysis
Regional distribution centers in Dallas-Fort Worth and Silicon Valley concentrate software delivery infrastructure for cloud-native deployment. The vendor ecosystem draws from US-based engineering talent pools for HL7 FHIR development, Indian IT services for technical support scaling, and Irish data centers for EU-compliant hosting redundancy. Single-source vulnerability concentrates in FHIR implementation expertise shortages that delay product roadmaps. Distribution runs through direct sales teams for enterprise hospital contracts and value-added resellers for independent practice segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US practice management systems market functions as a cost-of-compliance story where ONC Cures Act Final Rule certification requirements erect barrier-to-entry moats that favor incumbent platforms with dedicated regulatory affairs infrastructure.
For Market Incumbents: Anchor enterprise client retention through deeper revenue cycle integration that locks hospital systems into backward-compatible upgrade paths. Defend against cloud-native displacement by accelerating AI-embedded billing module deployment before Athenahealth captures the independent practice sweet spot. Prioritize certification investment in Medicaid reimbursement rule alignment to capture federally funded procurement windows in Texas and Florida rural counties. For New Entrants and Emerging Players: Federally qualified health centers in underserved Texas counties represent the most penetrable buyer archetype for modular point solutions that bypass full-platform certification burdens. Target rural health clinics with standalone scheduling tools that layer atop legacy infrastructure through HL7 FHIR APIs rather than rip-and-replace strategies. Pursue group purchasing organization partnerships with California independent physician associations to aggregate bargaining power across hundreds of member clinics. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by hospital-anchored platforms seeking ambulatory footprint expansion. Long-term viability hinges on regulatory compliance infrastructure that sustains certification through successive ONC rule iterations. Acquisition target archetypes include cloud-native revenue cycle specialists with proven FHIR implementation expertise. Watch state-level Medicaid reimbursement rule changes as inflection indicators for federal funding eligibility that drives procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| ONC Certification Investment | ONC Cures Act Final Rule mandates create defensible market position against uncertified competitors. |
| Revenue Cycle Integration | Backward integration into billing operations locks hospital systems into upgrade-compatible platforms. |
| AI-Embedded Module Development | Machine learning claims scrubbing captures margin pools from standalone revenue cycle vendors. |
| Group Purchasing Organization Partnerships | California IPA contracts aggregate hundreds of independent practices into single procurement events. |
| Medicaid Reimbursement Alignment | State rule compatibility determines federal funding eligibility for rural health clinic modernization. |
Research Approach
Independent corroboration across hospital CIO interviews, independent practice administrator surveys, and GPO contracts managers underwrites the qualitative findings in this study. Primary fieldwork engaged health IT procurement officers, ONC certification consultants, revenue cycle operations directors, and ambulatory surgical center administrators across Texas, California, and Florida. Secondary validation drew from CMS Medicare reimbursement databases, ONC certified health IT product listings, state Medicaid program documentation, and hospital system 10-K disclosures. Bottom-up practice-level deployment estimates triangulate against top-down vendor revenue segmentation.
Comparable-period anchoring to historical cloud migration timelines and FHIR adoption curves shapes the projection horizon across deployment model, end-user scale, and service type dimensions. The analytical framework models subscription revenue recognition patterns, certification renewal cycles, and interoperability implementation lag times. CAGRs derive from segment-level growth rate convergence rather than single-point extrapolation. Forecast inputs include state-level Medicaid reimbursement rule change schedules and rural health clinic federal funding allocation trends.
Revisions become necessary when ONC rule amendments alter certification pathways, major hospital system consolidation shifts procurement concentration, or FHIR implementation expertise shortages deepen beyond current training pipeline capacity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Integrated Operating Room Management Systems Market
Healthcare IT
Healthcare Revenue Cycle Management (RCM) Software Market
Healthcare IT
Global Hospital Asset Tracking and Inventory Management Systems Market
Healthcare IT
Healthcare HR Software Market
Healthcare IT
Healthcare AIDC Market
Healthcare IT
Patient Registry Software Market
Healthcare IT
Healthcare Contact Center Solution Market
Healthcare IT
Wearable Biosensors Market
Healthcare IT
Global Back-End Revenue Cycle Management Market
Healthcare IT
Healthcare Technology Management Market
Healthcare IT
Healthcare IT Market
Healthcare IT
Cognitive Assessment and Training in Healthcare Market
Healthcare IT
Senior Care Technologies Market
Healthcare IT
Global Pharmaceutical Quality Management Software Market
Healthcare IT
E-Prescribing Systems Market
Healthcare IT
Hospital Capacity Management Solutions Market