
 Asia Pacific Pharmaceutical Glass Packaging Market | 2026-2036
Asia Pacific Pharmaceutical Glass Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Pharmaceutical Glass Packaging Market Insights
Type I borosilicate glass certification is unwinding as the baseline requirement across premium injectable packaging in Asia Pacific. SGD Pharma leverages its European technical heritage to sustain high-barrier coating capabilities for biologics in India and Southeast Asia. Schott AG anchors regional supply through its Malaysian and Indian manufacturing footprint, while Shandong Pharmaceutical Glass dominates domestic Chinese demand with cost-competitive borosilicate output.
Pharmaceutical glass packaging denotes containers fabricated from borosilicate or soda-lime glass, engineered with hydrolytic resistance Class I or II per pharmacopeial standards, formed through tubular or molded conversion processes to ensure chemical inertness and thermal shock tolerance for drug stability. Vials capture the dominant volume share across the product type dimension, driven by mRNA vaccine cold-chain requirements and prefilled syringe back-filling operations. Ampoules represent the fastest-expanding segment within oral medications and diagnostic reagents, where single-unit dosing and tamper-evident breakage properties command premium positioning.
India's CDSCO mandates DMF-linked packaging material approvals for imported drug products, while China's NMPA enforces GB standards for glass grain water resistance that filter out uncertified local suppliers. Japan's PMDA aligns with ICH Q3D elemental impurity guidelines, compelling manufacturers to certify extractable profiles for metal oxide content. Stakeholders must monitor how ASEAN harmonization of pharmaceutical packaging standards reshapes cross-border qualification timelines and supplier switching costs.
Market Dynamics
Type I borosilicate glass certification is hardening from a premium differentiator into a baseline procurement filter across Asia Pacific injectable packaging. Biologics manufacturers in China and India now disqualify suppliers lacking hydrolytic resistance Class I documentation, compressing qualification timelines and reshaping supplier tiers.
Growth Catalysts
- India's PLI scheme for pharmaceuticals:Production-linked incentives accelerate domestic manufacturing of Type I glass vials, reducing import dependency for biologic drug containment.
- mRNA vaccine cold-chain requirements:Temperature-sensitive biologics demand borosilicate vials with thermal shock tolerance, pulling capacity expansion in Jiangsu and Zhejiang provinces.
- ASEAN harmonization of pharmaceutical packaging standards:Cross-border qualification alignment reduces supplier switching costs and streamlines multi-country drug registrations.
Market Restraints
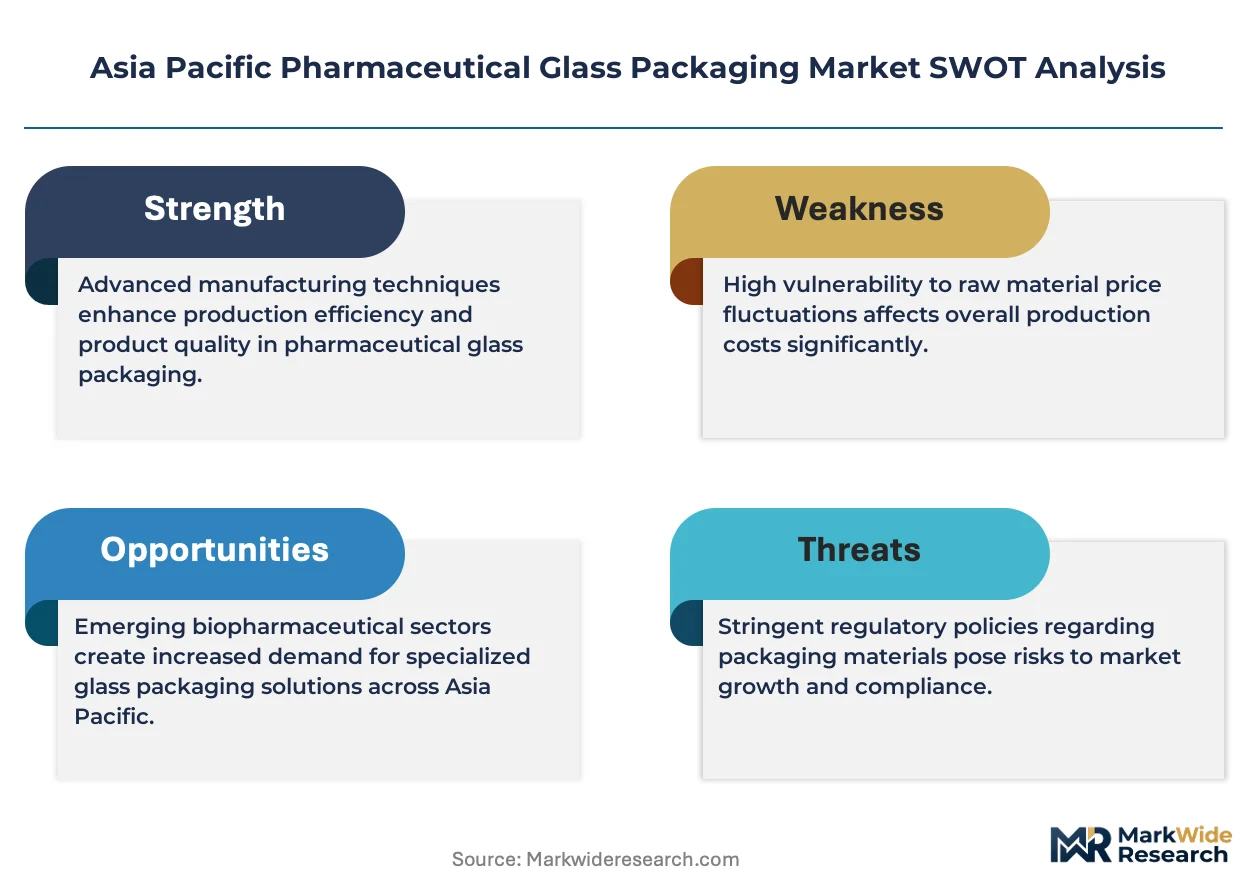
- Borosilicate raw material concentration:Specialty silica and alumina supply concentrates among limited global chemical suppliers, exposing converters to input cost volatility.
- China's NMPA enforcement of GB standards:Stringent glass grain water resistance testing filters out uncertified local suppliers, constraining qualified domestic capacity.
- Polymer substitution in oral solids:High-density polyethylene and cyclic olefin polymer bottles capture share in moisture-sensitive tablet applications where barrier demands are moderate.
Strategic Opportunities
- Vietnam and Indonesia biologics manufacturing:Greenfield injectable drug facilities in Southeast Asian markets lack established local glass packaging supply, creating first-mover qualification windows.
- Prefilled syringe back-filling integration:Glass vial-to-syringe fill-finish automation convergence enables packaging converters to capture downstream value in parenteral delivery systems.
- Japan's PMDA ICH Q3D alignment:Elemental impurity certification requirements for metal oxide extractables create premium positioning for verified low-alumina borosilicate formulations.
Industry Challenges
- DMF-linked packaging material approvals:India's CDSCO mandates drug master file documentation for imported containers, extending qualification timelines for new supplier entry.
- Specialized glass-forming technician scarcity:Tubular glass conversion and molded vial production require skilled heat-process operators that training pipelines have not replenished.
- Legacy soda-lime capacity stranded:Class II hydrolytic resistance equipment cannot be retrofitted for Class I borosilicate output, forcing asset write-downs or dedicated low-margin product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Pharmaceutical Glass Packaging Market |
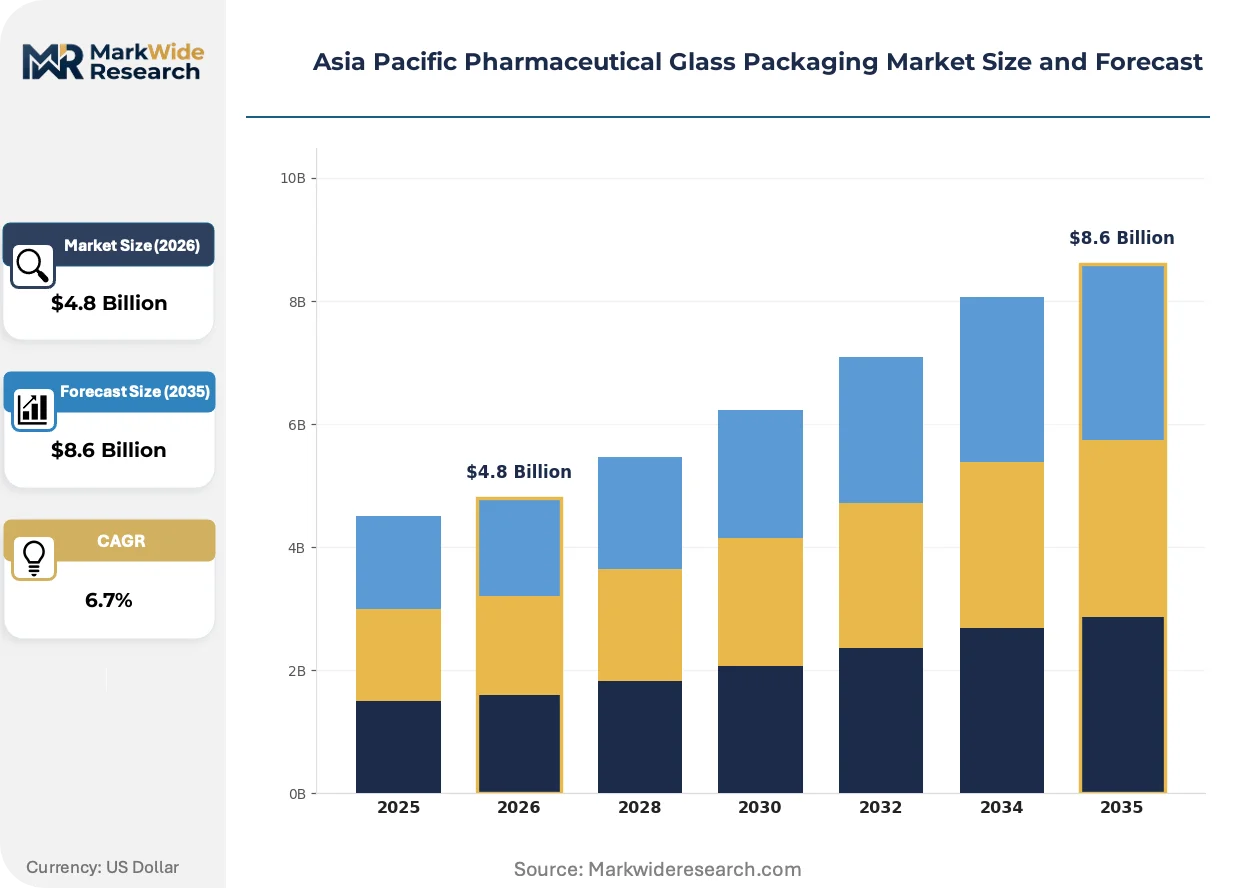
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ampoules, Vials, Bottles, Cartridges Closure Type: Rubber Stoppers, Aluminum Caps, Flip Off Caps, Screw Caps End User: Pharmaceutical Companies, Biotech Firms, Contract Manufacturers, Research Institutions Application: Injectables, Oral Medications, Diagnostic Products, Vaccine Storage |
| Companies Covered | SGD Pharma, Becton, Dickinson and Company, Schott AG, Corning Inc., Shandong Pharmaceutical Glass, Gerresheimer AG, AGI Greenpac Limited, Nipro Corp., Stevanato Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Pharmaceutical Glass Packaging Market Trends and Innovations
Glass packaging technology is bifurcating between commodity soda-lime containers for oral solids and engineered borosilicate systems for biologics, with regulatory chemistry requirements driving the wedge. Converter investment now concentrates on coating capabilities and dimensional precision rather than volume scale alone.
Silicon dioxide barrier coatings applied via chemical vapor deposition are displacing uncoated borosilicate vials in high-value biologic applications. Contract manufacturers serving multinational pharmaceutical firms specify coated containers for protein-based drugs requiring extended shelf stability. The technology is displacing premium pricing for European-imported vials by enabling Asian converters to match extractable performance profiles.
China's NMPA enforcement of GB 4806.5 food-contact glass standards is tightening migration limits for metal oxide leachables. Domestic converters must recertify product lines or exit the pharmaceutical supply chain for exported drug products. Japanese and South Korean drug sponsors now audit Chinese suppliers against both GB standards and ICH Q3D elemental impurity guidelines, layering compliance costs onto procurement decisions.
Biologics procurement teams are consolidating supplier panels from twelve-plus vendors to three qualified partners per container format. Large molecule drug sponsors in Australia and Singapore now mandate single-source accountability for vial, stopper, and seal combinations. This concentration is most visible in China's Yangtze River Delta, where CDMOs pre-qualify packaging configurations during drug development phases to avoid late-stage regulatory delays.
Asia Pacific Pharmaceutical Glass Packaging Market Segmentation
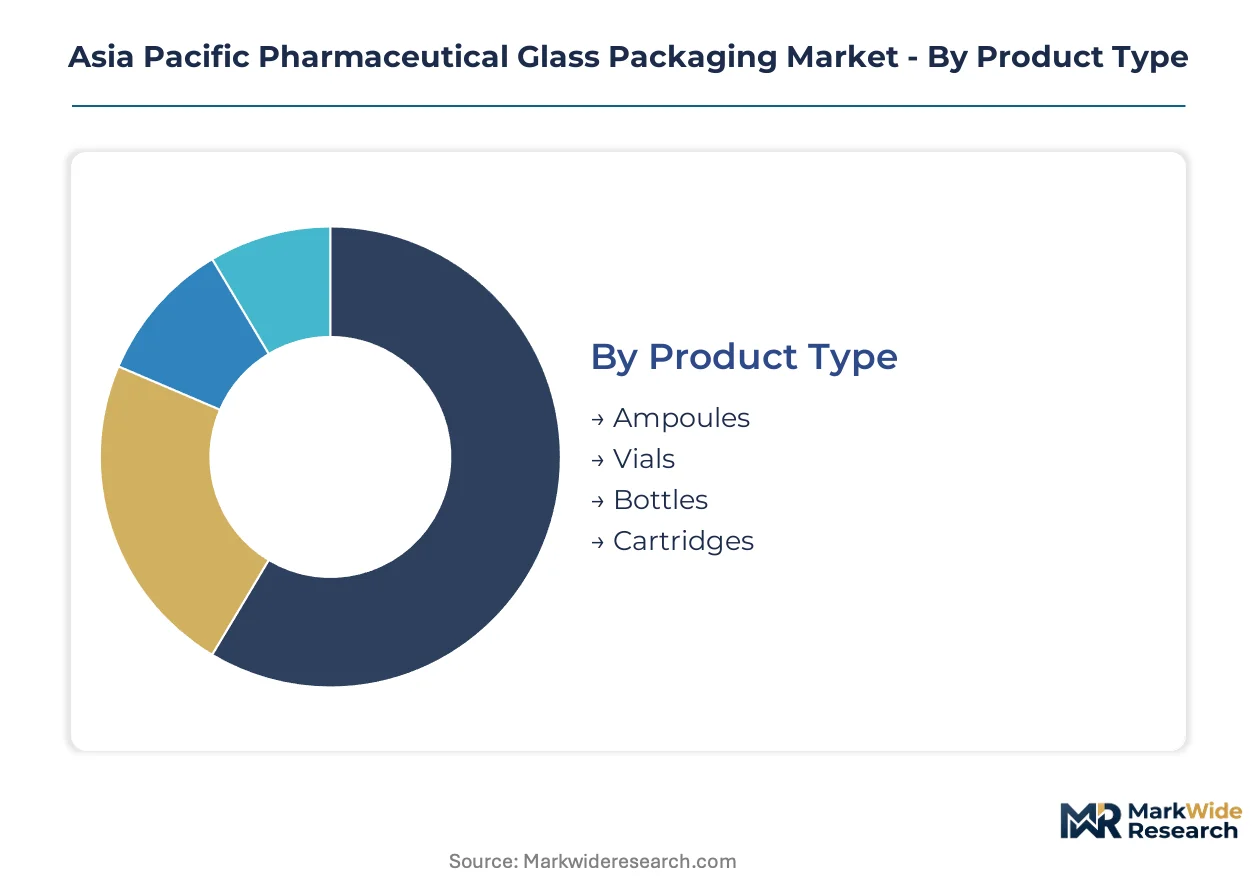
Pharmaceutical glass packaging in Asia Pacific segments across four intersecting dimensions that determine qualification pathways and margin capture. Product type and application together dictate hydrolytic resistance requirements, while closure integration and end-user specifications govern supplier certification complexity.
Product Type:
Margin pools concentrate in formats serving temperature-sensitive biologics and automated fill-finish lines, where dimensional precision commands premium positioning.
- Vials:Tubular and molded borosilicate containers engineered for hydrolytic resistance Class I per pharmacopeial standards. Demand concentrates in China's Jiangsu and Zhejiang provinces where mRNA vaccine cold-chain requirements and prefilled syringe back-filling operations pull capacity expansion.
- Ampoules:Single-unit glass containers with scored necks for tamper-evident breakage, formed through tubular conversion processes. Biotech firms in India and Southeast Asia specify ampoules for oral medications and diagnostic reagents where dose integrity and breakage indication justify unit-dose positioning.
- Bottles:Molded soda-lime and borosilicate containers for multi-dose liquid and solid formulations. Oral solid dosage manufacturers in Japan and South Korea source amber and flint glass bottles for moisture-sensitive tablet applications.
- Cartridges:Cylindrical glass reservoirs engineered for pen-injector and auto-injector integration, requiring tight dimensional tolerances for plunger seal compatibility. Penetration remains limited in Asia Pacific versus European and North American markets.
Vials hold installed capacity across Malaysian and Indian manufacturing footprints. Ampoules is rotating up the share rankings as diagnostic reagent demand accelerates.
Closure Type:
Closure selection follows container format with rubber-to-glass interface chemistry determining extractable profiles and seal integrity under thermal stress.
- Rubber Stoppers:Bromobutyl and chlorobutyl elastomer formulations laminated with fluoropolymer films to reduce protein adsorption. CDMOs in China's Yangtze River Delta pre-qualify stopper-vial combinations during drug development phases to avoid late-stage regulatory delays.
- Flip Off Caps:Aluminum-plastic composite closures providing tamper evidence and sterile access for multi-dose vials. Contract manufacturers serving multinational pharmaceutical firms specify flip-off configurations for protein-based drugs requiring extended shelf stability.
- Aluminum Caps:Crimped metal closures for ampoule and bottle sealing, with lacquer-lined interiors preventing metal ion migration. India's CDSCO mandates DMF-linked documentation for imported aluminum closure assemblies.
- Screw Caps:Threaded polypropylene or phenolic closures for oral solid and liquid bottles where resealability outweighs tamper evidence requirements. Domestic Chinese converters supply screw cap assemblies under GB 4806.5 food-contact standards.
Rubber stoppers dominate injectable format pairing. Flip off caps is climbing the fastest as biologics procurement panels consolidate to three qualified partners per container format.
End User:
End-user category determines order scale, qualification timeline, and technical service intensity, with biologics sponsors imposing the most stringent supplier accountability.
- Biotech Firms:Developers of monoclonal antibodies, mRNA therapeutics, and cell therapies requiring Type I borosilicate containment with documented extractable profiles. China's NMPA enforcement of GB standards for glass grain water resistance filters out uncertified local suppliers serving this segment.
- Pharmaceutical Companies:Integrated drug manufacturers with established supplier panels and volume-scale procurement. Japan's PMDA alignment with ICH Q3D elemental impurity guidelines compiles manufacturers to certify metal oxide content for pharmaceutical company sponsors.
- Contract Manufacturers:CDMOs and CMOs serving multiple drug sponsors with format-flexible packaging requirements. Vietnam and Indonesia biologics manufacturing greenfield facilities lack established local glass packaging supply, creating first-mover qualification windows for contract manufacturers.
- Research Institutions:Academic and clinical trial material suppliers with small-batch, multi-format needs and abbreviated qualification pathways. Research institutions typically source through distributor channels rather than direct converter relationships.
Pharmaceutical companies hold installed capacity through long-term supply agreements. Biotech firms is gaining share fastest as monoclonal antibody and mRNA pipeline expansion accelerates.
Application:
Application chemistry dictates hydrolytic resistance class, with parenteral formats requiring Class I borosilicate and oral solids tolerating Class II soda-lime in moisture-barrier configurations.
- Injectables:Parenteral drug products including biologics, vaccines, and small-molecule solutions requiring sterile, pyrogen-free containment with demonstrated chemical inertness. Temperature-sensitive biologics demand borosilicate vials with thermal shock tolerance, pulling capacity expansion in regional manufacturing clusters.
- Vaccine Storage:Cold-chain distribution formats for temperature-sensitive immunization products, including mRNA and viral vector platforms. ASEAN harmonization of pharmaceutical packaging standards reduces supplier switching costs for vaccine storage applications across multi-country registrations.
- Oral Medications:Solid and liquid dosage forms in bottles and ampoules where moisture and light protection govern barrier requirements. Polymer substitution in high-density polyethylene and cyclic olefin polymer bottles captures share in moisture-sensitive tablet applications where barrier demands are moderate.
- Diagnostic Products:Reagent containers for in-vitro diagnostics, including single-unit ampoules for point-of-care testing. Diagnostic product manufacturers specify silicon dioxide barrier coatings applied via chemical vapor deposition for extended shelf stability.
Injectables hold installed capacity through biologics manufacturing expansion. Vaccine storage is rotating up the share rankings as regional cold-chain infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity fragments sharply across the Asia Pacific pharmaceutical glass packaging landscape. India's biologics manufacturers prioritize cost-competitive Type I borosilicate sourcing under PLI incentives, while Japan's PMDA-regulated sponsors absorb premium pricing for elemental impurity-certified containment. China's NMPA enforcement has bifurcated domestic supply between qualified Jiangsu-Zhejiang clusters and filtered-out uncertified capacity.
China
Jiangsu and Zhejiang provinces concentrate injectable drug production capacity for mRNA vaccines and biologics. NMPA enforcement of GB standards for glass grain water resistance has eliminated uncertified local suppliers from pharmaceutical supply chains. Shandong Pharmaceutical Glass anchors domestic borosilicate output with cost-competitive manufacturing serving both export and domestic drug sponsors.
India
Monoclonal antibody and mRNA pipeline expansion accelerates demand for Type I borosilicate vials across Maharashtra and Gujarat pharmaceutical clusters. CDSCO mandates DMF-linked packaging material approvals for imported drug products, extending qualification timelines for foreign supplier entry. The PLI scheme for pharmaceuticals accelerates domestic manufacturing of Type I glass vials, reducing import dependency for biologic drug containment.
Japan
PMDA alignment with ICH Q3D elemental impurity guidelines compels manufacturers to certify extractable profiles for metal oxide content in biologics packaging. Osaka and Tokyo pharmaceutical sponsors command premium positioning for verified low-alumina borosilicate formulations. Contract manufacturers serving multinational firms specify coated containers for protein-based drugs requiring extended shelf stability.
South Korea
MFDS-regulated biologics manufacturing in Seoul Capital Area and Busan-Ulsan corridor drives demand for hydrolytic resistance Class I documentation. CDMOs pre-qualify packaging configurations during drug development phases to avoid late-stage regulatory delays. Domestic converters face layered compliance audits against both Korean standards and ICH Q3D guidelines from Japanese and Australian drug sponsors.
Vietnam
Greenfield injectable drug facilities in Ho Chi Minh City and Hanoi industrial zones lack established local glass packaging supply, creating first-mover qualification windows. ASEAN harmonization of pharmaceutical packaging standards reduces supplier switching costs for contract manufacturers establishing multi-country drug registrations. Foreign packaging converters target Vietnam for regional hub positioning serving Southeast Asian biologics manufacturing expansion.
Asia Pacific Pharmaceutical Glass Packaging Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Asia Pacific pharmaceutical glass packaging market. European-heritage specialists anchor premium-tier coating capabilities and high-barrier certification, while domestic Chinese and Indian converters capture volume scale through cost-optimized borosilicate output. Three archetypes dominate: multinational technical specialists with regional manufacturing footprints, domestic scale leaders serving local pharmaceutical clusters, and emerging Southeast Asian entrants targeting qualification windows in under-supplied markets. Competitive dynamics center on capacity expansion in Jiangsu and Zhejiang provinces and strategic partnerships for prefilled syringe back-filling integration.
Within the multinational specialist tier, SGD Pharma leverages its European technical heritage to sustain high-barrier coating capabilities for biologics across India and Southeast Asia. Schott AG anchors regional supply through Malaysian and Indian manufacturing footprints, exemplifying the technical-architecture archetype that drug sponsors specify for temperature-sensitive biologics. Among domestic scale leaders, Shandong Pharmaceutical Glass occupies a position representing cost-competitive borosilicate output serving China's concentrated injectable drug production demand.
| Leading Market Players |
|---|
| SGD Pharma |
| Becton, Dickinson and Company |
| Schott AG |
| Corning Inc. |
| Shandong Pharmaceutical Glass |
| Gerresheimer AG |
| AGI Greenpac Limited |
| Nipro Corp. |
| Stevanato Group |
| Others |
Pricing and Supply Chain Analysis
Type I borosilicate glass certification gates both supplier qualification and price differentiation across Asia Pacific injectable packaging. China's NMPA enforcement of GB standards for glass grain water resistance simultaneously filters uncertified domestic capacity and stratifies pricing tiers between verified Jiangsu-Zhejiang suppliers and premium European-heritage imports.
Pricing Analysis
After-sales technical service and DMF-linked regulatory support drive lifetime value for packaging converters serving multinational biologics sponsors. Three-tier pricing structure across premium, standard, and economy levels separates silicon dioxide barrier-coated vials from uncoated borosilicate and legacy soda-lime alternatives. Cost compression in standard-tier uncoated borosilicate is intensifying because India's PLI scheme accelerates domestic Type I vial manufacturing. Biotech firms demonstrate lowest price sensitivity for elemental impurity-certified containment, while generic injectable manufacturers in Vietnam and Indonesia prioritize landed cost minimization.
Supply Chain Analysis
Inbound logistics costs for specialty silica and alumina concentrates are climbing on Shanghai-Rotterdam and Shanghai-Mumbai trade lanes, compressing converter margins on European-imported raw materials. Borosilicate glass supply concentrates in China, Germany, and India, with tubular conversion capacity anchored in Malaysian and Indian manufacturing footprints. Converter operations draw from specialty silica deposits, boron trioxide chemical feedstock, and fluoropolymer film laminates for barrier coatings. Single-source vulnerability in bromobutyl rubber stopper supply exposes fill-finish operations to qualification delays. Distribution runs through direct converter relationships with CDMO procurement panels and pharmaceutical company supply chain hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific pharmaceutical glass packaging is fundamentally a service-attach opportunity where regulatory filing support and extractable profile documentation expand faster than commodity container sales. Technical service contracts for DMF preparation and elemental impurity testing now generate recurring revenue streams that outpace hardware margins.
For Market Incumbents: Consolidate supplier panels through exclusive coating technology licensing agreements and captive backward integration into bromobutyl rubber compounding. Polymer substitution in oral solid dosage bottles threatens soda-lime capacity utilization. Vertical integration into barrier coating chemical vapor deposition equipment defends premium positioning against emerging Asian converters. For New Entrants and Emerging Players: Differentiate on rapid DMF-linked qualification timelines for Vietnam and Indonesia greenfield biologics facilities lacking established local glass packaging supply. The most penetrable white-space sits in prefilled syringe back-filling integration where automated vial-to-syringe conversion commands downstream value capture. Target contract manufacturers with bundled stopper-vial-seal configuration pre-qualification services. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across silicon dioxide barrier coating capabilities as biologics procurement panels consolidate to three qualified partners per container format. Long-term viability over the coming decade favors converters with demonstrated ICH Q3D elemental impurity certification and established relationships with Japanese PMDA-regulated sponsors. Acquisition targets should display coating equipment ownership and in-house extractables testing laboratories. The signal to watch is ASEAN harmonization implementation timelines that compress cross-border qualification windows.| Strategic Initiative | Industry Significance |
|---|---|
| DMF-Linked Packaging Qualification | CDSCO mandates extend foreign supplier entry timelines, favoring incumbent documentation archives. |
| Barrier Coating Capacity Expansion | Chemical vapor deposition equipment enables Asian converters to match European extractable performance profiles. |
| Prefilled Syringe Back-Filling Integration | Automated fill-finish convergence captures downstream value in parenteral delivery systems. |
| ASEAN Harmonization Compliance | Cross-border standard alignment reduces multi-country drug registration supplier switching costs. |
| Elemental Impurity Testing Infrastructure | In-house ICH Q3D certification capabilities command premium positioning with Japanese PMDA sponsors. |
Research Methodology
Initial hypotheses were tested against primary input from regulatory affairs leads at biologics sponsors, pharmaceutical packaging procurement directors, CDMO supply chain managers, and glass converter technical sales executives and refined through secondary validation. Primary fieldwork combined structured interviews with trade data from Chinese customs records, Indian CDSCO DMF filings, Japanese PMDA submission databases, and ASEAN pharmaceutical harmonization documentation. Bottom-up capacity modeling across Jiangsu, Zhejiang, Maharashtra, and Gujarat manufacturing clusters triangulated against top-down demand estimates from mRNA vaccine and monoclonal antibody pipeline disclosures.
Variance decomposition across product type, application chemistry, closure integration format, and regional regulatory cluster shaped the analytical framework. Modeled dimensions included hydrolytic resistance class, end-user category, and country-specific qualification pathway complexity. CAGRs were derived from segment-level volume trajectories and value-per-unit escalation patterns for barrier-coated versus uncoated borosilicate formats. Forecast inputs incorporated PLI scheme capacity addition schedules and NMPA enforcement intensity assumptions.
Decision-makers should treat outputs as directional under sustained biologics manufacturing expansion and stable raw material supply; material deviation would warrant model refresh. Forecasts assume continued Type I borosilicate certification hardening and ASEAN regulatory convergence without major trade policy disruption. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Pharmaceutical Glass Packaging Market
Glass Packaging
Philippines Container Glass Market
Glass Packaging
Retail Glass Packaging Market
Glass Packaging
Asia - Pacific Glass Bottles and Containers Market
Glass Packaging
North America Glass Bottles/Containers Market
Glass Packaging
United Kingdom Container Glass Market
Glass Packaging
Middle East and Africa Glass Packaging Market
Glass Packaging
Croatia Container Glass Market
Glass Packaging
Portugal Container Glass Market
Glass Packaging
Glass Packaging Market
Glass Packaging
Russia Container Glass Market
Glass Packaging
Glass Veil Market
Glass Packaging
Hermetic Jars Market
Glass Packaging
Boston Round Glass Bottle Market
Glass Packaging
Glass Frosting for Packaging Market
Glass Packaging
Europe Cosmetic and Perfumery Glass Bottle Packaging Market