
 Fast Food Wrapping Paper Market | 2026-2036
Fast Food Wrapping Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Fast Food Wrapping Paper Market Analysis
Subscription-based grease-barrier coating services is consolidating how fast-food chains procure wrapping materials, shifting capital expenditure into recurring operational contracts. Huhtamäki Oyj leverages its global converting footprint to anchor supply agreements with multinational quick-service brands. Mondi plc specializes in kraft-paper barrier innovations that sustain performance under hot, oily conditions. Georgia-Pacific LLC dominates North American distribution through integrated pulp-to-paper mill networks.
Fast food wrapping paper denotes food-grade paper engineered with silicone, quilon, or aqueous barrier coatings to resist grease penetration and maintain tensile integrity at temperatures exceeding 85°C, serving the primary commercial purpose of protecting food quality and consumer handling safety during quick-service consumption. Waxed paper retains established share in legacy burger and sandwich applications, though eco-friendly design variants are capturing margin pools as chain-level sustainability commitments harden. Quick service restaurants represent the dominant end-user channel, while food trucks constitute the fastest-growing segment due to mobile kitchen expansion and limited on-site dishwashing infrastructure.
The FDA regulates indirect food-contact substances under 21 CFR, while the EU F-Gas Regulation and REACH framework constrain fluorochemical barrier chemistries, collectively elevating demand for PFAS-free coating technologies. BIS certification requirements in India further shape import and local manufacturing standards for food-contact papers. Stakeholders must monitor evolving state-level PFAS prohibitions in the United States and emerging compostability mandates across European member states to anticipate reformulation timelines and raw-material sourcing pivots.
Market Dynamics
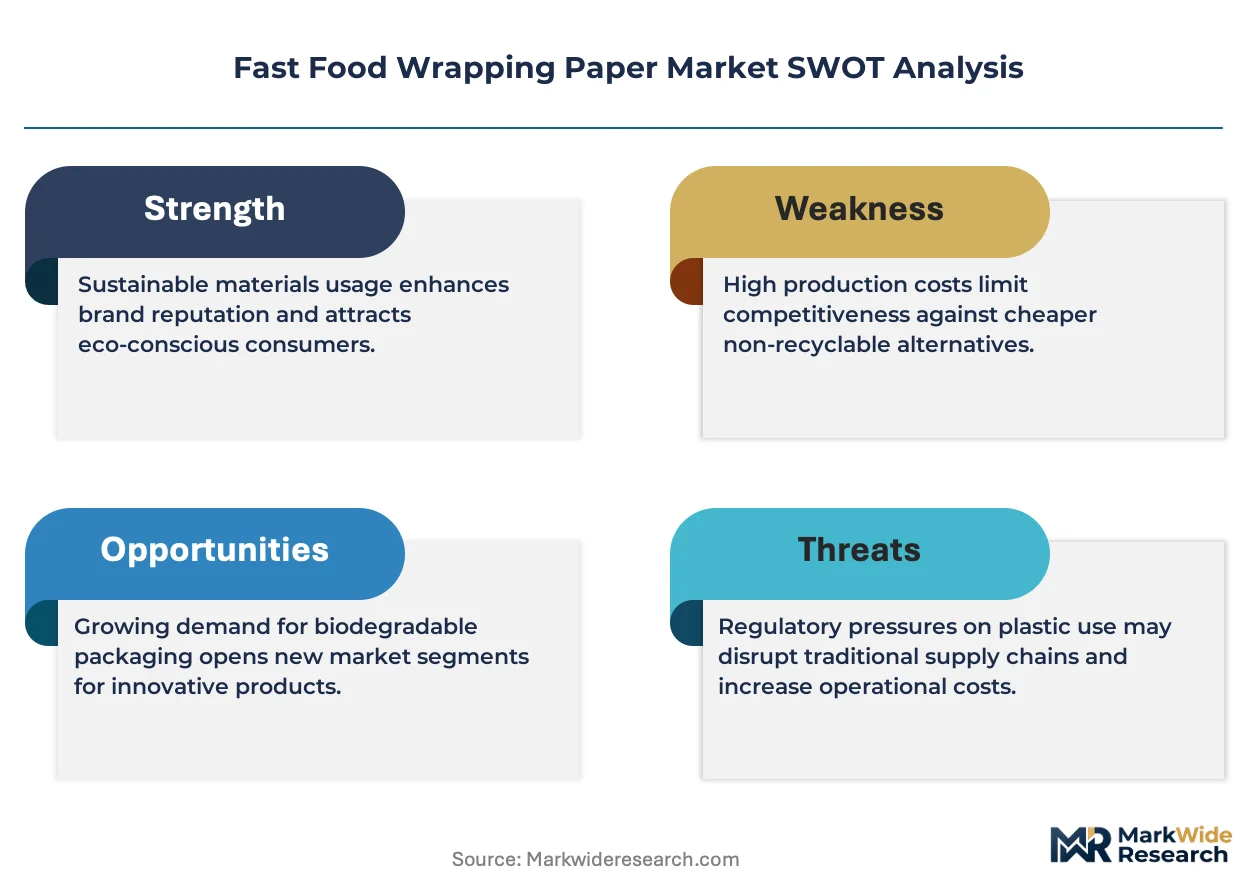
PFAS-free barrier chemistry migration is compressing incumbent coating supply chains while forcing rapid qualification cycles for silicone and aqueous alternatives across quick-service procurement desks.
Growth Catalysts
- EU F-Gas Regulation:The directive's phase-down of fluorinated gases is redirecting foodservice packaging investment toward cellulose-based grease barriers, tightening specifications for quick-service restaurant supply agreements.
- Quick-service restaurant expansion:Chains in Indonesia and Vietnam are scaling dine-in and takeaway volumes, pulling fiber-based wrap consumption upward through centralized distribution hubs.
- Aqueous coating technology:Water-based barrier formulations are achieving parity with legacy quilon performance at oven temperatures above 85°C, unlocking conversion in hot-hold sandwich applications.
Market Restraints
- Pulp cost volatility:Kraft fiber input prices swing with Nordic and North American softwood harvest cycles, squeezing converter margins on fixed-price annual contracts.
- Coating chemistry concentration:PFAS-free silicone supply concentrates among three specialty chemical houses in Germany and Japan, creating single-source vulnerability for mid-tier converters.
- Competing substrates:Molded fiber clamshells and bagasse trays are capturing premium burger and bowl applications where presentation value exceeds wrap economics.
Strategic Opportunities
- Compostability mandates:Emerging European member-state requirements for industrial compostability certification are creating first-mover advantage for converters with TÜV OK Compost INDUSTRIAL validation.
- Food truck channel penetration:Mobile kitchen operators lack dishwashing infrastructure and represent an underserved wrap volume segment with high SKU velocity and low switching costs.
- Barrier-plus-print convergence:Digital flexo over aqueous barriers is enabling short-run customized wraps for regional chain limited-time offers, collapsing minimum order quantities.
Industry Challenges
- Food-contact chemist scarcity:Qualified formulation scientists capable of navigating FDA 21 CFR and REACH dual compliance are concentrated among legacy packaging multinationals, constraining independent converter R&D velocity.
- Qualification timeline compression:Quick-service brand technical audits for new coating platforms now demand 18-month migration and sensory panels, extending payback periods for capital-intensive barrier lines.
- Legacy equipment retrofit friction:Aqueous coating systems require humidity-controlled drying tunnels incompatible with existing waxed-paper converting assets, forcing greenfield investment or contract tolling arrangements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fast Food Wrapping Paper Market |
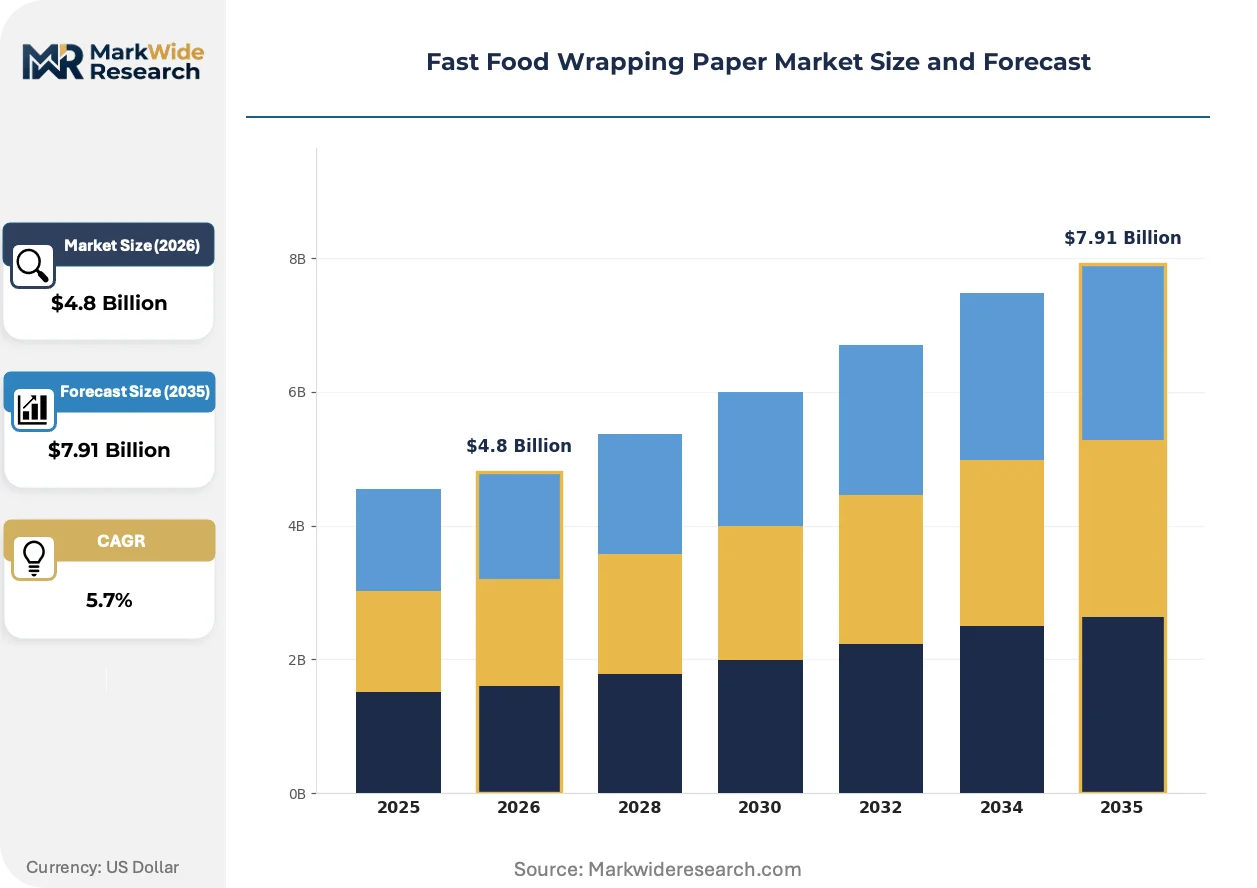
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Paper, Plastic, Waxed Paper, Aluminum Foil End User: Quick Service Restaurants, Food Trucks, Cafés, Catering Services Packaging Size: Small, Medium, Large, Extra Large Design Type: Printed, Plain, Customized, Eco-Friendly |
| Companies Covered | Berry Global, Inc., Amcor plc, Mondi plc, Huhtamäki Oyj, Sonoco Products Company, WestRock Company, International Paper Company, Graphic Packaging Holding Company, Georgia-Pacific LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fast Food Wrapping Paper Market Emerging Trajectories
Active barrier chemistry substitution and digital print integration are compressing product development cycles while fragmenting procurement authority across sustainability, operations, and brand marketing functions.
Silicone-based grease barriers are absorbing volume share previously held by quilon chrome complexes in hot sandwich applications. Quick-service chains with 2025 sustainability targets are accelerating qualification timelines from 36 to 18 months. The technology shift is absorbing margin from specialty chemical intermediaries while consolidating converter relationships around coating equipment lessors.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating fluorochemical options from European food-contact papers by 2026. The regulation is forcing reformulation investments across coating houses and paper mills serving EU quick-service brands. Southeast Asian exporters to European markets are responding by pre-certifying PFAS-free grades to maintain customs clearance velocity.
Subscription-based coating services are displacing capital purchase models among mid-size quick-service chains. Brand procurement teams are trading upfront extrusion line investment for per-meter operational charges tied to volume tiers. The shift is most visible in North American regional burger chains seeking to preserve balance sheet flexibility during store network expansion.
Fast Food Wrapping Paper Market Segmentation
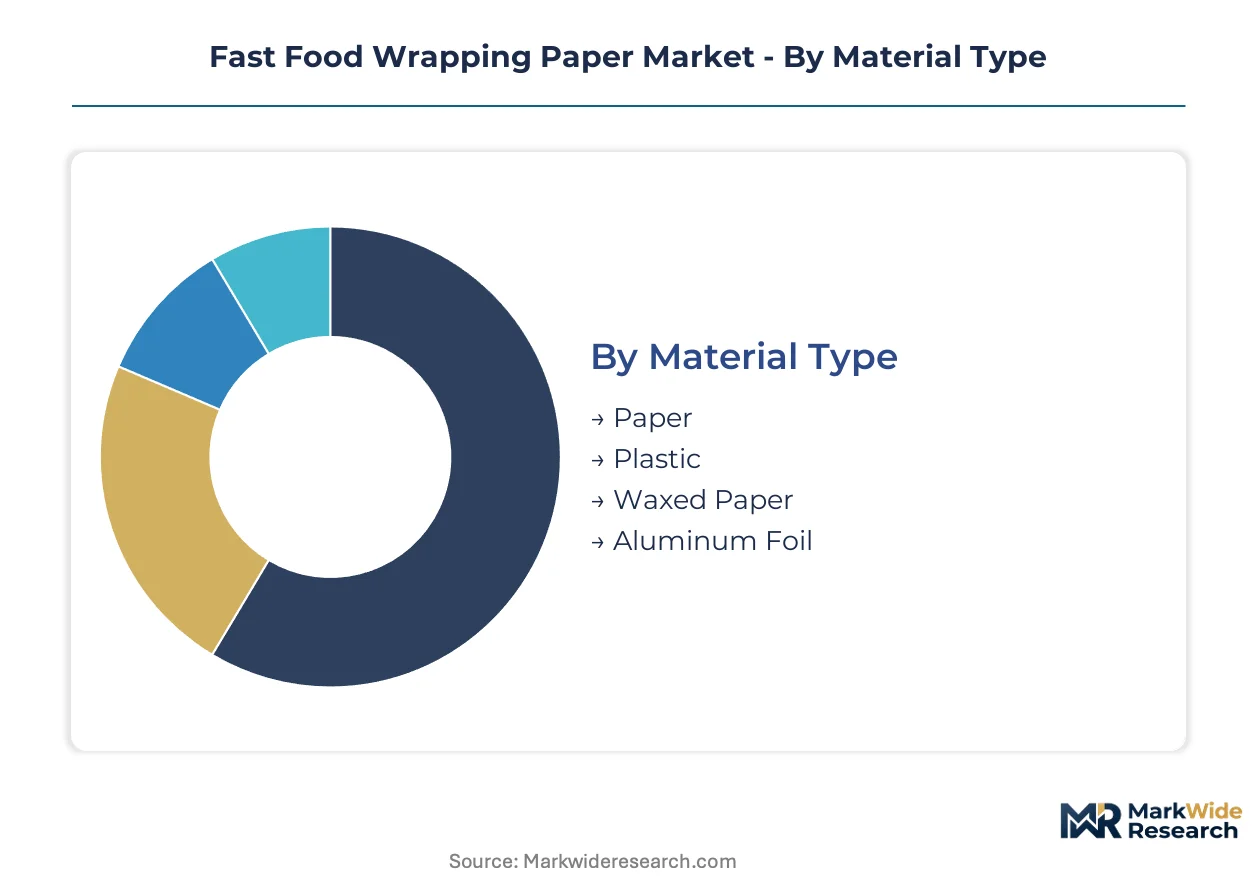
Segmentation in fast food wrapping paper reveals how coating chemistry, end-use channel requirements, and sustainability positioning split procurement budgets across incompatible specification tiers. Material composition and end-user channel together determine barrier performance thresholds and volume contract structures.
Material Type:
Specialty chemical supply for grease-resistant coatings concentrates among German and Japanese formulators, forcing converters to align material strategies with qualified coating house capabilities.
- Paper:Kraft fiber substrates engineered with silicone or aqueous barriers dominate quick-service restaurant procurement. Indonesia and Vietnam pull substantial volume as dine-in and takeaway operations scale store networks across Southeast Asia.
- Waxed Paper:Paraffin-impregnated grades retain entrenched share in legacy burger and sandwich applications where cost sensitivity outweighs compostability requirements. Fixed-price annual contracts expose converters to Nordic softwood pulp cost volatility.
- Plastic:Polypropylene and polyethylene wraps persist in high-moisture applications where fiber barriers fail, though EU Single-Use Plastics Directive compliance costs are compressing volume.
- Aluminum Foil:Laminated foil-paper composites serve hot-hold applications exceeding 85°C where radiant heat retention matters, limited by material cost and recycling infrastructure gaps.
Paper absorbs the bulk of installed capacity; waxed paper is expanding most quickly as regional chains defer sustainability capital expenditure.
End User:
Channel-specific handling requirements and dishwashing infrastructure availability create divergent specification demands that fragment converter customer service models.
- Quick Service Restaurants:Centralized procurement desks at multinational chains enforce 18-month qualification timelines for PFAS-free coating migration and sensory panels. Subscription-based coating services are displacing capital purchase models among mid-size operators.
- Food Trucks:Mobile kitchen operators lack on-site dishwashing infrastructure and generate high SKU velocity with low switching costs. This channel is climbing the fastest as urban food truck permits multiply across North American and European cities.
- Cafés:Premium bakery and coffee chains prioritize presentation value and brand-customized print over pure wrap economics, accepting higher per-unit costs for differentiated consumer touchpoints.
- Catering Services:Event-based volume spikes demand flexible minimum order quantities and rapid turnaround, favoring converters with digital flexo capabilities for short-run customization.
Quick Service Restaurants command the dominant share of contract volume; food trucks are gaining share fastest due to infrastructure constraints and low capital barriers to entry.
Packaging Size:
Equipment line configurations at converting facilities lock in size-specific die-cutting and folding capabilities that shape customer acquisition strategies.
- Medium:Standard sandwich and burger dimensions align with high-velocity quick-service SKUs. This tier captures the steepest expansion trajectory as portion-size standardization reduces inventory complexity.
- Large:Submarine and wrap formats serve diversified menu portfolios at regional chains expanding into bowl and burrito categories.
- Small:Slider and breakfast biscuit applications concentrate in morning-daypart specialists and coffee chain food attachments.
- Extra Large:Family-size and sharing formats remain niche, limited by food waste concerns and inconsistent demand patterns outside promotional windows.
Medium size absorbs the bulk of installed capacity; large formats are expanding most quickly as menu diversification stretches portion specifications.
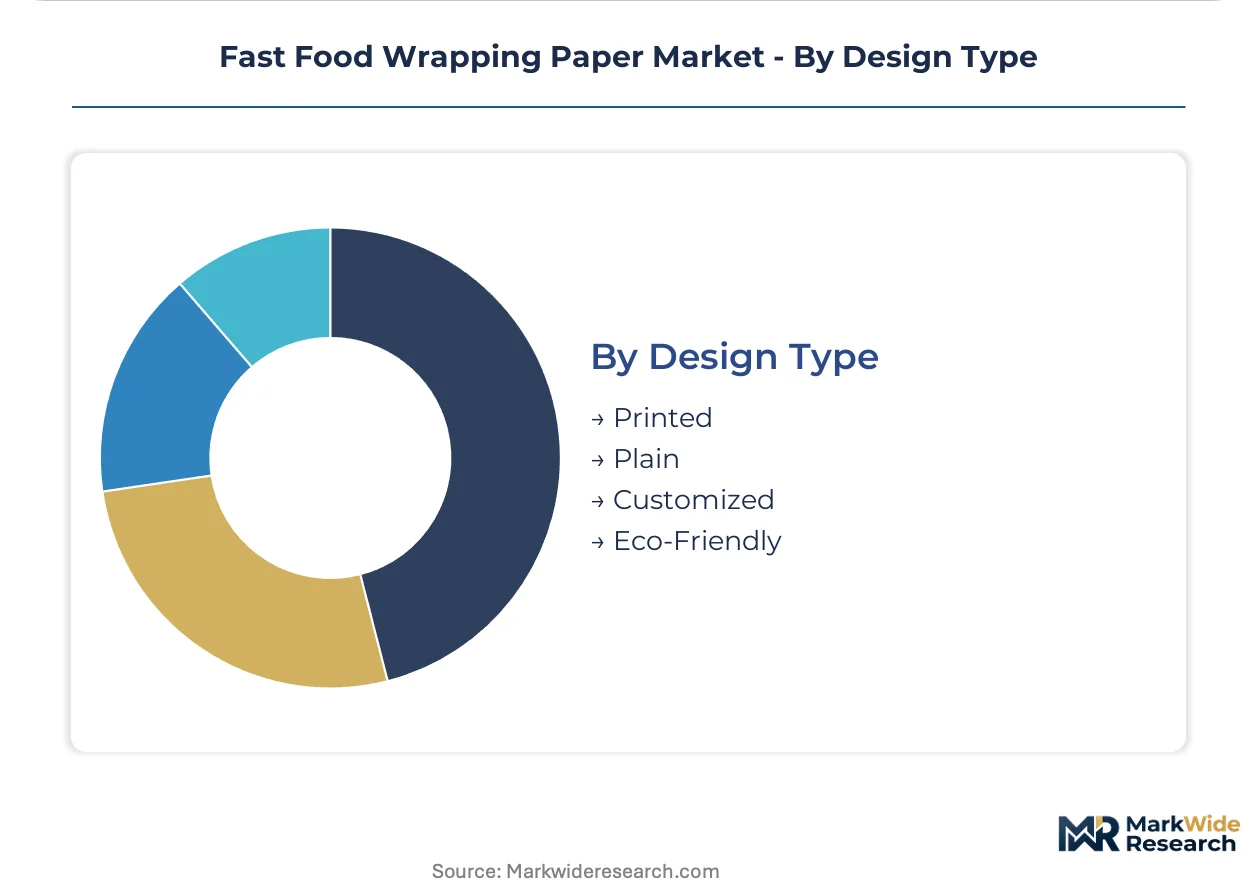
Design Type:
Brand marketing and sustainability functions are fragmenting procurement authority, collapsing traditional specifications into competing aesthetic and certification requirements.
- Printed:Rotogravure and flexo over aqueous barriers enable seasonal limited-time offers with regional customization. Digital print integration is compressing minimum order quantities for mid-tier chains.
- Eco-Friendly:TÜV OK Compost INDUSTRIAL certification and PFAS-free claims capture margin pools as chain-level sustainability commitments harden. REACH Annex XVII restrictions are eliminating fluorochemical options from European food-contact papers.
- Plain:Unprinted kraft grades serve cost-optimized operators and private-label distributors where brand communication occurs through secondary packaging.
- Customized:Bespoke die-cuts and windowed formats for premium positioning concentrate in boutique burger concepts and celebrity chef fast-casual ventures.
Printed designs absorb the bulk of installed capacity; eco-friendly variants are expanding most quickly as regulatory deadlines and consumer preference converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jakarta anchors Southeast Asian demand as quick-service chains expand dine-in and takeaway operations across Indonesia's urban corridors. Fiber-based wrap consumption climbs through centralized distribution hubs serving multinational brands and local operators alike.
United States
Quick-service procurement desks enforce 18-month qualification timelines for PFAS-free coating migration. FDA 21 CFR regulations govern indirect food-contact substances while state-level PFAS prohibitions accelerate reformulation investments. Georgia-Pacific's integrated pulp-to-paper mill networks dominate distribution across the Southeast and Pacific Northwest.
Germany
REACH Annex XVII restrictions eliminate fluorochemical options from European food-contact papers by 2026. The EU F-Gas Regulation phase-down redirects packaging investment toward cellulose-based grease barriers. Specialty chemical formulators in the Rhine-Ruhr industrial cluster concentrate silicone barrier supply for converter qualification cycles.
Indonesia
Local and international fast-food chains scale store networks across Java and Sumatra, pulling kraft-paper barrier volume upward. BIS certification requirements shape import standards for food-contact papers entering from regional suppliers. Surabaya's converting facilities expand aqueous coating capacity to serve centralized quick-service distribution.
Vietnam
Dine-in and takeaway volumes multiply as urban quick-service penetration deepens in Ho Chi Minh City and Hanoi. Exporters pre-certify PFAS-free grades to maintain EU customs clearance velocity amid REACH compliance deadlines. Da Nang's packaging corridor attracts tolling arrangements for mid-tier converters lacking humidity-controlled drying infrastructure.
India
Domestic quick-service expansion drives demand for grease-resistant wraps in Mumbai and Delhi-NCR metro corridors. BIS certification mandates govern local manufacturing and import standards for food-grade papers. Gujarat's paper mills invest in silicone coating lines to capture share from regional burger and sandwich chains.
Fast Food Wrapping Paper Market Vendor Landscape
Capital-heavy integrated paper producers compete with asset-light specialty converters for quick-service supply agreements. Market structure consolidates around three tiers: multinational packaging conglomerates with global converting footprints, regional mills with captive pulp supply, and independent converters dependent on tolling arrangements. Strategic archetypes include barrier technology licensors, subscription-based coating service providers, and vertically integrated fiber-to-wrap operators. Dominant competitive moves encompass M&A to secure aqueous coating capabilities and strategic partnerships to anchor multinational brand supply agreements.
Among Nordic-based packaging conglomerates, Huhtamäki Oyj and Mondi plc occupy positions exemplifying the integrated converter archetype with global qualification relationships. Georgia-Pacific LLC represents the North American pulp-to-paper mill network model. These three entities anchor the competitive structure through distinct geographic and capability positioning rather than overlapping strategic territory.
| Leading Market Players |
|---|
| Berry Global, Inc. |
| Amcor plc |
| Mondi plc |
| Huhtamäki Oyj |
| Sonoco Products Company |
| WestRock Company |
| International Paper Company |
| Graphic Packaging Holding Company |
| Georgia-Pacific LLC |
| Others |
Supply Flow & Price Mechanics
Aqueous coating technology migration is compressing converter economics while concentrating supply relationships around humidity-controlled drying infrastructure in Germany and Japan. This dual squeeze elevates barrier-grade kraft paper premiums and locks mid-tier operators into tolling arrangements with asset-heavy specialists.
Pricing Analysis
Throughput-based subscription contracts anchor pricing for quick-service procurement desks trading capital expenditure for per-meter operational charges. Three-tier pricing structure across premium, standard, and economy levels separates TÜV-certified compostable grades from conventional silicone barriers and legacy waxed paper. Cost compression in standard-tier aqueous coatings is intensifying because Nordic softwood pulp volatility exposes fixed-price annual contracts. Regional burger chains exhibit highest price sensitivity; multinational quick-service brands with centralized sustainability targets accept premium positioning for PFAS-free certification.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese specialty chemical houses controlling silicone barrier formulation. Raw material flows draw from Nordic softwood pulp harvests, Southeast Asian kraft fiber expansion, and Rhine-Ruhr chemical intermediates. Tariff exposure runs through EU-ASEAN trade corridors as Indonesian and Vietnamese converters pre-certify grades for European customs clearance. Distribution runs through multinational packaging conglomerates with integrated converting footprints and regional mills with captive pulp supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PFAS-free coating capacity scarcity props pricing power for qualified converters, constraining volume growth to equipment commissioning timelines rather than demand absorption.
For Market Incumbents: To counter aqueous coating equipment retrofit friction, anchor supply agreements through subscription-based service models that preserve customer balance sheet flexibility. Prioritize backward integration into humidity-controlled drying infrastructure in Vietnam and Indonesia to capture Southeast Asian quick-service expansion. For New Entrants and Emerging Players: Capture food truck channel volume through digital flexo customization capabilities that collapse minimum order quantities for mobile kitchen operators. Penetrate underserved North American urban markets via tolling arrangements with established coating houses rather than greenfield capital deployment. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational packaging conglomerates seeking aqueous barrier capabilities. Five-to-ten-year viability hinges on REACH-compliant coating chemistry portfolios. Monitor state-level PFAS prohibitions in the United States as inflection indicator for accelerated consolidation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Coating Qualification | REACH Annex XVII deadlines force 18-month migration panels at quick-service technical desks. |
| Humidity-Controlled Drying Infrastructure | Asset-heavy investments in Da Nang and Surabaya lock in Southeast Asian tolling relationships. |
| Subscription Service Model Deployment | Per-meter operational charges displace capital purchase models among mid-size regional chains. |
| Digital Flexo Print Integration | Short-run customization collapses minimum order quantities for limited-time menu offers. |
| TÜV Compostability Certification | OK Compost INDUSTRIAL validation captures margin pools as European mandates harden. |
Methodological Framework
Trade databases, regulatory filings, and industry association reports formed the secondary backbone, supplemented by primary interviews with quick-service procurement directors, coating house technical leads, paper mill operations managers, and food truck fleet operators. Bottom-up volume triangulation across material type, end-user channel, and regional production clusters was cross-validated against top-down spend analysis at multinational brand headquarters.
Historical trendline analysis of barrier-grade kraft paper consumption patterns informed projection modeling across the analysis window. Segmentation dimensions included coating chemistry tier, end-user channel infrastructure, and sustainability certification status. CAGRs were derived from curve-fitting approaches applied to qualifying cycle timelines and store network expansion trajectories in Indonesia and Vietnam.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU F-Gas Regulation enforcement intensity and Nordic softwood harvest variability. Forecasts reflect documented assumptions about qualification timeline compression and aqueous coating performance parity thresholds. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Paper Based Consumer Bags Market
Paper & Paperboard Packaging
Commercial Paper Bags Market
Paper & Paperboard Packaging
Global VCI Paper Market
Paper & Paperboard Packaging
Hanging Box Market
Paper & Paperboard Packaging
Release Paper Market
Paper & Paperboard Packaging
Paper Cup Machine Market
Paper & Paperboard Packaging
Paper Coaster Market
Paper & Paperboard Packaging
Kraft Paper Shopping Bag Market
Paper & Paperboard Packaging
North America Paper Cups Market
Paper & Paperboard Packaging
Paper Release Liners Market
Paper & Paperboard Packaging
Paper Canisters Market
Paper & Paperboard Packaging
US Corrugated and Folding Boxboard Market
Paper & Paperboard Packaging
Middle East and Africa Corrugated Box Market
Paper & Paperboard Packaging
Malaysia Corrugated Boxes Market
Paper & Paperboard Packaging
Corrugated Mailers Market
Paper & Paperboard Packaging
Australia Corrugated Board Packaging Market