
 Metal Cans Market | 2026-2036
Metal Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Cans Market Analysis
Multi-source procurement among beverage multinationals is recalibrating how converters secure aluminum rolling supply. Ball Corporation leverages captive metal supply agreements across North American smelter networks. Crown Holdings anchors its position through deep relationships with multinational brewers and soft-drink bottlers. Silgan Holdings differentiates via diversified substrate exposure spanning steel and aluminum formats.
Metal cans are cylindrical containers formed from aluminum alloy, tinplate, or electrolytic chromium-coated steel through drawing, wall-ironing, and necking processes, engineered to provide hermetic sealing, stackability, and infinite recyclability for shelf-stable consumer goods. Aluminum cans lead product type volumes due to lightweighting advantages and established closed-loop recycling infrastructure across OECD markets. Food and beverage end use generates the dominant value pool, while pharmaceutical-grade tinplate demand sustains premium margin niches requiring stringent barrier performance.
The EPA regulates volatile organic compound emissions from can coating operations under Clean Air Act standards, while the EU Green Deal mandates minimum recycled content thresholds for packaging placed on European markets. FDA compliance for food-contact coatings and BIS certification requirements in India shape product formulation and market access protocols. Stakeholders must monitor evolving extended producer responsibility frameworks and alloy cost volatility to align capacity investments with regulatory and raw-material trajectories.
Market Dynamics
The metal cans sector is rebalancing around aluminum supply concentration and circular-economy mandates, with beverage brand owners forcing converters to restructure rolling metal procurement and alloy sourcing strategies.
Growth Catalysts
- EU Green Deal packaging mandates:Minimum recycled content thresholds for packaging placed on European markets are pulling demand toward infinitely recyclable aluminum formats.
- Beverage sector procurement consolidation:Multinational brewers and soft-drink bottlers are consolidating supplier relationships to secure volume commitments and alloy quality consistency.
- Lightweighting technology diffusion:Wall-ironing and necking process improvements are reducing aluminum gauge requirements per can, lowering unit material costs and transportation emissions simultaneously.
Market Restraints
- Aluminum ingot price volatility:London Metal Exchange price swings for primary aluminum directly compress converter margins and destabilize annual contract negotiations.
- Smelter network concentration:North American primary aluminum production remains geographically concentrated, exposing can sheet supply to regional energy cost shocks and logistics bottlenecks.
- Polymer bottle substitution:PET packaging continues eroding metal can share in still water and non-carbonated beverage segments where barrier requirements are less stringent.
Strategic Opportunities
- India BIS certification expansion:Food-contact coating standards are tightening, creating premium positioning for converters with pre-certified pharmaceutical-grade tinplate capabilities.
- Two-piece aluminum aerosol convergence:Monobloc extrusion technology is crossing over from personal care into food-grade pressurized dispensing applications.
- Extended producer responsibility frameworks:Deposit-return schemes in Brazil and EU member states are generating closed-loop aluminum flows that captive recycler-converter networks can monetize.
Industry Challenges
- Coating chemist talent scarcity:Formulation expertise for BPA-non-intent epoxy alternatives is concentrated among a narrow cohort of specialty chemical suppliers and their trained technical staff.
- Legacy steel line conversion capex:Tinplate food can manufacturers face capital intensity in retrofitting drawing presses for aluminum alloy compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Cans Market |
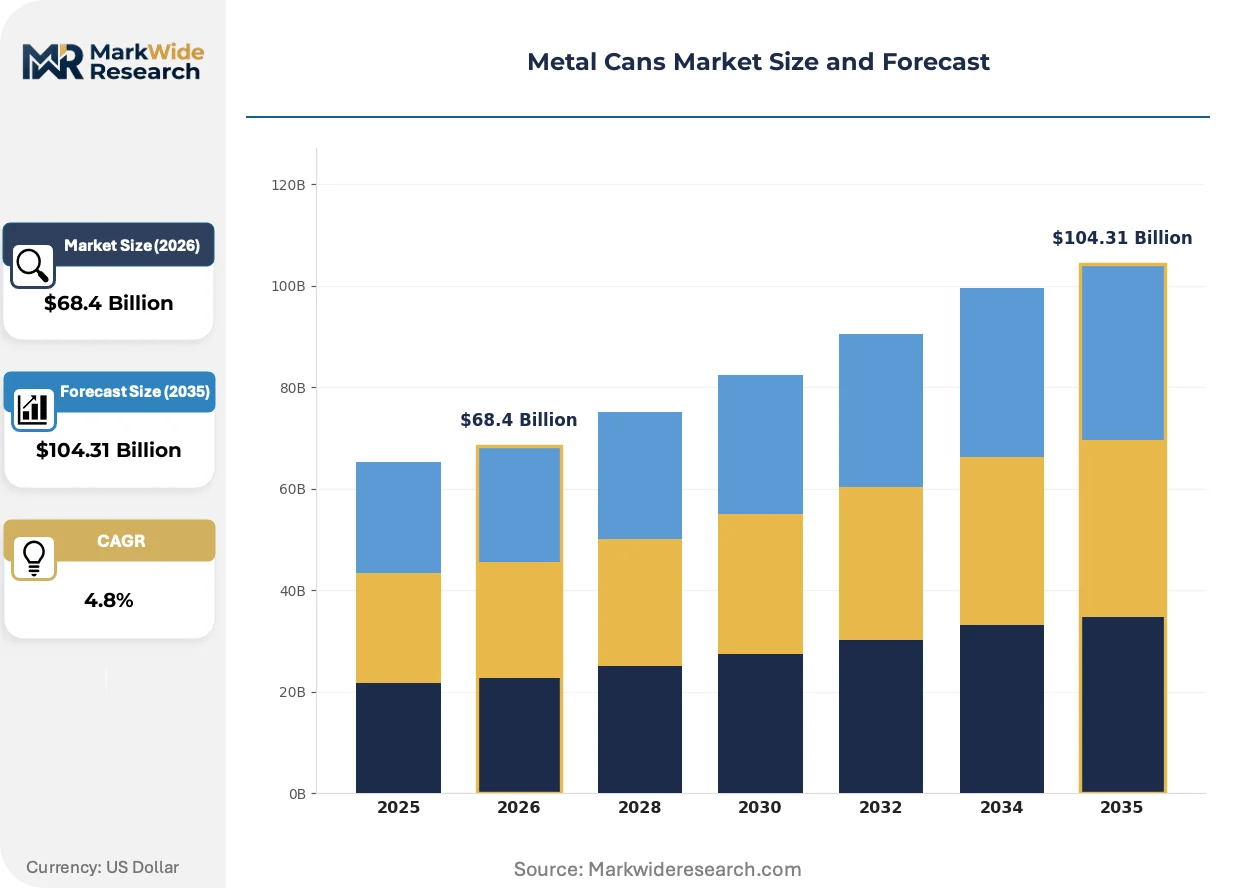
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $104.31 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Cans, Steel Cans, Tinplate Cans, Others End Use Industry: Food & Beverage, Personal Care, Household Products, Pharmaceuticals Capacity: Small, Medium, Large, Extra Large Distribution Channel: Online Retail, Supermarkets, Distributors, Wholesale |
| Companies Covered | Ball Corporation, Crown Holdings, Inc., Ardagh Group, Silgan Holdings Inc., CAN-PACK Group, CPMC Holdings Limited, CCL Industries, Kian Joo Group, Toyo Seikan Group Holdings Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Cans Market Emerging Trajectories
Digital printing and smart packaging integration are compressing design-to-shelf timelines, while regulatory chemistry restrictions are forcing coating reformulation investments across OECD manufacturing footprints.
Digital sleeve printing technology is modularizing how beverage brands execute limited-edition campaigns and regional customization. Mid-tier craft brewers are adopting this capability to compress minimum order quantities from millions to tens of thousands. The technology is modularizing traditional converter economics by decoupling volume scale from graphic flexibility.
The EPA Clean Air Act volatile organic compound standards are tightening emissions thresholds for can coating cure ovens and solvent-based application systems. North American coating facilities are retrofitting thermal oxidizers and shifting toward waterborne and UV-curable formulations. Food-contact coating compliance timelines are compressing as state-level disclosure requirements in California add parallel obligations to federal FDA oversight.
Direct-to-retailer procurement contracts are displacing traditional distributor-mediated aluminum can purchasing in the craft beverage segment. Smaller brewers are negotiating directly with regional converters for truckload quantities, bypassing beverage distribution cooperatives. This pattern is most visible in the United States Pacific Northwest and Mountain West states where microbrewery density supports converter direct-sales infrastructure investment.
Metal Cans Market Segmentation
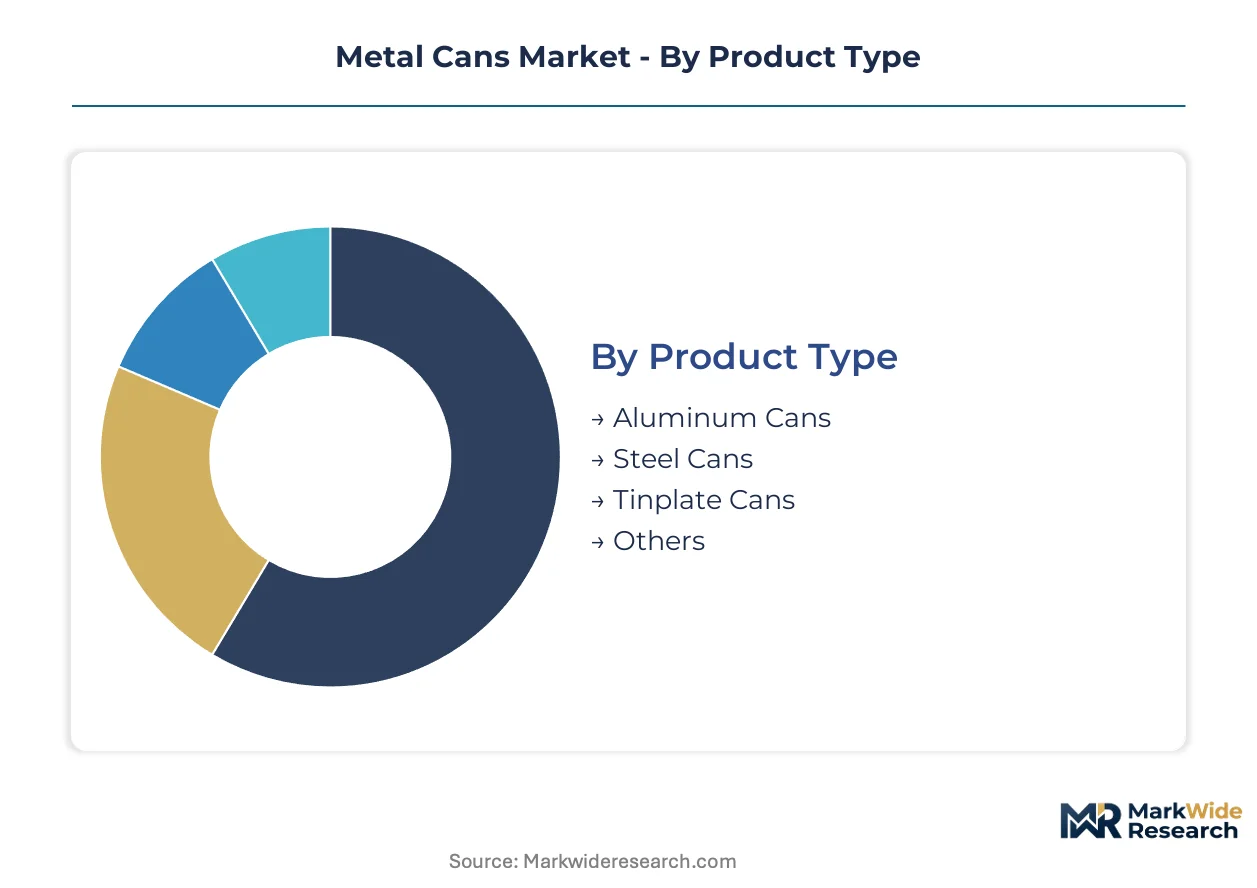
Metal can converters configure production lines around substrate alloy specifications and end-use barrier requirements. Segmentation reveals where aluminum gauge optimization diverges from tinplate corrosion resistance, and which capacity formats align with beverage scale versus pharmaceutical batch sizes.
Product Type:
Aluminum formats dominate standalone beverage applications where lightweighting drives logistics economics, while steel and tinplate variants embed into food preservation systems requiring thermal processing compatibility.
- Aluminum Cans:Drawn and wall-ironed from 3104-H19 alloy sheet with reduced gauge profiles enabling single-serve beverage packaging. Brazil's CAN-PACK Group anchors regional production scale as EU Green Deal recycled content mandates pull procurement toward closed-loop aluminum formats.
- Steel Cans:Manufactured from tinplate or electrolytic chromium-coated steel through three-piece seaming for processed foods requiring retort sterilization. North American food processors specify tinplate for acidic contents where aluminum corrosion resistance proves insufficient.
- Tinplate Cans:Cold-rolled low-carbon steel with electrolytic tin coating delivers hermetic sealing for shelf-stable fish, meat, and vegetable preserves. India BIS certification requirements for food-contact coatings create premium positioning for pharmaceutical-grade tinplate capabilities.
- Others:Composite and hybrid substrate formats including aluminum-steel laminates for niche aerosol and specialty chemical applications.
Aluminum Cans lead volumes today; Tinplate Cans are gaining share fastest in pharmaceutical-grade niches.
End Use Industry:
Segment economics split between high-volume beverage procurement with thin margins and specialized pharmaceutical packaging commanding formulation certification premiums.
- Food & Beverage:Carbonated soft drinks, beer, and ready-to-drink beverages consume two-piece aluminum draw-redraw capacity. Craft brewers in the US Pacific Northwest negotiate direct procurement contracts with regional converters, bypassing traditional distribution cooperatives.
- Personal Care:Monobloc aluminum aerosols for deodorants and hair sprays utilize extrusion forming rather than deep drawing. European REACH compliance timelines for propellant and coating chemistry constrain formulation flexibility.
- Household Products:Steel aerosols for insecticides and cleaning solvents require internal epoxy phenolic lining systems. EPA Clean Air Act VOC thresholds are forcing thermal oxidizer retrofits at North American coating facilities serving this segment.
- Pharmaceuticals:Tinplate and aluminum formats for metered-dose inhalers and topical preparations demand FDA food-contact coating validation. CDSCO and BIS parallel certification requirements in India extend approval timelines for multinational suppliers.
Food & Beverage generates absolute volume; Pharmaceuticals delivers the steepest margin expansion trajectory.
Capacity:
Format sizing aligns with consumption occasion patterns and retail channel requirements, from single-serve convenience to institutional foodservice scale.
- Small:Sub-150ml formats for energy shots, pharmaceutical unit doses, and sample-size personal care products. Digital printing technology enables craft brewers to compress minimum order quantities for limited-edition small-format campaigns.
- Medium:Standard 330ml and 355ml beverage cans represent the volume core of converter economics. Ball Corporation secures captive metal supply agreements across North American smelter networks for this capacity tier.
- Large:473ml and 500ml formats for craft beer and premium beverages. Crown Holdings anchors positioning through multinational brewer relationships specifying alloy quality consistency at this scale.
- Extra Large:Foodservice and institutional formats exceeding 1 liter for processed foods and cooking oils. Silgan Holdings differentiates via diversified substrate exposure spanning steel and aluminum in this capacity range.
Medium capacity commands production scale today; Small formats are expanding most quickly through craft beverage customization.
Distribution Channel:
Channel structure determines converter customer concentration and contract pricing mechanics, from direct procurement to distributor-mediated aggregation.
- Online Retail:E-commerce direct-to-consumer fulfillment for craft beverages and subscription food boxes. Amazon and specialized beverage platforms require damage-resistant packaging with graphic differentiation.
- Supermarkets:Mass retail shelf placement drives standardized pallet configurations and high-speed filling line compatibility. Walmart and Carrefour procurement teams negotiate annual volume commitments with tier-one converters.
- Distributors:Beverage distribution cooperatives aggregate fragmented craft brewery demand into truckload quantities. This channel is losing share to direct converter relationships in microbrewery-dense US regions.
- Wholesale:Foodservice and institutional supply chains for restaurants, catering, and military procurement. Sysco and US Foods specify steel can formats for thermal processing compatibility in large-batch food preparation.
Supermarkets anchor volume throughput today; Online Retail is climbing the fastest through direct-to-consumer beverage subscription growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's CAN-PACK Group anchors regional production scale as beverage brand owners expand aluminum can procurement amid tightening circular-economy mandates. Demand concentrates across five strategic markets where regulatory frameworks and industrial clustering reshape converter economics.
United States
Craft brewers in the Pacific Northwest and Mountain West states negotiate direct procurement contracts with regional converters, bypassing traditional beverage distribution cooperatives. EPA Clean Air Act volatile organic compound standards force thermal oxidizer retrofits at coating facilities. Ball Corporation leverages captive metal supply agreements across North American smelter networks concentrated in the Southeast and Midwest.
Germany
Beverage multinationals consolidate supplier relationships to secure volume commitments and alloy quality consistency for premium export markets. EU Green Deal minimum recycled content thresholds pull procurement toward closed-loop aluminum formats. The Ruhr industrial corridor hosts specialized coating chemist talent pools concentrated among epoxy alternative formulators serving pharmaceutical-grade tinplate niches.
India
Food-contact coating standards tighten under BIS certification expansion, creating premium positioning for converters with pre-certified pharmaceutical-grade capabilities. CDSCO parallel certification requirements extend approval timelines for multinational suppliers. Maharashtra and Gujarat industrial zones concentrate tinplate conversion capacity serving domestic processed food processors and aerosol manufacturers.
Brazil
Deposit-return schemes generate closed-loop aluminum flows that captive recycler-converter networks monetize across the beverage supply chain. ANVISA pharmaceutical packaging regulations align with FDA validation protocols for metered-dose inhaler formats. São Paulo state anchors CAN-PACK Group's regional production scale with integrated smelter-to-can sheet vertical coordination.
Japan
Monobloc aluminum aerosol extrusion technology crosses over from personal care into food-grade pressurized dispensing applications under METI industrial guidance. JIS standards for food-contact coatings exceed baseline OECD requirements, filtering market access for foreign converters. The Kanto region around Tokyo concentrates precision aerosol manufacturing for cosmetic and pharmaceutical export markets.
Metal Cans Market Vendor Landscape
Global majors compete with regional champions across aluminum rolling supply and coating formulation capabilities. The vendor base stratifies into three tiers: integrated multinationals with captive metal agreements, diversified substrate specialists spanning steel and aluminum, and national champions serving protected domestic markets. Strategic archetypes include alloy-integrated converters, coating technology licensors, and region-anchored volume players. Competitive moves center on backward integration into smelter networks and portfolio diversification across beverage, food, and pharmaceutical end uses.
Among North American integrated players, Ball Corporation and Crown Holdings occupy positions as scale-driven converters with multinational brewer relationships, while Silgan Holdings exemplifies the diversified substrate archetype through steel-aluminum format flexibility. CAN-PACK Group anchors the regional champion model with Brazil-centric production scale and EU market penetration.
| Leading Market Players |
|---|
| Ball Corporation |
| Crown Holdings, Inc. |
| Ardagh Group |
| Silgan Holdings Inc. |
| CAN-PACK Group |
| CPMC Holdings Limited |
| CCL Industries |
| Kian Joo Group |
| Toyo Seikan Group Holdings Ltd. |
| Others |
Supply Flow & Price Mechanics
Captive metal supply agreements across North American smelter networks anchor both converter supply security and pricing power, as Ball Corporation's backward integration into primary aluminum rolling insulates against London Metal Exchange volatility while compressing competitor margins.
Pricing Analysis
Input-cost pass-through from primary aluminum ingot movements dominates converter pricing structures, with London Metal Exchange price swings compressing margins on non-integrated players. Three-tier pricing structure across premium pharmaceutical-grade tinplate, standard beverage aluminum, and economy steel formats reflects certification grade and volume scale differentiation. Pricing pressure stems from PET bottle substitution in still water segments, eroding metal can share. Craft brewers in the US Pacific Northwest exhibit highest price sensitivity, negotiating direct truckload contracts with regional converters.
Supply Chain Analysis
Dual-sourcing requirements from multinational beverage brand owners mandate multi-supplier qualification across North American, Brazilian, and German aluminum rolling capacity. Raw material dependencies center on 3104-H19 alloy sheet, electrolytic tinplate, and epoxy phenolic coating chemistries. Supply chain risk concentrates in single-source vulnerability for BPA-non-intent coating formulations, where specialty chemical supplier concentration limits formulation flexibility. Distribution runs through direct-to-retailer procurement contracts displacing traditional beverage distribution cooperatives in microbrewery-dense regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's deposit-return scheme economics against India's tightening BIS certification timelines create a geographic-arbitrage play, with converters capturing closed-loop aluminum value in São Paulo state while premium tinplate margins expand in Maharashtra industrial zones.
For Market Incumbents: Acquire coating formulation expertise by recruiting chemist talent pools from Ruhr industrial corridor epoxy alternative specialists, defending against PET bottle substitution threat through lightweighting R&D investment in wall-ironing gauge reduction. Backward integration into captive smelter networks remains the priority lever for margin defense against London Metal Exchange volatility. For New Entrants and Emerging Players: Capture pharmaceutical-grade tinplate white space in India by securing pre-certified CDSCO capabilities before multinational approval timelines extend, targeting Maharashtra and Gujarat industrial zones with BIS-compliant food-contact coating positioning. Direct-to-craft-brewer channel control in US Mountain West states offers the most penetrable entry vector. For Investors and Strategic Acquirers: Roll-up economics work for regional converter platforms because deposit-return scheme infrastructure creates captive recycler-converter network moats in Brazil and EU member states. Long-term viability hinges on aluminum circular-economy asset positioning. Watch EU Green Deal recycled content threshold enforcement as the signal to watch for inflection in premium aluminum procurement premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Smelter Networks | Ball Corporation's captive metal agreements insulate margin compression from London Metal Exchange volatility. |
| Pharmaceutical-Grade Certification Investment | BIS and CDSCO pre-certification in India creates premium positioning for tinplate barrier performance applications. |
| Lightweighting Technology Deployment | Wall-ironing gauge reduction lowers unit material costs for beverage converters competing against PET substitution. |
| Direct-to-Retailer Channel Expansion | Craft brewer procurement bypasses distribution cooperatives in US Pacific Northwest microbrewery clusters. |
| Closed-Loop Recycling Infrastructure | Brazilian deposit-return schemes monetize aluminum flows through captive recycler-converter vertical coordination. |
Methodological Framework
Multiple input streams — primary interviews with beverage procurement directors, coating facility plant managers, and aluminum rolling supply specialists, alongside secondary validation through EPA Clean Air Act enforcement records, EU Green Deal regulatory filings, and London Metal Exchange price data — were reconciled through bottom-up and top-down triangulation.
Cross-referencing historical volume trajectories against panel input from converter capacity planners and brand owner procurement strategists shaped the analytical framework across the analysis window. Segmentation dimensions modeled include substrate alloy type, end-use industry barrier requirements, capacity format sizing, and distribution channel structure. CAGRs were derived from alloy cost trajectory assumptions and regulatory mandate implementation schedules.
Aluminum ingot price volatility, EU recycled content threshold enforcement timing, and India BIS certification expansion pace are the dominant revision risks to modeled outputs. Deviation in London Metal Exchange primary aluminum pricing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Tinplate Packaging Market
Metal Packaging
Metal Food Cans Market
Metal Packaging
Europe Metal Closures Market
Metal Packaging
Asia Pacific Metal Cans Market
Metal Packaging
Vietnam Metal Packaging Market
Metal Packaging
Italy Metal Packaging Market
Metal Packaging
Egypt Metal Packaging Market
Metal Packaging
Bi-Metal Cans Market
Metal Packaging
Brass Foils Market
Metal Packaging
Aluminum Foil Market
Metal Packaging
United Arab Emirates Metal Packaging Market
Metal Packaging
United Kingdom Metal Packaging Market
Metal Packaging
Food Tins and Drink Cans Market
Metal Packaging
South Africa Metal Packaging Market
Metal Packaging
Honeycomb Aluminum Foil Market
Metal Packaging
Germany Metal Packaging Market