
 Converter Aluminum Foil Market | 2026-2036
Converter Aluminum Foil Market Size, Share, and Industry Trends Forecast 2026-2036
Converter Aluminum Foil Market Outlook
Chinese rolling mill capacity is restructuring regional supply flows for converter aluminum foil. Symetal Aluminium Foil Industry leverages integrated smelter-to-foil operations in Southeastern Europe. All Foils, Inc. sustains specialized thin-gauge production for North American pharmaceutical clients. Raviraj Foils Limited anchors domestic Indian supply through backward integration into cold rolling.
Converter aluminum foil denotes cold-rolled aluminum sheet between 0.006 mm and 0.2 mm thickness, annealed to achieve dead-fold properties and barrier performance against moisture, oxygen, and light. Manufacturers produce it through tandem rolling followed by double-reduction to serve flexible packaging, pharmaceutical blister packs, and thermal insulation applications. Laminated foil captures expanding margin pools as multilayer barrier requirements intensify across food and pharmaceutical sectors. Flexible foil leads volume throughput but faces substitution pressure from metallized films in snack packaging. Heavy gauge segments occupy stable industrial niches in HVAC and construction insulation where structural rigidity outweighs weight minimization priorities.
FDA enforces contact-substance compliance for pharmaceutical-grade converter foil under 21 CFR regulations, while EMA's MDR framework elevates traceability requirements across European medical packaging supply chains. India's BIS certification mandates specific alloy compositions and gauge tolerances for domestic converter foil sales. Stakeholders must monitor evolving Extended Producer Responsibility frameworks in the EU and India, as recycling-content thresholds and carbon-border adjustments reshape raw material sourcing economics and regional competitiveness.
Market Dynamics
Pharmaceutical packaging specifications are tightening across multiple jurisdictions, forcing converter foil producers to recalibrate alloy purity and traceability systems while absorbing certification costs that smaller mills cannot shoulder.
Growth Catalysts
- EMA MDR traceability mandates:European medical device regulations now require lot-level tracking through packaging materials, elevating demand for certified pharmaceutical-grade foil with embedded serialization compatibility.
- India's western manufacturing corridor:Cold rolling and foil conversion capacity is clustering along the Mumbai-Ahmedabad industrial belt, creating density economies that attract multinational pharmaceutical packaging tenders.
- Blister pack barrier specifications:Moisture and oxygen transmission rate requirements for generic drug exports are tightening, pulling ultra-thin gauge foil into standard pharmaceutical workflows.
Market Restraints
- Primary aluminum price volatility:Converter foil margins compress when LME aluminum spikes, as long-term pharmaceutical supply contracts rarely include full pass-through clauses.
- Rolling mill concentration in China:Regional supply flows depend on a narrowing set of integrated producers, exposing downstream converters to allocation risk during energy rationing periods.
- Metallized film substitution:Snack and confectionery segments are migrating to vacuum-metallized polymer films for cost and weight advantages in non-barrier-critical applications.
Strategic Opportunities
- Extended Producer Responsibility frameworks:EU recycling-content thresholds and carbon-border adjustments are creating first-mover advantages for converters with verified post-consumer aluminum sourcing.
- Southeast Asian pharmaceutical growth:Vietnam and Indonesia are expanding domestic generic drug manufacturing, opening import substitution opportunities for foil suppliers with ASEAN certification.
- Digital watermark integration:Covert authentication features embedded during rolling are enabling premium pricing for anti-counterfeiting pharmaceutical packaging contracts.
Industry Challenges
- REACH compliance documentation:European chemical safety data requirements demand extensive alloy constituent testing, extending certification timelines for new product qualifications.
- Double-reduction equipment scarcity:Tandem rolling mills capable of sub-0.01 mm gauge production face 18-24 month lead times, constraining capacity expansion for thin-gauge pharmaceutical grades.
- Legacy ERP integration:Lot traceability systems required by FDA 21 CFR regulations often conflict with existing mill scheduling software, forcing expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Converter Aluminum Foil Market |
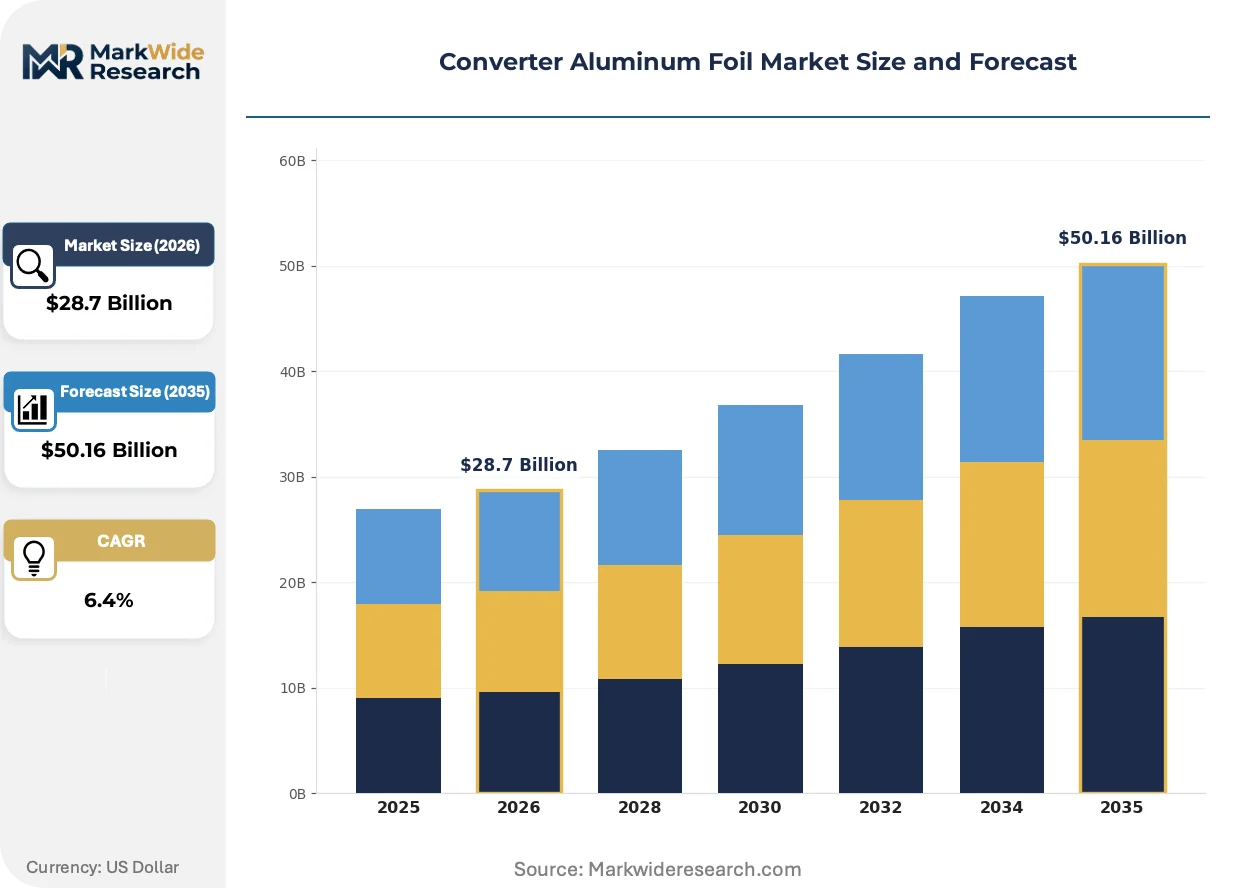
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $50.16 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Foil, Heavy Duty Foil, Laminated Foil, Foil Sheets End Use: Food Packaging, Pharmaceutical Packaging, Industrial Applications, Insulation Thickness: Thin Gauge, Medium Gauge, Heavy Gauge, Ultra-Thin Coating Type: Plain Foil, Coated Foil, Printed Foil, Embossed Foil |
| Companies Covered | Alufoil Products Pvt. Ltd, Amco India Ltd, Nadco Tapes & Labels, Inc., Myra Foils, Raviraj Foils Limited, Aluminium Foil Converters Pvt. Ltd, Symetal Aluminium Foil Industry, All Foils, Inc., Bright Packaging Industry Berhad, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Converter Aluminum Foil Market Strategic Shifts
Active material science and regulatory engineering are converging to redefine converter foil performance benchmarks across pharmaceutical and food barrier applications.
Atomic layer deposition (ALD) barrier coatings are rewriting the competitive map for ultra-thin pharmaceutical foil. ALD applies nanometer-scale ceramic films directly onto aluminum surfaces, enabling sub-0.006 mm gauges to achieve moisture transmission rates previously requiring twice the metal thickness. European blister pack manufacturers are qualifying ALD-treated foil for moisture-sensitive biologics, compressing material costs per thousand doses while maintaining USP <671> compliance.
REACH substance restrictions are tightening the acceptable impurity profile for converter foil destined for European medical packaging. ECHA's candidate list expansions now cover specific alloy additives used in conventional rolling lubricants, forcing mills to reformulate process chemistry. German and Swiss pharmaceutical packaging converters are demanding certified REACH-compliant foil streams, segmenting supplier bases between Europe-qualified and general-industrial grades.
Consolidated procurement by generic drug multinationals is compressing supplier bases and elongating contract durations. Large pharmaceutical manufacturers are reducing their qualified foil vendors from six to three per region, favoring integrated producers with captive smelter supply and in-house laboratory testing. This concentration is most visible in North American and Western European markets, where three-year supply agreements with fixed volume tiers are displacing spot-market purchasing for standard blister pack specifications.
Converter Aluminum Foil Market Segmentation
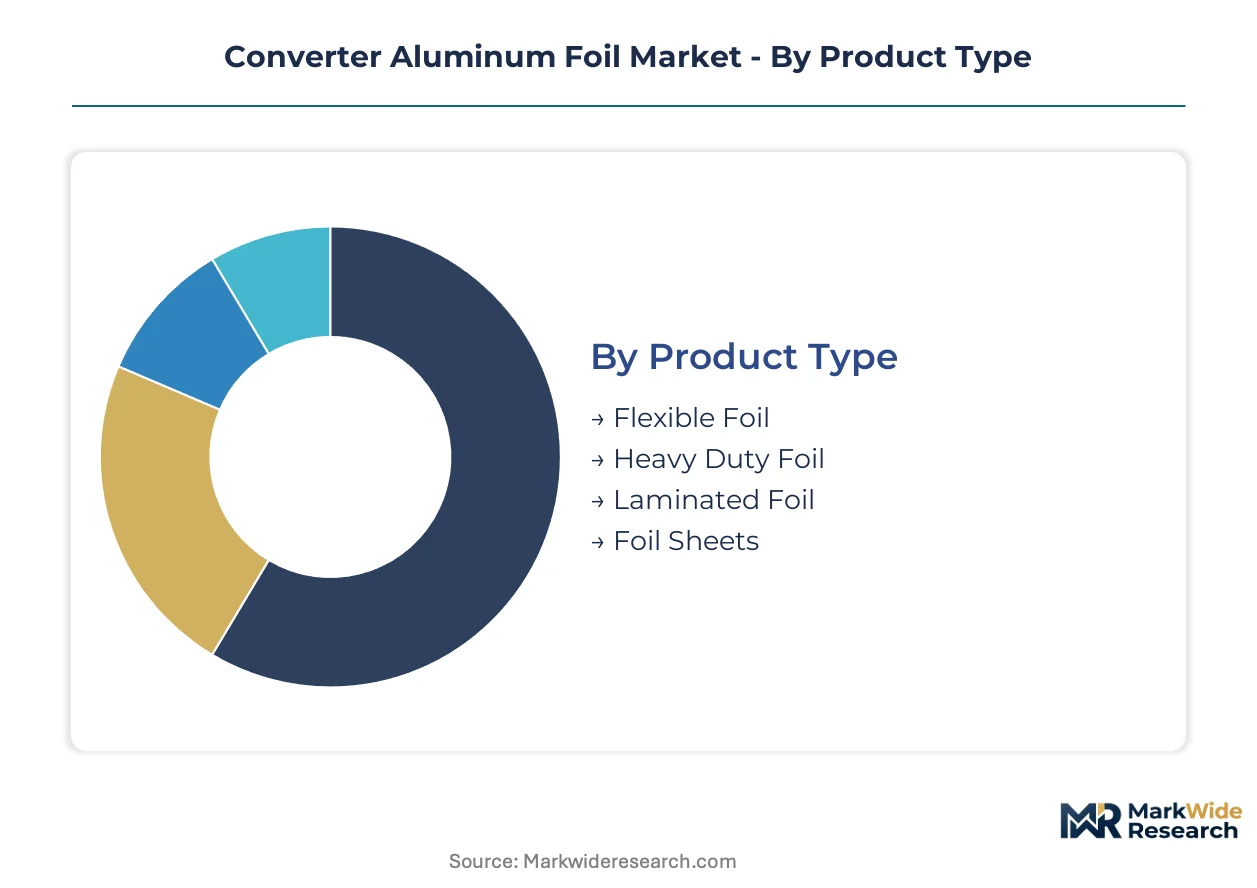
Converter aluminum foil segmentation reflects divergent technical requirements across barrier-critical pharmaceutical workflows and cost-sensitive food packaging. Thickness specifications and coating technologies determine alloy selection, rolling protocols, and downstream lamination compatibility.
Product Type:
Volume throughput concentrates in standardized gauges, while premium margins accrue to specialized barrier constructions.
- Flexible Foil:Cold-rolled aluminum between 0.006 mm and 0.05 mm, annealed for dead-fold properties in blister packs and pouch laminations. Demand clusters in India's western manufacturing corridor for generic drug exports facing tightened moisture transmission specifications. Primary aluminum price volatility compresses margins during LME spikes.
- Laminated Foil:Multilayer constructions combining aluminum with polymer films or paper substrates via adhesive or extrusion lamination. European pharmaceutical packaging converters prioritize REACH-compliant laminated structures for biologics requiring extended shelf stability. ALD barrier coatings are enabling sub-0.006 mm metal layers in next-generation laminations.
- Heavy Duty Foil:Gauges above 0.1 mm serving industrial thermal insulation and structural HVAC applications.
- Foil Sheets:Pre-cut formats for foodservice and retail consumer segments.
Today's leader: Laminated Foil. Tomorrow's challenger: Flexible Foil with ALD enhancement.
End Use:
Regulatory stringency separates pharmaceutical qualification requirements from commodity food packaging economics.
- Pharmaceutical Packaging:Blister packs, strip packs, and cold-form foils governed by FDA 21 CFR contact-substance rules and EMA MDR traceability mandates. Lot-level serialization compatibility now filters supplier selection in North American and Western European markets. Consolidated procurement by generic drug multinationals has reduced qualified vendors per region from six to three.
- Food Packaging:Flexible pouches, lidding, and wrap applications where metallized films are displacing foil in snack and confectionery segments. Vacuum-metallized polymer alternatives capture cost and weight advantages in non-barrier-critical applications.
- Industrial Applications:Cable wrapping, capacitors, and heat exchanger components.
- Insulation:Building and HVAC thermal barriers where structural rigidity outweighs weight minimization.
Pharmaceutical Packaging commands the steepest expansion trajectory. Food Packaging faces substitution pressure.
Thickness:
Gauge selection balances material cost against barrier performance thresholds.
- Ultra-Thin:Sub-0.006 mm foils enabled by atomic layer deposition ceramic coatings, achieving moisture transmission rates previously requiring double the metal thickness. European blister pack manufacturers are qualifying ALD-treated ultra-thin gauges for moisture-sensitive biologics under USP standards.
- Thin Gauge:0.006 mm to 0.02 mm standard for pharmaceutical blister packs, now pulled into generic drug workflows by tightening oxygen and moisture specifications.
- Medium Gauge:0.02 mm to 0.1 mm for general flexible packaging and lidding applications.
- Heavy Gauge:Above 0.1 mm for industrial insulation and structural applications.
Ultra-Thin is climbing the fastest. Thin Gauge maintains volume dominance.
Coating Type:
Surface modification determines printability, heat-seal compatibility, and corrosion resistance.
- Coated Foil:Heat-seal lacquers and primers applied via roll coating for pharmaceutical lidding and food tray applications. REACH compliance documentation now extends to coating chemistry, extending certification timelines for European market entry.
- Printed Foil:Rotogravure or flexographic decoration for branded pharmaceutical and consumer packaging. Digital watermark integration during printing enables covert authentication features for anti-counterfeiting contracts.
- Plain Foil:Unmodified surfaces for secondary lamination or industrial applications.
- Embossed Foil:Textured surfaces for aesthetic differentiation and structural rigidity in foodservice.
Coated Foil leads pharmaceutical qualification. Printed Foil is gaining share fastest through security feature integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands rolling mill capacity that reshapes trade flows, while India's western corridor concentrates pharmaceutical foil conversion. Germany and Switzerland enforce the strictest pharmaceutical-grade specifications. The United States maintains specialized thin-gauge production for domestic drug packaging.
China
Integrated smelter-to-foil operations dominate supply, with energy rationing periodically constraining allocation to downstream converters. NMPA pharmaceutical contact-substance rules align with international standards but add documentation layers for export certification. Zhengzhou and Shandong industrial clusters host tandem rolling capacity that serves both domestic flexible packaging and export pharmaceutical grades.
India
Generic drug export growth pulls ultra-thin gauge foil into standard blister pack workflows at accelerating rates. BIS certification mandates specific alloy compositions and gauge tolerances for domestic sales, filtering qualified suppliers. The Mumbai-Ahmedabad manufacturing corridor clusters cold rolling and conversion capacity, attracting multinational pharmaceutical packaging tenders through density economies.
Germany
EMA MDR traceability mandates elevate lot-level tracking requirements through packaging materials, favoring certified pharmaceutical-grade suppliers with embedded serialization systems. REACH compliance documentation demands extensive alloy constituent testing, extending certification timelines for new product qualifications. The Rhine-Ruhr industrial region maintains specialized laminating capacity for biologics requiring extended shelf stability.
United States
FDA 21 CFR contact-substance regulations enforce strict purity standards for pharmaceutical-grade foil, with lot traceability systems filtering supplier selection. Consolidated procurement by generic drug multinationals has reduced qualified vendors per region from six to three, elongating contract durations. The Midwest and Southeast host thin-gauge specialists serving North American pharmaceutical clients with captive laboratory testing.
Switzerland
Swissmedic pharmaceutical packaging requirements exceed baseline EU standards, creating a premium tier for ultra-high-purity foil with full alloy traceability. CSRD sustainability reporting obligations extend to packaging material supply chains, favoring converters with verified post-consumer aluminum sourcing. Basel and Zurich pharmaceutical clusters demand REACH-compliant foil streams with embedded digital watermark authentication for anti-counterfeiting applications.
Converter Aluminum Foil Market Competitive Environment
Chinese producers anchor the scale-driven tier; European specialists hold the premium certification tier. The vendor base separates between integrated mills with captive smelter supply and independent converters sourcing primary metal on spot markets. Three archetypes dominate: vertically integrated multinationals, regional qualification specialists, and niche thin-gauge operators. Competitive moves center on backward integration into cold rolling and strategic partnerships for ALD barrier coating access.
Among Indian fabricators, Raviraj Foils Limited and Alufoil Products Pvt. Ltd occupy positions within the domestic supply tier, with the former representing backward-integrated models and the latter exemplifying conversion-focused operations. Symetal Aluminium Foil Industry anchors Southeastern European supply through integrated smelter-to-foil structures. All Foils, Inc. sits within the North American specialist tier. These named entities illustrate archetype diversity rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Alufoil Products Pvt. Ltd |
| Amco India Ltd |
| Nadco Tapes & Labels, Inc. |
| Myra Foils |
| Raviraj Foils Limited |
| Aluminium Foil Converters Pvt. Ltd |
| Symetal Aluminium Foil Industry |
| All Foils, Inc. |
| Bright Packaging Industry Berhad |
| Others |
Value Chain & Pricing Dynamics
Consolidated procurement by generic drug multinationals now dictates three-year contract structures with fixed volume tiers, compressing spot-market liquidity and anchoring pharmaceutical-grade foil pricing to certification premiums rather than raw metal volatility.
Pricing Analysis
Capacity additions in China's Zhengzhou and Shandong clusters are reshaping price floors for standard flexible foil grades, while European REACH-compliant material commands certification premiums. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade levels separates lot-traceable EMA MDR-compliant foil from general-purpose output. Cost compression in thin-gauge pharmaceutical segments is intensifying because double-reduction equipment scarcity constrains qualified supply expansion. Generic drug exporters in India exhibit the highest price sensitivity, whereas Swiss biologics manufacturers accept premium positioning for full alloy traceability.
Supply Chain Analysis
Dual-sourcing requirements mandated by FDA 21 CFR and EMA MDR traceability rules force pharmaceutical packaging converters to qualify multiple mills per region, fragmenting volume concentration. Primary aluminum supply draws from Chinese integrated smelters, Indian captive producers, and Middle Eastern export-oriented capacity. Rolling lubricant chemistry and ceramic ALD coating precursors constitute critical input dependencies. Single-source vulnerability concentrates in sub-0.01 mm gauge tandem rolling mills facing 18-24 month equipment lead times. Distribution runs through regional laminating hubs in Germany's Rhine-Ruhr, India's Mumbai-Ahmedabad corridor, and the US Midwest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Converter aluminum foil has entered a late-cycle quality phase where EMA MDR traceability mandates and REACH compliance documentation filter supplier bases toward integrated producers with in-house laboratory testing and captive smelter supply.
For Market Incumbents: Anticipate metallized film substitution in snack packaging by accelerating ALD barrier coating partnerships for ultra-thin pharmaceutical gauges. Backward integration into cold rolling secures gauge tolerance control against Chinese mill allocation risk during energy rationing periods. Prioritize ERP middleware development to resolve lot traceability conflicts with legacy scheduling software.
For New Entrants and Emerging Players: Enter via Vietnam and Indonesia's expanding generic drug manufacturing corridors, where ASEAN certification requirements remain less stringent than European MDR frameworks. Southeast Asian pharmaceutical growth offers the most penetrable geography for import substitution. Lead with digital watermark integration capabilities to capture anti-counterfeiting packaging contracts.
For Investors and Strategic Acquirers: Pharmaceutical packaging converters with embedded serialization systems are the most active acquirer in this space, seeking captive foil supply to secure three-year tender qualifications. Five-to-ten-year viability hinges on verified post-consumer aluminum sourcing for EU carbon-border adjustment compliance. Monitor Extended Producer Responsibility recycling-content threshold announcements as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cold Rolling | Captive gauge control reduces qualification risk for FDA 21 CFR pharmaceutical contracts. |
| ALD Barrier Coating Partnership | Sub-0.006 mm ceramic deposition enables USP-compliant biologics packaging at reduced metal cost. |
| ERP Middleware Development | Lot traceability system integration resolves FDA serialization conflicts with legacy mill scheduling. |
| Post-Consumer Aluminum Sourcing | Verified recycling streams secure EU carbon-border adjustment advantages for European tenders. |
| Digital Watermark Integration | Covert authentication features embedded during rolling capture premium anti-counterfeiting contracts. |
Study Parameters
Direct dialogue with rolling mill operations managers, pharmaceutical packaging procurement leads, regulatory affairs directors at laminating converters, and EMA compliance consultants grounded qualitative assessment. Secondary validation drew from FDA 21 CFR filings, EMA MDR technical documentation, BIS certification registries, and customs trade flow data. Bottom-up capacity modeling triangulated against top-down pharmaceutical packaging demand projections.
Bottom-up analysis segmented volume and value across product type, end-use, thickness, and coating technology dimensions throughout the forecast period. CAGRs were derived from rolling mill capacity expansion pipelines cross-referenced with generic drug export growth trajectories. ALD coating adoption curves and REACH compliance cost pass-through assumptions informed premium segment elasticity.
Inputs from rolling mill operations managers and pharmaceutical procurement leads were available through the study window; gaps in privately held contract pricing introduce uncertainty bands around margin compression estimates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Metal Pails Market
Metal Packaging
France Metal Packaging Market
Metal Packaging
Saudi Arabia Metal Packaging Market
Metal Packaging
India Metal Packaging Market
Metal Packaging
South Africa Metal Packaging Market
Metal Packaging
Aluminium Bottle Market
Metal Packaging
Metal Cans Market
Metal Packaging
Packaging Metallization Market
Metal Packaging
Household Aluminum Foils Market
Metal Packaging
Tin Cans Market
Metal Packaging
Bi-Metal Cans Market
Metal Packaging
Global Laminated Aluminium Foil Market
Metal Packaging
Cans Market
Metal Packaging
Aluminum Cans Market
Metal Packaging
Australia Metal Packaging Market
Metal Packaging
Aluminum Foil Packaging Market