
 Pressurized Metal Containers Market | 2026-2036
Pressurized Metal Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Pressurized Metal Containers Market Analytics
A widening capital-intensity divergence between integrated steel sourcers and toll-coaters is redrawing competitive boundaries in pressurized metal containers. Ball Corporation leverages captive aluminum supply chains to sustain margin stability across beverage can volumes. Crown Holdings Inc. anchors its position through deep R&D investment in lightweighting alloys, while Ardagh Group competes via geographic diversification across European and North American production nodes.
Pressurized metal containers are sealed cylindrical vessels fabricated from aluminum or tinplate steel, engineered to withstand internal pressures ranging from 1.5 to 12 bar depending on application, with welded or seamed sidewalls and precision-formed domes. These containers store and dispense products through controlled valve release, serving as critical packaging for propellant-driven formulations in consumer and industrial sectors. Aerosol cans dominate value contribution given their ubiquity in personal care and household applications, while industrial containers capture specialized margin pools through corrosion-resistant linings and UN-certified transport ratings. Beverage cans represent a mature volume base with incremental growth tethered to carbonated soft drink and beer consumption patterns.
The EPA regulates volatile organic compound emissions from aerosol propellants under Clean Air Act mandates, while FDA oversight governs pharmaceutical-grade container contact surfaces and leachate thresholds. REACH restricts specific coating chemistries and heavy metal content across European supply chains, compelling reformulation of interior epoxy phenolic linings. Stakeholders must monitor evolving extended producer responsibility frameworks and deposit-return scheme expansions as these mechanisms reshape container economics and material recovery obligations.
Market Dynamics
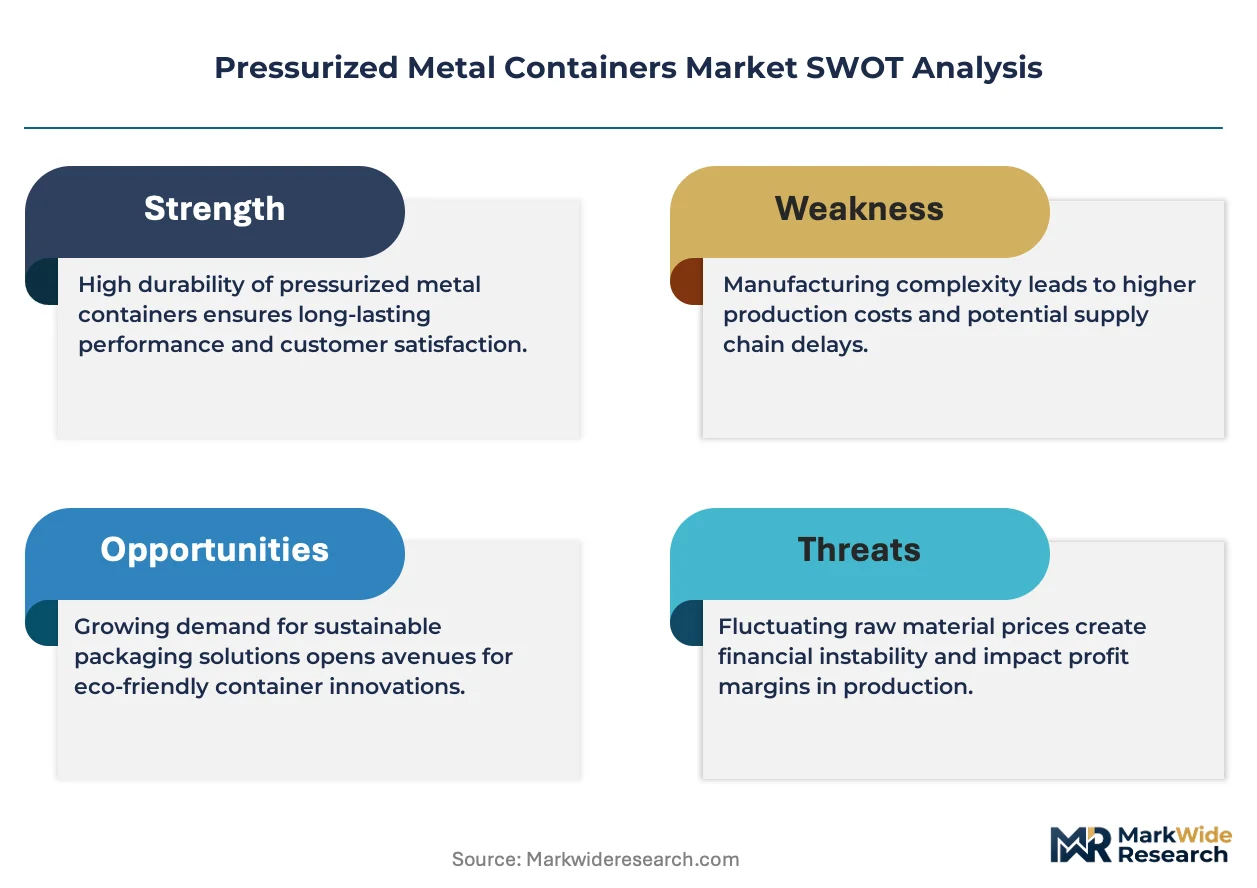
REACH compliance deadlines are compressing coating reformulation timelines across European supply chains, forcing simultaneous R&D acceleration and inventory phase-outs that reshape working capital requirements for container manufacturers.
Growth Catalysts
- Extended Producer Responsibility frameworks:EU member states are mandating deposit-return schemes that increase container recovery rates and create circular revenue streams for compliant manufacturers.
- India's PLI scheme:Production-linked incentives for consumer goods manufacturing are expanding domestic aerosol filling capacity and downstream container demand.
- Lightweighting alloys:Advanced aluminum-magnesium formulations reduce material intensity per unit while maintaining pressure ratings, cutting freight costs for beverage and personal care applications.
Market Restraints
- Aluminum ingot price volatility:London Metal Exchange pricing swings compress margin predictability for non-integrated container producers lacking captive smelter arrangements.
- Epoxy phenolic lining dependency:REACH Annex XVII restrictions on bisphenol-A derivatives force costly substitution trials with unproven long-term corrosion performance.
- Tinplate concentration in China:Baoshan and Shougang control critical cold-rolling capacity, creating single-source vulnerability for European and North American canmakers.
Strategic Opportunities
- Brazil's underpenetrated home care segment:Aerosol adoption in surface disinfectants and air fresheners lags North American per-capita consumption by 60%, creating white space for format conversion.
- Pharmaceutical-grade pressurized delivery:Metered-dose inhaler containers for respiratory therapies face capacity constraints as generic drugmakers expand production.
- Digital printing convergence with inline inspection:Direct-to-can decoration eliminates label substrates while AI-driven defect detection reduces scrap rates in high-speed lines.
Industry Challenges
- Coating chemist scarcity:Formulation expertise for interior linings that satisfy both FDA leachate thresholds and EPA VOC requirements commands premium compensation and extended recruitment cycles.
- UN certification timelines:Transport container testing for dangerous goods classifications requires 12-18 month validation periods that delay industrial market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pressurized Metal Containers Market |
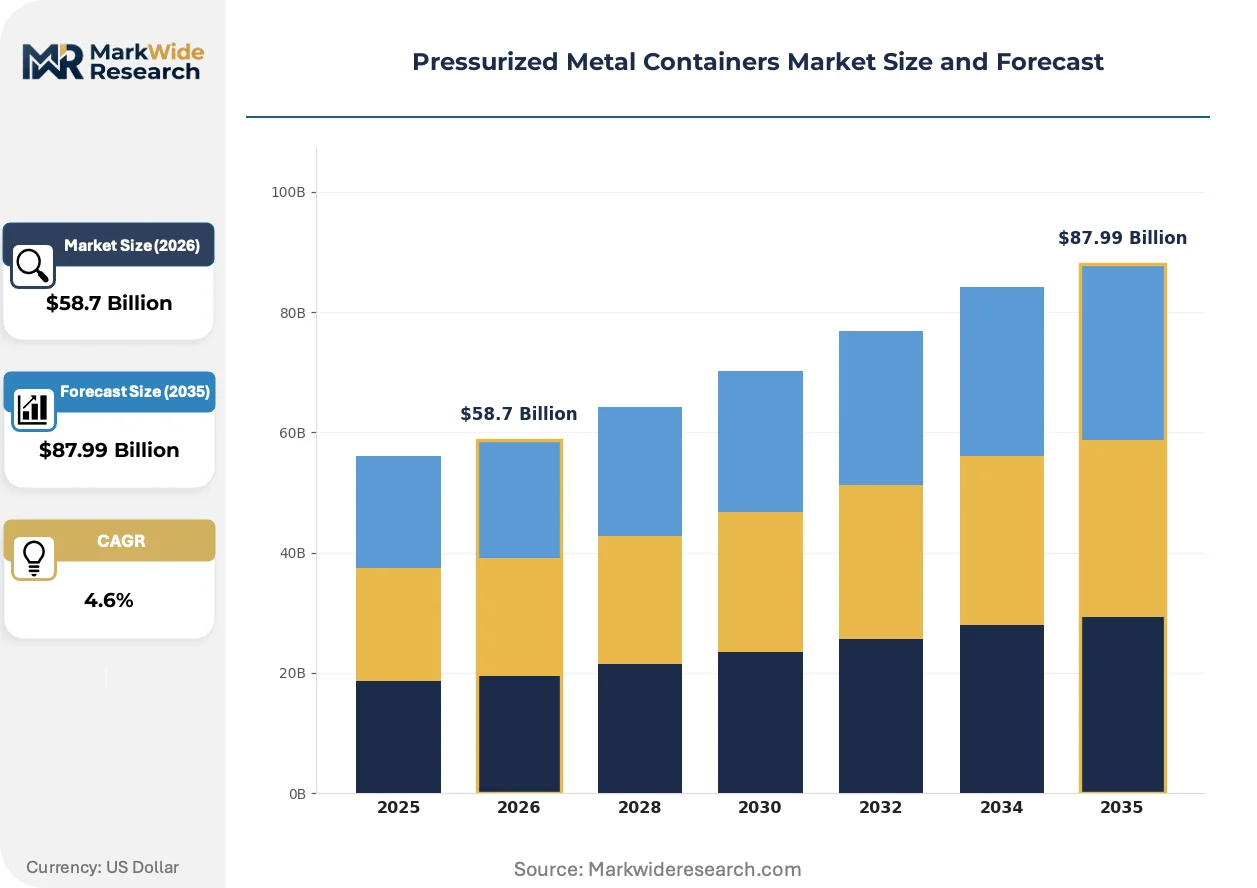
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $87.99 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aerosol Cans, Fuel Cans, Beverage Cans, Industrial Containers End User: Food & Beverage Industry, Automotive Industry, Pharmaceutical Sector, Home Care Products Packaging Type: Rigid Containers, Flexible Containers, Composite Containers, Refillable Containers Technology: Injection Molding, Blow Molding, Metal Stamping, Laser Cutting |
| Companies Covered | Ball Corporation, Crown Holdings Inc., Ardagh Group, Can-Pack, Silgan Holdings, Trivium Packaging, Toyo Seikan Group Holdings, Mauser Packaging Solutions, CCL Container, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pressurized Metal Containers Market Evolving Landscape
Material science advances and regulatory chemistry constraints are converging to redefine container specifications, with sustainability mandates now dictating alloy selection and coating architecture rather than treating these as secondary attributes.
Polymer-lined aluminum monobloc construction is decomposing the traditional three-piece tinplate assembly for personal care applications. Prestige fragrance houses and sun care brands are adopting monobloc formats at 15-20% annual expansion rates. This technology is decomposing the established supplier base by favoring extrusion specialists over traditional drawn-and-ironed canmakers.
EPA Significant New Alternatives Policy evaluations are accelerating hydrofluoroolefin propellant transitions ahead of Clean Air Act phase-down schedules. Aerosol formulators must revalidate valve compatibility and spray characteristics under compressed timelines. Household product categories face the steepest compliance curves as existing stock-keeping units require simultaneous reformulation.
Direct-store-delivery networks are consolidating procurement decisions for carbonated beverages into fewer regional bottler headquarters. This concentration shifts volume allocation power toward buyers capable of committing to multi-year aluminum supply agreements. The phenomenon is most pronounced in the southeastern United States, where independent bottler mergers have reduced active supplier negotiation points by 40% since 2019.
Pressurized Metal Containers Market Segmentation
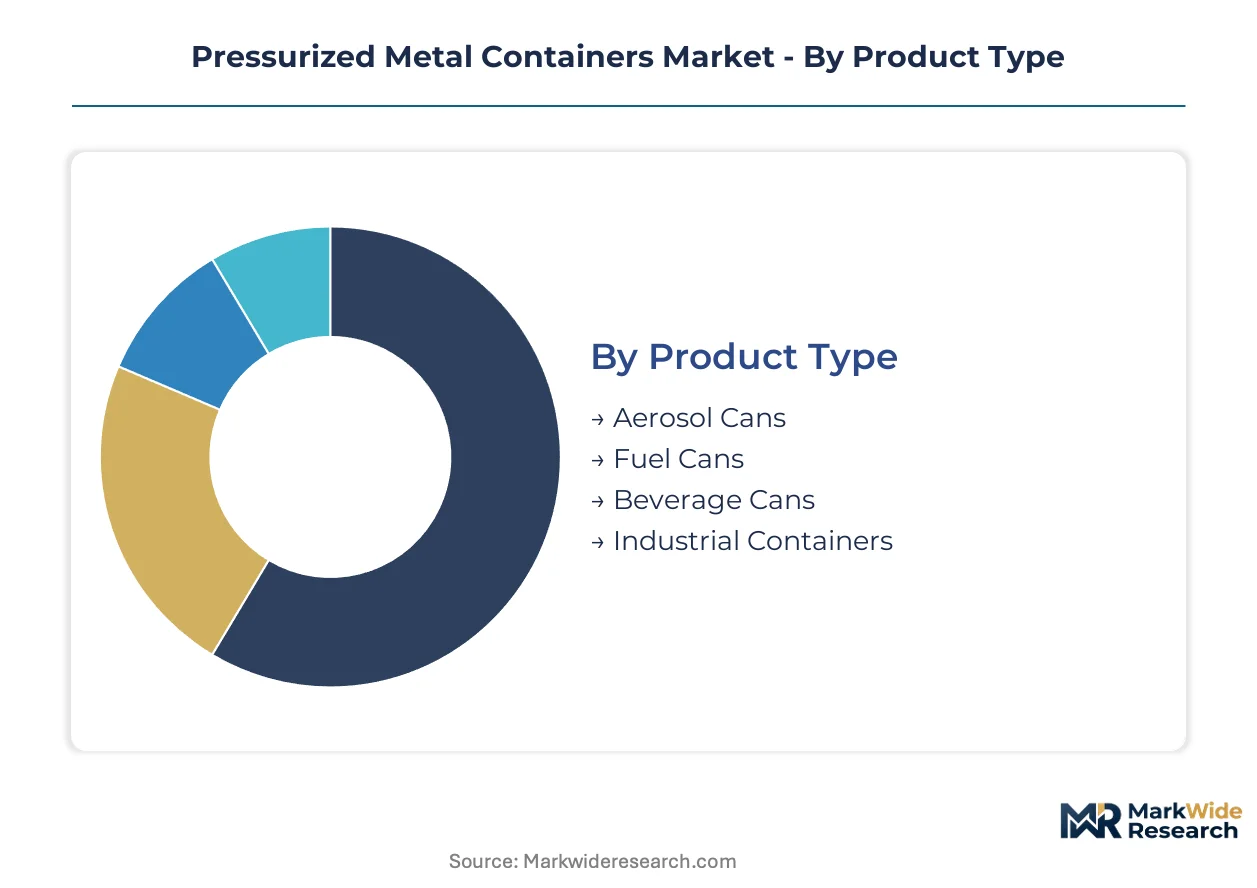
Pressurized metal containers serve divergent performance requirements across consumer and industrial channels. Each segment category carries distinct margin profiles, certification burdens, and channel access patterns that reshape supplier economics.
Product Type:
Aerosol cans move through mass retail and direct-store-delivery networks. Beverage cans consolidate through bottler procurement hubs. Industrial containers route through specialized distributors with UN certification capabilities.
- Aerosol Cans:Three-piece tinplate or aluminum monobloc construction withstands propellant pressures from 2.5 to 12 bar. Personal care and household formulations in India and Brazil are expanding filling capacity faster than mature North American markets. REACH-compliant interior linings and EPA VOC thresholds drive coating reformulation costs.
- Beverage Cans:Drawn-and-ironed aluminum two-piece construction dominates carbonated soft drinks and beer. Crown Holdings and Ball Corporation compete through lightweighting alloys that reduce freight cost per thousand units. Direct-store-delivery consolidation in the southeastern United States has reduced active negotiation points.
- Fuel Cans:UN-certified steel construction for flammable liquid transport with precision-seamed closures. Automotive aftermarket channels and emergency preparedness retail.
- Industrial Containers:Corrosion-resistant linings for chemical propellants and compressed gases. Specialized margin pools through transport certification and hazardous material compliance.
Aerosol cans dominate installed base. Beverage cans are where expansion concentrates through lightweighting alloy adoption.
End User:
Customer procurement sophistication varies sharply. Pharmaceutical buyers impose FDA leachate thresholds. Automotive channels prioritize UN transport ratings. Home care segments face the steepest EPA propellant transition curves.
- Food & Beverage Industry:High-volume aluminum can demand from carbonated soft drink and beer producers. Procurement consolidation into regional bottler headquarters shifts volume allocation power toward multi-year supply agreement committers.
- Home Care Products:Aerosol format adoption in surface disinfectants and air fresheners. Brazil's underpenetrated segment lags North American per-capita consumption, creating white space for format conversion from trigger sprays.
- Pharmaceutical Sector:Metered-dose inhaler containers for respiratory therapies. FDA governs contact surface specifications and extractables testing. Generic drugmaker expansion faces capacity constraints in precision-formed aluminum monobloc supply.
- Automotive Industry:Fuel cans and specialized pressurized lubricant containers. UN certification timelines of 12-18 months delay market entry for new transport classifications.
Food & Beverage Industry commands volume scale. Home Care Products is climbing the fastest on aerosol format conversion.
Packaging Type:
Structural format determines material recovery economics and circular revenue potential. Rigid formats align with deposit-return schemes. Refillable systems require reverse logistics infrastructure.
- Rigid Containers:Dominant aluminum and tinplate construction for pressure retention. EU extended producer responsibility frameworks and deposit-return schemes increase recovery rates for compliant manufacturers.
- Refillable Containers:Steel and aluminum systems designed for multiple use cycles. Industrial gas and beverage fountain applications concentrate in Germany and Nordic markets with established reverse logistics.
- Flexible Containers:Laminated film constructions with limited pressure ratings. Niche applications in personal care sample formats.
- Composite Containers:Hybrid material systems combining metal ends with fiber or plastic bodies. Cost-driven substitution in non-critical pressure applications.
Rigid Containers dominate installed base. Refillable Containers are gaining share fastest on circular economy policy alignment.
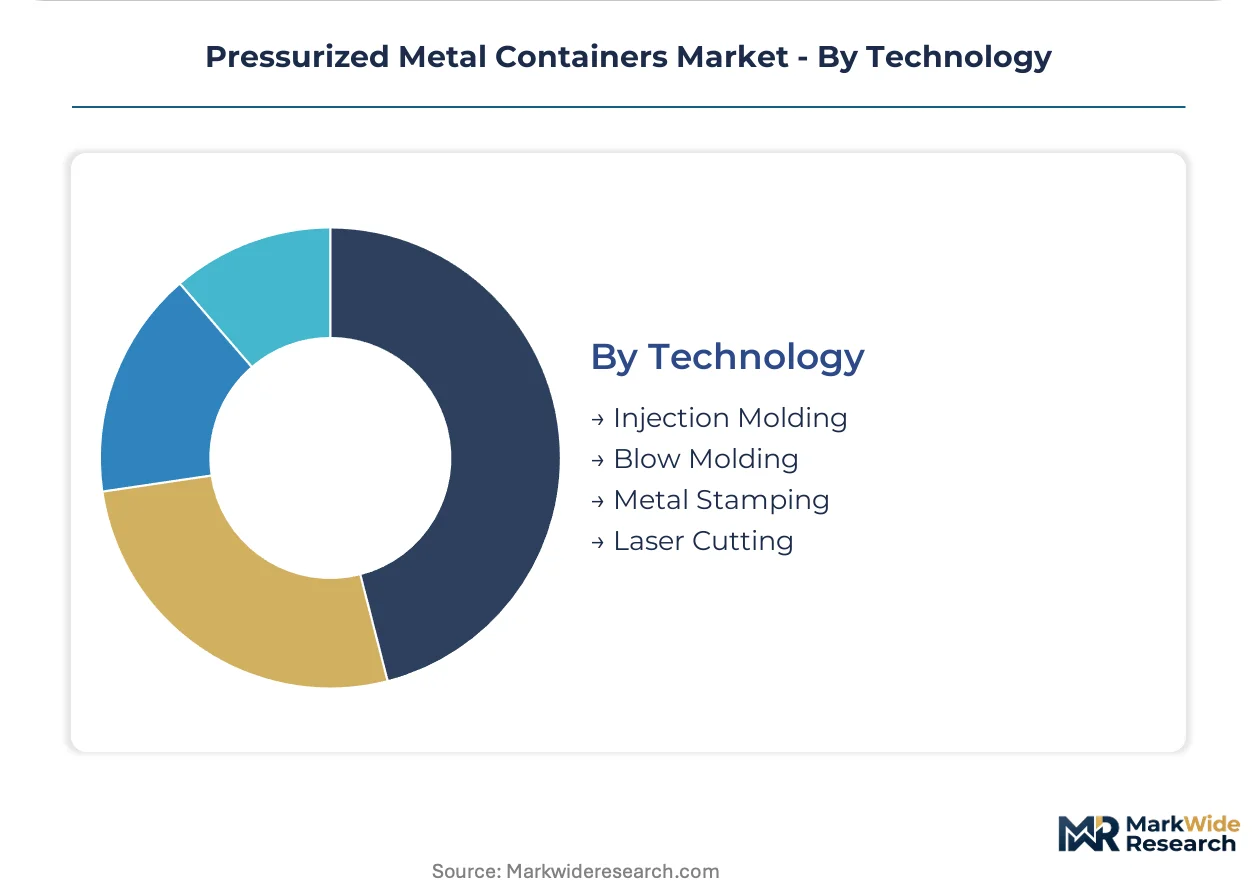
Technology:
Process selection ties to material form and geometric complexity. Metal stamping and drawing dominate cylindrical pressure vessels. Laser cutting enables precision venting and decoration integration.
- Metal Stamping:Progressive die forming of tinplate and aluminum for three-piece can bodies and domes. Baoshan and Shougang cold-rolling concentration in China creates single-source vulnerability for European and North American canmakers.
- Blow Molding:Limited relevance for metal containers; primarily polymer-based formats. Excluded from high-pressure metal vessel production.
- Injection Molding:Polymer component production for valves, actuators, and overcaps. Precision tolerances for propellant seal integrity.
- Laser Cutting:Precision trimming of drawn cup edges and integrated venting features. Digital printing convergence enables direct-to-can decoration with inline defect detection.
Metal Stamping dominates installed base. Laser Cutting is where technology investment concentrates for decoration and quality integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes pressurized metal containers primarily for industrial chemical transport, while India and Brazil concentrate demand in aerosol personal care and home care formats. This consumption-mix differential shapes capacity investment patterns and regulatory compliance priorities across manufacturing clusters.
United States
Carbonated beverage can demand from regional bottler consolidation drives aluminum procurement. EPA Clean Air Act mandates accelerate hydrofluoroolefin propellant transitions in household aerosol categories. Southeast bottler mergers have reduced active supplier negotiation points by 40% since 2019, concentrating volume allocation power.
Germany
Refillable beverage container systems and industrial gas cylinders sustain steel and aluminum demand. EU Green Deal extended producer responsibility frameworks mandate deposit-return schemes that increase recovery rates. The Ruhr industrial corridor hosts specialized coating facilities serving REACH-compliant interior lining specifications.
China
Domestic aerosol filling capacity expansion for personal care and home care products outpaces mature markets. GB standards and dual carbon goals tighten material efficiency requirements for container production. Baoshan and Shougang cold-rolling concentration in Shanghai and Beijing creates single-source vulnerability for European and North American canmakers.
India
Production-linked incentive schemes for consumer goods manufacturing expand domestic aerosol filling infrastructure. BIS certification requirements for food-contact metal surfaces govern interior coating specifications. Maharashtra and Gujarat industrial corridors attract multinational container fabricators seeking export-oriented manufacturing bases.
Brazil
Aerosol format adoption in surface disinfectants and air fresheners lags North American per-capita consumption by 60%. ANVISA pharmaceutical-grade container standards create compliance barriers for metered-dose inhaler imports. São Paulo manufacturing clusters concentrate domestic tinplate conversion capacity for regional consumer goods supply.
Pressurized Metal Containers Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive aluminum supply chains separating margin-stable volume players from toll-coating dependent competitors. Three-piece tinplate fabricators compete against aluminum monobloc extrusion specialists for personal care applications. Strategic moves concentrate on lightweighting alloy R&D acceleration and geographic diversification across European and North American production nodes.
Among integrated aluminum suppliers, Ball Corporation exemplifies captive supply chain architecture, while Crown Holdings Inc. occupies a position emphasizing materials science investment. Ardagh Group represents geographic diversification strategy across multiple continental production networks. These three entities anchor distinct competitive vectors within a market where backward integration into primary metal sourcing determines margin predictability.
| Leading Market Players |
|---|
| Ball Corporation |
| Crown Holdings Inc. |
| Ardagh Group |
| Can-Pack |
| Silgan Holdings |
| Trivium Packaging |
| Toyo Seikan Group Holdings |
| Mauser Packaging Solutions |
| CCL Container |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Baoshan and Shougang cold-rolling facilities shapes aluminum and tinplate price floors across European and North American canmaking operations, with scale advantages concentrating procurement leverage among integrated producers while toll-coaters absorb margin volatility from London Metal Exchange swings.
Pricing Analysis
After-sales coating service contracts and lining reformulation support packages drive lifetime value for container manufacturers facing REACH compliance deadlines. Three-tier pricing structure across UN-certified industrial, FDA-compliant pharmaceutical, and standard consumer grades separates premium corrosion-resistant specifications from economy personal care formats. Cost compression in non-integrated aluminum sourcing is intensifying because LME price volatility lacks captive smelter hedging. Regional bottler procurement consolidation in the southeastern United States has shifted volume allocation power toward buyers with multi-year supply commitments, making independent canmakers most price-sensitive while integrated aluminum suppliers maintain margin stability.
Supply Chain Analysis
Inventory lead times for epoxy phenolic lining chemistries have extended as REACH Annex XVII restrictions force simultaneous R&D acceleration and inventory phase-outs across European coating facilities. Raw material supply draws from Chinese cold-rolled steel, Australian bauxite for aluminum smelting, and German specialty chemical inputs for interior linings. Single-source vulnerability concentrates in Shanghai and Beijing where Baoshan and Shougang control critical tinplate capacity, creating supply chain risk for European and North American fabricators lacking alternative sourcing. Distribution runs through specialized industrial gas distributors with UN certification capabilities, direct-store-delivery bottler networks for beverages, and mass retail channels for aerosol consumer goods.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored to aluminum price normalization following LME volatility peaks, with downstream demand from carbonated beverage and aerosol personal care channels reinforcing volume visibility.
For Market Incumbents: Secure captive aluminum supply arrangements or long-term tolling agreements to insulate margin predictability from London Metal Exchange swings. Accelerate lightweighting alloy R&D investment to maintain freight cost advantages as direct-store-delivery consolidation shifts buyer power toward regional bottler headquarters. Defensive positioning against monobloc extrusion specialists requires deepening coating formulation expertise for REACH-compliant interior linings.
For New Entrants and Emerging Players: Metered-dose inhaler container capacity gaps present a service-layer opening where incumbent supply constraints delay generic drugmaker expansion. Brazil's underpenetrated home care aerosol segment offers format conversion white space as surface disinfectant and air freshener adoption lags North American consumption patterns. Target pharmaceutical-grade aluminum monobloc fabrication with ANVISA pre-certification to bypass import barriers for respiratory therapy delivery systems.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among coating formulation specialists with captive REACH compliance capabilities and long-term supply agreements with European consumer goods multinationals. Long-term viability over the mid-term projection horizon favors targets with backward integration into aluminum sourcing or exclusive tolling arrangements with primary metal producers. Monitor hydrofluoroolefin propellant transition timelines as an inflection signal for valve compatibility revalidation demand and coating reformulation service intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Lightweighting Alloy R&D Acceleration | Crown Holdings and Ball Corporation compete through material science investment reducing freight cost per thousand units. |
| REACH-Compliant Coating Reformulation | Ruhr industrial corridor facilities serve interior lining specifications as Annex XVII restrictions force chemistry substitution. |
| Captive Aluminum Supply Integration | Backward integration into primary metal sourcing separates margin-stable volume players from toll-coating dependent competitors. |
| Pharmaceutical-Grade Monobloc Capacity Expansion | Generic drugmaker production growth faces aluminum container supply constraints in precision-formed metered-dose inhaler formats. |
| Brazilian Home Care Aerosol Market Development | São Paulo manufacturing clusters concentrate tinplate conversion capacity for regional surface disinfectant and air freshener format conversion. |
Research Methodology
Operator-level perspectives from coating formulators, aerosol filling line engineers, beverage bottler procurement directors, and aluminum smelter tolling managers anchored the qualitative base for supply chain dynamics and pricing formation mechanisms. Primary interview insights combined with secondary validation from SEC 10-K filings of publicly traded container manufacturers, customs and trade data on aluminum and tinplate imports, EPA Clean Air Act regulatory dockets, and ECHA REACH substance restriction notifications. Bottom-up unit economics modeling triangulated against top-down industry association capacity estimates produced convergent demand figures.
Sensitivity analysis around aluminum price volatility scenarios, REACH compliance deadline shifts, and propellant transition timelines tested forecast robustness across the projection horizon. Segmentation dimensions modeled include product type construction, end-use industry certification requirements, packaging format circular economy alignment, and manufacturing technology process selection. CAGRs derived from historical volume trajectories adjusted for capacity expansion announcements and regulatory-driven demand inflections. Industry-specific forecast inputs incorporated beverage can lightweighting adoption curves and aerosol filling capacity buildout in India's PLI-supported industrial corridors.
Underlying assumptions cover sustained aluminum price normalization, REACH Annex XVII enforcement timelines, and extended producer responsibility scheme expansions, with deviation risk concentrated in LME volatility spikes and coating chemist labor scarcity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
North America Metal Packaging Market
Metal Packaging
Global Laminated Aluminium Foil Market
Metal Packaging
Household Aluminum Foils Market
Metal Packaging
3-Piece Metal Cans Market
Metal Packaging
PTP Aluminum Foil Market
Metal Packaging
Vietnam Metal Packaging Market
Metal Packaging
United Arab Emirates Metal Packaging Market
Metal Packaging
Europe Metal Packaging Market
Metal Packaging
Middle East and Africa Metal Cans Market
Metal Packaging
Packaging Metallization Market
Metal Packaging
Latin America Metal Packaging Market
Metal Packaging
Tinplate Packaging Market
Metal Packaging
Collapsible Aluminium Tube Market
Metal Packaging
Metal Packaging Market
Metal Packaging
France Metal Packaging Market
Metal Packaging
APAC Food Cans Market