
 North America 3 Piece Metal Cans Market | 2026-2036
North America 3 Piece Metal Cans Market Size, Share, and Industry Trends Forecast 2026-2036
North America 3 Piece Metal Cans Market Insights
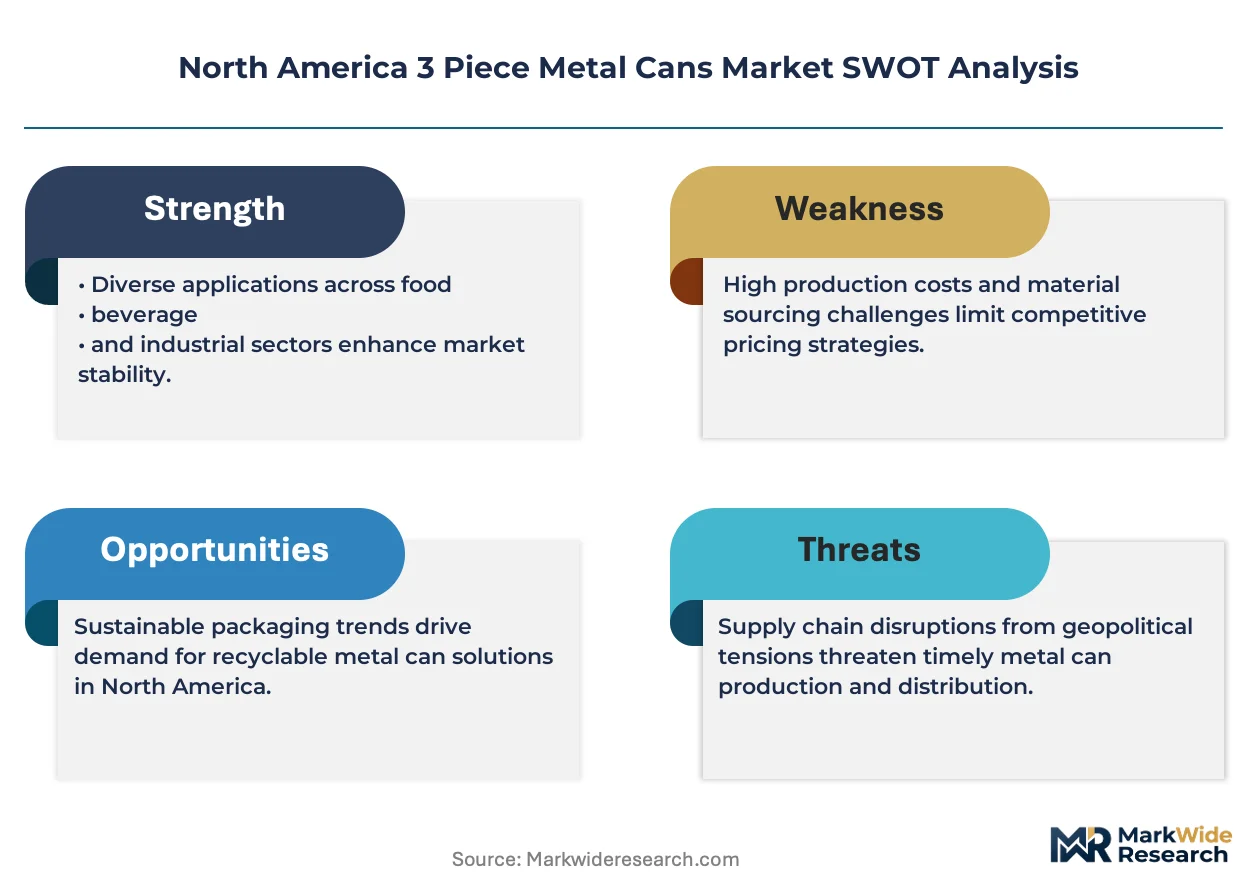
Extended producer responsibility mandates across multiple Canadian provinces and several US states is rebalancing procurement criteria toward infinitely recyclable steel substrates. Silgan Containers leverages captive steel supply agreements to sustain cost predictability across Midwest production facilities. Crown Holdings anchors its position through beverage can specialization, while Ardagh Metal Packaging competes on lightweighting technology for food tins.
Three piece metal cans consist of separate cylindrical body, top lid, and bottom end components joined through seaming or welding processes, typically fabricated from tinplate or electrolytic chromium-coated steel with interior lacquer coatings to prevent corrosion. These containers serve primary industrial functions for shelf-stable food preservation, hazardous chemical containment, and pharmaceutical product protection. Pails and drums dominate volume within industrial chemical applications where UN-rated certification requirements create sticky demand patterns. Food and beverage end users represent the fastest-expanding segment as processors substitute steel for plastic under retailer sustainability mandates. Small-format tins command premium positioning in personal care and specialty food channels where shelf differentiation justifies unit cost premiums.
FDA food contact substance regulations govern interior coating chemistries, while EPA hazardous waste container standards dictate wall thickness and closure integrity for chemical drums. OSHA workplace safety requirements further shape pail and drum specifications for manual handling weight limits and stacking load ratings. Stakeholders must monitor state-level packaging fee structures and deposit return system expansions as these programs directly alter total cost of ownership calculations for material selection decisions.
Market Dynamics
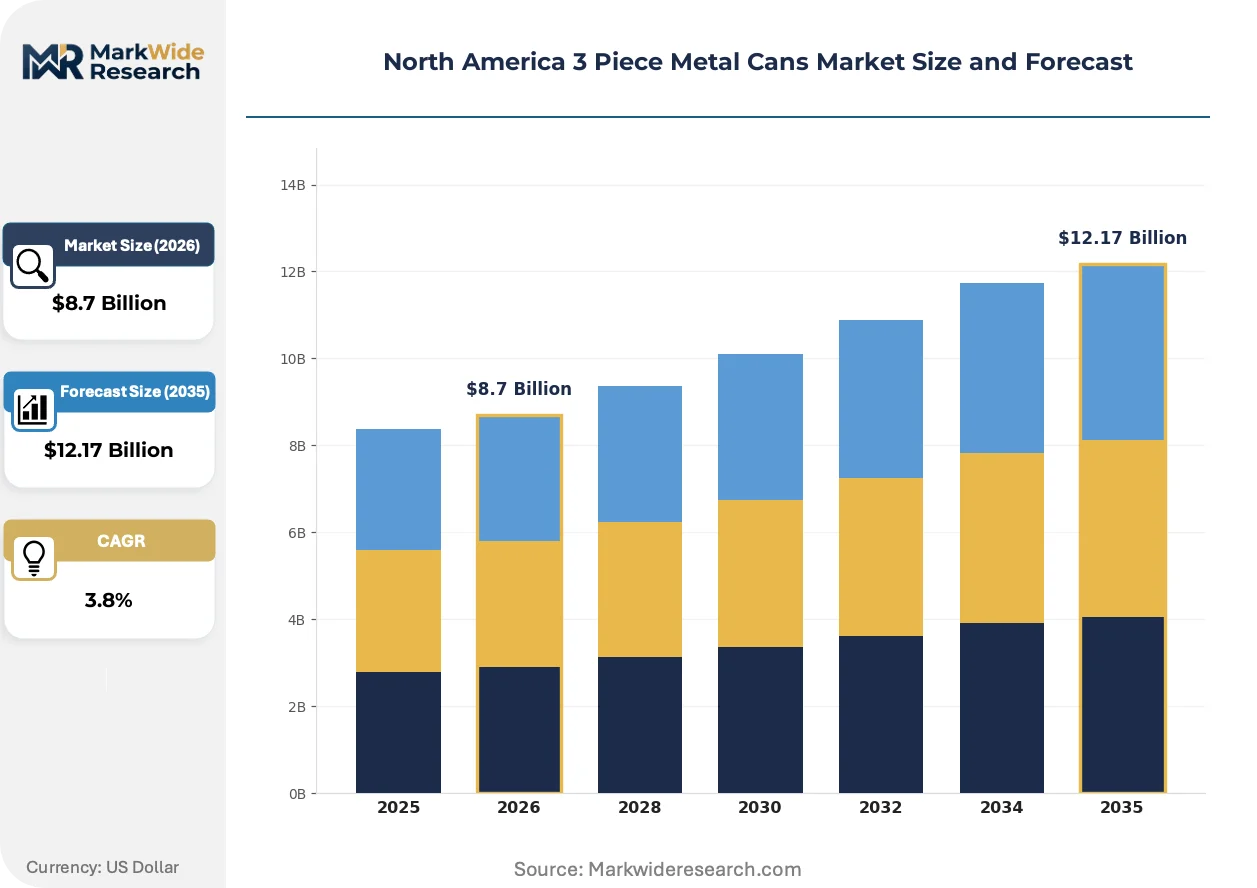
Extended producer responsibility frameworks across Canadian provinces and US states are redirecting procurement toward steel substrates, creating structural demand pull as food processors abandon plastic packaging to preempt compliance costs and retailer sustainability mandates.
Growth Catalysts
- Deposit Return System Expansion:State-level bottle bill modernizations in Oregon, Maine, and California are expanding coverage to food containers, creating guaranteed offtake streams for steel can recyclers.
- Steel Scrap Arbitrage:Regional mini-mill concentration around the Great Lakes industrial corridor is generating captive feedstock loops that lower raw material volatility for can manufacturers.
- Retailer Sustainability Mandates:Major grocery chains are imposing packaging scorecards that penalize plastic alternatives, forcing CPG processors to specify tinplate and ECCS substrates.
Market Restraints
- Tinplate Input Cost Volatility:Spot prices for electrolytic tinplate fluctuate with LME tin and steel billet indices, compressing converter margins during commodity spikes.
- Single-Point Supply Risk:Domestic tinplate rolling capacity concentrates among three integrated steel producers, creating vulnerability to mill maintenance cycles or force majeure events.
- Lightweighting Ceiling:Wall thickness reduction for three-piece cans hits structural limits at approximately 0.15mm before seaming integrity fails UN drop-test requirements.
Strategic Opportunities
- Quebec and British Columbia EPR Acceleration:Provincial packaging fee structures coming into force prioritize infinitely recyclable materials, creating cost advantages for steel versus aluminum or composite cans.
- Aseptic Food Tins:Retort-compatible interior lacquer advances are opening shelf-stable dairy and ready-meal segments previously locked in multilayer pouches.
- Direct-to-Processor Digital Sourcing:Platform-based procurement is disintermediating traditional distributor networks for mid-volume food manufacturers in the Midwest.
Industry Challenges
- Welding Technician Scarcity:Electric resistance welding expertise is aging out of the workforce faster than community college programs can replenish certified operators.
- Interior Coating Reformulation Timelines:FDA food contact notifications for bisphenol-A alternatives require month-long migration studies that delay new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America 3 Piece Metal Cans Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.17 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drums, Pails, Tins, Barrels End User: Food & Beverage, Chemicals, Pharmaceuticals, Personal Care Size: Small, Medium, Large, Extra Large Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Silgan Containers, Mauser Packaging Solutions, Crown Holdings, Hudson Technologies, Elemental Container Inc., Ball Corporation, Metal Container Corporation, ZERO Manufacturing, Ardagh Metal Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America 3 Piece Metal Cans Market Trends and Innovations
Active innovation fronts in metal can manufacturing center on material efficiency, regulatory chemistry compliance, and procurement digitization that compresses specification-to-delivery cycles for regional food processors.
Ultrathin tinplate substrates with enhanced chromium passivation are absorbing volume from conventional heavier gauges in vegetable and soup can applications. Midwestern vegetable processors are specifying these materials for standard shelf-stable lines, enabling wall-thickness reductions without compromising double-seam integrity or retort cycle performance.
EPA hazardous waste container standards are tightening closure specifications for UN-rated pails and drums used in chemical distribution. Industrial packaging converters serving the Ohio River Valley petrochemical corridor are redesigning lug and gasket geometries to satisfy drop-test protocol revisions, with drum fabricators absorbing certification costs to maintain hazardous material shipping authorizations.
Specification consolidation among national food retailers is compressing the supplier base for private-label canned goods. Regional co-packers in Michigan and Illinois are responding by qualifying dual-source steel agreements, while direct mill relationships replace distributor intermediaries for volume-stable accounts.
North America 3 Piece Metal Cans Market Segmentation
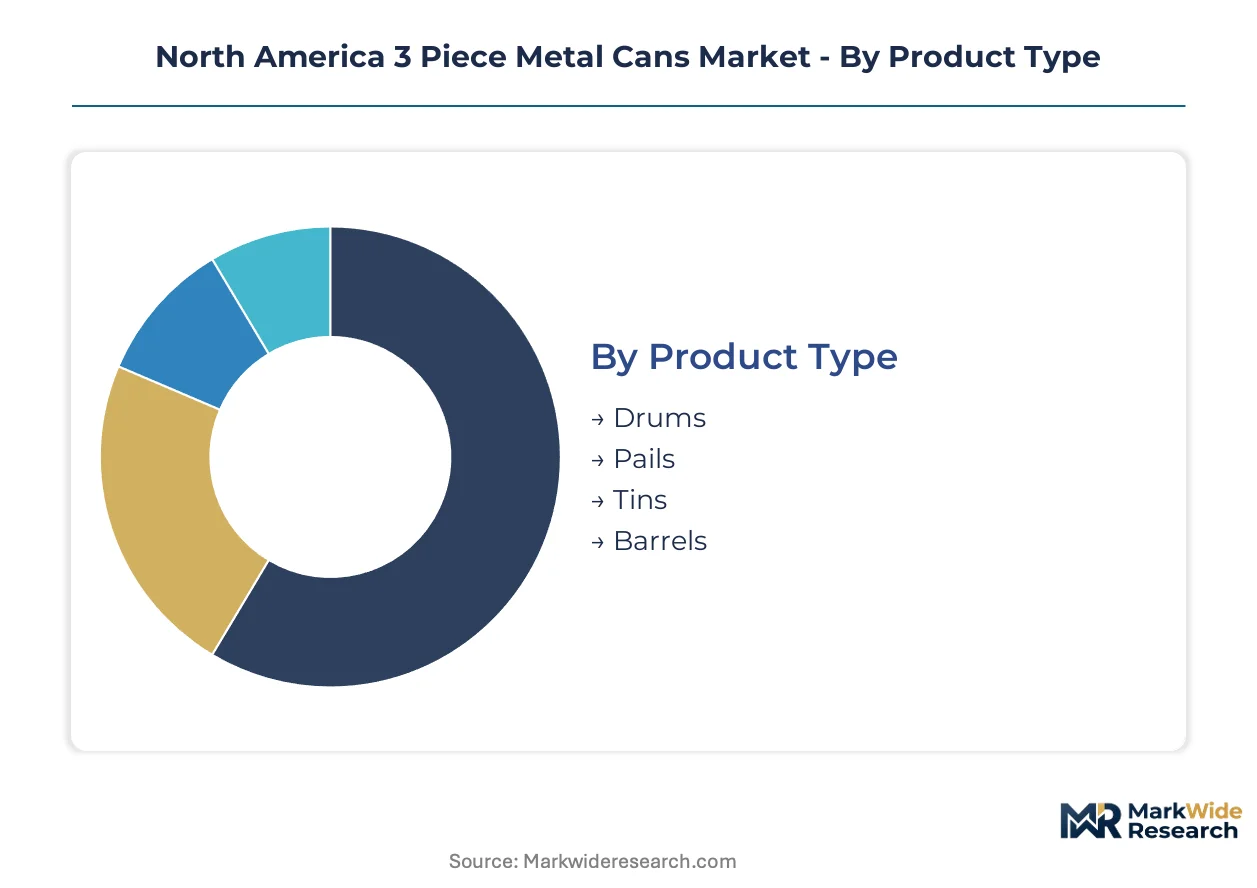
Three-piece metal can procurement varies sharply by containment duty, regulatory exposure, and volume scale. Segmentation reveals where tinplate specifications tighten and where ECCS substrates displace alternatives.
Product Type:
Buyers differentiate primarily by UN certification requirements and seaming complexity rather than unit economics alone.
- Drums:Cylindrical steel containers with rolled rims and tight-head or open-head configurations, engineered to meet EPA hazardous waste container standards for chemical containment. Demand clusters along the Ohio River Valley petrochemical corridor where UN-rated certification creates sticky specifications. Drum fabricators absorb recertification costs to maintain hazardous material shipping authorizations.
- Pails:Tapered cylindrical containers with lug closures and gasket-sealed lids, standardized at 5-gallon capacity for manual handling compliance under OSHA workplace safety limits. Midwest industrial chemical distributors specify pails for coatings, adhesives, and lubricants where stacking load ratings determine procurement decisions.
- Tins:Small-format containers with seamed or soldered construction, typically fabricated from lighter tinplate gauges for shelf-stable food and personal care applications. Specialty food processors in Michigan and Illinois specify tins for premium positioning where shelf differentiation justifies unit cost premiums.
- Barrels:Large-volume cylindrical containers exceeding 30-gallon capacity, constructed from heavier gauge steel with reinforced chimes for forklift handling. Food-grade barrel specifications serve bulk ingredient storage for Great Lakes region processors.
Drums lead volumes today; tins are gaining share fastest.
End User:
Regulatory jurisdiction and coating chemistry requirements segment buyers into distinct specification clusters.
- Food & Beverage:Processors of shelf-stable vegetables, soups, and ready-meals specifying retort-compatible interior lacquers under FDA food contact substance regulations. EPA recycling mandates and state-level deposit legislation are tightening material recovery requirements across Oregon, Maine, and California.
- Chemicals:Industrial coatings, solvents, and petrochemical distributors requiring UN-rated certification for hazardous material transport. Ohio River Valley fabricators dominate procurement with captive steel supply agreements.
- Pharmaceuticals:Drug manufacturers specifying tamper-evident closures and inert interior coatings for active ingredient protection. FDA compliance timelines for bisphenol-A alternative notifications extend qualification cycles.
- Personal Care:Cosmetic and grooming product brands sourcing small-format tins for premium shelf presentation. Retailer sustainability scorecards penalize plastic alternatives, forcing specification shifts toward steel substrates.
Food & Beverage anchors volume; Personal Care shows the steepest expansion trajectory.
Size:
Handling economics and filling line compatibility determine size selection more than material cost per unit.
- Small:Containers under 1 liter, dominating personal care and specialty food channels where unit premiums absorb higher per-volume material costs.
- Medium:1-5 liter formats, standard for vegetable processors and soup manufacturers in the Great Lakes industrial corridor.
- Large:5-30 liter capacities, serving institutional food service and bulk chemical distribution with forklift-compatible stacking geometry.
- Extra Large:Exceeding 30 liters, restricted to drum and barrel categories where wall thickness requirements escalate with capacity.
Medium sizes dominate current procurement; Small formats are climbing the fastest.
Distribution Channel:
Order frequency and specification complexity segment buyers between direct mill relationships and intermediary networks.
- Online:Platform-based procurement for mid-volume manufacturers, compressing specification-to-delivery cycles through digital catalog standardization.
- Retail:Packaged goods sold through hardware and industrial supply stores, concentrating in pail and drum categories for maintenance and construction end users.
- Wholesale:Distributor networks serving regional co-packers with inventory buffering for volume-unstable accounts.
- Direct Sales:Mill-direct relationships for national food retailers and chemical processors with volume-stable demand, displacing traditional distributor intermediaries.
Direct Sales commands the largest volume flow; Online channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Welding technician concentrations anchor production capacity across the Great Lakes industrial corridor, where electric resistance welding expertise pools around legacy steel communities. EPA recycling mandates and state-level deposit legislation are tightening material recovery requirements across multiple jurisdictions.
United States
Food and beverage processors in Michigan, Ohio, and Illinois are expanding procurement of steel-based packaging to replace plastic alternatives. EPA hazardous waste container standards dictate wall thickness and closure integrity for chemical drums used in the Ohio River Valley petrochemical corridor. Midwestern vegetable processors around Grand Rapids and Toledo specify ultrathin tinplate substrates for standard shelf-stable lines.
Canada
Extended producer responsibility frameworks across Quebec and British Columbia prioritize infinitely recyclable materials, creating cost advantages for steel versus aluminum or composite cans. Provincial packaging fee structures coming into force redirect procurement criteria toward tinplate and ECCS substrates. Fabricators in Hamilton and Sarnia leverage captive steel supply agreements to sustain cost predictability.
Mexico
Industrial chemical distributors in Nuevo León specify pails for coatings, adhesives, and lubricants where OSHA-aligned workplace safety limits shape procurement decisions. The country's national environmental regulator is aligning hazardous waste container standards with EPA protocols. Monterrey-based fabricators serve cross-border supply chains for Great Lakes region processors.
North America 3 Piece Metal Cans Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the North America 3 Piece Metal Cans Market, with integrated steel mills and captive coating facilities facing specialized fabricators outsourcing substrate supply. The vendor base concentrates around three strategic tiers: integrated packaging conglomerates with captive steel agreements, mid-scale regional specialists serving single end-use verticals, and commodity drum fabricators competing on turnaround speed. Dominant competitive moves include backward integration into tinplate rolling capacity and geographic densification around the Great Lakes industrial corridor to compress logistics costs.
Among integrated packaging conglomerates, Silgan Containers and Crown Holdings represent the scale-driven archetype, while Ardagh Metal Packaging exemplifies lightweighting technology specialists. These three occupy positions within the premium-tier vector where direct mill relationships and specification consolidation among national food retailers create defensive moats. Mauser Packaging Solutions anchors the industrial chemical containment segment. Regional specialists in Michigan and Illinois respond by qualifying dual-source steel agreements and displacing distributor intermediaries for volume-stable accounts.
| Leading Market Players |
|---|
| Silgan Containers |
| Mauser Packaging Solutions |
| Crown Holdings |
| Hudson Technologies |
| Elemental Container Inc. |
| Ball Corporation |
| Metal Container Corporation |
| ZERO Manufacturing |
| Ardagh Metal Packaging |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap fabricators across Michigan and Ohio anchor regional supply networks through conservative balance-sheet management, translating low leverage into pricing discipline that resists spot-market volatility during tinplate commodity spikes.
Pricing Analysis
Contract-based long-term offtake agreements dominate volume procurement for national food retailers, separating premium UN-certified drums from standard food tins from economy-grade industrial pails. Price differentiation rests on certification grade and volume scale, with EPA hazardous waste container standards creating sticky premiums for drum fabricators. Cost compression in standard food can tiers is intensifying because ultrathin tinplate substrates displace heavier gauges without performance sacrifice. Small-format specialty tins show least price sensitivity as shelf differentiation absorbs material premiums.
Supply Chain Analysis
Direct-to-processor digital channels handle mid-volume manufacturer demand, while mill-direct relationships serve national accounts with volume-stable procurement. Geographic supply concentrates in the United States, Canada, and Mexico, with raw material dependencies on electrolytic tinplate, chromium-coated steel, and interior lacquer chemistries. Single-source vulnerability pervades domestic tinplate rolling capacity where three integrated producers control substrate supply. Distribution runs through captive steel agreements and platform-based procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in lightweighting technology and direct sourcing platforms, with ultrathin substrate adoption and disintermediated procurement compressing unit economics for qualified producers.
For Market Incumbents: Cement defensive positioning through backward integration into tinplate rolling capacity and geographic densification around the Great Lakes industrial corridor. Welding technician scarcity threatens production continuity; community college apprenticeship partnerships secure workforce pipelines. Qualify dual-source steel agreements to mitigate single-point mill risk during force majeure events. For New Entrants and Emerging Players: Aseptic food tin technology opens white-space penetration in shelf-stable dairy and ready-meal segments previously locked in multilayer pouches. Quebec and British Columbia EPR acceleration creates jurisdictional arbitrage where steel substrate cost advantages versus aluminum accelerate procurement shifts. Target platform-based direct sourcing for mid-volume Midwest food manufacturers seeking specification-to-delivery compression. For Investors and Strategic Acquirers: Valuations sit cheapest among regional drum fabricators with UN certification moats and Ohio River Valley petrochemical corridor exposure. Long-term viability hinges on EPA hazardous waste container standard continuity and deposit return system expansion across Oregon, Maine, and California. Monitor state-level packaging fee structure implementation as inflection indicator for steel versus aluminum procurement shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tinplate Rolling | Captive steel supply agreements insulate Silgan and Crown from LME tin volatility. |
| Lightweighting Technology Investment | Ultrathin chromium-passivated substrates enable wall-thickness reduction without seaming failure. |
| Direct-to-Processor Digital Platform | Platform-based procurement disintermediates distributor networks for Michigan and Illinois co-packers. |
| EPR Compliance Certification | Quebec and British Columbia fee structures reward infinitely recyclable steel substrates. |
| Welding Technician Apprenticeship Program | Community college partnerships replenish electric resistance welding expertise aging from workforce. |
Research Methodology
Direct dialogue with plant managers at Great Lakes can fabricators, procurement leads at downstream food processors, distribution channel partners, and technical R&D directors for interior coating chemistries grounded qualitative findings. Secondary validation drew from EPA hazardous waste container standards filings, FDA food contact substance notifications, state-level deposit legislation records, and SEC 10-K disclosures from integrated packaging conglomerates. Bottom-up volume triangulation across product type, end user, size, and distribution channel dimensions converged with top-down market sizing.
Segment-level value outputs across the projection horizon reflect modeled interactions between tinplate input cost trajectories, EPR framework expansion timelines, and welding technician supply constraints. Segmentation dimensions included product type, end user vertical, container size tier, and regional regulatory cluster. CAGRs were derived from regression analysis of historical procurement patterns against policy implementation schedules and steel scrap arbitrage dynamics.
The model holds under stable EPA and FDA regulatory continuity; deviation in interior coating reformulation timelines or force majeure events at domestic tinplate mills would shift volume trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Middle East and Africa Metal Cans Market
Metal Packaging
Europe Food Cans Market
Metal Packaging
Tin Cans Market
Metal Packaging
Egypt Metal Packaging Market
Metal Packaging
South Africa Metal Packaging Market
Metal Packaging
Middle East and Africa Metal Packaging Market
Metal Packaging
Asia-Pacific Metal Packaging Market
Metal Packaging
Global Metal Print Packaging Market
Metal Packaging
Metal Aerosol Packaging Market
Metal Packaging
Europe Metal Packaging Market
Metal Packaging
North America Metal Packaging Market
Metal Packaging
Asia Pacific Metal Cans Market
Metal Packaging
Cans Market
Metal Packaging
Household Aluminum Foils Market
Metal Packaging
Metal Aerosol Can Market
Metal Packaging
Europe Metal Cans Market