
 Foil Laminates Market | 2026-2036
Foil Laminates Market Size, Share, and Industry Trends Forecast 2026-2036
Foil Laminates Market Analysis
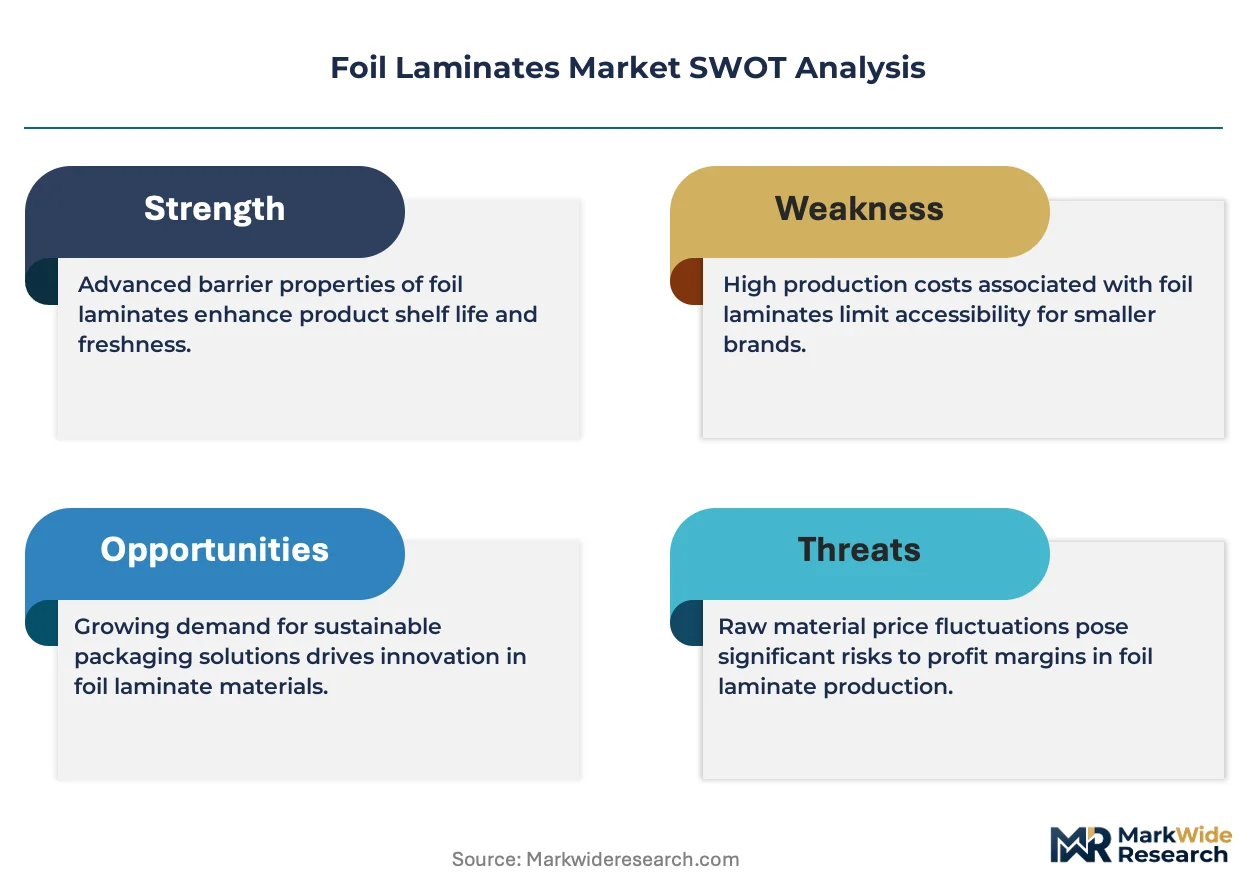
REACH compliance is hardening the cost-of-entry calculus for European foil laminate suppliers. Amcor leverages its integrated film-to-laminate platform to sustain margin stability under evolving chemical disclosure rules. UFlex anchors South Asian supply through captive resin and metallizing assets. Constantia Flexibles differentiates via pharmaceutical-grade cleanroom certification that navigates EMA packaging material guidelines.
Foil laminates bond aluminum foil, polymer films, or paper substrates through extrusion coating or adhesive lamination to create barrier structures with oxygen transmission rates below 0.1 cc/m²/day. These constructions protect moisture-sensitive pharmaceuticals, extend shelf-stable food formats, and shield electronic components from electromagnetic interference. Aluminum foil laminates dominate pharmaceutical cold-form blister applications where zero-light transmission and near-zero moisture vapor transmission justify premium positioning. Composite laminates grow fastest in flexible food pouches as brands replace rigid formats with source-reduced structures. Digital printing technology expands run-length flexibility for short-sku pharmaceutical and specialty food labels.
FDA enforces strict extractables and leachables testing for pharmaceutical foil laminates under container closure integrity guidance, while EPA regulates solvent emissions from adhesive lamination processes. EMA's MDR and EU F-Gas Regulation jointly pressure converters toward water-based adhesives and lower-carbon barrier alternatives. ISO 15378 pharmaceutical packaging materials certification now gates supplier qualification for major drug manufacturers. Stakeholders must monitor how evolving extended producer responsibility frameworks reshape laminate recyclability requirements and material substitution timelines.
Market Dynamics
Pharmaceutical serialization mandates and EU F-Gas Regulation phase-down schedules are compressing converter margins while forcing capital redeployment toward water-based adhesive systems and high-barrier polymer alternatives.
Growth Catalysts
- EMA MDR compliance deadlines:European drug manufacturers are accelerating qualification of ISO 15378-certified laminate suppliers to meet container closure integrity requirements for biologics packaging.
- Cold-chain pharmaceutical expansion:Temperature-sensitive mRNA therapies require foil laminates with ultra-low moisture vapor transmission rates, pulling investment into seven-layer coextrusion capabilities.
- German precision packaging clusters:Concentrated demand from Stuttgart and Munich pharma hubs sustains specialized converter capacity for high-value blister formats.
Market Restraints
- Aluminum ingot price volatility:Primary metal cost swings transmit directly into laminate converter margins, compressing returns on fixed-price pharmaceutical contracts.
- Adhesive solvent regulatory friction:EPA Maximum Achievable Control Technology standards for volatile organic compound emissions are raising compliance costs for solvent-based lamination lines.
- Mono-material substitution threat:Polyethylene and polypropylene barrier films with metallized or SiOx coatings are capturing shelf-stable food applications at lower unit economics.
Strategic Opportunities
- Indian pharmaceutical export growth:CDSCO-aligned packaging material certification is creating first-mover advantage for converters establishing dedicated cleanroom capacity in Hyderabad and Ahmedabad.
- Digital print-to-laminate integration:Short-run pharmaceutical labeling with variable serialization data is opening service-based revenue streams distinct from commodity laminate supply.
- EU Green Deal circularity mandates:Extended producer responsibility frameworks for flexible packaging are rewarding design-for-recycling laminate architectures with preferential producer fee structures.
Industry Challenges
- Cleanroom certification timelines:ISO 14644 Class 8 qualification for pharmaceutical laminate production extends facility commissioning by 14-18 months, tying up capital before revenue generation.
- Extractables and leachables validation backlog:FDA container closure integrity testing protocols create bottlenecks in supplier qualification, delaying new laminate approvals for generic drug launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foil Laminates Market |
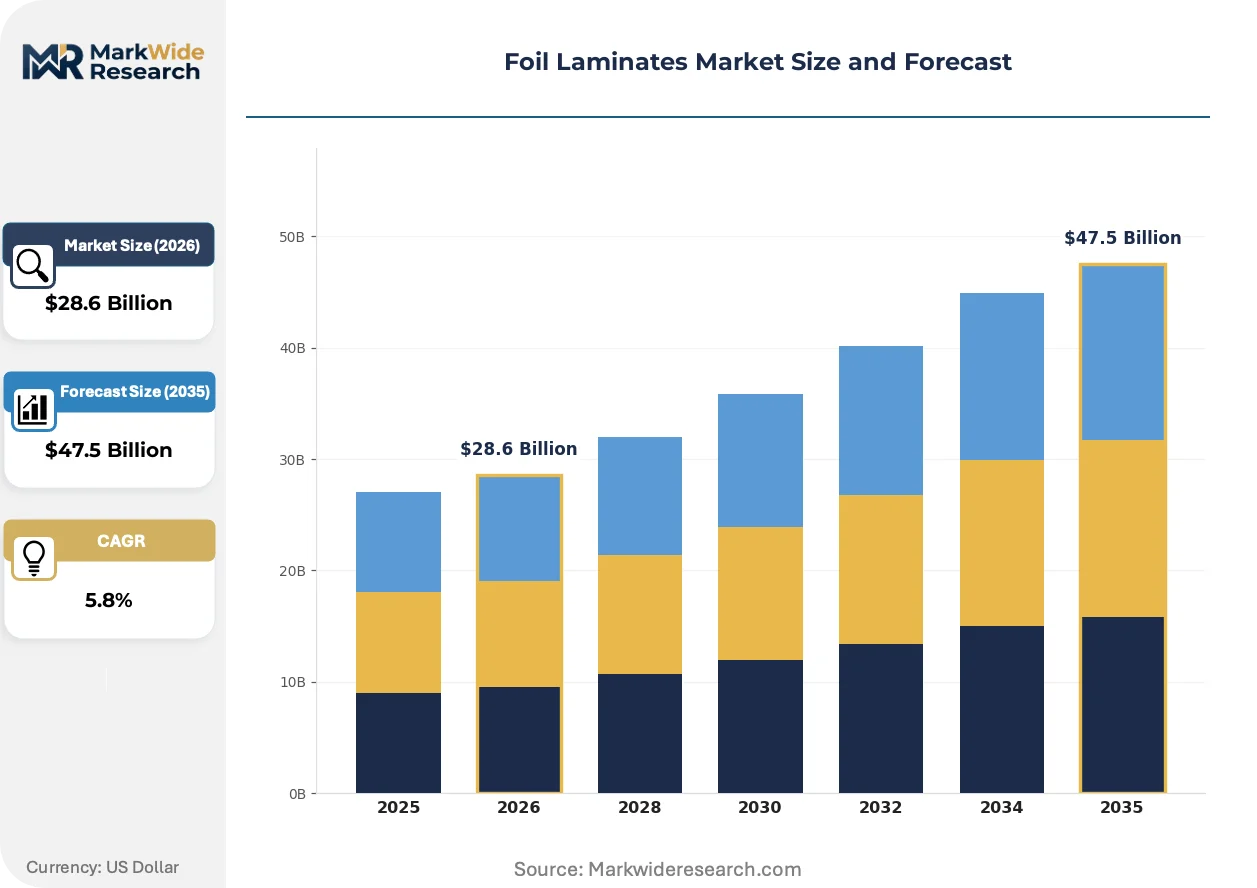
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Foil, Composite Laminates, Plastic Foils, Paper Laminates End Use Industry: Food Packaging, Pharmaceutical, Electronics, Building & Construction Application: Flexible Packaging, Rigid Packaging, Labels, Adhesive Tapes Technology: Extrusion Coating, Cold Lamination, Hot Lamination, Digital Printing |
| Companies Covered | Amcor, UFlex, Huhtamaki, Constantia Flexibles, Mondi, Cosmo Films, Toray Plastics, Hindalco Industries, DUNMORE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foil Laminates Market Emerging Trajectories
Barrier technology substitution and regulatory chemistry restrictions are fragmenting the converter landscape into solvent-free specialists, high-barrier polymer innovators, and integrated film-to-laminate platforms.
Water-based polyurethane adhesive systems are rewriting the competitive economics of pharmaceutical lamination. Mid-size European converters are retrofitting solvent recovery lines to aqueous coating within 24-month payback windows. This transition is compressing the addressable market for conventional solvent-based equipment suppliers while expanding service contracts for adhesive formulation partners.
REACH Article 33 disclosure requirements for substances of very high concern are forcing laminate suppliers to map full material composition through tier-three suppliers. The industrial consequence is accelerated phase-out of certain phthalate plasticizers and bisphenol-based epoxy coatings. German pharmaceutical packaging buyers are now requiring signed compliance attestations before contract renewal, shifting procurement qualification timelines.
Brand-owner sustainability scorecards are driving specification of recyclable mono-material laminates with equivalent barrier performance. Food manufacturers in France and the Netherlands are piloting all-polyethylene pouches with ethylene vinyl alcohol copolymer core layers to replace aluminum foil structures. Retail private-label programs in these markets are capturing shelf space through explicit recyclability claims on packaging.
Foil Laminates Market Segmentation
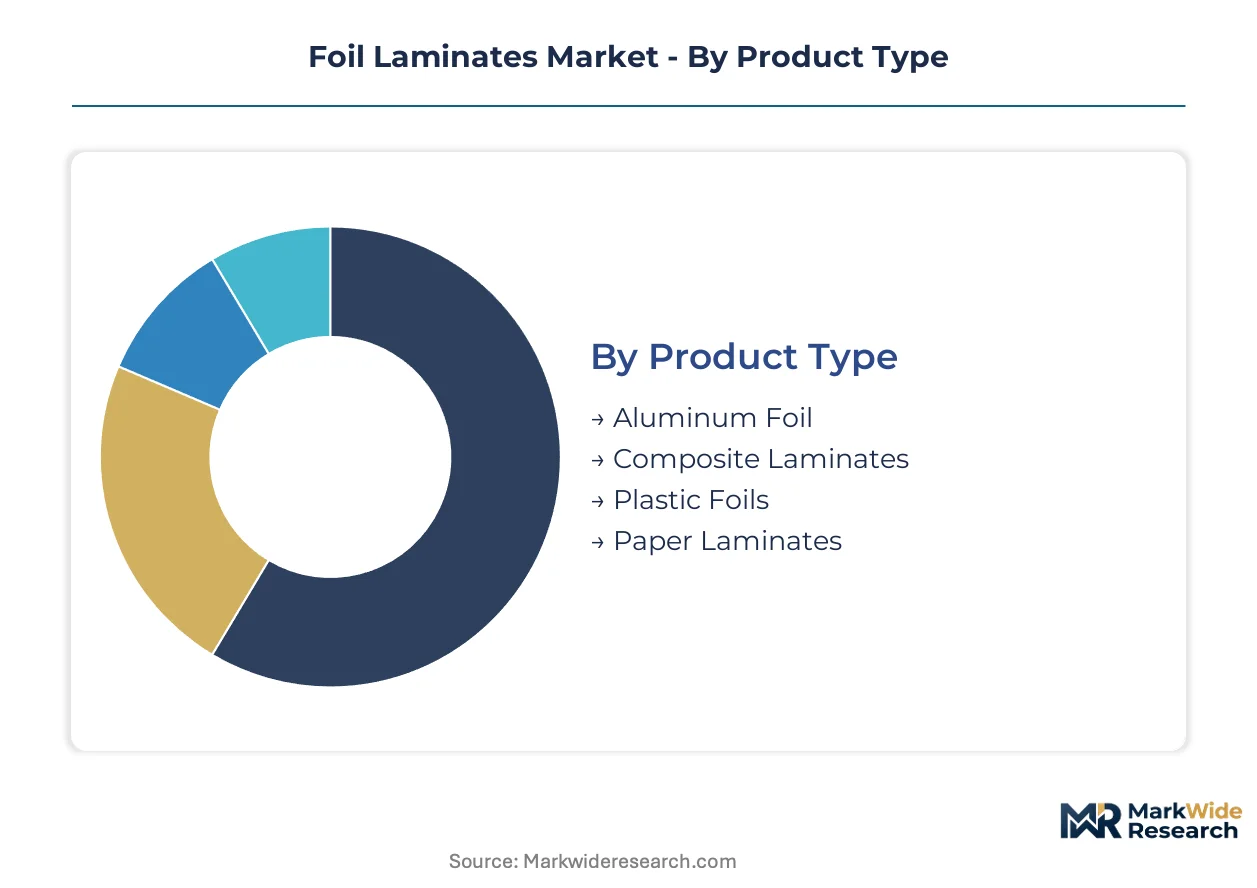
Foil laminate segmentation reveals how substrate choice, end-use requirements, and conversion technology interact to determine margin structure. Each dimension carries distinct regulatory exposure and capital intensity profiles that reshape supplier positioning.
Product Type:
Integration depth varies sharply—aluminum foil operates as standalone barrier material while composite and plastic foils embed into multi-layer structures requiring adhesive or extrusion bonding.
- Aluminum Foil:Pure metal substrate delivers near-zero oxygen and moisture vapor transmission rates through cold-form processing. German pharmaceutical packaging clusters in Stuttgart and Munich sustain demand for zero-light-transmission blister formats under EMA MDR compliance deadlines.
- Composite Laminates:Multi-substrate constructions bond foil, film, and paper through extrusion or adhesive lamination to optimize barrier-to-weight ratios. Food manufacturers in France and the Netherlands pilot these structures to replace rigid formats with source-reduced flexible pouches under EU Green Deal circularity mandates.
- Plastic Foils:Metallized or SiOx-coated polymer films offer barrier performance at lower unit economics for shelf-stable applications.
- Paper Laminates:Fiber-based substrates with foil or film layers serve premium confectionery and tobacco packaging where tactile quality differentiates shelf presence.
Volume placements concentrate in Aluminum Foil; the faster expansion belongs to Composite Laminates.
End Use Industry:
Cost tier stratification separates premium-certified pharmaceutical supply from commodity food and industrial applications with divergent qualification timelines.
- Pharmaceutical:Cold-form blister and strip packaging demand ISO 15378-certified cleanroom production with extractables and leachables validation. Temperature-sensitive mRNA therapies pull investment into seven-layer coextrusion capabilities with ultra-low moisture vapor transmission specifications.
- Food Packaging:Shelf-stable and retort pouch applications drive specification of high-barrier laminates with extended producer responsibility compliance. Retail private-label programs in the Netherlands capture shelf space through explicit recyclability claims on mono-material pouch structures.
- Electronics:Electromagnetic interference shielding for flexible circuits and cable assemblies requires controlled-impedance laminate constructions.
- Building & Construction:Vapor barriers and radiant insulation applications utilize reinforced foil laminates for HVAC and roofing systems.
Revenue concentration sits with Pharmaceutical; Food Packaging climbs fastest on format substitution trends.
Application:
Customer type fragmentation distinguishes brand-direct pharmaceutical specifications from converter-mediated food and industrial demand.
- Flexible Packaging:Pouches, sachets, and flow-wrap structures dominate unit volume across food and pharmaceutical sectors. Digital print-to-laminate integration enables short-run pharmaceutical labeling with variable serialization data for compliance markets.
- Rigid Packaging:Thermoformed trays and formed blisters require deep-draw aluminum foil laminates with precise thickness tolerance.
- Labels:Pressure-sensitive and in-mold constructions utilize foil laminates for premium cosmetic and beverage applications.
- Adhesive Tapes:Industrial masking and HVAC sealing tapes demand high-tack acrylic or rubber-based adhesive systems on foil carriers.
Flexible Packaging commands the largest placement base; Labels gain share fastest on pharmaceutical serialization mandates.
Technology:
Supply concentration clusters around solvent-free and water-based systems as regulatory chemistry restrictions phase out conventional adhesive processes.
- Extrusion Coating:Molten polymer bonding delivers high line speeds and strong adhesion for composite food packaging structures. Mid-size European converters retrofit solvent recovery lines to aqueous coating within compressed payback windows under EPA Maximum Achievable Control Technology standards.
- Hot Lamination:Thermal adhesive activation suits heat-resistant substrates for industrial and building applications.
- Cold Lamination:Pressure-sensitive adhesive systems enable room-temperature bonding for temperature-sensitive films and papers.
- Digital Printing:Inkjet and toner-based imaging integrates directly into laminate production for short-SKU pharmaceutical and specialty food labels with variable data requirements.
Extrusion Coating anchors current capacity deployment; Digital Printing expands most quickly on run-length flexibility demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's pharmaceutical special economic zones in Hyderabad and Ahmedabad concentrate foil laminate demand through export-oriented drug packaging facilities serving regulated markets.
Germany
EMA MDR compliance deadlines accelerate ISO 15378-certified laminate qualification for biologics packaging. The EU F-Gas Regulation forces converter investment into water-based adhesive systems. Stuttgart and Munich precision pharma clusters sustain specialized capacity for cold-form blister formats.
United States
FDA extractables and leachables testing requirements drive container closure integrity investment for generic drug launches. EPA Maximum Achievable Control Technology standards raise compliance costs for solvent-based lamination. New Jersey and North Carolina pharmaceutical manufacturing corridors anchor laminate specification demand.
India
CDSCO-aligned packaging material certification creates first-mover advantage for cleanroom capacity expansion. The PLI scheme for pharmaceuticals incentivizes domestic laminate supply chain development. Hyderabad and Ahmedabad export clusters concentrate dedicated cleanroom investments for regulated market access.
France
EU Green Deal circularity mandates reward design-for-recycling laminate architectures with preferential producer fee structures. ANSM pharmaceutical packaging guidelines tighten material composition disclosure requirements. Paris and Lyon food manufacturing hubs pilot all-polyethylene pouches replacing aluminum foil structures.
China
NMPA pharmaceutical packaging material standards align with international barrier performance benchmarks. Dual carbon goals accelerate solvent-free lamination technology adoption. Yangtze River Delta contract manufacturing clusters integrate foil laminate supply for export pharmaceutical production.
Foil Laminates Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation concentrates among integrated film-to-laminate platforms with captive resin and metallizing assets. Three archetypes dominate: global packaging conglomerates with pharmaceutical certification depth, regional converters with cost-optimized food packaging focus, and aluminum producers with downstream lamination integration. M&A activity targets ISO 15378-certified cleanroom capacity, while capital deployment prioritizes water-based adhesive line retrofits.
Among the integrated packaging conglomerates, Amcor and Mondi occupy positions spanning pharmaceutical-grade certification and food packaging scale. UFlex anchors South Asian supply through captive resin assets. Constantia Flexibles exemplifies the pharmaceutical-specialist archetype with EMA-aligned cleanroom infrastructure. These three represent distinct competitive vectors: global reach, regional vertical integration, and regulatory-specialized certification depth.
| Leading Market Players |
|---|
| Amcor |
| UFlex |
| Huhtamaki |
| Constantia Flexibles |
| Mondi |
| Cosmo Films |
| Toray Plastics |
| Hindalco Industries |
| DUNMORE |
| Others |
Supply Flow & Price Mechanics
London Metal Exchange aluminum ingot pricing cascades through foil laminate supply chains into three distinct procurement tiers: pharmaceutical buyers absorbing premium certification costs, food manufacturers negotiating volume-based contract structures, and industrial purchasers exposed to spot-market volatility.
Pricing Analysis
Short lead-time premiums separate pharmaceutical contract tiers from commodity spot transactions. Three-tier pricing structure across ISO 15378-certified premium, standard food-grade, and economy industrial tiers reflects qualification investment recovery. Price differentiation hinges on cleanroom certification grade and adhesive chemistry compliance under REACH Article 33. Cost compression in standard food-grade laminates is intensifying because mono-material barrier films are displacing aluminum foil structures in shelf-stable applications. Industrial purchasers show highest price sensitivity due to uncontracted spot aluminum exposure, while pharmaceutical buyers prioritize supply security over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with German precision pharma clusters for ISO 15378-certified cold-form blister capacity. Primary aluminum smelting concentrates in China, Russia, and Canada; adhesive resin production centers on Germany, the United States, and South Korea. Raw material dependencies span primary aluminum ingot, polyurethane adhesive formulations, and metallized polyester film substrates. Tariff exposure on Chinese aluminum imports threatens converter margin stability. Distribution runs through converter-direct pharmaceutical supply agreements and distributor-mediated food packaging channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA MDR compliance deadlines have erected a cost-of-compliance moat around ISO 15378-certified laminate production, fragmenting competitive returns between certified incumbents and excluded commodity suppliers.
For Market Incumbents: Cement pharmaceutical certification depth through captive cleanroom capacity expansion in Stuttgart and Munich clusters. Prioritize water-based adhesive line retrofits ahead of EU F-Gas Regulation phase-down deadlines to defend margin position against solvent-free specialists. Backward integration into metallized film production reduces aluminum price volatility exposure for fixed-price pharmaceutical contracts. For New Entrants and Emerging Players: E-commerce-enabled digital print-to-laminate services offer lowest barrier-to-entry for short-run pharmaceutical serialization demand. Target Indian pharmaceutical export corridors in Hyderabad and Ahmedabad where CDSCO-aligned certification creates first-mover advantage before domestic capacity saturation. White-space exists in recyclable mono-material laminate design-for-recycling architectures serving Dutch and French retail private-label programs. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-size European converters with stranded solvent-based assets and established pharmaceutical customer relationships in Germany. Long-term viability hinges on water-based technology transition completion and EMA-aligned regulatory positioning. Watch for aluminum ingot price inflection as signal for contract repricing windows and M&A timing.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Adhesive Line Retrofit | EPA MACT compliance and EU F-Gas Regulation alignment protect converter operating licenses. |
| ISO 15378 Cleanroom Capacity Expansion | EMA MDR deadlines accelerate supplier qualification timelines for biologics packaging contracts. |
| Backward Integration into Metallized Film | Captive polyester metallizing reduces aluminum price volatility transmission into pharmaceutical margins. |
| Digital Print-to-Laminate Service Launch | Short-run pharmaceutical serialization demand opens service-based revenue distinct from commodity supply. |
| Design-for-Recycling Architecture Development | EU Green Deal extended producer responsibility frameworks reward recyclable laminate structures with preferential fees. |
Methodological Framework
Document review covered trade association technical standards, regulatory filing databases, and customs import records, complemented by interviews with converter operations directors, pharmaceutical packaging procurement managers, adhesive formulation specialists, and food manufacturer sustainability officers. Primary fieldwork across Germany, India, and the United States validated secondary data on capacity utilization and certification timelines. Bottom-up demand modeling from end-use consumption patterns triangulated against top-down supply-side capacity assessments.
Segment-level value and volume estimates reflect disaggregation across aluminum foil, composite laminate, plastic foil, and paper laminate product types; pharmaceutical, food packaging, electronics, and building construction end-use industries; and extrusion coating, hot lamination, cold lamination, and digital printing technology categories. CAGRs were derived from regression analysis of historical demand elasticities against projected regulatory compliance deadlines and format substitution trends. Forecast inputs incorporated aluminum price cycle assumptions and pharmaceutical serialization mandate implementation schedules.
The model holds under stable regulatory enforcement intensity and intact pharmaceutical export growth trajectories; deviation in aluminum price volatility spikes or accelerated mono-material substitution would shift laminate demand composition. Forecasts reflect documented assumptions about cleanroom certification timelines and adhesive chemistry transition costs. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Crimped End Mailing Tubes Market
Packaging Materials
EPE Liner Market
Packaging Materials
Bakeable Trays Market
Packaging Materials
Europe Single-Use Packaging Market
Packaging Materials
Single-Use Packaging Market
Packaging Materials
Brazil Packaging Market
Packaging Materials
Global Hot Stamping Foils Market
Packaging Materials
Middle East and Africa Single-Use Packaging Market
Packaging Materials
Twist Tie Market
Packaging Materials
Gift Wrapping Product Market
Packaging Materials
Tertiary Packaging Market
Packaging Materials
Global Adherence Packaging Market
Packaging Materials
Sun Control Films Market
Packaging Materials
Lubricant Packaging Market
Packaging Materials
Cold Seal Films Market
Packaging Materials
Europe Paint Packaging Market