
 Metal Food Cans Market | 2026-2036
Metal Food Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Food Cans Market Outlook
Modular multi-pack configurations is recalibrating how retail buyers procure shelf-stable packaging. Crown Holdings, Inc. leverages its beverage-can manufacturing scale to cross-supply food processors with lightweight steel formats. Ardagh Group anchors European demand through integrated metal supply and recycling infrastructure. Silgan Holdings Inc. differentiates via specialized easy-open ends and shaped containers for premium ready-meals.
Metal food cans are cylindrical containers fabricated from tinplate steel or aluminum, typically featuring interior epoxy or polyethylene coatings and double-seamed lids to achieve hermetic sealing against oxygen and light ingress. They serve as the dominant preservation format for thermally processed foods requiring multiyear shelf stability without refrigeration. Steel cans retain dominant share across vegetable and soup categories due to structural rigidity and compatibility with retort sterilization cycles. Aluminum cans represent the fastest-expanding product type within beverage end uses where weight reduction and chill-response properties command procurement preference. Epoxy coatings continue to face substitution pressure from polyethylene alternatives as REACH restrictions on bisphenol-A migration intensify testing protocols.
The US FDA governs food-contact substance notifications for can coatings under 21 CFR regulations, while EPA oversight of steel mill emissions shapes substrate cost structures for domestic producers. EU REACH and F-Gas Regulation compliance is redirecting R&D expenditure toward non-PVC lining chemistries across European manufacturing footprints. Stakeholders must monitor evolving coating substance restrictions and retort-energy benchmarks to preserve market access and avoid stranded capital in legacy production assets.
Market Dynamics
EU REACH restrictions on bisphenol-A migration are forcing wholesale coating chemistry transitions across European can manufacturing, while retort-energy benchmarks in Germany and France accelerate capital redeployment toward non-epoxy lining systems.
Growth Catalysts
- Canned pet food demand:North American and Western European pet owners are converting to shelf-stable wet food formats, driving steel and aluminum can procurement from protein processors and specialty nutrition formulators.
- REACH compliance R&D:European manufacturers are redirecting technical expenditure toward polyethylene and polyester linings, creating compliant capacity that preserves market access across EU member states.
- German acidic food preference:Food processors in Baden-Württemberg and Bavaria specify epoxy-lined steel cans for sauerkraut, pickled vegetables, and tomato products, anchoring regional substrate demand.
Market Restraints
- Tinplate price volatility:Hot-rolled coil steel and tin coating costs fluctuate with Chinese export policy and energy input prices, compressing margin predictability for can fabricators.
- Aluminum supply concentration:Primary smelting capacity clusters in China, Russia, and the GCC states, exposing European and North American can makers to geopolitical disruption and tariff exposure.
- Retort sterilization energy intensity:Thermal processing cycles for low-acid foods require sustained high-pressure steam, embedding carbon cost liability under EU ETS and national carbon border adjustments.
Strategic Opportunities
- Indian organized retail expansion:Modern trade penetration in Maharashtra, Karnataka, and Tamil Nadu is creating first-mover advantage for shelf-stable packaging suppliers to dairy and ready-to-eat curry processors.
- Easy-open end technology:Full-aperture aluminum ends and ring-pull steel configurations are penetrating premium ready-meal and single-serve soup segments in France and the UK.
- F-Gas Regulation tailwind:EU restrictions on fluorinated greenhouse gases in manufacturing processes are accelerating investment in aqueous-based coating application systems with lower thermal footprint.
Industry Challenges
- Coating chemist scarcity:Formulation expertise in non-BPA polyester and acrylic systems remains concentrated among aging technical specialists in Germany and the Netherlands, constraining scale-up velocity.
- Legacy line conversion capex:Retort-compatible spray coating equipment and modified atmosphere sealing stations require seven-figure capital commitments per production line.
- Migration testing timeline:EFSA and FDA notification protocols for new food-contact substances extend 18-36 months, delaying commercialization of compliant lining innovations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Food Cans Market |
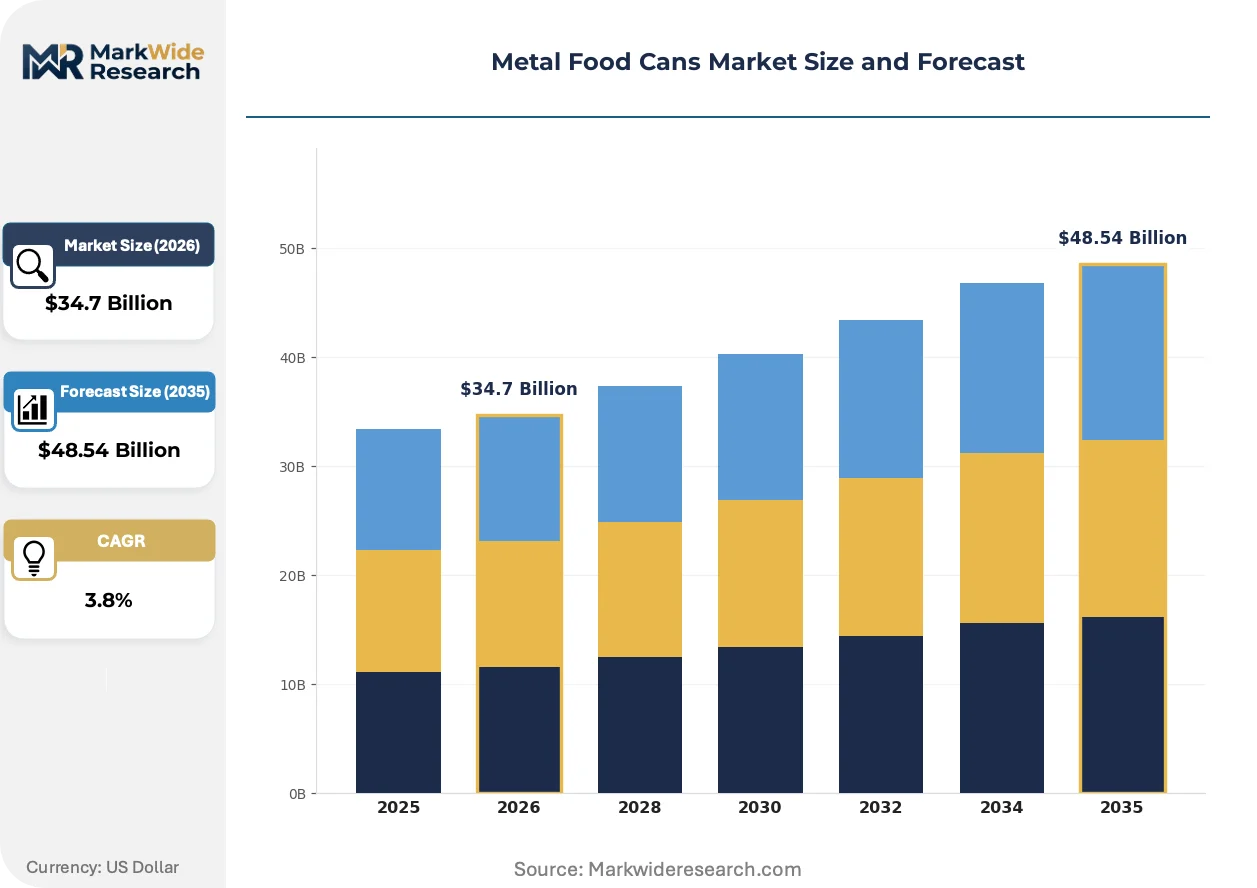
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $48.54 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Cans, Steel Cans, Composite Cans, Specialty Cans End Use: Fruits, Vegetables, Beverages, Soups Capacity: Small, Medium, Large, Extra Large Coating Type: PVC, Epoxy, Polyethylene, Others |
| Companies Covered | Ardagh Group, Can-Pack S.A., Crown Holdings, Inc, Kian Joo Can Factory Berhad, CPMC Holdings Limited, Ball Corporation, Toyo Seikan Group Holdings, Ltd., Envases Group, Silgan Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Food Cans Market Strategic Shifts
Coating chemistry transitions and end-format specialization are fragmenting procurement specifications across food processing verticals, while energy and material compliance pressures reshape manufacturing footprints.
Polyester-based interior linings are overtaking epoxy-phenolic formulations in European acidic food applications. German tomato paste and sauerkraut processors are specifying these alternatives to preempt REACH enforcement actions. The shift is compressing qualified supplier pools and elevating technical service requirements for can makers.
EU F-Gas Regulation phase-down schedules are forcing coating application system redesigns across manufacturing plants in France, Italy, and Spain. Aqueous and UV-cured processes are displacing solvent-based thermal cure systems with fluorinated blowing agents. Pasta sauce and ready-meal canners in Northern Italy are prioritizing suppliers with converted lines to secure supply continuity.
Modular multi-pack configurations are recalibrating retail buyer procurement patterns for shelf-stable proteins and vegetables. Club store and e-commerce channel managers in the United States and Germany are specifying variety-assorted shelf-ready packaging over single-SKU bulk formats. Pet food processors in the Midwest and Pacific Northwest are converting line configurations to accommodate these palletization and shelf-merchandising requirements.
Metal Food Cans Market Segmentation
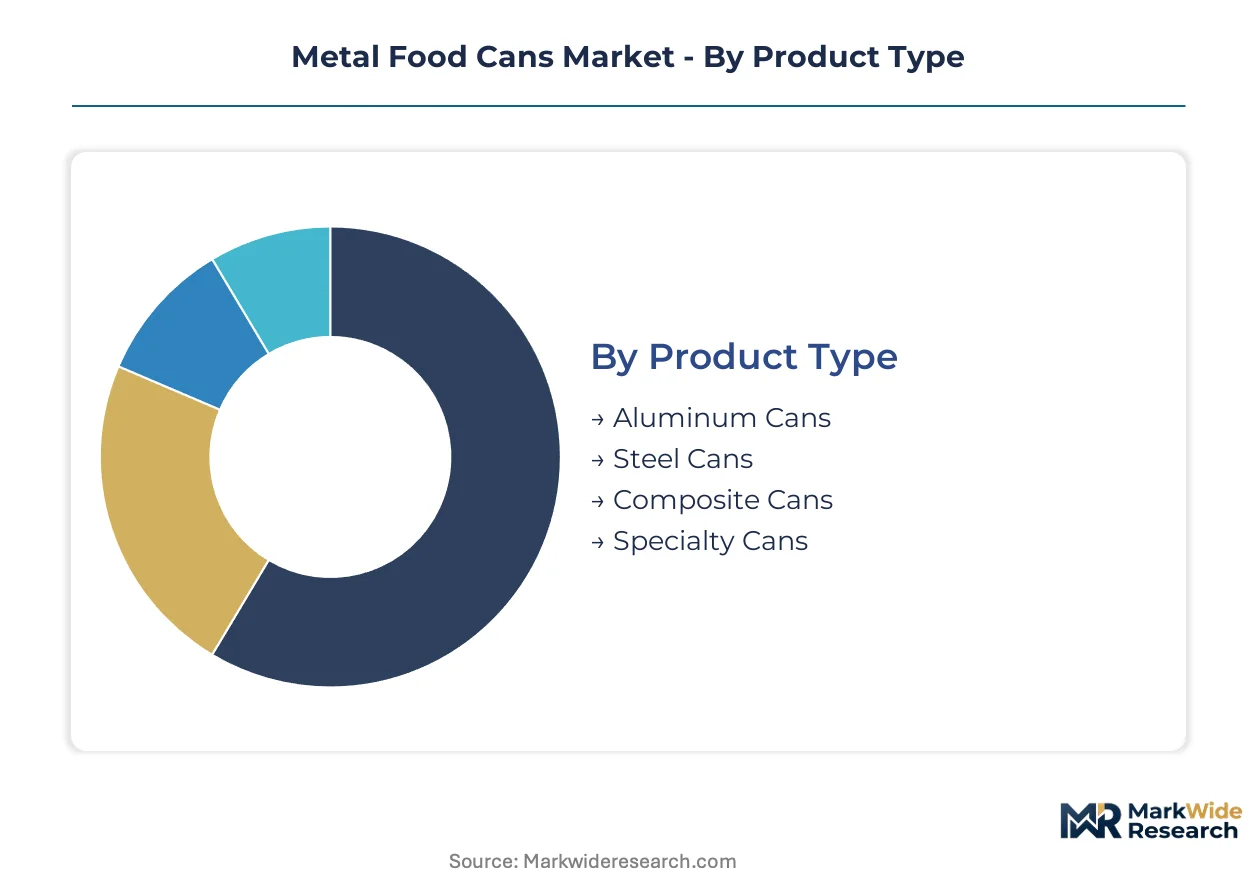
Procurement specifications for metal food cans fragment sharply across substrate chemistry, thermal processing requirements, and retail channel formats. Manufacturers must align production assets with distinct capital intensity profiles and regulatory compliance thresholds to capture volume across diverging end-use verticals.
Product Type:
Steel can fabrication demands the heaviest upfront investment in welding, coating, and retort-compatible seaming equipment, while aluminum and composite formats require different metallurgical and lamination capital stacks.
- Steel Cans:Tinplate or chromium-coated steel substrates deliver structural rigidity for high-pressure retort sterilization cycles. German sauerkraut and tomato paste processors in Baden-Württemberg specify epoxy-lined steel formats to withstand acidic content and thermal shock.
- Aluminum Cans:Lightweight, highly conductive substrates dominate beverage applications where chill-response speed commands procurement preference. North American pet food processors are converting aluminum lines to capture wet-format nutrition demand.
- Composite Cans:Paperboard-body constructions with metal ends serve dry goods and premium gift formats where decoration flexibility outweighs hermetic sealing requirements.
- Specialty Cans:Shaped, embossed, or easy-open configurations target premium ready-meal positioning in French and UK retail channels.
Most installed capacity flows through Steel Cans. Expansion is steepest in Aluminum Cans.
End Use:
Volume concentration and margin structure vary dramatically across thermal processing intensity, acidity levels, and retail channel velocity.
- Vegetables:Low-acid products require sustained high-pressure steam retort cycles, embedding energy cost liability under EU ETS frameworks. French and Italian processors prioritize suppliers with converted aqueous coating lines.
- Soups:Ready-to-serve formats in single-serve and family-size configurations drive demand for easy-open end technology. UK retailers specify full-aperture aluminum ends for premium positioning.
- Fruits:High-acid content permits lighter thermal processing but demands corrosion-resistant interior linings compliant with REACH migration limits.
- Beverages:Carbonated and still drinks favor aluminum for weight reduction and recycling economics, though this segment sits at the edge of traditional food can definitions.
Procurement volume concentrates in Vegetables. Technical innovation investment flows heaviest into Soups.
Capacity:
Line configuration and tooling amortization schedules diverge across format scale, with changeover complexity penalizing mid-size runs.
- Large:Institutional and foodservice formats for soups and vegetables dominate commercial volume, requiring dedicated high-speed seaming lines with minimal SKU flexibility.
- Small:Single-serve portions for premium pet food and ready-meals command per-unit premiums but demand frequent changeovers that compress equipment utilization rates.
- Medium:Standard household sizes for vegetables and fruits balance throughput efficiency with retail assortment breadth.
- Extra Large:Industrial and export bulk formats serve processors with captive canning operations or long-distribution supply chains.
Large-format lines absorb the majority of substrate tonnage. Small-format capacity additions are climbing fastest in North American pet food corridors.
Coating Type:
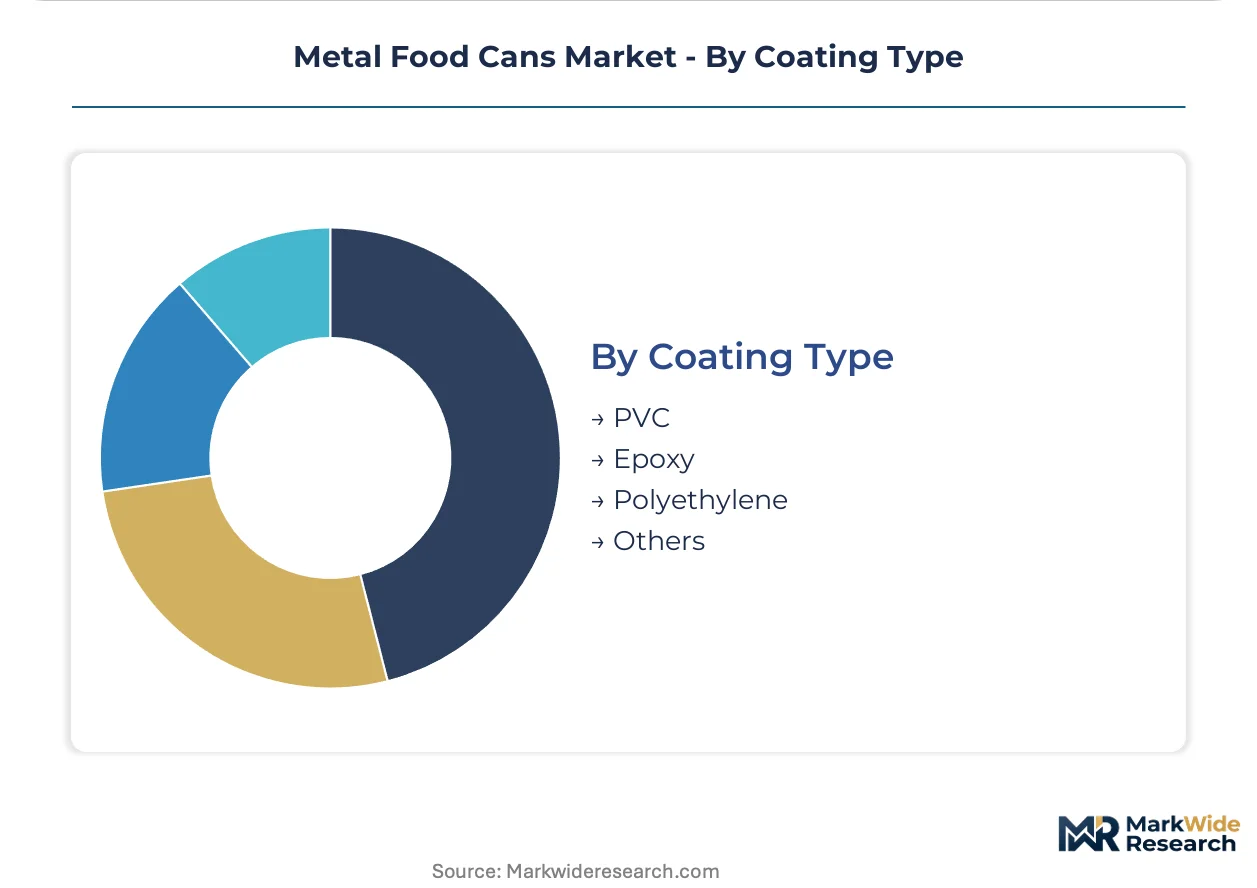
Regulatory pressure on migration limits and fluorinated greenhouse gas emissions is forcing wholesale chemistry transitions with diverging capital reinvestment requirements.
- Epoxy:Phenolic-epoxy systems retain dominant share for acidic foods but face substitution pressure as EFSA tightens bisphenol-A scrutiny. German processors still specify these linings for proven corrosion resistance.
- Polyethylene:Polyester and polyethylene alternatives are capturing share in European acidic applications as REACH compliance becomes non-negotiable. Formulation expertise scarcity in Germany and the Netherlands constrains scale-up velocity.
- PVC:Organosol coatings for aggressive chemical resistance are retreating under F-Gas Regulation phase-down schedules and vinyl chloride monomer concerns.
- Others:Acrylic and hybrid systems occupy niche positions where specific migration profiles or UV-cure compatibility drive specification.
Epoxy retains the largest installed coating base. Polyethylene is gaining share fastest among European can makers retooling for compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The metal food can industry traces its modern scale to nineteenth-century British innovations in tinplate preservation, with German engineering later refining high-volume fabrication techniques that spread across continental Europe and North America.
Germany
Baden-Württemberg and Bavaria host Europe's densest concentration of acidic food processors, with sauerkraut and tomato paste manufacturers specifying epoxy-lined steel formats. ECHA REACH enforcement on bisphenol-A migration is accelerating coating chemistry transitions toward polyester alternatives. Stuttgart-area fabricators are retooling spray application lines to aqueous systems ahead of F-Gas Regulation phase-down deadlines.
United States
Midwestern pet food corridors in Iowa and Nebraska are driving aluminum can procurement as wet-format nutrition demand converts shelf-stable buyers. FDA 21 CFR oversight of food-contact substance notifications shapes coating innovation timelines. Pacific Northwest processors in Oregon and Washington are expanding easy-open end capacity for premium single-serve soup formats.
France
Northern Italian pasta sauce canners are prioritizing suppliers with F-Gas-compliant coating lines to secure supply continuity. EFSA migration testing protocols for new lining chemistries extend commercialization timelines. Lyon-area ready-meal processors are specifying full-aperture aluminum ends for club store variety-pack configurations.
China
Yangtze River Delta steel mills supply tinplate substrate to domestic can fabricators serving export-oriented vegetable processors. SAMR food-contact material standards and GB technical regulations govern interior coating compliance. Shandong Peninsula manufacturers are expanding retort-compatible capacity for seafood and mushroom exports to Japanese buyers.
India
Maharashtra and Karnataka organized retail expansion is creating first-mover opportunity for shelf-stable packaging suppliers to dairy and curry processors. FSSAI food safety standards and BIS material specifications shape import substitution strategies. Tamil Nadu can makers are investing in welded steel lines for tropical fruit pulp exports to Middle Eastern markets.
Metal Food Cans Market Competitive Environment
Premium-margin players sit above commodity-margin players across coating technology specialization and integrated recycling infrastructure. The vendor base clusters around three strategic archetypes: diversified packaging conglomerates with cross-category manufacturing scale, regional metal specialists with captive substrate supply, and technology-focused innovators in easy-open end formats. Consolidation pressure is intensifying through asset-heavy line conversions for REACH compliance, while strategic partnerships between coating chemists and fabricators are accelerating qualified supplier pool formation.
Within the diversified conglomerate tier, Crown Holdings, Inc. and Ardagh Group exemplify scale-driven positioning across beverage and food can cross-supply. Silgan Holdings Inc. occupies a specialist position in premium format innovation. Toyo Seikan Group Holdings, Ltd. anchors Asia-Pacific substrate integration. These three names represent distinct competitive vectors: Crown Holdings leverages North American beverage scale, Ardagh commands European recycling infrastructure, and Silgan targets shaped-container differentiation for ready-meal positioning.
| Leading Market Players |
|---|
| Ardagh Group |
| Can-Pack S.A. |
| Crown Holdings, Inc |
| Kian Joo Can Factory Berhad |
| CPMC Holdings Limited |
| Ball Corporation |
| Toyo Seikan Group Holdings, Ltd. |
| Envases Group |
| Silgan Holdings Inc. |
| Others |
Value Chain & Pricing Dynamics
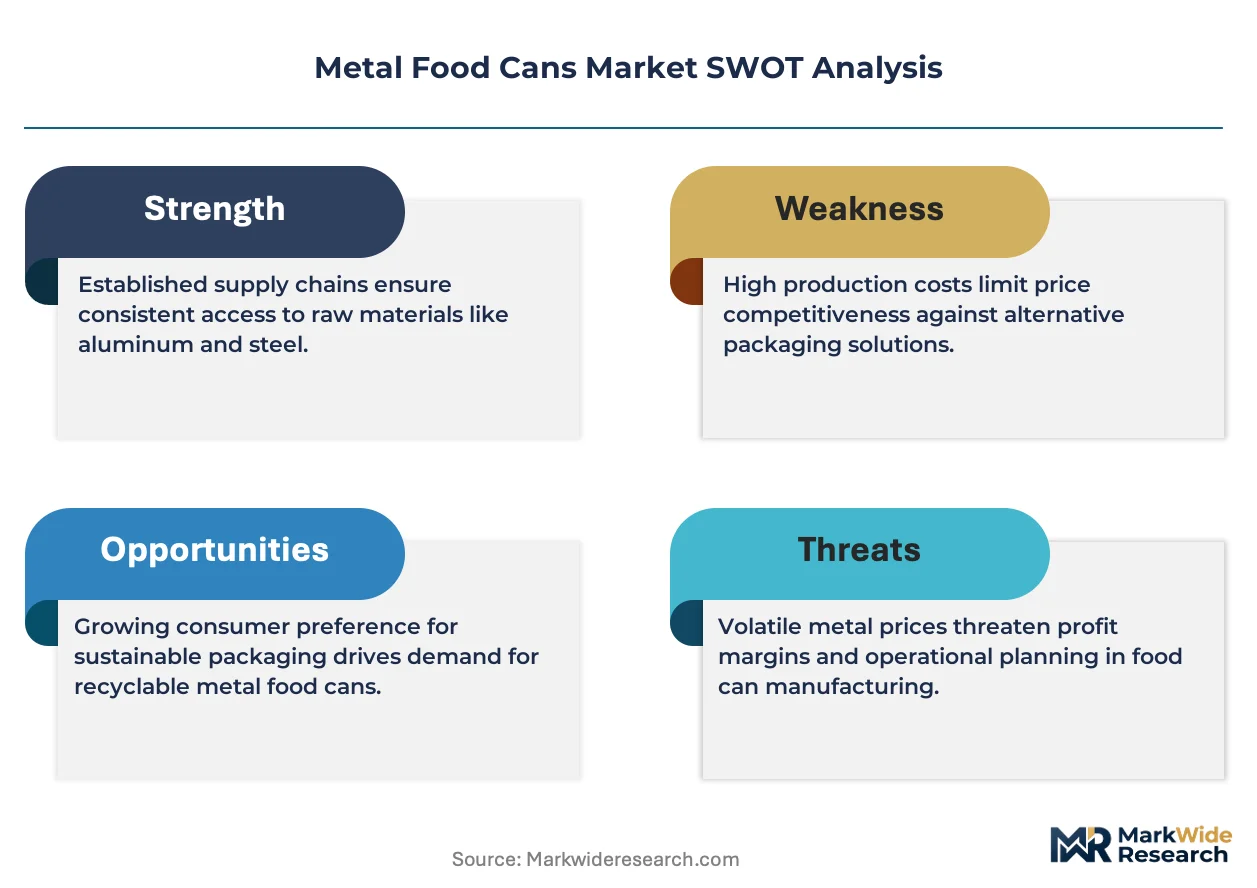
EU F-Gas Regulation phase-down schedules gate qualified supply access and premium-tier pricing power for European can fabricators converting coating application lines. Compliance-ready aqueous and UV-cured systems command procurement premiums from pasta sauce and ready-meal processors in Northern Italy and Lyon-area suppliers, while non-compliant legacy capacity faces stranded asset risk and price erosion.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant polyester-lined formats from legacy epoxy systems and commodity uncoated steel. Price differentiation hinges on coating chemistry certification tier and volume scale commitments from pet food processors. Cost compression in standard-tier epoxy-lined cans is intensifying because EFSA migration testing timelines delay compliant alternative commercialization. Club store buyers in Germany and the United States exhibit highest price sensitivity, while premium ready-meal brands in France show lowest.
Supply Chain Analysis
Tinplate substrate supply rests on Chinese hot-rolled coil steel exports, German cold-rolling capacity in the Ruhr region, and Japanese electrolytic tin coating specialists. Raw material dependencies include tin ingot, chromium for alternative coatings, and epoxy or polyester resin chemistries. Single-source vulnerability concentrates in Chinese primary aluminum smelting and German coating formulation expertise. Distribution runs through integrated metal recyclers in European closed-loop systems and regional can fabricators serving protein processors in the American Midwest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The metal food cans market functions as a stable compounder anchored by shelf-stable pet food demand converting North American and Western European owners from dry to wet nutrition formats.
For Market Incumbents: To counter REACH compliance-driven coating chemistry transitions, Crown Holdings and Ardagh Group should deepen backward integration into aqueous coating application equipment and captive polyester resin supply. Silgan Holdings can defend margin position by controlling easy-open end patent portfolios and expanding shaped-container capacity in French premium ready-meal corridors. For New Entrants and Emerging Players: Capture white-space opportunity in Maharashtra and Karnataka organized retail by supplying welded steel cans to dairy and curry processors ahead of multinational fabricator entry. Target Tamil Nadu tropical fruit pulp exporters with retort-compatible formats for Middle Eastern buyers, leveraging FSSAI compliance as go-to-market credential against unqualified imports. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap European coating specialists with EFSA-qualified polyester formulations because REACH enforcement compresses qualified supplier pools and elevates acquisition multiples for compliant capacity. Watch EFSA bisphenol-A migration limit tightening as inflection signal for accelerated epoxy-to-polyester substitution capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Coating Chemistry Transition | Polyester lining R&D preserves EU market access under REACH bisphenol-A scrutiny. |
| Backward Integration into Substrate | Captive tinplate supply from Ruhr-region steel mills insulates German fabricators from Chinese export volatility. |
| Easy-Open End Patent Expansion | Full-aperture aluminum technology captures premium positioning in UK and French retail channels. |
| Geographic Manufacturing Footprint | Maharashtra and Karnataka production sites secure first-mover advantage in Indian organized retail expansion. |
| Closed-Loop Recycling Infrastructure | Integrated metal recovery systems in Ardagh's European network lower substrate cost and ETS liability. |
Study Parameters
Direct dialogue with coating chemists, can fabrication plant managers, pet food procurement directors, and ready-meal brand technical buyers grounded qualitative insights in operational reality. Secondary validation drew from EFSA migration testing protocols, EPA steel mill emission disclosures, EU ETS carbon cost benchmarks, and SEC filings from Crown Holdings, Silgan, and Ardagh. Bottom-up demand modeling across substrate type, coating chemistry, and end-use vertical triangulated against top-down macroeconomic indicators.
Bottom-up volume builds aggregated procurement patterns from named processor clusters in Baden-Württemberg, Iowa, and Lyon, while top-down constraints applied EU regulatory phase-down schedules and Chinese export policy assumptions across the analysis window. Segmentation dimensions spanned substrate chemistry, thermal processing intensity, coating compliance tier, and retail channel format. CAGRs derived from elasticity-adjusted demand curves incorporating pet food format conversion rates and REACH compliance capex cycles.
EFSA bisphenol-A limit revisions, Chinese tinplate export tariff adjustments, and EU ETS carbon border implementation timing are the dominant revision risks to modeled outcomes. Forecasts embed documented assumptions about coating commercialization timelines and retort energy cost trajectories. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Latin America Metal Packaging Market
Metal Packaging
Cans Market
Metal Packaging
3-Piece Metal Cans Market
Metal Packaging
North America 3 Piece Metal Cans Market
Metal Packaging
France Metal Packaging Market
Metal Packaging
Middle East and Africa Food Cans Market
Metal Packaging
Australia Metal Packaging Market
Metal Packaging
Europe Food Cans Market
Metal Packaging
Metal Packaging Coatings Market
Metal Packaging
Specialty Tin Cans Market
Metal Packaging
Metal Cans Market
Metal Packaging
North America Metal Cans Market
Metal Packaging
Aluminum Foil Market
Metal Packaging
Household Aluminum Foils Market
Metal Packaging
Thailand Metal Packaging Market
Metal Packaging
Aluminum Foil Packaging Market