
 Europe Metal Cans Market | 2026-2036
Europe Metal Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Metal Cans Market Foresight
Market Context
European aluminum sheet producers is rebalancing capacity toward beverage can body stock after years of prioritizing automotive alloys. Ball Corporation leverages its integrated European metal supply network to secure rolling mill access across multiple countries. Crown Holdings, Inc. anchors its position through deep relationships with Central European brewers and soft drink bottlers. Ardagh Group S.A. differentiates via lightweighting technology that reduces metal content per can without sacrificing pressure performance.
Technical Definition and Segment Structure
Europe metal cans are cylindrical containers fabricated from aluminum or tinplate steel, typically featuring double-seamed ends and internal protective linings, designed for hermetic preservation of food, beverages, aerosols, and industrial products. Aluminum cans dominate the beverage channel due to superior recyclability and chill-response properties, while steel cans sustain their food industry position through cost efficiency and compatibility with retort sterilization processes. The beverage end user segment leads volume, driven by craft beer proliferation and sparkling water substitution for plastic bottles. Composite cans represent the fastest-growing product type, capturing personal care and premium gift applications where decoration flexibility outweighs unit cost premiums.
Regulatory Framework
The EU Green Deal and REACH regulations mandate recycled content thresholds and restrict certain epoxy-based can coatings, compelling manufacturers to reformulate internal linings and document supply chain provenance. ECHA substance evaluations and national extended producer responsibility schemes in France, Germany, and Italy shape compliance costs and recycling infrastructure investment requirements. Stakeholders must monitor the interplay between the EU Packaging and Packaging Waste Regulation revisions and national deposit-return scheme expansions to anticipate format mix shifts and margin compression timelines.
Market Dynamics
EU Green Deal packaging circularity mandates are forcing beverage and food manufacturers to abandon plastic formats, redirecting capital toward aluminum can expansion and steel can lightweighting programs across the continent.
Growth Catalysts
- EU Green Deal Packaging Rules:Mandatory recycled content thresholds and extended producer responsibility schemes in France, Germany, and Italy compel brand owners to specify metal formats over multi-material alternatives.
- Deposit-Return Scheme Expansion:National DRS rollouts in Central and Eastern European states create closed-loop economics that favor infinitely recyclable aluminum beverage cans.
- Retort-Compatible Steel Formats:Italian and Spanish food processors sustain demand for tinplate containers capable of withstanding aggressive sterilization temperatures for shelf-stable prepared meals.
Market Restraints
- Aluminum Sheet Supply Concentration:European rolling mill capacity tilts toward automotive alloys, constraining beverage can body stock availability and elongating lead times for can makers.
- Epoxy-Based Coating Restrictions:ECHA substance evaluations under REACH threaten conventional BPA-NI lining chemistries, forcing costly reformulation cycles without drop-in replacements.
- Glass Bottle Resurgence:Premium beer and mineral water segments in Germany and Belgium retain refillable glass loyalty, capping aluminum penetration in high-margin categories.
Strategic Opportunities
- Polish and Romanian Beverage Markets:Underdeveloped canning infrastructure in these high-growth economies offers first-mover positioning for aluminum line investments ahead of DRS implementation.
- Personal Care Aerosol Conversion:REACH restrictions on propellant and packaging combinations push cosmetic brands toward aluminum monobloc cans with compatible valve systems.
- Digital Printing Integration:Direct-to-can decoration technology eliminates label substrates, aligning with EU single-use plastics directives while enabling short-run customization for craft producers.
Industry Challenges
- Linings Chemist Talent Scarcity:Formulation expertise for BPA-alternative epoxy and polyester coatings sits concentrated with a handful of European suppliers, elongating R&D timelines.
- Legacy Seaming Equipment Compatibility:Lightweighted can ends require precise double-seam geometry adjustments that strain older filling lines in Southern European canneries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Metal Cans Market |
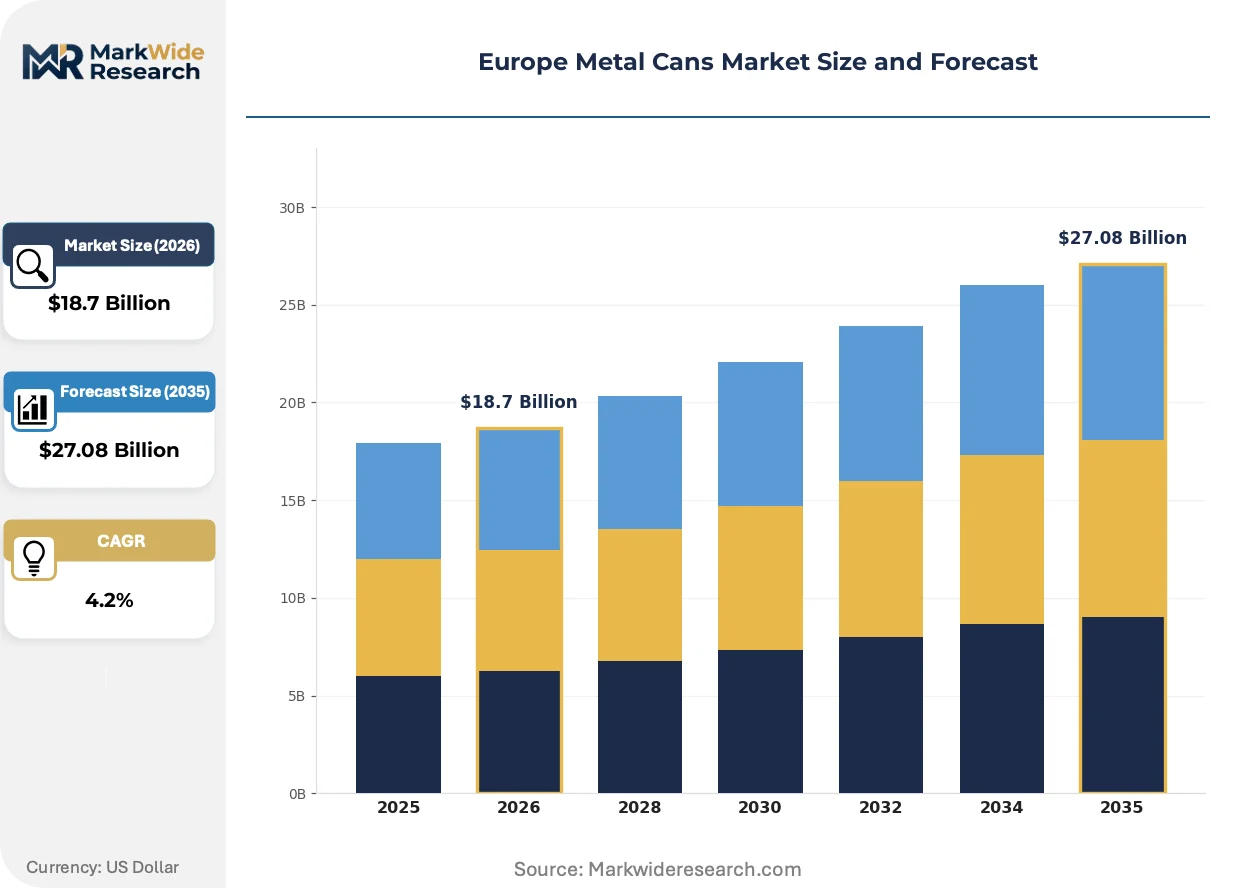
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Cans, Steel Cans, Composite Cans, Biodegradable Cans End User: Food Industry, Beverage Industry, Personal Care, Chemicals Size: Small, Medium, Large, Extra Large Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Direct Sales |
| Companies Covered | Ball Corporation, Crown Holdings, Inc., Ardagh Group S.A., Silgan Holdings Inc., CANPACK S.A., Sonoco Products Co, Trivium Packaging B.V., Mauser Packaging Solutions, Massilly Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Metal Cans Market Shifts & Advancements
Digital manufacturing and regulatory chemistry mandates are compressing product development cycles while opening new format possibilities beyond traditional two-piece beverage and three-piece food cans.
Polymer-based internal linings with non-epoxy chemistries are overtaking conventional BPA-NI coatings in beverage applications. German and Austrian brewers have accelerated qualification timelines for polyester and acrylic alternatives. This transition is overtaking established supply relationships as can makers requalify entire coating portfolios under ECHA scrutiny.
REACH substance evaluations and the EU Packaging and Packaging Waste Regulation revisions are compelling manufacturers to document full supply chain provenance for can coatings and metal substrates. Food processors in Italy now require mill certificates tracing tinplate origin through secondary smelting operations. Small-format beverage can producers face disproportionate compliance burdens relative to their volume scale.
Brand owners in the premium craft beer segment are contracting directly with can decorators for short-run, seasonally rotated artwork rather than committing to annual volume agreements with integrated can makers. Belgian and Dutch brewers lead this disintermediation, leveraging digital printing partnerships that bypass traditional label supply chains. This procurement fragmentation concentrates in markets with dense microbrewery populations and established design agency ecosystems.
Europe Metal Cans Market Segmentation
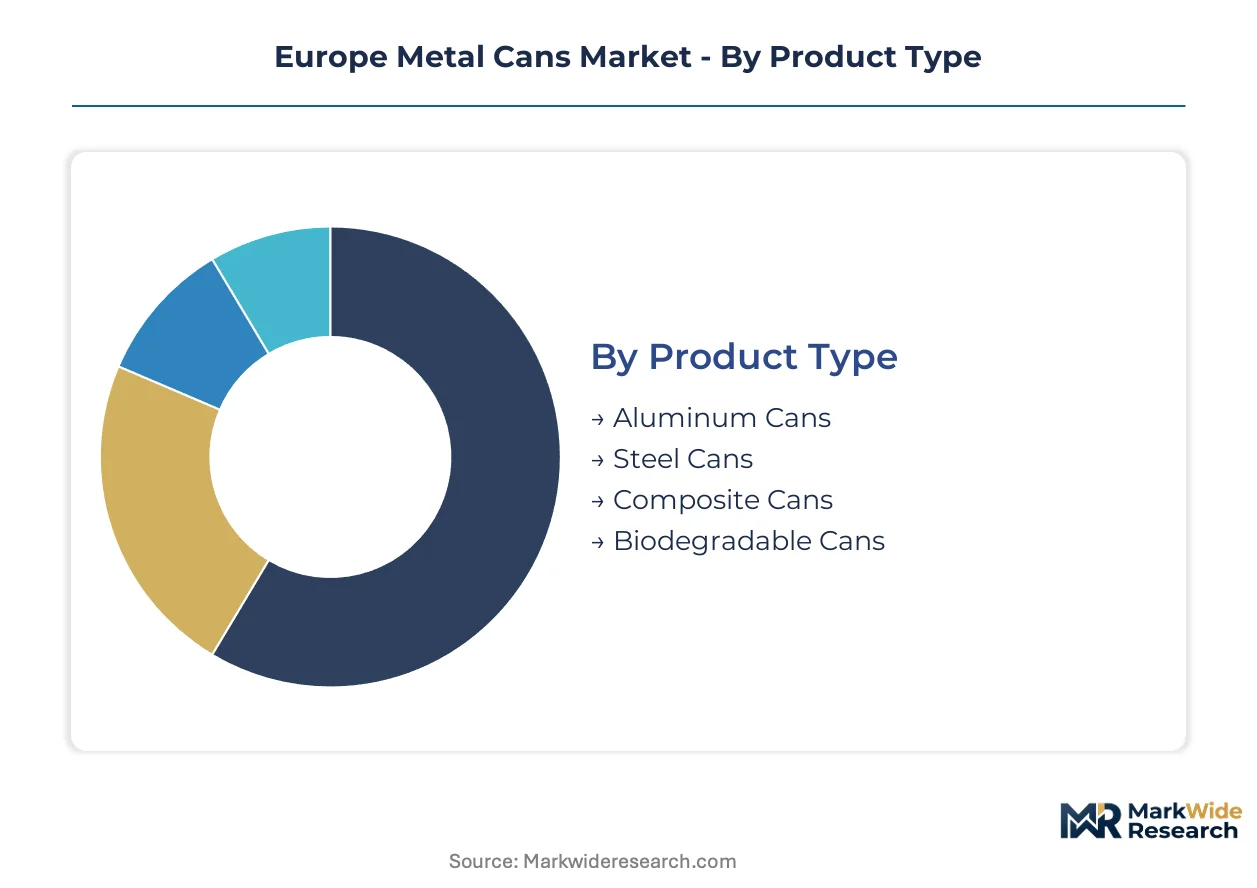
Metal can segmentation in Europe tracks divergent compliance burdens across product formats and end-use channels. REACH coating restrictions and EU Green Deal recycled content mandates fragment specification requirements, forcing manufacturers to maintain parallel qualification streams for beverage, food, and industrial applications.
Product Type:
REACH substance evaluations and the EU Packaging and Packaging Waste Regulation impose distinct certification timelines on each material substrate, with aluminum facing recycled content verification while steel confronts tin coating documentation.
- Aluminum Cans:Two-piece drawn-and-ironed construction dominates beverage applications through superior recyclability and rapid chill response. German and French brewers are expanding aluminum lines as deposit-return schemes create closed-loop economics favoring this infinitely recyclable format.
- Steel Cans:Three-piece welded or two-piece drawn tinplate containers withstand aggressive retort sterilization temperatures required for shelf-stable prepared meals. Italian and Spanish food processors sustain demand for steel formats where cost efficiency and thermal durability outweigh aluminum alternatives.
- Composite Cans:Spiral-wound paperboard bodies with metal ends serve personal care and premium gift applications where decoration flexibility commands unit cost premiums.
- Biodegradable Cans:Experimental formats using bio-based barrier coatings remain pre-commercial, constrained by EFSA food contact approvals and limited European composting infrastructure compatibility.
Leading the category by volume: Aluminum Cans. Growing fastest: Composite Cans.
End User:
End-use segmentation maps directly onto diverging margin structures, with beverage commanding premium pricing for lightweight formats while food tolerates thinner substrates at lower unit economics.
- Food Industry:Retort-compatible tinplate containers preserve shelf-stable vegetables, fish, and ready meals through aggressive thermal processing. Southern European canneries in Italy and Spain concentrate demand for three-piece formats with epoxy-phenolic linings undergoing ECHA requalification.
- Beverage Industry:Aluminum two-piece cans capture carbonated soft drinks, beer, and sparkling water substitution from plastic bottles. Central European brewers in Poland and Romania are accelerating canning infrastructure investment ahead of national deposit-return scheme rollouts.
- Personal Care:Aluminum monobloc aerosol cans with compatible valve systems replace laminate packaging as REACH restricts propellant and packaging combinations.
- Chemicals:Industrial pails and specialty containers require UN certification for hazardous material transport, concentrating demand with specialized steel drum manufacturers.
Volume leadership: Beverage Industry. Steepest expansion trajectory: Personal Care.
Size:
Size segmentation reflects filling line compatibility constraints and retail shelf-space optimization rather than fundamental material differences.
- Small:Single-serve formats (150-250ml) capture energy drinks and premium spirits in travel retail channels.
- Medium:Standard beverage cans (330-500ml) constitute the baseline volume across European supermarkets.
- Large:Family-size food cans (400-800g) align with Southern European household consumption patterns for preserved vegetables and legumes.
- Extra Large:Institutional and foodservice formats (1kg+) concentrate in contract catering and industrial ingredient supply.
Standard medium formats dominate unit volume. Small formats gain share fastest through convenience channel expansion.
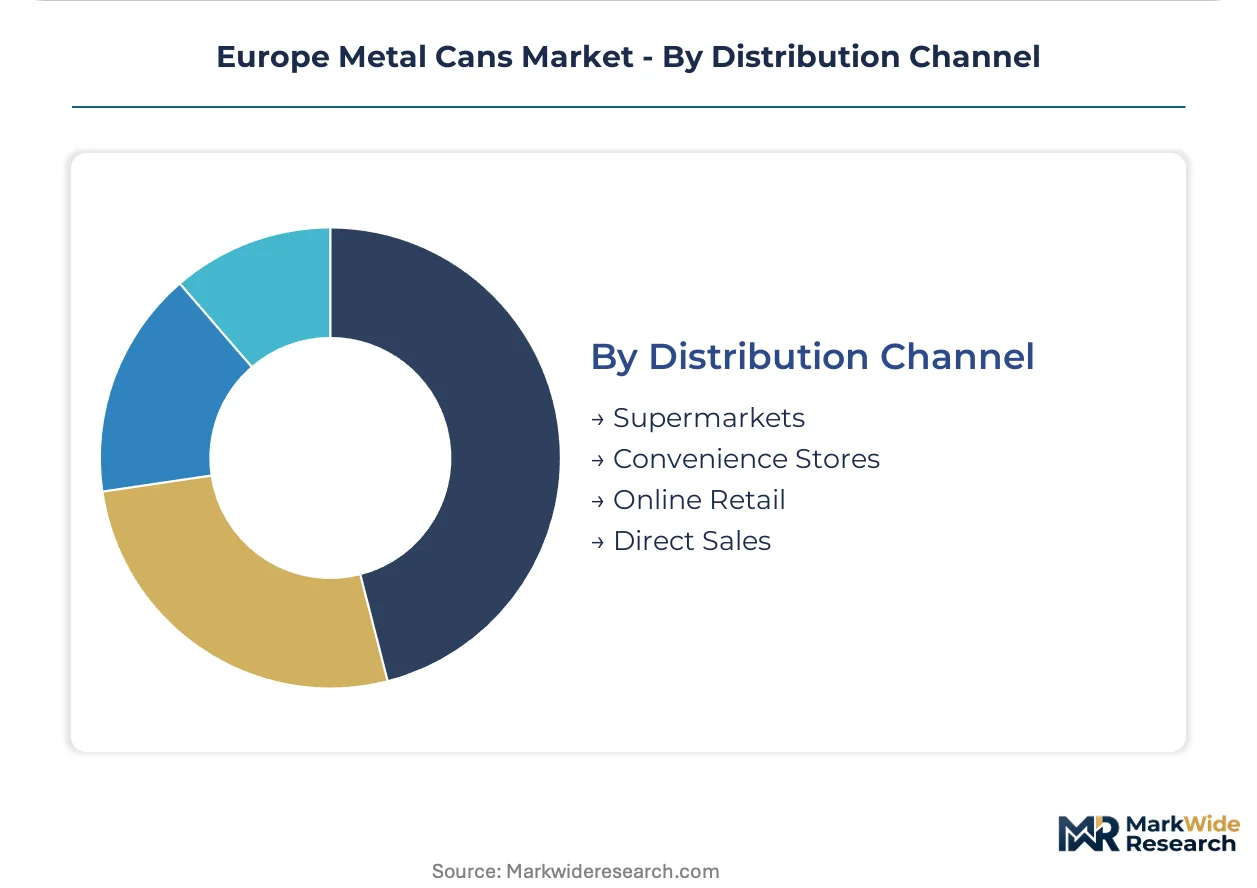
Distribution Channel:
Channel segmentation determines decoration requirements and order lot sizes, with digital printing integration enabling short-run customization for fragmented demand.
- Supermarkets:High-volume standardized formats with annual artwork commitments predominate in this consolidated retail channel.
- Convenience Stores:Smaller lot sizes and regional variant requirements favor flexible manufacturing configurations.
- Online Retail:Direct-to-consumer shipping durability tests lightweight can designs, with secondary packaging innovations compensating for reduced wall thickness.
- Direct Sales:Craft brewers in Belgium and the Netherlands contract directly with can decorators for seasonally rotated artwork, bypassing integrated can maker relationships.
Supermarkets anchor volume concentration. Direct sales expand most quickly through craft beverage disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum rolling mill capacity in Germany anchors European beverage can body stock supply, while Italian tinplate production sustains steel food can demand across Southern Europe. This raw-material geography shapes regional manufacturing investment patterns and regulatory compliance clustering.
Germany
Beverage producers in Bavaria and North Rhine-Westphalia are expanding aluminum canning lines ahead of national deposit-return scheme implementation. The EU Green Deal packaging circularity mandates compel brewers to specify infinitely recyclable formats over plastic alternatives. Rolling mill complexes in the Ruhr region are rebalancing capacity from automotive alloys toward can body stock.
France
Sparkling water bottlers in the Île-de-France and Auvergne-Rhône-Alpes regions are converting from PET to aluminum formats under extended producer responsibility schemes. ECHA substance evaluations are forcing rapid reformulation of internal can linings away from conventional epoxy chemistries. Can manufacturing clusters around Lyon and Paris serve craft beer microbreweries with short-run digital decoration.
Italy
Food processors in Emilia-Romagna and Lombardy sustain demand for retort-compatible steel cans for shelf-stable prepared meals. REACH restrictions on BPA-NI coatings are elongating R&D timelines for tinplate container linings. The Parma cannery corridor concentrates three-piece steel can production for tomato preserves and legumes.
Spain
Andalusian and Murcian vegetable canneries retain strong preference for cost-efficient steel formats despite aluminum alternatives. National packaging waste regulations are tightening recycled content documentation requirements for tinplate substrates. The Murcia agricultural processing zone anchors tomato and artichoke can production.
Poland
Underdeveloped beverage canning infrastructure in the Łódź and Silesian regions offers first-mover positioning ahead of deposit-return scheme rollout. EU Green Deal mandates are redirecting capital from plastic bottling toward aluminum line investments. Warsaw-based distributors are building regional filling capacity for Central European craft brewers.
Europe Metal Cans Market Competitive Landscape
Global majors compete with regional champions across manufacturing scale and coating technology portfolios. The vendor base separates into integrated aluminum specialists, diversified metal packaging conglomerates, and steel-focused food can fabricators. Three archetypes dominate: beverage-can pure-plays with captive rolling mill relationships, multi-material packaging houses balancing aluminum and tinplate exposure, and aerosol monobloc specialists serving personal care conversion. Capacity expansion and strategic partnerships constitute the primary competitive vectors as deposit-return scheme economics reshape procurement patterns.
Among integrated beverage can specialists, Ball Corporation and Crown Holdings exemplify the scale-driven archetype with European rolling mill network access. Ardagh Group occupies a position within the diversified packaging tier, spanning aluminum beverage and steel food formats. These three entities anchor competitive positioning as ECHA coating reformulations and EU Green Deal recycled content mandates compress margin structures across the industry.
| Leading Market Players |
|---|
| Ball Corporation |
| Crown Holdings, Inc. |
| Ardagh Group S.A. |
| Silgan Holdings Inc. |
| CANPACK S.A. |
| Sonoco Products Co |
| Trivium Packaging B.V. |
| Mauser Packaging Solutions |
| Massilly Group |
| Others |
Supply & Pricing Matrix
Coating chemist scarcity in the Rhine-Ruhr industrial corridor widens spreads between premium certified cans and economy-grade alternatives as labor-cost differentials compound raw-material premiums.
Pricing Analysis
Extended producer responsibility compliance bundling separates premium-tier aluminum beverage cans with full coating documentation from unbundled economy steel formats lacking provenance verification. Pricing stratifies across premium, standard, and economy tiers based on REACH certification status and volume-commitment scale. Cost compression in the standard tier intensifies because rolling mill capacity rebalancing elongates lead times for can body stock. Small-format craft brewers exhibit highest price sensitivity while multinational beverage conglomerates absorb premiums for closed-loop supply guarantees.
Supply Chain Analysis
Deposit-return scheme logistics create reverse-collection flows that feed directly back into German and French smelter networks for closed-loop aluminum regeneration. Primary supply draws from German rolling mills, Italian tinplate producers, and Spanish secondary steel processors. Raw-material dependencies center on aluminum ingot, tin-coated steel sheet, and BPA-alternative epoxy resins. Single-source vulnerability concentrates in European coating-chemist talent pools concentrated around Basel and Ludwigshafen. Distribution runs through integrated can maker networks serving consolidated retail channels alongside direct-to-brewery decorator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
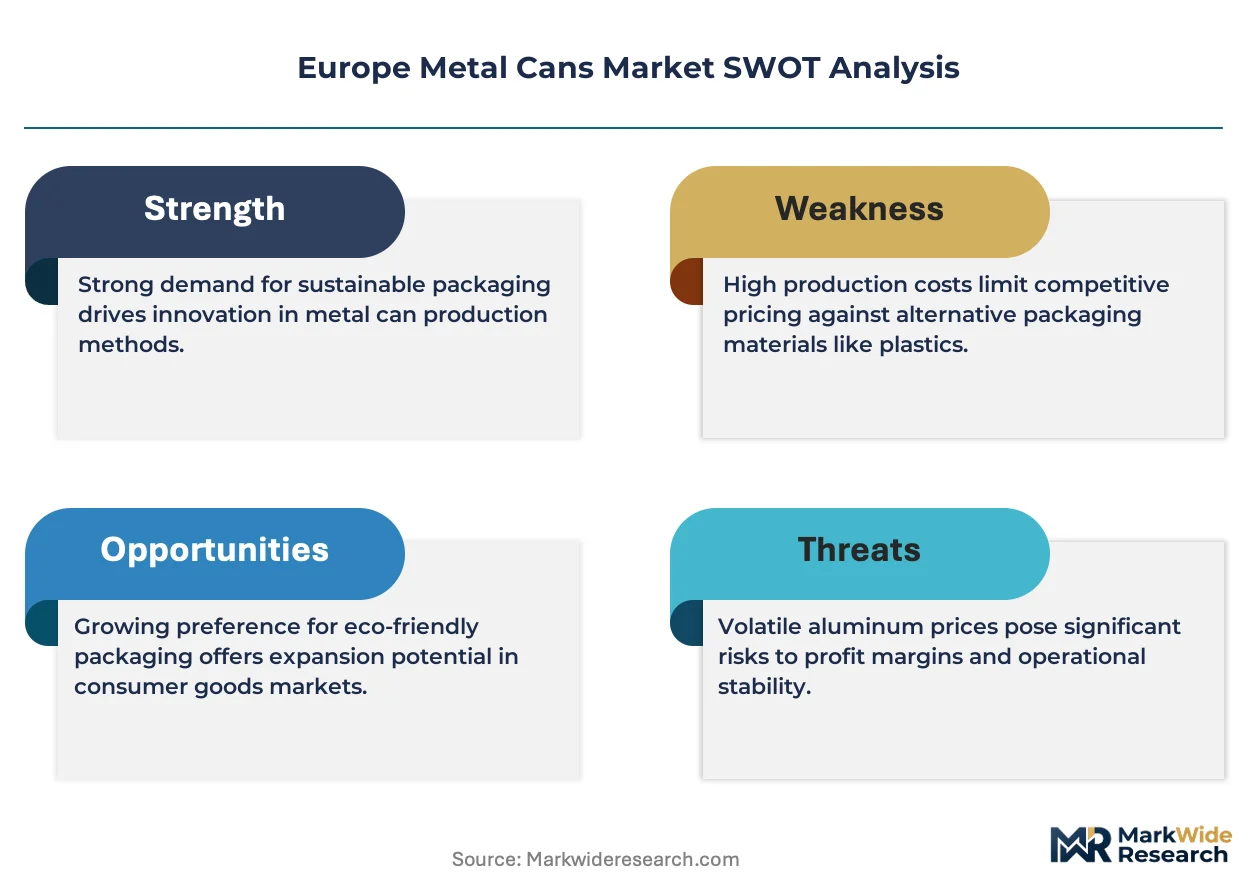
EU Green Deal compliance costs are forcing sub-scale can makers toward exit or acquisition as margin compression eliminates players lacking captive coating R&D capabilities.
For Market Incumbents: Lock in rolling mill capacity allocations through multi-year offtake agreements before automotive alloy demand rebounds. Acquire distressed coating-chemist teams from exiting competitors to consolidate BPA-alternative formulation expertise. The threat of glass bottle resurgence in German premium beer segments demands lightweighting investment to preserve aluminum's cost position. For New Entrants and Emerging Players: Polish craft brewers represent the most penetrable buyer archetype as underdeveloped canning infrastructure meets accelerating deposit-return scheme rollout. Romanian mineral water bottlers offer parallel white-space opportunity ahead of national DRS implementation. Pursue digital printing partnerships to bypass integrated can maker relationships and capture short-run customization demand. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap coating specialists given ECHA substance evaluation timelines that elongate qualification barriers. Five-to-ten-year viability favors targets with proven polyester and acrylic lining portfolios already deployed in commercial volumes. Monitor German deposit-return scheme implementation velocity as the inflection signal for aluminum demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating R&D | Captive BPA-alternative formulation capability insulates against ECHA-driven supply disruption. |
| Poland-Romania Capacity Expansion | First-mover positioning ahead of Central European deposit-return scheme economics activation. |
| Digital Printing Partnership | Direct-to-can decoration bypasses label substrates and aligns with EU single-use plastics directives. |
| Lightweighting Technology Investment | Reduced metal content per can preserves margin compression threatened by aluminum sheet premiums. |
| Closed-Loop Recycling Network | DRS-integrated collection systems secure infinitely recyclable aluminum supply for brand owner commitments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with can manufacturing executives, coating R&D directors, beverage procurement leads, and food industry packaging managers provided operational validation. Secondary sources encompassed ECHA substance evaluation databases, EU Packaging and Packaging Waste Regulation revision drafts, national extended producer responsibility scheme filings, and rolling mill capacity announcements. Bottom-up volume modeling triangulated against top-down macroeconomic drivers across the analysis window.
Granularity-level modeling distinguished aluminum versus steel substrate economics, beverage versus food end-use margin structures, and national regulatory implementation timelines. Segmentation dimensions spanned product type, end-user industry, format size, and distribution channel across country-level clusters. CAGRs derived from volume trajectory analysis incorporating capacity expansion announcements and substitution elasticity parameters. Forecast inputs included deposit-return scheme rollout schedules and REACH coating restriction phase-in timelines.
Revisions become necessary when ECHA substance evaluation timelines accelerate, EU Packaging and Packaging Waste Regulation recycled content thresholds shift, or aluminum rolling mill capacity rebalancing diverges from modeled assumptions. Practitioners should monitor German and French deposit-return scheme implementation rates and coating chemist labor market tightness for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Asia Pacific Metal Cans Market
Metal Packaging
North America Aluminium Cans Market
Metal Packaging
Metal Containers Market
Metal Packaging
Cans Market
Metal Packaging
Global Laminated Steel for Cans Market
Metal Packaging
Metal Food Cans Market
Metal Packaging
PTP Aluminum Foil Market
Metal Packaging
Novelty Tins Market
Metal Packaging
Middle East and Africa Metal Cans Market
Metal Packaging
United Kingdom Metal Packaging Market
Metal Packaging
Metal Aerosol Packaging Market
Metal Packaging
United Arab Emirates Metal Packaging Market
Metal Packaging
Metal Aerosol Can Market
Metal Packaging
Tinplate Packaging Market
Metal Packaging
Pressurized Metal Containers Market
Metal Packaging
Tin Cans Market