
 USB Charger Market | 2026-2036
USB Charger Market Size, Share, and Industry Trends Forecast 2026-2036
USB Charger Market Outlook
Subscription-based firmware updates for power delivery profiles is pivoting how charger vendors monetize hardware. Anker Innovations Limited leverages its charging technology stack to sustain premium positioning across multiple voltage tiers. Samsung anchors its ecosystem strategy through proprietary Super Fast Charging protocols that lock in device loyalty. Baseus competes on design velocity, releasing form-factor variants that occupy shelf space faster than incumbents refresh lines.
A USB charger converts alternating current from wall outlets or direct current from vehicle ports and batteries into regulated low-voltage direct current suitable for rechargeable devices, typically outputting 5V to 48V with wattage ratings from 5W to 240W depending on the power delivery protocol implemented. Wall chargers generate the largest revenue pool due to universal household penetration, while power banks represent the fastest-expanding category as mobile work patterns extend time-away-from-outlet requirements. Power Delivery technology leads protocol adoption among laptop and tablet segments, whereas Quick Charge dominates the installed base of mid-tier Android smartphones.
The EU's Common Charger Directive and Ecodesign regulations mandate interoperability and efficiency thresholds that reshape product roadmaps for any vendor accessing European consumers. The FCC in the United States governs electromagnetic emissions from switching power supplies, while China's GB standards enforce safety and efficiency benchmarks for domestic production and export certification. Stakeholders must monitor how regional efficiency mandates and protocol standardization timelines reshape which charging technologies retain compatibility advantages versus which become stranded investments.
Market Dynamics
USB-C protocol unification is compressing charger variety into interchangeable hardware, eroding proprietary lock-in while Shenzhen manufacturing clusters capture economies of scale across voltage tiers.
Growth Catalysts
- EU Common Charger Directive:Mandated interoperability eliminates fragmented cable inventories and reduces consumer replacement friction across member states.
- Power Delivery 3.1 protocol:Extended Power Range specifications enable single-cable charging for laptops up to 240W, collapsing adapter count in mobile workstations.
- Shenzhen component ecosystem:Dense supplier networks for GaN semiconductors and magnetic components compress development cycles and BOM costs.
Market Restraints
- GaN wafer supply concentration:Limited foundry capacity for gallium nitride substrates creates input bottlenecks during demand surges.
- Legacy USB-A installed base:Billions of functioning micro-USB and Type-A ports slow replacement cycles in emerging markets.
- RoHS compliance costs:Lead-free soldering and restricted substance testing add certification overhead for low-margin SKUs.
Strategic Opportunities
- India BIS certification pipeline:Mandatory quality registration for electronics imports creates first-mover advantage for compliant vendors in fast-urbanizing tier-2 cities.
- Vehicle USB-C integration:Automotive OEMs are embedding 100W+ charging ports as standard cabin features, opening aftermarket retrofit demand.
- Subscription firmware services:Power profile updates delivered over-the-air enable recurring revenue attachment to hardware margins.
Industry Challenges
- Thermal engineering talent scarcity:GaN switching frequencies demand specialized magnetics design expertise concentrated among Taiwanese and Korean engineering pools.
- Multi-protocol certification stacking:Simultaneous USB-IF, Qualcomm Quick Charge, and proprietary vendor program approvals extend time-to-revenue by quarters.
- Reverse logistics complexity:E-waste directives in Germany and France mandate take-back infrastructure that smaller vendors struggle to operationalize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USB Charger Market |
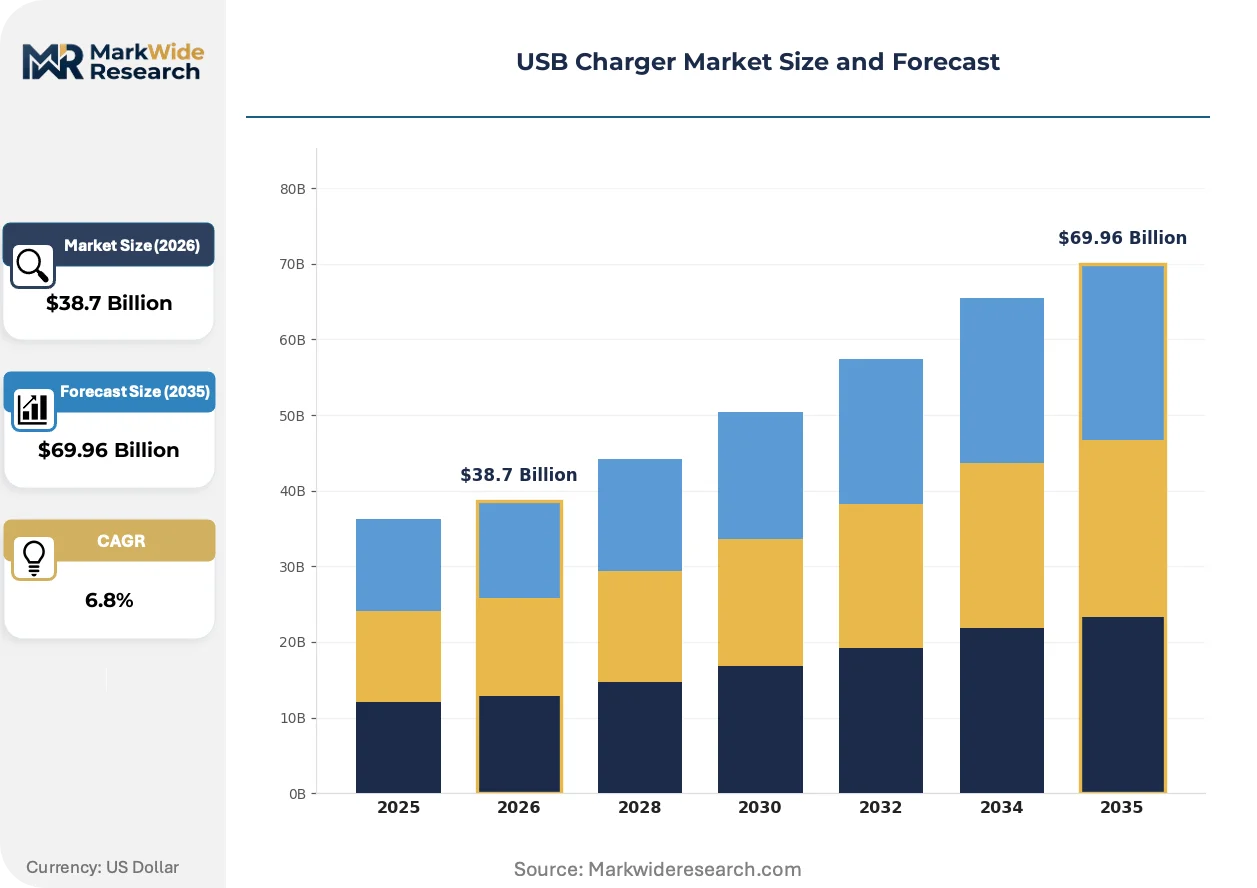
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall Charger, Car Charger, Wireless Charger, Power Bank Technology: Fast Charging, USB-C, Quick Charge, Power Delivery End User: Consumer Electronics, Automotive, Enterprises, Healthcare Distribution Channel: Online Retail, Offline Retail, Wholesalers, Direct Sales |
| Companies Covered | Anker Innovations Limited, Apple, Samsung, Belkin International, Xiaomi, Huawei, Baseus, RAVPower, BULL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USB Charger Market Strategic Shifts
Gallium nitride semiconductors and intelligent power negotiation chips are redefining thermal and spatial constraints, while regulatory pressure on interoperability accelerates hardware commoditization.
GaN-on-silicon power ICs are decentralizing thermal management away from bulky heatsinks toward compact planar magnetics. Laptop OEMs now specify 65W adapters under 60 cubic centimeters, collapsing the physical envelope that previously differentiated premium from standard tiers. This compression is decentralizing value capture from enclosure engineering toward semiconductor and firmware layers.
REACH substance restrictions and EU Ecodesign efficiency tiers are mandating standby power below 0.5W and active-mode minimums that obsolete older controller architectures. Vendors must redesign flyback topologies or exit European distribution. The directive hits low-cost wall charger imports hardest, consolidating shelf presence among firms with in-house compliance teams.
Enterprise procurement of charging infrastructure is consolidating around managed service contracts bundling hardware, installation, and firmware lifecycle support. Facility managers in US commercial real estate now specify port density and usage analytics over unit economics. This shift concentrates purchasing authority with integrated workplace technology providers rather than retail channel fragmentation.
USB Charger Market Segmentation
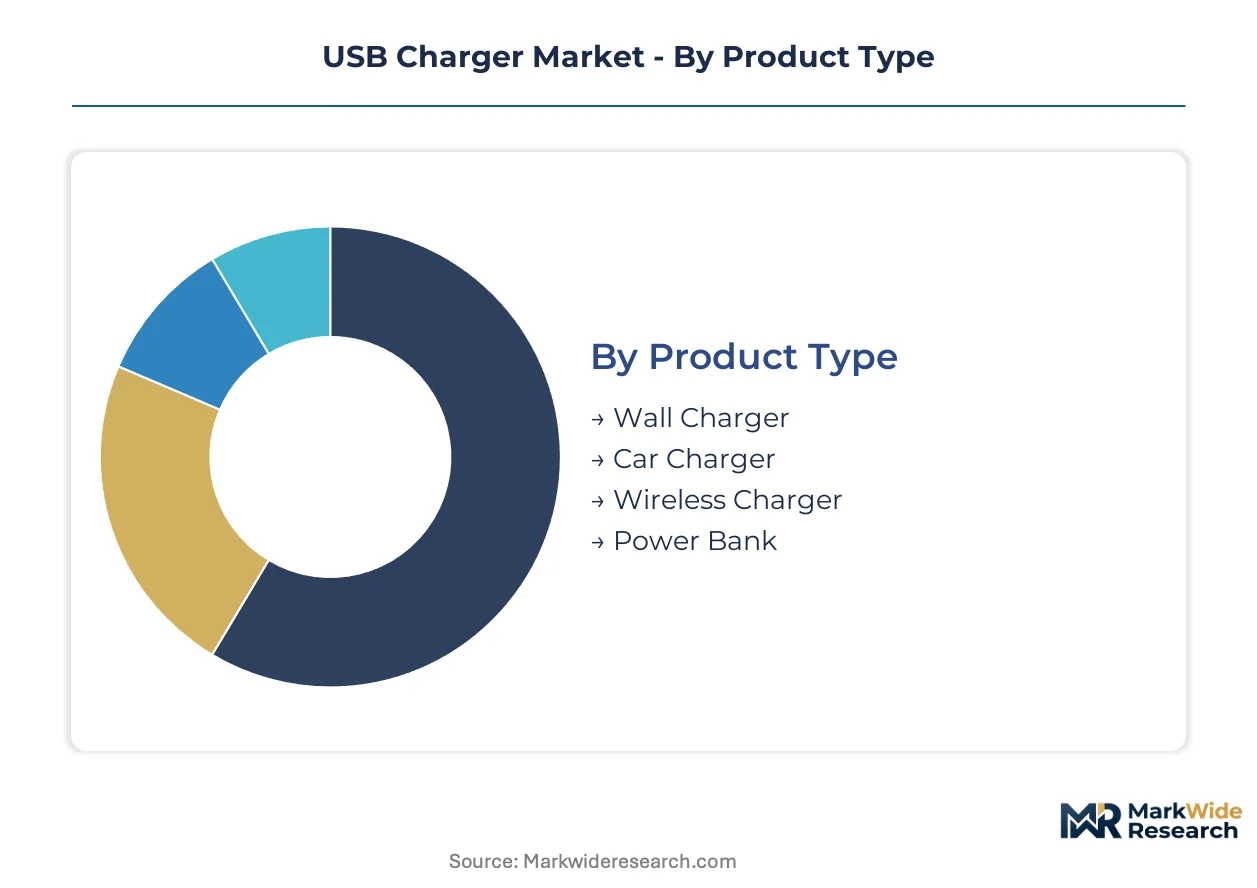
USB charger segmentation reveals how power delivery architectures split between standalone accessories and embedded systems. Product type and technology categories determine whether vendors capture consumer replacement cycles or long-term OEM supply contracts.
Product Type:
Standalone chargers dominate household and mobile use cases, while embedded variants integrate directly into vehicle cabins and furniture infrastructure.
- Wall Charger:AC-to-DC adapters with GaN semiconductors now achieve 65W output in sub-60cc enclosures. Shenzhen manufacturing clusters supply the majority of global volume for residential and office desk deployments where outlet density drives replacement demand.
- Power Bank:Lithium-polymer or lithium-ion battery packs with bidirectional charging capability extend device runtime away from grid access. Mobile workforce expansion across India and Southeast Asia pushes capacity requirements toward 20,000mAh+ configurations.
- Car Charger:Cigarette lighter adapters delivering 12V-to-5V conversion for vehicle cabins.
- Wireless Charger:Inductive charging pads using Qi protocol for smartphone and wearable topping.
Volume placements concentrate in Wall Charger; the faster expansion belongs to Power Bank.
Technology:
Protocol differentiation separates premium pricing tiers from commodity hardware, with certification requirements fragmenting vendor roadmaps.
- Power Delivery:USB-IF standard enabling 240W Extended Power Range through single USB-C cables. Laptop OEMs in the United States and Germany now specify PD 3.1 as baseline for workstation adapter bundles, collapsing multi-cable inventories.
- Fast Charging:Umbrella term encompassing proprietary vendor protocols and licensed implementations. Chinese smartphone brands push 100W+ configurations through MIIT-certified adapters, creating protocol lock-in that slows interoperability adoption.
- USB-C:Connector standard mandated by EU Common Charger Directive for universal interoperability.
- Quick Charge:Qualcomm-licensed protocol dominating mid-tier Android installed base.
Certification stacking burdens Power Delivery most heavily; USB-C gains share fastest as regulatory deadlines approach.
End User:
Demand concentration shifts from individual consumers toward institutional procurement with lifecycle management requirements.
- Consumer Electronics:Individual purchasers replacing smartphone and laptop adapters. Replacement cycles compress in China and South Korea where OEM bundled chargers decline and aftermarket volume surges.
- Enterprises:Facility managers specifying charging infrastructure for commercial real estate and logistics fleets. US workplace technology providers now bundle hardware with usage analytics and firmware update subscriptions.
- Automotive:OEM embedded ports and aftermarket retrofit demand.
- Healthcare:Medical-grade isolated power supplies for patient-contact equipment.
Enterprise procurement is climbing the fastest; Consumer Electronics retains the largest placement base.
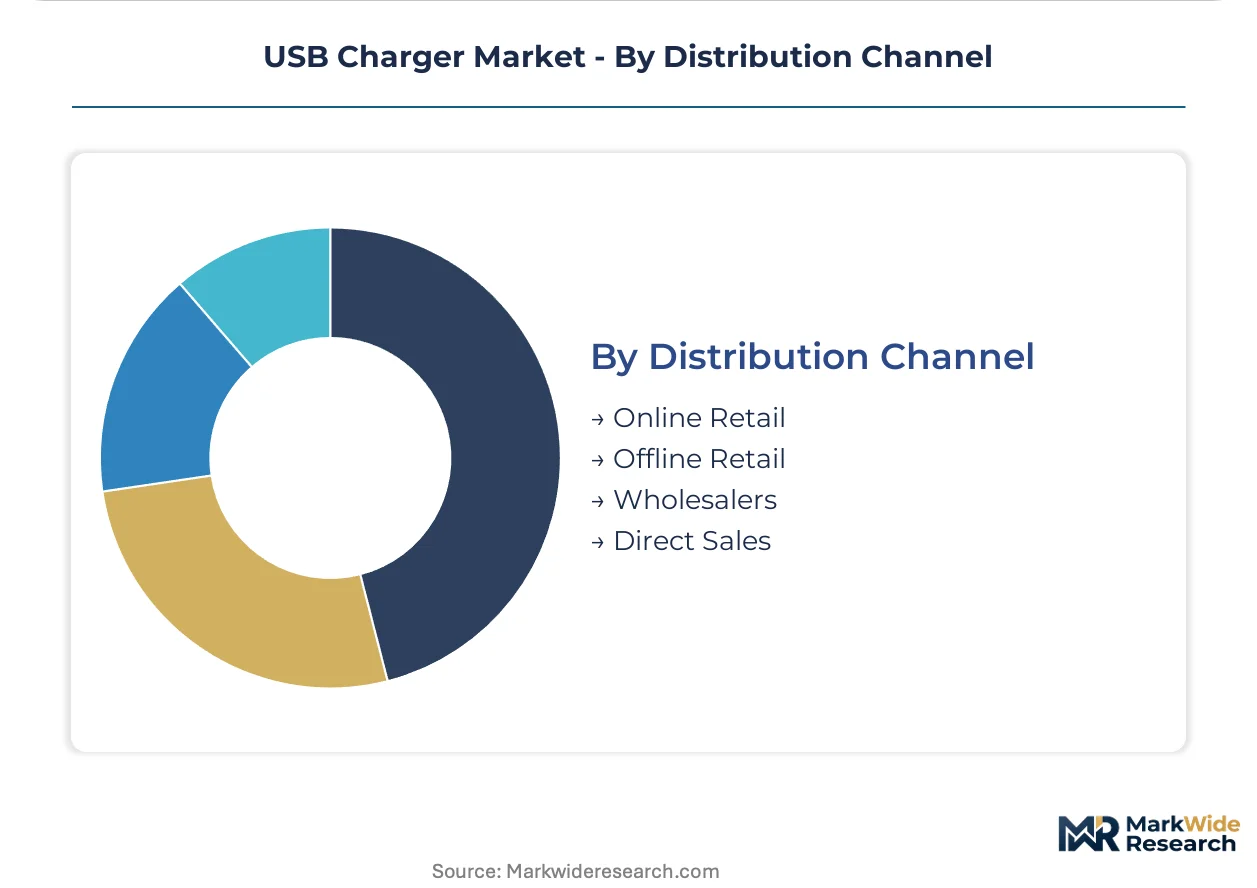
Distribution Channel:
Channel selection determines margin capture versus volume scale, with digital platforms eroding traditional retail gatekeepers.
- Online Retail:E-commerce platforms and direct-to-consumer storefronts. Amazon and Tmall capture the majority of replacement charger volume in the United States and China, compressing brand markup through price transparency.
- Offline Retail:Electronics specialty stores and mass merchant shelf space. European electronics retailers in Germany and France maintain charger presence through impulse placement near checkout, though EU Ecodesign compliance costs push smaller vendors toward online-only distribution.
- Wholesalers:B2B bulk procurement for enterprise and educational deployments.
- Direct Sales:OEM bundled accessories and enterprise managed service contracts.
Wholesalers dominate enterprise volume; Online Retail shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in China's Pearl River Delta while consumption fragments across high-income economies with divergent regulatory timelines. Shenzhen-based fabs supply global volume, yet demand-side policy momentum now sits in Brussels, Washington, and New Delhi.
United States
Enterprise procurement of workplace charging infrastructure now bundles hardware with firmware lifecycle management. FCC electromagnetic emission standards govern switching power supply certification, creating compliance overhead for import-dependent vendors. California's commercial real estate sector leads specification of port density analytics over unit economics.
Germany
Industrial automation and medical device OEMs drive demand for isolated power supplies with extended temperature ratings. EU Ecodesign efficiency tiers and REACH substance restrictions mandate standby power below 0.5W, obsoleting older controller architectures. Bavarian engineering consultancies specialize in GaN magnetics thermal design for automotive embedded systems.
China
Domestic smartphone OEMs are removing bundled chargers, shifting replacement volume to aftermarket channels. MIIT certification requirements for 100W+ fast charging adapters create protocol lock-in that slows interoperability adoption. Shenzhen's Nanshan and Bao'an districts host dense supplier networks for GaN semiconductors and magnetic components.
India
Mobile workforce expansion across tier-2 cities pushes power bank capacity requirements toward 20,000mAh+ configurations. BIS mandatory quality registration for electronics imports creates first-mover advantage for compliant vendors in fast-urbanizing markets. Tamil Nadu and Karnataka electronics manufacturing zones attract charger assembly investments under PLI scheme incentives.
South Korea
Consumer replacement cycles compress as OEM bundled chargers decline and aftermarket volume surges. MFDS-equivalent national standards enforce safety benchmarks for domestic production and export certification. Seoul-based semiconductor design houses supply intelligent power negotiation chips for laptop adapter bundles.
USB Charger Market Competitive Environment
Capital-heavy producers compete with asset-light designers across a market that fragments vertically by protocol certification depth rather than horizontally by geography. GaN foundry partnerships and magnetic component sourcing determine who captures premium-tier positioning. Three archetypes dominate: integrated OEMs with captive semiconductor supply, specialist accessory brands with design velocity advantages, and contract manufacturers serving private-label retail. Competitive moves center on M&A for protocol patent portfolios and capacity expansion in India BIS-certified assembly.
Within the specialist accessory tier, Anker Innovations Limited and Baseus exemplify design-velocity strategies that compress form-factor refresh cycles. Among integrated technology conglomerates, Samsung and Apple occupy positions where proprietary charging protocols reinforce device ecosystem lock-in. Chinese electronics manufacturers including Xiaomi and Huawei represent scale-driven archetypes with vertically integrated supply chains spanning semiconductor procurement through retail distribution.
| Leading Market Players |
|---|
| Anker Innovations Limited |
| Apple |
| Samsung |
| Belkin International |
| Xiaomi |
| Huawei |
| Baseus |
| RAVPower |
| BULL |
| Others |
Value Chain & Pricing Dynamics
Enterprise procurement consolidation around managed workplace charging contracts in the United States and Germany is compressing unit economics and forcing Shenzhen contract manufacturers toward GaN semiconductor integration to preserve margin.
Pricing Analysis
Margin tightening in the economy tier reflects REACH compliance cost absorption by low-SKU vendors exiting European distribution. Three-tier pricing structure across premium, standard, and economy levels separates USB-IF certified PD 3.1 adapters from Quick Charge licensed variants and unbranded commodity hardware. Price differentiation hinges on certification grade and GaN semiconductor inclusion. Small-scale importers face acute price sensitivity; enterprise facility managers prioritize lifecycle service bundling over unit cost.
Supply Chain Analysis
Freight cost volatility from Pearl River Delta ports to Rotterdam and Long Beach compresses landed margins for seasonal inventory builds. Manufacturing concentrates in China, Taiwan, and South Korea, with GaN-on-silicon wafers drawing from Taiwanese foundry capacity and magnetic components sourcing from Shenzhen's Bao'an supplier networks. Single-source vulnerability in GaN substrate production creates input bottlenecks during demand surges. Distribution runs through Amazon and Tmall for consumer replacement cycles, while wholesalers capture enterprise B2B volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GaN wafer foundry capacity constraints prop pricing power toward semiconductor-integrated vendors, creating durable margin shelter for backward-integrated producers.
For Market Incumbents: Cement GaN foundry partnerships or captive wafer supply agreements to defend against fabless design-house entrants. Prioritize India BIS certification pipeline investment to capture tier-2 city replacement demand before compliance barriers rise. Channel control through enterprise managed service contracts locks out retail-fragmented competitors.
For New Entrants and Emerging Players: Fleet operators in European logistics represent an underserved buyer archetype seeking embedded vehicle cabin charging with usage analytics. Target automotive aftermarket retrofit demand with 100W+ PD 3.1 adapters. Pursue direct sales to workplace technology providers bundling hardware with firmware subscription services.
For Investors and Strategic Acquirers: The window for entry favors GaN magnetics engineering specialists with Taiwanese or Korean thermal design talent. Long-term viability rests on protocol patent portfolios rather than enclosure manufacturing. Watch EU Ecodesign efficiency tier enforcement as inflection signal for compliance-capable vendor consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN Foundry Partnership | Secures semiconductor supply from Taiwan's concentrated wafer capacity. |
| India BIS Certification | Creates first-mover barrier in fast-urbanizing tier-2 electronics markets. |
| Enterprise Managed Service Launch | Bundles hardware with firmware lifecycle support for facility managers. |
| Protocol Patent Acquisition | Builds defensive moat against USB-C standardization commoditization. |
| Automotive Embedded System Integration | Captures OEM specification for 100W+ cabin charging ports. |
Study Parameters
Multi-period observation of GaN semiconductor pricing, EU regulatory filing timelines, and Shenzhen export volumes anchored the trend analysis, supplemented by interviews with power supply design engineers, USB-IF certification program managers, enterprise facility procurement officers, and aftermarket distribution channel heads. Secondary validation drew from FCC equipment authorization databases, EU Ecodesign implementing measure texts, China customs export statistics, and SEC filings of publicly traded charging accessory vendors. Bottom-up SKU-level volume estimates triangulated against top-down regional consumption models.
Segment-weighting applied product type, technology protocol, and end-user archetype dimensions across the projection horizon, with enterprise versus consumer splits calibrated to commercial real estate leasing data and smartphone OEM bundled charger policy shifts. CAGRs derived from installed base replacement cycle analysis and power delivery protocol adoption curves. Forecast inputs included GaN wafer foundry capacity expansion announcements and BIS certification registration timelines.
Revisions become necessary when GaN substrate supply disruptions, EU efficiency tier enforcement delays, or India PLI scheme modifications materialize. Forecasts reflect documented assumptions about protocol standardization velocity and manufacturing cost curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Semiconductor Micro Components Market
Electronic Components
Global Waveguide Components and Assemblies Market
Electronic Components
PTC Resettable Device Market
Electronic Components
Automation Component Market
Electronic Components
Audio DSP Market
Electronic Components
China Data Converter Market
Electronic Components
Discrete Capacitors Market
Electronic Components
North America Miniature Ball Bearing Market
Electronic Components
Chip Shield Market
Electronic Components
Encoder Market
Electronic Components
Intel Motherboards Market
Electronic Components
Docking Station Market
Electronic Components
Touch Screen Controllers Market
Electronic Components
Wireless Charging Stand Market
Electronic Components
Household Appliances Electric Commutators Market
Electronic Components
Electromechanical Relay Market