
 Anti-Vibration Mounts Market | 2026-2036
Anti-Vibration Mounts Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Vibration Mounts Market Analysis
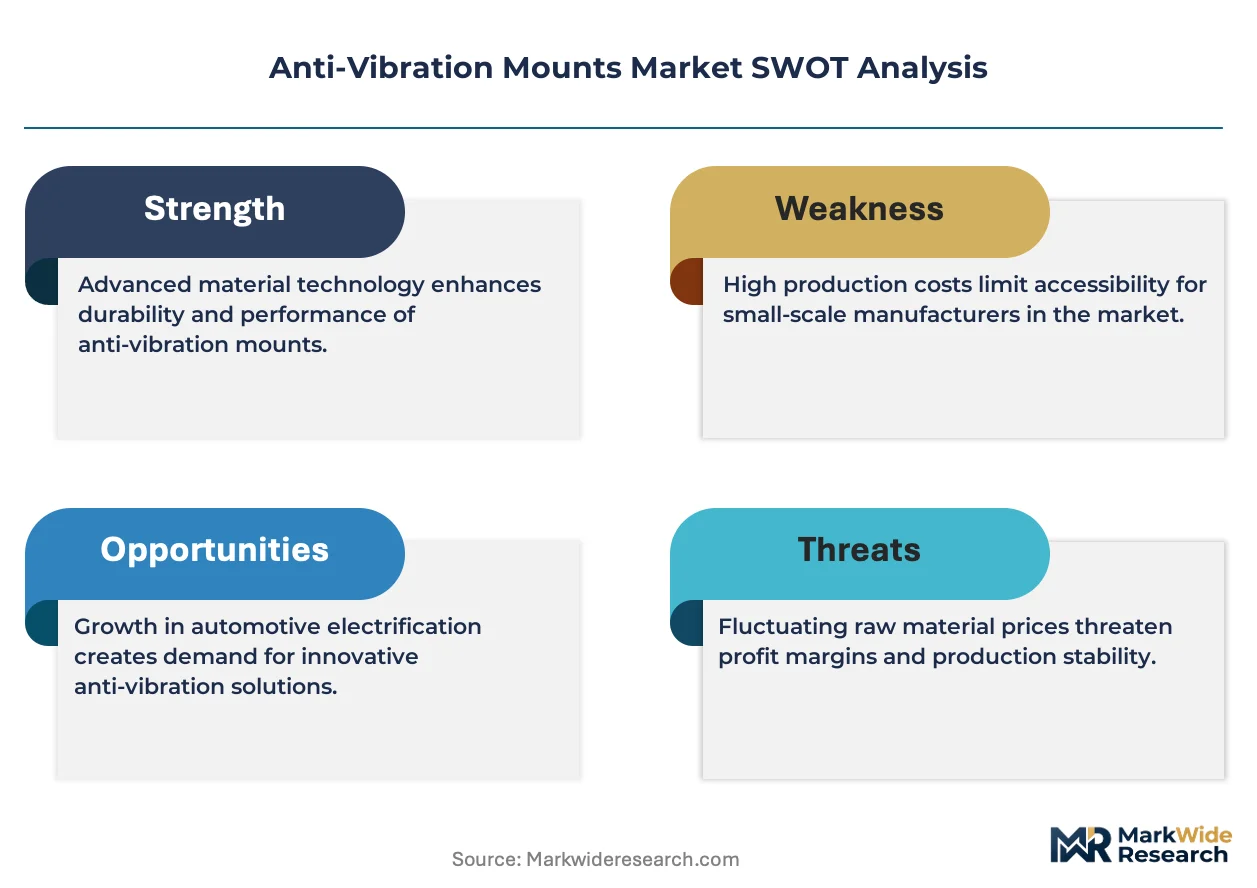
High-damping specification tiers is collapsing into mainstream industrial procurement as OEMs demand validated vibration attenuation certificates. LORD Corporation leverages its polymer science heritage to sustain premium positioning in aerospace-qualified mounts. Vibracoustic anchors European automotive supply through captive elastomer compounding and just-in-sequence delivery. Trelleborg competes across marine and energy applications with modular platform designs that reduce installation complexity.
Anti-vibration mounts are engineered isolation devices comprising elastomeric elements bonded to metallic substrates, manufactured through compression molding or injection bonding to achieve specified static deflection and dynamic stiffness ratios. Their primary purpose is attenuating mechanical oscillation transmission between equipment and supporting structures to protect precision machinery and improve operational longevity. Rubber mounts dominate volume in industrial machinery installations where cost sensitivity and moderate frequency isolation suffice. Aerospace applications command premium margins due to FAA certification requirements and fire-smoke-toxicity compliance testing. Isolators lead growth in electronics manufacturing as semiconductor fabrication tools demand sub-micron vibration control.
FAA airworthiness standards, EPA noise emission regulations, and EU REACH chemical restrictions collectively tighten material traceability and performance documentation requirements across supply chains. The EPA mandates workplace noise exposure limits that drive facility retrofit programs, while REACH restricts certain plasticizers and accelerators in rubber formulations. Stakeholders must monitor evolving OEM sustainability scorecards and preemptive material qualification to maintain specification access.
Market Dynamics
Automotive electrification is forcing complete redesign of NVH isolation architectures as EV powertrains eliminate engine masking noise and expose high-frequency motor whine, requiring elastomeric mounts with tuned dynamic stiffness across broader frequency ranges.
Growth Catalysts
- EU F-Gas Regulation:Mandates for low-global-warming-potential materials accelerate adoption of bio-based rubber compounds in precision manufacturing clusters.
- Semiconductor fabrication expansion:Sub-micron lithography equipment demands active-passive hybrid isolation systems that attenuate floor-borne vibration below 0.25 micrometers.
- German automotive headquarters concentration:Proximity of BMW, Mercedes-Benz, and Volkswagen engineering centers drives specification-grade mount qualification volumes.
Market Restraints
- Natural rubber price volatility:Thai and Indonesian supply disruptions transmit directly to compounder margins, compressing working capital cycles.
- REACH chemical restrictions:ECHA's accelerating substance-of-very-high-concern listings force reformulation of plasticizers and accelerators with 18-month requalification timelines.
- Metallic substrate concentration:Cold-rolled steel supply from Chinese mills creates single-source dependency for bonded mount substrates.
Strategic Opportunities
- India PLI scheme for automotive components:Domestic value-add requirements for electric vehicle assemblies create localized mount manufacturing incentives.
- Wind turbine nacelle isolation:Offshore installations above 15MW require tuned mass damper integration with elastomeric mounts for blade pitch control stability.
- Medical imaging equipment:MRI gradient coil vibration isolation represents untapped specification-grade demand with FDA 510(k) pathway differentiation.
Industry Challenges
- Polymer rheology expertise scarcity:Compound formulation for multi-frequency damping requires PhD-level material scientists that machine shops cannot access.
- FAA fire-smoke-toxicity certification:Aerospace mount qualification spans 24-36 months with $2-4 million testing investment, gating mid-tier supplier entry.
- Legacy hydraulic press retrofit:Compression molding equipment from the 1990s lacks precision temperature control for next-generation silicone compounds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Vibration Mounts Market |
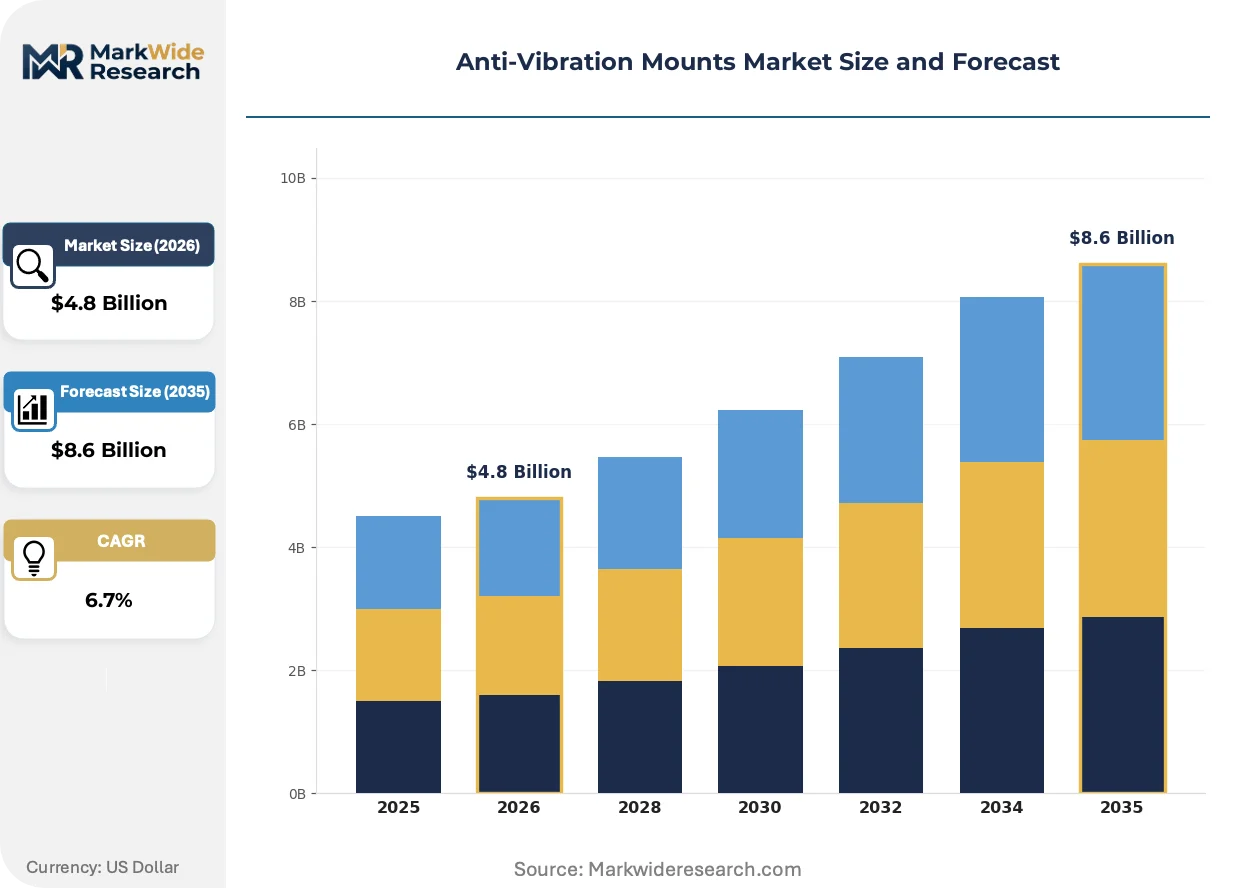
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber Mounts, Metal Mounts, Neoprene Mounts, Isolators Application: Industrial Machinery, Automotive, Aerospace, Electronics End User: Manufacturing, Construction, Transportation, Energy Installation Type: Custom, Standard, Modular, Others |
| Companies Covered | Sumitomo Riko, Farrat, LORD Corporation, Trelleborg, FUKOKU Co. Ltd., ContiTech, Vibracoustic, VibraSystems Inc., Hutchinson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Vibration Mounts Market Emerging Trajectories
Material science advances and regulatory chemistry restrictions are splitting the competitive landscape between premium validated systems and commoditized industrial mounts, with digital manufacturing tools compressing development cycles.
Magnetorheological elastomers is bifurcating the active vibration control segment by enabling real-time stiffness modulation through magnetic field application. Automotive OEMs in Germany and Japan are integrating these smart mounts into adaptive suspension architectures. The technology is compressing the addressable market for passive hydraulic mounts above 50kg payload capacity.
REACH Annex XVII expansion is restricting phthalate plasticizers and certain accelerators in rubber vulcanization, forcing compounders to qualify bio-based alternatives. ECHA's 2024-2026 substance evaluation roadmap targets additional curatives used in high-damping formulations. Aerospace and medical device segments are responding with preemptive material qualification to avoid supply interruption.
Consolidated supplier frameworks are displacing spot purchasing in industrial machinery procurement. Large automotive groups now mandate single-source NVH system contracts covering mounts, bushings, and damping modules. This concentration is most visible in Stuttgart and Wolfsburg engineering centers, where Volkswagen and Porsche have reduced qualified mount suppliers from twelve to four.
Anti-Vibration Mounts Market Segmentation
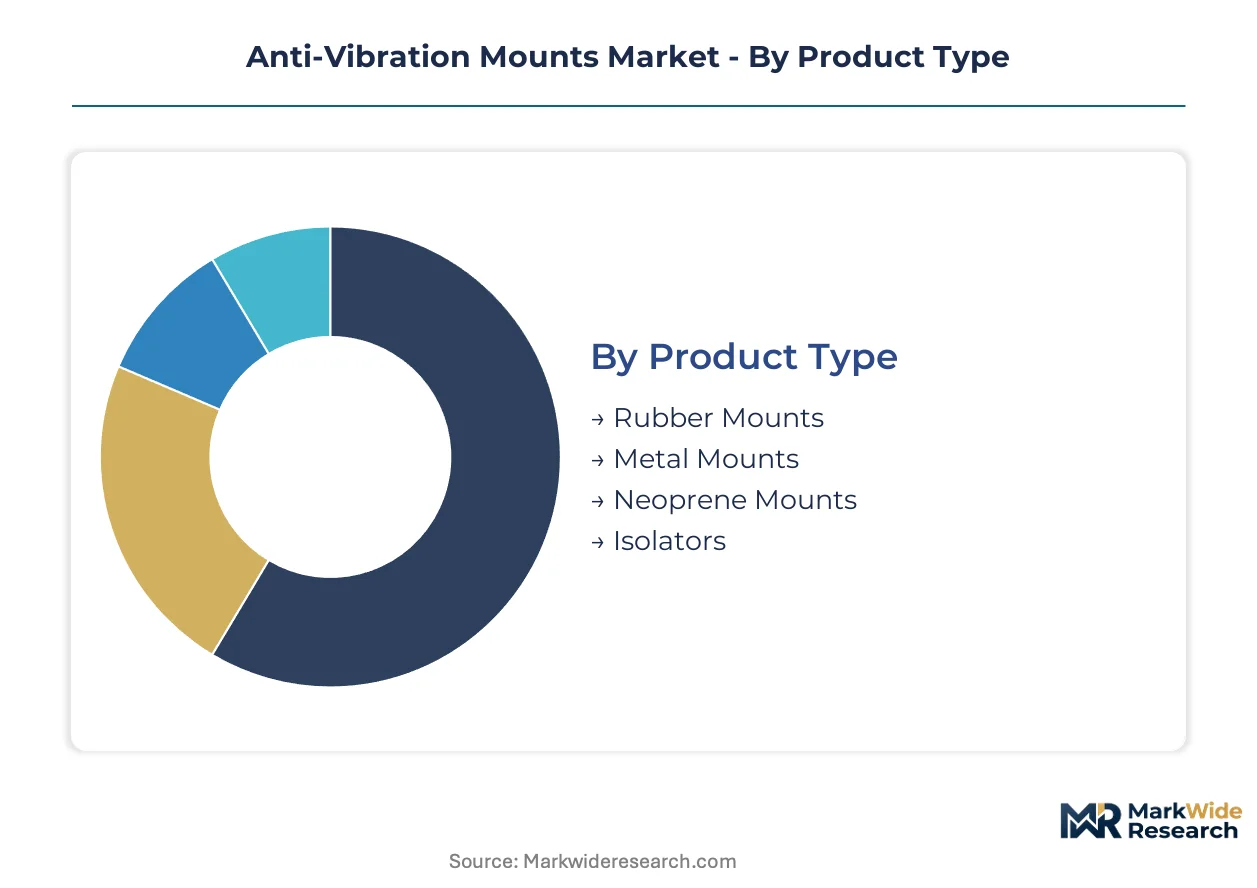
Segmentation in anti-vibration mounts determines specification pathways, with elastomer chemistry and bonding architecture dictating which end-uses remain accessible. Procurement committees increasingly segment by validated performance tiers rather than commodity grades, compressing mid-market supplier margins.
Product Type:
Metal mounts face the strongest substitution pressure as composite-reinforced elastomers capture payload ratings above 500kg in automotive applications.
- Rubber Mounts:Compression-molded natural rubber compounds bonded to carbon steel substrates deliver static deflection ratios of 15-25% under rated load. German automotive OEMs in Stuttgart and Wolfsburg specify these for powertrain isolation, with EU REACH compliance now mandating bio-based rubber alternatives for new platform qualifications.
- Isolators:Precision-engineered systems combining elastomeric elements with constrained layer damping achieve sub-micron vibration attenuation for semiconductor lithography equipment. Demand concentrates in Taiwan and South Korea fabrication facilities where floor-borne vibration must register below 0.25 micrometers for EUV patterning accuracy.
- Metal Mounts:Spring-steel and wire rope isolators serve heavy industrial machinery where temperature excursions exceed elastomer limits.
- Neoprene Mounts:Chloroprene-based compounds resist ozone and petroleum exposure in marine and outdoor installations.
Rubber mounts anchor the volume base while isolators gain share at the steepest rate.
Application:
Cost tier stratification separates specification-grade aerospace mounts from price-sensitive industrial machinery procurement.
- Automotive:EV powertrain redesigns require elastomeric mounts with tuned dynamic stiffness across 200-2000 Hz to mask high-frequency motor whine. BMW, Mercedes-Benz, and Volkswagen engineering centers in Germany drive qualification volumes for next-generation NVH architectures.
- Aerospace:FAA-certified mounts must pass fire-smoke-toxicity testing per 14 CFR 25.853, with qualification cycles spanning 24-36 months. Boeing and Airbus specification-grade demand concentrates in Wichita and Toulouse manufacturing clusters.
- Industrial Machinery:General-purpose rubber mounts serve metalworking and printing equipment where moderate frequency isolation suffices.
- Electronics:Active-passive hybrid systems protect semiconductor fabrication tools from micro-vibration.
Automotive applications command the largest revenue pool while electronics expands most quickly on fabrication capacity buildouts.
End User:
Customer type concentration favors manufacturing over construction due to precision machinery replacement cycles and specification-grade procurement frameworks.
- Manufacturing:Discrete and process manufacturers specify validated vibration attenuation certificates for CNC machining centers, injection molding presses, and automated assembly lines. Japanese and German precision manufacturing clusters drive premium mount adoption with 7-10 year replacement cycles.
- Energy:Wind turbine nacelle isolation for offshore installations above 15MW requires tuned mass damper integration with elastomeric mounts. Danish and German North Sea projects specify multi-frequency damping for blade pitch control stability.
- Transportation:Railway rolling stock and commercial vehicle OEMs procure suspension bushings and cab mounts under long-term supply agreements.
- Construction:Temporary equipment mounting for generators and compressors favors lowest-cost rubber solutions.
Manufacturing end users generate the steadiest demand flow while energy climbs fastest on offshore wind deployment.
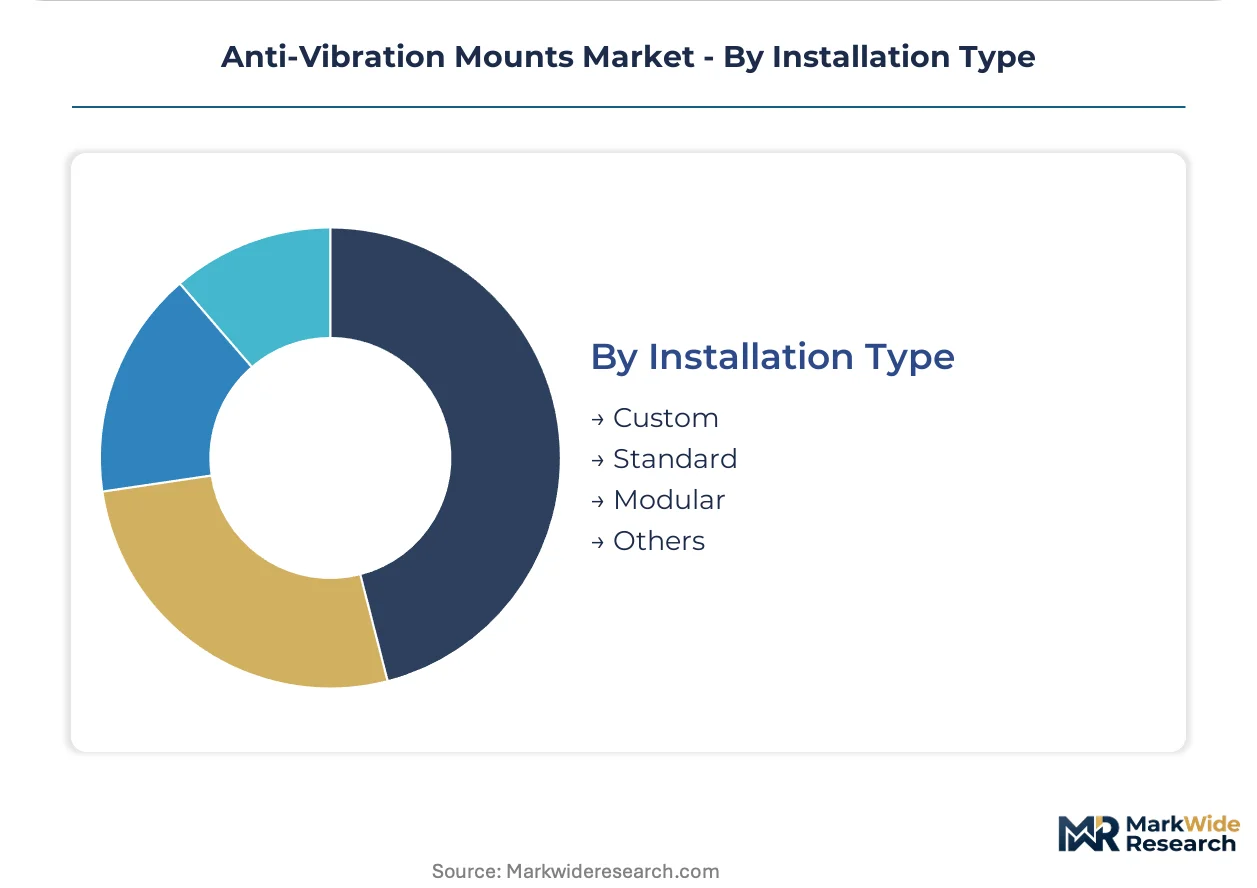
Installation Type:
Supply concentration in captive compounding favors custom solutions over standard catalog offerings for high-volume automotive contracts.
- Custom:Application-specific elastomer formulations and bond geometries address unique mass, center-of-gravity, and excitation frequency profiles. Volkswagen and Porsche consolidated qualified suppliers from twelve to four for single-source NVH system contracts covering mounts, bushings, and damping modules.
- Modular:Platform designs reduce installation complexity across marine and energy applications through interchangeable elastomer cartridges and standardized metallic interfaces. Trelleborg competes in this segment with configurable product families.
- Standard:Catalog offerings serve maintenance-repair-operations procurement with immediate availability.
- Others:Semi-custom adaptations of standard platforms for mid-tier industrial customers.
Custom installations dominate automotive revenue while modular formats expand most rapidly in marine and renewable energy sectors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. German automotive OEMs absorb premium pricing for specification-grade mounts, while Indian procurement remains acutely price-sensitive despite PLI scheme incentives.
Germany
Stuttgart and Wolfsburg engineering centers drive qualification volumes for EV powertrain isolation. BMW, Mercedes-Benz, and Volkswagen consolidated qualified suppliers from twelve to four under single-source NVH contracts. KBA vehicle type approval mandates documentation of vibration attenuation performance for all new platform registrations.
United States
Semiconductor fabrication expansion in Arizona and Texas demands sub-micron isolation systems. Boeing and Airbus supply chains concentrate specification-grade demand in Wichita manufacturing clusters. FAA fire-smoke-toxicity certification per 14 CFR 25.853 governs aerospace mount qualification with 24-36 month testing cycles.
China
Yangtze River Delta fabrication facilities require active-passive hybrid systems for EUV lithography. MIIT industrial equipment standards mandate vibration limits for precision machinery installations. Qingdao and Shanghai port infrastructure drives marine mount demand for vessel engine isolation.
Japan
Tokyo and Osaka precision manufacturing clusters sustain 7-10 year replacement cycles for CNC machining centers. METI carbon neutrality roadmaps accelerate bio-based rubber compound adoption. Nagoya automotive suppliers integrate magnetorheological elastomers into adaptive suspension architectures.
India
Chennai and Pune automotive hubs localize mount production under PLI scheme domestic value-add requirements. BIS certification for industrial machinery creates compliance barriers for imported substitutes. Tamil Nadu and Maharashtra precision manufacturing clusters drive specification-grade adoption despite persistent cost sensitivity.
Anti-Vibration Mounts Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Premium validated systems command 3-4x pricing multiples over commoditized industrial mounts. Three archetypes dominate: polymer science specialists with aerospace heritage, automotive-anchored elastomer compounders with captive supply chains, and modular platform designers serving marine and energy applications. Consolidation through supplier reduction programs and backward integration into rubber compounding represent the dominant competitive moves.
Among Japanese polymer specialists, Sumitomo Riko and FUKOKU Co. Ltd. occupy positions emphasizing material science depth. LORD Corporation exemplifies the aerospace-qualified archetype with FAA certification heritage. Trelleborg anchors the modular platform segment across marine and renewable energy applications. Vibracoustic represents automotive-anchored compounders with European headquarters proximity to German OEM engineering centers.
| Leading Market Players |
|---|
| Sumitomo Riko |
| Farrat |
| LORD Corporation |
| Trelleborg |
| FUKOKU Co. Ltd. |
| ContiTech |
| Vibracoustic |
| VibraSystems Inc. |
| Hutchinson |
| Others |
Supply Flow & Price Mechanics
Eighteen-month requalification timelines for REACH-compliant rubber compounds compress working capital cycles and concentrate pricing power among compounders with captive elastomer production. This lead-time compression rewards German automotive-anchored suppliers while squeezing spot-market procurement in price-sensitive industrial tiers.
Pricing Analysis
After-sales validation certificates and extended warranty contracts now drive lifetime value above hardware margins. Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified aerospace mounts from German OEM specification-grade systems and catalog industrial offerings. Price differentiation rests on certification tier and volume scale, with automotive single-source contracts commanding stability while commodity rubber mounts face cost compression from Thai natural rubber volatility. Electronics manufacturing exhibits lowest price sensitivity due to sub-micron performance requirements, whereas construction procurement remains acutely cost-driven.
Supply Chain Analysis
Inbound logistics costs from Southeast Asian rubber plantations through Rotterdam and Hamburg ports strain compounder margins during container availability crunches. Supply concentrates in Thailand and Indonesia for natural rubber feedstock, Germany and Japan for precision elastomer compounding, and China for cold-rolled steel substrates. Raw material dependencies span natural rubber, silicone polymers, and carbon steel stampings. Single-source vulnerability in Chinese metallic substrate supply creates qualification risk for bonded mount architectures. Distribution runs through captive just-in-sequence delivery for automotive OEMs and distributor networks for industrial maintenance procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from vibration attenuation certification and predictive maintenance contracts expands faster than hardware sales as OEMs demand documented performance over product-only procurement. This recurring layer rewards compounders with polymer rheology expertise and testing infrastructure.
For Market Incumbents: Fortify specification-grade positioning through backward integration into bio-based rubber compounding ahead of REACH Annex XVII expansion. Invest in magnetorheological elastomer R&D to defend against smart mount substitution in automotive adaptive suspension. Consolidate supplier frameworks by absorbing qualified compounders in Stuttgart and Wolfsburg engineering corridors.
For New Entrants and Emerging Players: Lead with India PLI scheme localization for electric vehicle mount assemblies, where domestic value-add requirements create white-space alongside cost-sensitive procurement patterns. Target semiconductor fabrication isolation in Taiwan and South Korea, where sub-micron requirements exceed incumbent capacity. Pursue FDA 510(k) pathway differentiation for MRI gradient coil vibration isolation as a specification-grade entry point.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming elastomer divisions lacking aerospace certification heritage. Five-to-ten year viability hinges on REACH compliance infrastructure and OEM sustainability scorecard positioning. Monitor ECHA substance-of-very-high-concern listings as inflection indicators for forced reformulation cycles that reward preemptive material qualification.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Compounding | REACH Annex XVII compliance secures German automotive qualification access against regulatory disruption. |
| Magnetorheological Elastomer Development | Real-time stiffness modulation captures adaptive suspension architecture share from passive hydraulic mounts. |
| India PLI Scheme Manufacturing Localization | Domestic value-add requirements for electric vehicle assemblies unlock automotive OEM contract eligibility. |
| FAA Fire-Smoke-Toxicity Certification Investment | Fourteen CFR 25.853 compliance gates premium aerospace mount pricing and Boeing supply chain access. |
| Semiconductor Fab Isolation System Partnership | Sub-micron vibration attenuation below 0.25 micrometers captures Taiwan and South Korea fabrication expansion. |
Methodological Framework
Initial hypotheses were tested against primary input from elastomer compounders, automotive NVH procurement teams, aerospace certification engineers, and semiconductor fab facility managers and refined through secondary validation. Primary fieldwork drew from plant managers at German automotive headquarters, technical R&D directors at polymer specialists, and aftermarket service heads at industrial distributors. Secondary sources included KBA vehicle type approval databases, ECHA substance evaluation roadmaps, FAA airworthiness directive filings, and customs trade data for natural rubber imports. Bottom-up segment sizing triangulated against top-down OEM procurement value chain analysis.
Variance decomposition across product type, application, end user, and installation type segmentation dimensions shaped the analytical framework over the projection horizon. Modeled dimensions encompassed elastomer chemistry, bonding architecture, industry vertical, and geographic regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating EV powertrain penetration rates and semiconductor fabrication capacity buildouts. Industry-specific inputs included REACH compliance transition timelines and FAA certification cycle durations.
The analysis sits within stated boundaries; outcomes outside sustained German automotive engineering concentration or accelerated ECHA restriction timelines would require recalibration. Forecasts reflect documented assumptions regarding natural rubber supply stability and OEM supplier consolidation trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Middle East and Africa Industrial Centrifuge Market
Industrial Equipment
Seismic Data Acquisition Equipment Market
Industrial Equipment
Global Pneumatic Actuators Market
Industrial Equipment
Pin Marking Machine Market
Industrial Equipment
Glass Washer Market
Industrial Equipment
Digital Load Indicator Market
Industrial Equipment
TIG Torch Market
Industrial Equipment
Global Safety Relays and Timers Market
Industrial Equipment
Camera Tripods Market
Industrial Equipment
Electric Cartridge Heaters Market
Industrial Equipment
Global Abrasive Waterjet Cutting Machine Market
Industrial Equipment
Diaphragm Coupling Market
Industrial Equipment
Global Linear Bearings Market
Industrial Equipment
Asia-Pacific Fans and Blowers Market
Industrial Equipment
Middle-East Fans and Blowers Market
Industrial Equipment
Air Bearings Market