
 Electrolytic Capacitor Market | 2026-2036
Electrolytic Capacitor Market Size, Share, and Industry Trends Forecast 2026-2036
Electrolytic Capacitor Market Foresight
High-voltage grade specifications above 450V is collapsing the traditional cost-per-microfarad calculus that governed commodity sourcing. Nippon Chemi-Con Corporation leverages captive aluminum foil etching facilities to secure anode material consistency across automotive qualification programs. Panasonic Corporation dominates surface-mount polymer hybrid lines serving telecommunications base station power supplies. Nichicon Corporation specializes in snap-in and screw-terminal formats for industrial machinery inverter modules.
An electrolytic capacitor is a polarized capacitor that uses an oxide layer on a metal anode—typically aluminum or tantalum—as the dielectric, with an electrolyte or solid conductive polymer serving as the cathode connection; its capacitance density ranges from 1μF to several farads with voltage ratings spanning 4V to 600V. The device primarily buffers voltage ripple, stores energy, and filters noise in DC power conversion circuits across electronic systems. Aluminum product types sustain the largest volume base due to cost efficiency in consumer electronics adapters and LED drivers, while tantalum formats command premium positioning in miniaturized aerospace and medical instrumentation where volumetric efficiency determines board layout. Surface mount form factors are displacing radial through-hole configurations in telecommunications equipment as OEMs prioritize automated assembly and reduced mechanical stress during reflow soldering.
The EU REACH regulation restricts hexavalent chromium in corrosion inhibitors used in electrolyte formulations, compelling reformulation investments by suppliers seeking CE-marked product access. China's GB standards for electronic components mandate flame-retardant sleeve materials and specified endurance testing protocols that differentiate export-grade from domestic-only production lots. The US EPA oversees hazardous substance reporting for electrolyte solvents in manufacturing facilities, affecting plant location decisions for producers serving North American automotive OEMs. Stakeholders must monitor polymer hybrid substitution rates against wet aluminum legacy designs, as this technology trajectory determines which production asset bases retain competitive relevance through the forecast horizon.
Market Dynamics
Polymer hybrid electrolytic technology is compressing legacy wet aluminum designs across telecommunications and automotive power electronics, forcing capacitor manufacturers to retool etching lines and reformulate electrolyte chemistry to maintain qualification status with tier-one OEMs.
Growth Catalysts
- Automotive Electrification Mandates:Inverter and onboard charger assemblies in EV platforms are expanding procurement volumes for high-voltage grade components. China's dual carbon goals and the US IRA clean vehicle credits are accelerating domestic content requirements.
- REACH Substance Restrictions:ECHA enforcement of hexavalent chromium limits in corrosion inhibitors is pushing European manufacturers toward low-impedance electrolyte formulations that command premium positioning.
- Surface-Mount Adoption:Telecommunications base station OEMs are displacing radial through-hole configurations with polymer hybrid surface-mount formats to enable automated assembly and reduce mechanical stress during reflow soldering.
Market Restraints
- Aluminum Foil Supply Concentration:Captive etching facilities in Japan and China control anode material consistency, creating procurement bottlenecks for second-tier capacitor manufacturers without backward integration into foil production.
- RoHS Lead-Free Transition Costs:European termination design compliance requires retooling of snap-in and screw-terminal production lines, elevating capital intensity for industrial machinery inverter module suppliers.
- Solid Polymer Substitution Threat:Conductive polymer cathode technologies are displacing traditional wet electrolyte designs in consumer electronics adapters below 100V ratings, compressing addressable market for legacy aluminum formats.
Strategic Opportunities
- Underpenetrated Medical Instrumentation:Tantalum volumetric efficiency in miniaturized aerospace and diagnostic equipment remains underserved by domestic Chinese manufacturers focused on consumer electronics scale.
- GB Standards Export Differentiation:China's mandatory flame-retardant sleeve materials and endurance testing protocols create dual-track production capabilities that can be leveraged for Southeast Asian electronics manufacturing hubs.
- Polymer-Tantalum Convergence:Hybrid solid electrolyte formulations combining polymer conductivity with tantalum volumetric density are opening board layout possibilities in implantable cardiac devices and portable imaging systems.
Industry Challenges
- Electrolyte Chemistry Talent Scarcity:Formulation expertise for low-impedance, high-temperature electrolytes resides with a narrow cohort of Japanese and German specialists, constraining R&D velocity for emerging market entrants.
- Automotive Qualification Timelines:AEC-Q200 certification cycles spanning 18-24 months for new capacitor series delay revenue recognition from design-in to volume production.
- Legacy Equipment Integration Friction:Industrial machinery inverter retrofit programs face compatibility constraints when polymer hybrid replacements cannot match wet aluminum ripple current specifications in existing thermal envelopes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrolytic Capacitor Market |
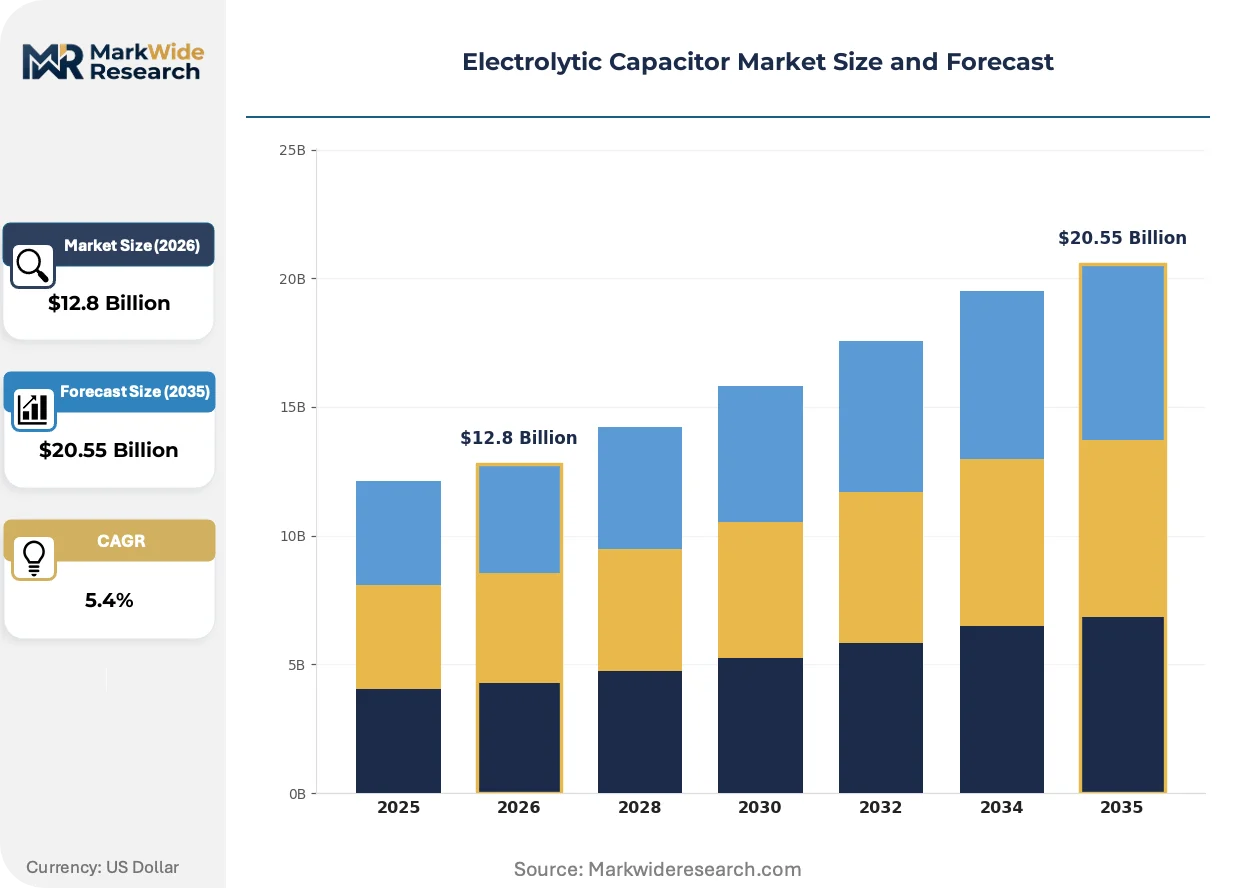
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $20.55 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Tantalum, Bipolar, Specialty Application: Consumer Electronics, Automotive, Industrial Machinery, Telecommunications Form Factor: Axial, Radial, Surface Mount, Through Hole End User: OEMs, Aftermarket Suppliers, Contract Manufacturers, Electronics Distributors |
| Companies Covered | Rubycon Corporation, TDK Electronics AG, Nippon Chemi-Con Corporation, Vishay Intertechnology Inc., Panasonic Corporation, Nichicon Corporation, SamYoung Electronic Co. Ltd., KEMET Corporation, Nantong Jianghai Capacitor Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrolytic Capacitor Market Shifts & Advancements
Capacitor manufacturers are converging on solid-state electrolyte architectures and automated surface-mount production while regulatory chemistry restrictions are forcing simultaneous reformulation of corrosion inhibitors and flame-retardant sleeve materials.
Polymer hybrid electrolytic capacitors are miniaturizing DC-link filtering functions in telecommunications power supplies and automotive onboard chargers. Base station OEMs in South Korea and Germany are adopting these formats at accelerating pace to reduce board area and enable higher switching frequencies. This technology trajectory is compressing the cost-per-microfarad advantage that wet aluminum designs historically maintained in 200V-450V applications.
REACH Annex XVII restrictions on hexavalent chromium compounds are compelling electrolyte suppliers to reformulate corrosion inhibitors for CE-marked product access. European capacitor manufacturers face reformulation investment requirements or exclusion from automotive and industrial machinery supply chains. The industrial inverter module segment is responding fastest, with snap-in format producers in Germany and Italy completing chemistry transitions ahead of consumer electronics adapter suppliers.
Buyer consolidation among EV battery management system integrators is concentrating procurement leverage with tier-one automotive electronics suppliers. Direct sourcing contracts are displacing traditional distributor inventory holding models in China and the US. This pattern is most visible in procurement for high-voltage DC-link capacitors serving 800V EV architectures, where CATL and BYD negotiate directly with Japanese foil etching specialists for anode material allocation.
Electrolytic Capacitor Market Segmentation
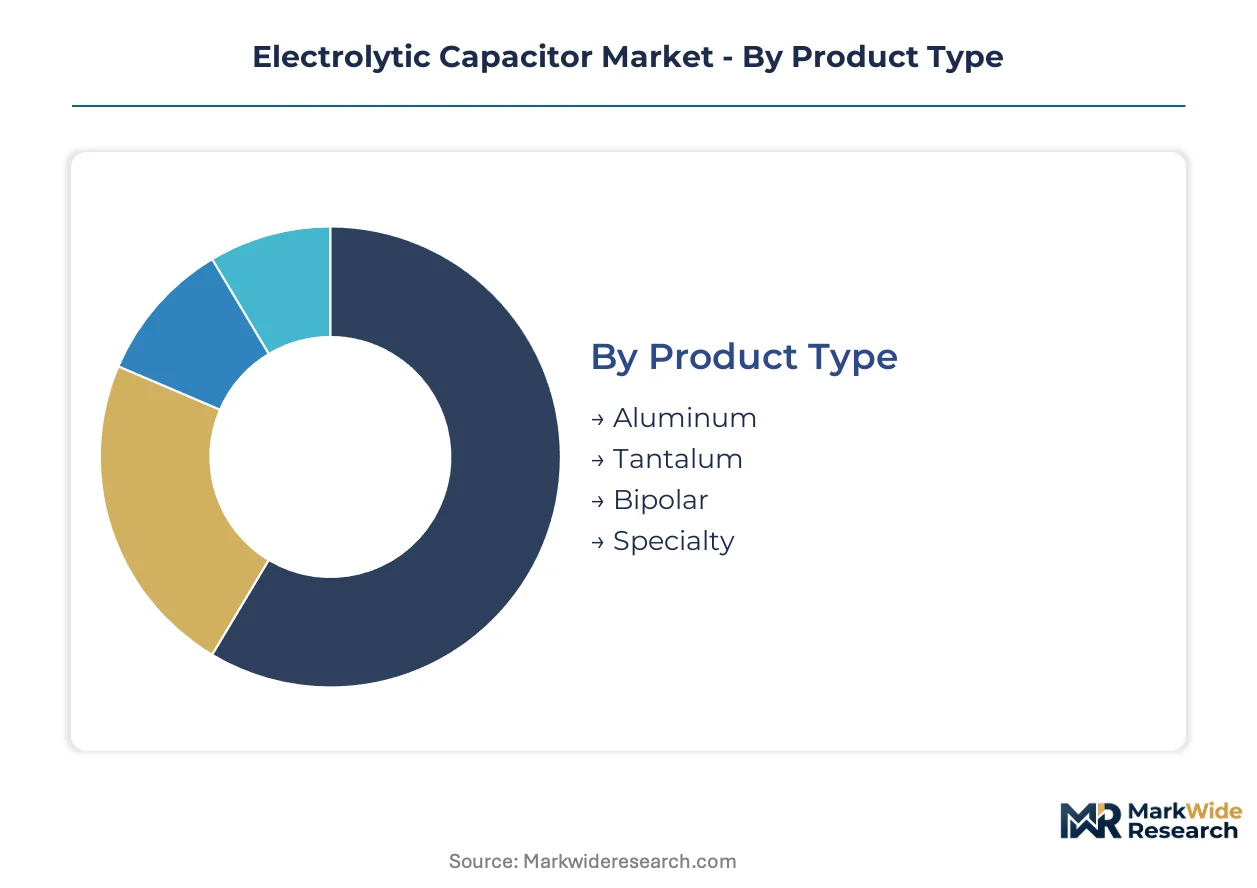
Electrolytic capacitor procurement patterns diverge sharply by voltage grade and thermal envelope requirements. Automotive qualification programs and telecommunications base station specifications create distinct margin tiers that reshape manufacturer portfolio priorities.
Product Type:
Aluminum formats command the deepest margin pools through scale economies in foil etching operations, while tantalum and specialty variants extract premiums from aerospace and medical instrumentation applications.
- Aluminum:Anode oxide layers formed on etched aluminum foil deliver capacitance density from 1μF to several farads across 4V-600V ratings. Demand concentrates in China's EV battery management system integrators and export-oriented consumer electronics adapter manufacturers, where CATL and BYD negotiate directly with Japanese foil etching specialists for material allocation.
- Tantalum:Manganese dioxide or conductive polymer cathode systems achieve superior volumetric efficiency in compact footprints. Procurement from implantable cardiac device and portable imaging system OEMs in Germany and the United States sustains premium positioning despite raw material cost volatility.
- Bipolar:Non-polarized construction suits audio crossover networks and motor phase compensation circuits where voltage reversal occurs.
- Specialty:Custom form factors and extended temperature ratings serve downhole drilling instrumentation and satellite power conditioning applications.
Aluminum holds installed capacity across automotive and consumer electronics fabs. Tantalum is rotating up the share rankings in medical instrumentation procurement.
Application:
Automotive electrification mandates are compressing legacy industrial machinery volumes while expanding high-voltage grade procurement.
- Automotive:Inverter DC-link buffering and onboard charger filtering functions demand 450V-600V ratings with AEC-Q200 qualification. China's dual carbon goals and the US IRA clean vehicle credits accelerate domestic content requirements for tier-one electronics suppliers.
- Consumer Electronics:Adapter and LED driver applications sustain aluminum electrolyte volume below 100V ratings. Solid polymer substitution threats from conductive polymer cathode technologies compress addressable market for wet aluminum legacy designs in smartphone charger procurement.
- Industrial Machinery:Snap-in and screw-terminal formats serve motor drive inverter modules with ripple current specifications that polymer hybrid replacements struggle to match in existing thermal envelopes.
- Telecommunications:Base station power supplies in South Korea and Germany are adopting polymer hybrid surface-mount formats to reduce board area and enable automated assembly.
Automotive is climbing the fastest in procurement value. Consumer electronics maintains volume leadership through adapter replacement cycles.
Form Factor:
Surface-mount adoption rates determine automated assembly compatibility and reflow soldering thermal stress tolerance.
- Surface Mount:Polymer hybrid constructions enable higher switching frequencies in telecommunications power supplies. Panasonic Corporation dominates these lines serving base station OEMs with reduced mechanical stress during reflow soldering.
- Radial:Through-hole cylindrical construction with lead wires extending from one end suits high-vibration industrial environments. Nichicon Corporation specializes in snap-in radial formats for machinery inverter modules.
- Axial:Lead wires extending from opposite ends accommodate legacy audio equipment and vintage electronics replacement markets.
- Through Hole:General category encompassing radial and axial configurations for hand-soldering repair operations and prototyping.
Surface mount is gaining share fastest in telecommunications procurement. Radial retains installed base in industrial retrofit programs.
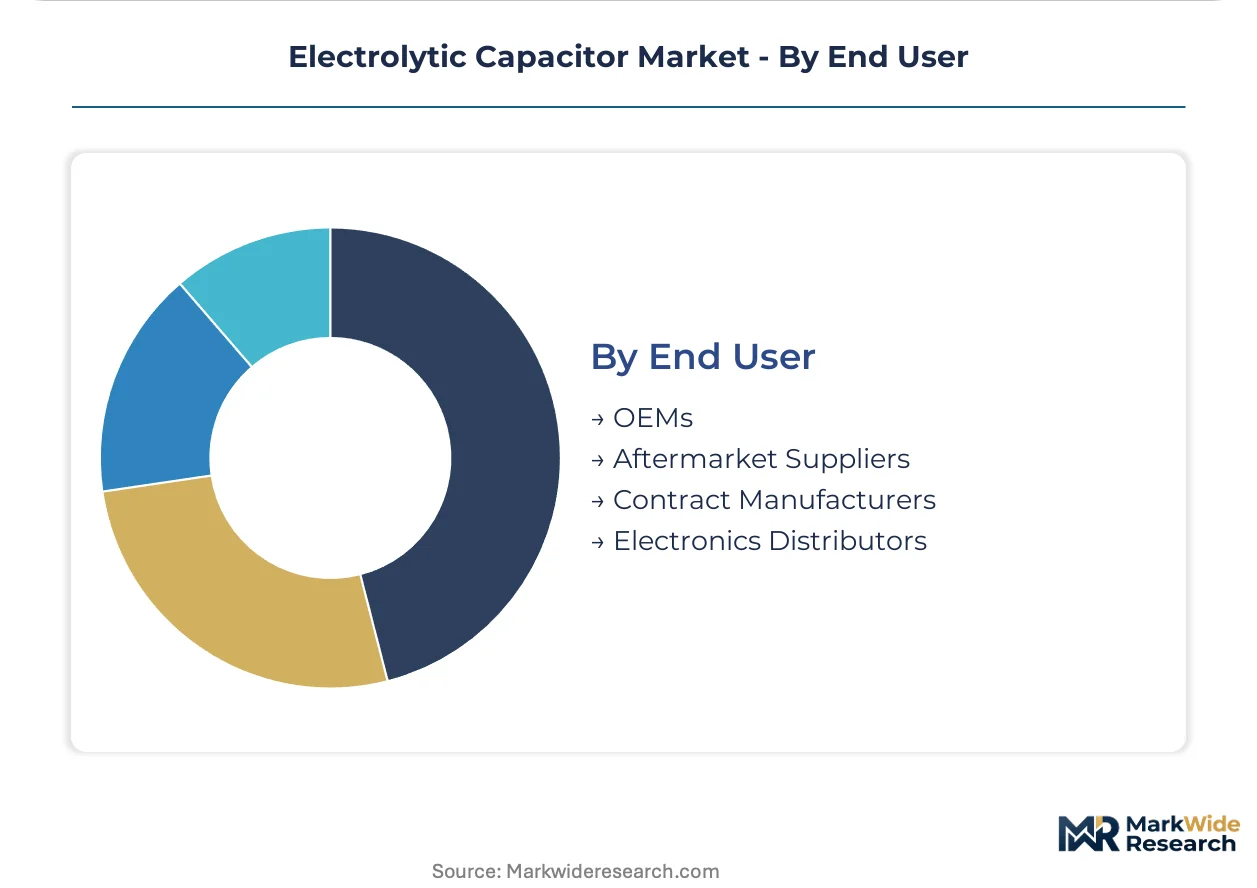
End User:
Direct sourcing contracts are displacing distributor inventory models in high-voltage automotive procurement.
- OEMs:Tier-one automotive electronics suppliers concentrate procurement leverage for 800V EV architecture DC-link capacitors. Direct negotiation with Japanese foil etching specialists bypasses traditional distribution channels.
- Contract Manufacturers:Foxconn and Flex electronics assembly operations in China and Vietnam source standardized aluminum formats for consumer electronics adapters at volume scale.
- Electronics Distributors:Arrow Electronics and Avnet maintain inventory positions for industrial machinery MRO procurement and prototyping volumes.
- Aftermarket Suppliers:Independent repair channels and refurbishment operations source cross-reference compatible replacements for legacy industrial equipment.
OEMs hold procurement leverage in automotive qualification programs. Contract manufacturers are rotating up the share rankings in consumer electronics scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Captive aluminum foil etching facilities concentrate in Japan and China, creating procurement bottlenecks that reshape capacitor supply chains. Tier-one automotive electronics suppliers in Germany and South Korea negotiate directly with these anode material specialists. Regulatory chemistry restrictions in Europe and domestic content mandates across major EV markets fragment production strategies.
China
CATL and BYD negotiate directly with Japanese foil etching specialists for anode material allocation serving 800V EV architectures. GB standards mandate flame-retardant sleeve materials and specified endurance testing protocols that differentiate export-grade from domestic-only production lots. The Yangtze River Delta hosts the densest cluster of capacitor fabs supplying both local battery management systems and export-oriented consumer electronics manufacturing.
Japan
Automotive qualification programs and AEC-Q200 certification requirements sustain premium positioning for high-voltage grade components in inverter assemblies. METI industrial policy supports domestic etching capacity retention amid polymer hybrid technology transitions. The Kanto region around Tokyo maintains the deepest concentration of formulation expertise for low-impedance, high-temperature electrolytes.
Germany
Industrial machinery inverter module producers face REACH Annex XVII restrictions on hexavalent chromium in corrosion inhibitors, compelling electrolyte reformulation investments. ECHA enforcement timelines have accelerated chemistry transitions ahead of consumer electronics adapter suppliers. Bavaria's automation equipment manufacturers drive snap-in format demand for motor drive applications where polymer hybrids struggle to match ripple current specifications.
South Korea
Telecommunications base station OEMs adopt polymer hybrid surface-mount formats at accelerating pace to reduce board area and enable higher switching frequencies. Domestic content requirements under clean energy transition programs align with IRA credit eligibility for North American EV supply chains. The Seoul Capital Area concentrates procurement leverage for DC-link filtering functions in power supply assemblies.
United States
IRA clean vehicle credits accelerate domestic content requirements for tier-one automotive electronics suppliers serving 800V architectures. EPA hazardous substance reporting for electrolyte solvents affects plant location decisions for producers supplying North American automotive OEMs. The Pacific Northwest and Southeast automotive corridors attract capacitor assembly investments seeking proximity to EV battery manufacturing clusters.
Electrolytic Capacitor Market Competitive Landscape
Concentration sits with Japanese and Chinese fabricators possessing captive aluminum foil etching capabilities. The vendor base stratifies across three tiers: vertically integrated specialists controlling anode material consistency, polymer hybrid technology leaders serving telecommunications base stations, and scale-driven assemblers sourcing etched foil on spot markets. Strategic moves center on backward integration into foil production and polymer electrolyte formulation licensing to secure automotive qualification status.
Within the captive-etching tier, Nippon Chemi-Con Corporation and Nichicon Corporation anchor Japanese supply consistency for automotive programs. Panasonic Corporation occupies a position exemplifying polymer hybrid specialization for surface-mount telecommunications applications. Among Chinese fabricators, Nantong Jianghai Capacitor Co. Ltd. represents the scale-driven archetype serving domestic EV and consumer electronics procurement.
| Leading Market Players |
|---|
| Rubycon Corporation |
| TDK Electronics AG |
| Nippon Chemi-Con Corporation |
| Vishay Intertechnology Inc. |
| Panasonic Corporation |
| Nichicon Corporation |
| SamYoung Electronic Co. Ltd. |
| KEMET Corporation |
| Nantong Jianghai Capacitor Co. Ltd. |
| Others |
Supply & Pricing Matrix
Captive aluminum foil etching capacity in Japan and China creates scale-driven cost floors that compress margin flexibility for second-tier assemblers sourcing anode material on spot markets. This concentration simultaneously elevates procurement leverage for tier-one automotive electronics suppliers negotiating direct allocation contracts while forcing price discipline on distributors holding standardized inventory positions.
Pricing Analysis
REACH Annex XVII dictates the pricing tier structure across European procurement, separating CE-marked automotive-grade components from industrial machinery formats still transitioning hexavalent chromium-free electrolyte formulations. Three-tier pricing structure across AEC-Q200 certified, industrial-grade, and consumer adapter levels reflects qualification investment recovery timelines. Cost compression in sub-100V consumer electronics adapters intensifies as conductive polymer cathode technologies displace wet aluminum legacy designs. Contract manufacturers in China exhibit highest price sensitivity due to volume-scale procurement of standardized formats, while implantable cardiac device OEMs in Germany accept premium positioning for tantalum volumetric efficiency.
Supply Chain Analysis
Inventory lead times for etched aluminum foil extend 16-20 weeks for non-captive buyers, creating working capital intensity that favors vertically integrated Japanese fabricators. Supply concentrates in Japan, China, and South Korea, with the Kanto region and Yangtze River Delta hosting densest etching capacity clusters. Raw material dependencies center on high-purity aluminum ingot, electrolyte solvent formulations, and conductive polymer precursors. Single-source vulnerability sits with Japanese specialists controlling low-impedance, high-temperature electrolyte formulation expertise. Distribution runs through direct OEM contracts displacing traditional distributor models in automotive procurement, while Arrow Electronics and Avnet maintain inventory positions for industrial MRO and prototyping volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technology substitution pressures and regulatory chemistry transitions fragment competitive positioning, creating white-space opportunities for specialists mastering polymer hybrid architectures or medical-grade tantalum formats.
For Market Incumbents: Consolidate backward integration into foil etching capacity to defend anode material allocation priority against CATL and BYD direct-sourcing negotiations. Deepen AEC-Q200 certification pipelines to capture 800V EV architecture procurement before qualification timelines lock in supplier relationships. Priority lever: polymer electrolyte formulation licensing to tier-two assemblers seeking automotive qualification status.
For New Entrants and Emerging Players: Anchor in underpenetrated medical instrumentation procurement for tantalum volumetric efficiency, where German and US implantable device OEMs remain underserved by Chinese scale-focused fabricants. Target polymer-tantalum hybrid development for portable imaging systems and cardiac applications. Go-to-market angle: GB standards-compliant export differentiation for Southeast Asian electronics manufacturing hubs seeking flame-retardant sleeve material compliance.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated specialists with captive etching capacity and active polymer hybrid transition programs. Long-term viability hinges on qualification status with tier-one automotive electronics suppliers rather than consumer electronics volume scale. Acquisition target archetype: Japanese or Chinese fabricators with AEC-Q200 certified series and active electrolyte chemistry R&D pipelines. Signal to watch: polymer hybrid substitution rates against wet aluminum in 200V-450V DC-link applications as inflection indicator for production asset relevance.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foil Etching | Secures anode material consistency for automotive qualification programs against CATL direct-sourcing pressure. |
| Polymer Hybrid Technology Licensing | Enables tier-two assemblers to access telecommunications base station procurement with surface-mount formats. |
| AEC-Q200 Certification Investment | Unlocks 800V EV architecture DC-link capacitor procurement before 18-24 month qualification cycles complete. |
| REACH-Compliant Electrolyte Reformulation | Maintains CE-marked product access as ECHA enforcement accelerates hexavalent chromium restrictions. |
| Medical-Grade Tantalum Capacity Expansion | Captures premium positioning in German implantable cardiac device and US portable imaging system procurement. |
Research Methodology
Cross-validation between capacitor manufacturer technical documentation and automotive OEM procurement specifications anchors the qualitative findings in this study. Primary interviews with electrolyte formulation chemists, Tier 1 supplier procurement directors, and industrial machinery inverter design engineers combined with secondary validation from METI industrial policy filings, ECHA REACH restriction timelines, and SEC 10-K supply chain disclosures. Bottom-up capacity utilization assessments at Japanese and Chinese etching facilities triangulate against top-down demand modeling from EV battery management system integrators.
Sensitivity analysis across voltage grade penetration rates and polymer hybrid substitution trajectories informs the analytical framework. Segmentation dimensions modeled include product type, application, form factor, and end-user procurement channel across the projection horizon. CAGRs derive from installed capacity expansion announcements, qualification pipeline visibility, and direct material allocation contract disclosures. Industry-specific forecast inputs incorporate AEC-Q200 certification cycle durations and GB standards compliance differentiation for export-grade production lots.
Material uncertainties — electrolyte chemistry talent scarcity constraining R&D velocity, automotive qualification timeline delays, and polymer hybrid ripple current specification gaps in industrial thermal envelopes — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and clean vehicle credit program continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Class D Audio Amplifier Market
Electronic Components
Handheld Devices Battery Market
Electronic Components
Audio DSP Market
Electronic Components
Braking Resistors Market
Electronic Components
Stretchable and Conformal Electronics Market
Electronic Components
Asia-Pacific USB Retimer Market
Electronic Components
Wearable Display Device Materials Market
Electronic Components
Household Appliances Electric Commutators Market
Electronic Components
Breadboards Market
Electronic Components
US Supercapacitor Market
Electronic Components
Electronic Shelf Label Market
Electronic Components
SAW Filters Market
Electronic Components
Automation Component Market
Electronic Components
Display Port Adapters Market
Electronic Components
Multi-Layer Ceramic Capacitor (MLCC) Market
Electronic Components
PTC Resettable Device Market