
 Global Capacitor Winding Machines Market | 2026-2036
Global Capacitor Winding Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Capacitor Winding Machines Market Analysis
Film-to-foil lamination tolerances in multilayer capacitor production is narrowing from ±5 micrometers to sub-2 micrometer precision, forcing equipment makers to integrate closed-loop tension control and laser edge alignment. Kaido Manufacturing leverages decades of Japanese precision engineering to anchor high-reliability military and aerospace winding systems. KOEM competes aggressively on cost-adjusted throughput for Asian electronics contract manufacturers. Wuxi Lead Intelligent Equipment specializes in servo-driven turret winders that dominate China's domestic renewable energy capacitor sector.
Capacitor winding machines are electromechanical systems that wrap dielectric films and conductive foils into cylindrical or flat wound elements, with typical operating speeds of 300 to 3,000 windings per minute and tension control accuracy within 1-3% of setpoint, producing the energy storage cores used in power electronics, EV inverters, and grid stabilization equipment. Fully automatic CNC platforms lead absolute revenue contribution due to their integration with Industry 4.0 line control and minimal changeover downtime for high-mix production. Advanced robotics technology represents the fastest-expanding segment as machine builders embed collaborative arms for automatic core loading and defective winding ejection, though conventional digital hybrid systems still occupy the largest installed base in cost-sensitive emerging manufacturing clusters.
EU REACH substance restrictions and RoHS directive compliance shape material choices for film insulation and solderable terminations, while China's SAMR enforces GB standards that mandate traceable calibration protocols for winding tension and layer count verification. Japan's METI promotes JIS-certified equipment for export qualification, creating regulatory segmentation between premium precision markets and general industrial supply. Stakeholders must monitor how dual carbon goals in Beijing and Brussels redirect capacitor demand toward DC-link and snubber applications in solar inverters and wind turbine converters.
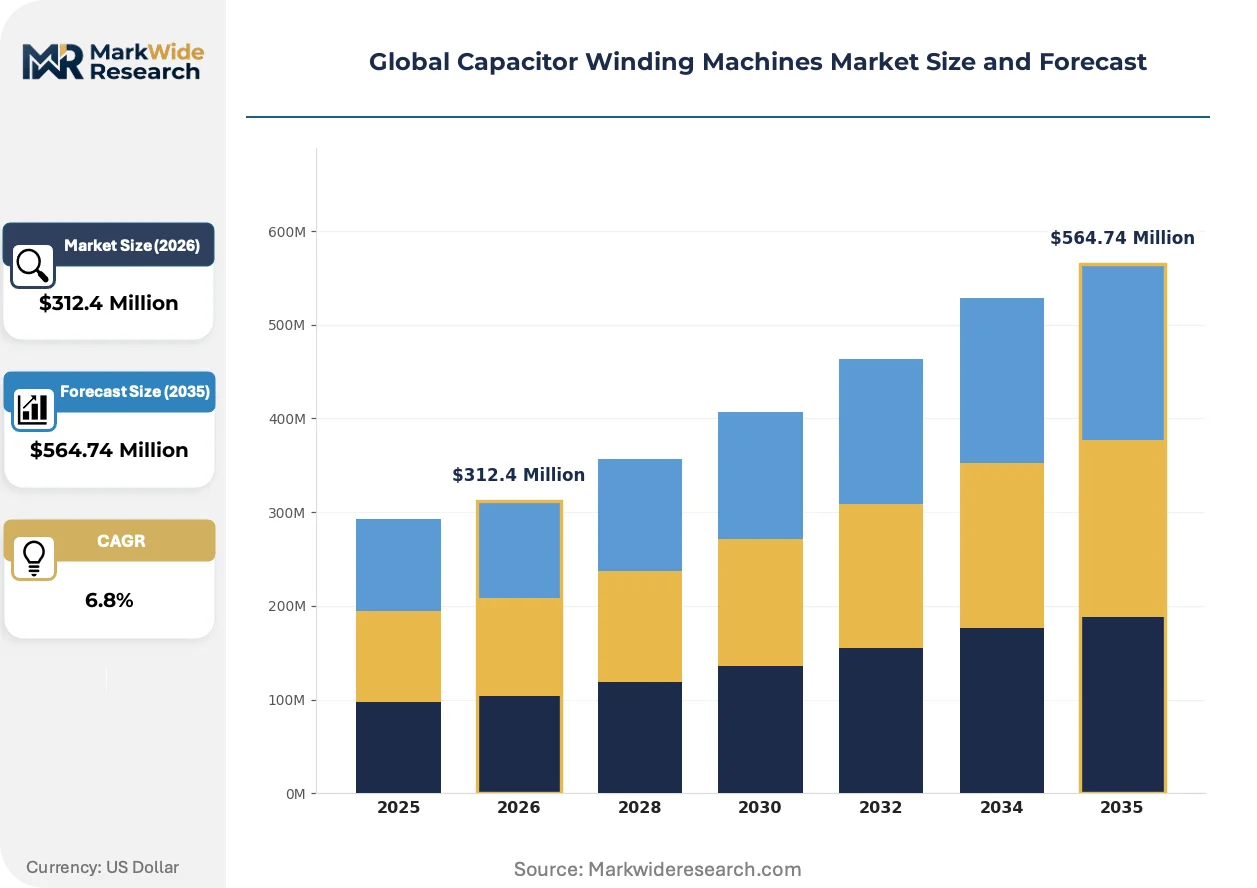
Market Dynamics
Precision tension control systems are compressing film-to-foil lamination tolerances from ±5 micrometers toward sub-2 micrometer thresholds, forcing equipment architecture redesigns across Japanese, German, and South Korean manufacturing bases.
Growth Catalysts
- EU RoHS substance restrictions:Tighter hazardous substance limits are accelerating replacement cycles for legacy winding equipment in European automotive capacitor plants.
- Electric vehicle powertrain expansion:German and South Korean EV manufacturers are scaling orders for precision winding systems capable of high-voltage DC-link capacitor production.
- China's GB standards enforcement:SAMR-mandated traceable calibration protocols are pushing domestic suppliers toward fully automatic CNC platform adoption.
Market Restraints
- Specialized servo motor supply concentration:High-precision torque motors for tension control systems source predominantly from Japanese and German suppliers, creating single-source vulnerability.
- Advanced ceramic capacitor substitution:MLCC technology advances in high-frequency applications are displacing wound film capacitors in consumer electronics below 50V ratings.
- REACH compliance material costs:ECHA-registered alternatives to legacy film dielectrics carry 15-40% price premiums, squeezing margin structures for mid-tier equipment buyers.
Strategic Opportunities
- Mexico automotive capacitor supply base:Nearshoring momentum among US tier-1 suppliers is creating demand for mid-speed winding systems with rapid format changeover capability.
- Solar inverter DC-link applications:Dual carbon goals in Beijing and Brussels are redirecting capacitor demand toward grid-tied renewable energy storage systems.
- Laser edge alignment convergence:Integration of machine vision with closed-loop tension control is enabling new equipment categories for aerospace-grade reliability requirements.
Industry Challenges
- Multi-axis motion programming expertise:CNC winding platform operation requires rare combinations of electromechanical troubleshooting and G-code optimization skills that outpace vocational training pipelines.
- Legacy analog system integration:Retrofitting Industry 4.0 data interfaces onto 1990s-era digital hybrid winders demands custom protocol bridging that extends commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Capacitor Winding Machines Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Semi-Automatic, Fully Automatic, CNC End User: Electronics Manufacturers, Automotive Supplies, Renewable Energy, Military Applications Technology: Conventional, Digital, Hybrid, Advanced Robotics Installation: On-Site, Off-Site, Mobile, Fixed |
| Companies Covered | Kaido Manufacturing, KOEM, Savy Mechanical, Metar Machines, Hilton International Industries, Roder Electronics Machinery, Unitronic Automation, Wuxi Lead Intelligent Equipment, Synthesis Winding Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Capacitor Winding Machines Market Emerging Trajectories
Digital twin architectures are virtualizing commissioning workflows, compressing equipment validation cycles while enabling remote diagnostics across distributed capacitor manufacturing networks.
Closed-loop laser edge alignment systems are replacing mechanical guide rollers in high-precision multilayer winding. Korean automotive inverter manufacturers are specifying these configurations for 800V EV platforms. This convergence of optical sensing with electromechanical control is virtualizing traditional mechanical tolerances into software-compensated parameters.
Japan's METI is promoting JIS-certified equipment export qualification frameworks that mandate documented calibration traceability for winding tension and layer count verification. This creates regulatory segmentation between premium precision markets and general industrial supply. Equipment builders targeting aerospace and medical capacitor segments are restructuring quality systems around these certification requirements.
Service unbundling is separating equipment hardware from predictive maintenance contracts and spare part subscription programs. Japanese precision engineering houses are pioneering outcome-based uptime guarantees that shift operational risk from capacitor manufacturers to machine builders. This restructuring is most visible in Germany's industrial electronics corridor where automotive tier-1 suppliers prefer total cost of ownership models over capital expenditure ownership.
Global Capacitor Winding Machines Market Segmentation
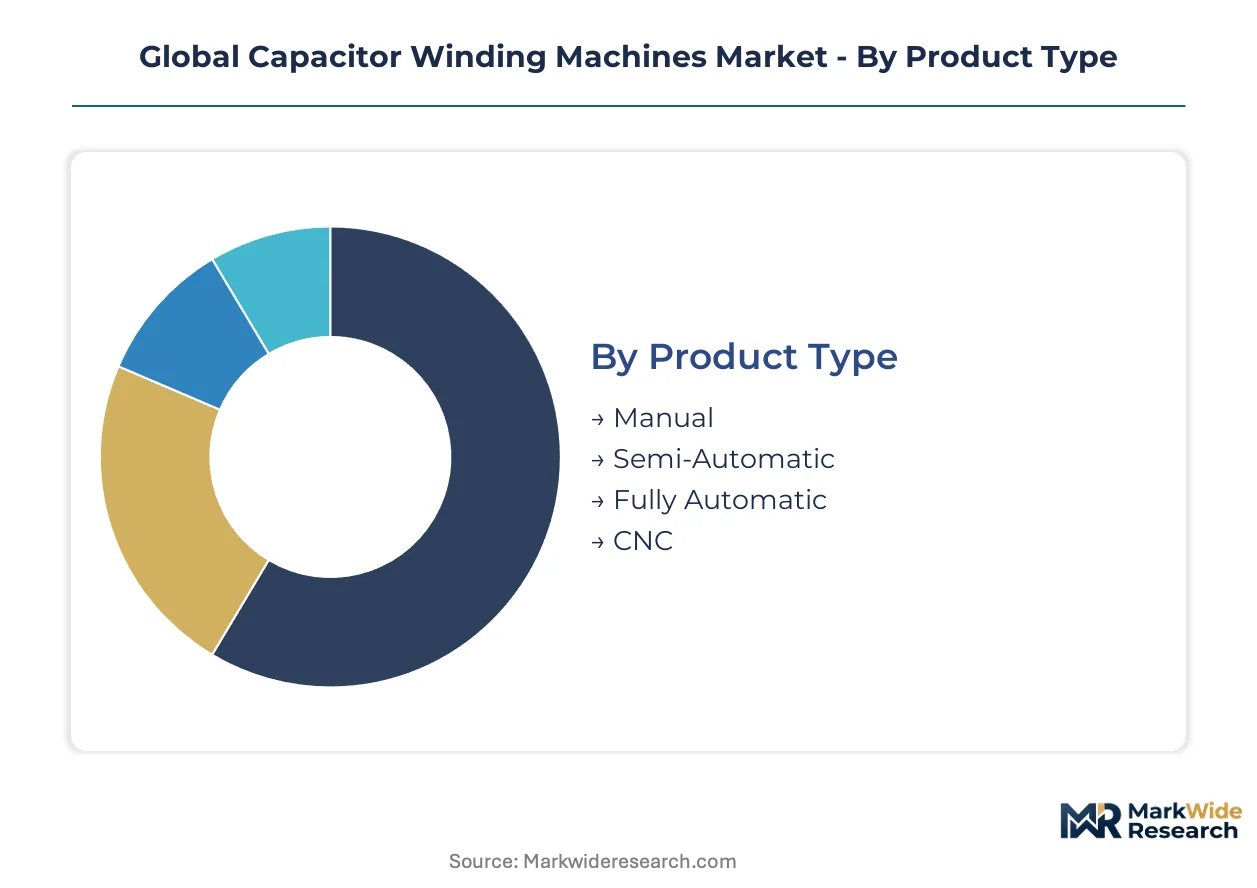
Capacitor winding machines segment across automation grade, end-use voltage requirements, control architecture, and deployment flexibility. Each dimension carries distinct margin structures and technical barriers that shape supplier positioning.
Product Type:
Automation sophistication defines capital intensity and changeover economics across buyer portfolios.
- Fully Automatic:These systems integrate programmable logic controllers with servo-driven tension modules, achieving sub-2 micrometer lamination precision through closed-loop feedback. German and South Korean EV powertrain manufacturers concentrate orders here as 800V DC-link capacitor demand accelerates.
- CNC:Computer numerical control platforms embed multi-axis motion programming for high-mix production with minimal downtime. China's SAMR-mandated GB standards for traceable calibration are pushing domestic electronics suppliers toward this tier.
- Semi-Automatic:Hybrid operator-machine workflows suit mid-volume contract manufacturers in Mexico's automotive capacitor corridor.
- Manual:Entry-level bench units serve prototype labs and specialty aerospace runs where lot sizes fall below automated changeover thresholds.
Fully Automatic holds installed capacity. CNC is rotating up the share rankings.
End User:
Application voltage and reliability certification requirements segment demand into divergent equipment specifications.
- Automotive Supplies:Tier-1 inverter manufacturers specify laser edge alignment and JIS-traceable calibration for 800V EV platforms. Korean and German OEMs are expanding qualification programs for winding equipment suppliers.
- Renewable Energy:Solar inverter and wind turbine converter producers need wide-format turret winders for DC-link and snubber capacitors. China's dual carbon goals are redirecting domestic equipment procurement toward this segment.
- Electronics Manufacturers:Consumer and industrial electronics contract manufacturers prioritize throughput-adjusted cost structures for film capacitors above 50V ratings.
- Military Applications:Aerospace and defense capacitor producers require documented calibration chains and failure-mode analysis that extend commissioning cycles.
Electronics Manufacturers retains volume leadership. Renewable Energy is climbing the fastest as grid storage deployment accelerates.
Technology:
Control system architecture determines integration depth with Industry 4.0 line management and predictive maintenance platforms.
- Advanced Robotics:Collaborative arms handle automatic core loading and defective winding ejection, compressing labor content per unit. Japanese precision engineering houses are embedding these modules into premium aerospace-grade systems.
- Digital:Native Ethernet connectivity and OPC-UA protocol support enable remote diagnostics across distributed manufacturing networks. German automotive tier-1 suppliers specify this architecture for multi-site standardization.
- Hybrid:Retrofitted digital interfaces on mechanical bases occupy the largest installed base in cost-sensitive emerging manufacturing clusters.
- Conventional:Analog control systems persist in legacy film capacitor plants facing compressed replacement timelines due to EU RoHS substance restrictions.
Hybrid dominates physical installed base. Advanced Robotics is gaining share fastest as labor costs and quality thresholds tighten.
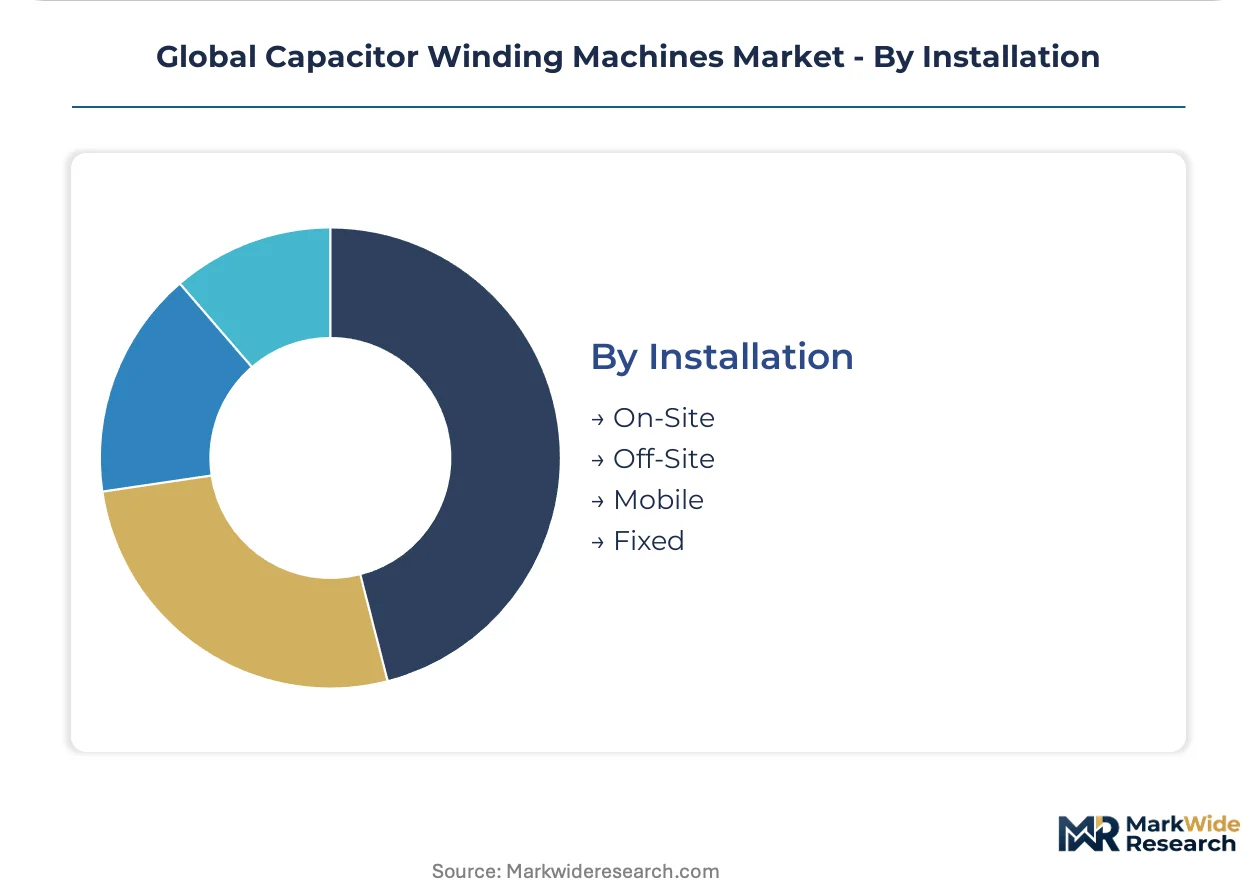
Installation:
Deployment mobility shapes equipment footprint constraints and commissioning logistics for capacitor producers.
- Fixed:Permanent foundation-mounted systems anchor high-volume automotive and renewable energy capacitor plants in Germany, South Korea, and China.
- On-Site:Factory-integrated commissioning with local protocol adaptation serves multinational electronics manufacturers with distributed production networks.
- Off-Site:Pre-commissioned skid-mounted units reduce installation downtime for capacity expansions in Mexico's nearshored automotive supply base.
- Mobile:Trailer-mounted configurations support military field repair operations and temporary renewable energy project staging.
Fixed installation holds capacity concentration. On-Site deployment is rotating up as digital twin validation compresses commissioning risk.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision winding equipment procurement concentrates among German automotive tier-1 suppliers, South Korean EV powertrain manufacturers, and Chinese renewable energy capacitor producers. Japanese industrial electronics corridors and Mexico's nearshored automotive supply base complete the demand map.
Germany
EV inverter manufacturers in Baden-Württemberg and Bavaria specify laser edge alignment systems for 800V DC-link capacitor production. ECHA-registered REACH compliance alternatives drive 15-40% material cost premiums, compressing margin structures for mid-tier equipment buyers. Stuttgart's automotive electronics cluster anchors qualification programs for winding equipment suppliers serving continental OEMs.
South Korea
Powertrain producers specify closed-loop tension control systems achieving sub-2 micrometer lamination precision for high-voltage platforms. MFDS-aligned quality protocols extend to industrial equipment calibration traceability requirements. Busan-Ulsan manufacturing corridors concentrate orders for precision winding systems as domestic EV production scales.
China
SAMR-mandated GB standards for traceable calibration protocols push domestic suppliers toward fully automatic CNC platform adoption. Dual carbon goals redirect capacitor demand toward DC-link and snubber applications in solar inverters and wind turbine converters. Wuxi and Yangtze River Delta industrial zones dominate domestic renewable energy capacitor equipment procurement.
Japan
METI-promoted JIS-certified equipment export qualification frameworks mandate documented calibration traceability for winding tension verification. Precision engineering houses in Nagoya and Osaka pioneer outcome-based uptime guarantee models. Kanto region industrial electronics corridors anchor high-reliability military and aerospace winding system demand.
Mexico
Nearshoring momentum among US tier-1 automotive suppliers creates demand for mid-speed winding systems with rapid format changeover capability. Nuevo León and Bajío Region capacitor plants favor pre-commissioned skid-mounted units to reduce installation downtime. Northern border states concentrate automotive-grade film capacitor production for North American EV supply chains.
Global Capacitor Winding Machines Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market strata. Precision engineering houses from Japan and Germany anchor premium segments through calibration-certification integration, while Asian fabricators compete on cost-adjusted throughput metrics. Three archetypes dominate: JIS-certified precision specialists, servo-driven turret winder manufacturers, and robotics-integrated platform builders. M&A activity concentrates on motion control software assets, and strategic partnerships link equipment makers with predictive maintenance platform providers.
Within the precision-specialist tier, Kaido Manufacturing exemplifies decades-long Japanese precision engineering heritage, while KOEM occupies a position among Korean fabricators competing on volume-adjusted economics. Wuxi Lead Intelligent Equipment represents Chinese servo-driven turret winder specialists capturing domestic renewable energy demand. These three anchors illustrate geographic segmentation between premium certification-driven markets and throughput-optimized emerging manufacturing clusters.
| Leading Market Players |
|---|
| Kaido Manufacturing |
| KOEM |
| Savy Mechanical |
| Metar Machines |
| Hilton International Industries |
| Roder Electronics Machinery |
| Unitronic Automation |
| Wuxi Lead Intelligent Equipment |
| Synthesis Winding Technologies |
| Others |
Supply Flow & Price Mechanics
The Yokohama-Hamburg maritime corridor carries precision servo motors and laser alignment modules from Japanese engineering houses to German automotive tier-1 plants, with freight cost volatility amplifying the spread between JIS-certified premium systems and standard CNC platforms while compressing margins for mid-tier buyers lacking volume scale or backward integration into motion control subsystems.
Pricing Analysis
Cost-plus contracts with steel and rare-earth magnet indexation dominate long-term equipment supply agreements between Japanese precision builders and German EV inverter manufacturers. Three-tier pricing structure across JIS-certified aerospace-grade, automotive-qualified CNC, and emerging-market hybrid systems separates buyers by calibration traceability requirements and after-sales bundling intensity. Cost compression in the mid-tier CNC segment is intensifying because SAMR-mandated GB standard compliance forces Chinese domestic suppliers to absorb certification investments without full pricing pass-through. Contract manufacturers in Mexico's automotive corridor exhibit highest price sensitivity due to nearshoring margin constraints, while Korean powertrain OEMs prioritize total cost of ownership over capital expenditure minimization.
Supply Chain Analysis
Export control regimes restricting high-precision torque motor technology limit flows from Japanese and German suppliers to Chinese equipment builders, fragmenting sourcing strategies across geopolitical blocs. Manufacturing concentration centers on Japan, Germany, and South Korea for closed-loop tension systems, while China dominates servo-driven turret winder mechanical fabrication. Supply chains draw from specialized rare-earth magnet processors, precision ball screw manufacturers, and machine vision sensor vendors, with single-source vulnerability concentrated in sub-2 micrometer laser edge alignment modules. Distribution runs through direct OEM qualification programs for automotive and aerospace segments, with regional distributor networks serving emerging market contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capacitor winding equipment incumbents face substitution pressure from advanced MLCC technology in consumer electronics below 50V ratings, requiring defensive positioning around high-voltage DC-link and aerospace-grade applications where film capacitor architecture retains irreplaceable performance characteristics.
For Market Incumbents: Build calibration-certification moats around JIS and GB standard traceability to lock out mid-tier competitors from Korean and Chinese automotive qualification programs. Deepen backward integration into motion control software assets through targeted acquisitions, insulating margin structures from rare-earth magnet price volatility. Defend against Korean fabricator cost competition by embedding predictive maintenance subscriptions that shift operational risk to equipment builders and capture recurring revenue streams. For New Entrants and Emerging Players: Establish a beachhead in Mexico's nearshored automotive capacitor supply base by offering pre-commissioned skid-mounted units with rapid format changeover capability that incumbent Japanese houses underserve due to qualification timeline priorities. Target renewable energy DC-link applications in China's Yangtze River Delta industrial zones where dual carbon goals redirect domestic procurement toward wide-format turret winders. Lead with outcome-based uptime guarantees rather than capital sale models to bypass incumbent channel relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with orphaned precision winding divisions lacking standalone scale to justify METI or SAMR certification maintenance investments. Long-term viability favors equipment builders with captive software-defined motion control architectures and installed base density sufficient to support predictive maintenance platform economics. Watch for inflection signals in Korean EV platform voltage migration beyond 800V, which would force wholesale equipment replacement cycles favoring laser edge alignment specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Motion Control Software Acquisition | Captures proprietary tension algorithms that differentiate sub-2 micrometer precision from commodity CNC platforms. |
| JIS Certification Investment | Unlocks aerospace and medical capacitor segments requiring documented calibration chains for export qualification. |
| Predictive Maintenance Platform Launch | Converts capital equipment sales to recurring revenue while shifting operational risk from capacitor manufacturers. |
| Mexico Regional Service Hub | Reduces commissioning downtime for nearshored automotive tier-1 suppliers demanding rapid format changeover. |
| Laser Edge Alignment Module Integration | Enables 800V EV platform qualification that Korean and German OEMs specify for next-generation inverter designs. |
Methodological Framework
Desk research of customs trade databases, SAMR GB standard filings, and METI JIS certification registries preceded structured interviews with capacitor plant engineering directors, precision winding equipment product managers, automotive tier-1 procurement leads, and renewable energy inverter supply chain heads. Primary fieldwork validated secondary findings through bottom-up triangulation against top-down production capacity estimates across German, South Korean, Chinese, Japanese, and Mexican manufacturing clusters.
Forecast assumptions held fixed the current EU RoHS substance restriction framework and China's dual carbon policy trajectory while varying EV adoption intensity and MLCC substitution rates across the projection horizon. The analytical framework modeled automation grade, end-use voltage requirements, control architecture, and deployment flexibility dimensions, with CAGRs derived from equipment replacement cycle analysis and capacity expansion announcements. Key inputs included powertrain platform voltage migration timelines and solar inverter deployment forecasts from grid interconnection databases.
Sensitivities concentrate around REACH compliance material cost trajectories and export control regime expansions affecting precision motion component flows. Forecasts reflect documented assumptions regarding qualification program durations and certification maintenance investments. Material shifts in Korean or German EV platform specifications beyond 800V architectures, or abrupt MLCC technology breakthroughs in high-voltage applications, would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
DUV Lithography Systems Market
Semiconductor Equipment
Global Photoresist Market
Semiconductor Equipment
Vacuum Coating Equipment Market
Semiconductor Equipment
Semiconductor Wafer Cleaning Equipment Market
Semiconductor Equipment
150mm Probe Station Market
Semiconductor Equipment
Semiconductor POD Cleaner Market
Semiconductor Equipment
Temperature Calibration Equipment Market
Semiconductor Equipment
Global Semiconductor Thermal Evaporators Market
Semiconductor Equipment
Wire Bonder Equipment Market
Semiconductor Equipment
Automatic Dicing Saw Market
Semiconductor Equipment
FOUP Cleaning System Market
Semiconductor Equipment
Semiconductor Assembly Equipment Market
Semiconductor Equipment
FOUP Load Port Market
Semiconductor Equipment
4-Inch SiC Laser Annealing Equipment Market
Semiconductor Equipment
X-Ray Lithography Equipment Market
Semiconductor Equipment
Acid Filling and Leveling Machine Market