
 North America Miniature Ball Bearing Market | 2026-2036
North America Miniature Ball Bearing Market Size, Share, and Industry Trends Forecast 2026-2036
North America Miniature Ball Bearing Market Intelligence
Ceramic hybrid construction is expanding its share in precision spindle applications as silicon nitride balls displace traditional steel in high-speed, high-temperature environments. SKF Group leverages its integrated ceramic ball manufacturing to sustain premium positioning across aerospace and medical segments. The Timken Company anchors its North American footprint through captive heat-treatment capabilities and defense-certified production lines. Barden Corporation specializes in angular-contact configurations for satellite momentum wheels, occupying a defensible niche against generalist competitors.
North America miniature ball bearings are precision rotary elements typically ranging from one millimetre to twelve millimetres in bore diameter, engineered from hardened alloy steel, engineered plastics, or ceramic composites to reduce rotational friction and support radial or axial loads in constrained envelopes. Their primary purpose is to enable reliable motion control in applications where space, weight, and energy efficiency impose strict physical boundaries. Metal ball bearings retain the dominant revenue share across automotive and industrial equipment applications, though hybrid ball bearings represent the fastest-expanding category as thermal stability requirements intensify in electrical appliance motors and consumer electronics cooling fans. Plastic ball bearings command concentrated margin pools in corrosive-process industrial equipment where chemical resistance eliminates conventional lubrication regimes.
The National Highway Traffic Safety Administration enforces durability standards that cascade into automotive component supplier qualification requirements, while the EPA regulates friction-related energy losses in rotating equipment sold across the United States. Health Canada and the FDA jointly shape medical device bearing specifications through biocompatibility and sterilization-resistance protocols that constrain material selection and surface finish. Stakeholders must monitor evolving FAA airworthiness directives for unmanned aerial systems, as these will determine certification burdens for miniature bearing producers serving the expanding commercial drone and urban air mobility sectors.
Market Dynamics
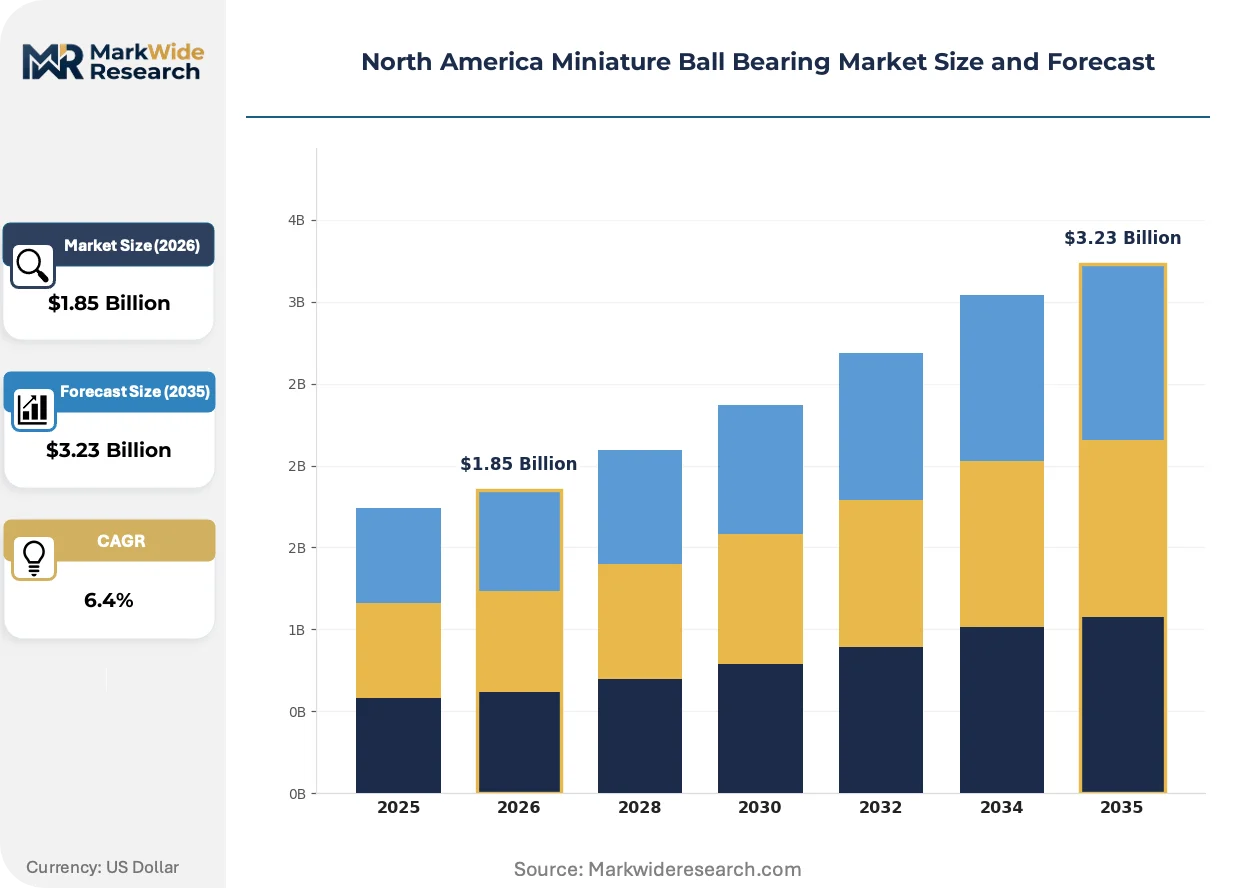
Hybrid ceramic ball architectures are compressing traditional steel bearing procurement across North American aerospace and medical corridors as thermal stability requirements harden. The EPA's friction-reduction mandates for rotating machinery accelerate supplier migration toward lubricant-free designs, while Mexico's Querétaro cluster concentrates precision manufacturing investment.
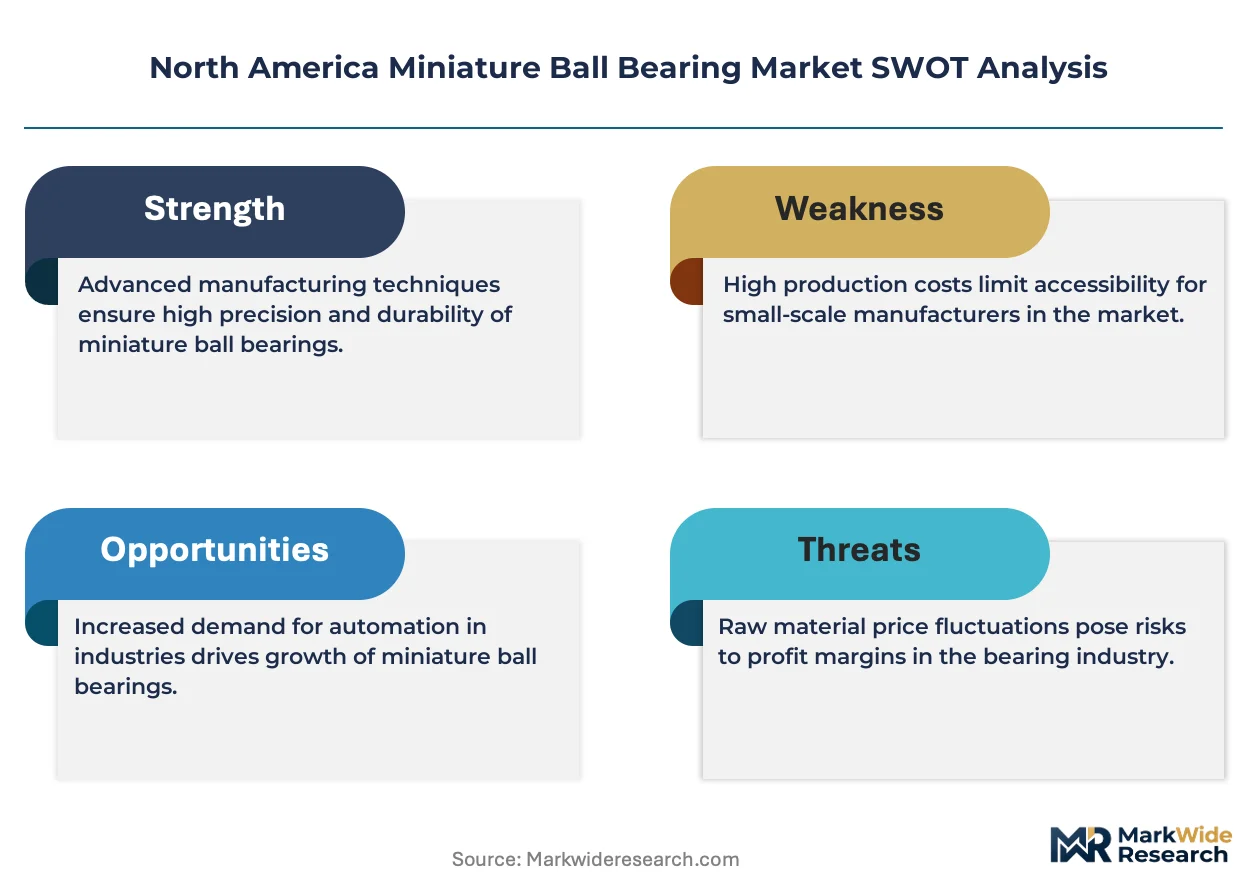
Growth Catalysts
- EPA Friction Mandates:Tightened energy-loss regulations for rotating equipment sold across the United States compel OEMs to specify low-friction hybrid bearings in appliance motors and cooling fans.
- Querétaro Aerospace Cluster:Mexico's concentrated precision manufacturing hub attracts tier-one actuator suppliers expanding captive bearing procurement for regional airframe assembly.
- Silicon Nitride Ball Adoption:Ceramic ball technology enables higher operating temperatures in dental turbine handpieces and surgical power tools, displacing conventional steel in California's medical device corridor.
Market Restraints
- Specialized Heat-Treatment Bottlenecks:Captive vacuum furnace capacity concentrates among three domestic suppliers, constraining throughput for aerospace-grade bearing qualification batches.
- Raw Material Concentration:High-purity silicon nitride powder production clusters in Asian supply chains, exposing North American hybrid bearing assemblers to ceramic ball cost volatility.
- FAA Certification Timelines:Extended airworthiness directive review periods for unmanned aerial systems delay commercial drone bearing qualification, freezing supplier revenue recognition.
Strategic Opportunities
- Urban Air Mobility Certification:Emerging FAA frameworks for electric vertical take-off aircraft create first-mover positioning for bearing suppliers achieving early propulsion system qualification.
- Corrosive-Process Industrial Equipment:Engineered plastic bearing architectures penetrate chemical processing plants across the Texas Gulf Coast where stainless steel lubrication regimes fail.
- Health Canada Sterilization Protocols:Accelerated biocompatibility standards for reusable surgical instruments drive specification upgrades in Ontario's medical device manufacturing base.
Industry Challenges
- Precision Grinding Talent Scarcity:Retiring master craftspeople in Rhode Island and Connecticut bearing corridors outpace apprenticeship program throughput, compressing yield rates on sub-five-millimeter bore geometries.
- Multi-Standard Compliance Burden:Simultaneous FDA biocompatibility, FAA airworthiness, and NHTSA automotive durability qualification requirements extend product development cycles for cross-sector suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Miniature Ball Bearing Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Ball Bearings, Plastic Ball Bearings, Hybrid Ball Bearings, Specialty Ball Bearings Application: Automotive Components, Electrical Appliances, Industrial Equipment, Consumer Electronics End User: Manufacturers, Distributors, Retailers, OEMs Component: Inner Ring, Outer Ring, Balls, Retainers |
| Companies Covered | Schaeffler AG, The Timken Company, SKF Group, Barden Corporation, RBC Bearings Inc., NSK Ltd., MinebeaMitsumi Inc., New Hampshire Ball Bearings, Inc., NTN Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Miniature Ball Bearing Market Strategic Shifts & Innovations
Material science convergence and procurement model compression are restructuring how North American buyers source precision rotary components. Three developments dominate the current window.
Silicon nitride hybrid bearing architectures deliver thermal stability beyond 800°C operating envelopes while maintaining dimensional precision under centrifugal load. Aerospace actuator OEMs in the United States and Canada specify these configurations for satellite momentum wheel and flight control surface applications. The technology is modularizing supplier value chains by decoupling ceramic ball sourcing from conventional steel raceway fabrication.
EPA friction-reduction mandates for rotating machinery establish maximum allowable energy losses in equipment sold across the United States. Industrial motor and appliance manufacturers respond by eliminating traditional lubrication regimes in favor of dry-running hybrid or full-ceramic bearing designs. Medical device producers face parallel pressure from FDA sterilization-resistance protocols that constrain surface finish and material selection for reusable surgical instruments.
Buyer consolidation among North American medical device OEMs compresses supplier qualification timelines while extending contract durations. Tier-one manufacturers in California and Minnesota now demand integrated design-to-delivery partnerships rather than catalog component procurement. This concentration is most visible in dental and orthopedic power tool segments where single-source agreements lock out generalist competitors.
North America Miniature Ball Bearing Market Segmentation
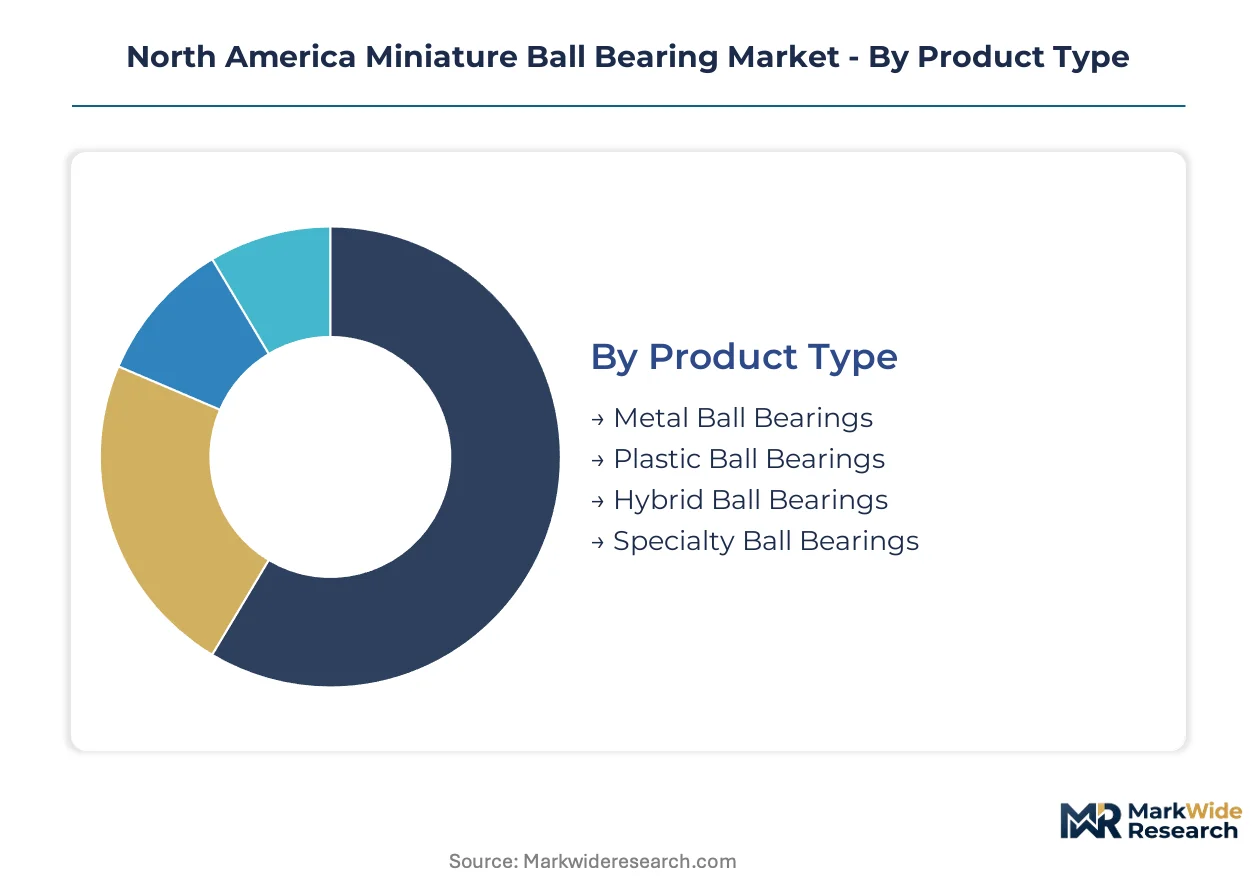
Miniature ball bearing procurement across North America fragments across material architectures, application environments, and qualification pathways. Each segment carries distinct certification burdens that determine supplier eligibility and contract duration.
Product Type:
FDA biocompatibility protocols apply to medical-grade metal and hybrid bearings, while EPA friction mandates drive lubricant-free ceramic architectures in appliance motors. FAA airworthiness directives govern specialty bearings for unmanned aerial systems.
- Metal Ball Bearings:Hardened alloy steel construction dominates automotive transmission and industrial gearbox applications. Demand concentrates in Michigan's automotive supplier corridor where NHTSA durability standards enforce batch qualification requirements. Steel bearings sit at the top of the volume ranking, with hybrid configurations climbing the fastest.
- Hybrid Ball Bearings:Silicon nitride balls paired with steel raceways enable dry-running operation above 800°C in dental turbines and surgical power tools. California's medical device corridor drives specification upgrades as sterilization-resistance protocols harden.
- Plastic Ball Bearings:Engineered polymer construction serves corrosive-process equipment across Texas Gulf Coast chemical plants where stainless steel lubrication regimes fail.
- Specialty Ball Bearings:Custom angular-contact designs for satellite momentum wheels require captive vacuum heat-treatment capabilities concentrated among three domestic suppliers.
Metal bearings command the highest absolute shipment volumes, though hybrid architectures gain share fastest in precision medical and aerospace applications.
Application:
End-use environments determine lubrication regime selection, with corrosive and sterile applications forcing material substitutions that compress conventional steel procurement.
- Automotive Components:Transmission and steering systems specify sub-ten-millimeter bore bearings under NHTSA durability enforcement. Tier-one suppliers in Ohio and Ontario consolidate procurement through long-term supply agreements.
- Electrical Appliances:Motor and cooling fan manufacturers eliminate traditional lubrication in favor of dry-running hybrid designs responding to EPA energy-loss regulations.
- Industrial Equipment:Precision spindles and robotics demand angular-contact configurations with sub-micron runout tolerances.
- Consumer Electronics:Miniature cooling fans and hard disk drives specify sub-five-millimeter bore geometries where Rhode Island grinding capacity constrains throughput.
Automotive components generate the largest order flow, while electrical appliance specifications expand most quickly under federal efficiency mandates.
End User:
Procurement authority concentrates among OEMs and tier-one manufacturers, with distributor networks losing share to direct design partnerships.
- OEMs:Tier-one medical device and aerospace manufacturers in California, Minnesota, and Querétaro demand integrated design-to-delivery partnerships rather than catalog procurement.
- Manufacturers:Captive bearing production for regional airframe assembly expands within Mexico's precision manufacturing cluster.
- Distributors:General industrial supply channels serve maintenance-repair-operations demand across fragmented metalworking shops.
- Retailers:Hobbyist and small-scale electronics repair markets access bearings through e-commerce and specialty hardware channels.
OEMs dominate contract value, with manufacturer direct procurement expanding fastest through cluster-based supply chain consolidation.
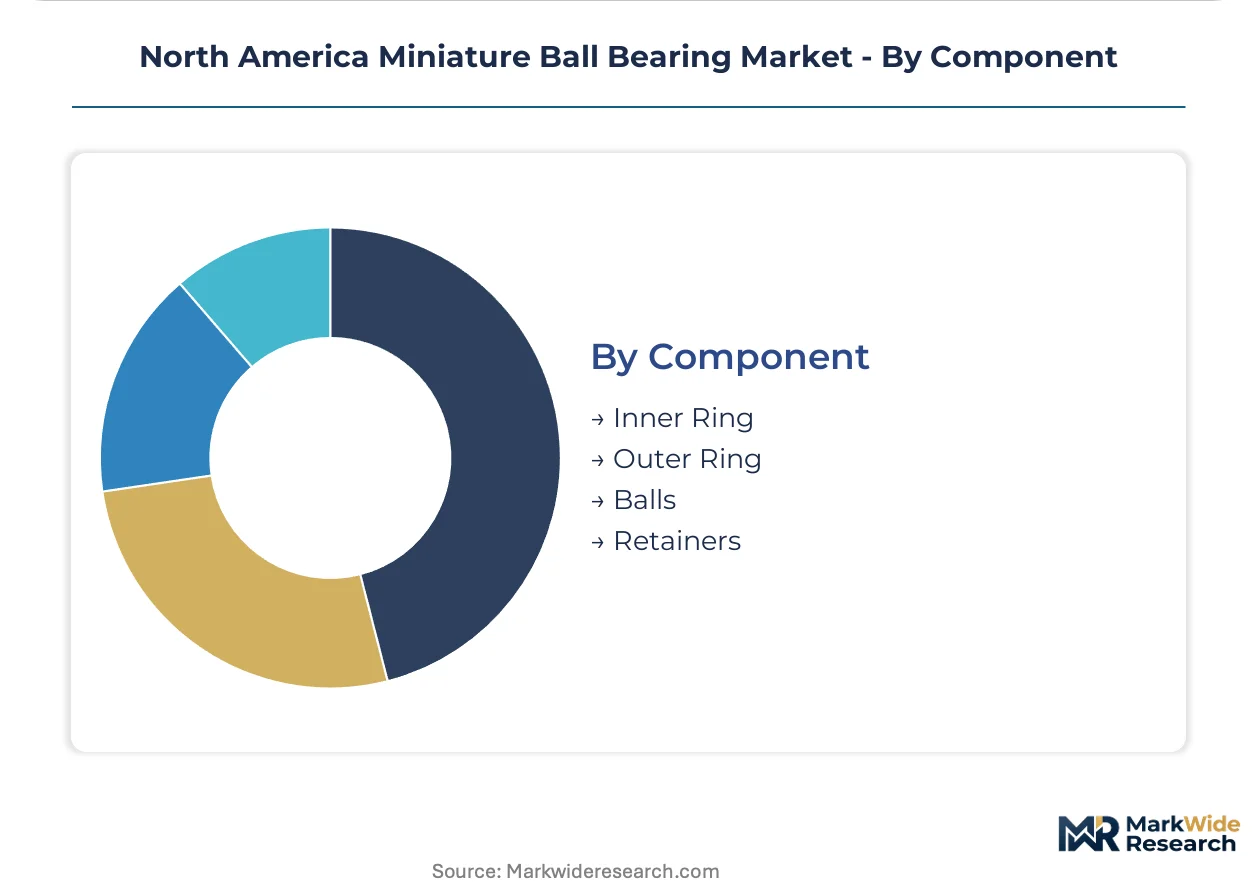
Component:
Sub-assembly sourcing strategies diverge based on heat-treatment and precision grinding capabilities concentrated among domestic specialists.
- Balls:Silicon nitride sphere production requires high-purity powder supply chains concentrated in Asian sources, exposing North American assemblers to ceramic input cost volatility.
- Inner Ring:Vacuum heat-treated raceway fabrication anchors among three domestic suppliers with aerospace qualification credentials.
- Outer Ring:Housing geometry standardization enables broader supplier qualification compared to inner ring precision requirements.
- Retainers:Polymer and machined brass cage designs separate rotational elements while minimizing mass in high-speed dental and surgical applications.
Balls command the most concentrated supply risk, with retainer procurement expanding most quickly through polymer substitution in corrosive environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Querétaro's aerospace cluster anchors North American precision bearing demand as tier-one actuator suppliers expand captive procurement for regional airframe assembly.
United States
California's medical device corridor and Michigan's automotive supplier networks drive specification diversity. The FDA enforces biocompatibility protocols for reusable surgical instruments while the EPA mandates friction-reduction in rotating equipment. Rhode Island and Connecticut grinding corridors face precision talent scarcity as master craftspeople retire.
Canada
Ontario's medical device manufacturing base accelerates sterilization-resistant bearing procurement under Health Canada protocols. The country's national aerospace regulator coordinates with the FAA on unmanned aerial system certification. Quebec's precision manufacturing infrastructure supports defense-qualified production lines.
Mexico
Querétaro's concentrated aerospace hub attracts tier-one suppliers establishing regional bearing procurement. The country's federal economic development programs incentivize precision manufacturing cluster formation. Baja California's electronics assembly corridors generate cooling fan bearing demand.
North America Miniature Ball Bearing Market Key Industry Players
Global majors compete with regional champions across certification credentials and captive manufacturing capabilities. The market structure consolidates around three domestic suppliers with aerospace-grade vacuum heat-treatment capacity, while Asian ceramic ball sources feed North American hybrid assembly operations. Strategic archetypes include integrated material scientists controlling silicon nitride production, defense-certified specialists occupying angular-contact niches, and scale-driven generalists serving automotive volume. Competitive moves concentrate on backward integration into ceramic ball manufacturing and geographic expansion into Mexico's precision cluster.
Within the integrated materials tier, SKF Group and Schaeffler AG exemplify global scale with captive ceramic capabilities. The Timken Company anchors North American positioning through defense-certified production infrastructure. Barden Corporation occupies a defensible specialist position in satellite momentum wheel applications. These three represent contrasting archetypes: vertical materials control, regional certification dominance, and precision niche specialization.
| Leading Market Players |
|---|
| Schaeffler AG |
| The Timken Company |
| SKF Group |
| Barden Corporation |
| RBC Bearings Inc. |
| NSK Ltd. |
| MinebeaMitsumi Inc. |
| New Hampshire Ball Bearings, Inc. |
| NTN Corporation |
| Others |
Cost & Logistics Intelligence
EPA friction-reduction mandates for rotating machinery establish qualification gates that restrict premium-tier pricing access to suppliers with certified low-friction architectures. Buyers in California's medical device corridor and Michigan's automotive networks face tiered procurement thresholds where only hybrid ceramic-qualified vendors capture contract value above standard steel benchmarks.
Pricing Analysis
Input-cost pass-through from high-purity silicon nitride powder volatility anchors hybrid bearing pricing premiums against standard steel alternatives. Three-tier pricing structure across aerospace-qualified, medical-grade, and industrial-standard levels differentiates on certification depth and heat-treatment pedigree. Pricing pressure stems from Asian ceramic ball sourcing concentration compressing margin buffers for North American assemblers. Tier-one OEMs in Querétaro and Minnesota exhibit lowest price sensitivity due to long-term supply agreement structures, while maintenance-repair-operations channels through industrial distributors face acute cost compression.
Supply Chain Analysis
Domestic-content mandates in U.S. defense procurement and Buy America provisions for federal infrastructure projects reshape sourcing toward captive North American heat-treatment capacity. Supply concentration centers on Japan and China for silicon nitride powder, Germany for precision grinding equipment, and domestic Rhode Island and Connecticut corridors for sub-five-millimeter bore finishing. Single-source vulnerability pervades vacuum furnace qualification batches concentrated among three domestic suppliers. Distribution runs through direct OEM partnerships in aerospace and medical segments, with industrial supply channels serving fragmented aftermarket demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Miniature Ball Bearing Market functions as a regulatory compounder where EPA friction mandates and FAA airworthiness protocols continuously escalate qualification barriers. The EPA's tightened energy-loss regulations for rotating equipment serve as the primary demand amplifier, forcing specification upgrades across appliance motor and cooling fan procurement.
For Market Incumbents: Deepen captive vacuum heat-treatment capacity in defense-certified production lines to lock out competitors from aerospace actuator procurement. Expand silicon nitride ball backward integration to insulate margin structures from Asian powder cost volatility. The threat of precision grinding talent scarcity in Rhode Island and Connecticut corridors compresses yield rates on sub-five-millimeter geometries, making apprenticeship program investment a critical defensive lever.
For New Entrants and Emerging Players: Distributor partnerships with medical device OEMs in Ontario and California offer the most penetrable entry vector for hybrid bearing qualification. Target corrosive-process industrial equipment across the Texas Gulf Coast where engineered plastic architectures displace failed stainless steel lubrication regimes. A design-to-delivery partnership model, rather than catalog component sales, aligns with tier-one buyer consolidation trends in dental and orthopedic power tools.
For Investors and Strategic Acquirers: Roll-up economics work for precision grinding specialists with aerospace qualification credentials because captive heat-treatment bottlenecks concentrate value in defensible domestic assets. The five-to-ten-year viability window favors acquisition targets with FDA biocompatibility and FAA airworthiness certifications already in place. Monitor FAA unmanned aerial system airworthiness directive timelines as the inflection signal for commercial drone bearing revenue recognition.
| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Ball Backward Integration | Captive silicon nitride production insulates SKF and Timken from Asian powder cost volatility. |
| Defense Certification Investment | FAA and NHTSA dual qualification opens long-term supply agreements with tier-one aerospace OEMs. |
| Querétaro Manufacturing Footprint | Regional cluster proximity reduces logistics costs for actuator suppliers serving Mexican airframe assembly. |
| Precision Grinding Apprenticeship Programs | Rhode Island and Connecticut talent pipelines address yield compression on sub-five-millimeter bore geometries. |
| Urban Air Mobility Partnership | Early electric vertical take-off aircraft propulsion qualification creates first-mover positioning against generalist competitors. |
Research Approach
Multiple input streams — primary interviews with bearing procurement managers, precision grinding operations heads, and aerospace actuator engineers, alongside secondary validation — were reconciled through bottom-up and top-down triangulation. Regulatory filings from the EPA, FDA, and FAA provided compliance benchmark data. SEC disclosures from SKF Group, Timken, and Schaeffler AG anchored financial performance segmentation. Trade data from U.S. Customs and Canadian import records traced silicon nitride powder sourcing patterns.
Historical shipment volumes were cross-referenced against executive panel inputs from tier-one medical device and aerospace OEMs. The analytical framework modeled demand across material architecture, application environment, and end-user procurement authority dimensions. CAGRs were derived from regression analysis of segment-level drivers rather than top-down allocation. Industry-specific forecast inputs included EPA mandate implementation timelines and FAA unmanned aerial system certification pathway developments.
Revisions become necessary when ceramic powder trade flows shift, FAA airworthiness timelines extend, or precision grinding labor availability deteriorates beyond modeled assumptions. Forecasts reflect documented assumptions about regulatory enforcement intensity and cluster-based supply chain consolidation. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Multi-Layer Ceramic Capacitor (MLCC) Market
Electronic Components
Laser Direct Structuring (LDS) Antenna Market
Electronic Components
Structural Electronics Market
Electronic Components
USB Wall Charger Market
Electronic Components
Data Acquisition Hardware Market
Electronic Components
Global Flexible Electronics and Circuit Market
Electronic Components
Bonding Wires and Ribbons Market
Electronic Components
Audio Amplifier Market
Electronic Components
Printed Circuit Board Market
Electronic Components
Global Capacitor Market
Electronic Components
Special Function Data Convertors Market
Electronic Components
USB Retimer Market
Electronic Components
Pulse Width Modulation Controllers Market
Electronic Components
2D Electronics Market
Electronic Components
Audio DSP Market
Electronic Components
Electronic Wipe Market