
 Flex-Rigid PCB Market | 2026-2036
Flex-Rigid PCB Market Size, Share, and Industry Trends Forecast 2026-2036
Flex-Rigid PCB Market Insights
REACH is realigning the cost-of-entry calculus for European-bound suppliers by mandating full material disclosure and restricted substance thresholds across the supply chain. Zhen Ding Technology Holding Limited leverages its integrated copper-clad laminate operations to control substrate purity from source. Nippon Mektron, Ltd. anchors its position through proprietary adhesiveless polyimide bonding technology that eliminates restricted halogenated compounds. Unimicron Technology Corporation competes on scale, operating megaflex facilities in Taiwan that batch-test every lot for SVHC compliance.
Flex-rigid PCBs combine flexible polyimide circuits with rigid FR-4 or metal-core sections through plated through-hole interconnection, achieving bend radii below 3mm while maintaining impedance control to 10GHz for high-speed signal routing. Multi-layer configurations now dominate value capture as aerospace and medical OEMs specify 8-12 layer stacks with sequential lamination and laser-drilled microvias. Consumer electronics applications favor double-sided rigid-flex hybrids that balance assembly density against unit cost in foldable smartphone hinge modules.
FDA device classification rules, EU MDR technical documentation requirements, and China's GB standards for automotive electronics collectively shape product qualification timelines and testing protocols across major demand centers. OEM procurement teams now require ISO 13485 certification and IPC-6013 Class 3 performance validation before design-in approval. Stakeholders must monitor how automotive functional safety standards migrate from ISO 26262 into medical and aerospace qualification frameworks.
Market Dynamics
Sequential lamination and laser-drilled microvia capabilities are concentrating fabrication margins among multilayer specialists, while REACH and RoHS compliance costs filter out smaller substrate suppliers across European-bound supply chains.
Growth Catalysts
- EU MDR Technical Documentation:Medical device OEMs now mandate IPC-6013 Class 3 validation for implantable electronics, accelerating qualification of high-reliability flex-rigid suppliers.
- Foldable Smartphone Hinge Modules:Consumer electronics manufacturers are specifying double-sided rigid-flex hybrids with sub-3mm bend radii for next-generation display assemblies.
- Shenzhen-Dongguan Cluster Capacity:China's concentrated multilayer fabrication base enables rapid prototyping turnaround for aerospace qualification programs.
Market Restraints
- High-Purity Polyimide Feedstock Volatility:Halogen-free substrate requirements under REACH restrict qualified resin suppliers to Japanese and Korean chemical specialists.
- Adhesiveless Bonding Process Barriers:Proprietary polyimide-to-copper lamination techniques remain concentrated among a handful of patent-holding fabricators.
- ISO 26262 Migration Friction:Automotive functional safety standards are creating qualification timeline conflicts for suppliers serving both medical and mobility sectors.
Strategic Opportunities
- Diagnostic Equipment Miniaturization:Wearable biosensor platforms are creating demand for ultra-thin 4-6 layer flex-rigid stacks with embedded passive components.
- China GB Standards Harmonization:Alignment between automotive electronics certification and international IPC frameworks reduces dual-qualification burden for export-oriented fabricators.
- Copper-Clad Laminate Backward Integration:Captive control over substrate purity from resin synthesis through final etching enables premium pricing in medical-grade segments.
Industry Challenges
- Sequential Lamination Specialist Shortage:Megaflex facility operators face acute competition for process engineers capable of managing 8-12 layer stack registration tolerances.
- SVHC Testing Bottlenecks:Batch-level substance of very high concern screening creates working capital strain for mid-volume fabricators serving EU medical OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flex-Rigid PCB Market |
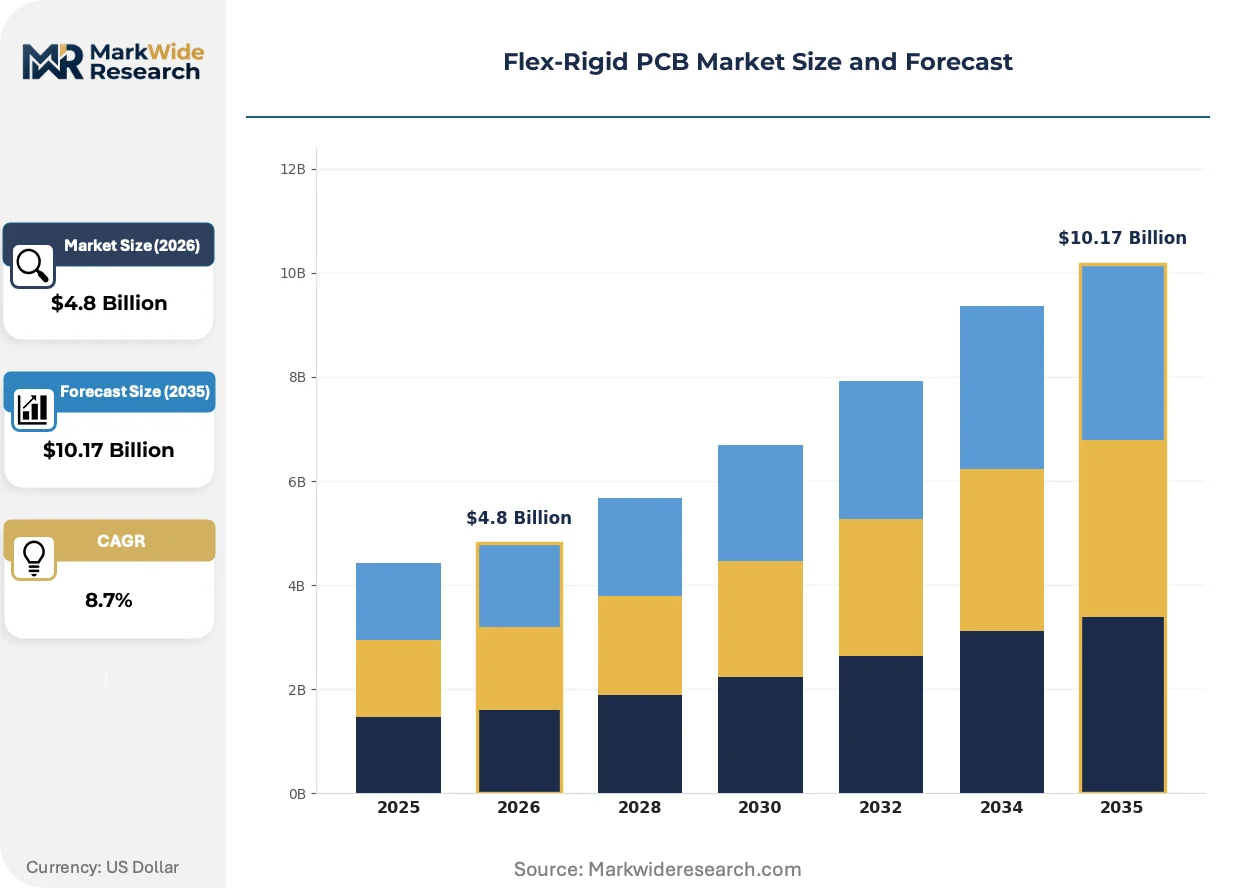
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided, Double-Sided, Multi-Layer, Rigid-Flex Application: Consumer Electronics, Medical Devices, Automotive, Aerospace Technology: Thermal Management, Signal Integrity, Surface Mount Technology, Embedded Components End User: OEMs, Contract Manufacturers, Electronics Assemblers, Research Institutions |
| Companies Covered | Zhen Ding Technology Holding Limited, Nippon Mektron, Ltd., Unimicron Technology Corporation, TTM Technologies, Inc., Interflex Co., Ltd., Sumitomo Electric Industries, Ltd., AT&S Austria Technologie & Systemtechnik AG, Flexium Interconnect, Inc., Meiko Electronics Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flex-Rigid PCB Market Trends and Innovations
Active developments across materials science, regulatory alignment, and procurement architecture are compressing product development cycles while elevating performance thresholds for high-density interconnection.
Adhesiveless polyimide bonding technology is unifying flexible circuit and rigid substrate fabrication into single-flow processes. Aerospace tier-1 suppliers are adopting these processes for satellite payload electronics, eliminating delamination risks in thermal cycling environments. This unification is compressing supplier qualification timelines from 18-month cycles toward 9-month benchmarks.
REACH restricted substance thresholds are tightening across the full material disclosure chain. ECHA enforcement of SVHC communication obligations now extends to imported subassemblies, forcing non-EU fabricators to deploy dedicated compliance documentation systems. Medical device contract manufacturers in Ireland and Germany are prioritizing suppliers with pre-validated halogen-free substrate libraries.
Specification-driven procurement is displacing price-first sourcing in high-reliability verticals. OEM engineering teams now embed IPC-6013 Class 3 requirements into initial RFQ documents, filtering respondent pools before commercial negotiation. This pattern is most pronounced in Swiss and Swedish diagnostic equipment supply chains, where ISO 13485 certification serves as a hard gate for design-in consideration.
Flex-Rigid PCB Market Segmentation
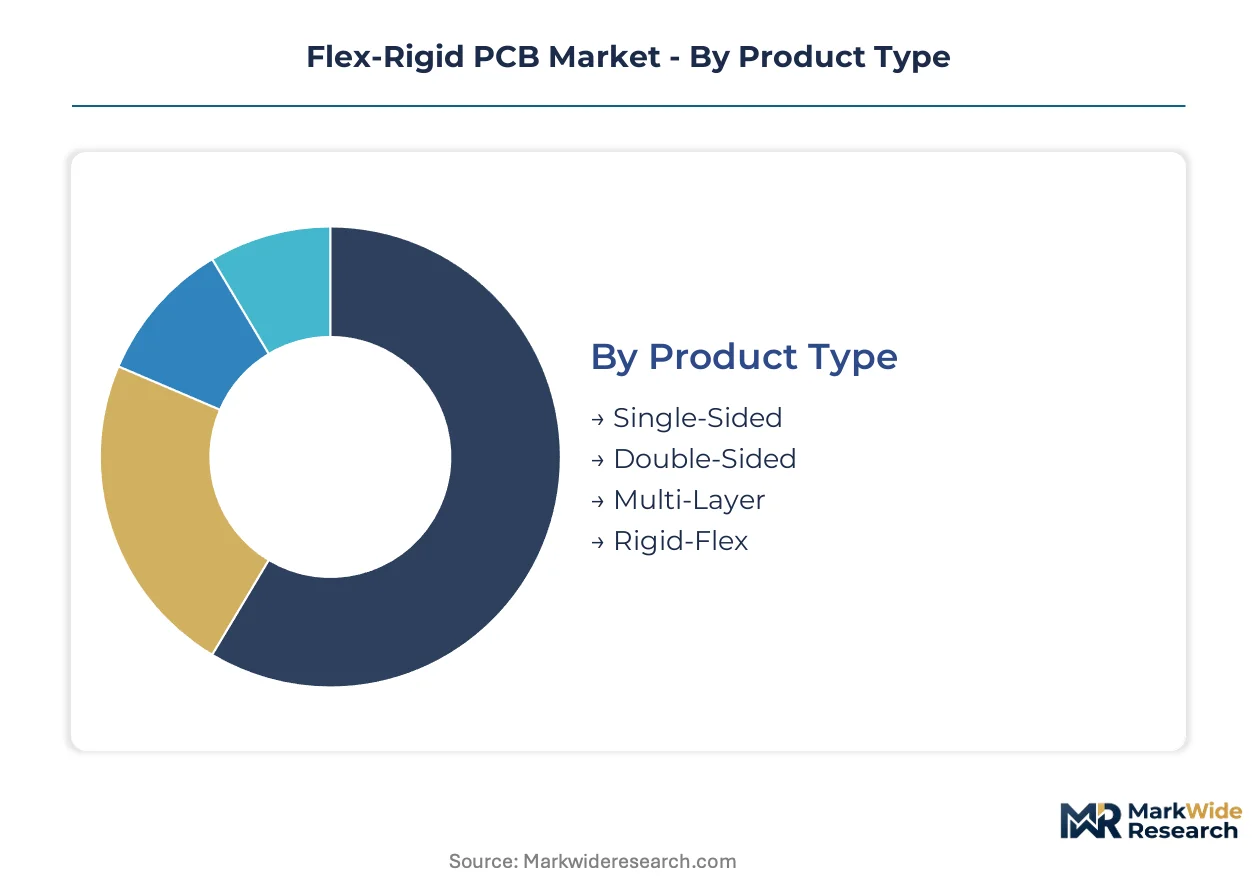
Flex-rigid PCB segmentation reveals how capital deployment, regulatory exposure, and end-use reliability requirements fragment manufacturing capabilities across distinct technical tiers. Procurement teams navigate these layers to match board complexity against qualification timelines and unit economics.
Product Type:
Multi-layer configurations demand the steepest upfront investment, requiring sequential lamination presses, laser drilling systems, and automated optical inspection lines that single-sided operations bypass entirely.
- Multi-Layer:Eight to twelve layer stacks with laser-drilled microvias and sequential lamination dominate aerospace and implantable medical electronics. Shenzhen-Dongguan cluster fabricators capture the bulk of qualification programs requiring IPC-6013 Class 3 validation.
- Rigid-Flex:Hybrid constructions bond polyimide flex sections to FR-4 or metal-core rigid substrates through plated through-hole interconnection. Foldable smartphone hinge modules in Chinese consumer electronics supply chains specify sub-3mm bend radii with impedance control to 10GHz.
- Double-Sided:Balanced density and cost for diagnostic equipment and wearable biosensor platforms.
- Single-Sided:Lowest barrier to entry; concentrated in prototyping and cost-constrained consumer applications.
Multi-layer absorbs the bulk of installed capacity; rigid-flex is expanding most quickly.
Application:
Medical device OEMs impose the most demanding qualification overhead, extending design-in cycles and filtering supplier pools through FDA and EU MDR documentation requirements.
- Medical Devices:Implantable electronics and diagnostic equipment mandate ISO 13485 certification and halogen-free substrate libraries. Irish and German contract manufacturers prioritize suppliers with pre-validated REACH compliance documentation.
- Aerospace:Satellite payload electronics require adhesiveless polyimide bonding to eliminate delamination risks during thermal cycling. Tier-1 suppliers compress qualification timelines from eighteen-month cycles toward nine-month benchmarks through unified fabrication flows.
- Automotive:Functional safety standards under ISO 26262 create timeline conflicts for suppliers serving parallel medical and mobility sectors.
- Consumer Electronics:Volume-driven procurement favors rapid prototyping turnaround from China's concentrated fabrication base.
Medical devices command premium positioning through regulatory barriers; consumer electronics drives volume scaling.
Technology:
Signal integrity capabilities separate high-reliability suppliers from commodity fabricators, with impedance control and high-speed routing demanding specialized equipment and process engineering.
- Signal Integrity:Impedance control to 10GHz and controlled dielectric constant specifications serve aerospace and medical high-speed routing requirements. Proprietary adhesiveless bonding techniques remain concentrated among patent-holding Japanese and Korean specialists.
- Thermal Management:Metal-core rigid sections and embedded heat spreaders address power dissipation in automotive electronics under China's GB standards.
- Embedded Components:Passive component integration into ultra-thin 4-6 layer stacks enables wearable biosensor miniaturization.
- Surface Mount Technology:Standard assembly integration for mid-density consumer and automotive applications.
Signal integrity commands the highest process engineering premiums; embedded components shows the steepest adoption trajectory in next-generation diagnostic platforms.
End User:
OEM procurement architecture increasingly embeds technical specifications into initial RFQ documents, filtering respondent pools before commercial negotiation begins.
- OEMs:Swiss and Swedish diagnostic equipment engineering teams require IPC-6013 Class 3 performance validation and ISO 13485 certification as hard gates for design-in consideration. Specification-driven procurement displaces price-first sourcing in these supply chains.
- Contract Manufacturers:Irish and German medical device CMs prioritize suppliers with pre-validated halogen-free substrate libraries to streamline EU MDR technical documentation.
- Electronics Assemblers:Volume-focused operations serving consumer electronics leverage Shenzhen-Dongguan cluster capacity for rapid turnaround.
- Research Institutions:Low-volume, high-mix requirements favor flexible prototyping relationships with smaller fabrication specialists.
OEMs concentrate strategic supplier development investment; contract manufacturers represent the fastest-climbing procurement channel as outsourcing deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's Qianhai Shenzhen-Hong Kong Modern Service Industry Cooperation Zone accelerates flex-rigid PCB cluster formation through tax incentives and bonded logistics facilities. This special-economic-zone framework concentrates multilayer fabrication capacity alongside upstream copper-clad laminate suppliers.
China
Implantable medical electronics and foldable smartphone hinge modules drive procurement from Shenzhen-Dongguan fabricators. GB standards for automotive electronics under MIIT harmonize with IPC frameworks for export qualification. The Pearl River Delta megaflex facilities batch-test every production lot for SVHC compliance under ECHA documentation requirements.
United States
Aerospace satellite payload electronics and diagnostic equipment OEMs specify adhesiveless polyimide bonding for thermal cycling reliability. FDA device classification rules extend qualification timelines for implantable flex-rigid suppliers. California's Bay Area hosts qualification programs for IPC-6013 Class 3 validation serving medical device contract manufacturers.
Germany
Automotive functional safety requirements under ISO 26262 create procurement specifications for high-reliability flex-rigid stacks. EU MDR technical documentation mandates REACH-compliant halogen-free substrate libraries. Bavaria's medical device contract manufacturers prioritize suppliers with pre-validated ECHA substance disclosure systems.
Japan
Proprietary adhesiveless polyimide bonding technology eliminates restricted halogenated compounds for aerospace and medical applications. METI industrial standards support high-frequency signal integrity specifications to 10GHz. Nagoya-area chemical specialists control high-purity polyimide feedstock supply for halogen-free substrate requirements.
Switzerland
Diagnostic equipment OEM engineering teams embed IPC-6013 Class 3 requirements into initial RFQ documents as hard gates. Swissmedic medical device regulations align with EU MDR technical documentation frameworks. Zurich-area procurement channels filter respondent pools through ISO 13485 certification before commercial negotiation begins.
Flex-Rigid PCB Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct capability tiers. The vendor base stratifies between megaflex facility operators achieving scale economies and mid-volume fabricators serving qualification-intensive medical and aerospace verticals. Three archetypes dominate: integrated substrate producers controlling resin-to-board purity, proprietary bonding technology holders, and scale-driven batch-testing specialists. Competitive moves concentrate on backward integration into copper-clad laminate production and geographic expansion through qualification program partnerships.
Within the integrated substrate tier, Zhen Ding Technology Holding Limited exemplifies captive control over material purity from resin synthesis through final etching. Among proprietary technology specialists, Nippon Mektron, Ltd. occupies a position defined by adhesiveless polyimide bonding processes. At the scale-driven compliance end, Unimicron Technology Corporation represents megaflex facility operators batch-testing every lot for SVHC thresholds.
| Leading Market Players |
|---|
| Zhen Ding Technology Holding Limited |
| Nippon Mektron, Ltd. |
| Unimicron Technology Corporation |
| TTM Technologies, Inc. |
| Interflex Co., Ltd. |
| Sumitomo Electric Industries, Ltd. |
| AT&S Austria Technologie & Systemtechnik AG |
| Flexium Interconnect, Inc. |
| Meiko Electronics Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Sequential lamination technology adoption simultaneously compresses fabrication economics and concentrates production capacity among megaflex facility operators in China's Pearl River Delta. REACH SVHC documentation requirements add compliance cost layers that filter smaller substrate suppliers from European-bound supply chains, reshaping competitive access to premium medical-grade segments.
Pricing Analysis
Lead-time-driven pricing stratification rewards rapid-turnaround qualification programs with premium positioning while spot inventory from Shenzhen-Dongguan clusters trades at compressed margins. Three-tier pricing structure across IPC-6013 Class 3 premium, standard automotive-grade, and economy consumer tiers reflects certification investment and batch-testing overhead. Cost compression in consumer electronics hinge modules intensifies as foldable smartphone OEMs consolidate supplier pools toward megaflex operators. Contract manufacturers serving EU medical device OEMs exhibit lowest price sensitivity due to MDR documentation lock-in effects.
Supply Chain Analysis
Process engineer scarcity across Taiwan, Japan, and China's coastal provinces constrains expansion of 8-12 layer stack registration capabilities. High-purity polyimide feedstock draws from Nagoya-area chemical specialists and Korean resin producers, tethering substrate purity to concentrated upstream chemistry capacity. Single-source vulnerability in adhesiveless bonding patent portfolios exposes aerospace qualification programs to licensing friction. Distribution runs through Shenzhen bonded logistics facilities for rapid prototyping, with finished boards shipping direct to German and Swiss diagnostic equipment contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH substance disclosure mandates construct a cost-of-compliance moat that rewards pre-validated halogen-free substrate libraries while filtering capital-constrained competitors from EU medical procurement channels.
For Market Incumbents: Hedge against adhesiveless bonding patent expiration risks by deepening captive control over copper-clad laminate purity from resin synthesis through final etching. Accelerate ISO 26262 functional safety certification investment to capture automotive electronics migration before timeline conflicts with medical sector qualification cycles strain capacity allocation.
For New Entrants and Emerging Players: Enter via diagnostic equipment miniaturization white space in wearable biosensor platforms requiring ultra-thin 4-6 layer stacks with embedded passive components. Target Ireland and Germany medical device contract manufacturer procurement channels by pre-building ECHA-compliant SVHC documentation systems before commercial engagement.
For Investors and Strategic Acquirers: Exit pathways concentrate in integrated substrate producers with backward control over halogen-free resin purity and established IPC-6013 Class 3 validation records. Long-term viability across the analysis window favors operators with megaflex scale and pre-validated REACH compliance infrastructure. Watch for GB standards harmonization completion as inflection signal for China export-oriented fabricator margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper-Clad Laminate | Captive substrate purity control enables premium medical-grade pricing and REACH compliance lock-in. |
| Adhesiveless Polyimide Bonding Patent Licensing | Proprietary lamination technology eliminates delamination risks for aerospace thermal cycling applications. |
| Megaflex Facility Capacity Expansion | Sequential lamination scale economies compress per-unit costs for high-layer-count medical and aerospace stacks. |
| Pre-Validated Halogen-Free Substrate Libraries | ECHA-compliant material disclosure systems accelerate EU MDR technical documentation approval timelines. |
| ISO 26262 Functional Safety Certification | Automotive qualification expands addressable market before medical-aerospace timeline conflicts intensify. |
Research Methodology
Document review covered IPC-6013 performance standards, ECHA SVHC candidate list updates, and FDA device classification guidance documents, complemented by interviews with PCB fabrication engineering directors, medical device OEM procurement managers, aerospace tier-1 supplier quality leads, and copper-clad laminate resin chemists. Secondary validation drew from MIIT GB standards publications, SEC 10-K filings of listed fabricators, and customs trade data for flex-rigid substrate imports. Bottom-up capacity modeling and top-down demand segmentation triangulated market sizing across product type, application, and end-user dimensions.
Cross-reference between historical qualification timeline data and expert panel input anchored growth trajectory assumptions across the projection horizon. Segmentation modeling captured multi-layer versus rigid-flex versus double-sided product tiers, medical versus aerospace versus automotive versus consumer electronics applications, and OEM versus contract manufacturer versus electronics assembler end-user channels. CAGRs derived from layer count expansion trends, foldable smartphone unit ramp assumptions, and implantable medical electronics regulatory approval velocity. High-purity polyimide feedstock pricing volatility and laser drilling equipment lead times informed scenario-weighted outputs.
Revisions become necessary when REACH restricted substance thresholds tighten beyond current ECHA candidate list scope, when adhesiveless bonding patent litigation reshapes technology access, or when GB standards harmonization stalls under MIIT implementation delays. Material deviation in these triggers warrants strategic pause and re-evaluation of capacity investment and qualification program prioritization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Global Smartphone Cover Glass Market
Electronic Components
Capacitor Aluminum Polymer Market
Electronic Components
US Supercapacitor Market
Electronic Components
Europe Water Cooled Capacitors Market
Electronic Components
Global Microfluidic Components Market
Electronic Components
North America USB Retimer Market
Electronic Components
Electromechanical Timers Market
Electronic Components
Audio Power Amplifier Market
Electronic Components
DVB/SAT Remote Controls Market
Electronic Components
North America Safety Relay and Timers Market
Electronic Components
Multi-Layer Ceramic Capacitor (MLCC) Market
Electronic Components
Coin Battery Holder Market
Electronic Components
Microspeaker Market
Electronic Components
Electrolytic Capacitor Market
Electronic Components
Electronic Shelf Label Market
Electronic Components
Audio Transistors Market