
 Organic Fixed Power Capacitors Sales Market | 2026-2036
Organic Fixed Power Capacitors Sales Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Fixed Power Capacitors Sales Market Insights
Southeast Asia is reconfiguring its electronics manufacturing footprint as Vietnam and Thailand add polymer film capacitor capacity to serve regional renewable energy build-outs. TDK leverages its ceramic-to-film technology bridge to anchor high-reliability supply chains for industrial inverter OEMs. Vishay competes through dielectric material specialization, particularly in high-temperature polypropylene formulations for automotive-grade power modules. WIMA GmbH & Co. KG sustains its position via precision film winding capabilities that dominate German industrial machinery retrofit markets.
Organic fixed power capacitors employ polymer, ceramic, or glass dielectric layers with metallized electrodes to store and condition electrical energy in AC and DC power systems, typically rated from low voltage through ultra high voltage classes depending on dielectric thickness and electrode geometry. Their primary purpose centers on power factor correction, harmonic filtering, and voltage stabilization across industrial drives and grid-connected inverters. Film-based segments occupy the margin-rich tier where polypropylene and polyester dielectrics command premium positioning for renewable energy inverters requiring extended thermal cycling life. Ceramic formulations lead unit volume in compact commercial equipment applications where space constraints override energy density requirements. Ultra high voltage categories represent the fastest-growing structural pocket as offshore wind and long-distance HVDC transmission projects multiply procurement specifications for oil-impregnated film capacitor banks.
EU REACH and RoHS frameworks restrict halogenated flame retardants and specific phthalates in capacitor housings and impregnation oils, compelling reformulation of organic dielectric systems toward bio-based ester chemistries. EPA regulations in the United States govern PCB contamination thresholds in legacy capacitor decommissioning, shaping replacement demand cycles and secondary material recovery protocols. China's GB standards and MIIT directives on dual carbon compliance are tightening efficiency benchmarks for power capacitors deployed in industrial motor drives. Stakeholders must monitor how divergent regional material compliance timelines fragment supply chain qualification requirements and force parallel product platform development.
Market Dynamics
EU F-Gas Regulation phase-down schedules and REACH substance restrictions are forcing capacitor manufacturers to abandon fluorinated dielectric gases and halogenated flame retardants, triggering parallel reformulation pipelines for biodegradable film chemistries and bio-based impregnation oils.
Growth Catalysts
- Offshore wind build-outs:HVDC transmission projects in Germany and Denmark are multiplying procurement specifications for oil-impregnated film capacitor banks rated at ultra high voltage classes.
- REACH compliance deadlines:ECHA substance evaluation timelines are compelling industrial automation OEMs to pre-qualify alternative dielectric formulations ahead of restriction enactment.
- Polypropylene film advances:Biaxial orientation process improvements are extending thermal cycling life for renewable energy inverters beyond 100,000 hours.
Market Restraints
- Metallized film supply concentration:Polypropylene resin and aluminum metallization capacity clusters in China and Germany, creating single-source vulnerability for tier-two capacitor assemblers.
- Bio-ester cost premiums:Castor oil-derived impregnation fluids trade at 40-60% above mineral oil equivalents, compressing margins on medium-voltage industrial capacitor lines.
- Ceramic dielectric substitution:MLCC technology advances in high-voltage ratings are displacing film capacitors in compact commercial equipment below 10 kV.
Strategic Opportunities
- Vietnam manufacturing expansion:Electronics clusters in Bac Ninh and Hai Phong are adding polymer film winding capacity to serve ASEAN solar inverter assembly.
- Dual carbon compliance in China:MIIT efficiency benchmarks for industrial motor drives are mandating power factor correction upgrades in legacy manufacturing facilities.
- Condition-based monitoring integration:Embedded capacitance sensors and predictive analytics are converging with film capacitor designs for grid-scale asset management.
Industry Challenges
- Polymer chemist scarcity:Formulation expertise in high-temperature polypropylene dielectrics concentrates among retiring specialists in German and Japanese capacitor divisions.
- Parallel qualification timelines:Divergent EU REACH, US EPA PCB thresholds, and China GB standards force manufacturers to maintain three separate product platforms for identical voltage ratings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Fixed Power Capacitors Sales Market |
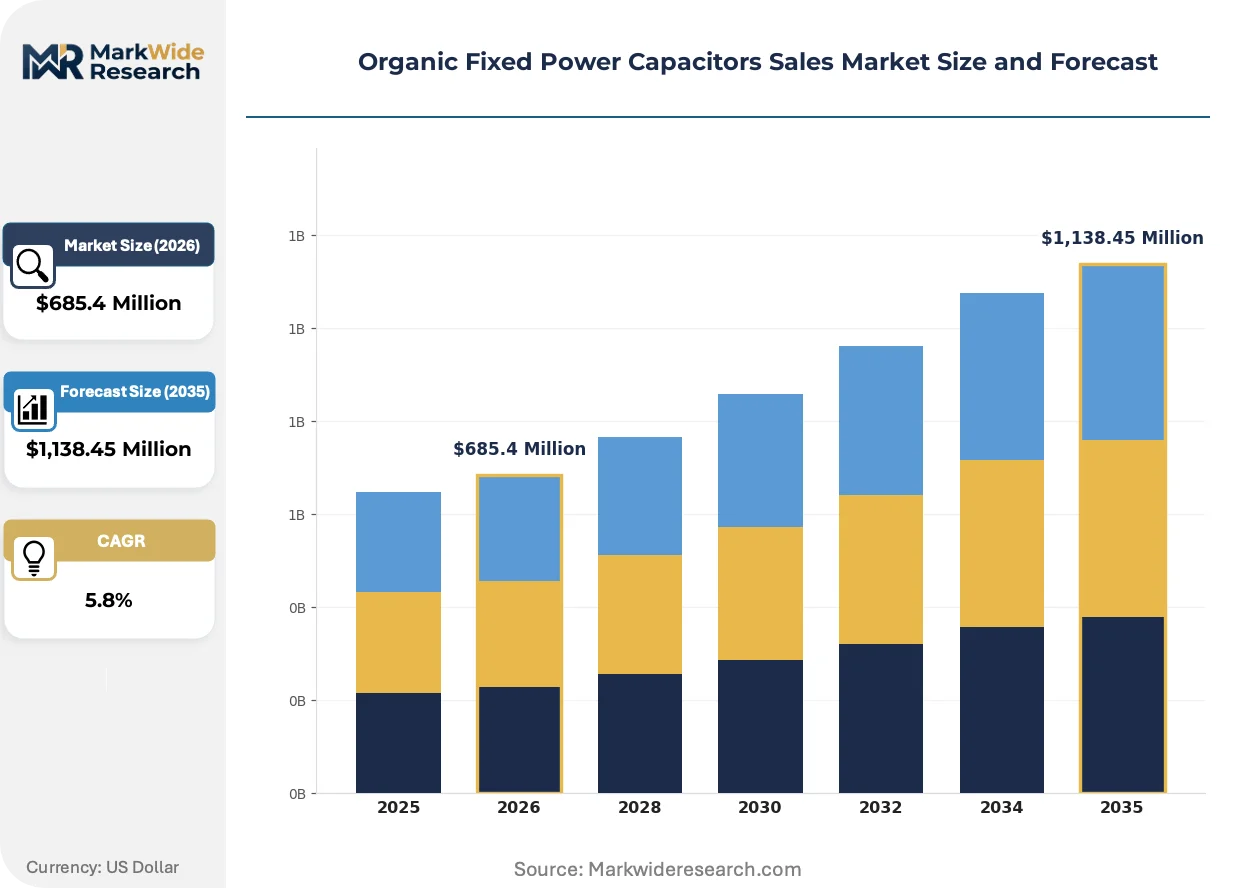
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Power Generation, Industrial Machinery, Renewable Energy, Commercial Equipment Material: Polymer, Ceramic, Film, Glass Capacity: Low Voltage, Medium Voltage, High Voltage, Ultra High Voltage End User: Manufacturers, Utilities, OEMs, Engineers |
| Companies Covered | TDK, Murata, Vishay, WIMA GmbH & Co. KG, KEMET Corporation, Illinois Capacitor, Inc., ABB Ltd., Schneider Electric SE, Eaton Corporation PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Fixed Power Capacitors Sales Market Trends and Innovations
Dielectric material science and manufacturing process control are converging to extend capacitor life cycles while regulatory chemistry restrictions are compressing formulation freedom, creating tension between performance durability and environmental compliance.
Metallized polypropylene film technology is hybridizing with segmented electrode patterns and self-healing layer architectures to contain failure propagation in grid-scale inverter applications. Siemens Gamesa and Vestas procurement specifications now mandate 30-year design life for offshore wind capacitor banks. This hybridizing architecture is compressing the addressable market for traditional all-film designs in ratings above 3.3 kV.
EU F-Gas Regulation Annex III phase-down schedules are banning perfluorocarbon and sulfur hexafluoride dielectric gases in capacitor impregnation systems by 2030. Manufacturers in Bavaria and Baden-Württemberg are accelerating bio-based ester trials to maintain CE marking eligibility. Ultra high voltage capacitor banks for HVDC converter stations face the steepest reformulation timeline, with prototype qualification cycles extending to 48 months.
Industrial inverter OEMs are consolidating supplier panels and demanding captive capacitor winding capacity within 500 kilometers of final assembly. This geographic consolidation is displacing fragmented distributor networks that historically served small-to-medium drive manufacturers. German automotive power module suppliers now specify direct mill relationships for polypropylene film rather than merchant capacitor procurement.
Organic Fixed Power Capacitors Sales Market Segmentation
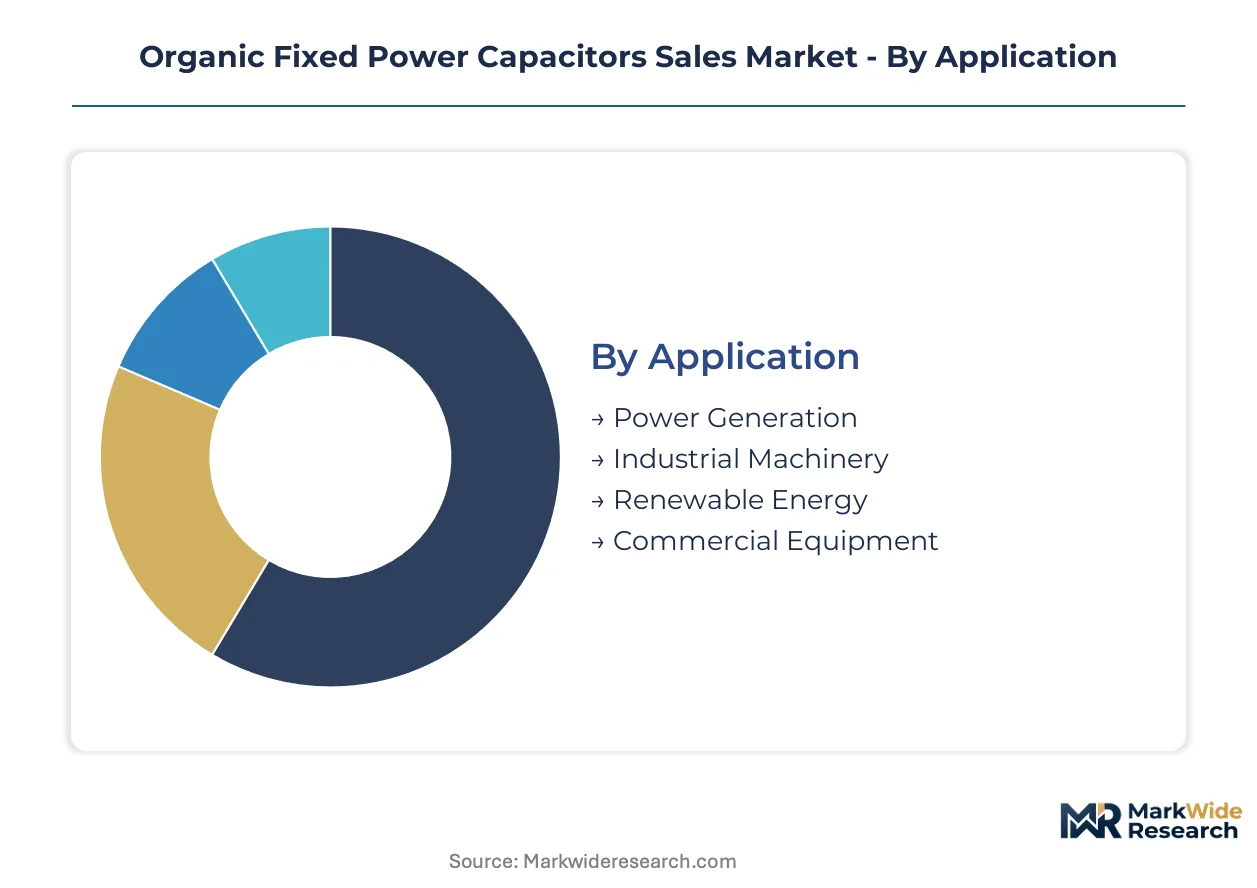
Segmentation in organic fixed power capacitors reveals distinct procurement cycles and margin structures across voltage classes and dielectric materials. Understanding these patterns allows suppliers to align inventory and qualification investments with actual replacement demand and new project timelines.
Application:
Replacement cycles vary dramatically across end-use contexts, with some segments demanding 30-year design life while others turn over in under a decade due to technology obsolescence.
- Power Generation:Capacitor banks in thermal and nuclear plants operate under steady-state conditions with scheduled 15-20 year replacement windows. ESKOM and NTPC procurement specifications emphasize oil-impregnated film designs for baseload stability, though coal plant retirements in Germany and the United States are compressing addressable volume.
- Renewable Energy:Solar inverters and wind turbine converters impose severe thermal cycling stress, driving demand for biaxially oriented polypropylene with metallized self-healing architectures. Procurement from Vestas and Siemens Gamesa mandates 100,000-hour life certification, creating qualification barriers for second-tier suppliers.
- Industrial Machinery:Motor drive applications across German automation clusters favor compact film capacitors for power factor correction. MIIT efficiency mandates in China are accelerating retrofit demand in legacy manufacturing facilities.
- Commercial Equipment:HVAC systems and uninterruptible power supplies prioritize unit cost over extended life, with ceramic dielectrics dominating below 10 kV ratings. MLCC substitution is eroding film capacitor share in this tier.
Industrial Machinery dominates installed base. Renewable Energy is where expansion concentrates.
Material:
Cost tiers separate segments by raw material intensity and processing complexity, with bio-based formulations commanding premium positioning.
- Film:Metallized polypropylene and polyester dielectrics anchor premium pricing through biaxial orientation precision and self-healing layer engineering. German wind energy OEMs specify direct mill relationships for polypropylene resin, bypassing merchant capacitor distributors.
- Polymer:Advanced polymer formulations incorporating bio-based ester impregnation systems are qualifying under EU REACH deadlines. Castor oil-derived chemistries trade at substantial premiums over mineral oil equivalents, compressing margins on medium-voltage industrial lines.
- Ceramic:MLCC technology serves compact commercial applications where space constraints override energy density requirements. Japanese suppliers lead high-voltage ceramic ratings that now displace film below 10 kV.
- Glass:Specialized glass dielectrics occupy niche ultra high voltage applications requiring extreme thermal stability. Limited supplier base and batch processing constraints restrict volume scalability.
Film commands the margin-rich tier. Polymer is climbing the fastest as REACH compliance deadlines force reformulation.
Capacity:
Supply concentration intensifies with voltage rating, as ultra high voltage categories demand specialized winding equipment and extended qualification protocols.
- Ultra High Voltage:Oil-impregnated film banks for HVDC converter stations and offshore wind collection systems require 48-month prototype qualification cycles. Procurement specifications from TenneT and National Grid mandate 30-year design life with embedded condition monitoring.
- High Voltage:Grid-scale inverter applications in the 3.3-30 kV range hybridize segmented electrode patterns with self-healing architectures. Siemens and ABB supplier panels are consolidating around captive winding capacity within 500 kilometers of final assembly.
- Medium Voltage:Industrial motor drives and distribution automation represent high-volume, price-sensitive demand. Chinese GB efficiency standards are mandating power factor correction upgrades across legacy manufacturing infrastructure.
- Low Voltage:Commercial and residential applications face severe ceramic substitution pressure. Distribution runs through fragmented distributor networks serving small-to-medium equipment manufacturers.
Medium Voltage holds volume leadership. Ultra High Voltage is gaining share fastest as offshore wind build-outs multiply.
End User:
Customer type determines procurement sophistication, with direct OEM relationships replacing traditional distribution for high-reliability applications.
- Utilities:Transmission system operators specify ultra high voltage capacitor banks with integrated predictive maintenance systems. Procurement centralization around grid-scale asset management platforms is displacing spot purchasing.
- OEMs:Industrial inverter and wind turbine manufacturers demand captive capacitor winding capacity co-located with final assembly. Direct mill relationships for polypropylene film are replacing merchant procurement.
- Engineers:Consulting engineers and EPC contractors influence specification during project design phase, creating early engagement opportunities for qualification-intensive applications.
- Manufacturers:Small-to-medium drive and equipment manufacturers remain dependent on distributor networks, though panel consolidation is reducing supplier count.
Utilities anchor long-cycle demand. OEMs are where supplier consolidation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA substance evaluation timelines under EU REACH are compelling industrial automation OEMs across Germany to pre-qualify alternative dielectric formulations ahead of restriction enactment, anchoring the dominant geography for organic fixed power capacitor demand.
Germany
Industrial automation clusters in Bavaria and Baden-Württemberg drive premium-grade capacitor uptake for motor drives and power factor correction. The EU F-Gas Regulation Annex III phase-down schedules are banning perfluorocarbon dielectric gases by 2030, forcing manufacturers in Bavaria to accelerate bio-based ester trials. Siemens Gamesa procurement specifications from Hamburg mandate 30-year design life for offshore wind capacitor banks.
China
MIIT efficiency benchmarks for industrial motor drives are mandating power factor correction upgrades across legacy manufacturing facilities in the Yangtze River Delta. GB standards and dual carbon compliance directives are tightening efficiency benchmarks for power capacitors deployed in heavy industry. Polypropylene resin and aluminum metallization capacity clusters in Jiangsu and Zhejiang provinces create supply concentration for tier-one assemblers.
United States
EPA regulations governing PCB contamination thresholds in legacy capacitor decommissioning are shaping replacement demand cycles across utility infrastructure. FERC grid reliability mandates are accelerating procurement of condition-monitored capacitor banks for transmission system operators. Industrial inverter OEMs in Texas and the Midwest are consolidating supplier panels around captive winding capacity within 500 kilometers of final assembly.
Vietnam
Electronics manufacturing clusters in Bac Ninh and Hai Phong are adding polymer film winding capacity to serve ASEAN solar inverter assembly demand. The country's national industrial regulator is implementing efficiency standards aligned with regional green energy transition commitments. Renewable energy developers are expanding procurement of organic dielectric capacitors for grid-scale inverters manufactured in northern industrial zones.
Denmark
HVDC transmission projects connecting offshore wind farms to continental Europe are multiplying procurement specifications for oil-impregnated film capacitor banks. National grid operator Energinet is mandating embedded condition monitoring systems for ultra high voltage capacitor installations. Vestas procurement specifications from Aarhus require 100,000-hour life certification for wind turbine converter applications.
Organic Fixed Power Capacitors Sales Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. German and Japanese specialists dominate high-temperature polypropylene formulation expertise, while East Asian fabricators anchor volume production for commercial equipment tiers. Three archetypes define competitive positioning: dielectric material specialists, precision winding engineers, and integrated power electronics suppliers. M&A activity is consolidating captive film supply relationships, and geographic co-location with inverter OEMs is displacing traditional distributor networks.
Among Japanese component manufacturers, TDK and Murata occupy positions bridging ceramic-to-film technology for industrial reliability applications. Vishay represents the material specialization archetype through its focus on high-temperature formulations. WIMA GmbH & Co. KG exemplifies the precision engineering tier with its German-based film winding capabilities for industrial machinery retrofit markets. These three anchors illustrate how competitive positioning stratifies between material science depth, manufacturing precision, and supply chain proximity to end-use demand.
| Leading Market Players |
|---|
| TDK |
| Murata |
| Vishay |
| WIMA GmbH & Co. KG |
| KEMET Corporation |
| Illinois Capacitor, Inc. |
| ABB Ltd. |
| Schneider Electric SE |
| Eaton Corporation PLC |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on Chinese polypropylene resin and German aluminum metallization capacity determines both pricing tier spreads and supply chain shape in organic fixed power capacitors. Bio-ester impregnation fluid shortages under EU F-Gas Regulation timelines are compressing margins on medium-voltage industrial lines while forcing geographic consolidation of captive winding capacity.
Pricing Analysis
German wind energy OEMs pay 40-60% premiums over Southeast Asian solar inverter assemblers for identical voltage-rated film capacitors. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified bio-based formulations from mineral oil equivalents and ceramic substitutions. Cost compression in low-voltage commercial tiers is intensifying because MLCC technology advances displace film below 10 kV. Small-to-medium drive manufacturers exhibit highest price sensitivity; utilities procuring ultra high voltage banks with embedded condition monitoring exhibit lowest.
Supply Chain Analysis
Contract manufacturing concentrates among German precision winding specialists and Vietnamese electronics clusters adding polymer film capacity in Bac Ninh and Hai Phong. Raw material supply draws from Chinese polypropylene resin production, German aluminum metallization facilities, and Indian castor oil bio-ester processors. Single-source vulnerability on biaxially oriented polypropylene film creates exposure for tier-two capacitor assemblers. Distribution runs through consolidated direct mill relationships for OEMs and fragmented distributor networks for small equipment manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as divergent regional compliance timelines force parallel product platform development, creating specialist niches for dielectric formulation chemists and precision winding engineers.
For Market Incumbents: Harden supply chain resilience through backward integration into polypropylene film production in Bavaria and Baden-Württemberg. Accelerate bio-based ester qualification ahead of ECHA substance evaluation deadlines. Lock captive winding capacity within 500 kilometers of Vestas and Siemens Gamesa final assembly to defend against Vietnamese cost competition.
For New Entrants and Emerging Players: Vietnamese solar inverter assembly clusters offer the most penetrable white-space target, with ASEAN renewable energy build-outs outpacing local polymer film capacitor supply. Target industrial machinery retrofit markets in China's Yangtze River Delta where MIIT efficiency mandates accelerate replacement demand. Qualify under dual carbon compliance directives as a differentiated go-to-market angle.
For Investors and Strategic Acquirers: EU F-Gas Regulation Annex III phase-down schedules reshape the acquisition landscape toward bio-based ester formulation capabilities. Five-to-ten year viability favors precision winding specialists with direct OEM relationships over merchant capacitor distributors. Monitor ECHA substance restriction enactment timelines as the signal indicating consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polypropylene Film | TDK and Vishay secure resin supply against Chinese export constraints for renewable energy OEMs. |
| Bio-Based Ester Qualification Program | WIMA GmbH & Co. KG maintains CE marking eligibility under EU REACH substance restrictions. |
| Captive Winding Capacity Expansion | Vietnamese electronics clusters in Bac Ninh serve ASEAN solar inverter assembly demand. |
| Condition Monitoring Integration | Energinet mandates embedded sensors for ultra high voltage capacitor bank procurement. |
| REACH Pre-Qualification Partnerships | German automation OEMs lock alternative dielectric formulations ahead of restriction enactment. |
Research Methodology
The analysis maps film dielectric, polymer bio-ester, ceramic MLCC, and glass ultra high voltage segments, each validated through capacitor R&D directors, wind turbine procurement managers, industrial drive OEM supply chain leads, and utility asset management officers. Primary interviews triangulate with secondary validation from ECHA substance evaluation databases, MIIT efficiency standard filings, FERC grid reliability reports, and customs trade data on polypropylene resin flows. Bottom-up capacitor shipment aggregation and top-down renewable energy inverter deployment forecasts cross-validate volume estimates.
Assumption sets held EU F-Gas Regulation phase-down schedules and REACH substance restriction timelines as fixed policy drivers while varying offshore wind build-out intensity and ceramic substitution rates across the projection horizon. Segmentation models incorporate voltage class, dielectric material, application end-use, and regional regulatory cluster dimensions. CAGRs derive from installed base replacement cycles and new project procurement specifications, with biaxial orientation process yield improvements and bio-ester cost curves as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese integrated power electronics suppliers or accelerated ceramic MLCC voltage rating advances would shift outcomes. Quarterly review of ECHA substance evaluation progress, MIIT efficiency mandate enforcement, and Vestas procurement specification updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
DC Power Supplies Market
Power Systems
Linear Voltage Regulators Market
Power Systems
Ultrafast Rectifiers Market
Power Systems
Transformer Tap Changers and Voltage Control Relay Market
Power Systems
Battery Equalizer Market
Power Systems
Global Battery Thermal Management System Market
Power Systems
Japan Vacuum Pressure Impregnated (VPI) Transformer Market
Power Systems
Asia-Pacific DC Distribution Networks Market
Power Systems
Gan-Powered Chargers Market
Power Systems
Photovoltaic Inverters Market
Power Systems
Battery Racks Market
Power Systems
Hybrid Inverters Market
Power Systems
Train Auxiliary Rectifier Market
Power Systems
Smart Power Strips Market
Power Systems
Global Excitation Systems Market
Power Systems
Solid State Transformer Market