
 Speaker Cone Material Market | 2026-2036
Speaker Cone Material Market Size, Share, and Industry Trends Forecast 2026-2036
Speaker Cone Material Market Analytics
The capability gap between vertically integrated cone manufacturers and outsourced assemblers is collapsing as raw material volatility reshapes cost structures. Dr. Kurt Muller GmbH & Co, KG leverages in-house pulp treatment and pressing operations to sustain margin control across European supply chains. B&C Speakers anchors its competitive position through dedicated polypropylene compounding lines that dominate professional audio OEM channels. SB Acoustics differentiates via Kevlar-composite formulations that occupy the premium studio monitor segment.
Speaker cone material encompasses engineered substrates—pulp blends, thermoplastic polymers, aramid fibers, and metal alloys—formed into diaphragms with controlled mass, stiffness, and internal damping to convert electrical signals into acoustic output with minimal harmonic distortion. Pulp formulations retain dominance in high-fidelity applications where natural fiber damping characteristics outperform synthetics, while polypropylene competes aggressively on cost and moisture resistance in automotive and outdoor installations. Kevlar-reinforced composites command the fastest expansion trajectory among material types as professional audio and home theater applications prioritize rigidity-to-weight ratios for extended frequency response.
The EPA governs volatile organic compound emissions from cone manufacturing adhesives and coatings in the United States, while REACH restricts hazardous substances in imported speaker components across European markets. China's SAMR enforces GB standards for electronic audio product safety and material labeling, creating compliance cost tiers that favor larger suppliers with dedicated certification laboratories. Stakeholders must monitor evolving chemical restriction schedules and automotive interior air quality mandates that will determine which material platforms retain market access across major economies.
Market Dynamics
Automotive electrification is compressing cone material specifications as EV cabin acoustics demand lighter diaphragms with extended mid-range clarity, forcing pulp formulators to engineer density below 0.45 g/cm³ without sacrificing stiffness.
Growth Catalysts
- REACH chemical restrictions:European hazardous substance limits on cone binders are accelerating migration toward water-based adhesive platforms certified for automotive interior air quality.
- Kevlar-composite rigidity:Professional studio monitor OEMs specify aramid-reinforced substrates for controlled breakup behavior above 8 kHz, displacing treated paper in mastering-grade installations.
- Stuttgart-Eching cluster:Germany's precision audio manufacturing concentration sustains specialized pulp treatment expertise unavailable in distributed supply bases.
Market Restraints
- Softwood pulp volatility:Nordic kraft pulp spot pricing swings of 40% within 18-month cycles destabilize cost structures for natural fiber cone specialists lacking long-term fiber supply contracts.
- Polypropylene feedstock concentration:Middle Eastern propylene derivative supply dominates global resin pricing, exposing compounders to freight arbitrage and currency hedging complexity.
- Moisture absorption ceiling:Untreated cellulose cones face dimensional stability limits above 75% relative humidity, constraining deployment in tropical marine and outdoor PA applications.
Strategic Opportunities
- India BIS certification pathway:Mandatory IS 616 safety standards for electronic audio products create first-mover advantage for cone suppliers establishing accredited testing partnerships in Mumbai and Bengaluru.
- Biomass-derived thermoplastics:Polyhydroxyalkanoate and lignin-reinforced compounds converge with circular economy mandates to unlock automotive OEM sustainability scorecard compliance.
- Direct-to-OEM digital sampling:Parametric cone specification platforms bypass distributor markup layers, enabling small-batch custom formulation for boutique monitor manufacturers.
Industry Challenges
- Pulp rheology expertise scarcity:Formulation chemists capable of tuning fiber length distribution and freeness for targeted Qts parameters command premium compensation in a shallow talent pool.
- Multi-jurisdiction certification timelines:Simultaneous EPA VOC adhesive validation, REACH SVHC screening, and China GB 8898 safety testing extend product launch cycles by 14-22 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Speaker Cone Material Market |
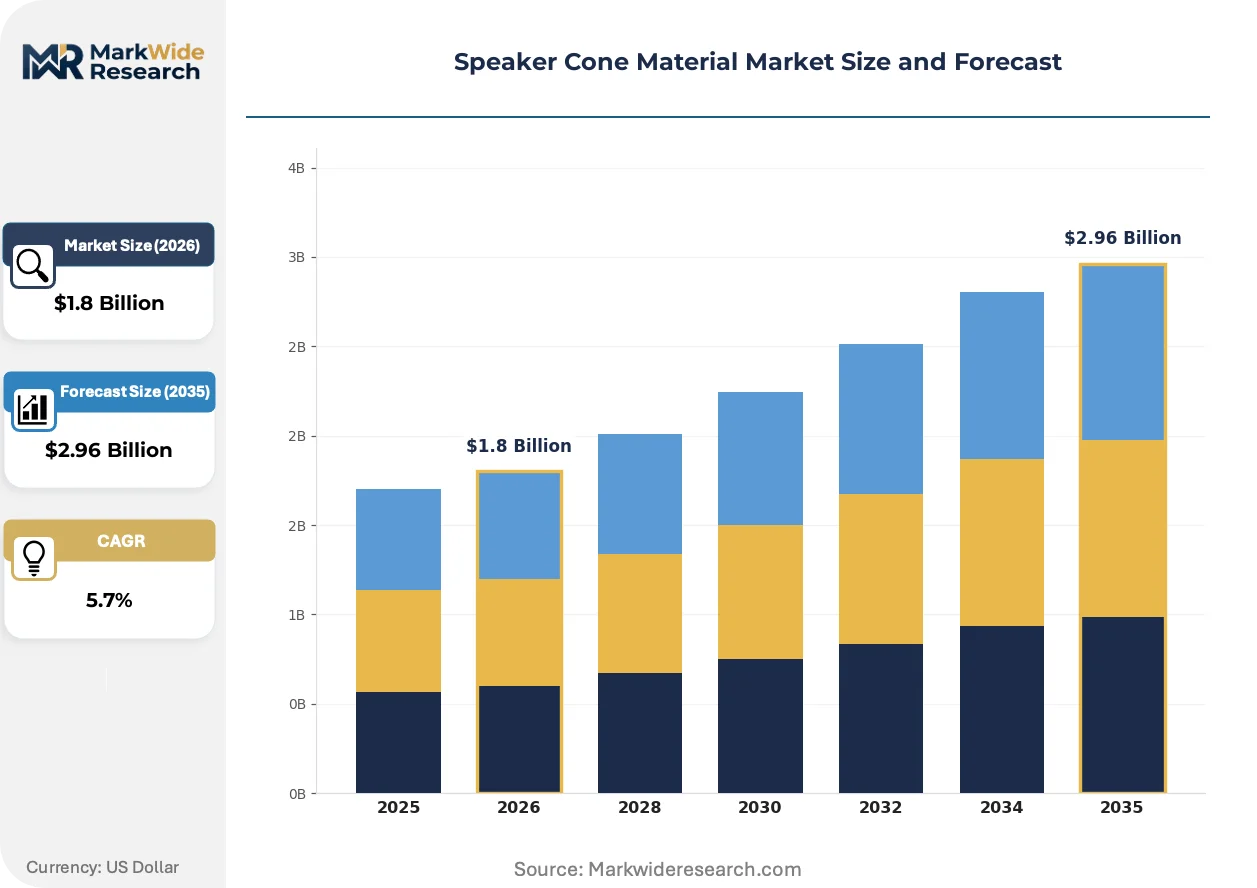
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Pulp, Polypropylene, Kevlar, Aluminum End User: Home Audio, Professional Audio, Automotive, Industrial Size: 4 inch, 8 inch, 12 inch, 15 inch Application: Home Theater, Sound Reinforcement, Musical Instruments, Multimedia |
| Companies Covered | Loudspeaker Components LLC, B&C Speakers, Dr. Kurt Muller GmbH & Co, KG, SB Acoustics, RTP Company, Harbeth Audio Ltd., Wharfedale, Vansonic Enterprise Co., Ltd, Hypex Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Speaker Cone Material Market Evolving Landscape
Material science convergence with automotive sustainability mandates is redefining cone specification criteria across passenger EV, professional audio, and consumer electronics channels simultaneously.
Hybrid pulp-synthetic laminates is bifurcating high-fidelity cone construction as diaphragm engineers bond micro-thin polypropylene skins to cellulose cores for moisture barrier performance without mass penalty. Premium automotive OEMs specify these constructions for door-mounted midbass drivers where thermal cycling and humidity exposure degrade pure pulp formulations. The technology is bifurcating supplier tiers between integrated pulp treatment-compounding operations and pure material converters lacking lamination capability.
China's GB standards enforcement through SAMR is tightening material traceability requirements for electronic audio components entering domestic distribution, compelling cone manufacturers to implement batch-level chemical composition documentation. Imported speaker assemblies now face mandatory disclosure of binder resin formulations and heavy metal content in metallic cone variants. European suppliers with pre-existing REACH documentation systems are adapting these data architectures to satisfy parallel Chinese compliance demands.
Specification behavior among professional audio procurement teams is compressing supplier qualification cycles as touring sound rental companies demand rapid cone replacement inventory without long-term vendor lock-in. Digital acoustic measurement standards enable remote validation of replacement diaphragm Thiele-Small parameters, reducing reliance on legacy distributor technical support relationships. This pattern concentrates in Germany's live event technology procurement channels where rental fleet standardization across multiple manufacturer platforms drives component-level sourcing autonomy.
Speaker Cone Material Market Segmentation
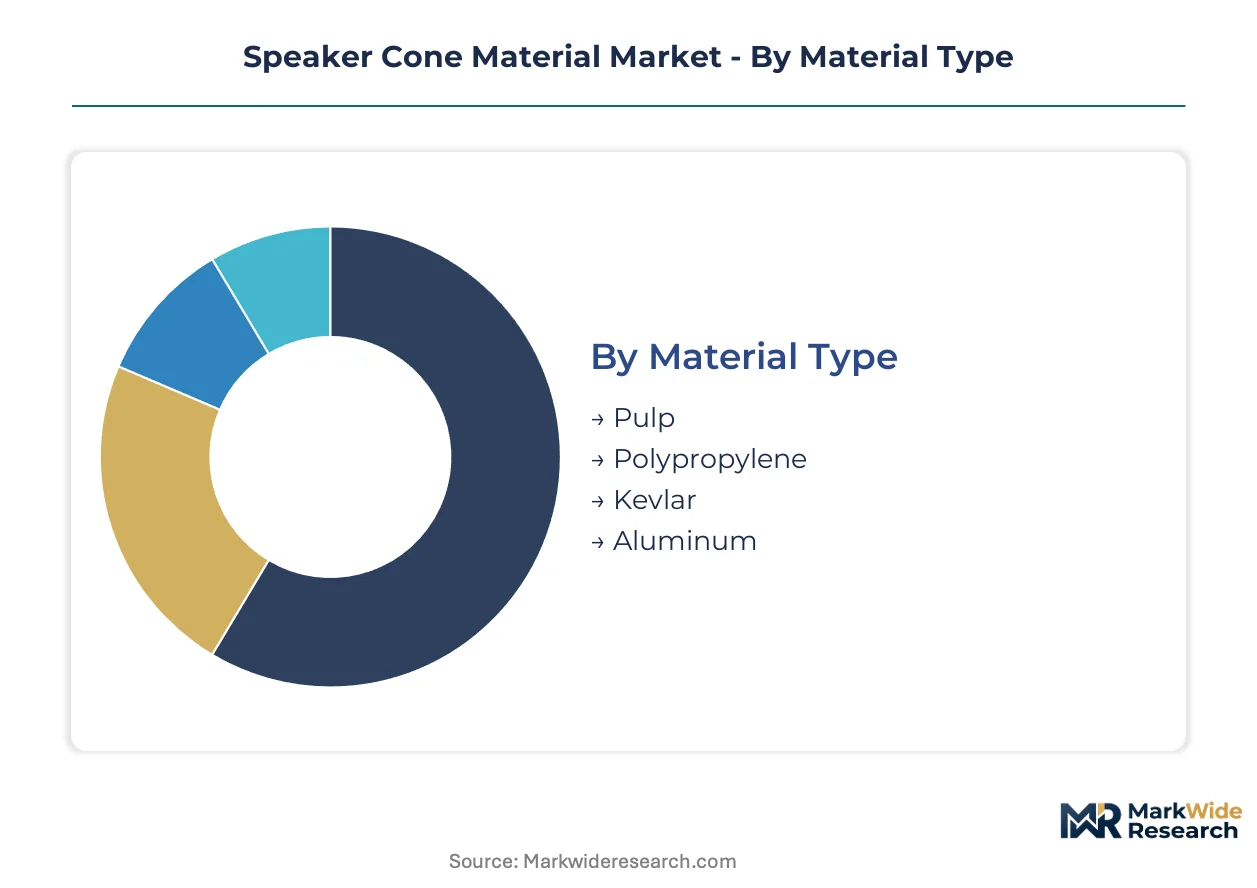
Material specifications for speaker cones diverge sharply across end-use channels, with automotive electrification and professional studio monitoring pulling formulations in opposite directions on density and damping targets. Segmentation reveals how supplier capabilities align with distinct performance-cost tradeoffs rather than universal substitution.
Material Type:
Pulp formulations dominate domestic supply chains in Germany and Japan where precision audio manufacturing clusters sustain captive fiber treatment expertise, while polypropylene and aluminum variants flow through export-oriented compounding operations in China and the Middle East.
- Pulp:Engineered cellulose fiber matrices with controlled freeness and lignin content deliver natural damping characteristics prized in high-fidelity applications. Demand concentrates in Stuttgart-Eching precision manufacturing corridors and Japanese OEM supply chains where fiber rheology expertise commands premium positioning. REACH chemical restrictions on traditional binders are accelerating water-based adhesive migration without sacrificing acoustic performance.
- Kevlar:Aramid-reinforced composites achieve rigidity-to-weight ratios above 10 GPa/(g/cm³) for extended frequency response in professional monitoring. Professional studio monitor procurement in Germany and live sound rental channels in the United States specify these substrates for controlled breakup behavior above 8 kHz, displacing treated paper in mastering-grade installations.
- Polypropylene:Thermoplastic diaphragms offer moisture resistance and cost efficiency for automotive door panels and outdoor PA systems.
- Aluminum:Metal alloy cones provide thermal stability and pistonic behavior for compression driver applications and high-SPL professional installations.
Pulp holds the largest share; momentum sits with Kevlar as professional audio specification tightens.
End User:
Customer procurement patterns separate into volume-driven automotive programs with 36-month qualification cycles versus boutique professional audio orders requiring parametric customization at sub-thousand-unit scale.
- Automotive:EV cabin acoustics specifications demand diaphragm densities below 0.45 g/cm³ with extended mid-range clarity for lightweight door-mounted arrays. European OEMs in Germany and premium electric vehicle manufacturers in the United States are compressing cone material specifications simultaneously with sustainability scorecard mandates favoring bio-derived substrates.
- Professional Audio:Touring sound rental companies and studio monitor OEMs prioritize rapid cone replacement inventory with verified Thiele-Small parameter consistency. Germany's live event technology procurement channels concentrate component-level sourcing autonomy where digital acoustic measurement standards enable remote validation without distributor technical support.
- Home Audio:Consumer electronics channels balance aesthetic finishing with acoustic performance for bookshelf and floor-standing loudspeaker systems.
- Industrial:Public address and commercial sound installations require environmental durability across humidity and temperature extremes.
Automotive commands the greatest volume; professional audio shows the steepest specification escalation.
Size:
Diaphragm diameter selection tracks enclosure volume constraints and target frequency response, with mid-range sizes serving cross-over points in multi-way systems.
- 4 inch:Compact midrange and full-range drivers for automotive dashboard arrays and portable professional monitors where space constraints dominate.
- 8 inch:Midbass applications in home theater and studio nearfield monitors balance low-frequency extension with directivity control.
- 12 inch:Subwoofer and bass guitar loudspeaker applications where excursion linearity and thermal power handling determine reliability in touring environments.
- 15 inch:Large-format sound reinforcement and musical instrument backline systems requiring maximum acoustic output per driver.
Eight-inch configurations anchor the largest installed base; fifteen-inch variants climb fastest on live event infrastructure investment.
Application:
Use-case environments dictate moisture barriers, UV stability, and cosmetic finishing requirements that filter material eligibility beyond raw acoustic parameters.
- Sound Reinforcement:Touring and installed PA systems demand rapid field replaceability and consistent batch-to-batch parameters across global rental fleets. Digital specification platforms bypass traditional distributor relationships in Germany and United States procurement channels.
- Home Theater:Multi-channel residential installations prioritize aesthetic grille compatibility and voicing consistency across matched speaker arrays.
- Musical Instruments:Bass guitar and keyboard amplification requires specific breakup characteristics and thermal durability under continuous high-SPL operation.
- Multimedia:Computer speakers, soundbars, and portable Bluetooth devices compete on cost and moisture resistance at mass production scale.
Sound reinforcement captures the most demanding specification environment; multimedia shows the greatest cost compression pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany's Stuttgart-Eching precision manufacturing corridor exceeds that of Chinese export-oriented compounding zones by substantial margins, reflecting captive fiber treatment expertise versus standardized resin formulation. European REACH compliance costs and automotive OEM sustainability scorecards concentrate value capture in Western supply chains. Asian manufacturers compete on polypropylene volume and moisture-resistant thermoplastic derivatives.
United States
Professional audio touring companies and live event rental fleets drive specification escalation for rapid-replacement cone inventory. EPA VOC adhesive regulations govern cone manufacturing emissions from pressing operations and coating applications. Nashville and Los Angeles anchor studio monitor OEM procurement channels where digital Thiele-Small parameter validation enables component-level sourcing autonomy.
Germany
Automotive electrification compresses diaphragm density specifications below 0.45 g/cm³ for EV cabin acoustic arrays while REACH chemical restrictions accelerate water-based adhesive migration. ECHA hazardous substance limits on cone binders reshape material qualification protocols. Stuttgart-Eching precision manufacturing clusters sustain specialized pulp rheology expertise unavailable in distributed supply bases.
China
Polypropylene compounding operations and thermoplastic diaphragm exports dominate volume manufacturing for automotive door panels and outdoor PA systems. SAMR enforces GB standards for electronic audio product safety and batch-level chemical composition documentation. Guangdong and Zhejiang provinces concentrate resin formulation capacity serving domestic OEM assembly and Southeast Asian export channels.
Japan
High-fidelity pulp formulation expertise serves domestic precision audio OEM supply chains with engineered cellulose fiber matrices. METI industrial standards and JIS certification requirements filter material eligibility for consumer electronics integration. Osaka-Kobe manufacturing corridors sustain captive fiber treatment operations for premium loudspeaker diaphragm production.
India
Mandatory BIS IS 616 safety standards for electronic audio products create certification barriers for imported cone assemblies. Mumbai and Bengaluru testing partnerships offer first-mover positioning for suppliers establishing accredited validation capacity. Maharashtra and Karnataka electronics manufacturing zones concentrate domestic loudspeaker assembly operations serving consumer and automotive aftermarket channels.
Speaker Cone Material Market Competitive Landscape
Concentration sits with integrated pulp treatment specialists and dedicated thermoplastic compounders rather than pure material converters lacking lamination or fiber rheology capabilities. European manufacturers control premium specification channels through captive supply chain stages. Three archetypes dominate: vertically integrated fiber formulators, polypropylene volume compounders, and aramid-reinforced composite specialists. Competitive moves center on backward integration into raw material supply and geographic expansion through accredited testing partnerships in emerging certification jurisdictions.
Among German GmbH-structured specialists, Dr. Kurt Muller GmbH & Co, KG exemplifies the integrated pulp treatment archetype with in-house pressing operations. B&C Speakers anchors the thermoplastic compounding tier through dedicated polypropylene lines. SB Acoustics occupies the premium composite position with Kevlar-reinforced formulations. These three represent distinct capability vectors rather than interchangeable substitution options.
| Leading Market Players |
|---|
| Loudspeaker Components LLC |
| B&C Speakers |
| Dr. Kurt Muller GmbH & Co, KG |
| SB Acoustics |
| RTP Company |
| Harbeth Audio Ltd. |
| Wharfedale |
| Vansonic Enterprise Co., Ltd |
| Hypex Electronics |
| Others |
Value Network & Pricing Analysis
Long-term pulp supply contracts lock in both fiber access and cost visibility for German cone manufacturers facing Nordic kraft spot volatility. These arrangements insulate integrated formulators from 18-month pricing swings while forcing non-integrated assemblers into spot market exposure.
Pricing Analysis
Configured-to-order pricing for Kevlar-composite cones commands substantial premiums over standard polypropylene diaphragms in professional audio channels. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with REACH-compliant water-based formulations carrying adhesive cost premiums. Pricing pressure stems from polypropylene feedstock concentration in Middle Eastern propylene derivatives, exposing compounders to freight arbitrage. Automotive OEMs exhibit highest price sensitivity due to sustainability scorecard mandates, while studio monitor manufacturers prioritize performance consistency over unit cost.
Supply Chain Analysis
Strait of Malacca transit underwrites resin supply security for Southeast Asian polypropylene compounders serving Chinese automotive assembly. Raw material sourcing draws from Nordic softwood pulp forests, Saudi propylene derivative complexes, and Japanese aramid fiber production. Single-source vulnerability concentrates in Middle Eastern resin supply, with limited alternative propylene capacity outside the region. Distribution runs through Stuttgart-Eching precision manufacturing clusters for European OEM qualification, while Guangdong and Zhejiang provinces anchor export-oriented thermoplastic diaphragm production.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against full-range driver array consolidation in premium automotive audio, where multi-material diaphragm assemblies threaten discrete cone demand.
For Market Incumbents: Consolidate backward into captive pulp treatment capacity to defend margin structures against Nordic fiber spot volatility. Lock in long-term softwood supply contracts before competitor offtake tightens. Prioritize REACH-compliant adhesive certification to maintain European automotive interior air quality qualification. For New Entrants and Emerging Players: Differentiate on biomass-derived thermoplastic formulations targeting automotive OEM sustainability scorecards. India's BIS certification pathway offers penetrable regulatory entry with limited incumbent accredited testing presence. Pursue direct-to-OEM digital sampling platforms to bypass distributor markup layers in boutique monitor channels. For Investors and Strategic Acquirers: Capital is best deployed toward integrated pulp treatment specialists with Stuttgart-Eching corridor positioning and established REACH documentation systems. Long-term viability hinges on fiber rheology expertise scarcity deepening competitive moats. Watch for polypropylene feedstock cost inflections signaling thermoplastic tier margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Treatment | Captive fiber processing insulates Dr. Kurt Muller GmbH from Nordic spot volatility. |
| Biomass-Derived Thermoplastic Development | Polyhydroxyalkanoate compounds unlock automotive OEM circular economy compliance. |
| Accredited Testing Partnership Expansion | BIS certification capacity in Mumbai and Bengaluru secures Indian market access. |
| Water-Based Adhesive Platform Migration | REACH-compliant binders preserve European automotive interior air quality eligibility. |
| Direct-to-OEM Digital Sampling Launch | Parametric specification platforms bypass distributor layers for boutique manufacturers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from listed audio component suppliers, ECHA REACH substance registrations, and automotive OEM sustainability disclosures. Primary interviews engaged cone formulation chemists, procurement leads at professional audio OEMs, pulp treatment plant managers, and automotive Tier 1 supplier quality engineers. Bottom-up volume modeling triangulated against top-down market sizing from trade association aggregates.
Segmentation dimensions modeled include material substrate type, end-use channel, diaphragm diameter, and application environment across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating EV penetration trajectories and professional audio infrastructure investment cycles. Forecast inputs weighted pulp density specification compression for automotive electrification and Kevlar-composite specification escalation in studio monitor procurement.
The analysis sits within stated boundaries; outcomes outside sustained REACH enforcement, stable Nordic pulp supply, and continued EV cabin acoustic array expansion would require recalibration. Forecasts reflect documented assumptions on fiber rheology expertise scarcity and polypropylene feedstock concentration. Practitioners should keep alternative scenarios live as automotive OEM sustainability mandate stringency and Chinese GB standards enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
China Crystal Oscillator Market
Electronic Components
Motherboard Battery Market
Electronic Components
Frequency Control and Timing Devices Market
Electronic Components
Asia-Pacific USB Retimer Market
Electronic Components
Global Circuit Protection Market
Electronic Components
Single Layer Capacitors Market
Electronic Components
Serial Device Servers Market
Electronic Components
High-Voltage Capacitor Market
Electronic Components
Timing Relay Market
Electronic Components
Battery Shunt Resistor Market
Electronic Components
North America Safety Relay and Timers Market
Electronic Components
Digital Potentiometer Market
Electronic Components
United States Radiation-Hardened Electronics Market
Electronic Components
Global Flexible Electronics and Circuit Market
Electronic Components
Semiconductor Micro Components Market
Electronic Components
Stretchable and Conformal Electronics Market