
 High Strength Steel (HSS) Market | 2026-2036
High Strength Steel (HSS) Market Size, Share, and Industry Trends Forecast 2026-2036
High Strength Steel (HSS) Market Foresight
ISO 15156 sour-service qualification is unwinding the competitive landscape for hydrogen-compatible HSS grades. ArcelorMittal leverages its integrated DRI-EAF route to sustain cost leadership in ultra-high-strength flat products. POSCO anchors Asia-Pacific supply through its proprietary PosMAC coating technology for corrosion-resistant automotive sheets. JFE Steel Corporation differentiates via specialized martensitic grades for hot-stamped safety components.
High strength steel encompasses alloys with yield strengths exceeding 355 MPa, produced through controlled thermomechanical processing or quenching and self-tempering to achieve multiphase microstructures including ferrite-bainite and retained austenite. These grades enable mass reduction of 15-25% versus conventional mild steel while maintaining crash energy absorption capacity in structural applications. Structural steel dominates volume consumption in commercial building frames and infrastructure girders where design codes now mandate higher strength-to-weight ratios. Automotive applications command premium pricing due to OEM qualification cycles and stringent property certification for A-pillar and rocker panel stampings. Tool steel remains a specialized margin pool serving die and mold fabricators requiring through-hardening consistency.
FCC emission standards, EPA fuel economy mandates, and EU Green Deal carbon border adjustments collectively accelerate lightweight material substitution in vehicle platforms. OSHA workplace exposure limits for hexavalent chromium during welding push fabricators toward pre-coated HSS grades that reduce post-weld surface treatment. Stakeholders must monitor evolving hydrogen embrittlement test protocols as hydrogen infrastructure deployment expands demand for HSS in pressure-boundary applications.
Market Dynamics
Automotive OEMs are compressing vehicle platform development cycles while EU Green Deal embodied carbon thresholds force simultaneous lightweighting and supply chain decarbonization, creating dual pressure on HSS specification and sourcing.
Growth Catalysts
- EU Green Deal carbon border adjustments:German and French automotive suppliers now specify HSS grades with verified embodied carbon below 1.5 tCO2e per ton, accelerating mill certification upgrades across the Stuttgart supplier corridor.
- NHTSA fuel economy mandates:Detroit Three OEMs expanded HSS content in body-in-white structures to 35-40% by mass, driving demand for third-generation advanced high-strength steel grades in A-pillar and rocker panel stampings.
- Quenching and partitioning process maturation:This thermomechanical route now delivers 1180 MPa tensile strength with 15% elongation, enabling single-piece hot-stamped door rings that replace multi-part welded assemblies.
Market Restraints
- Scrap price volatility:EAF-based HSS producers face margin compression when shredded auto scrap exceeds $420 per metric ton, particularly affecting specialty flat-rolled products with tight chemistry windows.
- Integrated mill concentration in Korea and Japan:POSCO and JFE Steel control 60% of Asia-Pacific ultra-high-strength coated sheet capacity, creating supply vulnerability for ASEAN automotive stampers without long-term offtake agreements.
- Hydrogen embrittlement susceptibility:Martensitic grades above 1200 MPa tensile strength require ISO 11114-4 compatible testing protocols that most fabricators lack, limiting deployment in hydrogen pressure-boundary applications.
Strategic Opportunities
- India PLI scheme for specialty steel:The $6.2 billion production-linked incentive creates first-mover advantage for HSS grades above 980 MPa in commercial vehicle chassis and construction equipment applications.
- Aluminum-steel hybrid joining:Friction stir welding of HSS to 6xxx series aluminum enables multi-material body structures that satisfy crash requirements while achieving 12-18% mass reduction versus all-steel designs.
- Pre-coated weldable grades:Zinc-magnesium-aluminum coatings eliminate hexavalent chromium post-treatment, opening EPA OSHA-compliant fabrication channels for smaller tier-two automotive stampers.
Industry Challenges
- ISO 15156 sour-service qualification timelines:Hydrogen-compatible HSS grades require 18-24 month test protocols for oilfield tubular applications, compressing first-mover advantage windows.
- Hot-stamping die capex intensity:Al-Si coated blank processing requires $4-6 million press-hardening line investments that tier-three automotive suppliers cannot finance without OEM co-investment.
- Multiphase microstructure consistency:Retained austenite volume fraction must hold within 8-12% across 200-ton coils to prevent springback variation in complex draw stampings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Strength Steel (HSS) Market |
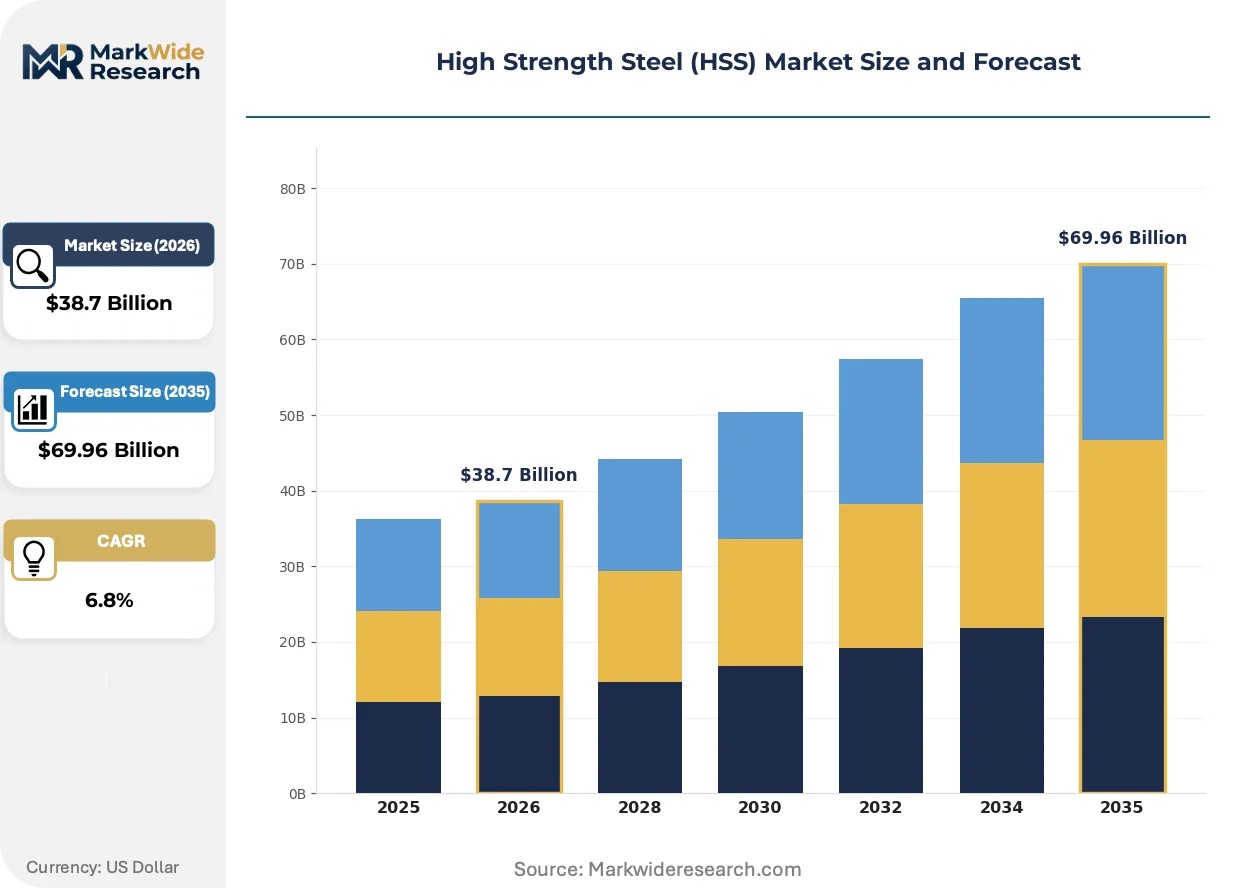
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Structural Steel, Tool Steel, Alloy Steel, Carbon Steel Application: Automotive, Construction, Aviation, Shipbuilding End User: Manufacturers, OEMs, Contractors, Fabricators Form: Sheets, Plates, Bars, Rods |
| Companies Covered | ThyssenKrupp AG, JFE Steel Corporation, Nippon Steel Corporation, SSAB AB, Baosteel Group Corporation, ArcelorMittal, Tata Steel Limited, Voestalpine AG, POSCO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Strength Steel (HSS) Market Shifts & Advancements
Third-generation advanced high-strength steels with improved ductility are overtaking first-generation dual-phase grades in automotive structural applications, while regulatory carbon accounting and hydrogen infrastructure deployment reshape specification priorities.
Quenching and partitioning (Q&P) steel is supplanting conventional martensitic grades in B-pillar and roof rail applications. BMW and Mercedes-Benz specifications now mandate Q&P 980/1180 for intrusion-resistant structures. This metallurgical shift is compressing demand for lower-elongation martensitic products while expanding the addressable market for hot-stamped complex-phase alternatives.
The EU Green Deal's embodied carbon thresholds are forcing mill-level supply chain reconfiguration. ArcelorMittal's integrated DRI-EAF route at Gijón and Dunkirk now commands premium positioning for automotive OEMs with Science Based Targets initiative commitments. German automotive suppliers in Lower Saxony are rejecting HSS shipments lacking ISO 14064-verified product carbon footprints.
Buyer consolidation among tier-one automotive stampers is concentrating procurement leverage. Magna, Gestamp, and Benteler now specify HSS grades with guaranteed hydrogen embrittlement resistance for fuel cell vehicle underbody protection. This certification-driven preference shift favors mills with in-house slow strain rate testing capability, disadvantaging commodity traders and smaller electric furnace operators.
High Strength Steel (HSS) Market Segmentation
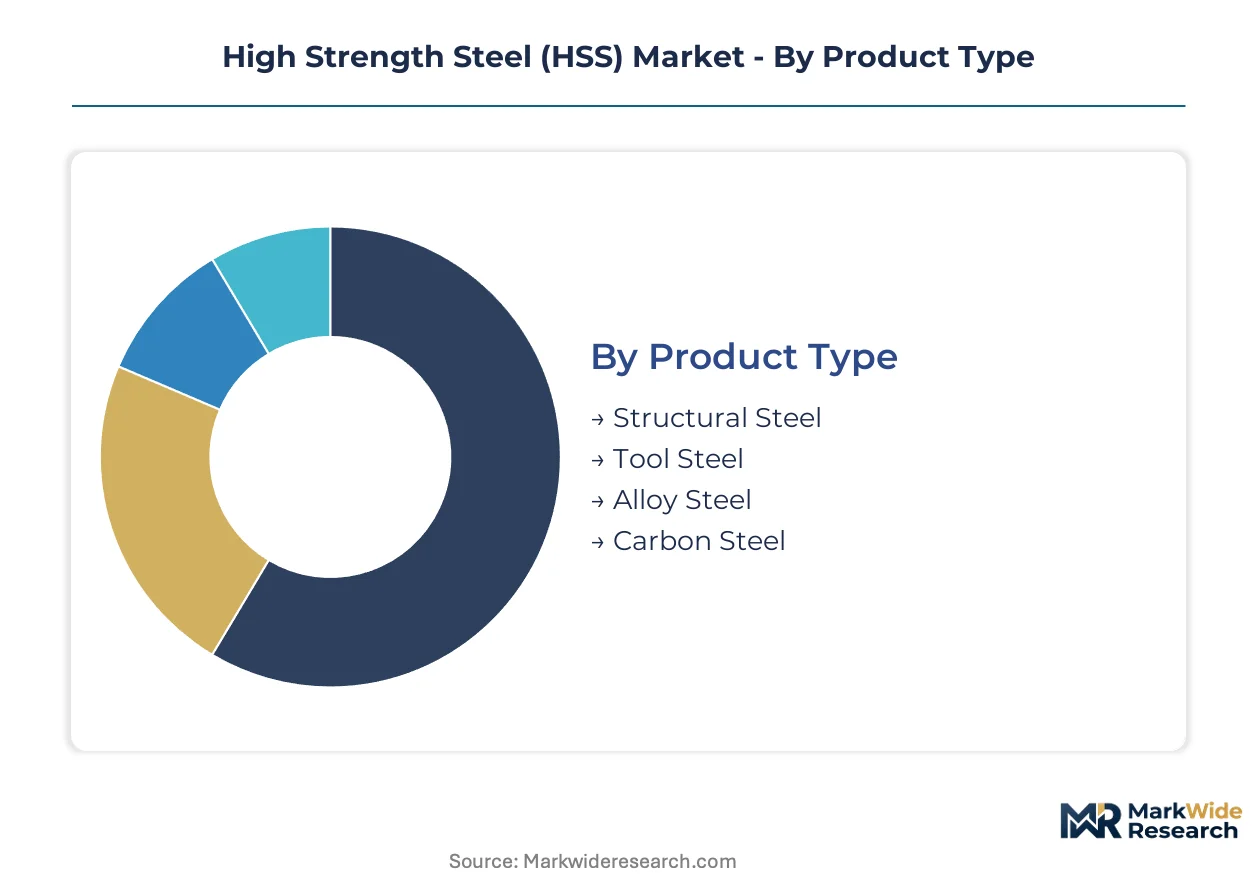
Channel configuration varies sharply across HSS segments. Mill-direct procurement dominates high-volume automotive grades, while distributor networks handle fragmented construction demand. Specification complexity and certification requirements determine whether segments flow through integrated mills, service centers, or specialized traders.
Product Type:
Structural steel moves primarily through mill-direct contracts with tier-one distributors, while tool steel channels through specialized service centers with heat-treatment capabilities. Alloy and carbon grades split between integrated mill relationships and spot-market procurement.
- Structural Steel:Yield strengths from 355 MPa to 690 MPa serve commercial building frames and infrastructure girders. Demand concentrates in Germany's automotive supplier corridor where design codes now mandate higher strength-to-weight ratios for bridge and highway applications. The EU Green Deal's embodied carbon thresholds are forcing mill-level reconfiguration of supply chains serving Stuttgart and Wolfsburg industrial clusters.
- Tool Steel:Through-hardening grades with guaranteed hardness consistency serve die and mold fabricators requiring dimensional stability. Procurement flows through specialized distributors with in-house metallurgical laboratories, particularly in Japan's manufacturing belt around Nagoya and Osaka. Premium positioning reflects small-batch customization and technical service intensity.
- Alloy Steel:Controlled chemistry grades with enhanced hardenability serve crankshaft and gear applications. Channel mix splits between OEM direct contracts and regional service centers.
- Carbon Steel:Standardized grades with moderate strength elevation serve general fabrication and non-critical structural applications. Volume flows through commodity distributors with minimal technical service.
By volume, Structural Steel leads. By growth pace, Tool Steel is climbing the fastest.
Application:
Cost tier stratification separates premium automotive specifications from commoditized construction procurement. Aviation and shipbuilding occupy intermediate positions with certification-driven pricing.
- Automotive:Third-generation advanced high-strength steels with multiphase microstructures enable 15-25% mass reduction in body-in-white structures. BMW and Mercedes-Benz specifications now mandate quenching and partitioning grades for intrusion-resistant B-pillar and roof rail applications. NHTSA fuel economy mandates are compressing platform development cycles while forcing simultaneous lightweighting investment.
- Construction:Standardized structural grades serve commercial building frames where design code evolution drives specification upgrades. Procurement concentrates in project-based tenders with price-sensitive contractor behavior.
- Aviation:Specialized high-strength low-alloy grades meet FAA fatigue and damage tolerance requirements for landing gear and structural fittings. Batch sizes remain small with extreme certification overhead.
- Shipbuilding:TMCP-produced grades with through-thickness toughness serve deck and hull applications. Demand tracks commercial vessel order cycles with Korean and Chinese yard concentration.
By volume, Construction leads. By margin expansion, Automotive is gaining share fastest.
End User:
Customer type determines contract structure and technical service intensity. OEMs demand guaranteed supply with embedded R&D collaboration, while fabricators prioritize availability and processing flexibility.
- Manufacturers:Tier-one automotive stampers like Magna and Gestamp specify hydrogen-compatible grades with guaranteed embrittlement resistance for fuel cell vehicle underbody protection. Long-term offtake agreements with mills include co-development clauses for next-generation grades.
- OEMs:Detroit Three automakers expanded HSS content to 35-40% by mass, driving consolidated procurement leverage and qualification-driven supplier selection. Direct mill relationships dominate with minimal distributor intermediation.
- Contractors:Construction project developers source through regional service centers with just-in-time delivery requirements. Price sensitivity limits specification upgrading.
- Fabricators:Tier-two and tier-three stampers lack hot-stamping die capex for Al-Si coated blank processing, creating dependency on OEM co-investment or service center toll processing.
By volume, Manufacturers lead. By contract value concentration, OEMs are expanding most quickly.
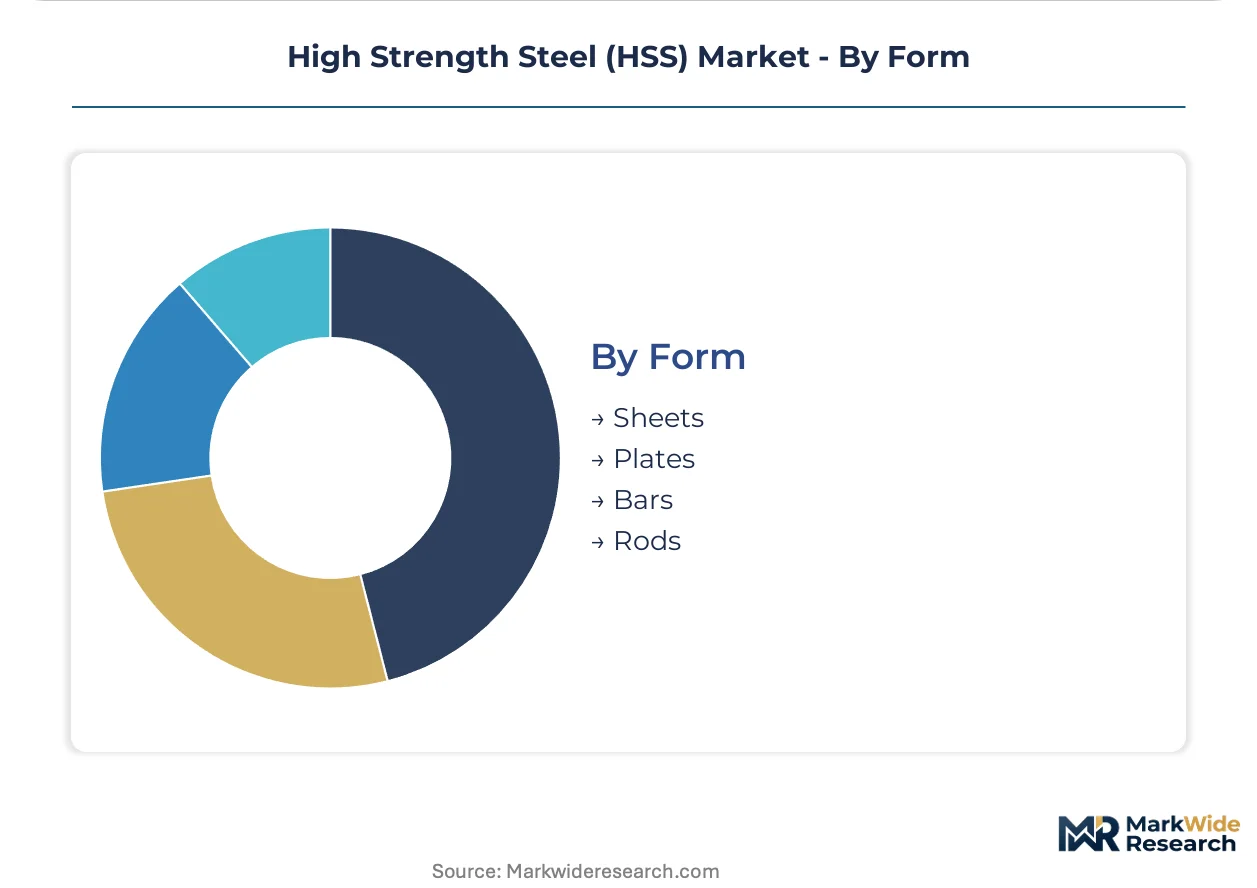
Form:
Processing economics and transportation cost structure create distinct channel configurations. Flat products require specialized coil handling infrastructure, while long products flow through more fragmented distribution.
- Sheets:Coiled flat products with zinc-magnesium-aluminum coatings serve automotive skin panels and structural stampings. ArcelorMittal's DRI-EAF route commands premium positioning for OEMs with Science Based Targets commitments.
- Plates:Heavy-gauge TMCP products serve shipbuilding and offshore structures with through-thickness toughness requirements. POSCO and JFE Steel control Asia-Pacific capacity.
- Bars:Long products serve crankshaft and axle applications with controlled hardenability. Regional mini-mill supply dominates with scrap-price volatility exposure.
- Rods:Wire rod forms serve cold-heading and drawing applications for fastener manufacture. Commodity pricing with minimal differentiation.
By volume, Sheets lead. By specification upgrading intensity, Plates are on the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's carbon border adjustments are accelerating mill-level certification upgrades across automotive supplier corridors, while India's PLI scheme for specialty steel redirects investment flows toward high-strength grades above 980 MPa.
Germany
NHTSA-aligned fuel economy pressures transmitted through Detroit Three supply chains are amplifying demand for third-generation advanced high-strength steels in Stuttgart's automotive supplier corridor. The EU Green Deal mandates embodied carbon thresholds below 1.5 tCO2e per ton, forcing mill certification upgrades at Wolfsburg-area stamping facilities. Lower Saxony fabricators now reject HSS shipments lacking ISO 14064-verified product carbon footprints.
United States
EPA fuel economy mandates and OSHA hexavalent chromium exposure limits are compressing platform development cycles while pushing fabricators toward pre-coated weldable grades. NHTSA standards expanded HSS content in body-in-white structures to 35-40% by mass across Michigan and Ohio automotive clusters. Detroit Three OEMs now consolidate procurement leverage for hydrogen-compatible grades in fuel cell vehicle underbody applications.
China
MIIT industrial upgrading directives and dual carbon goals are reshaping specification priorities for quenching and partitioning steel in Yangtze River Delta automotive manufacturing. GB standards evolution now parallels EU Green Deal carbon accounting frameworks for export-oriented suppliers. Shanghai and Jiangsu province mills are upgrading DRI-EAF routes to capture premium positioning in Science Based Targets supply chains.
Japan
METI technology roadmaps and JIS standards evolution are accelerating martensitic grade specialization for hot-stamped safety components in Nagoya-Osaka manufacturing belts. PMDA-aligned quality protocols extend into automotive materials certification, favoring mills with in-house slow strain rate testing capability. Chubu region fabricators dominate complex-phase alternatives for B-pillar and roof rail stampings.
India
The PLI scheme's $6.2 billion production-linked incentive is creating first-mover advantage for HSS grades above 980 MPa in Maharashtra and Gujarat commercial vehicle chassis applications. BIS standards harmonization with ISO 15156 sour-service protocols is extending qualification timelines for oilfield tubular grades. Tamil Nadu automotive clusters are attracting capacity expansion for construction equipment HSS specifications.
High Strength Steel (HSS) Market Competitive Landscape
Listed leaders compete with private specialists across integrated versus electric furnace production economics, creating tiered supply structures. Archetypal positioning splits between DRI-EAF route operators commanding carbon-accounting premiums, blast furnace incumbents with scale advantages in heavy plate, and regional mini-mills serving fragmented construction demand. Consolidation pressure concentrates in coated sheet capacity where automotive qualification cycles erect entry barriers. Dominant competitive moves include backward integration into direct reduced iron feedstock and captive hydrogen testing laboratory deployment.
Within the integrated mill tier, ArcelorMittal exemplifies the DRI-EAF route archetype through its Gijón and Dunkirk operations. POSCO and JFE Steel occupy positions anchoring Asia-Pacific ultra-high-strength coated sheet supply. ThyssenKrupp AG represents the European specialist archetype with concentration in automotive-grade flat products. Tata Steel Limited sits within the emerging market expansion vector targeting PLI-scheme incentives in Indian commercial vehicle applications.
| Leading Market Players |
|---|
| ThyssenKrupp AG |
| JFE Steel Corporation |
| Nippon Steel Corporation |
| SSAB AB |
| Baosteel Group Corporation |
| ArcelorMittal |
| Tata Steel Limited |
| Voestalpine AG |
| POSCO |
| Others |
Supply & Pricing Matrix
Eighteen-month automotive qualification cycles compress pricing power for unqualified mills while concentrating procurement leverage among tier-one stampers with long-term offtake agreements. This lead-time rigidity reinforces supply chain hierarchy, with EU Green Deal carbon thresholds adding certification premiums that separate DRI-EAF route operators from commodity blast furnace competitors.
Pricing Analysis
Certification level creates the primary spread between automotive-grade HSS and construction commodity tiers. Contract-based long-term offtake agreements dominate high-volume automotive procurement, while spot-market transactions serve fragmented construction demand. ISO 15156 sour-service and ISO 14064 carbon footprint credentials command 15-25% premiums over uncertified grades. Cost compression in standard structural grades is intensifying because regional mini-mill capacity expansion in India and Southeast Asia feeds oversupply. Tier-two automotive stampers exhibit highest price sensitivity due to hot-stamping die capex constraints, while OEMs with Science Based Targets commitments show lowest sensitivity to carbon-accounting premiums.
Supply Chain Analysis
China, South Korea, and Japan anchor global ultra-high-strength coated sheet capacity, with POSCO and JFE Steel controlling 60% of Asia-Pacific supply. Production draws from iron ore pellets, direct reduced iron feedstock, and high-grade metallurgical coal, with scrap-price volatility exposing EAF-based specialty producers to margin compression. Single-source vulnerability concentrates in Al-Si coated blank supply for hot-stamping applications, where automotive qualification cycles erect multi-year entry barriers. Distribution runs through mill-direct channels for automotive OEMs, while regional service centers handle construction-grade structural products with just-in-time delivery requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The HSS market is entering a cyclical recovery phase as automotive platform refresh cycles and EU Green Deal carbon border adjustments synchronize demand resurgence with supply chain reconfiguration.
For Market Incumbents: Compound defensive positioning through backward integration into direct reduced iron feedstock and captive hydrogen testing laboratory deployment. ArcelorMittal's integrated DRI-EAF route exemplifies cost leadership defense against emerging Indian PLI-scheme competitors. Certification investment in ISO 15156 and ISO 14064 protocols protects premium positioning as German automotive suppliers reject uncertified shipments. For New Entrants and Emerging Players: Lead with construction equipment and commercial vehicle chassis applications in Maharashtra and Gujarat, where India's PLI scheme creates first-mover advantage for grades above 980 MPa without automotive qualification cycle barriers. Pre-coated weldable grades with zinc-magnesium-aluminum coatings offer the most penetrable wedge, eliminating hexavalent chromium post-treatment for EPA OSHA-compliant tier-two stampers. For Investors and Strategic Acquirers: Long-term, this sits as a carbon-accounting infrastructure play because EU Green Deal thresholds and Science Based Targets commitments are irreversibly embedding certification requirements into automotive procurement. Acquisition targets should exhibit in-house slow strain rate testing capability and existing DRI-EAF route assets. The signal to watch is hydrogen infrastructure deployment pace, as fuel cell vehicle underbody protection demand will accelerate hydrogen-compatible grade premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into DRI Feedstock | ArcelorMittal's Gijón and Dunkirk operations command carbon-accounting premiums from BMW and Mercedes-Benz. |
| Hydrogen Testing Laboratory Deployment | In-house ISO 11114-4 capability qualifies mills for fuel cell vehicle underbody protection contracts. |
| PLI Scheme Capacity Expansion | Maharashtra and Gujarat mills capture first-mover advantage in commercial vehicle chassis grades above 980 MPa. |
| Pre-Coated Weldable Grade Development | Zinc-magnesium-aluminum coatings open EPA OSHA-compliant channels for tier-two automotive stampers. |
| Automotive Qualification Cycle Acceleration | Compressed 18-month Q&P steel approval timelines match Detroit Three platform development cycles. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with mill procurement directors, automotive platform engineers, and tier-one stamper supply chain managers; and secondary validation through customs/trade data, SEC 10-K filings, and IHS Markit vehicle production databases. Bottom-up and top-down triangulation cross-checked volume assumptions against OEM content-per-vehicle disclosures and regional steel consumption patterns.
Across the analysis window, the forecasting framework modeled demand through five segmentation dimensions: product type (structural, tool, alloy, carbon steel), application (automotive, construction, aviation, shipbuilding), end user (manufacturers, OEMs, contractors, fabricators), form (sheets, plates, bars, rods), and regional production cluster. CAGRs were derived from regression analysis of historical automotive platform cycles and EU regulatory implementation timelines, with specific inputs including NHTSA fuel economy mandate compliance schedules and MIIT industrial upgrading directive trajectories.
The analysis sits within stated boundaries; outcomes outside sustained automotive lightweighting investment and EU carbon border adjustment enforcement would require recalibration. Forecasts reflect assumptions about hydrogen infrastructure deployment pace, scrap price volatility bands, and automotive qualification cycle compression. Recalibration cycles align with material shifts in EU Green Deal implementation schedules and PLI scheme disbursement milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Polyphenylene Ether (PPE) Alloy Market
Advanced Alloys
Sintered Steel Market
Advanced Alloys
Forgings Market
Advanced Alloys
Tungsten Titanium Carbide Market
Advanced Alloys
Global Noble Ferroalloys Market
Advanced Alloys
India Aluminum Extrusion Market
Advanced Alloys
Powder Metallurgy Components Market
Advanced Alloys
Brazing Alloys Market
Advanced Alloys
Iron Gallium Alloy (Galfenol) Market
Advanced Alloys
Ballistic Material Market
Advanced Alloys
Thulium Silicide Market
Advanced Alloys
Plastic-Metal Hybrids Market
Advanced Alloys
India Shape Memory Alloy Market
Advanced Alloys
Magnesium Alloys Market
Advanced Alloys
Asia-Pacific Metal Casting Market
Advanced Alloys
Quenched and Tempered Steel Market