
 Global Vacuum Grease Market | 2026-2036
Global Vacuum Grease Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vacuum Grease Market Foresight
Capital-intensity divergence between integrated formulators and specialty blenders is bifurcating competitive dynamics in vacuum grease supply. DuPont leverages captive fluoropolymer feedstock to control raw material costs across perfluoropolyether grades. Nye Lubricants anchors its position through precision blending capabilities tailored to semiconductor OEM specifications. Kurt J Lesker competes by extending distribution reach into research laboratories and smaller vacuum system builders.
Vacuum grease denotes low-vapor-pressure lubricating compounds formulated from silicone, fluorinated, or hydrocarbon base stocks with vapor pressures below 10⁻⁷ Torr at 25°C, designed to maintain seal integrity and reduce outgassing in evacuated systems. The material serves critical functions in semiconductor etch chambers, aerospace propulsion test stands, and cryogenic research dewars where atmospheric contamination risks process failure. Fluorinated and perfluoropolyether product types command premium positioning due to chemical inertness demands in aggressive plasma environments. Semiconductor fabrication and aerospace end user industries concentrate margin pools where qualification cycles create sticky supplier relationships. Hydrocarbon grades occupy cost-sensitive applications in general laboratory and industrial vacuum systems with shorter equipment lifecycles.
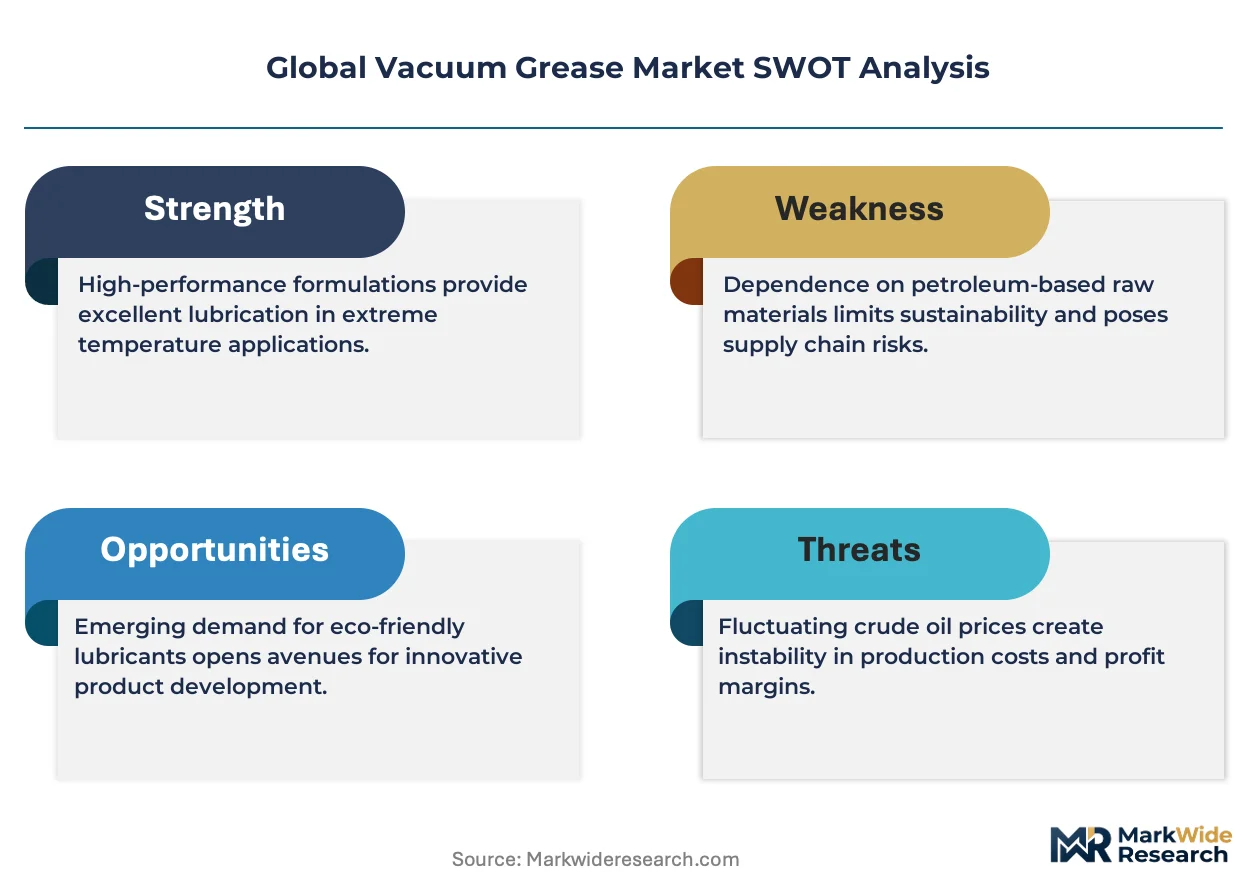
EPA oversight of per- and polyfluoroalkyl substances in the United States, REACH substance restrictions administered by ECHA in Europe, and Japan's METI chemical management framework are elevating compliance burdens for fluorinated grease formulators. These regulatory pressures are reshaping product development priorities toward shorter-chain fluorinated alternatives and silicone-based substitutes with equivalent vacuum performance. Stakeholders must monitor evolving substance restrictions while assessing reformulation investments against customer qualification timelines.
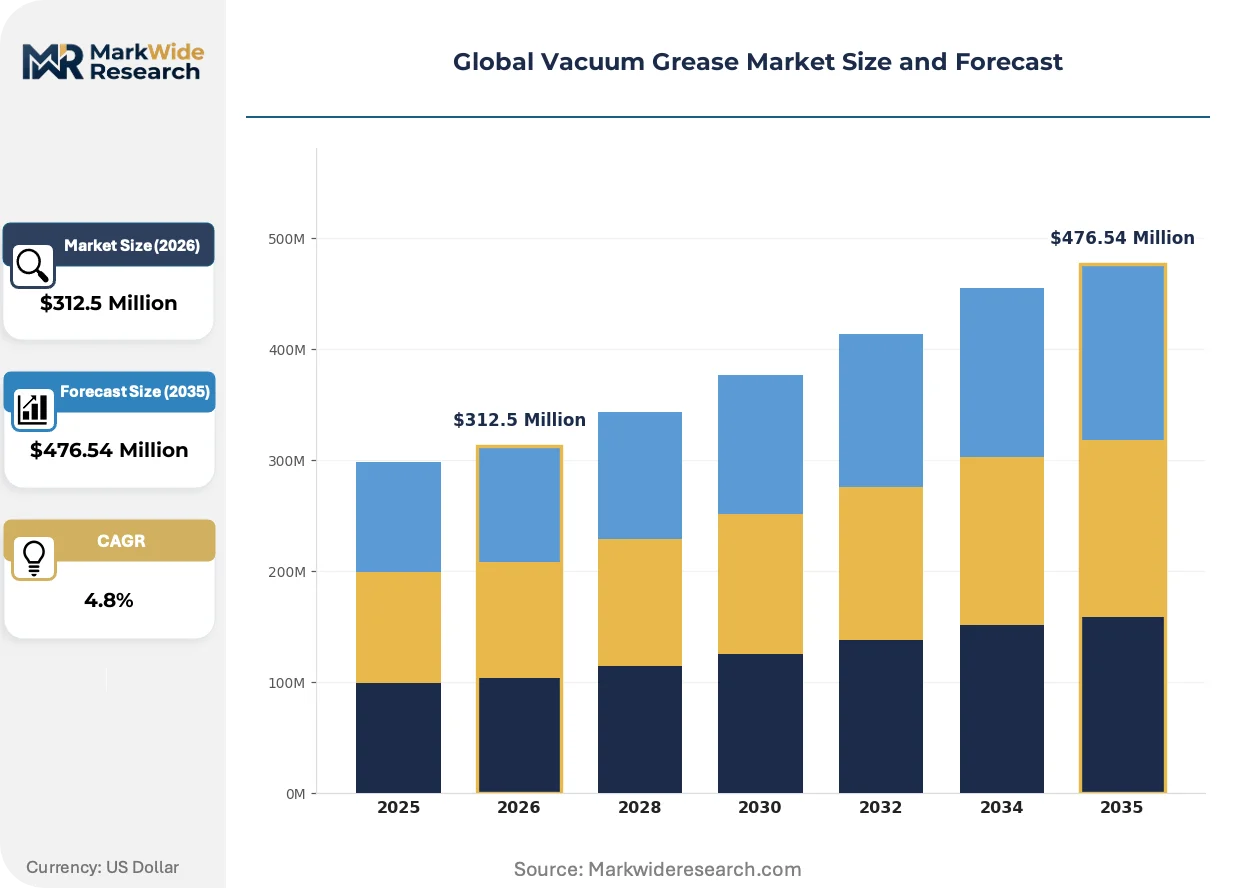
Market Dynamics
Semiconductor fabrication fabs are scaling vacuum grease consumption for wafer processing equipment, while REACH and RoHS compliance in Europe tightens purity requirements for fluorinated formulations. This dual pressure—demand pull from precision manufacturing and regulatory push toward reformulation—is restructuring competitive positioning among formulators.
Growth Catalysts
- Semiconductor capital expansion:Wafer processing equipment manufacturers in Taiwan, South Korea, and the United States are qualifying vacuum greases for next-generation etch chambers, creating sticky supplier relationships through extended certification cycles.
- REACH substance restrictions:ECHA's evolving framework on per- and polyfluoroalkyl substances is accelerating development of shorter-chain fluorinated alternatives that maintain vacuum performance while preempting regulatory bans.
- Cryogenic research infrastructure:National laboratories in Germany, Japan, and Switzerland are upgrading dewar sealing systems, driving specification-grade procurement for ultra-low-temperature vacuum greases.
Market Restraints
- Fluoropolymer feedstock concentration:Captive production of perfluoropolyether base stocks concentrates among integrated chemical producers, limiting blending flexibility for specialty formulators.
- EPA PFAS oversight:Emerging restrictions on per- and polyfluoroalkyl substances in the United States are forcing premature reformulation investments ahead of customer requalification timelines.
- Silicone substitution threat:Advanced silicone formulations with vapor pressures approaching 10⁻⁸ Torr are displacing fluorinated grades in non-plasma laboratory applications.
Strategic Opportunities
- India precision manufacturing:PLI scheme incentives for semiconductor and aerospace component production are creating first-mover advantages for grease formulators establishing local blending capabilities.
- Aerospace propulsion testing:Expansion of reusable launch vehicle programs in the United States and France is extending qualification demand for high-temperature vacuum sealants.
- Direct OEM contracting:Equipment manufacturers are unbundling lubricant procurement from system integrators, enabling margin capture through specification-in-design partnerships.
Industry Challenges
- Requalification timeline compression:Semiconductor fabs are compressing supplier validation cycles from 18 months to 9 months, straining formulator technical service capacity.
- Cross-contamination control:Multi-product blending facilities face ISO 14644 cleanroom upgrade requirements to prevent particulate migration between fluorinated and hydrocarbon grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vacuum Grease Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $476.54 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone-Based, Fluorinated, Hydrocarbon, Perfluoropolyether, Polyphenyl Ether Application: Vacuum Sealing, Lubrication, Heat Shielding, Electrical Insulation, Cryogenic Operations End User Industry: Aerospace & Defense, Semiconductor Fabrication, Research Laboratories, Chemical Processing, Optics Manufacturing Packaging Type: Tubes, Jars, Cartridges, Bulk Drums, Syringes |
| Companies Covered | DuPont, Chemours Company, Nye Lubricants, Kurt J Lesker, M&I Materials, Dow Corning Corporation, Klüber Lubrication, Santolubes LLC, Inland Vacuum Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vacuum Grease Market Shifts & Advancements
Reformulation chemistry is fragmenting the vacuum grease landscape as regulatory pressure on long-chain fluorinated compounds accelerates alternative base stock development. Three converging developments are reshaping product architecture and procurement patterns.
Perfluoropolyether chemistry is fragmenting traditional product hierarchies as shorter-chain formulations achieve vapor pressure parity with legacy grades. Aerospace propulsion test stand operators in France and the United States are piloting these alternatives to preempt supply disruption from EPA substance restrictions. The shift is compressing margins on established high-viscosity grades while opening specification slots for reformulated products.
ECHA's F-Gas Regulation amendments are tightening containment requirements for fluorinated greenhouse gases used in vacuum system manufacturing. European semiconductor equipment OEMs are redesigning seal architectures to reduce grease volume per joint, directly impacting per-unit consumption rates. German and Dutch fabs are demanding substance-by-substance disclosure for all fluorinated content, extending procurement documentation cycles.
Consolidated buying groups at major semiconductor foundries are unbundling lubricant procurement from capital equipment contracts. Direct negotiations with formulators are replacing distributor-mediated purchasing in Taiwan and South Korea, compressing channel margins while rewarding technical specification capabilities. The shift privileges blenders with in-house analytical laboratories capable of lot-specific certification.
Global Vacuum Grease Market Segmentation
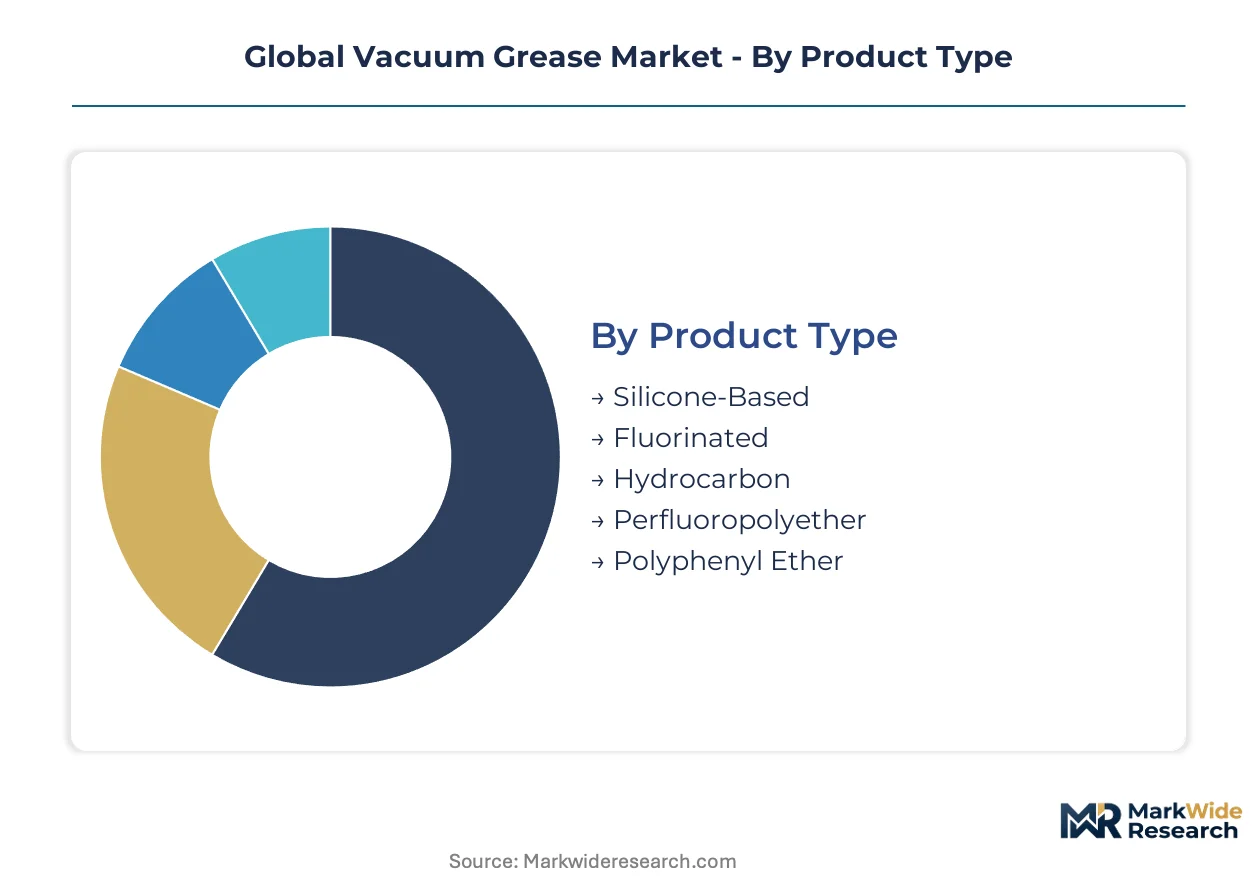
Vacuum grease segmentation reflects divergent technical requirements across precision manufacturing ecosystems. Product chemistry, application environment, and end-use certification standards create distinct margin tiers that reshape procurement patterns.
Product Type:
Substitution pressure from silicone alternatives is fragmenting traditional fluorinated hierarchies, with reformulation investments concentrating in segments facing imminent regulatory restriction.
- Perfluoropolyether:Molecularly engineered fluorocarbon chains deliver vapor pressures below 10⁻⁹ Torr with exceptional chemical inertness. Semiconductor etch chamber OEMs in Taiwan and Germany specify these grades for aggressive plasma environments where outgassing tolerance approaches zero.
- Fluorinated:Partially fluorinated base stocks balance performance against reformulation agility as ECHA substance restrictions tighten. French aerospace test facilities are qualifying shorter-chain variants to preempt supply disruption from evolving PFAS frameworks.
- Silicone-Based:Dimethylsiloxane formulations with vapor pressures reaching 10⁻⁸ Torr are displacing fluorinated grades in laboratory vacuum systems. METI chemical management in Japan is accelerating silicone adoption through simplified substance registration pathways.
- Hydrocarbon:Mineral oil and synthetic hydrocarbon blends serve cost-sensitive industrial applications with moderate vacuum requirements. General manufacturing facilities in India and Brazil specify these grades for equipment with shorter operational lifecycles.
- Polyphenyl Ether:Aromatic ether chemistry provides thermal stability beyond 250°C for specialized aerospace sealing. United States propulsion test stands at NASA facilities and SpaceX development sites represent concentrated demand nodes.
Silicone-Based retains volume leadership; Perfluoropolyether holds the steepest expansion curve.
Application:
Cost tier stratification separates specification-grade applications commanding lot-specific certification from commodity procurement in general industrial settings.
- Vacuum Sealing:Static and dynamic seal lubrication dominates consumption volume across all end-use sectors. Semiconductor fabrication fabs in South Korea and the Netherlands are redesigning seal architectures to reduce per-joint grease volume while maintaining integrity specifications.
- Lubrication:Rotary feedthrough and bearing lubrication in wafer processing equipment requires ultra-low particulate formulations. Taiwan-based equipment OEMs are consolidating supplier lists to three approved formulators per equipment platform.
- Cryogenic Operations:Ultra-low-temperature stability distinguishes specification grades for research dewar sealing. Swiss and German national laboratories are upgrading infrastructure with greases rated to 4 Kelvin operational limits.
- Heat Shielding:Thermal interface compounds for aerospace propulsion components require simultaneous vacuum compatibility and high-temperature resistance. Reusable launch vehicle programs in France and the United States are extending qualification timelines for these dual-performance grades.
- Electrical Insulation:Dielectric grease applications in vacuum-compatible electrical feedthroughs serve niche instrumentation markets. Scientific instrument manufacturers in Japan specify these grades for electron microscopy and mass spectrometry platforms.
Vacuum Sealing captures the largest revenue pool; Cryogenic Operations is climbing the fastest as research infrastructure investment accelerates.
End User Industry:
Customer type concentration creates sticky supplier relationships where qualification cycles exceed twelve months, privileging formulators with dedicated technical service capacity.
- Semiconductor Fabrication:Wafer processing equipment manufacturers represent the most demanding specification environment with substance-by-substance disclosure requirements. Consolidated buying groups at Taiwan Semiconductor Manufacturing and Samsung Foundry are unbundling lubricant procurement from capital equipment contracts.
- Aerospace & Defense:Propulsion test stand and satellite component applications require extended thermal cycling validation. United States reusable launch vehicle operators and French Ariane program suppliers are qualifying reformulated fluorinated alternatives ahead of anticipated EPA restrictions.
- Research Laboratories:National and university laboratory procurement emphasizes specification flexibility over volume scale. German Max Planck Institutes and Swiss Federal Institutes of Technology are driving demand for cryogenic-rated and ultra-high-vacuum formulations.
- Chemical Processing:Industrial vacuum system operators in specialty chemical and pharmaceutical manufacturing prioritize cost containment. Indian and Brazilian process industries are adopting hydrocarbon grades for batch processing equipment with defined maintenance intervals.
- Optics Manufacturing:Lens grinding and coating chamber applications require particulate-controlled formulations for surface quality preservation. Japanese precision optics clusters in Yamanashi and Osaka prefectures concentrate procurement among established silicone formulators.
Semiconductor Fabrication commands margin leadership; Research Laboratories is expanding most quickly as national science infrastructure investment intensifies.
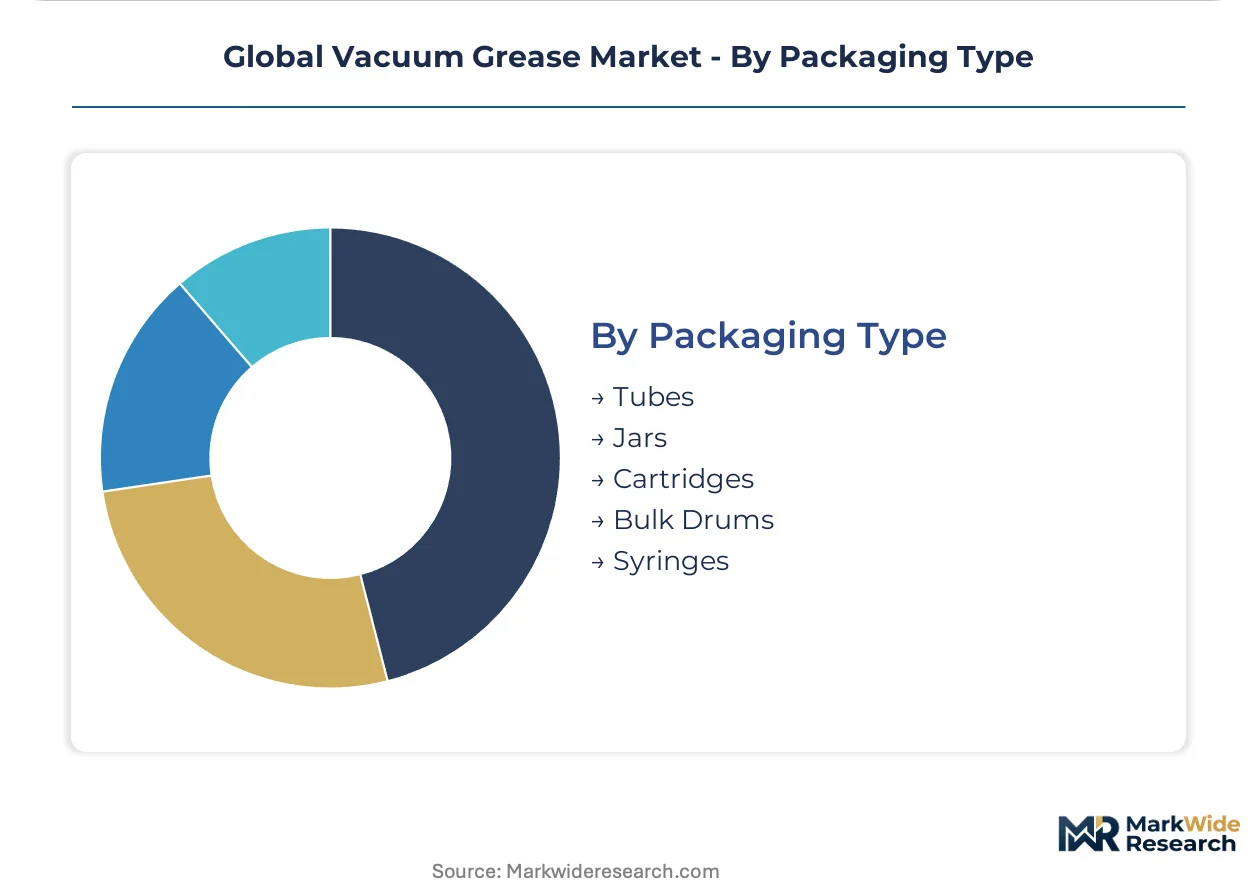
Packaging Type:
Supply concentration in precision dispensing formats is elevating packaging from logistics consideration to technical specification element.
- Syringes:Pre-filled precision dispensing eliminates contamination risk during cleanroom installation. Taiwan and South Korea semiconductor fabs are mandating syringe delivery for all etch chamber maintenance to prevent particulate introduction.
- Tubes:Collapsible aluminum and laminate tubes serve laboratory and field service applications requiring portability. Research institutions across Germany, Japan, and Switzerland standardize on tube formats for multi-site inventory management.
- Jars:Wide-mouth containers facilitate bulk sampling and custom blending operations. Specialty formulators in the United States utilize jar packaging for direct OEM sampling programs during qualification cycles.
- Cartridges:Pneumatic dispensing systems integrate with automated maintenance equipment in high-volume manufacturing. Aerospace propulsion test facilities in France are adopting cartridge systems for standardized seal refurbishment protocols.
- Bulk Drums:Industrial-scale supply serves chemical processing and general manufacturing with predictable consumption patterns. Indian PLI scheme beneficiaries in precision manufacturing are negotiating drum supply contracts for localized blending operations.
Syringes dominate specification-grade procurement; Bulk Drums retain volume leadership in cost-optimized segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: precision manufacturing clusters in East Asia and Western Europe prioritize perfluoropolyether grades for semiconductor fabrication, while North American aerospace operators and Indian industrial processors drive hydrocarbon and silicone volume through cost-optimized procurement frameworks.
United States
Semiconductor fabrication expansion in Arizona and Texas is accelerating qualification demand for ultra-low-outgassing formulations. EPA oversight of per- and polyfluoroalkyl substances is forcing premature reformulation investments among domestic blenders. NASA propulsion test stands in Mississippi and SpaceX development sites in California represent concentrated demand nodes for high-temperature vacuum sealants.
Germany
Wafer processing equipment OEMs in Dresden and Munich specify perfluoropolyether grades with substance-by-substance disclosure requirements. ECHA's REACH substance restrictions and F-Gas Regulation amendments are tightening containment standards for fluorinated content. Max Planck Institutes across Bavaria and Baden-Württemberg are upgrading cryogenic research infrastructure with greases rated to 4 Kelvin operational limits.
Japan
Precision optics clusters in Yamanashi and Osaka prefectures concentrate procurement among established silicone formulators for lens grinding applications. METI's chemical management framework is accelerating silicone adoption through simplified substance registration pathways compared to fluorinated alternatives. Tokyo Electron and domestic equipment OEMs are consolidating supplier lists to three approved formulators per wafer processing platform.
South Korea
Samsung Foundry and SK Hynix are unbundling lubricant procurement from capital equipment contracts, enabling direct negotiations with formulators. Consolidated buying groups are compressing channel margins while rewarding technical specification capabilities with in-house analytical laboratories. Pyeongtaek and Hwaseong semiconductor complexes mandate syringe delivery formats for all etch chamber maintenance to prevent particulate introduction.
India
PLI scheme incentives for semiconductor and aerospace component production are creating first-mover advantages for grease formulators establishing local blending capabilities. DGFT import documentation requirements are extending procurement cycles for specification-grade fluorinated products. Gujarat and Tamil Nadu precision manufacturing clusters are negotiating bulk drum supply contracts for localized hydrocarbon blending operations.
Global Vacuum Grease Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive fluoropolymer production separating cost-control capabilities from formulation-dependent competitors. Three archetypes populate this structure: integrated chemical producers with backward control over base stock supply, precision blenders with dedicated technical service capacity for OEM qualification cycles, and distribution-focused operators extending reach into research laboratories and smaller system builders. Competitive moves concentrate on geographic expansion into Indian PLI scheme zones and direct OEM contracting partnerships that bypass traditional distributor channels.
Among integrated chemical producers, DuPont and Chemours Company exemplify archetypes with upstream control over perfluoropolyether feedstock production. Nye Lubricants occupies a position within the precision blending tier, anchoring competitive dynamics through specification-in-design partnerships with semiconductor OEMs. Kurt J Lesker sits within the distribution-specialist vector, extending market presence into research laboratories and smaller vacuum system builders where qualification cycles remain less demanding.
| Leading Market Players |
|---|
| DuPont |
| Chemours Company |
| Nye Lubricants |
| Kurt J Lesker |
| M&I Materials |
| Dow Corning Corporation |
| Klüber Lubrication |
| Santolubes LLC |
| Inland Vacuum Industries |
| Others |
Supply & Pricing Matrix
Silicone-based alternatives displacing fluorinated grades in laboratory applications simultaneously redraw raw material sourcing maps and compress margin structures across formulation tiers. Japanese METI registration pathways favoring silicone chemistry redirect procurement toward dimethylsiloxane feedstocks, while ECHA substance restrictions on PFAS compounds force premium retention strategies for compliant fluorinated stocks.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between semiconductor foundries and approved formulators, with spot purchasing limited to research laboratory segments. Price differentiation separates specification-grade perfluoropolyether certified for etch chamber duty from standard silicone and economy hydrocarbon grades. Cost compression in fluorinated tiers intensifies as EPA oversight forces premature reformulation investments ahead of customer requalification timelines. Chemical processing operators in India and Brazil exhibit highest price sensitivity, while semiconductor OEMs in Taiwan and South Korea prioritize technical specification over unit cost.
Supply Chain Analysis
Perfluoropolyether base stock production concentrates among integrated chemical producers in the United States, Germany, and Japan, creating single-source vulnerability for specialty blenders lacking captive fluoropolymer supply. Formulation draws from fluorinated feedstocks, silicone precursors, and synthetic hydrocarbon base oils, with purity grades determining end-use eligibility. Tariff exposure on fluorinated imports into India extends procurement cycles through DGFT documentation requirements. Distribution runs through direct OEM contracting partnerships that bypass traditional distributor channels in East Asian semiconductor clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflect through specification-in-design partnerships where equipment OEMs embed approved formulators into wafer processing architectures, creating interoperability lock-in comparable to software ecosystems.
For Market Incumbents: Secure qualification pipeline density by extending technical service capacity into compressed 9-month semiconductor fab validation cycles. Deepen backward integration into perfluoropolyether feedstock production to offset raw material cost volatility from integrated chemical producers. Prioritize ISO 14644 cleanroom upgrades at multi-product blending facilities to prevent cross-contamination penalties during customer audits. For New Entrants and Emerging Players: Anchor in India's PLI scheme zones for semiconductor and aerospace component production, where localized blending capabilities confer first-mover advantage against import-dependent competitors. Target research laboratory segments in Germany and Switzerland with cryogenic-rated formulations, where qualification demands remain less stringent than semiconductor fabrication. Pursue direct contracting with national laboratory procurement officers through specification flexibility rather than volume scale. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision blenders with dedicated analytical laboratories and OEM qualification track records. Long-term viability rests on reformulation agility as regulatory frameworks fragment across EPA, ECHA, and METI jurisdictions. Monitor ECHA F-Gas Regulation amendment timelines as inflection indicators for substitution velocity toward silicone alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Feedstock | Captive perfluoropolyether supply insulates DuPont and Chemours from raw material cost volatility. |
| Direct OEM Contracting Partnerships | Taiwan Semiconductor Manufacturing and Samsung Foundry unbundling lubricant procurement rewards specification-in-design capabilities. |
| ISO 14644 Cleanroom Certification | Multi-product blenders prevent particulate migration penalties between fluorinated and hydrocarbon grades. |
| Shorter-Chain Fluorinated Reformulation | French aerospace test facilities pilot ECHA-compliant alternatives to preempt PFAS supply disruption. |
| India PLI Scheme Localization | Gujarat and Tamil Nadu precision manufacturing clusters negotiate bulk supply contracts for hydrocarbon blending. |
Research Methodology
Operator-level perspectives from vacuum system maintenance directors, semiconductor OEM procurement teams, specialty chemical plant managers, and national laboratory research coordinators anchored the qualitative base. Primary interview data triangulated against customs trade records, SEC filings from integrated chemical producers, ECHA substance restriction databases, and semiconductor equipment capex disclosures. Bottom-up consumption modeling across product chemistry, application environment, and end-use certification standards converged with top-down market sizing from regional production cluster analysis.
Sensitivity analysis tested forecast robustness across regulatory acceleration scenarios and substitution elasticity parameters throughout the projection horizon. Segmentation dimensions spanned base stock chemistry, vacuum performance tier, end-user industry qualification intensity, and packaging format precision. CAGRs derived from equipment installation run-rates, fab capacity expansion pipelines, and research infrastructure investment commitments. Forecast inputs incorporated EPA PFAS restriction timelines, ECHA F-Gas Regulation amendment trajectories, and METI chemical management framework evolution.
Material uncertainties — semiconductor capital expenditure cyclicality, regulatory restriction scope expansion, and silicone formulation performance parity achievement — sit outside the modeled envelope. Forecasts reflect assumptions on qualification cycle stability and OEM supplier list consolidation velocity. Practitioners should keep alternative scenarios live as ECHA substance restriction schedules and EPA enforcement priorities evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Natural Ingredient Insect Repellent Market
Specialty Chemicals
Silver Sulfate Market
Specialty Chemicals
Ethyl Polysilicate Market
Specialty Chemicals
Stearates Market
Specialty Chemicals
Superdisintegrants Market
Specialty Chemicals
Marine Hyaluronic Acid Market
Specialty Chemicals
Allantoin Market
Specialty Chemicals
Global Ceramide Market
Specialty Chemicals
Dipentene (Limonene) Market
Specialty Chemicals
Phosphonate Market
Specialty Chemicals
Zinc Methionine Chelates Market
Specialty Chemicals
Stable Isotopes Market
Specialty Chemicals
Biocides Market
Specialty Chemicals
Spiroglycol Market
Specialty Chemicals
Hyaluronic Acid Market
Specialty Chemicals
Epoxidized Soybean Oil Market