
 Global Amorphous Alloy Band Market | 2026-2036
Global Amorphous Alloy Band Market Size, Share, and Industry Trends Forecast 2026-2036
Global Amorphous Alloy Band Market Foresight
Direct procurement from melt-spinning foundries is rewriting how automotive suppliers and power utilities source magnetic core material. Hitachi Metals Ltd. leverages captive rapid-solidification capacity to anchor premium supply contracts across Japanese transformer OEMs. Qingdao Yunlu Advanced Materials Technology Co., Ltd. competes on scale, operating multiple melt-spinning lines that feed domestic grid modernization programs. VACUUMSCHMELZE GmbH differentiates through vacuum-melting precision, sustaining niche dominance in aerospace-grade cobalt-based ribbon for sensor applications.
Amorphous alloy band consists of metal glass ribbon produced by melt spinning molten alloy onto a rotating copper wheel at cooling rates exceeding one million degrees per second, yielding thicknesses of 20–30 micrometers with near-zero crystalline structure. This material delivers core losses 70–80% below conventional grain-oriented silicon steel, making it indispensable for distribution transformer cores and high-frequency magnetic components. Iron-based ribbon dominates volume demand from power generation utilities seeking minimum regulatory loss coefficients, while cobalt-based grades command concentrated margin pools in magnetic sensors for medical and defense end uses. Melt spinning remains the incumbent production technology, though rapid solidification variants are gaining traction for zirconium-based compositions targeting data storage device substrates.
China's MEE enforces escalating GB standards on transformer no-load losses, directly expanding addressable demand for amorphous core material. Japan's METI coordinates JIS certification pathways that constrain import eligibility for non-domestic ribbon suppliers. The EU F-Gas Regulation and REACH compliance layers add testing burdens for European transformer manufacturers sourcing Asian ribbon. Stakeholders must monitor how divergent efficiency certification timelines across Beijing, Tokyo, and Brussels reshape sourcing geography and captive melt-spinning investment decisions.
Market Dynamics
China's GB standards on transformer energy efficiency are compressing loss coefficients and forcing grid operators to abandon grain-oriented silicon steel for iron-based amorphous ribbon. This regulatory compression is redrawing procurement patterns across East Asian manufacturing clusters.
Growth Catalysts
- Dual carbon goals:China's national decarbonization framework mandates energy-efficient distribution infrastructure, directly expanding amorphous core deployment in provincial grid upgrades.
- Melt-spinning scale economies:Foundries in Shandong and Henan provinces now operate multi-line facilities that reduce unit costs for iron-based ribbon below competitive silicon steel thresholds.
- JIS certification pathways:Japan's METI maintains stringent domestic qualification standards that insulate certified suppliers from price-based import competition.
Market Restraints
- Cobalt price volatility:Aerospace-grade cobalt-based ribbon remains exposed to London Metal Exchange fluctuations that compress margin pools in sensor applications.
- Supply concentration risk:Rapid-solidification capacity clusters heavily in East Asian melt-spinning foundries, creating geographic vulnerability for European transformer OEMs.
- Technical brittleness:Amorphous ribbon's mechanical fragility during core winding limits adoption in mobile or vibration-intensive transformer deployments.
Strategic Opportunities
- EU F-Gas Regulation alignment:European transformer manufacturers face REACH and efficiency compliance layers that favor low-loss core materials in replacement cycles.
- Data storage substrates:Zirconium-based rapid solidification variants are penetrating magnetic recording media applications beyond traditional power distribution.
- Direct utility procurement:Power grid operators in India are bypassing distributor networks to source ribbon directly from melt-spinning foundries.
Industry Challenges
- Rapid-solidification engineering talent:The specialized metallurgical expertise required for consistent 20–30 micrometer ribbon production remains concentrated in legacy Japanese and Chinese facilities.
- GB standard compliance timelines:China's MEE accelerates loss-limit phase-outs faster than transformer OEMs can requalify supply chains, creating certification backlogs.
- Core winding automation:Legacy transformer manufacturing lines require capital-intensive retooling to handle amorphous ribbon without crystallization-inducing stress.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Amorphous Alloy Band Market |
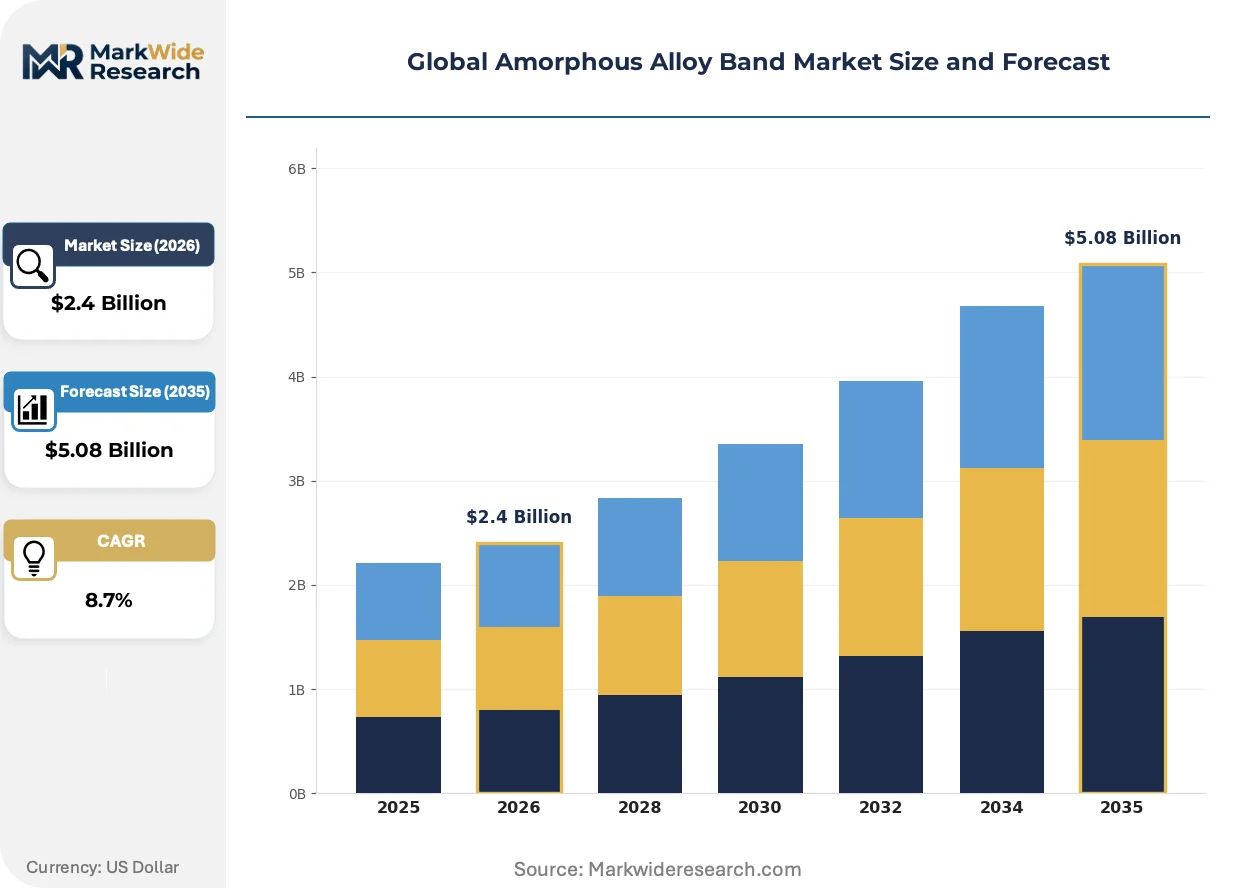
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cobalt-Based, Iron-Based, Zirconium-Based, Titanium-Based Technology: Rapid Solidification, Vacuum Melting, Melt Spinning, Injection Molding Application: Transformer Cores, Magnetic Sensors, Electrical Motors, Data Storage Devices End User Industry: Power Generation, Consumer Electronics, Telecommunications, Automotive Suppliers |
| Companies Covered | Hitachi Metals Ltd., Qingdao Yunlu Advanced Materials Technology Co., Ltd., Advanced Technology & Materials Co., Ltd., VACUUMSCHMELZE GmbH, Metglas Inc., China Amorphous Technology Co., Ltd., Henan Zhongyue Amorphous New Materials Co., Ltd., Foshan Huaxin Microlite Metal Co., Ltd., JFE Steel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Amorphous Alloy Band Market Shifts & Advancements
Amorphous alloy processing is diverging into application-specific rapid-solidification variants that optimize magnetic properties for distinct frequency and loss regimes. This specialization is fragmenting what was once a commoditized ribbon supply base.
Melt-spinning technology is hybridizing with in-line annealing systems that stabilize amorphous structure while enabling continuous coil production. Japanese transformer OEMs are adopting these integrated lines to reduce core loss variability. The technology is hybridizing quality control and throughput in ways that compress delivery cycles for grid modernization programs.
REACH compliance in the European Union is layering substance-testing burdens on transformer manufacturers sourcing Asian ribbon. The regulation forces batch-level documentation of alloy composition that extends procurement lead times. German and French OEMs are responding by qualifying secondary European melt-spinning sources despite higher unit costs.
Utility procurement departments are consolidating supplier rosters around foundries with captive rapid-solidification and in-house core-winding capabilities. This consolidation displaces independent ribbon distributors across Southeast Asian markets. The pattern is most visible in Vietnam and Thailand, where state grid operators now mandate single-source accountability for loss coefficient guarantees.
Global Amorphous Alloy Band Market Segmentation
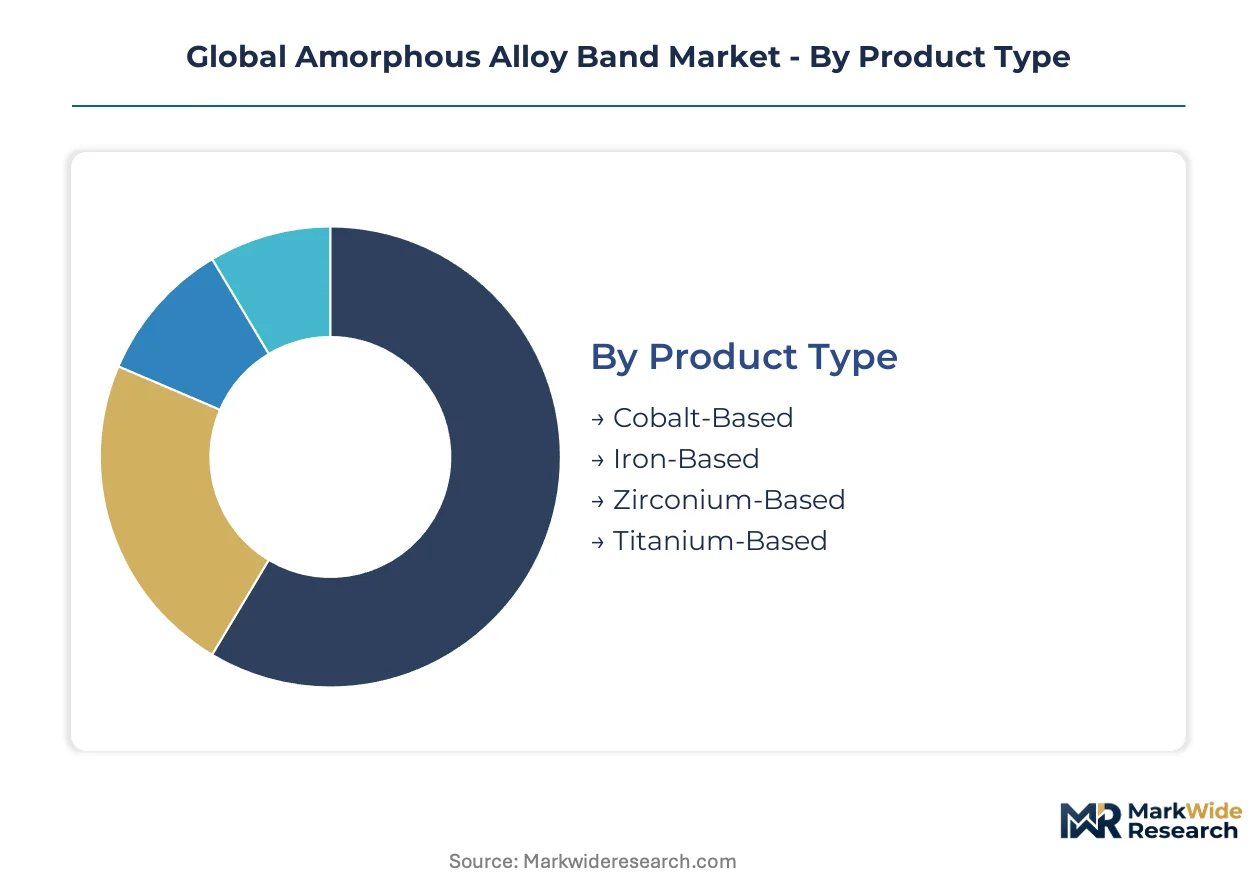
Segmentation in amorphous alloy band markets reveals how material composition, production technology, and end-use specifications create distinct competitive arenas. Procurement patterns diverge sharply between power utilities prioritizing core loss coefficients and aerospace sensor manufacturers demanding cobalt-based precision.
Product Type:
Mature iron-based grades anchor volume demand while emerging zirconium and titanium variants penetrate specialized frequency regimes.
- Iron-Based:Iron-silicon-boron compositions dominate distribution transformer cores with 70–80% loss reduction versus grain-oriented silicon steel. China's Shandong and Henan foundries concentrate melt-spinning capacity to serve provincial grid modernization under MEE efficiency mandates.
- Cobalt-Based:Cobalt-iron-boron-silicon alloys deliver near-zero magnetostriction for high-sensitivity magnetic sensors. Aerospace and medical device manufacturers in Japan absorb premium-priced ribbon qualified through METI JIS certification pathways.
- Zirconium-Based:Zr-Cu-Ni-Al compositions target data storage substrates via rapid solidification variants.
- Titanium-Based:Ti-based amorphous alloys serve niche corrosion-resistant magnetic components.
Iron-based ribbon handles the majority of throughput; zirconium-based formulations are expanding most quickly into magnetic recording media.
Technology:
Cost tiers separate incumbent melt-spinning from capital-intensive vacuum melting and emerging injection molding approaches.
- Melt Spinning:Molten alloy ejected onto copper wheels at 10^6 K/s cooling rates produces 20–30 micrometer ribbon. East Asian foundries achieve scale economies through multi-line facilities serving direct utility procurement.
- Vacuum Melting:Vacuum-induction melting followed by controlled solidification enables ultra-low oxygen content for aerospace-grade cobalt ribbon. German and French OEMs qualify European vacuum-melting sources to bypass REACH documentation burdens on Asian imports.
- Rapid Solidification:Variants optimized for zirconium-based compositions penetrate data storage applications.
- Injection Molding:Bulk metallic glass molding enables complex near-net-shape magnetic components.
Melt spinning commands the installed base; vacuum melting captures the steepest margin expansion in sensor-grade material.
Application:
Application segmentation tracks how loss-coefficient requirements and frequency regimes split demand between power infrastructure and precision electronics.
- Transformer Cores:Laminated iron-based ribbon cores meet China's GB standard loss limits phasing out conventional silicon steel. Grid operators in Vietnam and Thailand now mandate single-source accountability for efficiency guarantees.
- Magnetic Sensors:Cobalt-based ribbon's constant permeability enables medical imaging and defense applications. Japanese METI JIS certification insulates domestic suppliers from price-based import competition.
- Electrical Motors:High-frequency motor laminations absorb iron-based ribbon in automotive supplier programs.
- Data Storage Devices:Zirconium-based substrates for magnetic recording media.
Transformer cores absorb the dominant volume share; data storage devices are gaining share fastest as rapid solidification variants mature.
End User Industry:
Customer type segmentation exposes how procurement centralization varies between regulated utilities and dispersed electronics manufacturers.
- Power Generation:State grid operators in China, India, and Southeast Asia consolidate supplier rosters around foundries with captive melt-spinning and in-house core winding. India's CEA guidelines accelerate direct procurement from ribbon manufacturers.
- Automotive Suppliers:Tier-1 motor manufacturers qualify iron-based ribbon for electric drivetrain components. Core winding automation investments remain concentrated in Japanese and Korean transformer OEMs.
- Consumer Electronics:Smartphone and wearable manufacturers source miniature inductor cores.
- Telecommunications:5G infrastructure drives demand for high-frequency magnetic components.
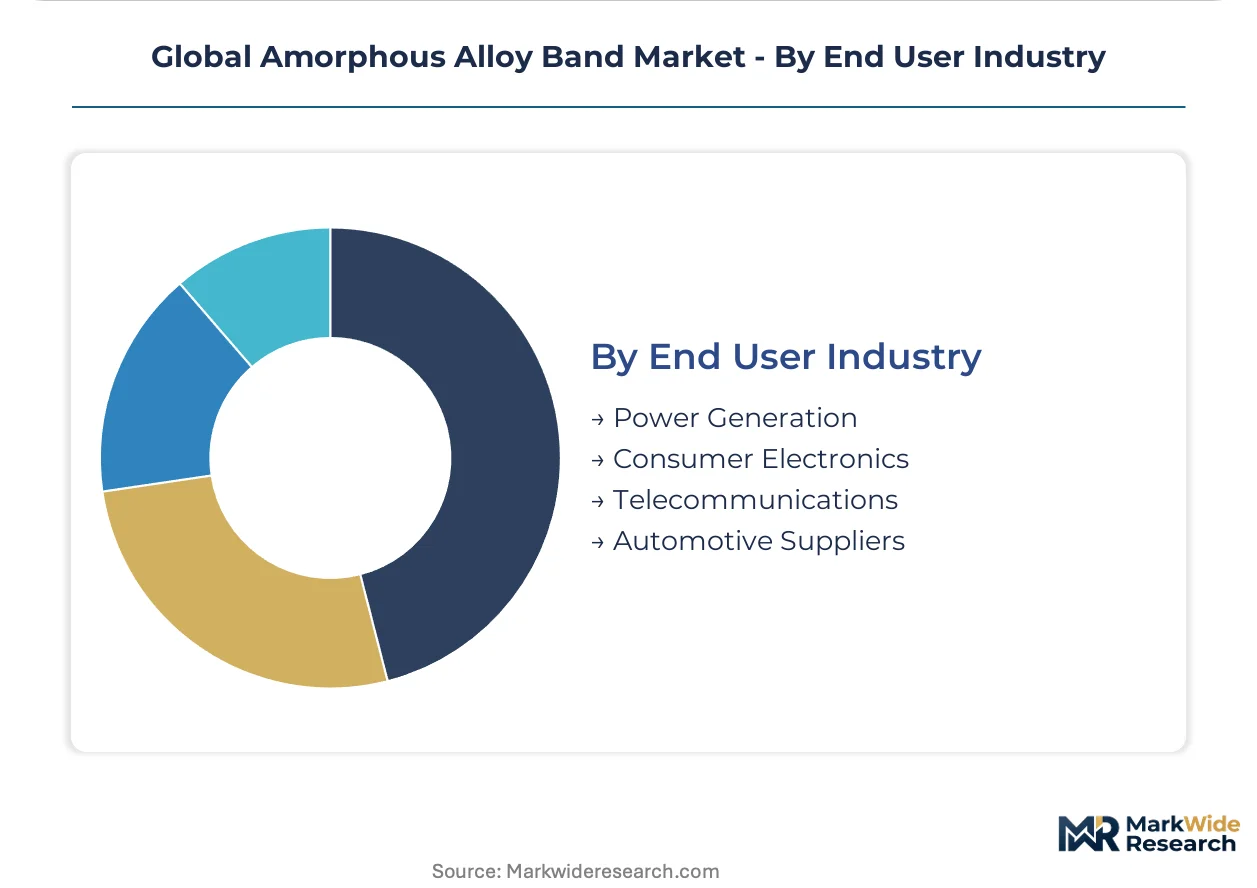
Power generation commands the largest procurement volumes; telecommunications is climbing the fastest on 5G deployment timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian melt-spinning foundries command pricing leverage over European transformer OEMs, while Indian grid operators exploit procurement reforms to source ribbon directly from Shandong and Henan production clusters.
China
Provincial grid operators in Shandong and Henan provinces absorb the majority of iron-based ribbon output from multi-line melt-spinning facilities. The Ministry of Ecology and Environment enforces escalating GB standards on transformer no-load losses, phasing out conventional silicon steel ahead of 2030 targets. Qingdao and Zhengzhou industrial corridors host the densest supplier networks serving state grid modernization programs.
Japan
Domestic transformer OEMs rely on METI-coordinated JIS certification pathways that constrain import eligibility for non-certified ribbon suppliers. Aerospace and medical device manufacturers in the Kanto region absorb premium-priced cobalt-based grades for magnetic sensor applications. Tokyo-based procurement departments prioritize qualified domestic sources over price-based Asian competition.
Germany
Transformer manufacturers in Baden-Württemberg and North Rhine-Westphalia qualify secondary European vacuum-melting sources to bypass REACH documentation burdens on Asian imports. The EU F-Gas Regulation and layered compliance requirements extend procurement lead times for ribbon batches. ECHA substance-testing mandates force batch-level documentation that favors regional suppliers despite higher unit costs.
India
State grid operators in Maharashtra and Gujarat consolidate supplier rosters around foundries with captive rapid-solidification capacity. Central Electricity Authority guidelines accelerate direct procurement from ribbon manufacturers, bypassing traditional distributor networks. The western industrial corridor attracts melt-spinning investment to serve utility-scale transformer deployment under national efficiency mandates.
Vietnam
State grid operators mandate single-source accountability for loss coefficient guarantees in distribution transformer procurement. Northern manufacturing zones near Hanoi host emerging core-winding facilities that source ribbon from Chinese melt-spinning foundries. The national power utility tightens supplier qualification requirements to match Thai and Indonesian grid modernization standards.
Global Amorphous Alloy Band Market Competitive Landscape
Scale-driven foundries and precision-grade specialists split the market into distinct competitive arenas with limited overlap. East Asian producers dominate volume throughput through multi-line melt-spinning facilities, while European and Japanese suppliers capture margin concentration in aerospace-grade and sensor-grade material. The vendor base stratifies across captive rapid-solidification operators, independent ribbon distributors, and integrated core-winding specialists. Capacity expansion in Shandong and Henan provinces and strategic partnerships between transformer OEMs and certified foundries represent the dominant competitive moves reshaping procurement geography.
Among Japanese and German precision-grade suppliers, Hitachi Metals Ltd. and VACUUMSCHMELZE GmbH occupy positions that exemplify certification-insulated market segments. Chinese scale-driven producers including Qingdao Yunlu Advanced Materials Technology Co., Ltd. anchor the volume tier supplying provincial grid operators under direct procurement frameworks. These three entities represent the archetypal positioning that defines competitive boundaries between premium-grade sensor applications and mass-market transformer core deployment.
| Leading Market Players |
|---|
| Hitachi Metals Ltd. |
| Qingdao Yunlu Advanced Materials Technology Co., Ltd. |
| Advanced Technology & Materials Co., Ltd. |
| VACUUMSCHMELZE GmbH |
| Metglas Inc. |
| China Amorphous Technology Co., Ltd. |
| Henan Zhongyue Amorphous New Materials Co., Ltd. |
| Foshan Huaxin Microlite Metal Co., Ltd. |
| JFE Steel Corporation |
| Others |
Supply & Pricing Matrix
Shandong and Henan foundries anchor global melt-spinning capacity, compressing unit costs for iron-based ribbon below silicon steel thresholds while concentrating pricing leverage among multi-line operators serving state grid procurement programs.
Pricing Analysis
Configured-to-order pricing for aerospace-grade cobalt ribbon commands substantial premiums over standard iron-based grades for distribution transformers. Pricing stratifies across JIS-certified sensor material, GB-compliant grid ribbon, and unqualified commodity tiers. Cost compression in standard iron-based ribbon intensifies because Shandong foundries scale multi-line output for direct utility procurement. State grid operators in China and India exhibit highest price sensitivity, while Japanese medical device manufacturers absorb premiums for METI-certified cobalt grades.
Supply Chain Analysis
Iron ore, boron, and cobalt feedstock flows concentrate procurement risk for ribbon manufacturers dependent on London Metal Exchange pricing. Melt-spinning capacity clusters in China, Japan, and Germany, with Shandong and Henan provinces hosting densest supplier networks. Single-source vulnerability runs through East Asian rapid-solidification foundries, exposing European transformer OEMs to logistics chokepoints and REACH documentation delays. Distribution runs through direct procurement frameworks where state grid operators consolidate supplier rosters around captive melt-spinning operators with in-house core-winding capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Grid modernization cycles position this market for cyclical recovery as China's dual carbon goals and India's CEA efficiency mandates accelerate transformer replacement programs.
For Market Incumbents: Entrench JIS and GB certification barriers by accelerating qualification timelines ahead of regulatory phase-outs. Hitachi Metals and Qingdao Yunlu should deepen backward integration into boron and silicon feedstock to offset cobalt price volatility. Captive rapid-solidification capacity in Shandong insulates against emerging Chinese scale players.
For New Entrants and Emerging Players: Build out vacuum-melting precision capability for European aerospace sensor markets where REACH compliance burdens disqualify Asian imports. India's direct procurement reforms create the most penetrable entry path for foundries offering single-source accountability. Qualify through CEA guidelines as a Tier-2 supplier to state utilities in Maharashtra and Gujarat.
For Investors and Strategic Acquirers: Long-term, this sits as a regulated infrastructure play because efficiency mandates in China, Japan, and India lock in replacement demand regardless of commodity cycles. Target acquisition archetype: mid-cap foundries with captive melt-spinning and qualified core-winding automation. Watch for inflection when GB standard loss-limit phase-outs accelerate faster than OEM supply chain requalification.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Line Melt-Spinning Expansion | Shandong foundries achieve scale economies that undercut silicon steel on transformer core cost. |
| JIS Certification Investment | METI pathways insulate Japanese suppliers from price-based import competition in sensor grades. |
| Backward Integration into Boron Supply | Captive feedstock hedges against London Metal Exchange volatility in cobalt-linked margin pools. |
| Direct Utility Procurement Frameworks | India's CEA guidelines displace distributor networks and consolidate supplier accountability. |
| Vacuum-Melting Precision Capacity | German and French OEMs qualify European sources to bypass REACH batch-documentation burdens. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with melt-spinning foundry managers, transformer OEM procurement directors, and state grid planning officers; and secondary validation through customs trade data, SEC filings of listed magnetic materials suppliers, GB and JIS standard documentation, and IEA grid investment reports. Bottom-up volume triangulation across iron-based, cobalt-based, and zirconium-based ribbon grades reconciled against top-down power transformer deployment forecasts.
Forecast inputs span product type segmentation by alloy composition, technology tier by solidification method, application split between transformer cores and magnetic sensors, and end-user concentration across power utilities and automotive suppliers. CAGRs derived from regression against historical transformer procurement cycles and regulatory mandate timelines, with elasticity assumptions for cobalt price volatility and silicon steel substitution thresholds.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed foundries or accelerated GB standard phase-outs would shift outcomes beyond modeled ranges. Cross-checking against IEA distribution infrastructure investment benchmarks and national transformer stock data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Nitinol Market
Advanced Alloys
Titanium Aluminide Market
Advanced Alloys
Metal Replacement Market
Advanced Alloys
Quartz Kitchen Countertops Market
Advanced Alloys
Soft Magnetic Material for Electric Vehicle Market
Advanced Alloys
India Aluminum Extrusion Market
Advanced Alloys
Molybdenum Disilicide Market
Advanced Alloys
Oxide Dispersion Strengthened (ODS) Alloys Market
Advanced Alloys
High Strength Steel (HSS) Market
Advanced Alloys
Ballistic Material Market
Advanced Alloys
Aramid Prepreg Market
Advanced Alloys
Thulium Silicide Market
Advanced Alloys
Middle East and Africa Aluminum Casting Market
Advanced Alloys
Lithium Nitride Market
Advanced Alloys
Polyphenylene Ether (PPE) Alloy Market
Advanced Alloys
Medium Entropy Alloys Market