
 Aluminum Composite Panel Market | 2026-2036
Aluminum Composite Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Composite Panel Market Intelligence
Fire-resistant specification-tier upgrades across commercial high-rises is unwinding a broader shift toward certified, code-compliant cladding systems. Alcoa Corporation leverages upstream aluminum supply control to secure raw material consistency for panel manufacturers. 3A Composites anchors European technical standards through its specialized focus on architectural-grade core formulations. Mitsubishi Chemical differentiates via advanced polymer core technologies that meet stringent reaction-to-fire classifications.
An aluminum composite panel consists of two thin aluminum sheets bonded to a non-aluminum core, typically polyethylene or mineral-filled material, with overall thickness ranging from 3mm to 6mm for standard facade applications and engineered to provide lightweight rigidity with weather resistance. The product serves primarily as an exterior cladding and architectural finishing system for commercial, institutional, and transportation infrastructure. Fire-resistant panels command premium positioning as building codes in major construction markets mandate stricter reaction-to-fire performance, while solar reflective coatings are gaining specification share in warm-climate regions where thermal performance drives energy compliance. Interior design applications represent a developing margin pool as designers specify thinner 3mm panels for feature walls and retail environments.
FDA guidelines on building material emissions intersect with EPA regional air quality standards to shape permissible core chemistries and coating formulations in US specification markets. REACH restrictions in Europe and China's GB standards collectively constrain halogenated core materials, pushing manufacturers toward mineral-filled and thermoplastic alternatives that satisfy multi-jurisdictional compliance. Stakeholders must track evolving fire safety test protocols across regulatory regimes to anticipate which core technologies will retain specification access.
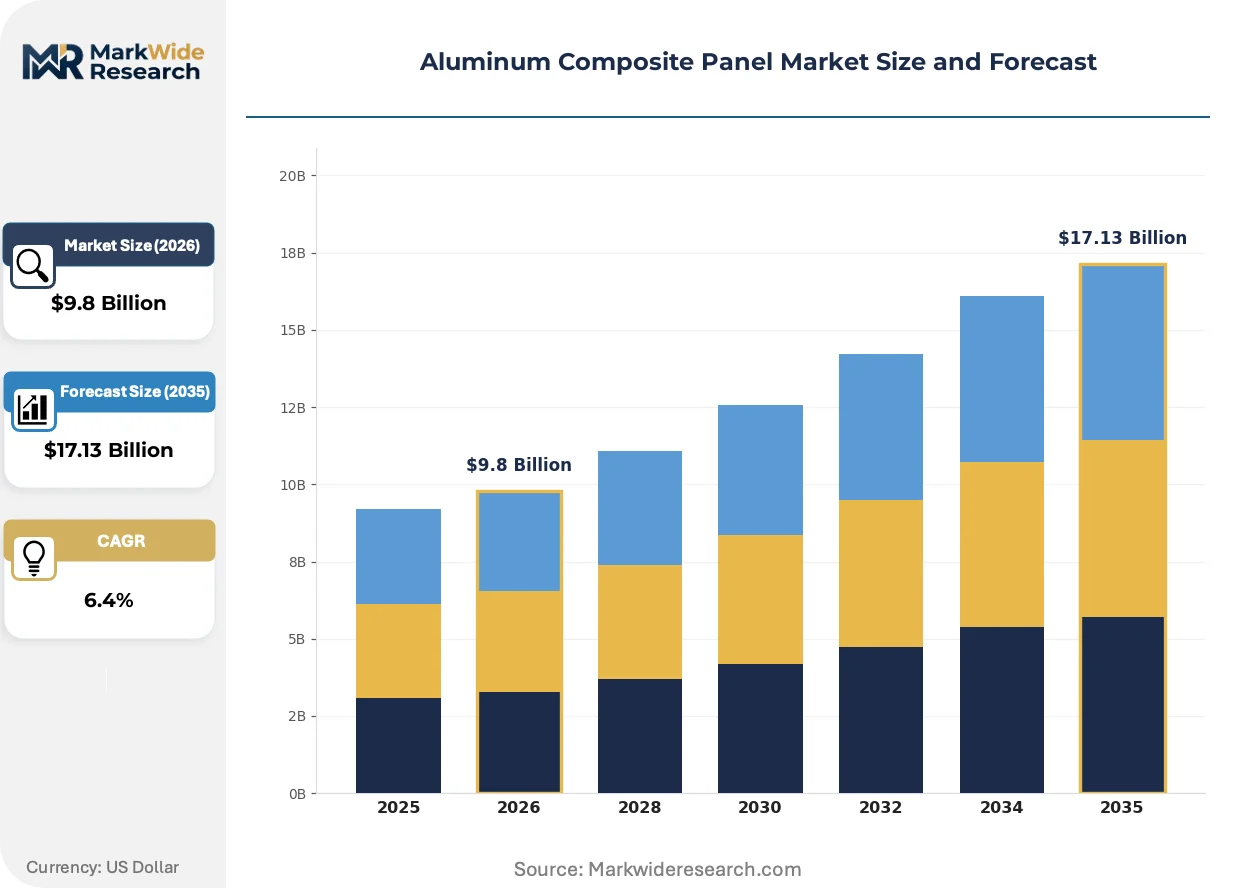
Market Dynamics
Fire-rated specification upgrades are compressing procurement timelines across commercial high-rises, as Jakarta, Singapore, and Bangkok authorities accelerate facade safety audits and mandate certified ACP systems for new permits.
Growth Catalysts
- GB 8624 fire classification mandates:China's Ministry of Emergency Management enforcement is redirecting procurement toward mineral-core panels in high-rise construction.
- Transit-oriented development clusters:Indonesia's Jakarta-Bandung corridor is specifying aluminum composite materials for station facades and retail podiums.
- Solar reflective coating specifications:Warm-climate commercial towers in Southeast Asia are prioritizing thermal performance coatings to meet energy compliance thresholds.
Market Restraints
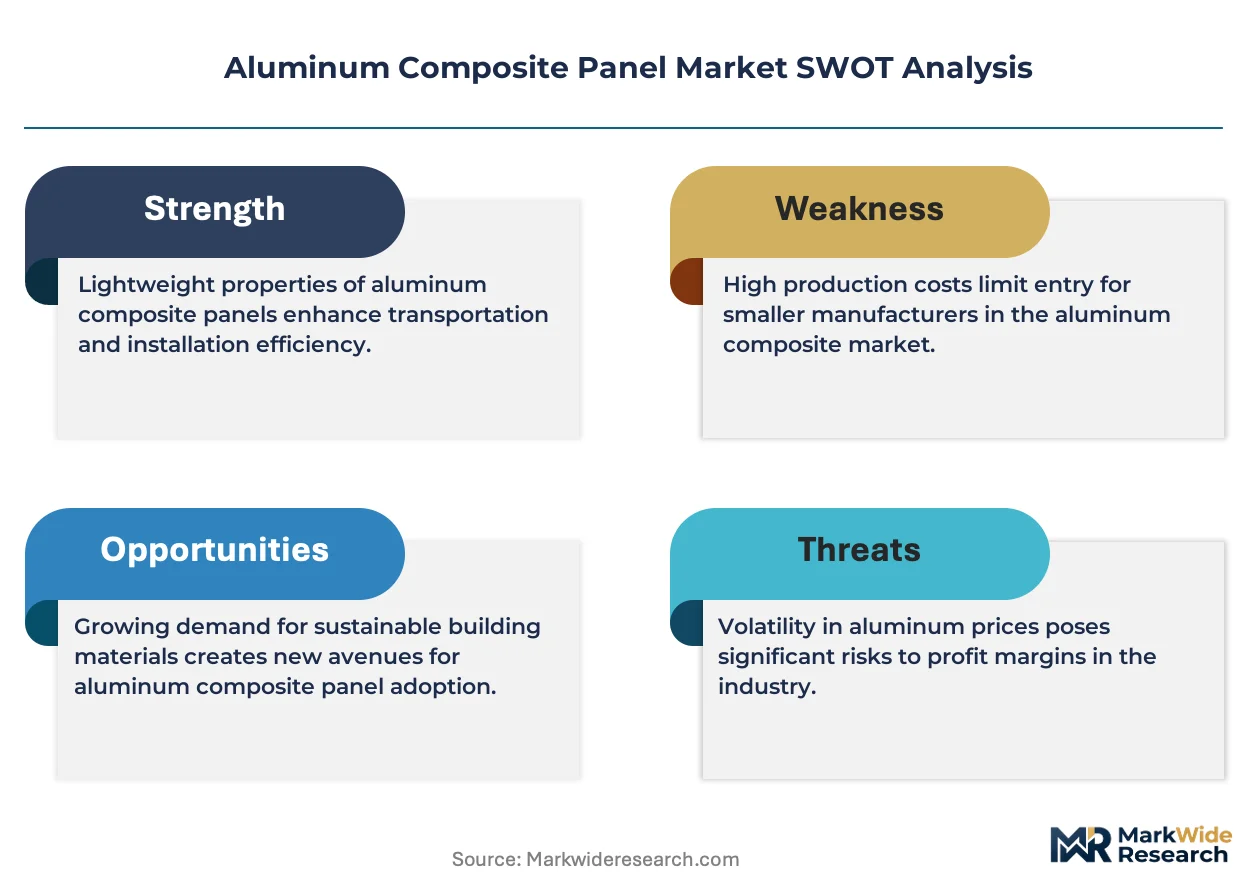
- Aluminum ingot price volatility:Raw material cost swings compress panel manufacturer margins and destabilize project bidding.
- Core chemistry restrictions:REACH halogenated material bans and China's MEE environmental standards constrain legacy polyethylene core formulations.
- Mineral-core production concentration:Limited qualified suppliers in Germany and Japan create supply bottlenecks for fire-rated specifications.
Strategic Opportunities
- Vietnam's secondary cities:Da Nang and Hai Phong commercial construction is underpenetrated for certified ACP systems.
- Interior feature wall applications:Retail and hospitality designers are specifying thinner 3mm panels for branded environments.
- EU Green Deal embodied carbon tracking:CSRD disclosure requirements create specification advantage for low-carbon core material suppliers.
Industry Challenges
- Multi-jurisdictional fire test certification:ASTM E84, EN 13501-1, and GB 8624 protocol divergence extends product validation timelines.
- Facade installer skill gaps:Specialized mineral-core panel handling and sealing techniques outpace regional contractor training capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Composite Panel Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fire-Resistant, Anti-Bacterial, Acoustic, Solar Reflective End User: Construction, Transportation, Signage, Interior Design Thickness: 3mm, 4mm, 6mm, 8mm Application: Facade Cladding, Roof Covering, Interior Wall, Exhibition Stands |
| Companies Covered | Alcoa Corporation, Alubond USA, 3A Composites, Alcadex, Alstrong Enterprises, Mitsubishi Chemical, Jyi Shyang Industrial, CCJX, Arconic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Composite Panel Market Strategic Shifts & Innovations
Specification-grade panel systems are fragmenting into performance-tiered categories as building codes harden and thermal efficiency targets tighten across tropical and temperate construction zones.
Mineral-filled thermoplastic core technology is decomposing the traditional polyethylene-core market. Singapore and Bangkok commercial developers are specifying these panels for all high-rise facades. The technology is decomposing price-competitive positioning for uncertified legacy suppliers.
REACH restrictions on halogenated flame retardants are forcing core chemistry reformulation across European supply chains. Manufacturers are accelerating mineral-filled and intumescent alternatives to retain specification access. German facade engineering firms are driving adoption fastest, with EN 13501-1 A2-s1,d0 classifications becoming baseline for premium commercial towers.
Specification-driven buyer concentration is compressing distributor influence. Large commercial developers in Jakarta and Manila are engaging panel manufacturers directly for certified supply agreements. This pattern is most visible in transit-oriented mixed-use projects where fire safety liability concentrates with the master developer.
Aluminum Composite Panel Market Segmentation
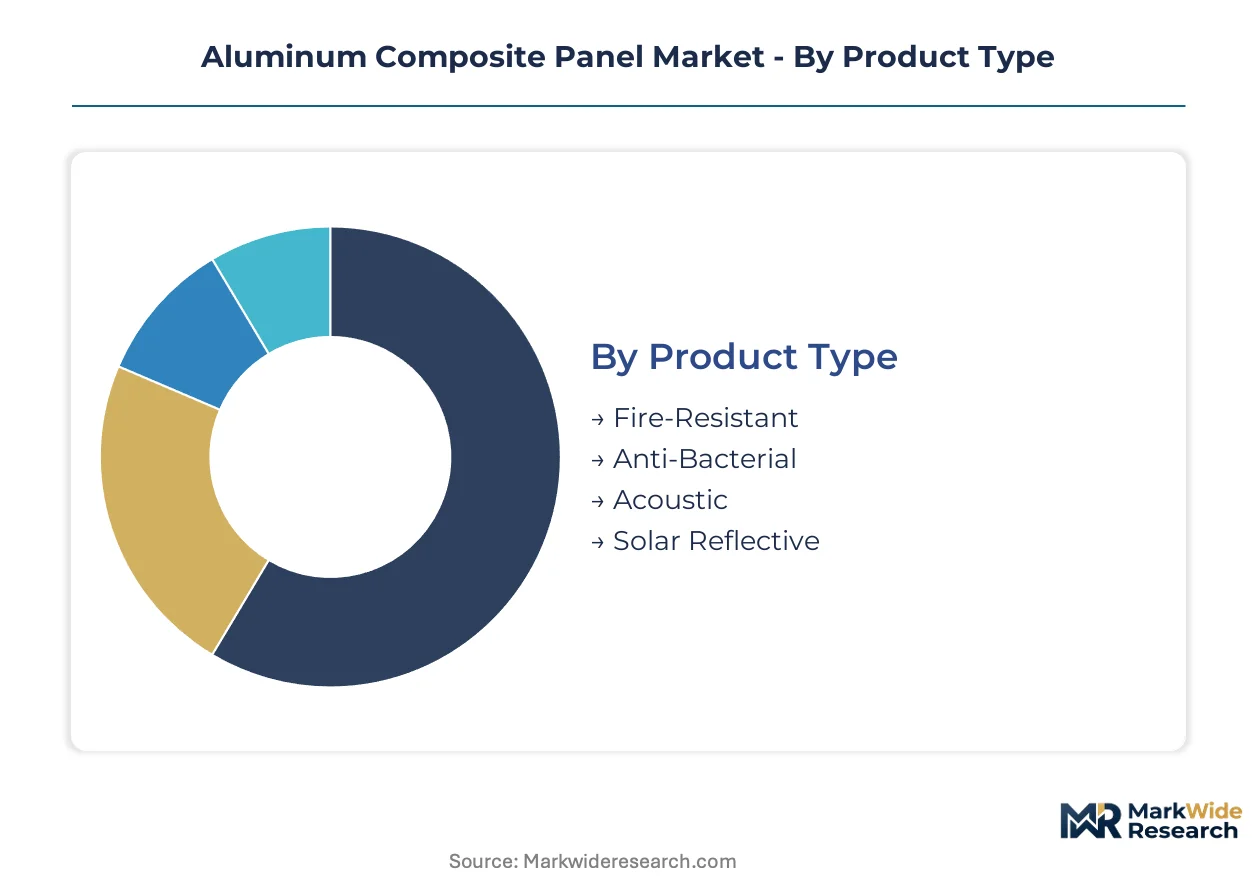
Aluminum composite panel demand fragments across performance tiers that align with diverging regulatory pressures and end-use specifications. Understanding these segment boundaries reveals where procurement premiums concentrate and which technical attributes command specification priority across construction, transportation, and interior environments.
Product Type:
Fire-resistant and solar reflective variants dominate export-led procurement from certified German and Japanese suppliers, while anti-bacterial and acoustic panels serve more localized specification pockets in healthcare and institutional markets.
- Fire-Resistant:Mineral-filled thermoplastic cores bonded to aluminum skins achieve EN 13501-1 A2-s1,d0 and GB 8624 Class A ratings. Jakarta and Singapore commercial towers mandate these panels for all high-rise facades as authorities accelerate safety audits and tighten permit requirements.
- Solar Reflective:Specially formulated fluoropolymer coatings with high solar reflectance index values reduce thermal load in warm-climate construction. Bangkok and Manila commercial developers specify these for energy compliance thresholds in premium office towers.
- Anti-Bacterial:Silver-ion or copper-infused surface treatments inhibit microbial growth on interior panels. Hospitals and pharmaceutical facilities in urban Southeast Asian centers drive niche specification.
- Acoustic:Perforated aluminum facing with sound-absorbing mineral wool backing attenuates noise in transit infrastructure. Airport terminals and rail stations across Indonesia specify these for passenger comfort zones.
Fire-resistant panels command the established base. The steepest expansion runs through solar reflective specifications.
End User:
Construction absorbs the dominant volume share, yet transportation and interior design applications are climbing the fastest as specification boundaries blur between exterior and interior performance requirements.
- Construction:Commercial high-rises, mixed-use developments, and institutional buildings specify ACP systems for facade cladding, canopy structures, and architectural screening. China's GB standards enforcement redirects procurement toward certified mineral-core systems in high-rise construction.
- Interior Design:Retail environments, hospitality lobbies, and corporate reception areas specify thinner 3mm panels for branded feature walls and wayfinding elements. Designers in Jakarta and Manila favor these for rapid installation and visual impact.
- Transportation:Metro stations, airport terminals, and bus rapid transit infrastructure use ACP for durable, low-maintenance interior and exterior surfaces. Indonesia's Jakarta-Bandung corridor transit-oriented development concentrates demand.
- Signage:Flatbed signage, corporate identity systems, and retail fascia applications utilize standard polyethylene-core panels. This segment faces margin pressure from digital display substitution.
Construction retains volume leadership. Interior design is gaining share fastest as specification migrates indoors.
Thickness:
Thickness selection maps directly to structural load requirements and fire performance tiers, with 4mm and 6mm variants anchoring commercial facade standards while 3mm serves interior and signage economies.
- 4mm:The commercial facade standard balances rigidity, weight, and cost for mid-rise curtain wall applications. This specification dominates Southeast Asian commercial construction procurement.
- 6mm:Enhanced structural capacity supports high-rise wind loads and large-format panel dimensions. Premium towers in Singapore and Bangkok specify these for architectural boldness and safety margins.
- 3mm:Lightweight profile suits interior feature walls, retail signage, and exhibition systems where structural demands are minimal. Interior designers favor this thickness for handling ease and design flexibility.
- 8mm:Heavy-duty specification for specialized structural applications including column covers and architectural soffits. Limited volume concentrates in landmark institutional projects.
4mm thickness commands the established base. The steepest expansion runs through 3mm interior applications.
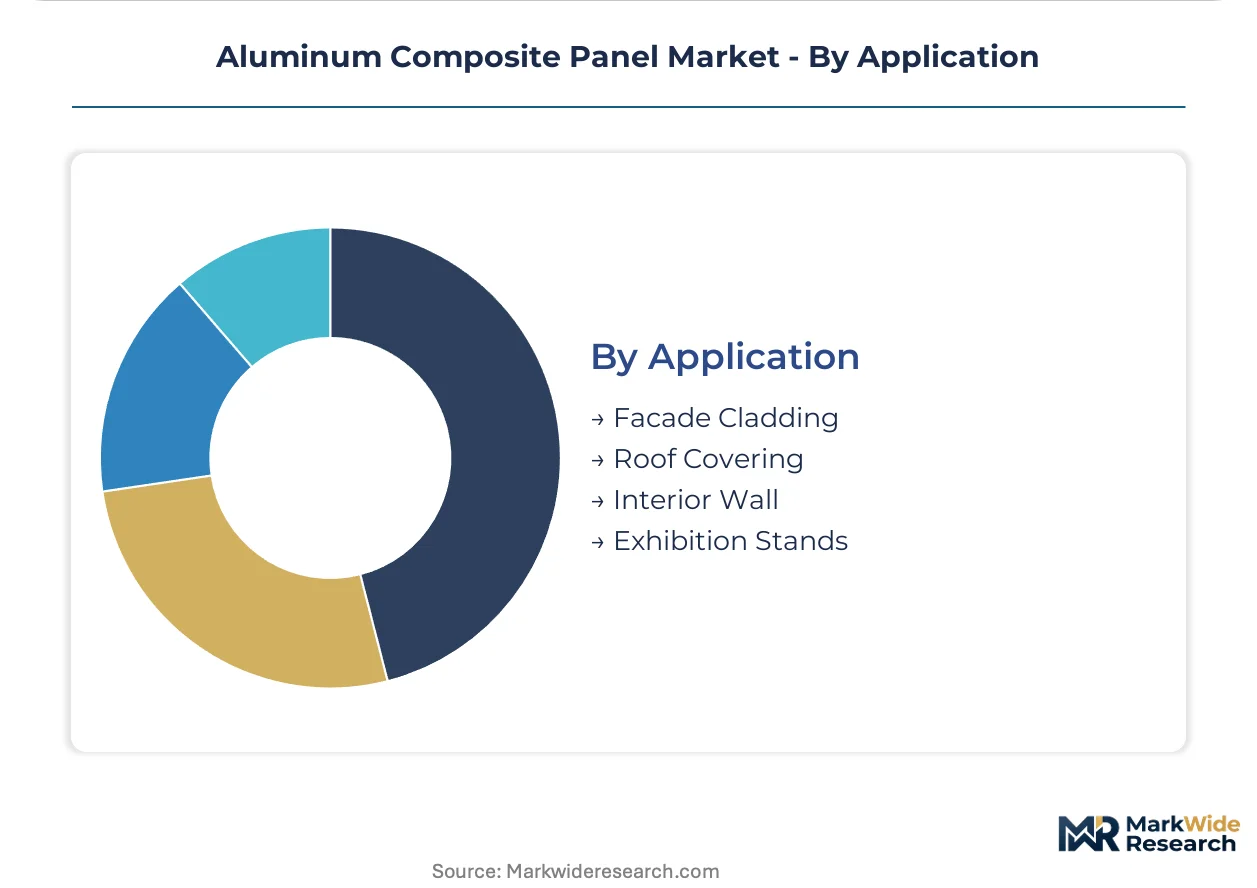
Application:
Facade cladding concentrates revenue and regulatory scrutiny, while interior wall and exhibition stand applications expand through specification migration and temporary construction trends.
- Facade Cladding:Primary exterior envelope application demanding weather resistance, thermal performance, and fire safety compliance. Southeast Asian commercial towers drive specification toward certified mineral-core systems.
- Interior Wall:Feature walls, partition systems, and ceiling applications in retail, hospitality, and corporate environments. Thinner panels and simplified installation expand designer adoption.
- Roof Covering:Canopies, soffits, and architectural roof elements requiring drainage integration and UV stability. Limited volume serves premium commercial and institutional projects.
- Exhibition Stands:Temporary and semi-permanent display structures for trade shows, retail activations, and events. Lightweight 3mm panels enable rapid assembly and reconfiguration.
Facade cladding commands the established base. Interior wall applications are climbing the fastest as specification boundaries shift.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qualified mineral-core production clusters in Germany and Japan constrain fire-rated panel availability as Southeast Asian demand accelerates. Procurement timelines compress where certified supply agreements concentrate with master developers. Code enforcement divergence across jurisdictions fragments specification pathways.
China
High-rise construction in the Yangtze River Delta and Pearl River Delta absorbs premium mineral-core volumes. MEE enforcement of GB 8624 fire classifications redirects procurement away from legacy polyethylene formulations. Shanghai and Shenzhen commercial towers mandate certified ACP systems for all new permits above 24 meters.
Indonesia
Transit-oriented development along the Jakarta-Bandung corridor specifies aluminum composite materials for station facades and retail podiums. National building code amendments tighten facade safety requirements for mixed-use towers. Surabaya and Makassar secondary markets show rising specification penetration for commercial high-rises.
Singapore
Urban Redevelopment Authority facade safety audits accelerate replacement cycles for existing cladding systems. EN 13501-1 A2-s1,d0 classifications serve as baseline specifications for premium commercial towers. Marina Bay and Jurong Lake District developments concentrate demand for solar reflective coated panels.
Germany
Facade engineering firms drive fastest adoption of REACH-compliant mineral-filled core alternatives. CSRD disclosure requirements under the EU Green Deal create specification advantage for low-carbon core material suppliers. The Rhine-Ruhr and Stuttgart industrial corridors anchor European technical standards for architectural-grade formulations.
Thailand
Bangkok commercial developers prioritize thermal performance coatings to meet energy compliance thresholds in premium office towers. Ministry of Interior building safety directives tighten reaction-to-fire requirements for high-rise construction. The Bangkok Metropolitan Region and Chiang Mai emerging commercial zones absorb expanding fire-rated panel volumes.
Aluminum Composite Panel Market Key Industry Players
Concentration sits with integrated aluminum suppliers and specialized core formulators who control upstream material consistency and certified formulation access. The vendor base stratifies across three tiers: global chemical conglomerates with polymer expertise, regional fabricators with distribution density, and niche specialists with project-specific engineering capabilities. Dominant competitive moves include backward integration into aluminum supply and strategic partnerships with facade engineering consultants to secure specification lock-in.
Within the integrated materials tier, Alcoa Corporation and Arconic represent upstream-controlled positioning through captive aluminum supply. Among specialized core formulators, 3A Composites and Mitsubishi Chemical occupy positions defined by regulatory compliance breadth across European and Asian fire safety protocols. Regional fabrication specialists including Alubond USA and Jyi Shyang Industrial exemplify distribution-led models serving project-specific procurement channels.
| Leading Market Players |
|---|
| Alcoa Corporation |
| Alubond USA |
| 3A Composites |
| Alcadex |
| Alstrong Enterprises |
| Mitsubishi Chemical |
| Jyi Shyang Industrial |
| CCJX |
| Arconic |
| Others |
Cost & Logistics Intelligence
Mineral-filled thermoplastic core substitution for legacy polyethylene formulations is simultaneously shifting procurement geography toward German and Japanese qualified suppliers and compressing price-competitive positioning for uncertified legacy manufacturers. This input transition concentrates pricing power with certified core formulators while elevating landed costs for Southeast Asian project developers.
Pricing Analysis
GB 8624 fire classification mandates dictate the pricing tier structure across commercial high-rise procurement. Three-tier pricing structure across premium mineral-core, standard fire-retardant, and economy polyethylene levels separates certified A2-s1,d0 panels from B1-rated alternatives from uncertified imports. Cost compression in economy-tier polyethylene panels is intensifying because REACH halogen restrictions and China's MEE environmental standards constrain legacy formulation access. Price-sensitive signage and temporary exhibition contractors exhibit highest elasticity, while liability-conscious master developers in Jakarta and Singapore show lowest sensitivity.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are extending lead times for mineral-core raw material inbound logistics. Qualified production clusters in Germany, Japan, and South Korea anchor supply for fire-rated specifications, drawing from aluminum ingot feedstock, fluoropolymer coating resins, and mineral filler compounds. Single-source vulnerability concentrates in Japanese specialized core formulators with limited qualified alternatives. Distribution runs through project-direct agreements with master developers, bypassing traditional distributor channels for certified volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aluminum composite panel market functions as a regulatory-entrenchment defensive moat, where multi-jurisdictional fire test certification creates switching costs that lock in specification relationships across project cycles.
For Market Incumbents: Fortify backward integration into aluminum supply and captive mineral-core formulation capacity to defend against raw material volatility and qualified supplier bottlenecks. Expand EN 13501-1 A2-s1,d0 certification coverage into Vietnam's secondary cities before local code enforcement tightens. Prioritize direct engagement with facade engineering consultants in Germany and Singapore to secure specification lock-in for premium commercial towers. For New Entrants and Emerging Players: Anchor in Vietnam's Da Nang and Hai Phong commercial construction zones where certified ACP penetration remains underdeveloped relative to Jakarta-Bandung corridor saturation. Target interior feature wall applications with thinner 3mm panel offerings where designer specification cycles are faster and fire certification requirements are less stringent than facade applications. Pursue retail and hospitality sector entry through rapid-installation value propositions. For Investors and Strategic Acquirers: The market sits at a code-enforcement acceleration phase that favors vertically integrated mineral-core specialists with multi-regional certification breadth. Long-term viability hinges on regulatory compliance scalability across GB, EN, and ASTM protocol convergence. Acquisition target archetype: German or Japanese core formulators with established A2-s1,d0 production and untapped Southeast Asian project-direct relationships. Monitor Singapore URA facade audit enforcement velocity as inflection indicator for replacement cycle demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Supply | Captive ingot sourcing from Alcoa or Arconic insulates margin compression from LME volatility. |
| Multi-Jurisdictional Certification Investment | Simultaneous GB 8624, EN 13501-1, and ASTM E84 access unlocks Jakarta, Singapore, and Bangkok procurement. |
| Mineral-Core Formulation Scale-Up | REACH-compliant thermoplastic core capacity expansion captures share from halogenated legacy suppliers. |
| Project-Direct Distribution Partnership | Master developer agreements in Indonesia's transit-oriented developments bypass distributor margin extraction. |
| Facade Engineering Consultant Engagement | Technical specification influence through German and Singapore engineering firms secures premium tower mandates. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with facade engineering consultants, commercial developer procurement directors, aluminum smelter sales executives, and mineral-core formulator technical directors. Secondary validation drew from Chinese GB standards documentation, European REACH regulatory filings, Indonesian building permit databases, and Southeast Asian customs trade records. Bottom-up project pipeline aggregation and top-down construction spend allocation were triangulated to reconcile volume estimates.
Across the analysis window, forecasts were constructed through segmented modeling across fire-performance tier, thickness specification, end-use application, and regional regulatory cluster dimensions. CAGRs were derived from elasticity-adjusted demand projections tied to code enforcement timelines and urban construction permit data. Key inputs included aluminum ingot price trajectory assumptions and mineral-core production capacity expansion announcements from qualified suppliers.
Material uncertainties — sudden regulatory protocol divergence, raw material supply disruption, or construction financing contraction — sit outside the modeled envelope. Forecasts reflect documented assumptions about code enforcement velocity and qualified supplier capacity scaling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Super Alloys Market
Advanced Alloys
Global Amorphous Alloy Band Market
Advanced Alloys
Lithium Nitride Market
Advanced Alloys
Global Metal Injection Molding Market
Advanced Alloys
Multi-Metal Aluminum Sandwich Panels Market
Advanced Alloys
Global Ferroalloys Market
Advanced Alloys
Powder Metallurgy Components Market
Advanced Alloys
Asia-Pacific Green Steel Market
Advanced Alloys
US Green Steel Market
Advanced Alloys
Global Metal Foams Market
Advanced Alloys
Cermet Market
Advanced Alloys
High Strength Steel (HSS) Market
Advanced Alloys
Steel Fiber Market
Advanced Alloys
Quenched and Tempered Steel Market
Advanced Alloys
Aluminum Die Casting Market
Advanced Alloys
Sintered Steel Market