
 Steel Fiber Market | 2026-2036
Steel Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Fiber Market Intelligence
Market Context
Ultra-high-tensile grade specifications is reorganizing procurement criteria across major infrastructure programs. Bekaert leverages its wire-drawing heritage to anchor premium product lines in European tunneling projects. ArcelorMittal sustains cost-competitive positions through captive steel feedstock and integrated melt-to-fiber operations. Sika AG differentiates via construction chemicals bundling, embedding steel fibers within shotcrete system sales.
Technical Definition and Segment Structure
Steel fiber denotes discrete, short metallic filaments manufactured from drawn carbon or stainless steel wire, typically ranging from 0.5 mm to 1.0 mm in diameter and 25 mm to 60 mm in length, engineered to arrest crack propagation and enhance post-crack tensile capacity in cementitious matrices. Macro fiber commands the dominant revenue share in concrete reinforcement applications where structural load-bearing requirements govern specification, while micro fiber penetrates faster in precast manufacturing segments seeking surface-finish optimization and plastic-shrinkage control. Mine support and shotcrete applications concentrate margin pools through performance-based procurement tied to ground-stability guarantees.
Regulatory Frame and Outlook
EN 14889-1 classifies steel fibers for concrete in Europe, while ASTM A820 governs U.S. material specifications and China's GB/T 39147 establishes domestic testing protocols. ECHA scrutiny of steel production emissions and REACH compliance for surface coatings are elevating low-carbon and stainless variants in public tender evaluations. Stakeholders must monitor evolving embodied-carbon thresholds in infrastructure procurement as specification-grade premiums widen against commodity-grade alternatives.
Market Dynamics
Ultra-high-tensile grade specifications are compressing procurement timelines across European tunneling and Chinese rail programs, forcing specification-grade premiums to widen against commodity alternatives as embodied-carbon thresholds harden in public tender evaluations.
Growth Catalysts
- EU Green Deal infrastructure mandates:Embodied-carbon thresholds in public works procurement are accelerating specification upgrades toward low-carbon and stainless steel fiber variants across Germany, France, and Italy.
- Shotcrete system bundling:Construction chemicals integrators are embedding steel fibers within guaranteed-performance ground-stability packages, expanding addressable project scope in tunneling and mine support.
- China high-speed rail expansion:National rail construction programs are concentrating procurement volumes for macro fiber in tunnel lining and track slab applications under centralized state purchasing.
Market Restraints
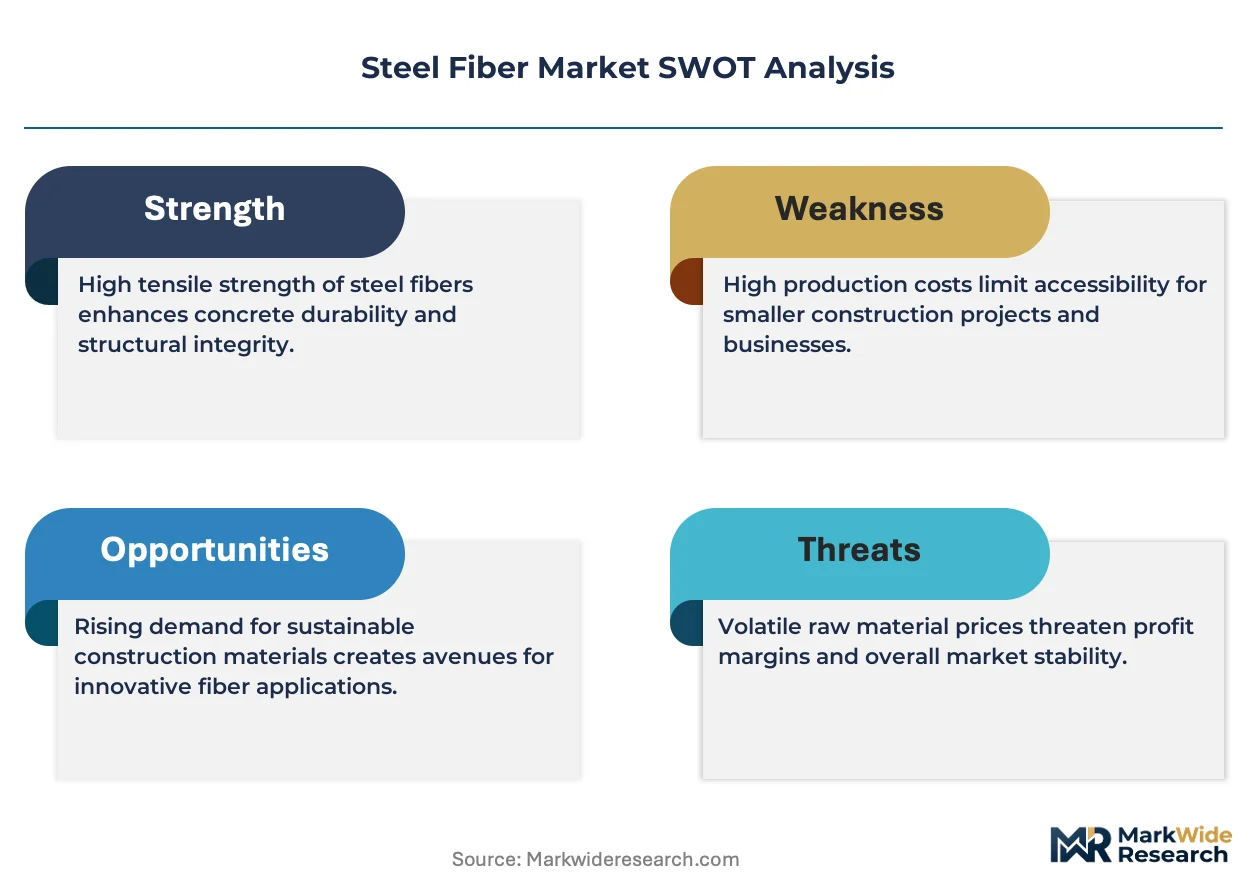
- Scrap steel price volatility:Drawn wire feedstock costs fluctuate with ferrous scrap indices, compressing margin stability for non-integrated producers lacking captive melt capacity.
- Polymer fiber substitution:Synthetic macro fibers are displacing steel in non-structural precast segments where corrosion resistance and weight reduction outweigh tensile performance requirements.
- REACH surface coating compliance:ECHA scrutiny of zinc and epoxy coatings is elevating qualification costs and extending certification timelines for European market entry.
Strategic Opportunities
- India infrastructure build-out:National highway and metro rail programs remain underpenetrated by performance-grade fiber reinforcement, creating first-mover positioning for specification-compliant suppliers.
- 3D-printed construction convergence:Integration of steel fiber dosing systems with robotic concrete deposition is opening application space in automated building fabrication pilots.
- CSRD supply chain disclosure:Corporate sustainability reporting mandates are creating procurement preference for suppliers with verified low-carbon production footprints and transparent embodied-carbon data.
Industry Challenges
- Shotcrete technician certification gaps:Qualified nozzle operators capable of achieving specified fiber distribution uniformity remain scarce across European tunneling contractors, constraining quality assurance.
- EN 14889-1 testing bottlenecks:Notified body capacity for fiber geometry and tensile strength verification is creating 12-18 month approval queues for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel Fiber Market |
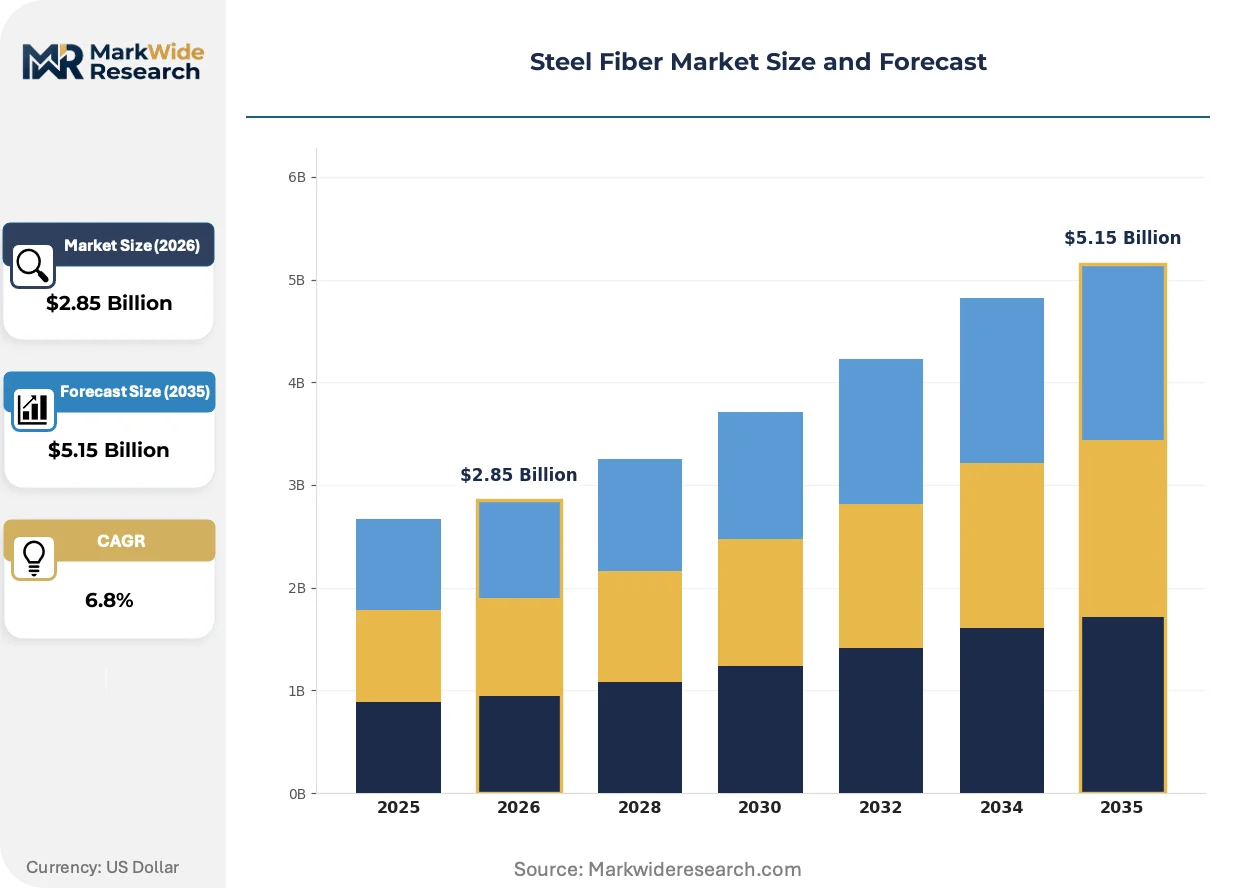
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $5.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Macro Fiber, Micro Fiber, Steel Mesh Fiber, Others Application: Concrete Reinforcement, Asphalt Pavements, Shotcrete, Mine Support End User: Construction, Mining, Infrastructure, Precast Manufacturing Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | Fibrometals, Sika AG, Bekaert, Kosteel, Jiangsu Shagang Group, ArcelorMittal, Green Steel Group, Daye, Nippon Seisen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Fiber Market Strategic Shifts & Innovations
Specification-grade fiber manufacturing is compressing toward tighter diameter tolerances and alloy-specific performance guarantees, while regulatory carbon accounting and automated construction methods are reshaping how reinforcement value is packaged and sold.
Hybrid stainless-carbon fiber blends are miniaturizing diameter specifications below 0.5 mm while maintaining tensile thresholds above 2,000 MPa. Precast manufacturers in Japan and South Korea are adopting these micro-scale variants for ultra-thin architectural panels where surface finish quality governs acceptance. The technology is miniaturizing the boundary between structural and aesthetic reinforcement applications, enabling single-fiber solutions to displace dual-system specifications.
REACH authorization requirements for zinc phosphate surface treatments are forcing coating chemistry migrations toward silane-based and chrome-free alternatives. European tunneling contractors are now demanding coating migration testing under EN 14889-1 Annex D as a standard tender precondition. German and Austrian public works agencies are responding by embedding coating compliance verification within performance-based ground-stability guarantee frameworks.
Performance-based procurement is consolidating specification authority among integrated shotcrete system providers who bundle fiber, accelerator, and application equipment under single-source liability. Traditional fiber distributors in the Benelux and Nordic regions are losing specification influence to construction chemicals majors with in-house nozzle fleets and real-time quality telemetry. This consolidation is most visible in Swiss alpine tunneling projects where ground-stability warranties now exceed 25 years and fiber selection is subordinate to system performance bonds.
Steel Fiber Market Segmentation
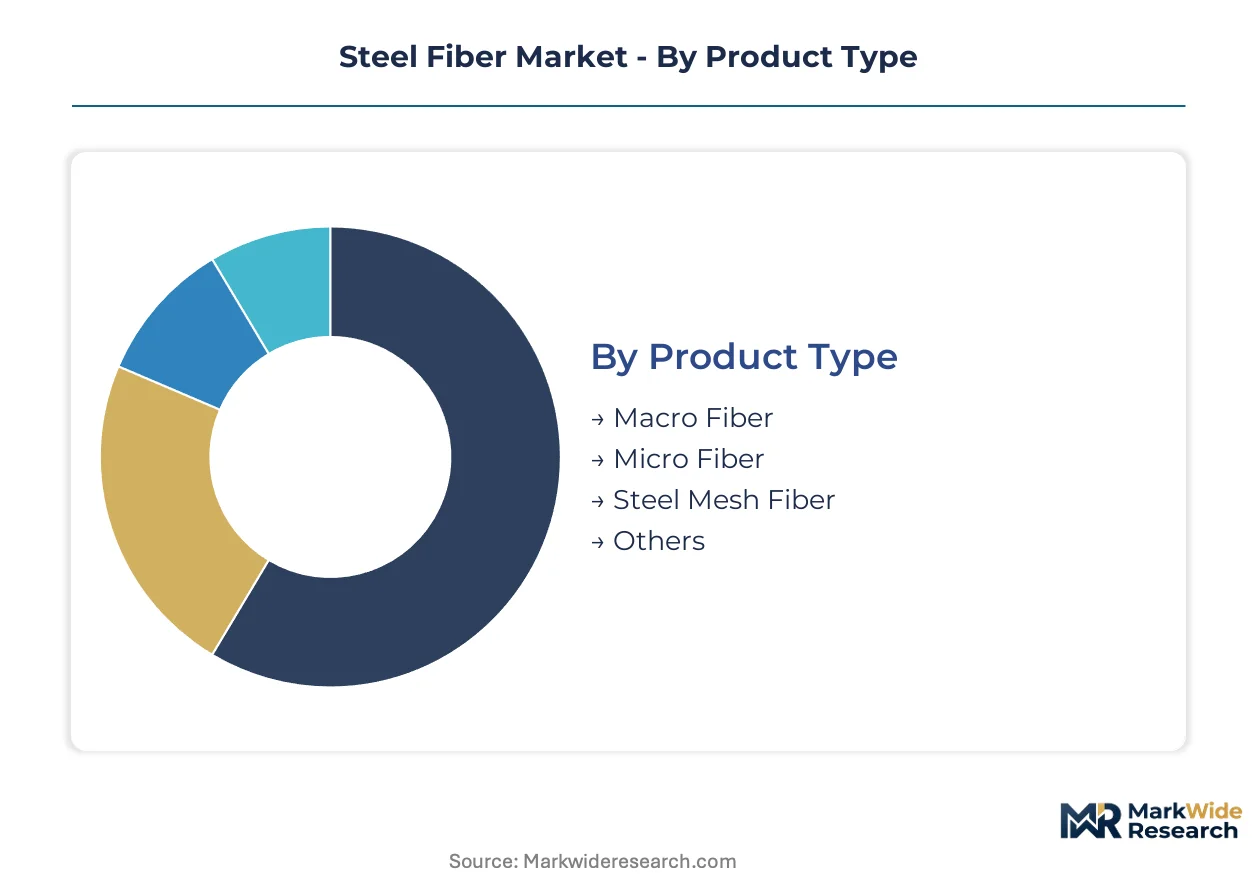
Segmentation in the steel fiber market determines specification authority and margin capture. Product geometry governs structural versus aesthetic applications, while application type dictates whether procurement flows through materials distributors or integrated system providers.
Product Type:
Channel mix varies sharply by fiber scale: macro grades move through construction chemicals integrators bundling shotcrete systems, while micro grades reach precast manufacturers via specialty distributors serving surface-finish optimization needs.
- Macro Fiber:Discrete filaments 0.5–1.0 mm diameter and 25–60 mm length engineered for post-crack tensile capacity in structural concrete. Demand concentrates in China's high-speed rail tunnel linings and European alpine projects where EN 14889-1 compliance is mandatory for public tender eligibility.
- Micro Fiber:Diameter specifications below 0.5 mm targeting plastic-shrinkage control and surface finish quality in cementitious matrices. Japanese and South Korean precast manufacturers are adopting these variants for ultra-thin architectural panels where aesthetic acceptance governs procurement.
- Steel Mesh Fiber:Interconnected filament networks providing three-dimensional reinforcement distribution.
- Others:Hybrid stainless-carbon blends and specialty alloy formulations for corrosion-critical environments.
By volume, macro fiber leads. By growth pace, micro fiber is ahead.
Application:
Cost tier stratification separates performance-guaranteed applications commanding premium pricing from commodity-grade alternatives competing on volume.
- Shotcrete:Wet-mix and dry-mix sprayed concrete applications requiring fiber distribution uniformity under ground-stability warranty frameworks. Swiss alpine tunneling contractors now demand 25-year performance bonds, consolidating procurement authority among integrated system providers with in-house nozzle fleets.
- Concrete Reinforcement:Structural load-bearing applications in building foundations, industrial floors, and bridge decks where crack-arrest specifications govern material selection.
- Mine Support:Underground ground control in hard-rock and soft-ground mining operations where fiber-reinforced shotcrete replaces traditional bolt-and-mesh systems.
- Asphalt Pavements:Thin overlay and full-depth pavement applications seeking fatigue resistance and reflective crack control.
Shotcrete commands the highest margin tier. Asphalt pavements are expanding most quickly as highway agencies specify fiber-modified overlays for rehabilitation.
End User:
Customer type determines specification influence: infrastructure agencies set embodied-carbon thresholds that cascade through contractor procurement, while precast manufacturers prioritize surface-finish consistency for architectural acceptance.
- Infrastructure:Public works agencies in Germany, France, and Italy mandating low-carbon and stainless steel fiber variants under EU Green Deal procurement frameworks.
- Construction:Commercial and residential building contractors selecting fiber reinforcement for industrial flooring and foundation applications.
- Precast Manufacturing:Producers of architectural panels, pipes, and modular elements seeking surface-quality optimization.
- Mining:Underground operators in Australia, Canada, and South Africa specifying fiber-reinforced shotcrete for ground support.
Infrastructure drives specification-grade volume. Precast manufacturing is climbing the fastest as thin-panel architectural demand expands.
Distribution Channel:
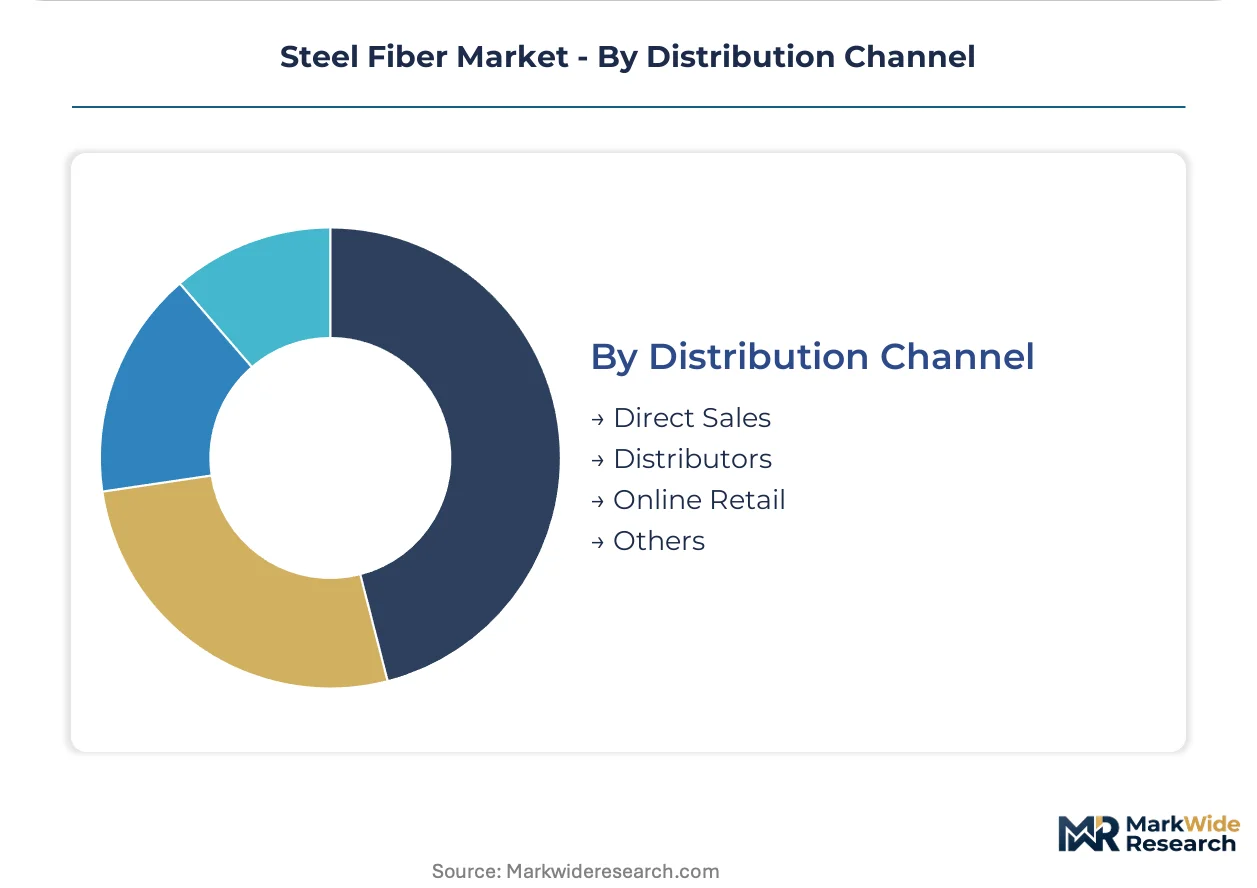
Supply concentration favors direct relationships in high-volume infrastructure, while fragmented project-scale demand flows through regional distributors.
- Direct Sales:Long-term supply agreements between fiber producers and construction chemicals majors, tunneling contractors, and national rail construction programs.
- Distributors:Regional specialty distributors serving mid-scale precast manufacturers and commercial construction contractors.
- Online Retail:Digital procurement platforms for small-volume project orders and aftermarket replacement.
- Others:Equipment-integrated supply through shotcrete machine OEMs and rental fleets.
Direct sales capture the largest contract value. Online retail is gaining share fastest among small contractors and maintenance operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics reveal concentrated supply origins against dispersed demand nodes. China and Belgium dominate outbound steel fiber shipments while import dependency shapes procurement strategies across infrastructure-deficit economies.
China
State rail construction programs concentrate macro fiber procurement through centralized purchasing bureaus. GB/T 39147 testing protocols govern domestic quality verification for tunnel lining applications. Yangtze River Delta manufacturers supply high-speed rail projects linking Shanghai to inland provinces.
Germany
Alpine tunneling contractors specify EN 14889-1 compliant fibers under 25-year ground-stability warranty frameworks. EU Green Deal embodied-carbon thresholds accelerate low-carbon variant adoption in public works. Bavarian construction chemicals integrators bundle fiber dosing with real-time quality telemetry.
United States
Federal highway rehabilitation programs specify fiber-modified asphalt overlays for fatigue resistance. ASTM A820 material standards govern specification compliance across state transportation departments. Texas and California DOTs lead procurement volume for bridge deck and pavement applications.
India
National highway and metro rail build-outs remain underpenetrated by performance-grade reinforcement. BIS certification requirements create qualification barriers for imported fiber suppliers. Maharashtra and Gujarat infrastructure agencies pilot specification-compliant shotcrete in Mumbai-Ahmedabad corridor projects.
Switzerland
Alpine base tunnel programs demand coating migration testing under EN 14889-1 Annex D as tender precondition. Swissmedic-equivalent construction product regulators enforce extended performance bond frameworks. Gotthard and Brenner corridor contractors consolidate procurement authority among integrated system providers.
Steel Fiber Market Key Industry Players
Listed leaders compete with private specialists across capital access and operational agility dimensions. The vendor base organizes around three strategic archetypes: construction chemicals majors bundling fiber within shotcrete systems, integrated steel producers leveraging captive wire feedstock, and specialty distributors serving precast surface-finish optimization. Dominant competitive moves include backward integration into wire drawing capacity and geographic expansion through construction chemicals distribution networks.
Within the integrated steel producer tier, ArcelorMittal and Bekaert exemplify archetypes leveraging upstream metal control. Sika AG occupies a position among construction chemicals majors embedding fiber within guaranteed-performance ground-stability packages. Jiangsu Shagang Group represents scale-driven Chinese supply concentration serving state rail construction programs.
| Leading Market Players |
|---|
| Fibrometals |
| Sika AG |
| Bekaert |
| Kosteel |
| Jiangsu Shagang Group |
| ArcelorMittal |
| Green Steel Group |
| Daye |
| Nippon Seisen |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between European tunneling contractors and integrated steel producers lock in both fiber supply access and price visibility across multi-year infrastructure programs. These contracts insulate procurement teams from ferrous scrap volatility while embedding EN 14889-1 certification costs into fixed unit pricing.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Specification-grade macro fiber commands premiums tied to tensile strength verification and REACH-compliant surface coatings, while commodity grades compete on volume scale. Cost compression in standard tiers is intensifying because polymer fiber substitution pressures non-structural applications. Precast manufacturers show highest price sensitivity; integrated shotcrete system providers demonstrate least sensitivity due to performance-bond pass-through.
Supply Chain Analysis
Inventory buffers at Belgian wire-drawing facilities and Yangtze River Delta melt shops extend lead times for EN 14889-1 certified product. Supply concentrates in China, Belgium, and Germany. Drawn carbon steel wire and stainless steel feedstock form critical input dependencies. Single-source vulnerability around zinc phosphate coating chemistry creates exposure to REACH authorization delays. Distribution runs through construction chemicals integrators bundling fiber with accelerator and telemetry equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment protects specification authority. EN 14889-1 certification requirements and 12-18 month notified body queues create switching costs that cement incumbent positions.
For Market Incumbents: Compound specification influence by embedding fiber within guaranteed-performance shotcrete system bundles. Backward integration into low-carbon wire drawing secures EU Green Deal eligibility against emerging low-carbon entrants. Invest in real-time quality telemetry to extend 25-year ground-stability warranty frameworks. For New Entrants and Emerging Players: Differentiate on embodied-carbon transparency to capture CSRD-driven procurement preference. Target India's underpenetrated highway and metro rail programs where BIS certification barriers filter out commodity competitors. Pursue joint venture structures with established construction chemicals distributors to bypass direct specification authority gaps. For Investors and Strategic Acquirers: Construction chemicals specialists with captive nozzle fleets and telemetry platforms represent the most defensible acquisition profile. Long-term viability hinges on consolidation of performance-based procurement authority among integrated system providers. Watch for ECHA coating authorization decisions as inflection indicator for chemistry migration costs and competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wire Drawing | Captive low-carbon feedstock secures EU Green Deal tender eligibility against scrap-dependent competitors. |
| Shotcrete System Bundling | Construction chemicals majors consolidate specification authority through guaranteed-performance ground-stability packages. |
| REACH-Compliant Coating Migration | Silane-based chemistry investments preempt ECHA authorization delays that strand zinc phosphate inventories. |
| Real-Time Quality Telemetry Deployment | Alpine tunneling contractors demand fiber distribution verification under 25-year performance bond frameworks. |
| India Market Entry via BIS Partnership | Maharashtra and Gujarat infrastructure pilots create first-mover positioning in specification-compliant shotcrete. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interview programs. Tunneling contractors, shotcrete nozzle operators, construction chemicals procurement leads, and precast manufacturing engineers provided operational perspective. Secondary validation drew from EN 14889-1 notified body filings, ECHA REACH authorization databases, EU public tender documentation, and customs trade data. Bottom-up fiber volume estimates triangulated against top-down infrastructure spending projections.
Across the analysis window, forecasts segment by product geometry, application type, and end-user procurement authority. Modeled dimensions include macro versus micro fiber specifications, shotcrete versus concrete reinforcement deployment, and infrastructure agency versus precast manufacturer demand. CAGRs derive from project pipeline analysis and specification-grade premium trajectories. Scrap steel price indices and embodied-carbon threshold evolution serve as key forecast inputs.
Material uncertainties — ferrous scrap volatility, ECHA coating authorization timelines, and polymer fiber substitution rates — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and infrastructure program continuity. Revision becomes warranted when EU Green Deal procurement thresholds accelerate faster than low-carbon production capacity expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Forgings Market
Advanced Alloys
Titanium Alloys Market
Advanced Alloys
Global Metal Injection Molding Market
Advanced Alloys
Global Metal Foams Market
Advanced Alloys
High Strength Steel (HSS) Market
Advanced Alloys
Polyphenylene Ether (PPE) Alloy Market
Advanced Alloys
Global Stainless Steel Forgings Market
Advanced Alloys
India Shape Memory Alloy Market
Advanced Alloys
Titanium Aluminide Market
Advanced Alloys
Molybdenum Disilicide Market
Advanced Alloys
Nickel Alloy Market
Advanced Alloys
Cermet Market
Advanced Alloys
Global Ti-6Al-4V Titanium Alloy Market
Advanced Alloys
Nickel Superalloy Market
Advanced Alloys
Soft Magnetic Material for Electric Vehicle Market
Advanced Alloys
Global Shape Memory Materials Market