
 Global Ti-6Al-4V Titanium Alloy Market | 2026-2036
Global Ti-6Al-4V Titanium Alloy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ti-6Al-4V Titanium Alloy Market Foresight
Market Context
The capital-intensity divergence between integrated primary producers and specialized downstream processors is reorganizing competitive tiers in Ti-6Al-4V supply. thyssenkrupp AG leverages captive titanium sponge capacity and vacuum arc remelting infrastructure to dominate European aerospace qualification. Allegheny Technologies Inc. sustains long-term contracts with Pratt & Whitney and GE Aerospace through its Monroe, North Carolina superalloy complex. Baoji Titanium Industry Co. Ltd anchors Chinese domestic supply for military aviation and civil airframe programs.
Technical Definition and Segment Structure
Ti-6Al-4V titanium alloy is an alpha-beta titanium alloy containing 6% aluminum and 4% vanadium by weight, offering tensile strength exceeding 900 MPa with density roughly 45% below steel, produced primarily through vacuum arc remelting or electron beam melting for critical structural applications. Aerospace Components command the largest value share as OEMs specify Ti-6Al-4V for landing gear, fan discs, and wing fittings under AMS 4928 and AMS 4967 standards. Powder Metallurgy represents the fastest-expanding technology segment as additive manufacturing qualification expands beyond prototyping into flight-critical hardware production.
Regulatory Framework and Outlook
FAA airworthiness directives and EASA certification specifications govern Ti-6Al-4V incorporation into commercial aircraft structures, while FDA 21 CFR Part 820 and ISO 5832-3 regulate biomedical implant-grade material traceability. ASTM F2924 and AMS 7000 establish powder chemistry and morphology standards that determine market access for additive manufacturing feedstock suppliers. Stakeholders must monitor evolving qualification pathways for electron beam melted and hot isostatically pressed components as regulatory bodies harmonize additive-specific standards with legacy wrought and cast specifications.
Market Dynamics
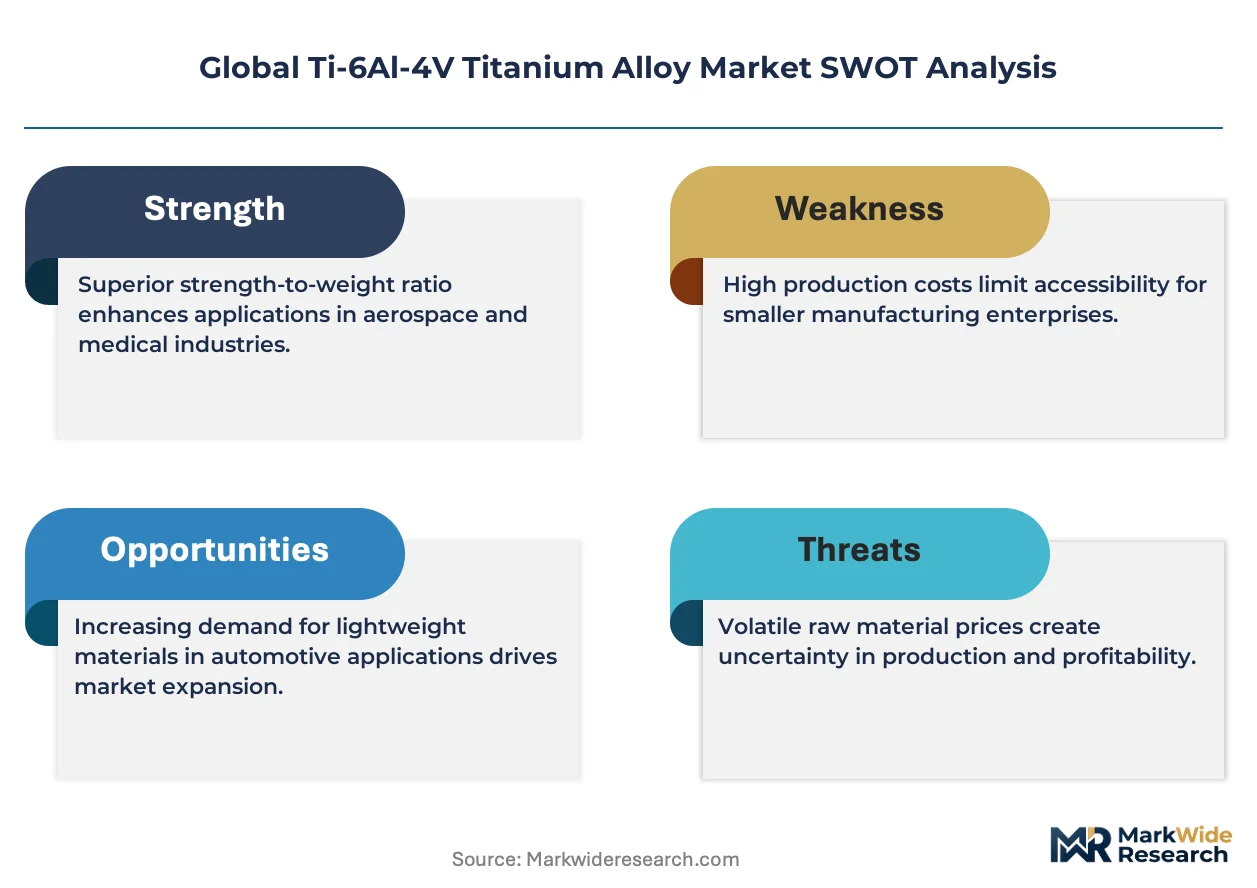
Qualification bottlenecks for additive manufacturing feedstock are compressing the supply base for flight-critical Ti-6Al-4V components, forcing processors to consolidate certification assets around electron beam melting and hot isostatic pressing infrastructure.
Growth Catalysts
- AMS 7000 Powder Specification:FAA and EASA alignment on additive feedstock standards is accelerating qualification timelines for aerospace suppliers seeking to produce flight-critical hardware through laser powder bed fusion.
- Defense Procurement Surge:Military aviation programs in the United States and China are expanding long-term offtake agreements for Ti-6Al-4V forgings used in fighter airframes and rotorcraft transmission housings.
- Sponge-to-Alloy Integration:Captive vacuum distillation capacity at primary titanium producers is tightening metallurgical control over interstitial oxygen content, reducing downstream remelting cycles.
Market Restraints
- Rutile Feedstock Concentration:Over 60% of chloride-grade titanium feedstock concentrates in Australian and South African mining operations, exposing alloy producers to concentrate supply disruptions.
- Triple Melt Requirement:Aerospace OEM specifications mandating vacuum arc remelting followed by two additional VAR or electroslag remelting cycles add 40-50% to energy costs versus single-melt commodity grades.
- Carbon Fiber Substitution:Wing and empennage applications below 120°C service temperature face displacement from thermoplastic composite laminates qualified under Boeing and Airbus material specifications.
Strategic Opportunities
- Indian Defense Indigenization:India's PLI scheme for aerospace components and offset obligations under Rafale and C-295 programs are creating captive demand for domestic Ti-6Al-4V forging capacity.
- Biomedical Implant Grade Expansion:ISO 5832-3 compliant material for spinal cages and hip stems represents an underpenetrated outlet for vacuum arc remelters with existing FDA master files.
- Hybrid Manufacturing Convergence:Near-net-shape plasma deposition combined with five-axis CNC finishing is opening geometrically complex landing gear brackets previously machined from solid billet.
Industry Challenges
- EBM Operator Certification Scarcity:Qualified technicians capable of parameter development for electron beam melting of Ti-6Al-4V command 40% wage premiums over conventional powder metallurgists.
- Dual-Certification Timeline Compression:Simaneous pursuit of NADCAP heat treatment and AS9100D quality system accreditation extends qualification cycles for new market entrants.
- Sponge Alloy Grade Mismatch:Technical-grade titanium sponge oversupply from Chinese chlorinator expansions cannot substitute for aerospace-qualified sponge with controlled nitrogen and hydrogen levels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ti-6Al-4V Titanium Alloy Market |
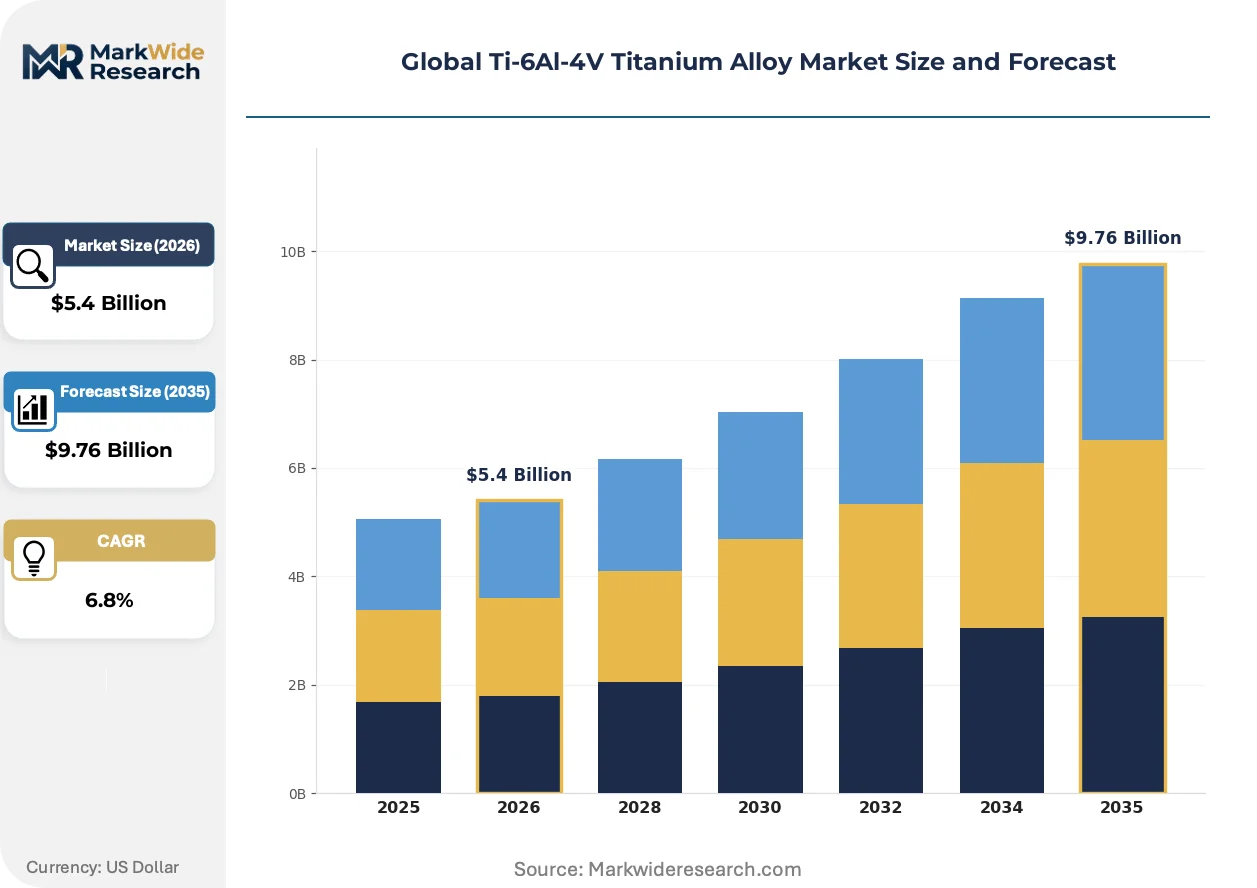
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $9.76 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bar, Sheet, Forging, Wire, Powder Application: Aerospace Components, Biomedical Implants, Marine Equipment, Sports Gear End User: OEM Manufacturers, Medical Device Makers, Marine Fabricators, Sports Equipment Producers Technology: Vacuum Arc Remelting, Powder Metallurgy, Electron Beam Melting, Hot Isostatic Pressing |
| Companies Covered | thyssenkrupp AG, AMETEK Inc., Allegheny Technologies Inc., Heraeus Holding GmbH, Sandvik AB, Baoji Titanium Industry Co. Ltd, Haynes International Inc, Hebei Metals Industrial Ltd., Carpenter Technology Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ti-6Al-4V Titanium Alloy Market Shifts & Advancements
Electron beam powder bed fusion and plasma cold hearth melting are redrawing the boundary between wrought and cast Ti-6Al-4V supply chains, compressing lead times for complex aerospace geometries while introducing new metallurgical variability risks.
Plasma rotating electrode process powder production is fragmenting the historical dominance of gas atomization for additive manufacturing feedstock. Defense contractors in the United States are qualifying PREP powder for critical rotating components, attracted by spherical morphology and reduced satellite particle contamination. The resulting supply bifurcation is creating distinct pricing tiers between plasma-derived and gas-atomized powder specifications.
EASA's evolving certification memorandum on additive manufacturing of metallic parts is forcing European Tier 1 suppliers to duplicate qualification dossiers across national competent authorities. The regulatory fragmentation is delaying production part approval for Ti-6Al-4V hip implants and turbine blades, compressing commercialization timelines for certified additive hardware. German and French notified bodies are responding with pilot harmonization programs.
Buy-side consolidation among aerospace OEMs is compressing supplier negotiation cycles from annual to quarterly cadences, with Boeing and Airbus extracting indexed raw material pass-through clauses. Tier 2 forgers are responding by pre-positioning sponge inventory and hedging vanadium ferroalloy positions through London Metal Exchange-linked contracts. The procurement compression is most acute in North American landing gear and engine disc supply chains.
Global Ti-6Al-4V Titanium Alloy Market Segmentation
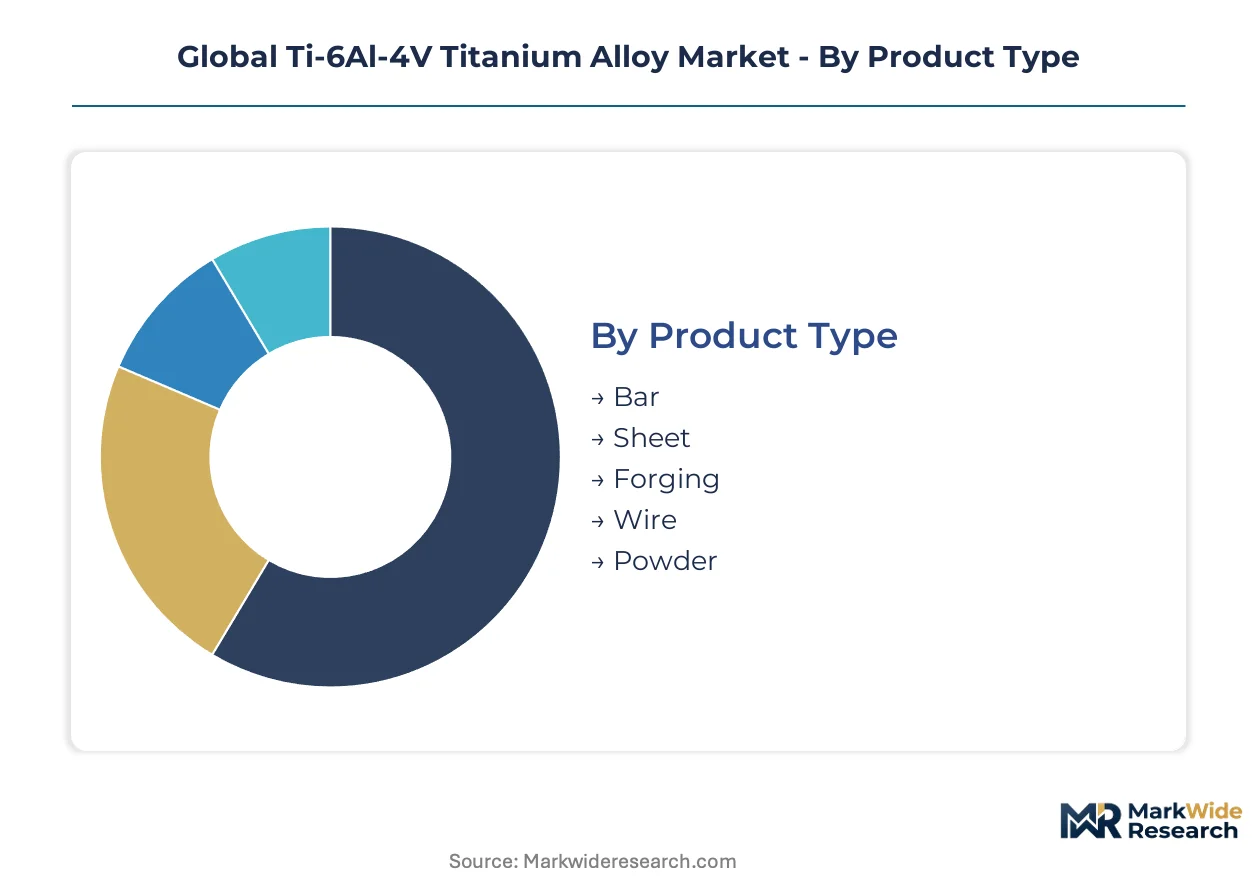
Ti-6Al-4V procurement patterns diverge sharply across form factors and processing routes, with aerospace qualification requirements dictating margin structures that commodity grades cannot access. Segmentation reveals where captive sponge-to-alloy integration commands pricing power versus standardized merchant supply.
Product Type:
Margin pools concentrate in precision-forged and powder forms where aerospace OEM specifications restrict qualified supplier bases.
- Bar:Mill products meeting AMS 4928 dominate structural airframe procurement, with Boeing and Airbus long-term agreements anchoring demand in the United States and Germany. Triple-melt vacuum arc remelting requirements limit the supplier base to integrated primary producers.
- Forging:Closed-die and isothermal pressings for landing gear and fan discs capture the highest value-add per kilogram, with Pratt & Whitney and GE Aerospace driving qualification timelines. The segment concentrates in North Carolina and Baoji manufacturing clusters.
- Sheet:Cold-rolled and hot-rolled plate serves wing skin and firewall applications under AMS 4911, with gauge thickness determining thermal processing complexity.
- Wire:Drawn products for fasteners and springs operate at lower specification tiers, with medical-grade wire representing a premium niche under ASTM F136.
- Powder:Gas-atomized and plasma-rotating electrode process feedstock serves additive manufacturing qualification under ASTM F2924, with spherical morphology specifications fragmenting supply tiers.
The dominant share belongs to Bar, while Powder is closing the gap fastest.
Application:
End-use specifications determine metallurgical control intensity, with flight-critical applications imposing interstitial element limits that biomedical and marine grades relax.
- Aerospace Components:Landing gear, engine discs, and wing fittings under AMS 4928 and AMS 4967 specifications absorb the majority of premium-grade sponge capacity. FAA and EASA airworthiness directives govern every heat of material.
- Biomedical Implants:Spinal cages, hip stems, and dental fixtures under ISO 5832-3 and FDA 21 CFR Part 820 require enhanced surface finish and traceability protocols, with ASTM F136 extra-low interstitial grade commanding sustained premiums.
- Marine Equipment:Propeller shafts and desalination pressure vessels exploit corrosion resistance without the oxygen control rigor of aerospace grades, with classification society rules substituting for aviation authority oversight.
- Sports Gear:Bicycle frames and golf club heads utilize commodity-grade Ti-6Al-4V where cosmetic finish outweighs mechanical property certification, with Asian contract manufacturers driving volume.
Aerospace Components retains volume leadership, though Biomedical Implants delivers the steadiest margin expansion trajectory.
End User:
Customer procurement sophistication separates long-term qualification partnerships from spot-market transactions.
- OEM Manufacturers:Boeing, Airbus, and defense primes negotiate indexed raw material pass-through clauses with quarterly cadence, squeezing Tier 2 forger margins.
- Medical Device Makers:Stryker, Zimmer Biomet, and DePuy Synthes maintain FDA master file systems that lock in qualified vacuum arc remelters for multi-year supply agreements.
- Marine Fabricators:Shipyards and offshore equipment builders source through distributors with less stringent heat certification requirements than aviation or medical channels.
- Sports Equipment Producers:Brand owners in Taiwan and China specify cosmetic-grade titanium with minimal metallurgical documentation, purchasing through commodity traders.
OEM Manufacturers command the largest procurement volumes, while Medical Device Makers are consolidating supplier relationships fastest.
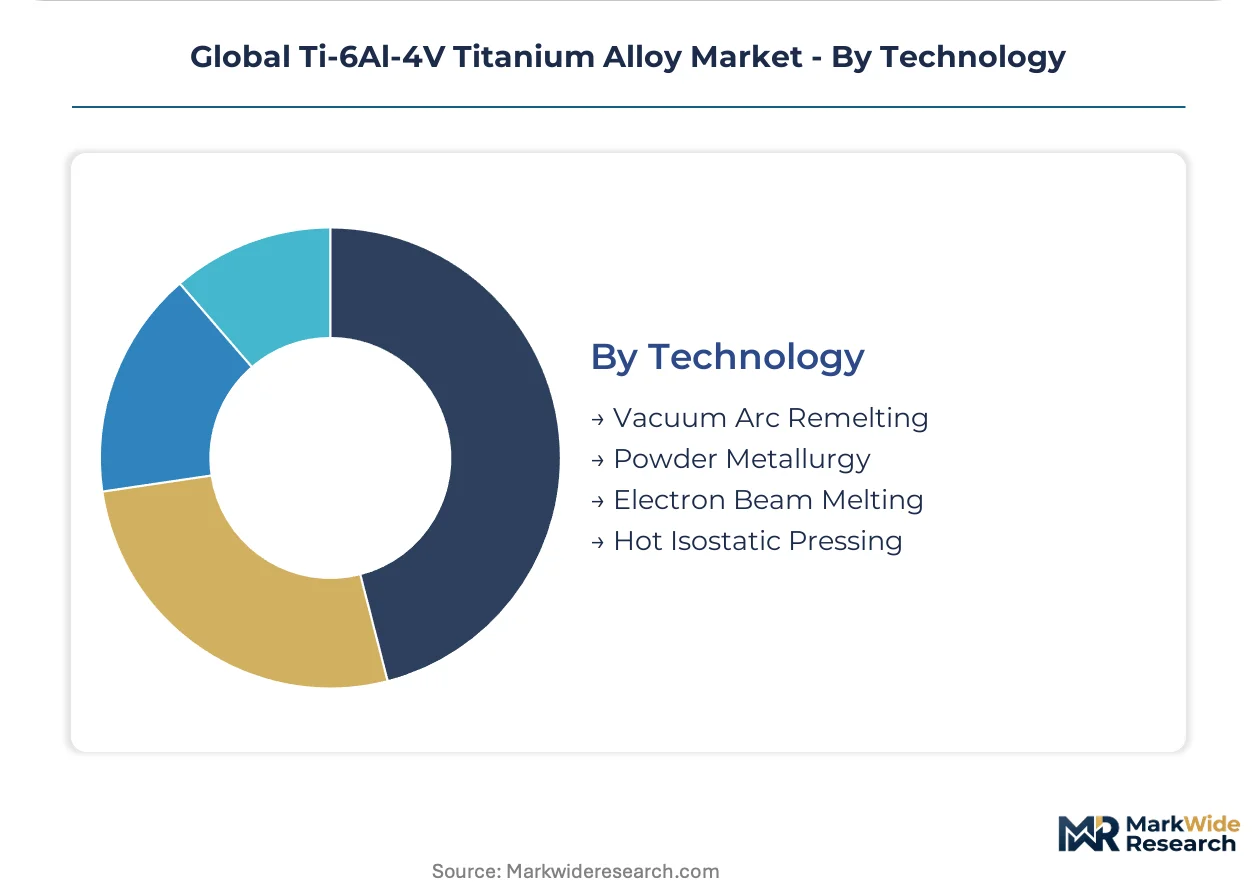
Technology:
Processing route selection dictates capital intensity and qualification timeline length, with additive methods disrupting traditional wrought supply chains.
- Vacuum Arc Remelting:The foundational triple-melt process for aerospace billet and forging stock, with VAR infrastructure concentrated at primary producers in Germany, the United States, and China.
- Electron Beam Melting:Powder bed fusion for near-net-shape aerospace brackets is gaining flight-critical approval under evolving EASA certification memoranda, though parameter development scarcity constrains capacity expansion.
- Powder Metallurgy:Hot isostatic pressing of pre-alloyed powder enables complex geometries impossible through conventional forging, with defense contractors qualifying PREP powder for rotating components.
- Hot Isostatic Pressing:Densification and healing of cast or additive microstructures, with HIP-plus-heat-treat workflows becoming standard for premium aerospace and medical applications.
Vacuum Arc Remelting holds installed capacity dominance, while Electron Beam Melting is expanding most quickly as FAA-EASA alignment on additive standards accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies, with aerospace OEMs in the United States and Germany driving premium-grade procurement while Chinese demand tilts toward defense indigenization and civil airframe expansion. Military aviation programs and commercial fleet renewal cycles create distinct metallurgical requirements in each concentration zone.
United States
Defense procurement surges from Pratt & Whitney and GE Aerospace anchor demand for triple-melt VAR forgings under FAA airworthiness directives. The Monroe superalloy complex in North Carolina concentrates landing gear and engine disc production. Boeing's indexed raw material pass-through clauses compress Tier 2 forger margins through quarterly negotiation cycles.
Germany
thyssenkrupp's captive titanium sponge capacity and vacuum arc remelting infrastructure dominate European aerospace qualification under EASA certification specifications. The Ruhr industrial cluster houses integrated primary production serving Airbus long-term agreements. German notified bodies pilot harmonization programs with French counterparts to streamline additive manufacturing approvals.
China
Baoji Titanium Industry anchors domestic supply for military aviation and civil airframe programs under MIIT industrial policy guidance. Technical-grade sponge oversupply from chlorinator expansions cannot substitute aerospace-qualified material with controlled nitrogen levels. The Shaanxi manufacturing cluster concentrates vacuum distillation and electron beam melting capacity for defense contractors.
India
PLI scheme incentives for aerospace components and Rafale offset obligations create captive demand for domestic Ti-6Al-4V forging capacity under CDSCO traceability protocols. Hyderabad and Bangalore clusters attract vacuum arc remelters seeking qualification for fighter airframe and rotorcraft transmission programs. BIS standards for titanium alloys remain under development, extending OEM approval timelines.
Japan
METI industrial coordination supports precision forging capabilities for rotating components in regional jet engines. Osaka-based processors supply medical-grade wire under PMDA pharmaceutical regulation alignment with ISO 5832-3. The Kansai cluster specializes in ASTM F136 extra-low interstitial material for spinal cage and hip stem applications.
Global Ti-6Al-4V Titanium Alloy Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with sponge-to-alloy captives commanding aerospace qualification premiums while merchant processors compete on spot-market responsiveness. German and Chinese integrated producers leverage backward titanium sponge control, whereas North American and European specialists concentrate on NADCAP-accredited heat treatment and forging. Two dominant competitive moves define current positioning: consolidation of certification assets around electron beam melting infrastructure, and pre-positioning of vanadium ferroalloy inventory through London Metal Exchange-linked hedging.
Among integrated primary producers, thyssenkrupp AG exemplifies the captive sponge-to-alloy archetype through its European vacuum arc remelting dominance. Allegheny Technologies Inc. and Baoji Titanium Industry Co. Ltd occupy positions within the aerospace-forging specialist tier, with the former representing North American long-term contract anchoring and the latter embodying Chinese defense-indigenization supply security. These three names illustrate the geographic and structural segmentation that governs competitive access to premium qualification pathways.
| Leading Market Players |
|---|
| thyssenkrupp AG |
| AMETEK Inc. |
| Allegheny Technologies Inc. |
| Heraeus Holding GmbH |
| Sandvik AB |
| Baoji Titanium Industry Co. Ltd |
| Haynes International Inc |
| Hebei Metals Industrial Ltd. |
| Carpenter Technology Corporation |
| Others |
Supply & Pricing Matrix
Ninety-day sponge inventory pre-positioning by Tier 2 forgers compresses working capital cycles while amplifying exposure to Australian rutile concentrate volatility, binding pricing power to backward integration into titanium sponge distillation capacity across Germany, China, and the United States.
Pricing Analysis
Long-term offtake agreements dominate aerospace procurement, with Boeing and Airbus extracting indexed raw material pass-through clauses that reset quarterly against London Metal Exchange vanadium ferroalloy benchmarks. Price differentiation hinges on triple-melt certification grade and NADCAP heat treatment accreditation, with flight-critical forgings commanding premiums over commodity bar stock. Cost compression in standard-grade mill products intensifies as Chinese technical-grade sponge oversupply saturates merchant markets. Spot-market buyers in marine and sports equipment segments exhibit highest price sensitivity, while medical device makers under FDA master file systems accept sustained premiums for ASTM F136 extra-low interstitial material.
Supply Chain Analysis
Strategic stockpiling of aerospace-qualified sponge prevails over just-in-time approaches, with integrated primary producers in Germany, the United States, and China maintaining six-month coverage against Australian and South African rutile concentrate disruptions. The supply chain draws from chloride-grade titanium feedstock, vanadium ferroalloy, and argon gas for remelting atmospheres. Single-source vulnerability concentrates in Australian mining operations supplying over sixty percent of rutile concentrate. Distribution runs through NADCAP-accredited forgers serving OEM direct contracts, with merchant distributors handling lower-specification marine and industrial offtake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in electron beam melting parameter development and additive manufacturing qualification consulting are expanding faster than hardware margins, as defense contractors and Tier 1 suppliers outsource certification dossier preparation and technician training programs.
For Market Incumbents: Shield qualified supplier status by consolidating NADCAP heat treatment and AS9100D accreditation assets around electron beam melting infrastructure, while deepening captive sponge distillation capacity to offset vanadium ferroalloy price volatility through London Metal Exchange-linked hedging programs. For New Entrants and Emerging Players: Anchor in Indian defense indigenization programs under PLI scheme incentives, targeting domestic forging capacity for Rafale and C-295 offset obligations with CDSCO traceability protocols as the regulatory entry pathway, while building qualification partnerships with Hyderabad and Bangalore aerospace clusters. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across additive manufacturing feedstock production as plasma rotating electrode process powder qualification fragments the gas atomization supply base, with five-to-ten year viability favoring processors with dual PREP and gas-atomization capability; the signal to watch is EASA certification memoranda harmonization progress with French and German notified bodies.| Strategic Initiative | Industry Significance |
|---|---|
| Triple-Melt VAR Capacity Expansion | Captive vacuum arc remelting infrastructure secures AMS 4928 qualification for Boeing and Airbus long-term agreements. |
| PREP Powder Qualification | Plasma rotating electrode process certification under ASTM F2924 opens defense contractor rotating component supply. |
| Indian Forging Joint Venture | Domestic Ti-6Al-4V capacity under PLI scheme meets Rafale offset obligations with CDSCO traceability. |
| EBM Parameter Development Licensing | Proprietary electron beam melting build recipes command 40% wage premiums in technician-scarce labor markets. |
| Vanadium Ferroalloy Hedging Program | London Metal Exchange-linked contracts stabilize input costs against quarterly OEM price renegotiation cycles. |
Research Methodology
A standing panel of vacuum arc remelting plant managers, aerospace OEM procurement directors, NADCAP heat treatment auditors, and additive manufacturing qualification engineers provided ongoing calibration across the analysis window. Primary interview insights combined with secondary validation from FAA airworthiness directive filings, EASA certification memoranda, ASTM and AMS specification databases, and SEC 10-K disclosures from publicly traded titanium processors. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators.
Consistency checks validated volume and value outputs against external benchmarks including customs trade data for titanium sponge and mill product flows, IEA industrial materials demand projections, and hospital procurement database trends for biomedical implant-grade material. The analytical framework modeled product type, application, end user, and technology dimensions across the projection horizon, with CAGRs derived from elasticity-adjusted demand curves incorporating defense procurement cycle phasing and commercial fleet renewal timelines.
Decision-makers should treat outputs as directional under assumptions of sustained FAA-EASA regulatory harmonization and stable Australian rutile concentrate supply; material deviation in additive manufacturing certification timelines or Chinese aerospace-qualified sponge availability would warrant model refresh. Revision becomes warranted when EASA additive manufacturing memoranda adoption crosses threshold implementation across German and French notified bodies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Master Alloys Market
Advanced Alloys
Super Alloys Market
Advanced Alloys
Welding Alloys Market
Advanced Alloys
Molybdenum Disilicide Market
Advanced Alloys
Thulium Silicide Market
Advanced Alloys
Global Noble Ferroalloys Market
Advanced Alloys
Automotive Aluminum Alloy (OE) Market
Advanced Alloys
Global Corrosion Resistant Alloys Market
Advanced Alloys
High Strength Steel (HSS) Market
Advanced Alloys
Metal Replacement Market
Advanced Alloys
India Shape Memory Alloy Market
Advanced Alloys
Quartz Kitchen Countertops Market
Advanced Alloys
Chromium Carbide Market
Advanced Alloys
Europe Ceramic Ball Bearings Market
Advanced Alloys
Europe Green Steel Market
Advanced Alloys
Cermet Market