
 Fiber Reinforced Composite Tapes Market | 2026-2036
Fiber Reinforced Composite Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Reinforced Composite Tapes Market Analytics
Automated fiber placement is fragmenting legacy hand-layup workflows across aerospace and automotive manufacturing. Toray Industries leverages its carbon fiber precursor verticality to dominate prepreg tape supply chains for commercial aviation. Hexcel Corporation anchors North American defense and space programs through qualified material specifications. SGL Carbon specializes in automotive-grade thermoplastic tapes, competing on cycle-time reduction against thermoset alternatives.
Fiber reinforced composite tapes are unidirectional or multi-axial fiber bundles pre-impregnated with thermoset or thermoplastic resin matrices, typically supplied in slit-tape formats with areal weights between 100-300 gsm for automated deposition processes. Their primary purpose is to deliver engineered stiffness-to-weight ratios in primary structural members where metals fail fatigue or corrosion limits. Carbon fiber material commands the dominant margin pool across aerospace structural reinforcement applications, while glass fiber occupies cost-sensitive automotive bonding and industrial insulation segments. Kevlar product types retain niche demand in marine surface protection where impact resistance outweighs modulus requirements.
FAA airworthiness standards and EASA certification specifications govern material qualification timelines for structural reinforcement tapes in commercial aviation, extending development cycles but creating barrier-to-entry advantages for incumbent suppliers. EPA hazardous air pollutant rules and REACH substance restrictions constrain resin chemistry choices, pushing formulation shifts toward lower-VOC thermoplastic systems. Stakeholders must monitor how NHTSA crashworthiness protocols and OEM lightweighting mandates reshape automotive tape specifications before committing capacity expansion decisions.
Market Dynamics
Automated fiber placement systems are compressing manufacturing cycle times and forcing tape suppliers to synchronize slit-tape specifications with deposition head geometries, locking in material-process co-development partnerships.
Growth Catalysts
- FAA airworthiness directives:Certification requirements for primary structural members in next-generation narrowbody programs are mandating qualified tape supply chains, extending incumbent supplier relationships.
- Thermoplastic resin chemistry:Out-of-autoclave processing is eliminating autoclave bottlenecks and enabling in-situ consolidation for automotive structural components.
- Stuttgart-Munich corridor:Germany's automotive supplier ecosystem is concentrating demand for glass fiber thermoplastic tapes in battery enclosure and floor pan applications.
Market Restraints
- Acrylonitrile price volatility:Carbon fiber precursor costs fluctuate with petrochemical feedstock indices, compressing margin predictability for tape converters.
- Single-source prepreg qualification:Aerospace OEMs lock specifications to qualified suppliers, creating switching costs that fragment procurement leverage.
- Thermoset cure cycle rigidity:Epoxy-based systems require controlled-temperature staging, limiting throughput scalability versus thermoplastic alternatives.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for advanced materials are attracting tape slitting and prepreg operations to serve domestic aerospace and defense programs.
- Hydrogen pressure vessel winding:Type IV composite tanks for fuel cell vehicles are creating demand for high-strength carbon fiber tape in filament winding formats.
- Digital thread integration:Automated fiber placement machines coupled with in-process inspection are virtualizing quality documentation and compressing certification timelines.
Industry Challenges
- Automated fiber placement technician scarcity:Machine programming and deposition path optimization require specialized training pipelines that lag equipment deployment.
- Multi-site qualification burden:Aerospace material specifications require duplicate testing across manufacturing locations, extending capacity expansion timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Reinforced Composite Tapes Market |
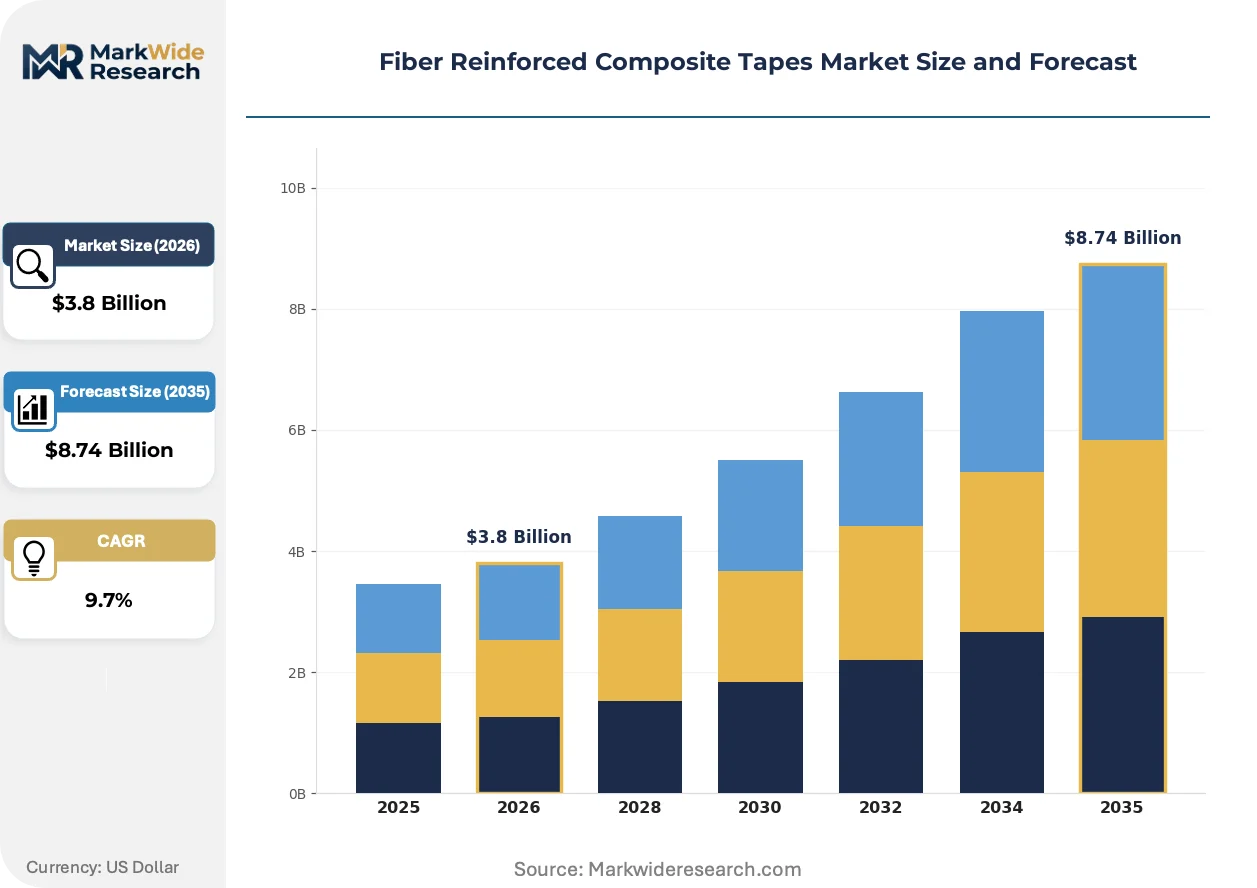
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Nylon, Polypropylene, Kevlar End User: Aerospace, Automotive, Marine, Industrial Application: Structural Reinforcement, Insulation, Surface Protection, Bonding Material: Glass Fiber, Carbon Fiber, Aramid Fiber, Others |
| Companies Covered | Toray Industries, Hexcel Corporation, SGL Carbon, Teijin Limited, Solvay, SABIC, Mitsubishi Chemical Group Corporation, BASF, Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Reinforced Composite Tapes Market Evolving Landscape
Digital manufacturing architectures are rewiring how tape specifications propagate from design systems to deposition equipment, collapsing traditional handoff friction between engineering and production.
Thermoplastic unidirectional tape systems are virtualizing legacy thermoset workflows in aerospace secondary structures and automotive load-bearing members. Tier 1 suppliers in Germany and Japan are qualifying these materials for wing skins and battery enclosures at accelerated timelines. The shift is compressing tool-to-part cycle times from hours to minutes and enabling weld-bonded assembly without mechanical fasteners.
REACH substance restrictions and EPA hazardous air pollutant rules are constraining epoxy resin formulations and pushing suppliers toward lower-VOC thermoplastic matrices. Formulators are reformulating toughening agents and hardener packages to maintain mechanical performance while meeting emission thresholds. Automotive applications in Europe and North America are responding fastest, with aerospace trailing due to longer qualification cycles.
Buyer concentration among airframe OEMs and battery enclosure integrators is consolidating procurement volumes and squeezing mid-tier tape converters. Long-term supply agreements with deposition equipment makers are replacing spot purchasing for slit-tape formats. This pattern is most visible in Germany's automotive corridor and Washington State's aerospace cluster, where qualified supplier lists are narrowing to vertically integrated material-process providers.
Fiber Reinforced Composite Tapes Market Segmentation
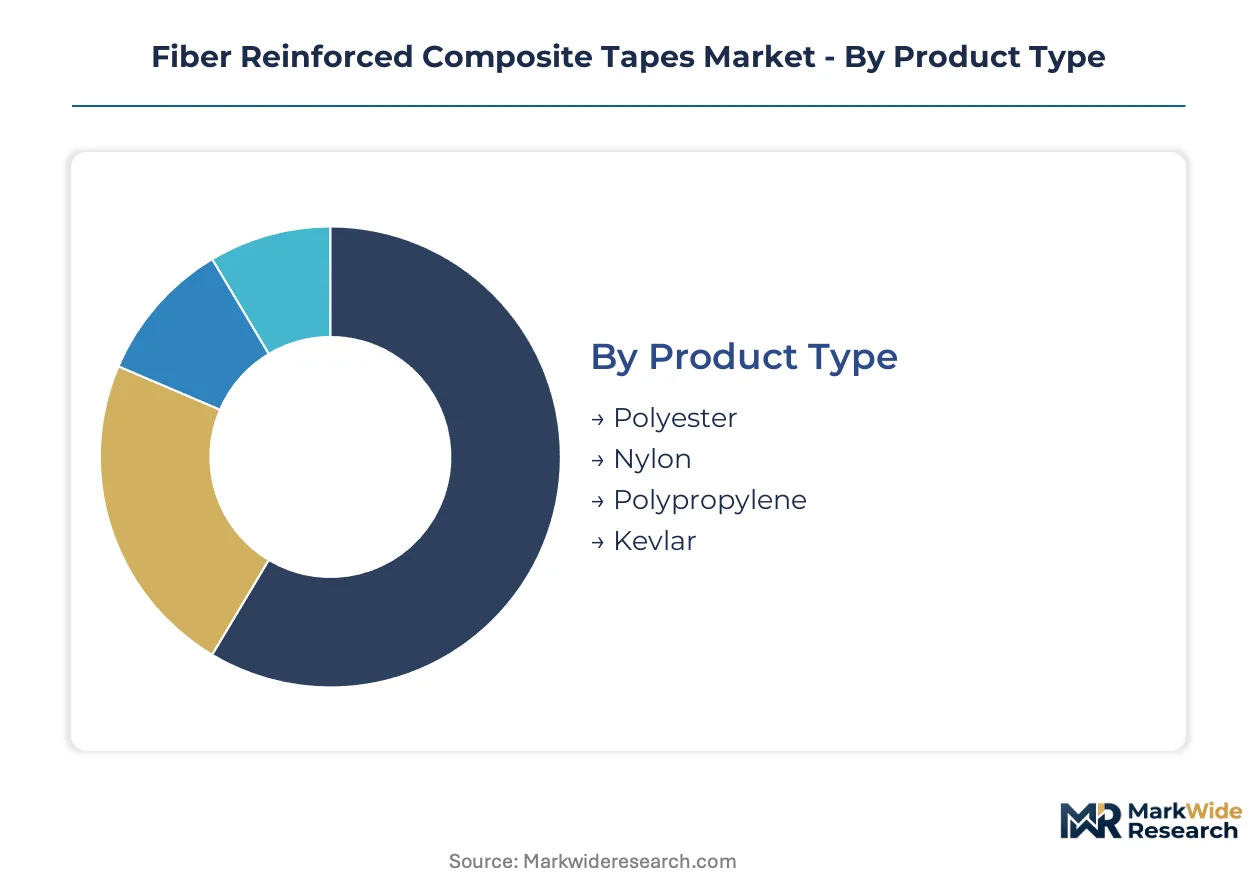
Segmentation in fiber reinforced composite tapes reveals how material chemistry, deposition geometry, and end-use certification requirements fragment procurement patterns. Suppliers must align slit-tape specifications with automated fiber placement head geometries while navigating divergent qualification timelines across aerospace and automotive programs.
Product Type:
Cost tier differentiation across polymer backbones determines resin matrix compatibility and deposition temperature windows.
- Polyester:Saturated thermoplastic matrices enable lower-temperature processing for automotive secondary structures. Demand concentrates in Germany's Stuttgart-Munich corridor for battery enclosure applications where cycle-time reduction outweighs modulus requirements.
- Nylon:Semi-crystalline polyamide systems deliver superior toughness for impact-resistant marine components. Procurement is accelerating in US Gulf Coast shipyards where surface protection specifications prioritize puncture resistance over stiffness-to-weight ratios.
- Polypropylene:Low-density olefin matrices serve cost-sensitive industrial insulation segments with minimal structural loading requirements.
- Kevlar:Aramid fiber reinforcement retains niche positioning where ballistic protection and vibration damping specifications govern material selection.
Polyester commands the established base. The steepest expansion runs through Nylon.
End User:
Application maturity and certification burden create divergent margin profiles across customer categories.
- Aerospace:FAA airworthiness directives and EASA certification specifications govern primary structural tape qualifications, extending supplier relationships but locking incumbent positions. Carbon fiber prepreg formats dominate wing skin and fuselage frame applications where fatigue limits exclude metallic alternatives.
- Automotive:NHTSA crashworthiness protocols and OEM lightweighting mandates are reshaping glass fiber thermoplastic specifications for floor pans and battery enclosures. Germany's supplier ecosystem is concentrating procurement volumes around qualified material-process providers.
- Marine:Impact-resistant Kevlar surface protection systems serve yacht hull and military vessel applications where puncture resistance outweighs modulus optimization.
- Industrial:Cost-driven insulation and bonding applications utilize glass fiber polyester formats with minimal performance certification requirements.
Aerospace commands the established base. Automotive is gaining share fastest.
Application:
Functional purpose determines fiber architecture, resin selection, and deposition automation requirements.
- Structural Reinforcement:Unidirectional carbon fiber tapes with thermoset epoxy matrices deliver engineered stiffness-to-weight ratios for primary load-bearing members. FAA-qualified supply chains in Washington State and Bavaria concentrate procurement among vertically integrated material-process providers.
- Insulation:Multi-axial glass fiber formats with thermoplastic binders serve thermal and electrical isolation requirements in industrial equipment housings.
- Surface Protection:Woven aramid and hybrid fiber systems protect marine and aerospace surfaces from abrasion and impact damage.
- Bonding:Adhesive-compatible tape formats enable composite-to-metal and composite-to-composite joining without mechanical fasteners.
Structural Reinforcement commands the established base. Surface Protection shows the steepest expansion trajectory.
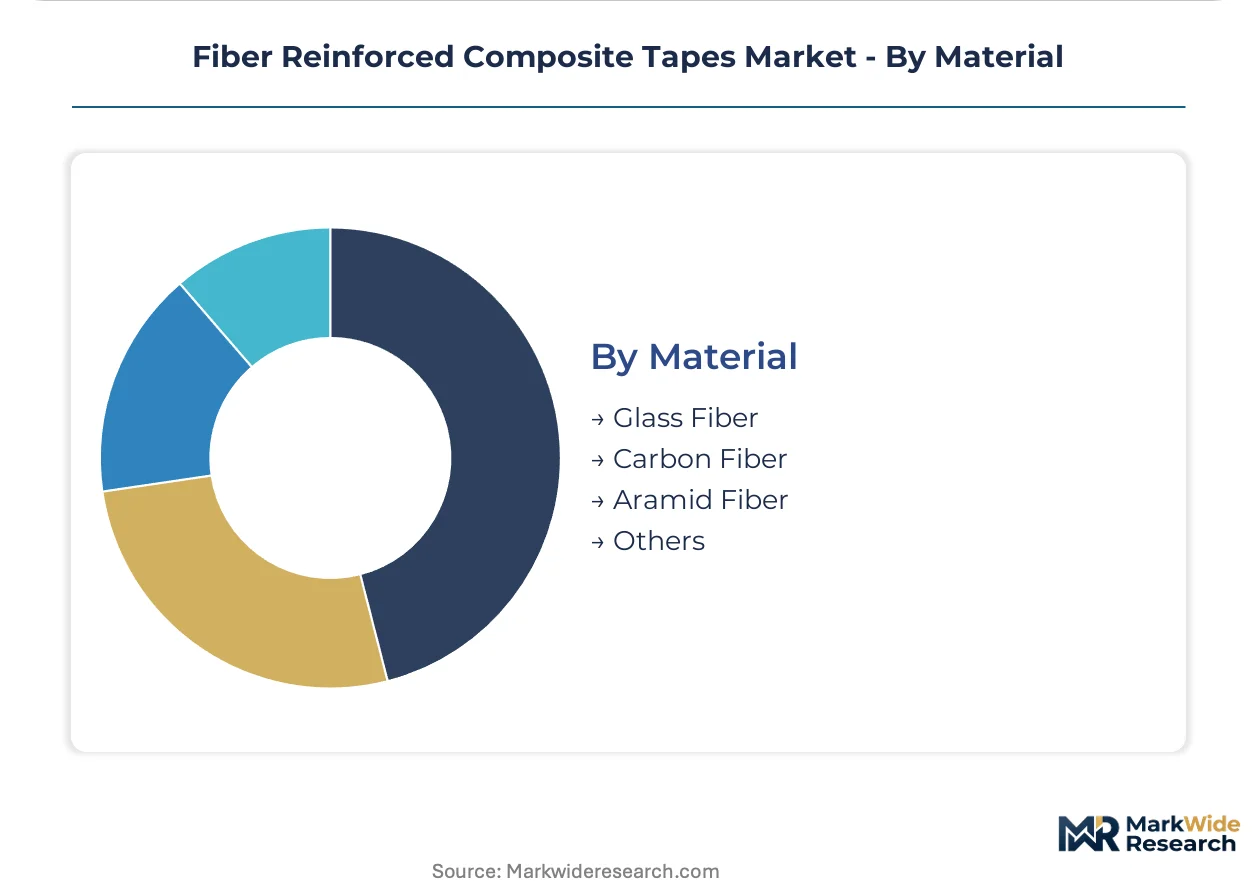
Material:
Fiber modulus and precursor chemistry anchor cost structures and performance ceilings across end-use specifications.
- Glass Fiber:E-glass and S-glass rovings dominate cost-sensitive automotive and industrial segments where modulus requirements permit higher density. India's PLI scheme for advanced materials is attracting slitting operations to serve domestic battery enclosure programs.
- Carbon Fiber:PAN-based precursors command premium positioning in aerospace primary structures where fatigue and corrosion limits exclude metals. Acrylonitrile price volatility compresses margin predictability for tape converters.
- Aramid Fiber:Kevlar and Twaron products retain specialized demand in marine impact protection and aerospace fairing applications.
- Others:Basalt and natural fiber alternatives occupy experimental niches seeking cost reduction or sustainability positioning.
Glass Fiber commands the established base. Carbon Fiber shows the steepest volume climb.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in fiber reinforced composite tapes tilt toward net-import status in aerospace-intensive economies while chemical-industry hubs maintain raw material surplus positions. Acrylonitrile precursor availability and automated fiber placement equipment density shape regional competitive standing.
United States
FAA airworthiness directives drive qualified tape procurement for Boeing and defense prime contractors. EPA hazardous air pollutant rules constrain resin formulation options in Washington State and California manufacturing corridors. The Pacific Northwest aerospace cluster around Seattle concentrates carbon fiber prepreg qualification activity.
Germany
Automotive lightweighting mandates from KBA accelerate glass fiber thermoplastic tape demand for battery enclosures. REACH substance restrictions push formulators toward lower-VOC matrices in Stuttgart-Munich supplier corridor operations. Bavaria's material-process providers lock in long-term supply agreements with deposition equipment makers.
China
MIIT dual carbon goals and commercial aviation indigenization programs expand domestic carbon fiber tape capacity. GB standards for composite pressure vessels create filament winding demand for hydrogen storage applications. Yangtze River Delta chemical parks integrate acrylonitrile precursor with tape slitting operations.
Japan
METI advanced materials initiatives support thermoplastic unidirectional tape development for aerospace secondary structures. JIS qualification protocols extend supplier relationships but barrier entry for foreign competitors. Nagoya aerospace manufacturing cluster concentrates Toray Industries and Mitsubishi Chemical Group production.
India
PLI scheme production-linked incentives attract tape slitting and prepreg operations for domestic aerospace and defense programs. BIS standards for composite materials lag aerospace OEM requirements, creating qualification bottlenecks. Gujarat and Maharashtra industrial corridors host emerging battery enclosure tape demand from EV manufacturers.
Fiber Reinforced Composite Tapes Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated material-process providers with qualified aerospace positions. Three strategic archetypes dominate: carbon fiber precursor-to-prepreg integrators, thermoplastic tape specialists, and diversified chemical conglomerates with composite divisions. Competitive moves center on long-term supply agreement lock-ins with automated fiber placement equipment makers and multi-site qualification investments to extend incumbent positions.
Within the precursor-integrated tier, Toray Industries and Mitsubishi Chemical Group exemplify backward control over PAN-based carbon fiber supply chains. Hexcel Corporation anchors North American defense and space qualification portfolios. SGL Carbon occupies a distinct position in automotive-grade thermoplastic tape supply, competing on cycle-time metrics against thermoset alternatives.
| Leading Market Players |
|---|
| Toray Industries |
| Hexcel Corporation |
| SGL Carbon |
| Teijin Limited |
| Solvay |
| SABIC |
| Mitsubishi Chemical Group Corporation |
| BASF |
| Evonik Industries |
| Others |
Value Network & Pricing Analysis
Yangtze River Delta freight corridors transmit acrylonitrile precursor cost volatility directly into tape converter margins while amplifying price differentiation between aerospace-qualified and industrial-grade supply tiers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across glass fiber polyester formats. Price differentiation separates FAA-qualified carbon fiber prepreg from automotive thermoplastic tiers, with certification grade and volume scale as primary drivers. Cost compression in industrial segments intensifies because spot purchasers substitute lower-grade alternatives. Automotive battery enclosure integrators exhibit highest price sensitivity; aerospace prime contractors show lowest.
Supply Chain Analysis
Acrylonitrile precursor availability centers on China, Japan, and South Korea for PAN-based carbon fiber feedstocks. Tape converters draw from carbon fiber rovings, thermoplastic resin pellets, and slit-tape winding equipment as critical inputs. Single-source prepreg qualification with Boeing and Airbus creates switching-cost vulnerability. Distribution runs through qualified material-process providers with automated fiber placement equipment partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated fiber placement equipment-tape co-development partnerships are reconfiguring this market toward platform-economics dynamics where interoperability standards lock in supplier ecosystems.
For Market Incumbents: Pre-empt thermoplastic unidirectional tape displacement of legacy thermoset workflows by accelerating multi-site qualification investments across Washington State and Bavaria manufacturing clusters. Lock in long-term supply agreements with deposition equipment makers before emerging Asian competitors achieve aerospace certification.
For New Entrants and Emerging Players: India's PLI scheme-subsidized battery enclosure tape operations represent the most penetrable entry point for automotive-grade glass fiber thermoplastic supply. Target Gujarat and Maharashtra industrial corridors with localized slitting capabilities and BIS pre-qualification services.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underperforming composite divisions lacking aerospace qualification depth. Monitor hydrogen pressure vessel filament winding demand acceleration as inflection indicator for high-strength carbon fiber tape capacity scarcity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Production | Toray Industries and Mitsubishi Chemical Group control PAN-based carbon fiber supply chains. |
| Multi-Site Qualification Investment | Hexcel Corporation extends incumbent positions through duplicate FAA testing across manufacturing locations. |
| Long-term Supply Agreement with Equipment Makers | SGL Carbon locks in automotive-grade thermoplastic tape partnerships with automated fiber placement vendors. |
| Thermoplastic Resin Chemistry Transition | REACH and EPA constraints push formulators toward lower-VOC matrices for out-of-autoclave processing. |
| Digital Thread Integration | In-process inspection virtualization compresses certification timelines for next-generation narrowbody programs. |
Research Methodology
Desk research of SEC 10-K filings, customs trade data, and FAA airworthiness directives preceded structured interviews with aerospace procurement managers, automotive Tier 1 supplier engineers, tape converter operations directors, and thermoplastic resin formulators. Bottom-up and top-down triangulation validated segment-level volume estimates against acrylonitrile precursor consumption patterns and automated fiber placement equipment deployment data.
Assumptions held acrylonitrile price indices and certification timeline durations fixed while varying automotive lightweighting mandate intensity and hydrogen storage tank demand trajectories. Segmentation modeling incorporated fiber type, resin chemistry, end-use certification tier, and regional production hub dimensions. CAGRs derived from slope analysis of historical qualified material shipments extrapolated across the projection horizon, with specific inputs from Boeing and Airbus narrowbody production schedules and NHTSA crashworthiness protocol revisions.
Practitioners should monitor FAA airworthiness directive amendments and REACH substance restriction updates for early signals requiring forecast revision. Cross-checking against acrylonitrile futures contract pricing and deposition equipment order backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Global Composite Materials Market
Composite Materials
High Performance Carbon Fiber Precursor Market
Composite Materials
Composite Material for Passenger Car Market
Composite Materials
Short Fiber Thermoplastic Composites Market
Composite Materials
Europe Aluminium Composite Panel Market
Composite Materials
High Temperature Composite Resin Market
Composite Materials
Global Lightweight Construction Material Market
Composite Materials
Global Composite Resin Market
Composite Materials
Pultrusion Market
Composite Materials
Global Carbon Fiber Composite Heating Elements Market
Composite Materials
Carbon Aerogel Market
Composite Materials
Marine Composites Market
Composite Materials
Graphite Carbon Raiser Market
Composite Materials
Carbon Thermoplastic Composites Market
Composite Materials
Asia-Pacific Natural Fiber Composites Market
Composite Materials
Global Molded FRP Grating Market