
 Asia-Pacific Metal Casting Market | 2026-2036
Asia-Pacific Metal Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Metal Casting Market Insights
Aluminum is pivoting from auxiliary components into primary structural parts across passenger vehicle platforms. Hitachi Metals leverages its integrated aluminum smelting and precision casting operations to supply Japanese automakers with high-strength chassis members. Bharat Forge anchors India's heavy-truck and defense casting supply through its Pune and Satara facilities, while Ryobi Limited dominates small-engine and automotive die-casting from its Thai and Chinese plants.
Asia-Pacific metal casting encompasses the pouring of molten ferrous and non-ferrous alloys into molds to produce engineered components with tolerances typically ranging from ±0.5 mm to ±2 mm depending on process control. Sand casting retains the largest volume share for industrial machinery and construction equipment, though die casting captures expanding margin pools in automotive components where thin-wall aluminum parts reduce vehicle weight. Investment casting sustains premium positioning in aerospace turbine blades and medical implants, while copper castings serve electrical infrastructure applications across the region's power grid buildouts.
China's MIIT enforces GB standards for automotive aluminum alloy castings, while India's BIS mandates material certification for construction and heavy industry castings, and Japan's METI promotes JIS-aligned energy efficiency benchmarks that shape foundry equipment upgrades. These frameworks collectively raise compliance costs for smaller operators while creating preferential market access for certified suppliers. Stakeholders must monitor evolving alloy purity requirements and carbon accounting rules that will reshape sourcing decisions across the ASEAN supply base.
Market Dynamics
China's MIIT and India's BIS emissions mandates are compressing design cycles for automotive castings, forcing foundries to retool for thin-wall aluminum die-casting while absorbing alloy certification costs that favor scaled operators over fragmented competitors.
Growth Catalysts
- MIIT Emissions Enforcement:China's GB standards for automotive aluminum alloy castings compel OEMs to substitute ferrous components with lightweight alternatives, expanding die-casting capacity across the Yangtze River Delta industrial cluster.
- EV Battery Housings:Electric vehicle manufacturers in China and India are placing dedicated orders for large-format aluminum castings that integrate thermal management functions previously handled by separate assemblies.
- Die-Casting Process Control:Real-time monitoring systems for molten metal temperature and pressure are reducing porosity defects in thin-wall applications, qualifying more suppliers for structural chassis contracts.
Market Restraints
- Aluminum Alloy Volatility:Primary aluminum ingot prices fluctuate with LME trading patterns, compressing margins for sand-casting operators locked into fixed-price construction equipment contracts.
- Induction Furnace Concentration:China's Jiangsu and Shandong provinces host over half the region's medium-frequency induction furnace manufacturing, creating single-source vulnerability for foundries upgrading melting capacity.
- Investment Casting Throughput Limits:Ceramic shell curing cycles constrain batch sizes for aerospace turbine blade orders, capping revenue velocity despite premium pricing.
Strategic Opportunities
- Indonesia Nickel-Casting Integration:Battery-grade nickel smelting investments in Sulawesi create feedstock proximity for stainless steel casting operations serving regional chemical processing infrastructure.
- Thailand Medical Implant Cluster:Investment casting for orthopedic implants remains underdeveloped outside Japan, presenting white space for ISO 13485-certified suppliers targeting ASEAN hospital procurement networks.
- BIS Construction Mandate Expansion:India's Bureau of Indian Standards is extending material certification to municipal water infrastructure castings, creating preferential access for domestic foundries with in-house metallurgical testing.
Industry Challenges
- Die-Casting Simulation Expertise Gap:Computational fluid dynamics modeling for multi-cavity mold design requires specialized training that outpaces regional technical education output.
- Alloy Traceability Documentation:Automotive OEMs now require lot-level chemical composition records extending back to primary smelter sources, forcing legacy foundries to reconstruct supply chain data systems.
- Induction Furnace Electromagnetic Compliance:Grid harmonic distortion regulations in Japan and South Korea demand power conditioning equipment that adds capex burden for melting operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Metal Casting Market |
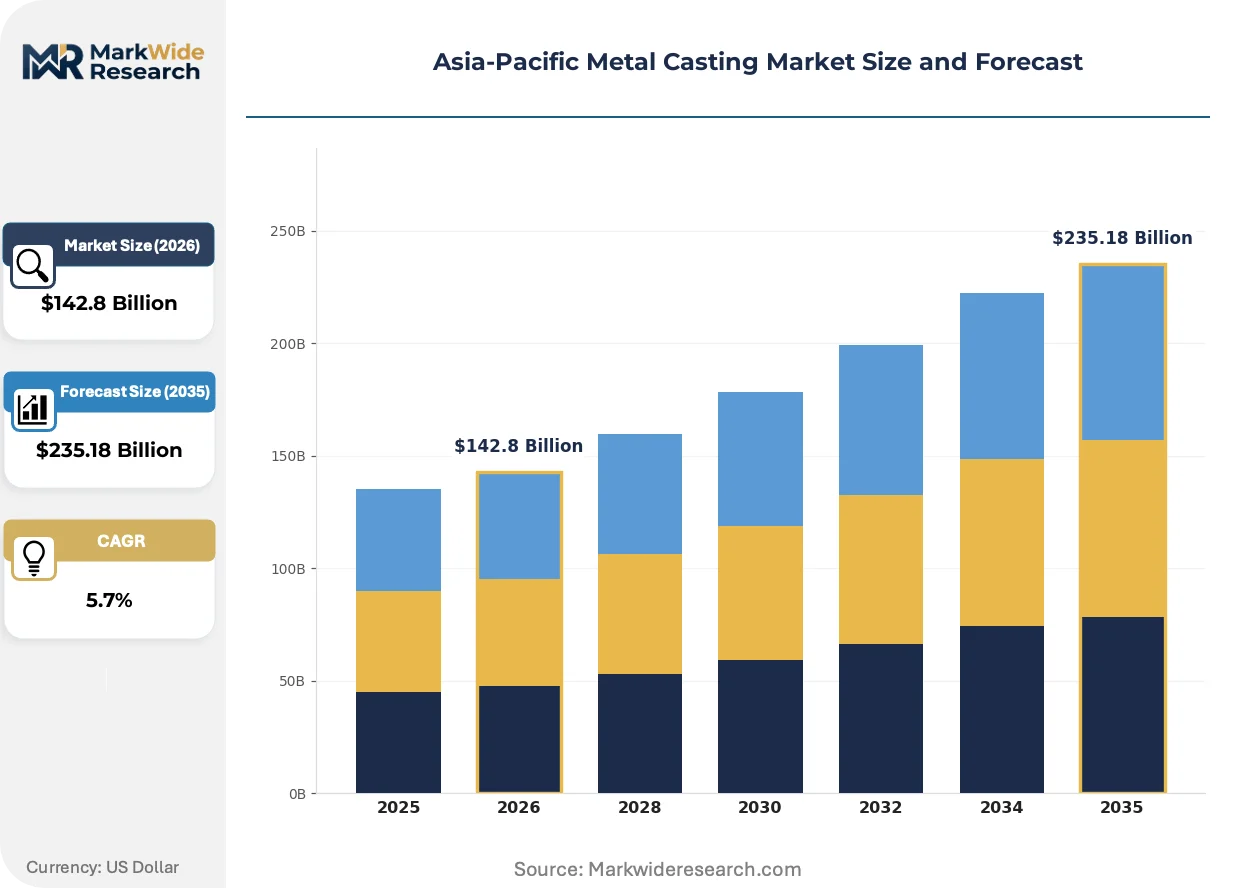
| Market Size in 2026 | $142.8 Billion |
| Market Size in 2035 | $235.18 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Iron Castings, Steel Castings, Aluminum Castings, Copper Castings Technology: Sand Casting, Die Casting, Investment Casting, Centrifugal Casting Application: Aerospace, Automotive Components, Industrial Machinery, Construction Equipment End User: OEMs, Manufacturing, Construction, Heavy Industry |
| Companies Covered | Ryobi Limited, Hitachi Metals, Nemak, Anhui Yingliu Electromechanical, Zhejiang Materials Industry Group, Bharat Forge, Tata Steel, GF Casting Solutions, Kosei Aluminum, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Metal Casting Market Trends and Innovations
Digitalization of foundry floor operations is compressing defect detection timelines and enabling lot-level traceability that automotive OEMs now mandate for structural casting qualifications across the region.
Real-time X-ray inspection systems integrated into high-pressure die-casting cells are automating porosity detection at cycle speeds that match production throughput. Japanese and Korean automakers have adopted this technology for chassis member qualifications since 2023. The technology is automating quality assurance roles that previously required offline laboratory analysis, reducing qualification timelines from weeks to days.
China's MIIT is tightening GB/T 23301 energy consumption limits for foundry induction furnaces, forcing equipment replacement or efficiency retrofits ahead of 2026 compliance deadlines. The regulation is accelerating scrappage of 1990s-era melting capacity across Shandong and Hebei provinces. Die-casting specialists with captive solar-plus-storage power systems are capturing preferential supplier status from carbon-accounting OEMs.
Automotive Tier-1 suppliers are consolidating casting procurement under single-source agreements that bundle design, tooling, and volume commitments across vehicle platforms. This displaces the traditional multi-source bidding model that fragmented orders across competing foundries. The pattern is most visible in China's Yangtze River Delta, where BYD and NIO suppliers are locking in dedicated die-casting cell capacity for five-year horizons.
Asia-Pacific Metal Casting Market Segmentation
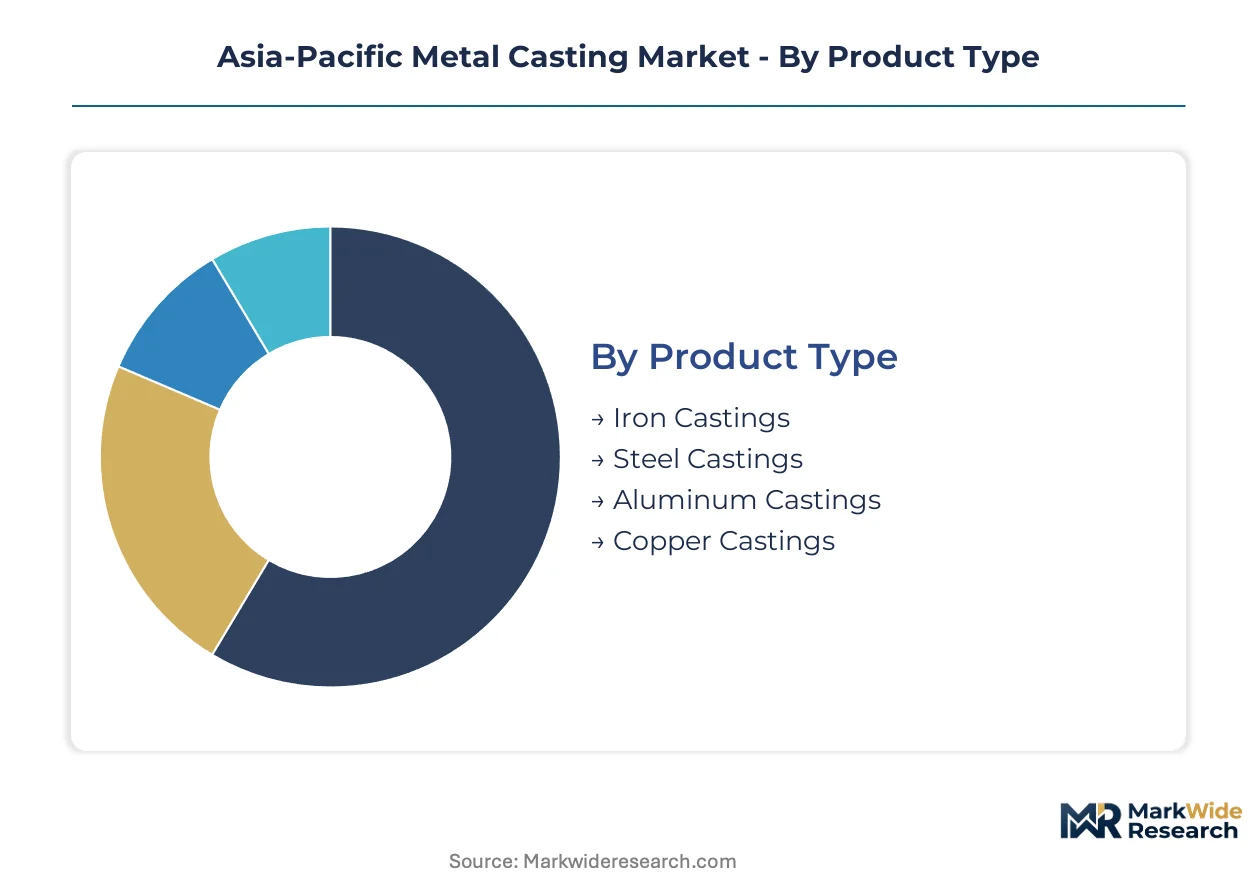
Asia-Pacific metal casting procurement increasingly sorts by certification burden rather than commodity pricing alone. OEMs now mandate lot-level traceability and alloy purity documentation that fragments the supplier base between certified tier-1 suppliers and uncertified regional competitors.
Product Type:
MIIT's GB standards for automotive aluminum and BIS construction mandates create divergent compliance pathways across alloy categories.
- Aluminum Castings:High-strength alloys with silicon and magnesium additions serve EV battery housings and chassis members under China's GB/T 23301 energy efficiency framework. Demand concentrates in Yangtze River Delta die-casting clusters serving BYD and NIO supply chains, with thermal management integration driving large-format casting adoption.
- Iron Castings:Gray and ductile iron grades retain dominance in construction equipment and industrial machinery where BIS certification governs municipal infrastructure applications. India's Satara and Pune foundry belts anchor heavy-truck brake drum and transmission housing supply.
- Steel Castings:Carbon and alloy steel grades withstand high-impact loading in mining equipment and defense applications across India's heavy industry procurement networks.
- Copper Castings:Electrical conductivity grades serve power grid infrastructure buildouts across ASEAN markets, with tin-bronze alloys dominating switchgear and transformer component specifications.
Iron Castings sits at the top of the volume ranking, with Aluminum Castings climbing the fastest.
Technology:
Process selection correlates directly with margin tier and customer type, with die-casting commanding premium positioning against sand-casting's commodity volume base.
- Die Casting:High-pressure aluminum injection into hardened steel molds achieves ±0.5 mm tolerances for thin-wall automotive structural members. Real-time X-ray inspection integration qualifies suppliers for Japanese and Korean OEM chassis contracts.
- Sand Casting:Green sand and chemically bonded molds accommodate ferrous alloys in single-piece runs up to several tonnes for construction and mining equipment. China's Hebei and Shandong provinces host the bulk of regional capacity.
- Investment Casting:Ceramic shell processes yield near-net-shape aerospace turbine blades and medical implants with surface finishes below Ra 3.2 micrometers.
- Centrifugal Casting:Rotational force distribution produces radially symmetric components such as pipes, bushings, and cylinder liners for chemical processing infrastructure.
Sand Casting retains the widest installed base, though Die Casting captures the steepest expansion trajectory as automotive lightweighting accelerates.
Application:
End-use requirements dictate alloy selection and certification depth, with aerospace and automotive imposing the most stringent documentation burdens.
- Automotive Components:Structural aluminum castings integrate crash management and thermal functions previously handled by multi-part assemblies. China's MIIT emissions mandates compress design cycles and favor suppliers with captive simulation capabilities.
- Industrial Machinery:Ferrous castings for pumps, valves, and gearboxes prioritize wear resistance and machinability over dimensional precision.
- Aerospace:Nickel-based superalloy turbine blades demand vacuum investment casting with ceramic core technology held by a limited supplier set.
- Construction Equipment:High-manganese steel and ductile iron castings withstand abrasive loading in excavator and loader applications across India's infrastructure buildout.
Automotive Components leads absolute revenue contribution, with Aerospace maintaining the highest value-per-kilogram positioning.
End User:
Procurement authority separates direct OEM relationships from indirect manufacturing demand, with certification requirements cascading differently across each channel.
- OEMs:Automotive and aerospace original equipment manufacturers enforce single-source agreements bundling design, tooling, and volume commitments across five-year horizons. Lot-level traceability to primary smelter sources is now mandatory.
- Heavy Industry:Defense, mining, and energy sector buyers prioritize domestic content requirements and long-term alloy availability over unit cost minimization.
- Manufacturing:Tier-2 and tier-3 component suppliers purchase standard grades through distributor networks with limited technical specification involvement.
- Construction:Municipal infrastructure contractors respond to BIS mandate expansion for water and sewage system castings, favoring domestic foundries with in-house metallurgical testing.
OEMs concentrate the highest-value procurement decisions, while Manufacturing represents the broadest addressable supplier base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta die-casting clusters anchor Asia-Pacific metal casting output, with China's MIIT emissions mandates compressing design cycles for aluminum structural components across the region's automotive supply chains.
China
EV battery housing demand from BYD and NIO suppliers drives large-format aluminum casting adoption. MIIT's GB/T 23301 energy consumption limits for induction furnaces force equipment replacement across Shandong and Hebei provinces. Die-casting capacity concentrates in Jiangsu and Zhejiang provinces serving thermal-integrated chassis contracts.
India
Heavy-truck brake drum and transmission housing orders expand from domestic OEMs and defense procurement. BIS material certification mandates for construction and municipal water infrastructure favor foundries with captive metallurgical testing. Pune and Satara foundry belts anchor Bharat Forge's casting supply for commercial vehicle platforms.
Japan
High-strength chassis member qualifications from Toyota and Honda sustain precision aluminum demand. METI-aligned JIS energy efficiency benchmarks shape foundry equipment upgrade cycles. Nagoya-area die-casting specialists integrate real-time X-ray inspection for porosity detection at production throughput speeds.
Thailand
Small-engine and automotive component exports to ASEAN markets drive die-casting volume. Japanese transplant OEMs enforce single-source agreements bundling design and tooling commitments. Rayong and Chonburi industrial estates host concentrated aluminum casting capacity serving regional motorcycle and passenger vehicle assembly.
South Korea
Hyundai-Kia structural casting qualifications demand lot-level traceability to primary smelter sources. Grid harmonic distortion regulations require power conditioning equipment for induction furnace operations. Gyeonggi-do and Ulsan foundry clusters supply crash management and thermal management integrated castings.
Asia-Pacific Metal Casting Market Competitive Landscape
Capacity expansion dominates the current landscape as automotive OEMs consolidate procurement under single-source agreements. The supplier base fragments between certified tier-1 die-casting specialists and uncertified regional sand-casting operators. Three archetypes define competitive positioning: integrated aluminum smelter-casters, precision die-casting technologists, and ferrous heavy-industry foundries. M&A activity and captive solar-plus-storage power investments represent the dominant competitive moves as carbon-accounting OEMs screen supplier energy profiles.
Within the integrated smelter-caster tier, Hitachi Metals and Bharat Forge exemplify divergent geographic and material specializations. Ryobi Limited occupies a position among precision die-casting technologists with Thai and Chinese manufacturing presence. These three companies anchor the competitive structure without exhausting the supplier diversity across the region's foundry base.
| Leading Market Players |
|---|
| Ryobi Limited |
| Hitachi Metals |
| Nemak |
| Anhui Yingliu Electromechanical |
| Zhejiang Materials Industry Group |
| Bharat Forge |
| Tata Steel |
| GF Casting Solutions |
| Kosei Aluminum |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap foundries across China's Hebei and Shandong provinces anchor regional supply discipline, translating captive scrap-metal sourcing into pricing resilience against LME aluminum volatility while sovereign-backed Indonesian nickel smelters reshape stainless steel casting feedstock economics.
Pricing Analysis
Input-cost pass-through from primary aluminum ingot movements dominates contract negotiations between Yangtze River Delta die-casters and automotive OEMs. Three-tier pricing structure across MIIT-certified premium, BIS-compliant standard, and uncertified economy levels separates suppliers by documentation depth. Cost compression in sand-casting tiers is intensifying because construction equipment buyers resist index-linked adjustments. Heavy industry procurement shows least price sensitivity due to domestic content mandates.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from BYD and NIO supply chains, while distributor networks serve tier-2 manufacturing demand. Geographic supply concentrates in China, India, and Thailand. Raw material dependencies draw from Indonesian nickel, Australian bauxite, and domestic scrap recovery streams. Single-source vulnerability permeates Jiangsu and Shandong induction furnace manufacturing. Distribution runs through dedicated die-casting cells under single-source agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with automotive OEMs consolidating procurement under traceability-mandated suppliers as EV battery housing demand shifts toward premium thermal-integrated specifications.
For Market Incumbents: Anticipate alloy traceability documentation requirements from Japanese and Korean automakers by retrofitting ERP systems for lot-level smelter-source tracking. Defensive consolidation through captive solar-plus-storage investments captures preferential supplier status from carbon-accounting OEMs. Threat substitution from magnesium die-casting in ultra-lightweight applications pressures aluminum chassis margins. For New Entrants and Emerging Players: Capture Thailand's underdeveloped orthopedic implant investment casting segment through ISO 13485 certification and ASEAN hospital procurement network penetration. White space concentrates in medical device supply outside Japan's established base. Go-to-market leverage rests on technical partnership with Japanese precision casting technologists for knowledge transfer. For Investors and Strategic Acquirers: Valuations sit cheapest among uncertified sand-casting operators facing MIIT furnace efficiency deadlines. Long-term viability favors tier-1 die-casting specialists with captive simulation capabilities and single-source OEM relationships. Signal to monitor: BIS mandate expansion into municipal water infrastructure castings triggering domestic foundry M&A.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Solar-Plus-Storage Installation | BYD and NIO suppliers with renewable power capture preferential carbon-accounting supplier status. |
| Real-Time X-Ray Inspection Integration | Toyota and Honda chassis qualifications now require porosity detection at production throughput speeds. |
| Backward Integration into Aluminum Smelting | Hitachi Metals models integrated feedstock control for Japanese automaker high-strength alloy supply. |
| ISO 13485 Certification Investment | Thailand medical implant casting opens ASEAN hospital procurement networks to qualified entrants. |
| Single-Source Agreement Consolidation | Yangtze River Delta die-casters lock five-year dedicated cell capacity under bundled design-tooling-volume contracts. |
Research Methodology
Direct dialogue with foundry operations managers, automotive Tier 1 procurement leads, metallurgical testing laboratory directors, and induction furnace equipment suppliers grounded qualitative insights. Secondary validation drew from MIIT GB standard filings, BIS certification registries, customs trade data for aluminum ingot flows, and SEC filings of listed casting specialists. Bottom-up capacity surveys across China's Hebei and Shandong provinces combined with top-down automotive production forecasts to triangulate demand estimates.
Segment-level value outputs across the analysis window reflect modeled interactions between alloy category, process technology, and end-use certification requirements. The analytical framework incorporated vehicle class, propulsion architecture, and content-per-vehicle dimensions alongside geographic production cluster dynamics. CAGRs derived from regression analysis of historical capacity utilization against OEM platform launch timelines, with EV battery housing adoption curves and MIIT furnace replacement cycles as specific forecast inputs.
Underlying measurement precision varies by segment; die-casting with real-time quality data carries tighter precision than sand-casting with fragmented operator reporting. Forecasts reflect assumptions regarding MIIT enforcement continuity, LME aluminum price bands, and BIS mandate expansion scope. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Nickel Boride Alloy Market
Advanced Alloys
Tungsten Alloy Market
Advanced Alloys
Global Noble Ferroalloys Market
Advanced Alloys
Global Amorphous Alloy Band Market
Advanced Alloys
Ultra High Strength Steel Market
Advanced Alloys
Polyphenylene Ether (PPE) Alloy Market
Advanced Alloys
Europe Aluminum Casting Market
Advanced Alloys
Europe Green Steel Market
Advanced Alloys
Automotive Aluminum Alloy (OE) Market
Advanced Alloys
Maraging Steel Market
Advanced Alloys
Steel Fiber Market
Advanced Alloys
Titanium Aluminide Market
Advanced Alloys
Thulium Silicide Market
Advanced Alloys
Cermet Market
Advanced Alloys
Asia-Pacific Green Steel Market
Advanced Alloys
India Shape Memory Alloy Market