
 Master Alloys Market | 2026-2036
Master Alloys Market Size, Share, and Industry Trends Forecast 2026-2036
Master Alloys Market Outlook
Product bundling around full-system master alloy packages is consolidating buyer procurement patterns across the supply base. KBM Affilips leverages its European laboratory network to sustain technical service relationships with specialty foundries. AMG Advanced Metallurgical Group N.V. anchors its position through captive tungsten and tantalum sources that secure raw material continuity. Rusal competes on scale, operating some of the largest aluminum master alloy furnaces serving Asian and Middle Eastern customers.
Master alloys are intermediate metallic products, typically containing 5-50% of an active element such as titanium, boron, or chromium, manufactured through aluminothermic reduction or vacuum induction melting for controlled introduction into base metals. They serve primarily to achieve precise chemical refinement, grain structure control, and mechanical property enhancement in finished alloys. Aluminum master alloys dominate volume flows given their centrality to automotive and construction castings, while titanium variants command premium positioning in aerospace and nuclear applications where melt consistency standards are most exacting. Powder forms are gaining traction in additive manufacturing feedstock chains, though ingots and wires still occupy the bulk of commercial transactions across transportation and industrial end uses.
The EPA enforces emissions thresholds that affect smelter operations and alloy refining economics across the United States. REACH and the EU Green Deal impose substance registration and carbon footprint disclosure obligations that reshape European sourcing decisions for master alloy consumers. China's GB standards and dual carbon goals from MEE are tightening energy intensity benchmarks for domestic ferroalloy and master alloy producers. Stakeholders must monitor how regulatory divergence across these jurisdictions affects cross-border qualification protocols and capital allocation for new smelting capacity.
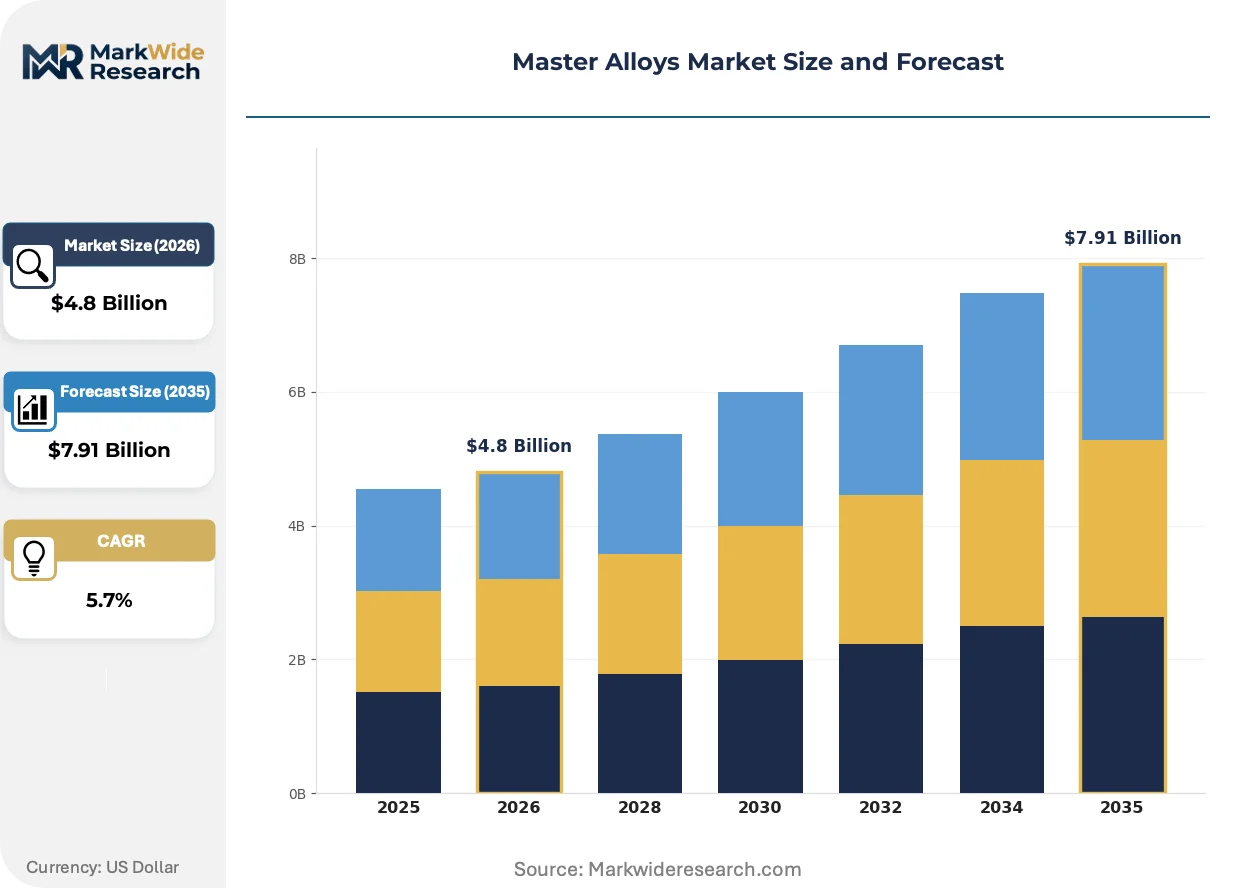
Market Dynamics
Lightweighting mandates in aerospace and automotive sectors are concentrating demand for titanium and aluminum master alloys, while regulatory divergence across the US, Europe, and China is fragmenting qualification protocols and reshaping capital deployment for new smelting capacity.
Growth Catalysts
- EPA emissions thresholds:US smelters are retrofitting refining operations to meet tightened environmental standards, accelerating demand for cleaner master alloy production technologies and process controls.
- Nuclear construction programs:China's expanding reactor fleet is consuming specialty master alloys for radiation-resistant components, pulling volume toward high-purity titanium and zirconium variants.
- Additive manufacturing feedstock:Powder-form master alloys are penetrating aerospace and medical implant supply chains as direct energy deposition and powder bed fusion methods mature.
Market Restraints
- Tungsten and tantalum supply concentration:Captive sourcing from conflict-sensitive regions creates raw material continuity risks for premium master alloy grades.
- Aluminothermic reduction energy intensity:Spikes in electricity and natural gas costs compress margins for aluminum master alloy producers operating energy-intensive batch furnaces.
- REACH substance registration:European chemical disclosure obligations extend lead times for new alloy formulations entering EU markets, favoring incumbent suppliers with existing dossiers.
Strategic Opportunities
- India's PLI scheme for specialty steel:Domestic foundry modernization incentives are opening procurement channels for boron and ferrotitanium master alloys in automotive and construction castings.
- Dual carbon goals enforcement:China's MEE energy intensity benchmarks are forcing domestic ferroalloy consolidation, creating import substitution openings for compliant foreign suppliers.
- Wire-feed additive manufacturing:Convergence of arc-based deposition and robotic positioning is expanding addressable demand for precision-drawn master alloy wire in repair and near-net-shape applications.
Industry Challenges
- Vacuum induction melting expertise:Shortages of metallurgists capable of controlling oxygen and nitrogen pickup during reactive metal processing constrain capacity expansion for aerospace-grade titanium master alloys.
- Cross-border qualification protocols:Divergent testing standards between FAA, EASA, and CAAC certification regimes force duplicate sampling and extended approval cycles for multinational alloy suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Master Alloys Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Copper, Magnesium, Titanium End User: Aerospace, Automotive, Electronics, Industrial Form: Ingots, Wires, Powders, Sheets Application: Transportation, Construction, Military, Nuclear |
| Companies Covered | ATI Inc., KBM Affilips, Alcoa Corporation, Materion Corporation, Rusal, AMG Advanced Metallurgical Group N.V., Carpenter Technology Corporation, Umicore, Arconic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Master Alloys Market Strategic Shifts
Spectral analysis and in-melt sensor integration are compressing quality assurance timelines, while regulatory carbon accounting and buyer procurement consolidation are restructuring how master alloy value chains capture and demonstrate technical compliance.
Machine vision systems paired with laser-induced breakdown spectroscopy are automating real-time composition verification during ladle treatment, enabling foundries to reduce laboratory hold times from hours to minutes. Aerospace tier-one suppliers in Germany and Japan are adopting these platforms fastest. The technology is automating away manual sampling protocols and reducing off-specification remelt costs.
REACH and the EU Green Deal carbon footprint disclosure obligations are forcing European master alloy consumers to document Scope 3 emissions from raw material extraction through final delivery. Smelters must now track energy sources and transport modes to maintain qualification status. Specialty foundries in France and Italy are responding by consolidating supplier panels to reduce audit complexity.
Full-system master alloy packages are displacing single-product spot purchasing as automotive OEMs centralize procurement under fewer metallurgical service contracts. Tier-one casting houses now specify bundled grain refiners, modifiers, and cleaners with guaranteed compatibility. This pattern is most visible in China's Yangtze River Delta automotive cluster, where domestic smelters compete on technical service depth rather than price per kilogram alone.
Master Alloys Market Segmentation
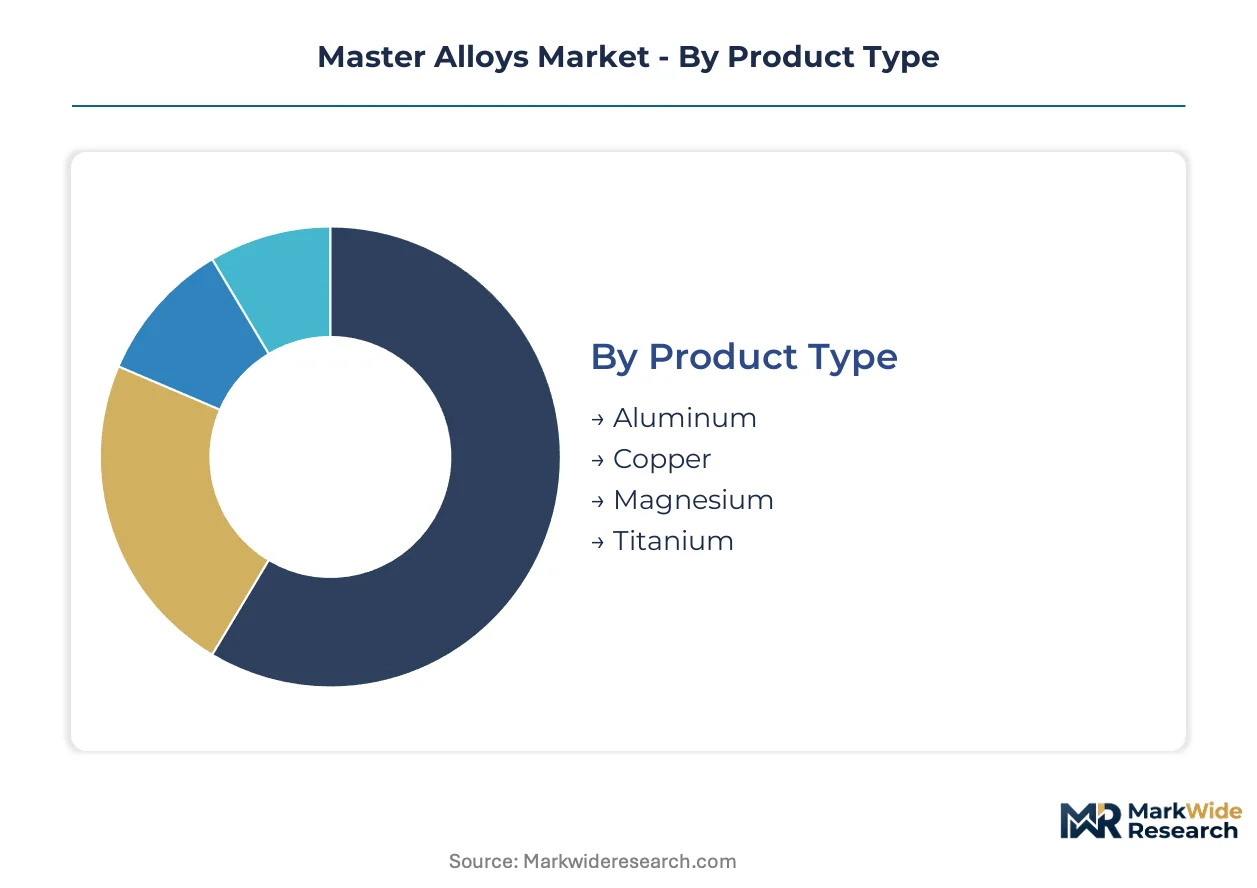
Master alloy procurement patterns diverge sharply across product chemistry, physical form, and end-use qualification requirements. Smelters configure furnace campaigns and inventory positions around these segment boundaries, since titanium aerospace grades and aluminum automotive volumes operate on entirely different technical and commercial rhythms.
Product Type:
Supply concentration varies dramatically by base metal chemistry, with captive raw material positions determining competitive viability in premium grades.
- Aluminum:These alloys contain 5-50% active elements like titanium, boron, or chromium introduced through aluminothermic reduction. Automotive cylinder head and wheel casting operations in Germany, China, and the United States consume the largest volumes, driven by lightweighting mandates and construction sector demand.
- Titanium:Vacuum induction melting produces these high-purity intermediates for aerospace and nuclear applications where oxygen and nitrogen control is critical. China's expanding reactor fleet and commercial aircraft backlogs are concentrating demand for zirconium-bearing variants.
- Copper:Deoxidation and property modification alloys serve electrical conductivity applications and marine hardware foundries.
- Magnesium:Grain refinement master alloys address corrosion resistance requirements in automotive transmission housings and portable electronics chassis.
Aluminum absorbs the bulk of installed capacity; titanium is expanding most quickly.
End User:
Customer technical requirements stratify the supply base, with qualification protocols acting as barriers between commodity and specialty tiers.
- Aerospace:FAA, EASA, and CAAC certification regimes enforce melt consistency standards for turbine blade and airframe alloys. Powder-form titanium master alloys are penetrating additive manufacturing feedstock chains as direct energy deposition methods mature.
- Automotive:Full-system master alloy packages are displacing single-product spot purchasing as OEMs centralize procurement under fewer metallurgical service contracts.
- Electronics:Thermal management and electromagnetic shielding applications drive demand for copper and magnesium variants with tight impurity specifications.
- Industrial:General foundry and construction casting applications prioritize cost efficiency over certification depth.
Automotive commands the largest revenue pool; aerospace demonstrates the steepest expansion trajectory.
Form:
Physical configuration determines handling economics and compatibility with downstream melting or deposition equipment.
- Ingots:Standard cast blocks dominate high-volume aluminum and copper master alloy transactions across transportation and construction end uses.
- Wires:Precision-drawn products serve robotic wire-feed additive manufacturing in repair and near-net-shape aerospace applications.
- Powders:Gas-atomized spherical powders are gaining traction in powder bed fusion medical implant and aerospace component production.
- Sheets:Rolled product forms address specialized cladding and brazing alloy requirements in heat exchanger manufacturing.
Ingots retain the dominant share of commercial transactions; powders are climbing the fastest as additive manufacturing scales.
Application:
End-use performance requirements dictate purity thresholds and documentation burdens, fragmenting pricing and supplier qualification status.
- Transportation:Automotive and commercial vehicle casting operations in China's Yangtze River Delta cluster drive bundled procurement of grain refiners, modifiers, and cleaners with guaranteed compatibility.
- Construction:Structural casting and architectural metal applications consume standard-grade aluminum master alloys where technical service depth matters less than price per kilogram.
- Military:Defense procurement specifications impose traceability and domestic sourcing requirements that reshape supply chain configurations.
- Nuclear:Radiation-resistant component specifications in China's expanding reactor fleet pull volume toward high-purity titanium and zirconium variants with extended qualification cycles.
Transportation absorbs the bulk of volume flows; nuclear is gaining share fastest on reactor construction timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes the largest volumes of master alloys while European and North American producers retain premium-grade manufacturing positions. Smelter capacity expansions in Asia are outpacing domestic raw material availability. Regulatory divergence across major economies is fragmenting qualification protocols for cross-border suppliers.
China
Domestic reactor construction and automotive lightweighting are accelerating consumption of high-purity titanium and aluminum variants. The Ministry of Ecology and Environment enforces dual carbon goals that tighten energy intensity benchmarks for ferroalloy producers. Yangtze River Delta foundry clusters now specify bundled master alloy packages with guaranteed chemical compatibility.
United States
Aerospace backlogs and defense procurement specifications are concentrating demand for vacuum-melted titanium grades. The EPA enforces emissions thresholds that affect smelter retrofit economics across the Midwest and Southeast. Pittsburgh and Cleveland metalworking corridors remain centers for specialty alloy qualification testing.
Germany
Automotive OEM procurement consolidation is pulling volume toward full-system metallurgical service contracts. REACH substance registration and EU Green Deal carbon disclosure obligations extend lead times for new formulations entering Bavarian and Baden-Württemberg foundries. Stuttgart and Munich aerospace tier-one suppliers are adopting real-time spectral analysis for composition verification.
India
Domestic specialty steel incentives under the PLI scheme are opening procurement channels for boron and ferrotitanium variants in automotive castings. The Bureau of Indian Standards issues technical specifications that reshape import substitution patterns. Gujarat and Maharashtra foundry modernization programs are consolidating supplier relationships around technical service depth.
Japan
Powder-form titanium master alloys are penetrating medical implant and aerospace additive manufacturing supply chains. METI industrial policy supports advanced materials R&D clusters in Nagoya and Osaka. Kansai region machine builders are integrating laser-induced breakdown spectroscopy for automated quality assurance.
Master Alloys Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base stratifies between scale-driven aluminum producers and captive-source premium-grade specialists. Three archetypes dominate: integrated miners with smelter networks, European laboratory-service specialists, and aerospace-focused vacuum-melting experts. Capacity expansion and strategic partnerships represent the dominant competitive vectors as qualification requirements tighten.
Within the integrated mining tier, Rusal and Alcoa Corporation exemplify scale-driven positions anchored by captive raw material access. KBM Affilips represents the European laboratory-service archetype with technical relationship depth. AMG Advanced Metallurgical Group N.V. occupies a specialty position through controlled-source refractory metal supply.
| Leading Market Players |
|---|
| ATI Inc. |
| KBM Affilips |
| Alcoa Corporation |
| Materion Corporation |
| Rusal |
| AMG Advanced Metallurgical Group N.V. |
| Carpenter Technology Corporation |
| Umicore |
| Arconic Corporation |
| Others |
Value Chain & Pricing Dynamics
London Metal Exchange aluminum pricing cascades through master alloy value chains, compressing margins for European smelters while amplifying bargaining power for Chinese producers with captive bauxite access. Energy cost differentials between natural gas-dependent European furnaces and coal-powered Chinese operations fragment pricing tiers across qualification regimes.
Pricing Analysis
Margin tightening in standard-grade aluminum master alloys reflects electricity cost spikes across German and Italian smelter corridors. Three-tier pricing structure across aerospace-certified, automotive-qualified, and industrial-standard grades separates vacuum-melted titanium batches from aluminothermic aluminum volumes. Cost-down pressure on commodity grades accelerates because Yangtze River Delta foundries consolidate procurement under bundled metallurgical service contracts. Automotive OEMs demonstrate highest price sensitivity; nuclear component suppliers exhibit least.
Supply Chain Analysis
Domestic-content mandates in China's nuclear construction program and India's PLI-scheme foundry incentives are reshaping sourcing patterns toward qualified local suppliers. Raw material supply concentrates in China, Russia, and Australia for bauxite-alumina flows; Rwanda and DRC anchor tantalum-tungsten streams for premium grades. Production rests on tungsten concentrate, aluminum scrap, and zirconium sponge as critical inputs. Single-source vulnerability in conflict-mineral corridors threatens aerospace-grade continuity. Distribution runs through technical-service-integrated direct contracts for aerospace tiers, spot-market distributors for industrial foundries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH substance registration and carbon disclosure obligations under the EU Green Deal erect compliance moats that favor incumbent suppliers with existing dossiers and audited supply chains.
For Market Incumbents: Hedge raw material exposure through captive tungsten-tantalum positions or long-term offtake agreements with Rwandan and Australian concentrate sources. Accelerate vacuum induction melting capacity additions in Poland or Czechia to exploit EU Green Deal carbon border adjustments while defending against Chinese import substitution. Certification investment in CAAC-qualified production lines captures China's reactor construction pipeline. For New Entrants and Emerging Players: Begin with wire-feed additive manufacturing master alloys serving Japanese medical implant and German aerospace repair applications, where qualification cycles remain shorter than full aerospace-grade certification. India's PLI-scheme automotive foundry modernization offers the most penetrable procurement channel. Technical service bundling rather than price-per-kilogram competition provides the essential go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor European laboratory-service specialists with REACH-compliant dossiers and established automotive OEM relationships in Germany and Italy. Five-to-ten-year viability hinges on carbon-accounting infrastructure and dual-certification capability across FAA-EASA regimes. Watch China's MEE enforcement intensity as the inflection signal for import substitution windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tantalum Concentrate | Secures conflict-mineral-compliant supply for aerospace-grade titanium master alloys. |
| Long-term Supply Agreement with Yangtze Delta Foundries | Locks volume commitments under bundled grain-refiner-modifier-cleaner packages. |
| Joint Venture for Vacuum Induction Melting Capacity | Spreads capital burden for CAAC-qualified production serving China's reactor fleet. |
| Green Manufacturing Transition to Renewable-Powered Furnaces | Preserves EU qualification status under carbon border adjustment mechanisms. |
| Acquisition of Powder Atomization Specialist | Captures additive manufacturing feedstock growth in medical implant supply chains. |
Study Parameters
Document review covered customs trade databases, SEC 10-K filings from listed metallurgical groups, and ECHA REACH registration dossiers, complemented by interviews with plant managers at European aluminum smelters, procurement leads at German automotive Tier 1 casters, and technical directors at Japanese powder metallurgy specialists. Secondary validation drew from London Metal Exchange price archives, American Foundry Society technical specifications, and IEA energy cost benchmarks. Bottom-up volume modeling triangulated against top-down end-use consumption estimates.
Historical production and trade flows were cross-referenced against panel input from industry participants to construct the analytical framework across the analysis window. Segmentation dimensions modeled include base metal chemistry, physical form, end-use qualification tier, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements. Forecast inputs incorporated reactor construction timelines from China's National Energy Administration and automotive lightweighting mandates from EPA and EU regulatory filings.
Underlying measurement precision varies by segment; aerospace-grade titanium master alloys carry tighter precision than industrial aluminum variants due to visible qualification protocols and disclosed contract volumes. Forecasts reflect documented assumptions about energy cost trajectories, regulatory enforcement intensity, and substitution elasticities between master alloy chemistries. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Aluminum Composite Panel Market
Advanced Alloys
Global Shape Memory Materials Market
Advanced Alloys
Multi-Metal Aluminum Sandwich Panels Market
Advanced Alloys
Super Alloys Market
Advanced Alloys
Global Amorphous Alloy Band Market
Advanced Alloys
Soft Magnetic Material for Electric Vehicle Market
Advanced Alloys
Global High Performance Alloys Market
Advanced Alloys
Metal Replacement Market
Advanced Alloys
Oxide Dispersion Strengthened (ODS) Alloys Market
Advanced Alloys
Global Noble Ferroalloys Market
Advanced Alloys
Nickel Alloy Market
Advanced Alloys
Maraging Steel Market
Advanced Alloys
Automotive Aluminum Alloy (OE) Market
Advanced Alloys
Titanium Aluminide Market
Advanced Alloys
Global Quartz Countertops Market
Advanced Alloys
Quenched and Tempered Steel Market