
 Nickel Boride Alloy Market | 2026-2036
Nickel Boride Alloy Market Size, Share, and Industry Trends Forecast 2026-2036
Nickel Boride Alloy Market Intelligence
Subscription-based coating reapplication services for industrial gas turbines is realigning how nickel boride alloy value gets captured. H.C. Starck GmbH leverages its German production base to dominate high-purity powder supply for European aerospace primes. Nippon Yakin Kogyo Co., Ltd. sustains captive melting capacity that anchors its position in Asian bar and sheet segments. Sandvik AB differentiates through integrated powder-to-coating control across cutting tool applications.
Nickel boride alloy comprises an intermetallic compound of nickel and boron, typically formulated with boron content between 5% and 25% by weight and produced through vacuum induction melting or mechanical alloying to achieve hardness exceeding 1000 HV. The material serves primarily as a wear-resistant coating and catalyst substrate in high-temperature industrial environments. Powder formulations lead volume consumption due to thermal spray deposition demand from aerospace maintenance programs, while coating applications represent the fastest-expanding margin pool as service-interval extensions become a priority for turbine operators. Bar and sheet forms remain mature segments with concentrated demand from defense magnetic material programs.
EPA emissions standards and OSHA workplace exposure limits govern boron compound handling at American Elements' U.S. facilities, while REACH registration requirements in Europe constrain powder import pathways for non-EU suppliers. China's GB standards for refractory metal alloys and Japan's JIS specifications for magnetic materials create layered compliance obligations for cross-border shipments. Stakeholders must monitor how evolving dual carbon goals in China and the EU Green Deal's embodied carbon tracking reshape alloy sourcing decisions for catalyst and electrical contact applications.
Market Dynamics
Thermal spray deposition technology is compressing coating turnaround times for aerospace maintenance operators, forcing powder suppliers to synchronize production schedules with turbine overhaul cycles rather than traditional batch manufacturing rhythms.
Growth Catalysts
- Aerospace turbine blade refurbishment cycles:Commercial aviation fleets are extending engine service intervals, driving recurring demand for nickel boride thermal barrier reapplications at MRO facilities concentrated in Germany and the United States.
- REACH registration pathways:ECHA compliance requirements for boron compound imports are consolidating qualified supplier pools, advantaging established European powder producers with pre-registered dossiers.
- Mechanical alloying advances:Attritor milling techniques are achieving sub-10-micron particle distributions, enabling denser coating microstructures for high-pressure turbine applications.
Market Restraints
- Boron raw material concentration:Over 70% of metallurgical-grade boron supply routes through Turkish and Chinese refining operations, exposing alloy producers to export quota volatility and shipping cost spikes.
- Vacuum induction melting capacity scarcity:Specialized VIM furnace availability constrains high-purity ingot output, with lead times stretching 16-20 weeks at qualified foundries in Japan and Germany.
- WC-Co cemented carbide substitution:Tungsten carbide coatings retain cost advantages in lower-temperature wear applications below 800°C, limiting nickel boride penetration in general industrial tooling.
Strategic Opportunities
- Indian catalyst substrate demand:Petrochemical expansion along the Gujarat-Maharashtra industrial corridor is creating import demand for boride alloy mesh structures in hydrogenation reactor applications.
- EU Green Deal embodied carbon tracking:Scope 3 emissions disclosure requirements are favoring European-sourced powders over intercontinental shipments for aerospace coating programs.
- Subscription coating services:Turbine operators are contracting fixed-cost reapplication programs, shifting value capture from material sales to performance-guaranteed service agreements.
Industry Challenges
- Certified thermal spray operator scarcity:FAA and EASA-qualified plasma spray technicians command 40% wage premiums, constraining coating shop expansion at independent service providers.
- Legacy ERP integration with predictive maintenance platforms:Alloy suppliers must reconcile batch-oriented manufacturing systems with customer demands for real-time coating thickness telemetry and automated reorder triggers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nickel Boride Alloy Market |
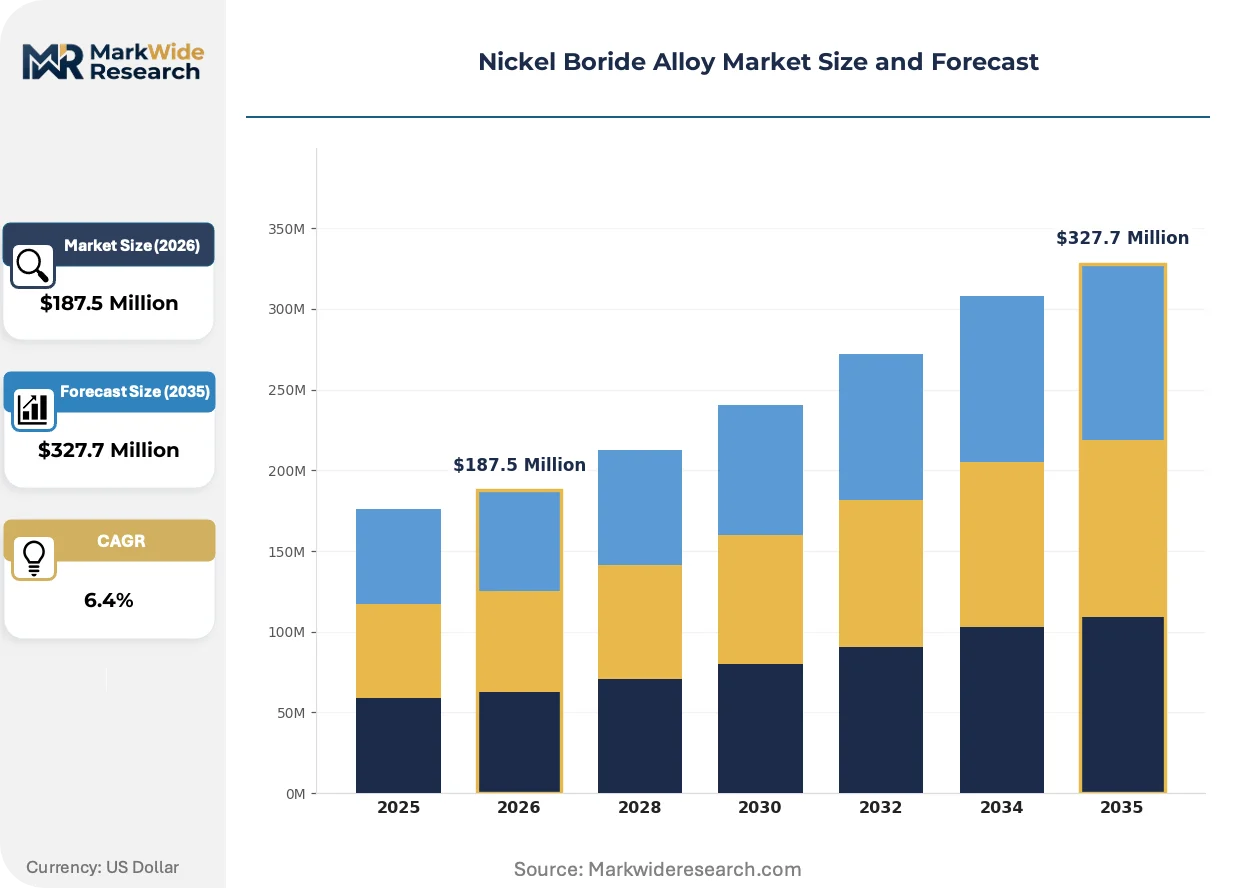
| Market Size in 2026 | $187.5 Million |
| Market Size in 2035 | $327.7 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Coating, Bar, Sheet End User: Aerospace, Automotive, Electronics, Defense Form: Solid, Liquid, Composite, Alloy Application: Catalysts, Cutting Tools, Electrical Contacts, Magnetic Materials |
| Companies Covered | Luoyang Tongrun Info Technology, H.C. Starck GmbH, KC Jones Plating Company, Nippon Denko, American Elements, Nippon Yakin Kogyo Co., Ltd., Materion Corporation, Sandvik AB, Liaoyang International Boron Alloys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nickel Boride Alloy Market Strategic Shifts & Innovations
Digital thread integration across powder production and coating deposition is collapsing quality assurance cycles, while regulatory carbon accounting and service-model reinvention are restructuring how value flows to alloy suppliers.
High-velocity oxygen fuel (HVOF) systems with in-flight particle diagnostics are unifying real-time velocity and temperature monitoring with automated spray parameter adjustment. Aerospace MRO shops in Stuttgart and Cincinnati are adopting these closed-loop systems to reduce coating variability. This convergence is unifying process control responsibility between equipment OEMs and powder suppliers, compressing traditional arm's-length procurement relationships.
EPA's evolving National Emission Standards for Hazardous Air Pollutants (NESHAP) for secondary nonferrous metals processing are tightening particulate capture requirements at boride alloy melting facilities. American producers are retrofitting baghouse systems and migrating select operations to argon-shrouded plasma melting to maintain operating permits. Bar and sheet producers serving defense magnetic material programs face the steepest compliance costs, accelerating qualification of alternative melting routes.
Turbine operators are unbundling coating reapplication from engine overhaul contracts, creating standalone procurement categories with dedicated category managers. This disintermediation of OEM service networks is visible most acutely among European low-cost carriers and independent power producers in the United States, who now negotiate directly with H.C. Starck and Sandvik for powder supply and certify third-party applicators separately.
Nickel Boride Alloy Market Segmentation
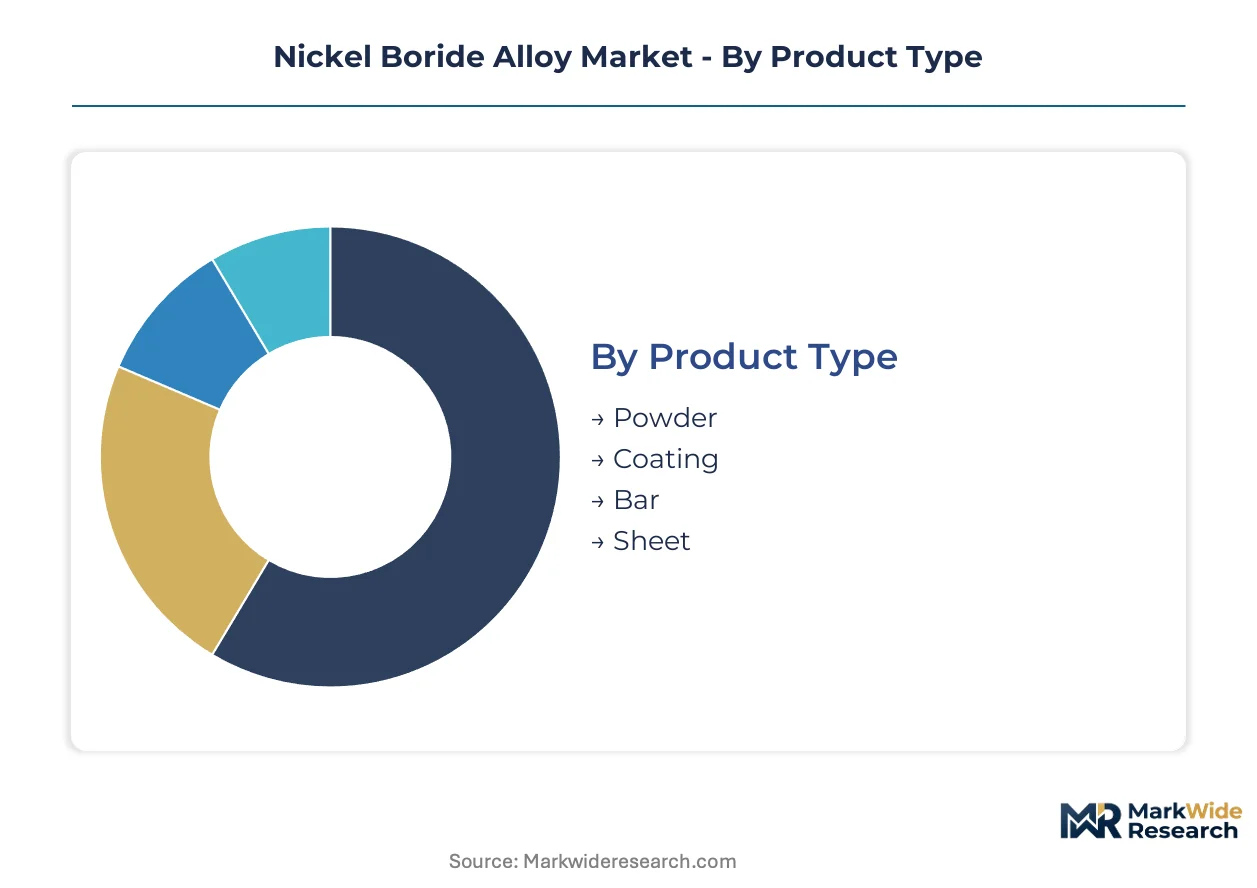
Segmentation in nickel boride alloys reveals how material form dictates value capture mechanisms and regulatory exposure. Powder suppliers synchronize production with turbine overhaul cycles, while coating service providers capture recurring revenue through performance contracts.
Product Type:
Supply concentration in vacuum induction melting capacity shapes competitive positioning across product categories, with qualified foundries in Germany and Japan commanding 16-20 week lead times.
- Powder:Thermal spray deposition formulations dominate volume consumption, with sub-10-micron particle distributions achieved through attritor milling. Aerospace maintenance programs in Germany and the United States drive procurement synchronization with turbine overhaul cycles rather than batch manufacturing rhythms.
- Coating:Thermal barrier reapplications represent the fastest-expanding margin pool as commercial aviation fleets extend engine service intervals. Subscription-based reapplication services are shifting value capture from material sales to performance-guaranteed agreements with MRO facilities.
- Bar:Defense magnetic material programs anchor concentrated demand, with BIS compliance requirements governing Indian import pathways for high-purity ingot feedstock.
- Sheet:Precision stamping applications in electrical contact assemblies require tight thickness tolerances, with JIS specifications constraining Japanese domestic supply qualification.
Powder absorbs the bulk of installed capacity; coating is expanding most quickly.
End User:
Cost tier differentiation separates specification-intensive aerospace procurement from price-sensitive automotive sourcing, with certification requirements acting as the primary segmentation mechanism.
- Aerospace:FAA and EASA-qualified plasma spray technicians command 40% wage premiums, constraining independent service provider expansion. Turbine blade refurbishment cycles create recurring demand for thermal barrier formulations at MRO facilities concentrated in Stuttgart and Cincinnati.
- Defense:Magnetic material programs for guidance systems require traceable vacuum induction melting pedigree, with NIST-traceable certification adding 15-20% cost premiums over commercial grades.
- Automotive:Catalytic converter substrate applications in heavy-duty diesel aftertreatment systems face tungsten carbide substitution pressure below 800°C operating thresholds.
- Electronics:Electrical contact miniaturization for semiconductor test sockets demands ultra-thin sheet with sub-micron surface finish specifications.
Aerospace commands the highest specification premiums; defense maintains the most stable procurement volumes.
Form:
Volume concentration in solid feedstock reflects the dominance of vacuum induction melting and mechanical alloying as primary production routes.
- Solid:Ingot and billet forms serve as feedstock for downstream powder atomization and bar rolling operations, with Turkish and Chinese boron raw material concentration exposing producers to export quota volatility.
- Composite:Nickel boride-reinforced matrices for cutting tool substrates achieve hardness exceeding 1000 HV through controlled dispersion of intermetallic phases.
- Liquid:Molten salt electrodeposition baths for precision coating applications require continuous boron content monitoring to maintain intermetallic stoichiometry within specification windows.
- Alloy:Master alloy additions for steelmaking desulfurization represent a mature, price-competitive segment with thin margin structures.
Solid forms anchor production volumes; composite formulations are climbing the fastest on cutting tool demand.
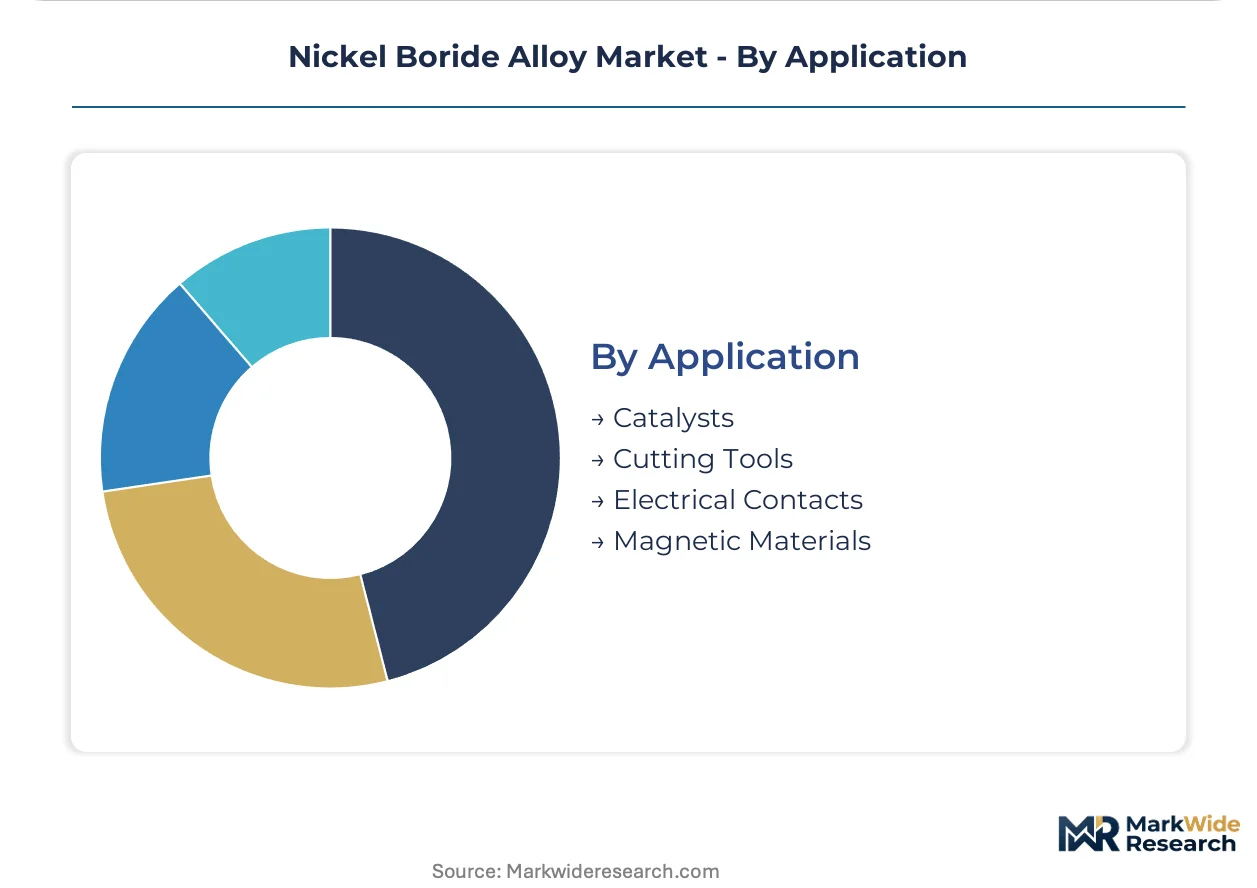
Application:
Margin structure varies sharply between catalyst substrate commodity sales and cutting tool coating service contracts, with application-specific technical support requirements driving customer stickiness.
- Catalysts:Hydrogenation reactor mesh structures for petrochemical expansion along India's Gujarat-Maharashtra industrial corridor create import demand for high-surface-area boride alloy formulations.
- Cutting Tools:Integrated powder-to-coating control enables real-time process parameter adjustment through HVOF systems with in-flight particle diagnostics, compressing quality assurance cycles at Sandvik's production facilities.
- Magnetic Materials:Defense programs require traceable vacuum induction melting pedigree with NIST-traceable certification, constraining qualified supplier pools to established European and Japanese producers.
- Electrical Contacts:Miniaturization trends in semiconductor test sockets drive demand for ultra-thin sheet with sub-micron surface finish specifications and controlled resistivity profiles.
Cutting tools capture the highest service-margin premiums; catalyst substrates maintain the broadest geographic demand base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European aerospace coating demand, with precision engineering corridors in Germany and industrial clusters across the United States, Japan, China, and India shaping regional procurement patterns for nickel boride alloys.
United States
Aerospace maintenance operators in Cincinnati and Hartford drive thermal spray powder consumption for turbine blade refurbishment cycles. EPA NESHAP standards for secondary nonferrous metals processing tighten particulate capture requirements at melting facilities. Defense magnetic material programs in the Northeast corridor sustain stable demand for vacuum induction melted bar and sheet forms.
Germany
REACH registration pathways for boron compound imports consolidate qualified supplier pools around established European powder producers. ECHA compliance requirements constrain import pathways for non-EU suppliers. The Stuttgart-Essen precision engineering corridor concentrates aerospace coating service providers and thermal spray deposition capacity for commercial aviation MRO.
Japan
JIS specifications for magnetic materials constrain domestic supply qualification for electrical contact and defense applications. METI industrial standards govern refractory metal alloy production for high-temperature industrial environments. Captive vacuum induction melting capacity in the Chubu region anchors regional supply security for bar and sheet segments.
China
GB standards for refractory metal alloys create layered compliance obligations for cross-border shipments of nickel boride powder and ingot forms. Dual carbon goals reshape alloy sourcing decisions for catalyst and electrical contact applications. Yangtze River Delta petrochemical expansion generates import substitution demand for hydrogenation reactor mesh structures.
India
BIS compliance requirements govern import pathways for high-purity ingot feedstock serving defense magnetic material programs. Petrochemical expansion along the Gujarat-Maharashtra industrial corridor creates demand for boride alloy catalyst substrates in hydrogenation reactor applications. Mumbai-Pune engineering clusters concentrate precision stamping capacity for electrical contact assemblies.
Nickel Boride Alloy Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the nickel boride alloy landscape. The market structure concentrates around vacuum induction melting capacity holders and specialized coating service providers. Three archetypes dominate: integrated powder-to-coating specialists, captive melting capacity owners, and regional trading houses. Capacity expansion and REACH registration dossier completion represent the primary competitive moves.
Among German-based producers, H.C. Starck GmbH exemplifies the integrated powder specialist archetype. Japanese fabricators Nippon Yakin Kogyo Co., Ltd. and Nippon Denko occupy positions anchored by captive melting infrastructure. American Elements represents the North American regulatory compliance-focused tier. These three names illustrate how geographic origin and corporate structure align with distinct strategic positioning in thermal barrier and magnetic material supply chains.
| Leading Market Players |
|---|
| Luoyang Tongrun Info Technology |
| H.C. Starck GmbH |
| KC Jones Plating Company |
| Nippon Denko |
| American Elements |
| Nippon Yakin Kogyo Co., Ltd. |
| Materion Corporation |
| Sandvik AB |
| Liaoyang International Boron Alloys |
| Others |
Cost & Logistics Intelligence
Aerospace MRO procurement teams concentrated in Stuttgart and Cincinnati anchor pricing power through long-term coating service contracts rather than spot powder purchases. REACH registration dossiers and ECHA compliance requirements create supplier qualification moats that insulate established European producers from price competition.
Pricing Analysis
Performance-guaranteed uptime contracts now anchor value capture as turbine operators shift from material procurement to subscription reapplication services. Three-tier pricing structure across aerospace-qualified, industrial-grade, and master alloy additive tiers reflects certification pedigree and boron purity levels. Cost compression in industrial-grade powder runs through tungsten carbide substitution pressure below 800°C thresholds. Automotive catalytic converter substrate buyers exhibit highest price sensitivity; defense magnetic material programs accept 15-20% NIST-traceable certification premiums.
Supply Chain Analysis
Dual-sourcing mandates from FAA and EASA-qualified MRO facilities require powder suppliers to maintain qualified secondary production lines across Germany and Japan. Metallurgical-grade boron feedstock draws from Turkish and Chinese refining operations, exposing alloy producers to export quota volatility. Single-source vulnerability concentrates in vacuum induction melting capacity at qualified foundries. Distribution runs through direct mill relationships with aerospace primes and authorized coating service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where REACH registration pathways and ECHA dossier completion create insurmountable barrier-to-entry moats for non-European entrants.
For Market Incumbents: Lock in powder supply contracts with Stuttgart and Cincinnati MRO clusters before subscription service models fully commoditize material margins. Deepen captive vacuum induction melting capacity in Germany and Japan to offset 16-20 week lead time scarcity. Accelerate attritor milling qualification for sub-10-micron particle distributions to defend against mechanical alloying advances from Asian competitors. For New Entrants and Emerging Players: The mid-tier pricing gap between H.C. Starck premium formulations and Chinese commodity powder offers white-space entry through BIS-compliant ingot feedstock for Indian defense magnetic material programs. Target Gujarat-Maharashtra petrochemical expansion for hydrogenation reactor mesh structures. Pursue joint qualification pathways with independent plasma spray shops lacking FAA-certified technician benches. For Investors and Strategic Acquirers: The window for entry favors REACH-registered European powder specialists with pre-validated ECHA dossiers over asset-light trading houses. Long-term viability hinges on coating service revenue recurringity rather than transactional material sales. Watch for EPA NESHAP enforcement actions against American secondary nonferrous smelters as inflection signal for domestic supply consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Dossier Completion | ECHA pre-registration locks out Turkish and Chinese powder competitors from European aerospace supply chains. |
| Backward Integration into Boron Refining | Turkish metallurgical-grade boron source control mitigates export quota volatility for German vacuum induction melting operations. |
| Subscription Coating Service Launch | Fixed-cost reapplication contracts with Cincinnati MRO facilities shift value capture from material sales to performance guarantees. |
| Attritor Milling Capacity Addition | Sub-10-micron particle distribution capability enables denser coating microstructures for high-pressure turbine applications. |
| Joint Venture with Indian Fabricator | BIS-compliant ingot production in Gujarat-Maharashtra corridor captures petrochemical catalyst substrate demand growth. |
Research Approach
Trade databases, ECHA registration filings, and aerospace MRO procurement records formed the secondary backbone for demand quantification. Primary interviews with vacuum induction melting plant managers, thermal spray coating shop operators, powder procurement leads at European aerospace primes, and defense magnetic material program officers validated supply-side constraints. Bottom-up powder consumption estimates triangulated against top-down alloy production capacity data across German, Japanese, and American facilities.
Historical trendline analysis of thermal spray deposition cycles and turbine blade refurbishment intervals informed the projection framework across the analysis window. Segmentation dimensions modeled include product form, end-use industry, boron content grade, and regional regulatory cluster. CAGRs derived from curve-fitting techniques applied to aerospace fleet age profiles and MRO capacity expansion announcements. Forecast inputs incorporated EPA NESHAP compliance cost trajectories and EU Green Deal embodied carbon tracking implementation timelines.
Underlying measurement precision varies by segment; powder and coating applications carry tighter precision than mature bar and sheet categories. Forecasts reflect assumptions around REACH registration pathway stability and vacuum induction melting capacity expansion rates. Deviation in Turkish or Chinese boron export policy would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Green Steel Market
Advanced Alloys
Maraging Steel Market
Advanced Alloys
Europe Ceramic Ball Bearings Market
Advanced Alloys
Nitinol Market
Advanced Alloys
Aluminum Die Casting Market
Advanced Alloys
Titanium Alloys Market
Advanced Alloys
Global Aluminum Foams Market
Advanced Alloys
Global Shape Memory Alloys Market
Advanced Alloys
Global Braze Alloys Market
Advanced Alloys
Chromium Carbide Overlay Plate Market
Advanced Alloys
Global Metal Injection Molding Market
Advanced Alloys
Brazing Alloys Market
Advanced Alloys
High Strength Steel (HSS) Market
Advanced Alloys
Chromium Carbide Market
Advanced Alloys
Nickel Superalloy Market
Advanced Alloys
Aluminum Composite Panel Market