
 India Aluminum Extrusion Market | 2026-2036
India Aluminum Extrusion Market Size, Share, and Industry Trends Forecast 2026-2036
India Aluminum Extrusion Market Insights
Modular framing systems for commercial facades is shifting procurement preferences among Indian builders toward pre-engineered aluminum assemblies. Jindal Aluminium Limited leverages its integrated billet-to-profile operations to serve this segment with shortened lead times. Hindalco Industries Limited anchors supply through its captive smelter network and downstream extrusion capacity. Vedanta Aluminium competes on raw material cost advantage from its Jharsuguda smelter complex.
India aluminum extrusion involves shaping aluminum alloy billets—typically 6063, 6061, or 6082 series—through heated dies to produce profiles with precise dimensional tolerances and surface finishes for structural and decorative applications. Hot extrusion dominates Indian output given its suitability for complex cross-sections in building and transportation applications. The construction end use industry leads volume absorption, with profiles commanding the largest product type share due to fenestration and curtain wall deployment. Cold extrusion technology represents a faster-growing niche where tighter tolerances for automotive and electrical connectors command premium positioning.
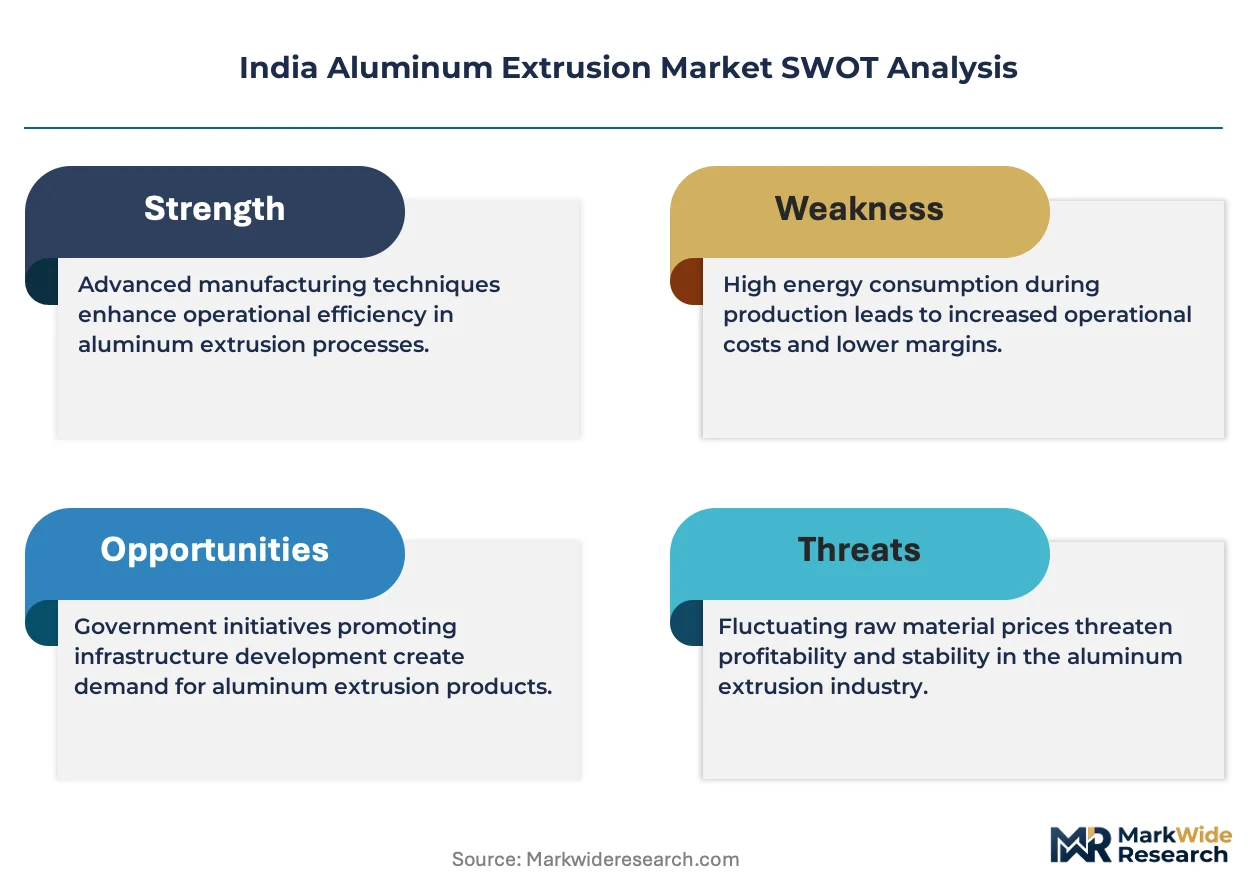
BIS standards mandate dimensional and alloy compliance for structural aluminum extrusions deployed in Indian infrastructure, while the PLI scheme for specialty steel and metals incentivizes domestic capacity expansion in value-added profiles. The CEA regulates electrical conductor specifications where aluminum extrusions substitute copper in transmission hardware. Stakeholders must monitor alloy price volatility from LME-linked primary aluminum contracts and assess backward integration into billet casting as a margin defense strategy.
Market Dynamics
Modular facade systems are compressing traditional procurement cycles as Indian builders shift from site-fabricated assemblies to pre-engineered aluminum solutions, forcing extruders to reconfigure die inventories and logistics networks around project-based delivery.
Growth Catalysts
- BIS certification mandate:Mandatory compliance for structural aluminum extrusions deployed in Indian infrastructure creates quality-based barriers that favor organized domestic manufacturers over unorganized imports.
- Automotive lightweighting:Electric vehicle platforms in Gujarat and Tamil Nadu are absorbing high-strength 6082-series profiles for battery enclosures and crash structures at expanding volumes.
- PLI scheme for specialty metals:Production-linked incentives for value-added aluminum products are accelerating capital deployment into downstream extrusion capacity across Maharashtra and Karnataka.
Market Restraints
- LME-linked primary aluminum volatility:Input cost swings from London Metal Exchange contracts compress margin predictability for extruders lacking captive smelter supply.
- Scrap import dependency:Secondary billet producers rely on aluminum scrap shipments from Middle Eastern and Southeast Asian sources, exposing supply to shipping rate fluctuations and customs clearance delays.
- Die development lead times:Complex profile geometries require 8-12 week tool fabrication cycles that conflict with construction project acceleration demands.
Strategic Opportunities
- Electrical transmission hardware:Central Electricity Authority specifications favoring aluminum over copper in conductor hardware open replacement demand across state power distribution companies.
- Cold extrusion precision components:Tighter tolerances achievable through cold forming are capturing automotive connector and electrical terminal applications at premium positioning.
- Railway rolling stock modernization:Indian Railways' aluminum-intensive trainset procurement is creating dedicated demand channels for structural hollow profiles and interior trim sections.
Industry Challenges
- Die maintenance specialist scarcity:Skilled tool steel refurbishment technicians capable of extending die life beyond 500 metric tons remain concentrated in legacy manufacturing clusters.
- Alloy homogenization furnace bottlenecks:Billet casting operations require capital-intensive soaking pit capacity that smaller extruders struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Aluminum Extrusion Market |
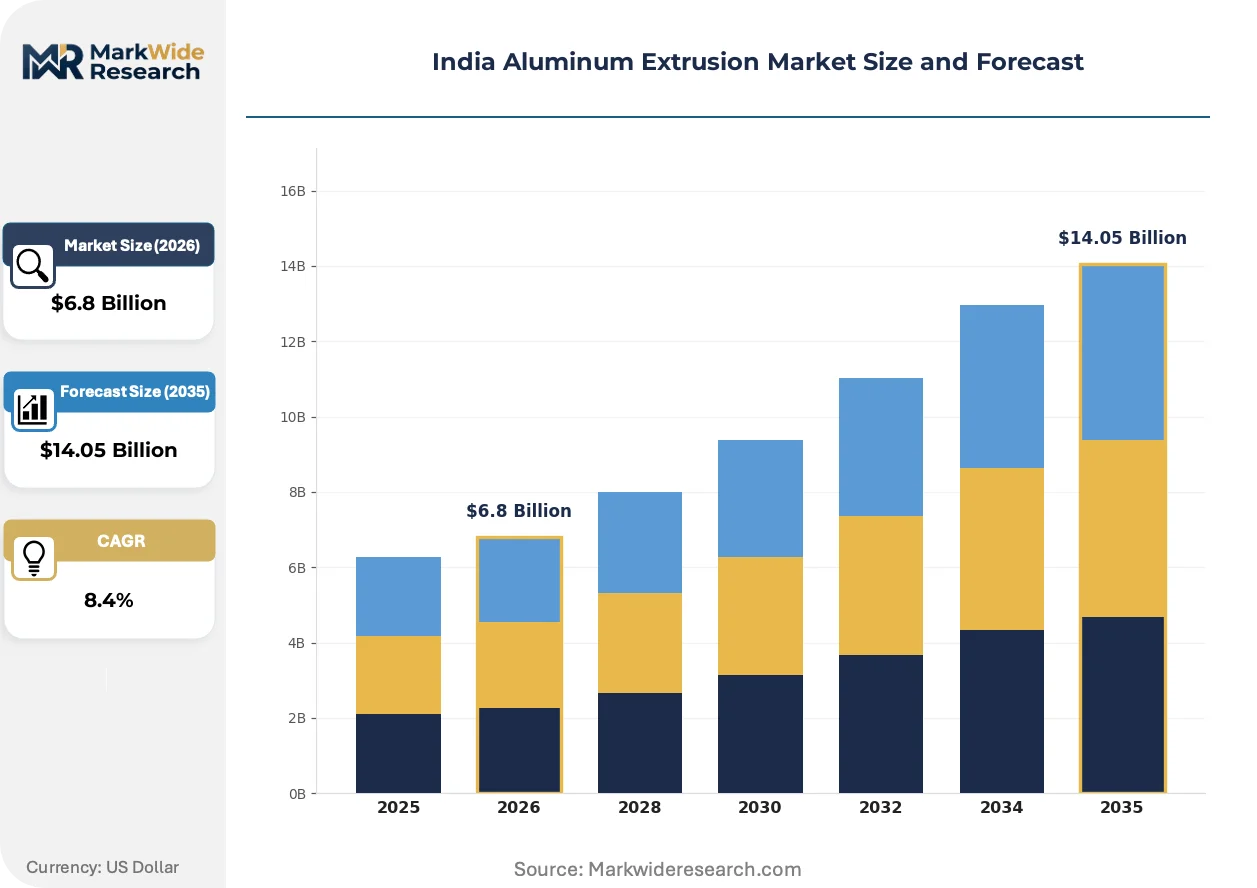
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
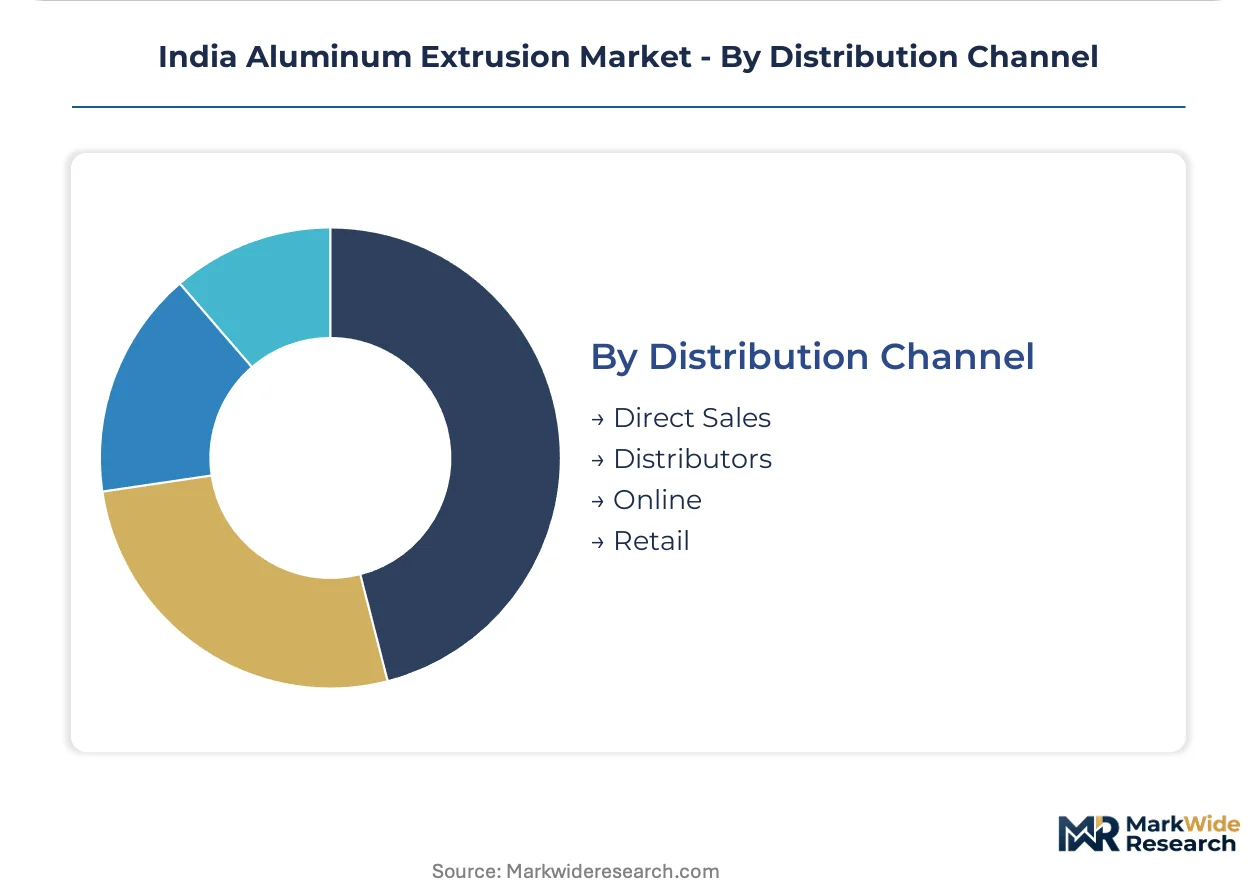
| Segmentation | Product Type: Bars, Sheets, Tubes, Profiles End Use Industry: Construction, Automotive, Transportation, Electrical Technology: Cold Extrusion, Hot Extrusion, Direct Extrusion, Indirect Extrusion Distribution Channel: Direct Sales, Distributors, Online, Retail |
| Companies Covered | KMC Aluminium, Indian Extrusions, Jindal Aluminium Limited, Eleanor Industries, KPS Aluminium & Glass, Hindalco Industries Limited, Alom Group, RY Extrusion, Vedanta Aluminium, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Aluminum Extrusion Market Trends and Innovations
Digital die design workflows and automated handling systems are compressing profile development cycles while regulatory pressure on embodied carbon intensifies scrutiny of smelter energy sources across the supply base.
Direct metal laser sintering for prototype die inserts is decentralizing tool validation timelines. Automotive tier-one suppliers in Pune and Chennai are adopting printed insert trials to compress new profile qualification from months to weeks. This capability is decentralizing geographic concentration of die-making expertise previously locked in traditional toolroom clusters.
The Bureau of Indian Standards' tightened alloy composition verification protocols are mandating spectrometer-based testing at extrusion plant entry points. Manufacturers must now document trace element compliance for every billet heat, adding capital equipment burdens but filtering substandard imports. Maharashtra-based fabricators serving curtain wall projects are responding fastest to these documentation requirements.
Builder procurement teams are consolidating vendor panels around extruders offering integrated finishing and fabrication services. Large commercial developers in Bengaluru and Hyderabad now specify anodized and powder-coated assemblies delivered site-ready, displacing traditional two-step sourcing through separate finishing job shops. This bundling preference is most visible in premium commercial facade contracts where project timelines tolerate limited supplier flexibility.
India Aluminum Extrusion Market Segmentation
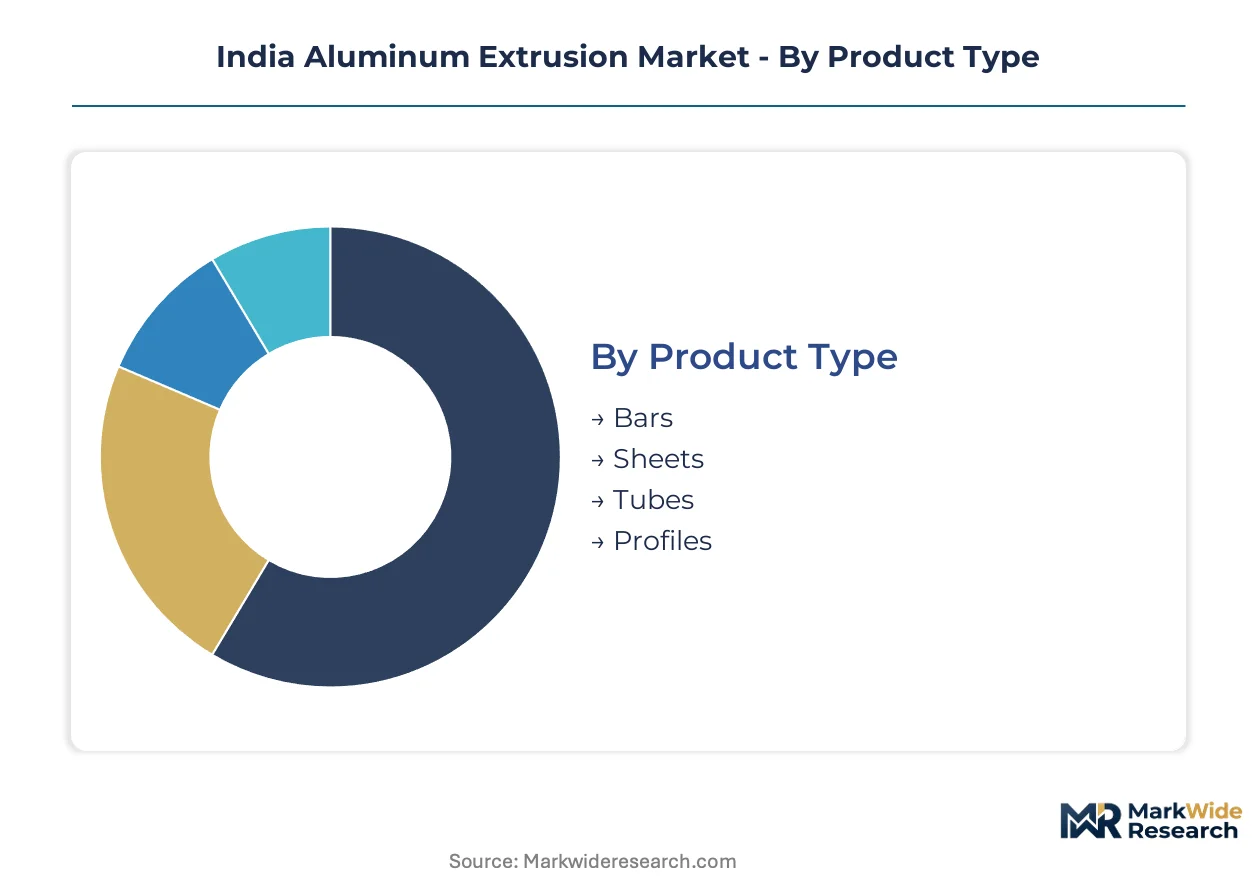
Segmentation in the India aluminum extrusion market reveals how procurement patterns diverge across fabrication methods, end-use specifications, and supply chain configurations. Understanding these divisions exposes where margin pools concentrate and which technology investments align with demand trajectories.
Product Type:
The customization spectrum spans from standardized mill forms to engineered geometries requiring die-specific investment and dimensional precision.
- Profiles:Complex cross-sections—T-slots, channels, angles, and hollow sections—serve fenestration systems and structural glazing with tight tolerances. Gujarat and Maharashtra fabricators absorb the largest volumes for commercial facade contracts where BIS compliance is mandatory.
- Tubes:Seamless and porthole-extruded hollow sections supply fluid handling, pneumatic systems, and furniture framing. Karnataka automotive clusters source 6061-series structural tubing for chassis subassemblies at expanding call-off rates.
- Bars:Solid round, square, and hexagonal stock feed machining centers and architectural hardware production. Standard alloy grades dominate procurement with limited differentiation beyond dimensional certification.
- Sheets:Flat-rolled extruded plate serves tooling bases, heat sinks, and electrical busbar applications where uniform thickness trumps geometric complexity.
Leading the category by volume: Profiles. Expanding most quickly: Tubes driven by automotive hollow section demand.
End Use Industry:
Application maturity creates divergent margin structures, from commoditized construction supply to precision-automotive qualification requirements.
- Construction:Curtain wall systems, window frames, and structural glazing absorb the dominant share of Indian extrusion output. Maharashtra and Telangana developers specify pre-anodized assemblies with documented alloy traceability under tightened BIS protocols.
- Automotive:Crash structures, battery enclosures, and trim components demand 6082-series high-strength alloys with homogenized microstructures. Tamil Nadu EV platforms and Pune commercial vehicle plants qualify suppliers through extended PPAP cycles.
- Transportation:Railway interior panels, flooring sections, and HVAC housings for Indian Railways trainsets require fire-rated alloy specifications and longitudinal weld integrity.
- Electrical:Busbar sections, switchgear housings, and transmission hardware substitute aluminum for copper under CEA conductor specifications. State power distribution companies in Gujarat and Rajasthan drive replacement procurement.
Construction dominates volume absorption. Automotive climbs fastest on lightweighting mandates.
Technology:
Process selection hinges on tolerance requirements, batch scale, and tooling amortization across the temperature and force application spectrum.
- Hot Extrusion:Billet heating to 450-500°C enables complex cross-section formation with reduced deformation resistance. This process anchors Indian output for building and transportation applications where surface finish and dimensional flexibility outweigh precision premiums.
- Cold Extrusion:Room-temperature forming achieves tighter tolerances and superior surface integrity for automotive connectors and electrical terminals. The technology commands positioning premiums but requires higher press tonnage and specialized lubrication systems.
- Direct Extrusion:Ram-forward billet movement through stationary dies constitutes the conventional approach for standard profile geometries and high-volume production runs.
- Indirect Extrusion:Moving container with stationary die reduces friction and enables more uniform material flow for challenging alloys and hollow sections with thin walls.
Hot extrusion leads installed capacity. Cold extrusion gains share fastest in precision-component supply.
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and the buyer's internal specification capability.
- Direct Sales:Large developers, automotive OEMs, and infrastructure contractors source through mill-direct contracts with dedicated account engineering and project-based die development. Maharashtra commercial facade specialists and Tamil Nadu automotive tier-ones concentrate procurement here.
- Distributors:Regional stockists hold standard profiles and bars for fabrication shops and smaller builders requiring immediate availability across Gujarat, Karnataka, and Rajasthan industrial corridors.
- Online:Digital platforms serve prototype quantities, custom-cut lengths, and catalog-standard sections for research institutions and small-scale manufacturers with limited procurement staff.
- Retail:Hardware chains and metal service centers supply hobbyist, renovation, and light fabrication demand with minimal technical specification overhead.
Direct sales capture the largest contract value. Online channels expand fastest among digitizing mid-scale fabricators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's aluminum extrusion production concentrates in western and southern states, while consumption spreads across industrial corridors. Gujarat and Maharashtra host the largest smelter-to-extrusion complexes. Regional demand patterns diverge between construction-heavy western markets and automotive-driven southern clusters.
Gujarat
Dahej and Mundra industrial zones anchor captive smelter operations feeding downstream extrusion presses. The state's port infrastructure enables scrap import access for secondary billet producers. Mundra-based fabricators supply pre-anodized facade assemblies to Mumbai and Delhi-NCR developers under compressed lead-time contracts.
Maharashtra
Mumbai-Pune corridor absorbs the highest construction-grade profile volumes for commercial high-rise glazing. BIS certification mandates tightened alloy verification protocols for structural extrusions deployed in metro rail and airport infrastructure. Thane and Nagpur extrusion plants serve curtain wall contractors with integrated powder-coating capabilities.
Karnataka
Bengaluru's precision manufacturing ecosystem drives cold extrusion demand for electrical connectors and automotive terminals. The state's machine tool industry sources 6061-series structural tubing for automation frame assemblies. Mysuru and Hubballi plants specialize in hollow sections for railway interior panel systems.
Tamil Nadu
Chennai automotive clusters qualify suppliers through extended production part approval cycles for EV battery enclosure profiles. Sriperumbudur and Oragadam industrial zones host tier-one stamping plants that call off 6082-series high-strength extrusions for crash structures. The state's wind energy sector absorbs structural tubing for turbine nacelle framing.
Telangana
Hyderabad's pharmaceutical and IT infrastructure construction drives fenestration system procurement from regional extruders. The state's electronics manufacturing clusters source heat sink profiles for server rack thermal management. Warangal-based fabricators are expanding anodizing capacity to capture premium architectural finishing contracts.
India Aluminum Extrusion Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across India's aluminum extrusion landscape. Hindalco Industries Limited and Vedanta Aluminium leverage captive primary metal supply to defend margin positions against billet-dependent processors. Three archetypes dominate: integrated smelter-extruders, independent profile specialists with backward billet casting, and toll extrusion job shops serving project-specific die development. Capacity expansion and die inventory diversification constitute the primary competitive moves as builders consolidate vendor panels.
Among integrated metal producers, Hindalco Industries Limited and Vedanta Aluminium exemplify the smelter-tied archetype with upstream control over primary aluminum supply. Jindal Aluminium Limited occupies a position within the independent specialist tier, representing fabricators that have invested in captive billet casting and multi-press extrusion complexes. These three companies anchor the organized sector's supply response to BIS-mandated quality compliance and project-based delivery requirements.
| Leading Market Players |
|---|
| KMC Aluminium |
| Indian Extrusions |
| Jindal Aluminium Limited |
| Eleanor Industries |
| KPS Aluminium & Glass |
| Hindalco Industries Limited |
| Alom Group |
| RY Extrusion |
| Vedanta Aluminium |
| Others |
Pricing and Supply Chain Analysis
Captive smelter-to-extrusion integration anchors both supply security and pricing power for Hindalco and Vedanta, while billet-dependent processors absorb LME-linked volatility that compresses margin predictability. This structural divergence forces independent extruders toward backward integration or toll-processing contracts to defend position against integrated competitors.
Pricing Analysis
Cost-down pressure on standard construction profiles accelerates because unorganized imports and secondary billet producers compete aggressively on alloy-grade substitution. Three-tier pricing structure across BIS-certified structural grades, commercial-quality mill finish, and secondary-scrap blends separates procurement channels. Brand premiums attach to documented traceability and integrated finishing services. Automotive tier-ones show least price sensitivity due to extended PPAP qualification cycles, while small fabricators in Rajasthan and Gujarat drive commoditization at the economy tier.
Supply Chain Analysis
Freight costs from Middle Eastern scrap sources and Mundra port congestion expose secondary billet producers to working capital strain during shipping rate spikes. Primary aluminum supply concentrates in India, Australia, and Indonesia, while scrap feedstock draws from UAE, Malaysia, and Saudi Arabia. Die steel and lubricant additives hinge on German and Japanese specialty chemical imports. Single-source vulnerability sits with high-performance die steel from select European toolmakers. Distribution runs through mill-direct contracts for large developers, regional stockists for standard profiles, and emerging digital platforms for prototype quantities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
BIS certification mandates have erected a cost-of-compliance moat that filters substandard imports and rewards organized domestic manufacturers with verified alloy traceability. This regulatory barrier favors incumbents with capital equipment for spectrometer-based testing and heat documentation systems.
For Market Incumbents: Acquire die maintenance specialist capabilities and captive homogenization furnace capacity to extend tool life beyond 500 metric tons and reduce billet casting bottlenecks. Consolidate vendor panels around integrated finishing services to capture premium facade contracts. Threat substitution from cold extrusion precision components demands investment in higher-tonnage presses and specialized lubrication systems. Geographic expansion into Tamil Nadu EV clusters and Karnataka electrical connector markets anchors volume defense. For New Entrants and Emerging Players: Enter via toll extrusion partnerships with project-specific die development to bypass capital-intensive billet casting requirements. White-space targets concentrate in cold extrusion precision components for automotive connectors and electrical terminals where tolerance premiums offset press investment. The most penetrable segment sits with mid-scale fabricators in Telangana and Karnataka seeking prototype-to-production flexibility. Go-to-market positioning as a BIS-compliant specialty die shop with rapid turnaround compresses qualification timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated metal conglomerates seeking downstream extrusion capacity and regional market access. Long-term viability favors smelter-tied operations or independent specialists with captive billet casting and multi-press complexes over toll-dependent job shops. Target acquisition archetype: Maharashtra or Gujarat-based extruders with integrated powder-coating and anodizing capabilities serving commercial facade contractors. Signal to watch: PLI scheme disbursement acceleration indicating policy commitment to specialty metals capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Billet Casting | Captive 6063 and 6082 alloy supply insulates margin from LME volatility and scrap import delays. |
| Cold Extrusion Capacity Addition | Higher-tonnage presses with specialized lubrication capture automotive connector premiums in Pune and Chennai clusters. |
| Integrated Finishing Service Expansion | Site-ready anodized and powder-coated assemblies displace two-step sourcing for Bengaluru commercial developers. |
| Die Inventory Diversification | Modular facade system tooling compresses project-based delivery cycles for Maharashtra curtain wall contractors. |
| Digital Platform Development | Online channels serve prototype quantities and custom-cut lengths for digitizing mid-scale fabricators. |
Research Methodology
Document review covered BIS certification protocols, CEA conductor specifications, PLI scheme disbursement records, and customs trade data, complemented by interviews with extrusion plant managers, die maintenance specialists, automotive tier-one procurement leads, and commercial facade contractors. Secondary validation drew from SEC filings of listed metal producers, Ministry of Commerce import-export databases, and Indian Railways tender documentation. Bottom-up capacity assessments across Gujarat, Maharashtra, Karnataka, Tamil Nadu, and Telangana facilities were triangulated against top-down consumption estimates from construction project pipelines and automotive platform ramp schedules.
Segmented volume and value trajectories were modeled across product type, end-use industry, technology, and distribution channel dimensions throughout the forecast period. CAGRs were derived from regression analysis of historical billet-to-profile conversion ratios, alloy price elasticity coefficients, and project-based demand call-off patterns. Industry-specific inputs included EV battery enclosure content per vehicle, railway rolling stock aluminum intensity targets, and transmission hardware substitution rates from copper to aluminum conductors.
Revisions become necessary when LME primary aluminum volatility exceeds historical bands, BIS enforcement intensity shifts, or PLI scheme eligibility criteria change. Forecasts reflect documented assumptions regarding alloy homogenization capacity expansion, die steel availability, and scrap import clearance efficiency. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Cermet Market
Advanced Alloys
Sintered Steel Market
Advanced Alloys
Global Amorphous Alloy Band Market
Advanced Alloys
Tantalum Carbide Market
Advanced Alloys
Powder Metallurgy Components Market
Advanced Alloys
Quartz Kitchen Countertops Market
Advanced Alloys
Global Aluminum Silicon Carbide (Alsic) Market
Advanced Alloys
Molybdenum Disilicide Market
Advanced Alloys
Forgings Market
Advanced Alloys
Global Metal Injection Molding Market
Advanced Alloys
Global Braze Alloys Market
Advanced Alloys
Europe Aluminum Casting Market
Advanced Alloys
Europe Green Steel Market
Advanced Alloys
Battery Alloys Market
Advanced Alloys
Aramid Prepreg Market
Advanced Alloys
Ultra High Strength Steel Market