
 Aluminum Chemicals Market | 2026-2036
Aluminum Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Chemicals Market Intelligence
The increasing use of long-term project financing for large-scale municipal water infrastructure is tilting the competitive landscape toward suppliers with proven scale and reliability. Alcoa Corporation leverages its backward integration into bauxite mining to ensure cost control and supply stability. BASF SE competes on specialized formulations for high-value applications like catalysts and coatings. United Company Rusal Plc anchors its market position through significant production capacity and control over key Eurasian supply routes.
Aluminum chemicals are a group of compounds derived primarily from the processing of bauxite ore through methods like the Bayer process. These materials, such as aluminum sulfate, function as highly effective coagulants and flocculants in various industrial processes. Their primary purpose is to remove suspended solids and impurities from liquids. Aluminum sulfate remains the dominant product type due to its extensive use in water treatment. The pulp & paper application represents a mature but stable demand source for these chemicals.
Regulatory frameworks including the US EPA's National Primary Drinking Water Regulations and the EU's REACH directive dictate purity standards and permissible applications. These rules directly influence demand for specific grades of aluminum chemicals, particularly in the water treatment and pharmaceutical sectors. Producers must therefore focus on securing stable raw material supply chains while adapting their product portfolios to meet evolving environmental and health-based compliance mandates across key markets.
Market Dynamics
The central force shaping the aluminum chemicals market is the increasing stringency of global water quality regulations. This regulatory pressure, particularly for industrial and municipal wastewater, is creating a distinct demand divergence between standard and high-purity grades of coagulants.
Growth Catalysts
- Stricter Wastewater Regulations:Mandates such as the EU's Urban Waste Water Treatment Directive are compelling municipalities and industries to invest in more effective water treatment solutions, directly benefiting aluminum sulfate and polyaluminum chloride demand.
- Pulp & Paper Demand Stability:The pulp and paper industry remains a significant and stable consumer of aluminum sulfate for sizing and retention aid applications, providing a consistent demand floor for producers.
- Industrialization in Asia:Rapid industrial infrastructure development in China and India necessitates greater use of aluminum chemicals in construction, manufacturing, and environmental management, particularly for high-purity grades.
Market Restraints
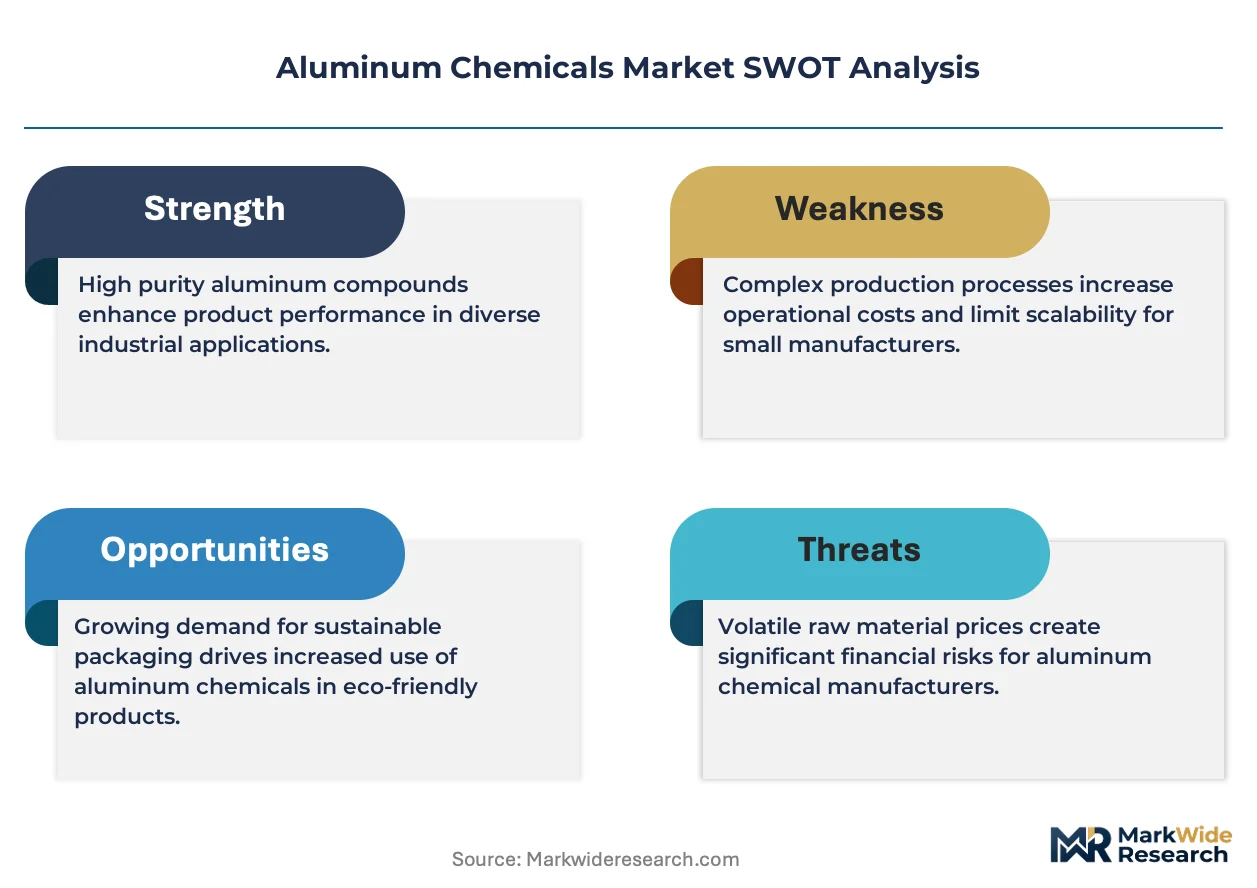
- Bauxite Price Volatility:As the primary raw material, the price and availability of bauxite ore are subject to geopolitical factors and mining disruptions, creating significant input cost volatility for producers using the Bayer process.
- Energy-Intensive Production:The conversion of bauxite to alumina and subsequent chemicals is an energy-intensive process, exposing manufacturers' margins to fluctuations in global electricity and natural gas prices.
- Substitution from Alternatives:In certain water treatment applications, aluminum chemicals face competition from iron-based coagulants and organic polymers, which can offer performance or cost advantages under specific pH and water conditions.
Strategic Opportunities
- High-Purity Alumina Applications:Growing demand for synthetic sapphires in electronics, separators in lithium-ion batteries, and advanced ceramics opens a high-value market for non-metallurgical, high-purity alumina products.
- Pharmaceutical Grade Chemicals:Tightening purity standards for pharmaceutical excipients and antacids creates an opportunity for specialized aluminum hydroxide and oxide gels that meet stringent pharmacopeia requirements. *Water Infrastructure in Southeast Asia: Nations across Southeast Asia are investing heavily in new and upgraded municipal water and sanitation systems, representing an underpenetrated market for aluminum-based coagulants.
Industry Challenges
- Complex Global Logistics:Managing the global supply chain, which involves shipping bauxite from mining regions like Australia and Guinea to processing plants in North America and Europe, presents significant logistical and cost challenges.
- Navigating Divergent Regulations:Producers must contend with a complex web of varying international chemical regulations, such as the EU's REACH and the US EPA's TSCA, adding to compliance costs and administrative burdens.
- High Capital Expenditure:The construction and modernization of Bayer process refineries and downstream chemical plants require substantial capital investment, creating high barriers to entry and limiting capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Chemicals Market |
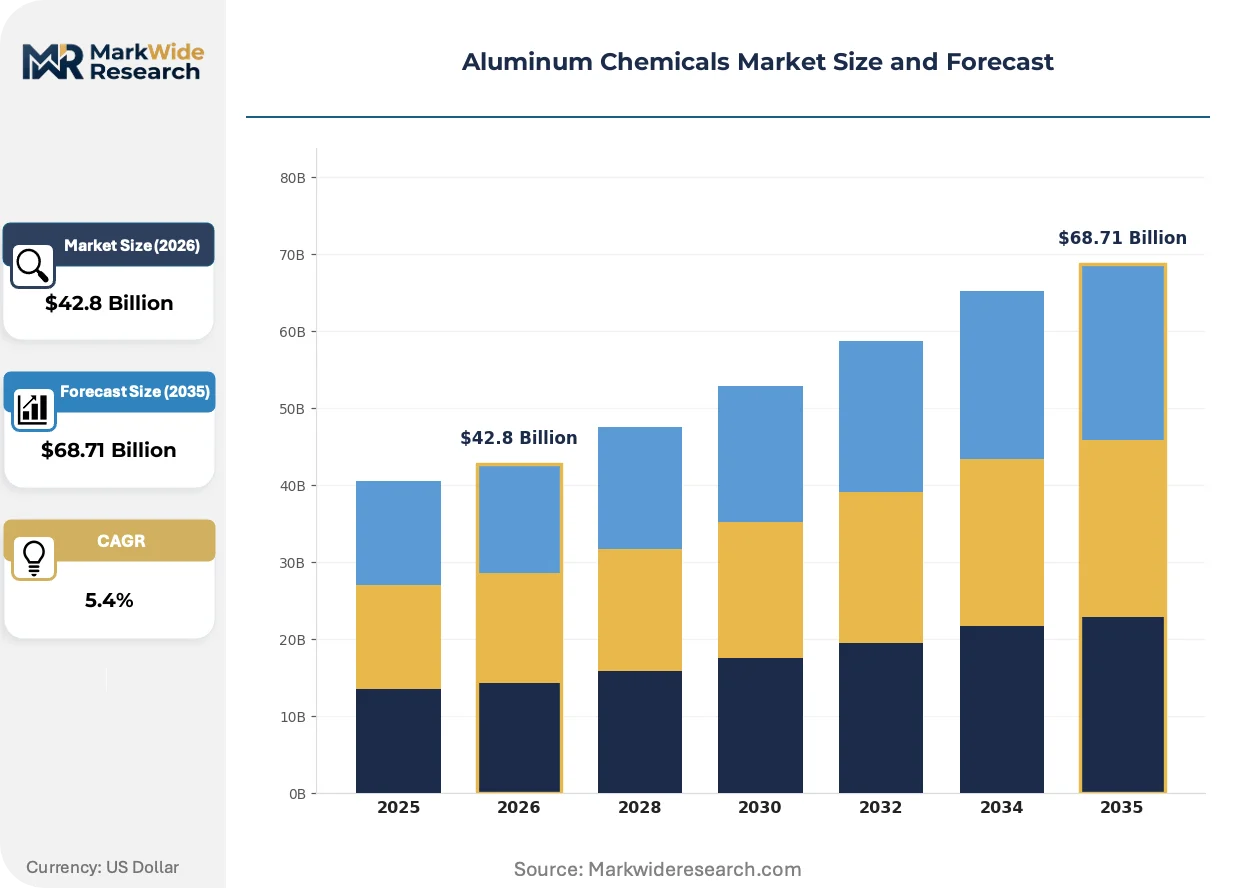
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $68.71 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Sulfate, Aluminum Chloride, Aluminum Nitrate, Aluminum Phosphate Application: Water Treatment, Pulp & Paper, Paints & Coatings, Textile End Use Industry: Construction, Food & Beverage, Pharmaceuticals, Agriculture Form: Granular, Powder, Liquid, Anhydrous |
| Companies Covered | Cabot Corporation, United Company Rusal Plc, Alcoa Corporation, Merck KGaA, J.M. Huber Corporation, Aluminum Corporation of China Limited, Evonik Industries AG, W.R. Grace & Co., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Chemicals Market Strategic Shifts & Innovations
The market's evolution is defined by a push toward higher-purity formulations and sustainable production methods. This shift responds directly to advanced manufacturing requirements and increasingly stringent environmental mandates that favor specialized chemical solutions over commoditized grades.
Specialty aluminum hydroxides function as highly effective non-halogenated flame retardants and smoke suppressants. End-use industries like electronics and construction materials are increasing their use to meet stricter fire safety codes. The market is migrating from commoditized, lower-grade fillers toward these engineered hydroxides that provide specific performance benefits beyond basic flame retardancy.
China's "dual carbon goals" and associated policies from the Ministry of Ecology and Environment (MEE) are tightening controls on industrial effluent. This forces high-polluting sectors, including textiles and petrochemicals, to upgrade their wastewater treatment capabilities. The industrial water treatment segment is most affected, now requiring more effective polyaluminum chloride formulations to achieve compliance.
A notable behavioral shift involves the move toward long-term, fixed-volume supply agreements for high-purity aluminum chemicals. This departure from opportunistic spot-market purchasing is favoring large-scale producers who can guarantee supply chain stability and quality consistency. The trend is most pronounced in the semiconductor and pharmaceutical sectors in Taiwan and South Korea, where material purity and uninterrupted supply are critical.
Aluminum Chemicals Market Segmentation
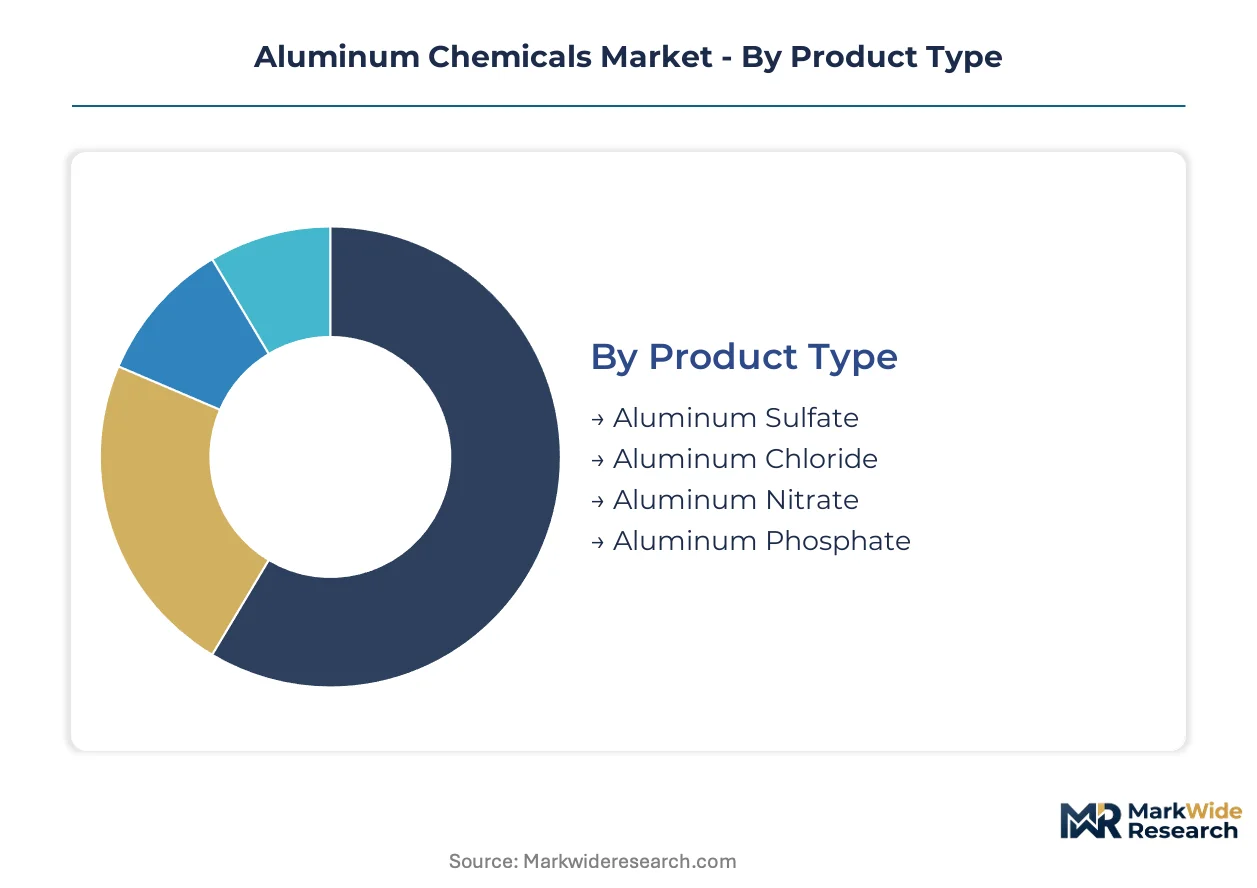
Understanding the aluminum chemicals market through segmentation reveals the specific drivers and applications shaping demand across diverse industries. This granular view highlights where innovation and regulatory compliance exert the strongest influence on product development and market penetration.
Product Type:
The product type segment illustrates a spectrum ranging from mature, high-volume compounds to emerging specialized formulations meeting niche industrial needs.
- Aluminum Sulfate:This compound, also known as alum, is a widely used coagulant in water purification due to its efficacy in removing suspended particles and impurities. Demand concentrates heavily in municipal water treatment plants and industrial wastewater facilities across China and India, driven by environmental mandates.
- Aluminum Chloride:A powerful Lewis acid, aluminum chloride functions as a catalyst in organic synthesis, a flocculant in wastewater treatment, and a component in antiperspirants. Its demand is growing in industrial wastewater treatment applications, particularly in Europe, where stricter discharge regulations necessitate advanced purification methods.
- Aluminum Nitrate:This salt finds application as a nitrating agent, a mordant in textile printing, and a corrosion inhibitor in various industrial processes.
- Aluminum Phosphate:Used as a flux in ceramics, a cement additive, and an antacid in pharmaceutical preparations, aluminum phosphate serves specialized industrial and medical needs.
Aluminum Sulfate handles the majority of throughput; Aluminum Chloride is the fastest mover on share.
Application:
The application segment delineates the diverse functional roles aluminum chemicals fulfill across critical industrial and environmental processes.
- Water Treatment:Aluminum chemicals, primarily aluminum sulfate and polyaluminum chloride, are fundamental for coagulation and flocculation in both drinking water purification and industrial wastewater remediation. This application is critical for public health and environmental compliance, especially with the EU's Urban Waste Water Treatment Directive.
- Pulp & Paper:The pulp and paper industry utilizes aluminum sulfate for sizing, retention aid, and effluent treatment, contributing to paper strength and process efficiency. This sector represents a mature but stable demand source, providing a consistent baseline for producers.
- Paints & Coatings:Aluminum compounds serve as pigments, extenders, and flame retardants in paints and coatings, enhancing durability and fire resistance.
- Textile:In the textile industry, aluminum chemicals act as mordants, helping dyes adhere to fabrics, and as flame retardants for specialized textiles.
Demand concentrates heavily in water treatment, while the pulp & paper sector provides a consistent baseline.
End Use Industry:
The end-use industry segment reflects how different economic sectors integrate aluminum chemicals into their core operations and products.
- Pharmaceuticals:High-purity aluminum hydroxide and aluminum oxide gels are critical as antacids, vaccine adjuvants, and excipients in drug formulations. This sector demands stringent purity standards and consistent supply, particularly from manufacturers meeting US FDA and European EMA requirements.
- Construction:Aluminum chemicals are incorporated into construction materials as admixtures, fire retardants, and waterproofing agents, enhancing material performance and safety. Rapid industrialization in China and India drives substantial demand for these applications.
- Food & Beverage:Aluminum compounds serve as leavening agents, firming agents, and clarifying agents in the food and beverage industry, adhering to specific food safety regulations.
- Agriculture:In agriculture, aluminum sulfate is used to adjust soil pH, and certain aluminum compounds act as fertilizer components or pest control agents.
Pharmaceuticals present a high-value growth driver, with construction offering substantial volume opportunities.
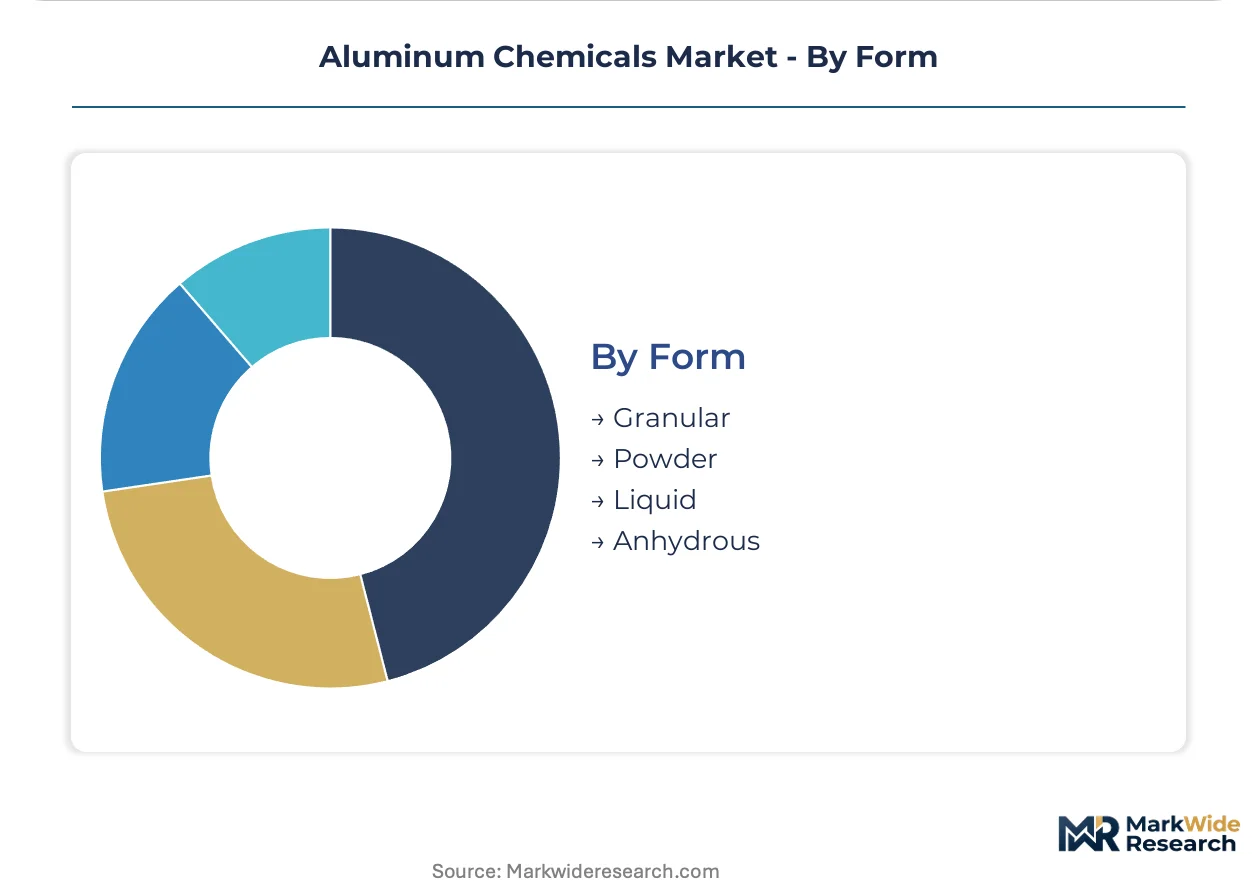
Form:
The form segment categorizes aluminum chemicals by their physical state, which dictates handling, storage, and application methods.
- Liquid:Liquid forms offer ease of handling, precise dosing, and suitability for automated feed systems in large-scale industrial and municipal applications. Their use is prevalent in modern water treatment facilities across North America and Europe.
- Powder:Powdered aluminum chemicals provide advantages in terms of transport efficiency, storage stability, and concentrated active ingredient content. This form is often preferred for bulk shipping and applications requiring minimal water content.
- Granular:Granular forms offer reduced dust, improved flowability, and controlled dissolution rates, making them suitable for specific industrial processes.
- Anhydrous:Anhydrous forms are devoid of water, offering higher purity and reactivity for specialized chemical synthesis and moisture-sensitive applications.
Liquid forms are preferred for operational convenience, while powder forms offer logistical advantages for bulk transport.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global aluminum chemicals market exhibits a complex trade dynamic, with some regions acting as significant net exporters of raw materials and intermediate products, while others primarily import for downstream processing. This balance shapes localized supply chains and influences pricing across diverse end-use sectors. Demand patterns vary significantly by geography, driven by differing industrialization rates and regulatory environments.
China
China's expanding industrial base requires substantial aluminum chemicals for manufacturing and environmental management. The Ministry of Ecology and Environment's "dual carbon goals" mandate stricter controls on industrial effluent. Manufacturing hubs in the Yangtze River Delta actively upgrade wastewater treatment capabilities, increasing demand for polyaluminum chloride.
United States
Municipal water treatment facilities and the pharmaceutical sector drive significant aluminum chemical consumption in the United States. The US EPA's National Primary Drinking Water Regulations enforce stringent purity standards for drinking water. Chemical producers in the Northeast Corridor focus on specialized formulations and high-purity grades for these demanding applications.
Germany
Advanced manufacturing and high-purity chemical needs underpin demand in Germany. The EU's Urban Waste Water Treatment Directive compels industries to invest in sophisticated water purification systems. Industrial clusters in the Rhine-Ruhr region consume aluminum chloride for wastewater treatment and specialized chemical synthesis.
India
Rapid industrialization and expanding urban water infrastructure necessitate substantial aluminum chemical volumes across India. BIS standards increasingly influence product specifications for water treatment chemicals and industrial applications. Major chemical manufacturing zones in Maharashtra and Gujarat see significant demand for aluminum sulfate in municipal water projects.
Japan
Electronics manufacturing and advanced materials production generate demand for high-purity aluminum chemicals in Japan. JIS standards dictate quality and performance requirements for chemical inputs across various industries. The Kanto region, with its concentration of technology companies, remains a critical consumption area for specialized aluminum compounds.
Aluminum Chemicals Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying essential materials to a diverse end-user base. The aluminum chemicals market exhibits a tiered structure, with large integrated producers controlling raw material sources and smaller, specialized firms focusing on niche applications. Competitive dynamics involve both backward integration to secure bauxite supply and forward integration into specialized formulations. Capacity expansion and strategic partnerships remain prevalent competitive moves among market participants.
Within the integrated producers, Alcoa Corporation exemplifies a strategy anchored by backward integration into bauxite mining, ensuring cost control and supply stability across its operations. United Company Rusal Plc, a significant Russian producer, anchors its market position through substantial production capacity and control over key Eurasian supply routes for its primary aluminum and chemical derivatives. German chemical giant BASF SE occupies a position focused on specialized formulations for high-value applications, including catalysts and coatings, representing the premium end of the market for advanced aluminum compounds. These players collectively demonstrate the market's reliance on both scale and specialized product development.
| Leading Market Players |
|---|
| Cabot Corporation |
| United Company Rusal Plc |
| Alcoa Corporation |
| Merck KGaA |
| J.M. Huber Corporation |
| Aluminum Corporation of China Limited |
| Evonik Industries AG |
| W.R. Grace & Co. |
| BASF SE |
Cost & Logistics Intelligence
China's industrial capacity dynamics influence downstream pricing power for aluminum chemicals, particularly for standard grades used in water treatment. This concentration affects global supply availability and can lead to localized pricing fluctuations. The market structure reflects a tension between commodity-driven pricing for basic chemicals and value-based pricing for high-purity formulations.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake agreements for high-purity aluminum chemicals. Pricing stratifies across pharmaceutical-grade purity levels, industrial-grade applications, and volume scale. Upward pricing pressure stems from bauxite price volatility and energy-intensive production costs. Municipal water treatment facilities are most price-sensitive for standard aluminum sulfate, while pharmaceutical and semiconductor manufacturers prioritize supply stability and certified purity over cost.
Supply Chain Analysis
Geopolitical instability affecting bauxite-rich regions like Guinea and Australia dominates raw material supply risk. The supply chain draws from concentrated bauxite mining operations in these countries, with processing primarily in China, Europe, and North America. Energy price fluctuations, particularly for natural gas and electricity, introduce significant input cost volatility. Distribution runs through global logistics networks, increasingly secured by long-term, fixed-volume supply agreements for high-purity grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires a strong substitution defense, as incumbents must navigate competition from iron-based coagulants and organic polymers. Strategic focus on specialized applications and supply chain resilience will be critical for sustained growth.
For Market Incumbents: Insulate core market share by deepening backward integration into bauxite mining operations. Invest in research and development for advanced polyaluminum chloride formulations that offer superior performance in challenging wastewater conditions. Secure long-term energy supply contracts to mitigate exposure to volatile electricity and natural gas prices. Pursue strategic partnerships with municipal water authorities to guarantee consistent demand for standard products.
For New Entrants and Emerging Players: Southeast Asia's underpenetrated municipal water infrastructure represents a significant white-space opportunity for new entrants. Target specialized applications requiring high-purity aluminum hydroxide gels for pharmaceutical excipients, meeting stringent pharmacopeia requirements. A go-to-market angle focusing on customized formulations that address specific regional water quality challenges and compliance mandates can differentiate offerings.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized chemical producers with proprietary formulations for advanced applications. Long-term viability hinges on the essential role of aluminum chemicals in water treatment and high-purity manufacturing processes. Acquisition targets should include firms with strong intellectual property in flame retardants or advanced ceramics. Increased M&A activity in high-purity alumina or advanced water treatment chemical producers is a critical signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for High-Purity Alumina | Increases supply for electronics and lithium-ion battery separators, meeting advanced manufacturing demand. |
| Backward Integration into Bauxite Mining | Ensures cost control and supply stability, mitigating raw material price volatility for producers. |
| Green Manufacturing Transition | Reduces energy consumption and waste, aligning with stricter environmental regulations and corporate sustainability goals. |
| Long-term Supply Agreements with Water Utilities | Provides stable demand and predictable revenue streams for standard aluminum chemicals. |
| Joint Venture for Pharmaceutical-Grade Production | Accelerates market entry and regulatory compliance for high-value aluminum hydroxide and oxide gels. |
Research Approach
Findings reconcile primary fieldwork against secondary review of environmental agency reports, customs data, and company 10-K filings. This involved in-depth interviews with plant managers, procurement leads at water treatment facilities, R&D directors for specialty chemicals, and regulatory compliance officers. The analysis triangulated insights from these diverse sources using both bottom-up and top-down validation approaches.
Forecast inputs considered include bauxite production trends, global water infrastructure spending, and regional regulatory mandates across the modeling period. The analytical framework integrated segmentation dimensions such as product type, application, end-use industry, form, and regional regulatory trends. Compound Annual Growth Rates were derived from historical data extrapolation, expert consensus, and projected regulatory impact on demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by specialized chemical startups or large diversified players would shift outcomes. Unforeseen geopolitical events impacting bauxite supply or rapid technological breakthroughs in alternative coagulants represent specific risk factors. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Airbag Propellant Chemicals Market
Chemicals
Global Methylene Chloride Market
Chemicals
Xanthates Market
Chemicals
Flatting Agents Market
Chemicals
Global Cysteine Market
Chemicals
Tromethamine Market
Chemicals
Elemental Fluorine Market
Chemicals
Asia Pacific Waterproofing Chemicals Market
Chemicals
1, 4 Butanediol Market
Chemicals
Global Acetic Anhydride Market
Chemicals
SLS and LABSA Market
Chemicals
LAMEA Dimethyl Phosphate Market
Chemicals
Global Amines Market
Chemicals
Isooctyl Alcohol Market
Chemicals
Italy Laboratory Chemicals Market
Chemicals
Para Cresol Market