
 Tromethamine Market | 2026-2036
Tromethamine Market Size, Share, and Industry Trends Forecast 2026-2036
Tromethamine Market Analytics
A shortage of trained fermentation chemists and downstream processing engineers is unwinding capacity expansion timelines at several tromethamine suppliers. ANGUS Chemical Company leverages its integrated nitroalkane platform to control raw material costs across North American operations. HOPAX anchors its position through specialized cGMP manufacturing for injectable-grade tromethamine in Taiwan. BioSpectra, Inc. differentiates by sustaining US-based production with multi-compendial certification for pharmaceutical and biotech end users.
Tromethamine, or tris(hydroxymethyl)aminomethane, is a crystalline organic compound with a molecular formula of C4H11NO3 and a pKa of 8.07 at 25°C, functioning as a biological buffer to maintain stable pH in cell culture media, protein formulations, and injectable drug products. Its primary industrial purpose centers on stabilizing active pharmaceutical ingredients and biologics against acid-base degradation during manufacturing, storage, and administration. The injection segment leads current revenue as parenteral biologics require the highest purity grades, while powder forms are gaining fastest in cell culture media as serum-free processes expand. Hospitals dominate end-user demand through cardiac care and metabolic disorder applications, though homecare delivery is emerging as ambulatory infusion protocols reduce inpatient stays.
The US FDA enforces ICH Q3D elemental impurity limits and USP-NF monograph compliance for tromethamine used in drug products, while the EMA applies comparable standards through the European Pharmacopoeia that govern market access for EU-bound supply. China's NMPA now requires domestic registration of imported excipients, creating additional documentation burdens for foreign manufacturers serving Chinese biopharma clients. Stakeholders must monitor evolving pharmacopoeial harmonization between USP, EP, and ChP standards, as diverging test methodologies could fragment quality specifications and complicate global supply strategies.
Market Dynamics
The tromethamine market is tightening around cGMP certification requirements as biopharma manufacturers demand single-source excipient accountability for parenteral drug filings. This regulatory compression is forcing supplier consolidation while simultaneously fragmenting regional supply strategies.
Growth Catalysts
- mRNA platform expansion:Peptide and nucleic acid drug manufacturers require high-purity buffering agents for lipid nanoparticle stabilization, pulling pharmaceutical-grade tromethamine into critical formulation workflows.
- ICH Q3D harmonization:Elemental impurity testing alignment across USP, EP, and ChP standards reduces qualification burdens for multi-regional drug filings, accelerating excipient standardization.
- Serum-free cell culture transition:Bioprocess engineers are eliminating animal-derived components, creating specification demand for synthetic buffering systems in mammalian cell production.
Market Restraints
- Nitroalkane feedstock volatility:Tromethamine synthesis depends on formaldehyde and nitromethane pricing, exposing margins to petrochemical derivative swings.
- Taiwan manufacturing concentration:Injectable-grade production clusters on the island, creating geographic risk exposure for parenteral drug supply security.
- Phosphate buffer substitution:Some generic injectable developers revert to traditional phosphate systems where pH tolerance permits, capping tromethamine penetration in cost-sensitive segments.
Strategic Opportunities
- India CDMO buildout:Domestic contract manufacturers are scaling peptide API capacity, creating demand for localized excipient sourcing under CDSCO import substitution incentives.
- Continuous bioprocessing adoption:Perfusion cell culture systems require real-time pH management, opening specification opportunities for in-line buffer supplementation.
- Homecare infusion expansion:Ambulatory delivery of enzyme replacement and metabolic therapies is extending buffer demand into patient-administered drug formats.
Industry Challenges
- Fermentation chemist scarcity:Downstream purification expertise shortages are delaying capacity ramp timelines at multi-compendial suppliers.
- Dual pharmacopoeial registration:Simultaneous USP-NF and EP compliance documentation extends qualification cycles for new manufacturing sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tromethamine Market |
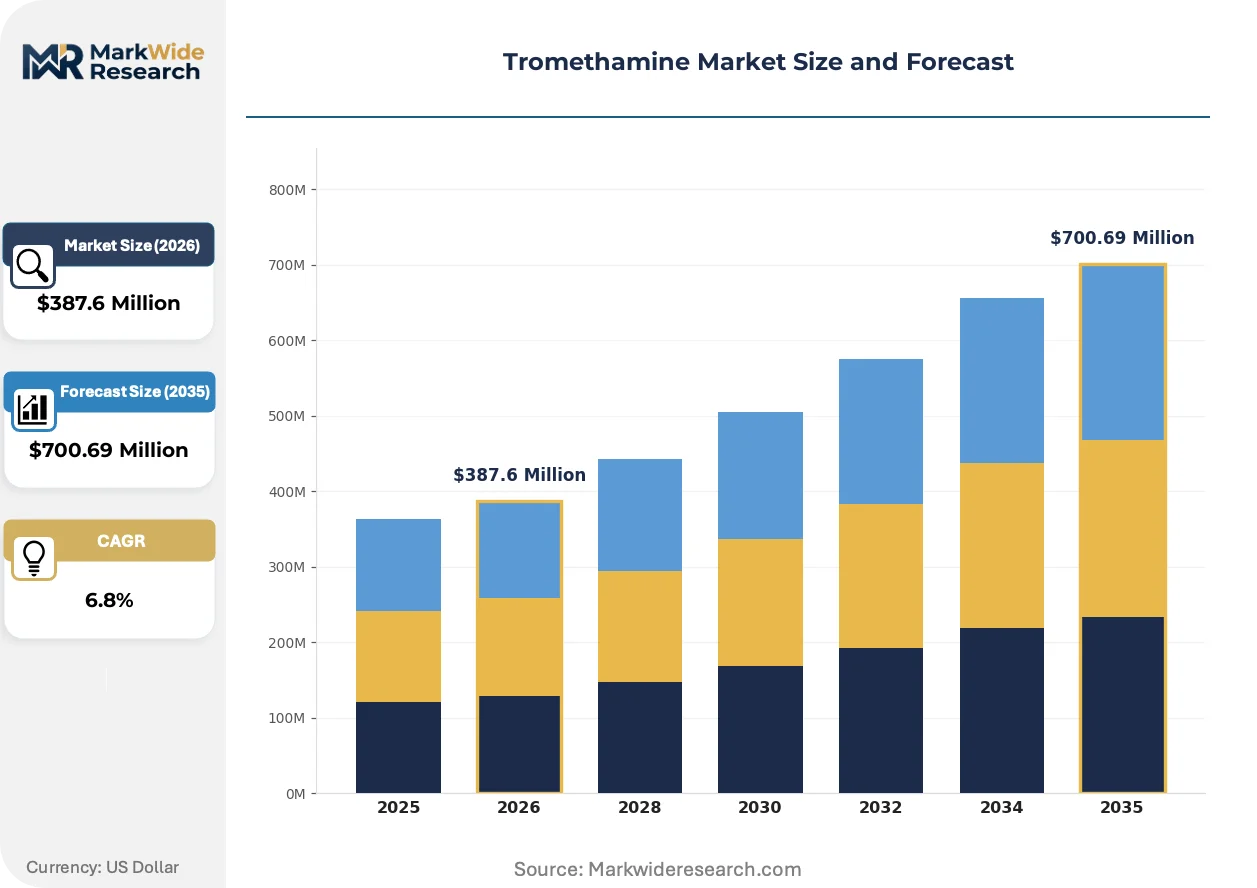
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection, Powder, Solution, Concentrate Application: Cardiac Care, Metabolic Disorders, Respiratory Support, Fluid Replacement End User: Hospitals, Clinics, Ambulatory Surgical Centers, Homecare Delivery Mode: Intravenous, Subcutaneous, Oral, Topical |
| Companies Covered | ANGUS Chemical Company, HOPAX, BioSpectra, Inc., Tokyo Chemical Industry Co., Ltd., FARMAK, a.s., Metrochem API Pvt Ltd, Spectrum Chemical Mfg. Corp., Thermo Fisher Scientific Inc., Hunan Dongting Pharmaceutical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tromethamine Market Evolving Landscape
Buffer chemistry is converging with bioprocess automation as real-time analytical technologies reshape how pH stability is monitored and maintained across manufacturing scales. These shifts are compressing specification tolerance bands while expanding application boundaries.
Single-use bioreactor systems are displacing stainless steel infrastructure in clinical-scale production, embedding pre-sterilized tromethamine buffer bags directly into closed processing trains. Contract manufacturers adopting these disposable formats are eliminating clean-in-place validation requirements. This displacement is compressing capital barriers for multi-product facilities while concentrating buffer specification authority with single-use system integrators.
EMA's revised Annex 1 guidelines on sterile manufacturing are mandating enhanced contamination control strategies for excipient handling in Grade A/B environments. Buffer suppliers must now demonstrate closed-system transfer protocols and environmental monitoring data in regulatory submissions. Parenteral drug manufacturers in the European Union are responding by qualifying suppliers with dedicated isolator filling lines, raising the technical barrier for market participation.
Long-term supply agreements are replacing spot purchasing for critical excipients as biopharma procurement teams prioritize supply continuity over unit cost optimization. Large molecule developers are locking in multi-year tromethamine contracts with audit rights and manufacturing site disclosure. This behavior shift is most visible among US-based gene therapy developers facing FDA scrutiny of excipient change control documentation.
Tromethamine Market Segmentation
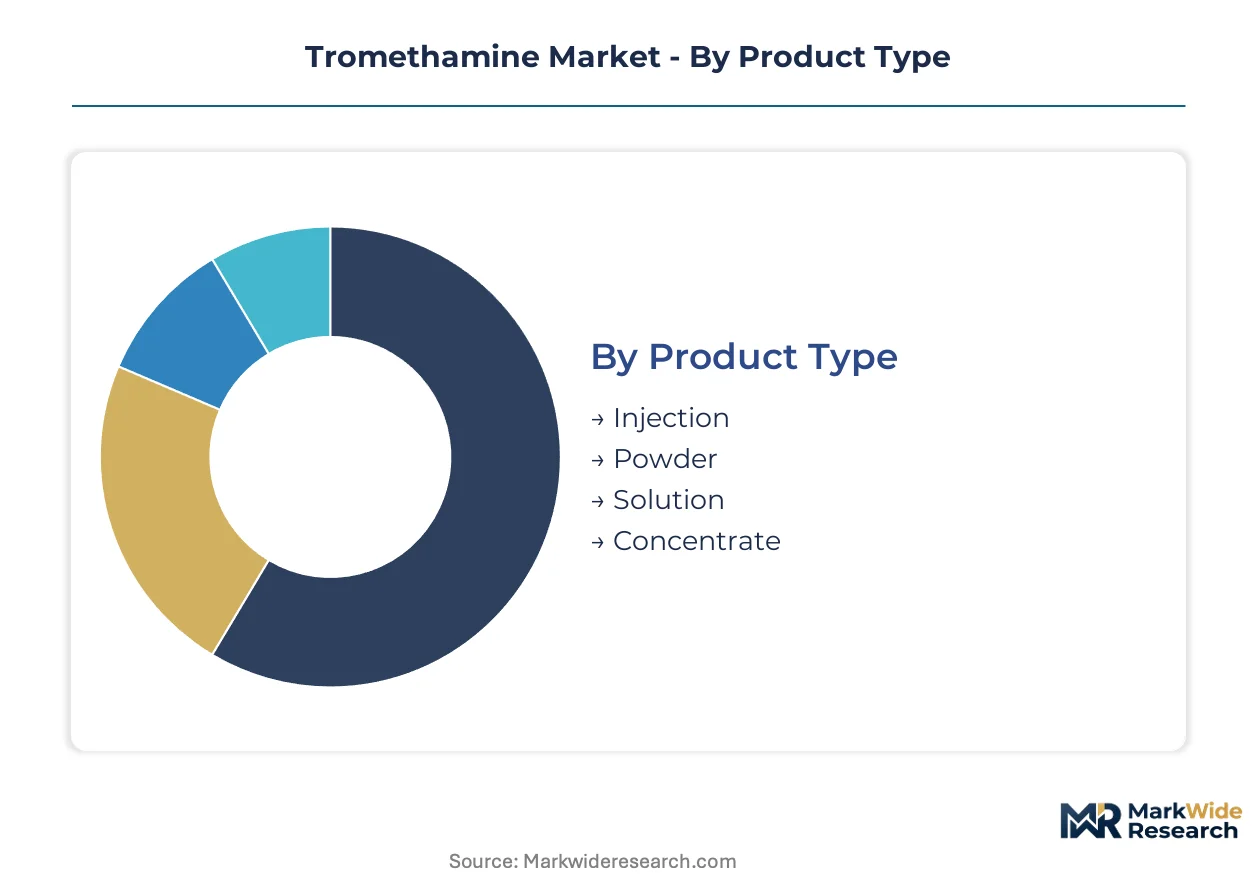
Tromethamine specification requirements fragment sharply across administration routes and clinical settings. Buffer purity grades, packaging formats, and regulatory documentation burdens diverge significantly between parenteral biologics and commodity therapeutic applications.
Product Type:
Injectable-grade formulations face the most acute substitution pressure from phosphate and acetate buffer systems where pharmacokinetic profiles permit interchangeability.
- Injection:Sterile, endotoxin-controlled solutions for parenteral drug formulations. Demand concentrates in US gene therapy developers requiring multi-compendial documentation for FDA biologics license applications. Phosphate buffers capture cost-sensitive generic injectables where pH 7.4-7.6 tolerance windows overlap.
- Powder:Crystalline tromethamine base requiring reconstitution prior to use. Chinese CDMOs scaling mRNA manufacturing drive procurement volumes for bulk powder formats with extended stability profiles. Lyophilization compatibility distinguishes premium grades from commodity chemical supply.
- Solution:Pre-formulated buffer concentrates at standardized molarities. European contract manufacturers favor ready-to-use solutions to minimize compounding validation overhead.
- Concentrate:High-strength formulations for dilution into final drug products. Dialysis and continuous renal replacement therapy applications specify concentrates for on-demand preparation.
Injection formats anchor the volume base while Powder gains share at the steepest rate.
Application:
Cost-tier stratification separates biologic formulation buffers from commodity acid-base correction therapies.
- Cardiac Care:Tromethamine neutralizes metabolic acidosis during open-heart surgery and postcardiac arrest resuscitation. US hospital systems standardize on premixed injection bags for emergency department and intensive care unit stocking.
- Metabolic Disorders:Enzyme replacement and rare disease therapies require tromethamine for pH stabilization of protein formulations. Homecare infusion expansion extends demand into patient-administered therapies for Pompe disease and Fabry disease.
- Respiratory Support:Adjunctive buffer therapy in acute respiratory distress syndrome. Mechanical ventilation protocols in German and French tertiary centers incorporate tromethamine for permissive hypercapnia management.
- Fluid Replacement:Correcting acid-base disturbances in volume resuscitation. Generic substitution pressure is most intense here as saline and lactated Ringer's solutions dominate cost-sensitive protocols.
Metabolic Disorders command the highest purity premiums while Fluid Replacement delivers the largest unit volumes.
End User:
Customer-type concentration shifts procurement authority from hospital pharmacy directors toward biopharma supply chain managers.
- Hospitals:Integrated health systems negotiate multi-year excipient contracts with audit rights and manufacturing site disclosure. Academic medical centers in Boston and San Francisco anchor demand for research-grade tromethamine in early-phase clinical trials.
- Clinics:Outpatient infusion centers administer enzyme replacement therapies on scheduled protocols. Taiwan's specialized metabolic disorder clinics source directly from HOPAX for traceable supply chains.
- Ambulatory Surgical Centers:Same-day cardiac procedures drive spot purchasing of premixed buffer solutions. Cost pressure from Medicare reimbursement cuts favors generic phosphate alternatives where clinically equivalent.
- Homecare:Patient-administered subcutaneous infusions for rare diseases. Swiss and Dutch reimbursement frameworks now cover home nursing support for tromethamine-containing therapies.
Hospitals retain the dominant procurement volume while Homecare expands most quickly.
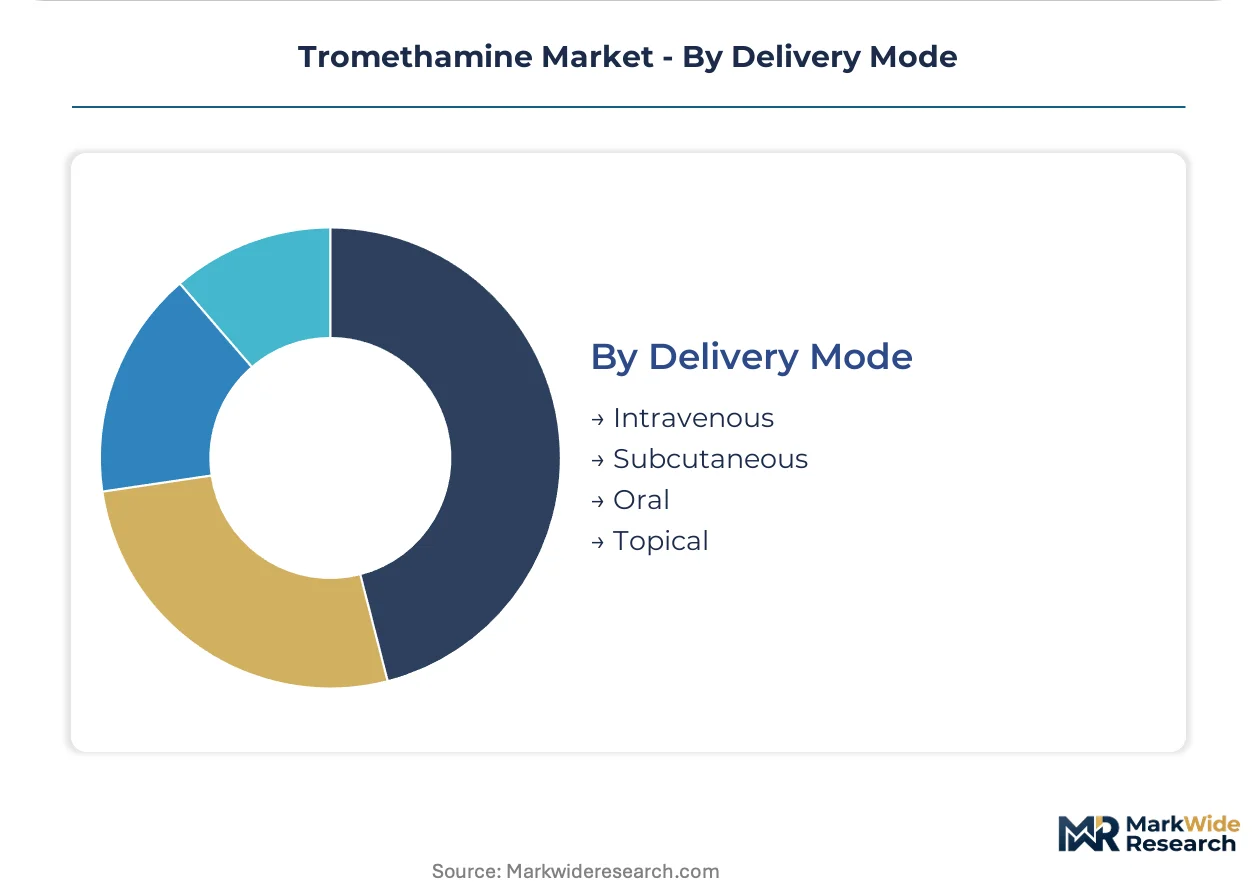
Delivery Mode:
Supply concentration in parenteral-grade manufacturing creates geographic risk exposure for non-intravenous formats.
- Intravenous:Direct bloodstream administration demands the most stringent endotoxin and particulate specifications. FDA's ICH Q3D enforcement drives elemental impurity testing to sub-ppm detection limits for IV applications.
- Subcutaneous:Homecare enzyme replacement therapies favor subcutaneous delivery for patient self-administration. Prefilled syringe compatibility requires specific osmolality and viscosity profiles.
- Oral:Limited applications in over-the-counter antacid formulations. Bioavailability constraints restrict pharmaceutical adoption despite lower manufacturing costs.
- Topical:Emerging use in wound care and dermatological preparations. Compounding pharmacies in Florida and California experiment with tromethamine-buffered topical formulations.
Intravenous delivery dominates current value capture while Subcutaneous climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's tightened ICH Q3D enforcement anchors North American demand, while CDSCO import substitution and NMPA domestic registration rules reshape supply strategies across Asia-Pacific manufacturing clusters.
United States
Gene therapy developers in Boston and San Francisco drive multi-compendial tromethamine procurement for FDA biologics license applications. The US FDA mandates elemental impurity testing to sub-ppm detection limits under ICH Q3D, forcing suppliers to upgrade analytical capabilities. Academic medical centers anchor research-grade demand for early-phase clinical trials.
Germany
EMA's revised Annex 1 guidelines on sterile manufacturing mandate enhanced contamination control for excipient handling in Grade A/B environments. Tertiary centers in Berlin and Munich incorporate tromethamine into mechanical ventilation protocols for permissive hypercapnia management. Suppliers must demonstrate closed-system transfer protocols and isolator filling lines to maintain market access.
China
Domestic CDMOs scaling peptide and mRNA drug production concentrate procurement volumes in Shanghai and Suzhou biotech clusters. NMPA now requires domestic registration of imported excipients, creating documentation burdens for foreign manufacturers serving Chinese biopharma clients. The Yangtze River Delta anchors national buffer demand as local production scales.
India
Domestic contract manufacturers scaling peptide API capacity create demand for localized excipient sourcing. CDSCO import substitution incentives favor domestic tromethamine production over foreign supply. Mumbai and Hyderabad pharmaceutical clusters drive procurement as CDMO buildout accelerates under government manufacturing promotion schemes.
Taiwan
Specialized metabolic disorder clinics source directly from local manufacturers for traceable supply chains. Injectable-grade production concentrates on the island, creating geographic risk exposure for parenteral drug supply security. Hsinchu and Taipei anchor precision chemical manufacturing for biopharma export markets.
Tromethamine Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with market structure tightening around cGMP certification requirements. Supplier consolidation accelerates as biopharma manufacturers demand single-source excipient accountability for parenteral drug filings. Three archetypes dominate: integrated nitroalkane platform operators, specialized cGMP manufacturers, and US-based multi-compendial certified producers. Competitive moves center on capacity expansion for pharmaceutical-grade output and strategic partnerships with single-use system integrators.
Among North American integrated chemical producers, ANGUS Chemical Company exemplifies backward control over nitroalkane feedstocks. HOPAX occupies a position within the specialized cGMP manufacturing tier, while BioSpectra, Inc. represents the US-based production archetype with multi-compendial certification focus. These three anchors illustrate how geographic and certification strategies differentiate competitive positioning across the supplier base.
| Leading Market Players |
|---|
| ANGUS Chemical Company |
| HOPAX |
| BioSpectra, Inc. |
| Tokyo Chemical Industry Co., Ltd. |
| FARMAK, a.s. |
| Metrochem API Pvt Ltd |
| Spectrum Chemical Mfg. Corp. |
| Thermo Fisher Scientific Inc. |
| Hunan Dongting Pharmaceutical Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Phosphate buffer substitution in cost-sensitive generic injectables simultaneously redistributes procurement volumes toward Asian manufacturing hubs and compresses margin structures for commodity-grade suppliers. This displacement dynamic concentrates pricing power with multi-compendial certified producers while forcing regional suppliers to compete on logistics proximity rather than specification superiority.
Pricing Analysis
Geographic price spreads between North American and Taiwanese injectable-grade supply reach multiples of three-to-five when factoring in FDA audit documentation and ICH Q3D testing compliance. Three-tier pricing structure across pharmaceutical-grade, technical-grade, and industrial-grade levels anchors the market, with certification tier and volume scale serving as the primary differentiation drivers. Cost compression in the technical-grade segment is intensifying because Chinese CDMOs are scaling captive buffer production under NMPA import substitution incentives. Generic injectable developers exhibit the highest price sensitivity, while gene therapy sponsors prioritize supply continuity over unit economics.
Supply Chain Analysis
Inventory lead times for pharmaceutical-grade tromethamine stretch to six-to-nine months when dual pharmacopoeial registration documentation is required for new manufacturing sites. Supply concentrates in Taiwan, the United States, and China, with raw material feeds drawing from formaldehyde and nitromethane derivatives tethered to petrochemical value chains. Single-source vulnerability dominates risk exposure as injectable-grade production clusters on Taiwan, creating geographic concentration for parenteral drug supply security. Distribution runs through direct long-term supply agreements with biopharma procurement teams rather than spot-market intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
mRNA platform expansion represents a high-growth disruption reshaping excipient demand structures, with lipid nanoparticle stabilization requirements pulling pharmaceutical-grade tromethamine into critical formulation workflows previously served by commodity buffers.
For Market Incumbents: Fortify cGMP certification moats by securing dedicated isolator filling lines ahead of EMA Annex 1 enforcement deadlines. Deepen backward integration into nitroalkane feedstocks to offset formaldehyde price volatility threatening margin structures. Lock in multi-year supply agreements with audit rights to preempt competitor poaching of gene therapy developer accounts. For New Entrants and Emerging Players: Anchor in India's CDMO buildout corridor, where CDSCO import substitution incentives favor domestic excipient sourcing over foreign supply. Target peptide API contract manufacturers in Mumbai and Hyderabad as the most penetrable customer archetype. Lead with rapid dual pharmacopoeial registration capabilities as the primary go-to-market wedge against established Taiwanese suppliers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed chemical platforms lacking pharmaceutical-grade certification infrastructure. Long-term viability hinges on five-to-ten year exposure to biologics formulation demand rather than commodity acid-base correction therapies. Monitor NMPA domestic excipient registration timelines as the signal for Chinese market access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Pharmacopoeial Registration Investment | Simultaneous USP-NF and EP compliance documentation accelerates qualification cycles for new manufacturing sites serving FDA and EMA filings. |
| Backward Integration into Nitroalkane Feedstocks | In-house production of formaldehyde and nitromethane derivatives insulates margins from petrochemical price volatility exposure. |
| Isolator Filling Line Deployment | Closed-system transfer protocols satisfy EMA Annex 1 contamination control mandates for Grade A/B excipient handling environments. |
| Long-term Supply Agreement Structuring | Multi-year contracts with audit rights and manufacturing site disclosure preempt competitor poaching of gene therapy developer accounts. |
| India CDMO Partnership Formation | Localized excipient sourcing under CDSCO import substitution incentives captures peptide API contract manufacturing demand in Mumbai and Hyderabad. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, USP-NF monograph updates, and trade customs data to establish supply volume baselines. Primary interviews engaged drug development executives at gene therapy sponsors, regulatory affairs leads at excipient suppliers, hospital procurement managers, and CDMO technical directors across the United States, Germany, China, and India. Bottom-up segmentation modeling triangulates against top-down industry association aggregates from pharmaceutical chemical trade bodies.
Segmentation dimensions modeled include product grade tier, administration route, end-use application, and regional regulatory cluster across the projection horizon. CAGRs derive from elasticity-adjusted demand curves incorporating mRNA platform expansion rates, serum-free cell culture transition velocity, and pharmacopoeial harmonization progress. Forecast inputs incorporate ICH Q3D enforcement intensity, NMPA domestic registration rule implementation, and CDSCO import substitution incentive uptake.
Material uncertainties — nitroalkane feedstock volatility, Taiwan manufacturing concentration risk, and phosphate buffer substitution acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory timeline adherence and biopharma capital allocation priorities. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Dicaprylyl Carbonate Market
Chemicals
Asia-Pacific Fluorosilicic Acid Market
Chemicals
Asia-Pacific Gamma Butyrolactone Market
Chemicals
SLS and LABSA Market
Chemicals
Global Bleaching Agents Market
Chemicals
Phosgene Market
Chemicals
Ethyl Chloride Market
Chemicals
Germany Methanol Market
Chemicals
Phenothiazine Market
Chemicals
LAMEA Dimethyl Phosphate Market
Chemicals
Valeryl Chloride Market
Chemicals
Hexamine Market
Chemicals
Sodium Cyanide Market
Chemicals
Global Organobromine Market
Chemicals
4-Dichlorodiphenyl Sulfone (DCDPS) Market
Chemicals
Vinyl Acetate Market