
 SLS and LABSA Market | 2026-2036
SLS and LABSA Market Size, Share, and Industry Trends Forecast 2026-2036
SLS and LABSA Market Analytics
Market Context
Asian petrochemical producers is expanding LABSA output to capture downstream surfactant demand. Sasol Chemicals leverages its Fischer-Tropsch feedstock integration to anchor supply security in Southern Africa and export corridors. BASF SE sustains technology leadership through continuous alkoxylation process refinement at its Ludwigshafen complex. Stepan Company dominates North American sulfonation capacity with dedicated units serving household and industrial cleaning formulators.
Technical Definition and Structural Segments
Sodium Lauryl Sulfate and Linear Alkyl Benzene Sulfonic Acid constitute anionic surfactants derived from lauryl alcohol or linear alkyl benzene feedstocks, typically exhibiting 28-30% active matter content and functioning as primary detergents, foaming agents, and emulsifiers across cleaning and personal care formulations. Personal Care applications lead value contribution due to premiumization in sulfate-free and mild-sulfate variants, while Household Cleaning anchors volume throughput as emerging economies expand packaged detergent penetration. Industrial Cleaning competes on specification intensity, with Agriculture and Oil & Gas end users demanding customized HLB values and electrolyte tolerance for hard-surface and crop-protection formulations.
Regulatory Frame and Outlook
REACH in Europe, EPA TSCA in the United States, and BIS standards in India govern biodegradability thresholds, aquatic toxicity limits, and active matter labeling for surfactant placement. These frameworks elevate compliance costs for non-integrated producers while creating specification premiums for certified grades. Stakeholders must monitor feedstock volatility in linear alkyl benzene and lauryl alcohol markets alongside evolving sulfate substitution trends in premium personal care segments.
Market Dynamics
REACH compliance and the EU Green Deal's chemical sustainability targets are compressing specification tolerances for biodegradability and aquatic toxicity, forcing reformulation investments across European supply chains while Asian producers capture volume growth in less regulated corridors.
Growth Catalysts
- India detergent production:Domestic packaged detergent penetration and export-oriented personal care manufacturing are scaling simultaneously, absorbing LABSA and SLS volumes at expanding rates.
- REACH biodegradability thresholds:European regulatory pressure is creating specification premiums for certified grades, rewarding compliant producers with margin capture opportunities.
- Sulfate-based cleansing systems:Cost advantages in anionic surfactant formulations continue to anchor volume demand from personal care formulators despite mild-sulfate marketing trends.
Market Restraints
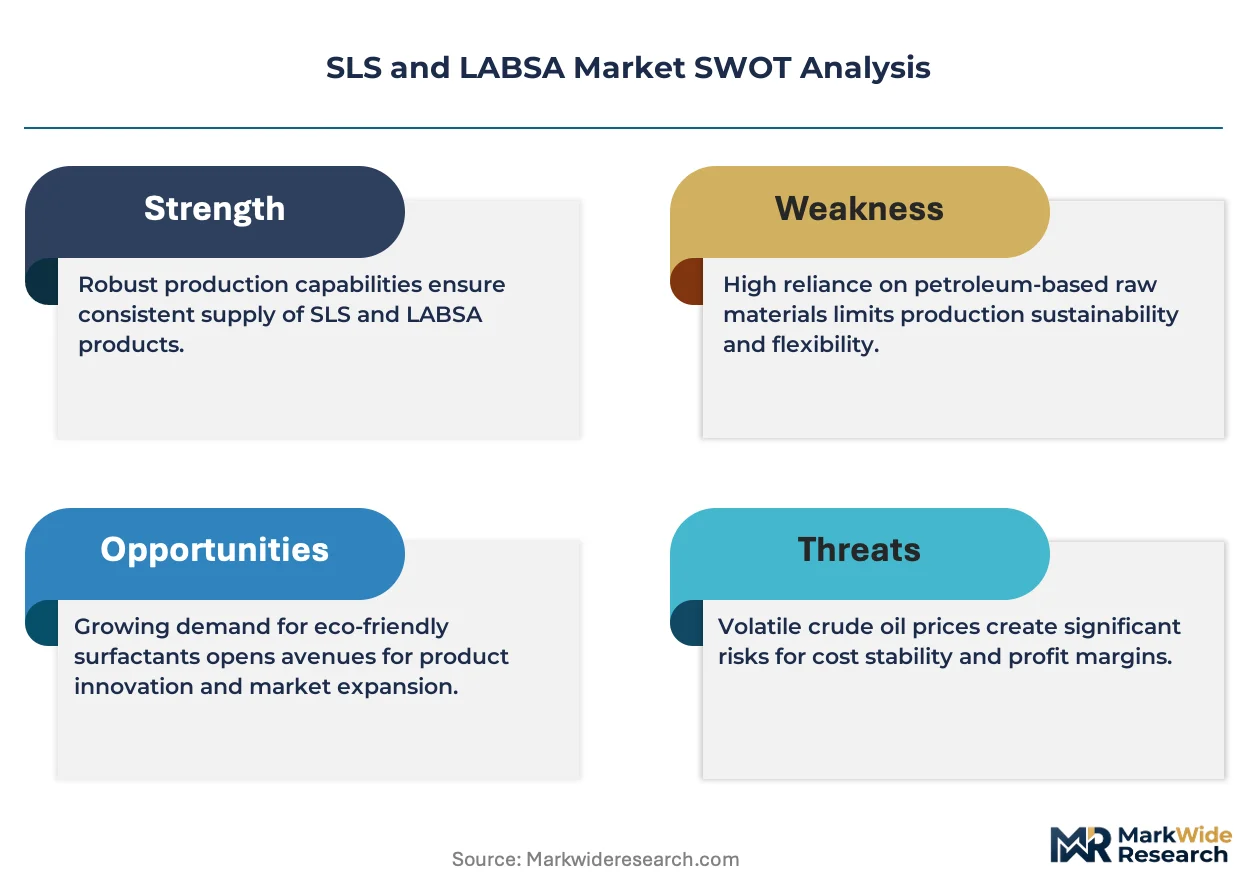
- Linear alkyl benzene feedstock volatility:Crude oil price sensitivity and paraffin supply disruptions transmit directly into LABSA production economics, compressing margins for non-integrated sulfonators.
- Southern African supply concentration:Fischer-Tropsch feedstock integration at a single major producer creates corridor dependency risks for export markets.
- Sulfate substitution in premium personal care:Mild-sulfate and sulfate-free marketing positioning is displacing standard SLS in high-margin cosmetic formulations.
Strategic Opportunities
- Indian export manufacturing corridors:Gujarat and Maharashtra industrial zones are attracting contract manufacturing investment for personal care brands seeking cost-competitive sulfate production.
- EU Green Deal chemical sustainability targets:Biodegradable surfactant mandates are opening specification windows for bio-based alkyl sulfate variants with enhanced aquatic toxicity profiles.
- Direct-to-formulator digital channels:Specialty chemical platforms are disintermediating traditional distributor networks for mid-volume industrial cleaning compounders.
Industry Challenges
- Sulfonation process engineering talent:Specialized reactor design and continuous process optimization expertise is concentrating at legacy producers, constraining new entrant scale-up.
- REACH registration timelines:Extended substance evaluation periods for novel surfactant chemistries are delaying commercialization of bio-based alternatives.
- Legacy formulation integration:Hard-surface and crop-protection compounders face requalification burdens when substituting certified-grade surfactants into established product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SLS and LABSA Market |
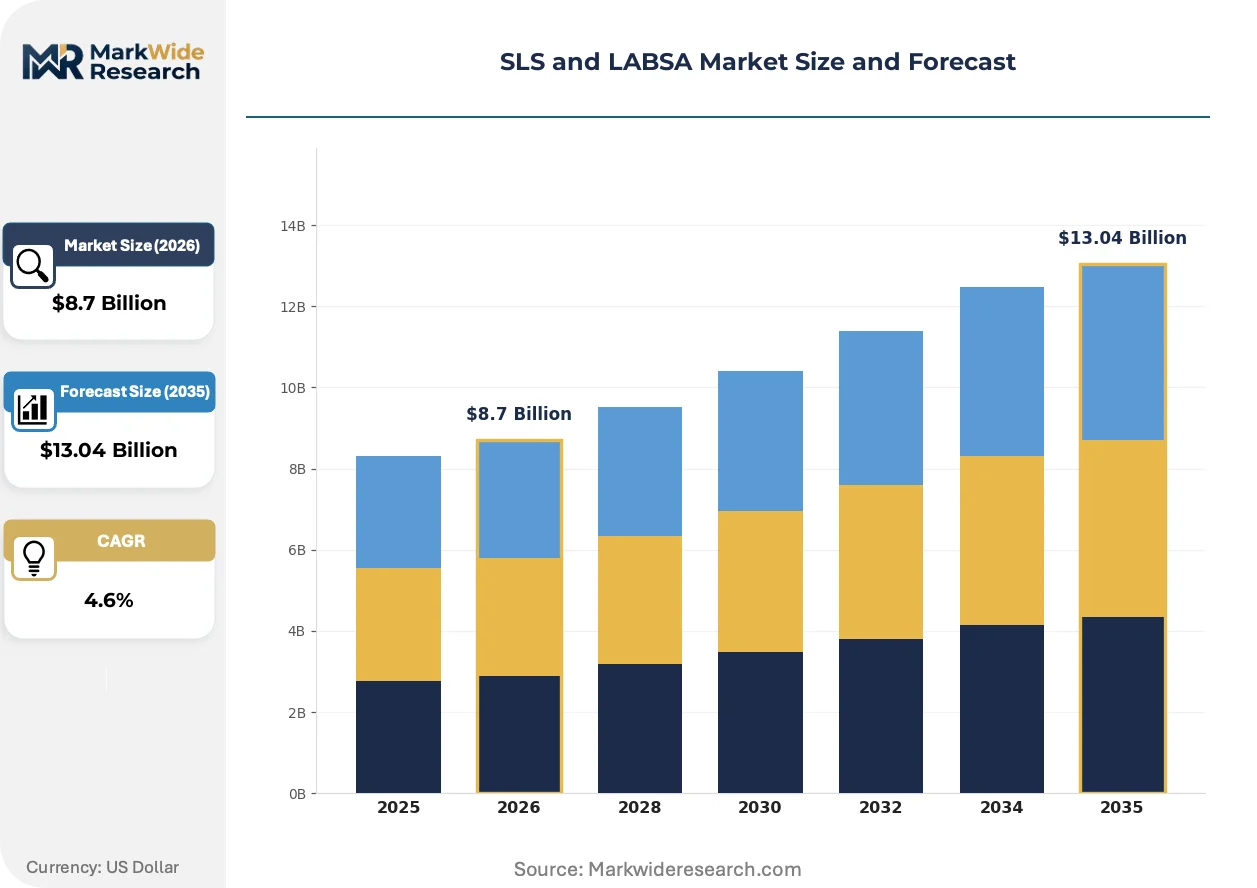
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Lauryl Sulfate, Linear Alkyl Benzene Sulfonic Acid, Surfactants, Alinea MGC Application: Personal Care, Household Cleaning, Industrial Cleaning, Agricultural End User: Cosmetics Manufacturers, Cleaning Product Producers, Agriculture Companies, Oil & Gas Distribution Channel: Online Retail, Direct Sales, Wholesale, Specialty Stores |
| Companies Covered | Sasol Chemicals LLC, Cepsa, BASF SE, Solvay, Fogla Group, Stepan Company, Kao Corporation, Clariant AG, Galaxy Surfactants Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SLS and LABSA Market Evolving Landscape
Formulation science and regulatory chemistry are converging to redefine acceptable surfactant performance, with biodegradability certification and mildness metrics displacing pure cost-per-active-unit procurement criteria.
Enzyme-augmented surfactant systems are overtaking conventional sulfate-only formulations in concentrated detergent applications. European household cleaning brands are adopting these hybrid chemistries to meet Ecolabel criteria. The technology is compressing dosage requirements and enabling compact packaging formats that reduce logistics costs.
REACH substance evaluation is tightening aquatic toxicity thresholds for anionic surfactants placed on the European market. ECHA's revised classification criteria are forcing reformulation of standard LABSA grades in industrial cleaning applications. German and Dutch formulators are accelerating qualification of bio-based alternatives to preempt authorization risks.
Formulators are consolidating supplier relationships around certified-grade producers with integrated biodegradability documentation. Industrial cleaning compounders in the United States are reducing vendor counts to streamline EPA TSCA compliance verification. The pattern is most visible in agriculture and oilfield chemical procurement, where electrolyte tolerance specifications must align with regulatory dossier completeness.
SLS and LABSA Market Segmentation
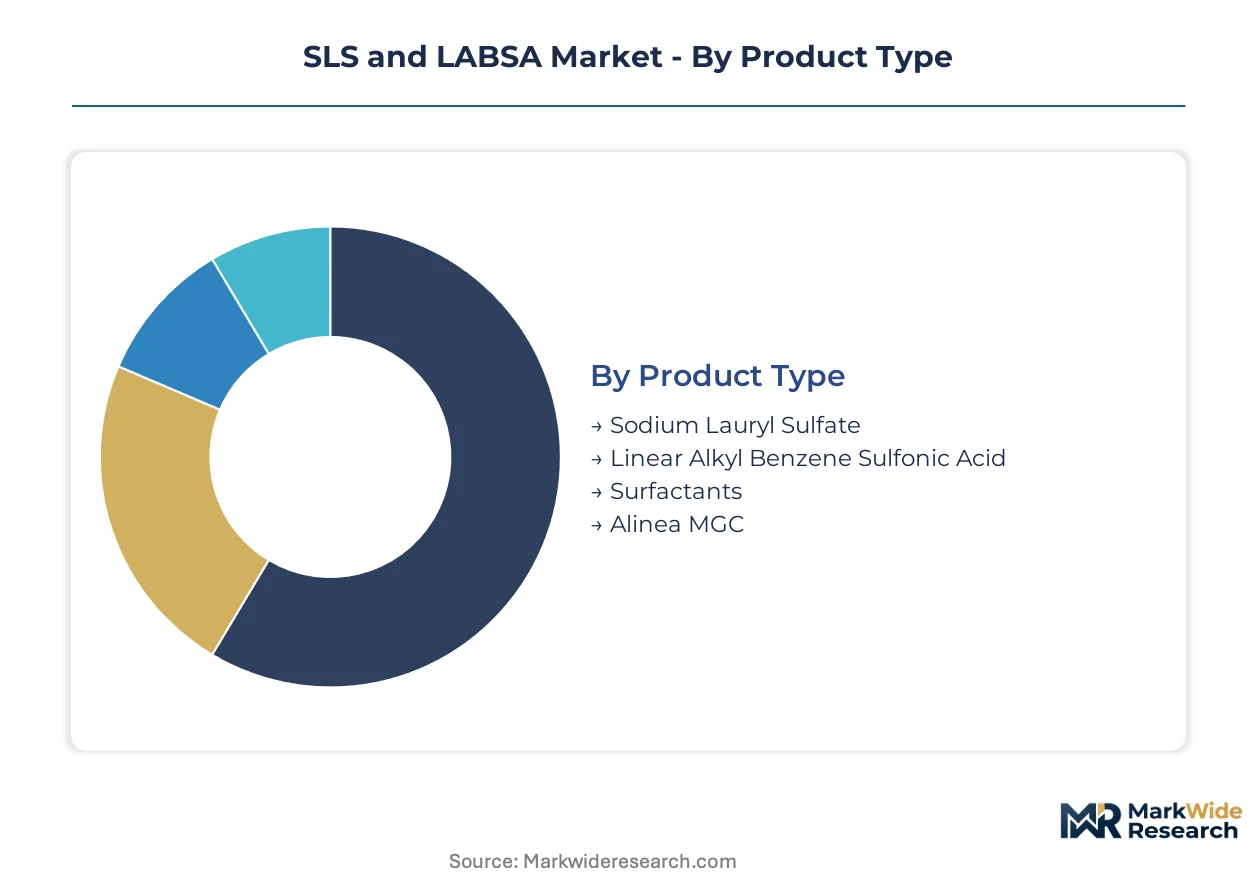
Segmentation in the SLS and LABSA market reveals how procurement criteria diverge across end-use specifications, regulatory exposure, and volume scale. Buyers prioritize biodegradability certification, active matter consistency, and supply security depending on their formulation complexity and geographic market access.
Product Type:
Buyers in this category differentiate by feedstock integration depth and sulfonation process sophistication required for their formulation base.
- Sodium Lauryl Sulfate:Derived from lauryl alcohol through sulfation, this anionic surfactant delivers consistent foaming and emulsification at 28-30% active matter. Personal care formulators in India absorb expanding volumes as domestic cosmetics manufacturing scales for export markets. Sulfate substitution trends in premium European cosmetics are compressing margins for standard grades.
- Linear Alkyl Benzene Sulfonic Acid:Manufactured via sulfonation of linear alkyl benzene, LABSA functions as a cost-effective primary detergent with superior hard-water tolerance. Household cleaning compounders across emerging economies anchor volume demand for this feedstock-efficient surfactant. Paraffin supply volatility transmits directly into production economics for non-integrated sulfonators.
- Surfactants:Broad category encompassing blended anionic systems and co-surfactant packages for multi-functional formulations.
- Alinea MGC:Specialty surfactant variant targeting niche applications with modified performance characteristics.
LABSA leads volumes today; Sodium Lauryl Sulfate is gaining share fastest in certified-grade personal care segments.
Application:
Volume concentration and specification intensity separate applications, with premiumization tolerance varying sharply across consumer versus industrial end-uses.
- Personal Care:Shampoos, body washes, and oral care formulations demand mild-sulfate and sulfate-free variants alongside standard SLS. REACH compliance in Europe and BIS standards in India are bifurcating procurement between certified-grade and commodity supply. German and Dutch formulators are accelerating bio-based alternative qualification to preempt ECHA authorization risks.
- Household Cleaning:Laundry detergents, dishwashing liquids, and surface cleaners consume LABSA at scale for cost-efficient primary detergency. Indian domestic packaged detergent penetration is absorbing expanding LABSA volumes from Gujarat-based sulfonation capacity. Enzyme-augmented hybrid systems are compressing dosage requirements for European Ecolabel-compliant brands.
- Industrial Cleaning:Hard-surface degreasers and metal processing formulations require customized HLB values and electrolyte tolerance.
- Agricultural:Crop protection adjuvants and tank-mix surfactants demand specific aquatic toxicity profiles for regulatory placement.
Household Cleaning anchors volume throughput; Personal Care commands the steepest expansion trajectory in value terms.
End User:
Integration depth and formulation complexity determine how end users source—direct from sulfonators for volume players, through distributors for specialty compounders.
- Cosmetics Manufacturers:Brand owners and contract manufacturers specify active matter purity and biodegradability certification for rinse-off and leave-on products. Maharashtra and Gujarat industrial zones are attracting personal care contract manufacturing investment seeking cost-competitive sulfate production. Consolidating supplier relationships around certified-grade producers with integrated documentation is streamlining compliance verification.
- Cleaning Product Producers:Formulators of household and industrial cleaning compounds prioritize feedstock cost stability and logistics efficiency. US-based industrial cleaning compounders are reducing vendor counts to streamline EPA TSCA compliance verification. Direct-to-formulator digital channels are disintermediating traditional distributor networks for mid-volume players.
- Agriculture Companies:Crop protection formulators require surfactant systems with defined electrolyte tolerance and regulatory dossier completeness.
- Oil & Gas:Drilling fluid and production chemical suppliers demand specialized HLB specifications for downhole performance.
Cleaning Product Producers dominate volume procurement; Cosmetics Manufacturers are climbing the fastest in certified-grade premium capture.
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and the need for regulatory documentation bundling.
- Online Retail:E-commerce platforms serve small-volume formulators and specialty compounders seeking rapid sample access and technical data sheets. Digital channels are compressing lead times for mid-tier industrial cleaning buyers with standardized specification requirements. Platform-based procurement reduces search costs for bio-based alternative qualification.
- Direct Sales:Integrated sulfonators and major producers maintain dedicated account teams for high-volume household and personal care formulators. Sasol Chemicals leverages Fischer-Tropsch feedstock integration to anchor direct supply relationships in Southern African export corridors. Technical service bundling including reformulation support justifies relationship concentration.
- Wholesale:Regional distributors aggregate volumes for fragmented industrial and agricultural end users with intermittent demand patterns.
- Specialty Stores:Niche channels serve laboratory-scale buyers and formulation development shops requiring small-batch flexibility.
Direct Sales leads volumes today; Online Retail is expanding most quickly in mid-tier segment penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting sulfonation capacity toward jurisdictions where REACH-equivalent compliance costs remain lower, with European formulators absorbing specification premiums while Asian producers capture volume expansion in less stringently regulated corridors.
India
Gujarat and Maharashtra industrial zones are scaling domestic packaged detergent production and export-oriented personal care manufacturing simultaneously. BIS standards govern active matter labeling and biodegradability thresholds for surfactant placement. The Mundra-Kandla chemical corridor is attracting sulfonation capacity expansions serving both household cleaning compounders and cosmetics contract manufacturers.
Germany
Ludwigshafen-based alkoxylation refinements anchor technology leadership for sulfate process optimization. ECHA's revised classification criteria under REACH substance evaluation are forcing reformulation of standard LABSA grades in industrial cleaning applications. German formulators are accelerating qualification of bio-based alternatives to preempt authorization risks for aquatic toxicity non-compliance.
United States
North American sulfonation capacity concentrates around dedicated units serving household and industrial cleaning formulators with standardized active matter specifications. EPA TSCA compliance verification is driving vendor consolidation among industrial cleaning compounders seeking streamlined regulatory dossier management. The Gulf Coast petrochemical corridor provides feedstock integration advantages for linear alkyl benzene supply security.
South Africa
Fischer-Tropsch feedstock integration creates supply corridor dependencies for export markets across sub-Saharan Africa and beyond. The country's chemical regulator enforces biodegradability thresholds aligned with evolving EU precedent. Secunda-based production complexes anchor regional supply security for sulfonate-dependent detergent manufacturers.
China
Yangtze River Delta petrochemical producers are expanding LABSA output to capture downstream surfactant demand from domestic and export markets. GB standards and MIIT guidelines govern chemical manufacturing sustainability targets with increasing stringency. The Ningbo-Zhoushan chemical industrial zone is consolidating sulfonation capacity for integrated detergent and personal care supply chains.
SLS and LABSA Market Competitive Landscape
Asian petrochemical producers anchor one tier through volume-scale sulfonation capacity; European specialists hold specification leadership through integrated biodegradability certification and alkoxylation process refinement. The vendor base stratifies across three archetypes: integrated petrochemical majors with captive feedstock, regional sulfonators serving domestic detergent markets, and specialty surfactant houses targeting certified-grade personal care segments. Capacity expansion and strategic partnerships represent the dominant competitive moves, with producers securing linear alkyl benzene supply agreements and qualifying bio-based alternatives ahead of regulatory deadlines.
Among integrated majors, Sasol Chemicals exemplifies Fischer-Tropsch feedstock integration archetypes, while BASF SE occupies a position representing continuous process refinement leadership. Stepan Company anchors North American sulfonation specialization. Galaxy Surfactants Ltd and Fogla Group represent Indian subcontinent volume-scale sulfonation capacity serving both domestic absorption and export manufacturing corridors.
| Leading Market Players |
|---|
| Sasol Chemicals LLC |
| Cepsa |
| BASF SE |
| Solvay |
| Fogla Group |
| Stepan Company |
| Kao Corporation |
| Clariant AG |
| Galaxy Surfactants Ltd |
| Others |
Value Network & Pricing Analysis
Linear alkyl benzene spot price indices cascade through sulfonation economics into three distinct procurement tiers, with feedstock-integrated producers capturing margin premiums while non-integrated sulfonators absorb volatility in commodity-grade segments.
Pricing Analysis
Distributor margin layers compress toward direct-to-formulator channels as specialty chemical platforms disintermediate traditional networks. Three-tier pricing structure across certified-grade, standard industrial, and commodity spot levels separates personal care formulators seeking REACH documentation from bulk detergent compounders prioritizing active matter consistency. Pricing pressure stems from paraffin supply disruptions transmitting directly into LABSA production costs. Household cleaning compounders exhibit highest price sensitivity, while cosmetics manufacturers absorb premiums for biodegradability-certified grades.
Supply Chain Analysis
Regional distribution centers cluster around Gujarat and Maharashtra industrial zones, anchoring hub-and-spoke patterns serving domestic Indian absorption and export manufacturing corridors. Supply concentration centers on India, China, and Germany, with sulfonation capacity expanding along the Mundra-Kandla and Ningbo-Zhoushan chemical corridors. Raw material dependencies rest on linear alkyl benzene, lauryl alcohol, and Fischer-Tropsch paraffin feedstocks. Single-source vulnerability concentrates in Southern African Fischer-Tropsch supply. Distribution runs through direct sales relationships for volume formulators and digital platforms for mid-tier industrial buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as packaged detergent penetration in emerging economies generates predictable volume absorption. Regulatory specification premiums reward early compliance investment.
For Market Incumbents: Deepen backward integration into linear alkyl benzene supply to defend against feedstock volatility squeezing non-integrated sulfonators. Expand certified-grade capacity ahead of REACH substance evaluation deadlines to capture specification premiums before bio-based alternatives gain traction. Concentrate technical service bundling around reformulation support to lock in cosmetics manufacturer relationships. For New Entrants and Emerging Players: Begin with enzyme-augmented surfactant systems targeting European Ecolabel-compliant household cleaning brands seeking dosage-compressed hybrid chemistries. Penetrate the Indian export manufacturing corridor through contract sulfonation services for personal care brands relocating production from higher-cost jurisdictions. Deploy direct-to-formulator digital channels to bypass established distributor networks in mid-volume industrial cleaning segments. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated petrochemical majors with captive Fischer-Tropsch or linear alkyl benzene supply and established biodegradability certification dossiers. Long-term viability favors producers with dual capability in standard sulfate and bio-based alkyl sulfate variants. Monitor ECHA authorization timelines for aquatic toxicity reclassification as the critical inflection signal for substitution-driven demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LAB Feedstock | Captive paraffin supply insulates margins from crude oil volatility transmission. |
| Certified-Grade Capacity Expansion | REACH-compliant sulfonation units command specification premiums in European personal care. |
| Long-term Supply Agreement | Fixed-price offtake contracts with Gujarat-based cosmetics contract manufacturers secure volume absorption. |
| Green Manufacturing Transition | Bio-based alkyl sulfate qualification preempts ECHA aquatic toxicity authorization risks. |
| Joint Venture | Technology-sharing partnerships with German alkoxylation specialists accelerate process refinement. |
Research Methodology
Bottom-up personal care and household cleaning formulation modeling reconciled against top-down sulfonation capacity tracking forms the analytical core. Primary interviews with plant managers at integrated petrochemical complexes, procurement leads at downstream detergent manufacturers, distribution channel partners, and technical R&D directors at specialty surfactant houses combined with secondary validation from customs/trade data, Cefic surfactant reports, and SEC 10-K filings. Triangulation across these sources ensures supply-side and demand-side estimates converge.
Historical trendline analysis of linear alkyl benzene and lauryl alcohol price series, cross-referenced against sulfonation operating rates and formulation substitution patterns, anchors the projection framework. Segmentation dimensions span product grade tier, end-use application intensity, regional production hub, and certification status. CAGRs derive from fitted trend extrapolation adjusted for regulatory phase-in schedules and feedstock cost trajectories. Forecast inputs include BIS standard implementation timelines and EU Green Deal chemical sustainability target enforcement.
Caveats apply where paraffin supply disruptions, REACH authorization delays, or sulfate substitution acceleration in premium cosmetics could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
5 Dinitroaniline Market
Chemicals
2-(4-(Bromomethyl)phenyl)propionic Acid (BMPPA) Market
Chemicals
Global Photoresist Chemicals Market
Chemicals
Sodium Azide Market
Chemicals
Iscotrizinol Market
Chemicals
Europe Tertiary Amines Market
Chemicals
Tromethamine Market
Chemicals
Ammonia Market
Chemicals
Waterborne Curing Agents Market
Chemicals
Africa Mining Chemicals Market
Chemicals
P-Ethylphenol Market
Chemicals
Europe Hydrazine Market
Chemicals
Ferric Oxide Market
Chemicals
Acrylic Acids and Esters Market
Chemicals
White Phosphorus Market
Chemicals
Natural Fatty Alcohols Market