
 Xanthates Market | 2026-2036
Xanthates Market Size, Share, and Industry Trends Forecast 2026-2036
Xanthates Market Analytics
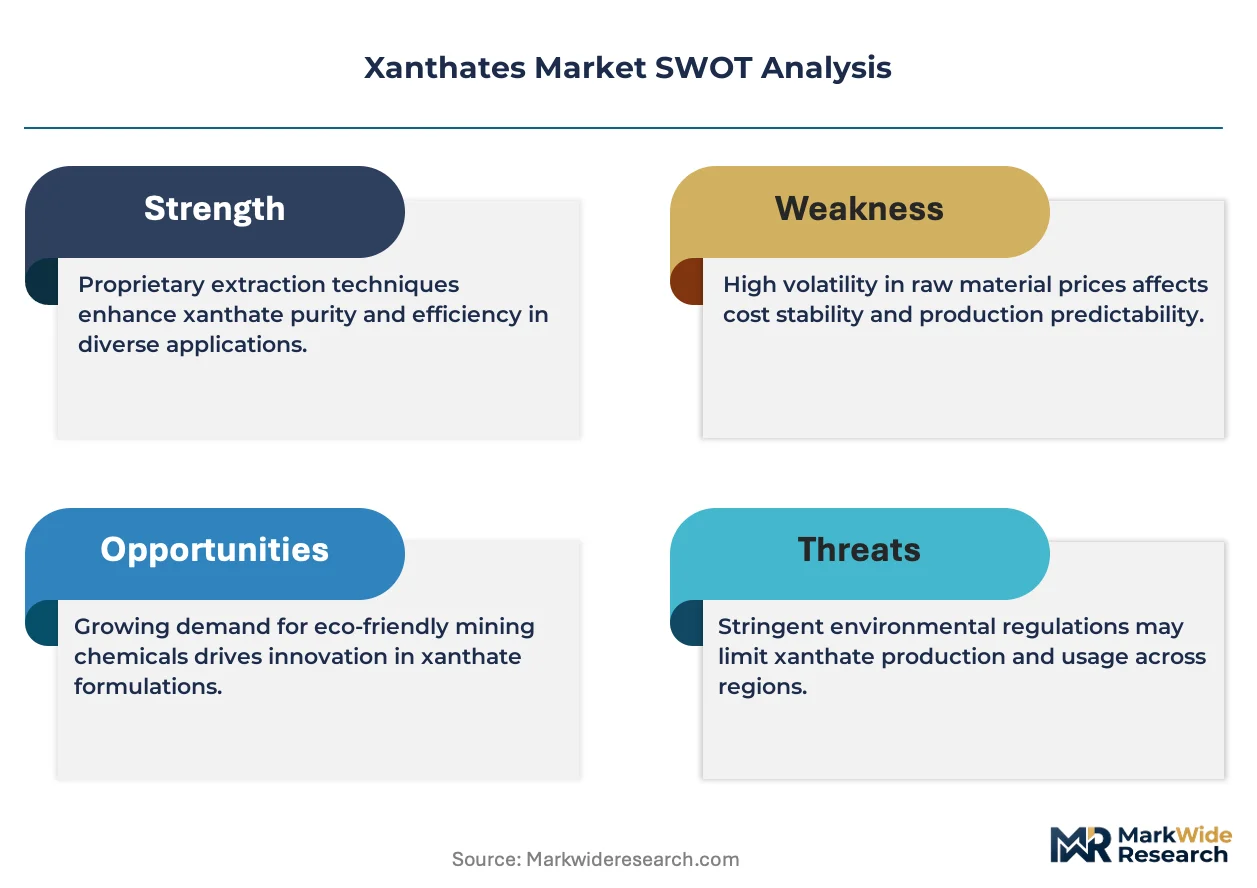
REACH registration requirements for sulfur-based flotation reagents is rebalancing the cost-of-entry calculus for European suppliers. Senmin International leverages its backward integration into carbon disulfide feedstock to sustain margin resilience across southern Africa's platinum and gold belts. Orica Limited anchors its position through dense distribution networks in Australia's iron ore corridors. Coogee Chemicals competes by specializing in custom xanthate blends for high-altitude Andean operations where water chemistry complicates standard formulations.
Xanthates are alkali metal or ammonium salts of xanthic acid, synthesized by reacting carbon disulfide with alkoxides in the presence of sodium or potassium hydroxide, typically yielding products with active ingredient concentrations between 80% and 90% that function as selective collectors in froth flotation circuits. Sodium xanthate dominates volume due to its cost efficiency in bulk base-metal operations, while potassium xanthate commands premium positioning in selective separation of complex polymetallic ores where float kinetics demand finer control. Froth flotation as an application absorbs the largest share of output, though rubber processing represents a concentrated margin pool tied to specialty accelerator demand in tire manufacturing clusters.
EPA effluent guidelines for mining operations in the United States constrain discharge of residual xanthate and byproduct thiocarbonates, while China's MEE enforces stricter limits on volatile organic compound emissions from carbon disulfide handling in xanthate synthesis. ISO 9001 certification has become a de facto market access requirement for supply contracts with major mining houses operating across multiple jurisdictions. Stakeholders must monitor evolving biodegradability testing protocols in the EU and their potential replication by mineral regulators in Brazil and South Africa.
Market Dynamics
Carbon disulfide feedstock volatility and REACH registration barriers are compressing supplier margins while concentrating procurement power among vertically integrated mining houses operating across multiple jurisdictions.
Growth Catalysts
- Copper belt expansion:Mining operations across Zambia and the Democratic Republic of Congo are scaling froth flotation capacity to process lower-grade sulfide deposits, intensifying collector chemical throughput requirements.
- Effluent rule tightening:EPA guidelines for mining discharge in the United States are mandating higher-purity xanthate formulations that reduce residual thiocarbonate contamination in tailings streams.
- Polymetallic complexity:Peruvian operators in the Andean cordillera are deploying selective potassium xanthate blends to achieve cleaner separation of copper-molybdenum-silver mineral assemblages.
Market Restraints
- Feedstock cost volatility:Carbon disulfide pricing fluctuates with natural gas and sulfur market swings, eroding margin predictability for non-integrated producers.
- Registration cost barriers:REACH compliance for sulfur-based flotation reagents imposes six-figure dossier expenses that freeze out smaller European compounders.
- Biodegradability testing uncertainty:Evolving EU protocols for aquatic toxicity assessment create formulation freeze periods as producers await validation standards.
Strategic Opportunities
- Andean high-altitude specialization:Custom xanthate blends engineered for depressed boiling points and altered water chemistry at elevation above 4,000 meters command technical premiums.
- Rubber accelerator diversification:Tire manufacturing clusters in East Asia present concentrated margin pools for specialty xanthate derivatives serving vulcanization chemistry.
- ISO 9001 certification arbitrage:De facto mining house procurement mandates create tiered access advantages for certified suppliers over uncertified regional competitors.
Industry Challenges
- Flotation chemistry expertise scarcity:Deep knowledge of collector-mineral interaction kinetics is concentrating among retiring specialists, constraining formulation innovation pipelines.
- Legacy equipment integration:Retrofitting automated dosing systems into existing flotation circuits requires sustained capex commitments that conflict with short-term concentrate price cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Xanthates Market |
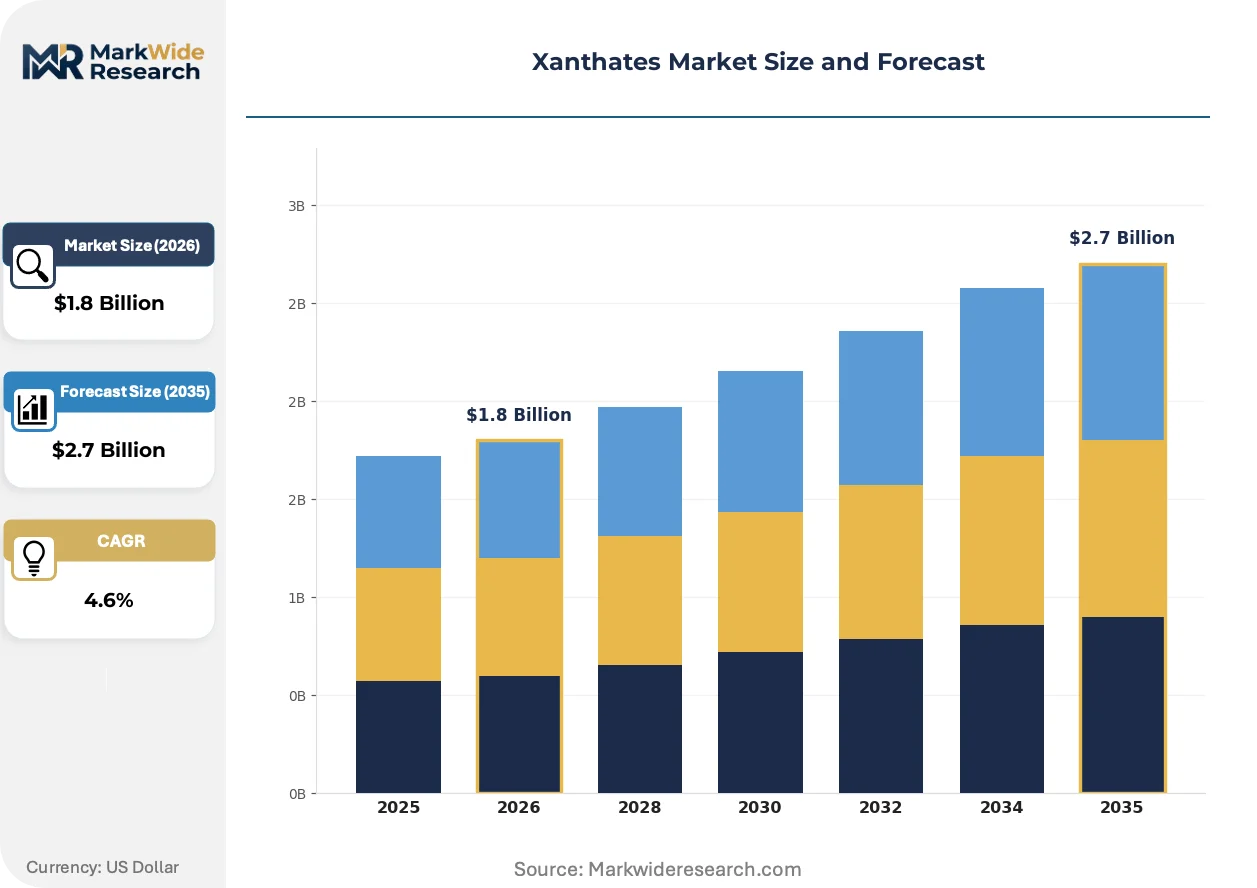
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Xanthate, Potassium Xanthate, Calcium Xanthate, Ammonium Xanthate End Use Industry: Mining, Agriculture, Chemicals, Pulp & Paper Application: Froth Flotation, Soil Treatment, Chemical Synthesis, Rubber Processing Packaging Type: Drum, Bag, Bulk, Sachet |
| Companies Covered | Senmin International, Coogee Chemicals, Orica Limited, Yantai Humon Chemical, China Xanthate International, QiXia TongDa Flotation Reagent, SNF Group, Tieling Flotation Reagent, Vanderbilt Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Xanthates Market Evolving Landscape
Digital process control and closed-loop reagent recovery systems are compressing consumption intensity per ton of concentrate produced while elevating technical service requirements.
Advanced sensor-based flotation control is integrating real-time xanthate dosing optimization with machine learning mineralogy analysis. Major copper operators in Chile are deploying these systems to reduce collector overdosing by 15-20% without sacrificing recovery rates. This technology is integrating process engineers directly into chemical supplier relationships, shifting procurement criteria toward technical service depth.
REACH authorization timelines for carbon disulfide derivatives are extending registration windows beyond historical norms. European compounders face 18-24 month dossier preparation cycles that delay market entry. Specialty xanthate producers with existing authorizations are capturing stranded demand from non-compliant competitors.
Long-term offtake contracting is displacing spot market purchasing among tier-one mining houses. Procurement teams at major copper and gold operators are locking in three-year supply agreements with fixed price collars. This pattern concentrates volume with established suppliers and compresses margin for traders serving smaller polymetallic projects.
Xanthates Market Segmentation
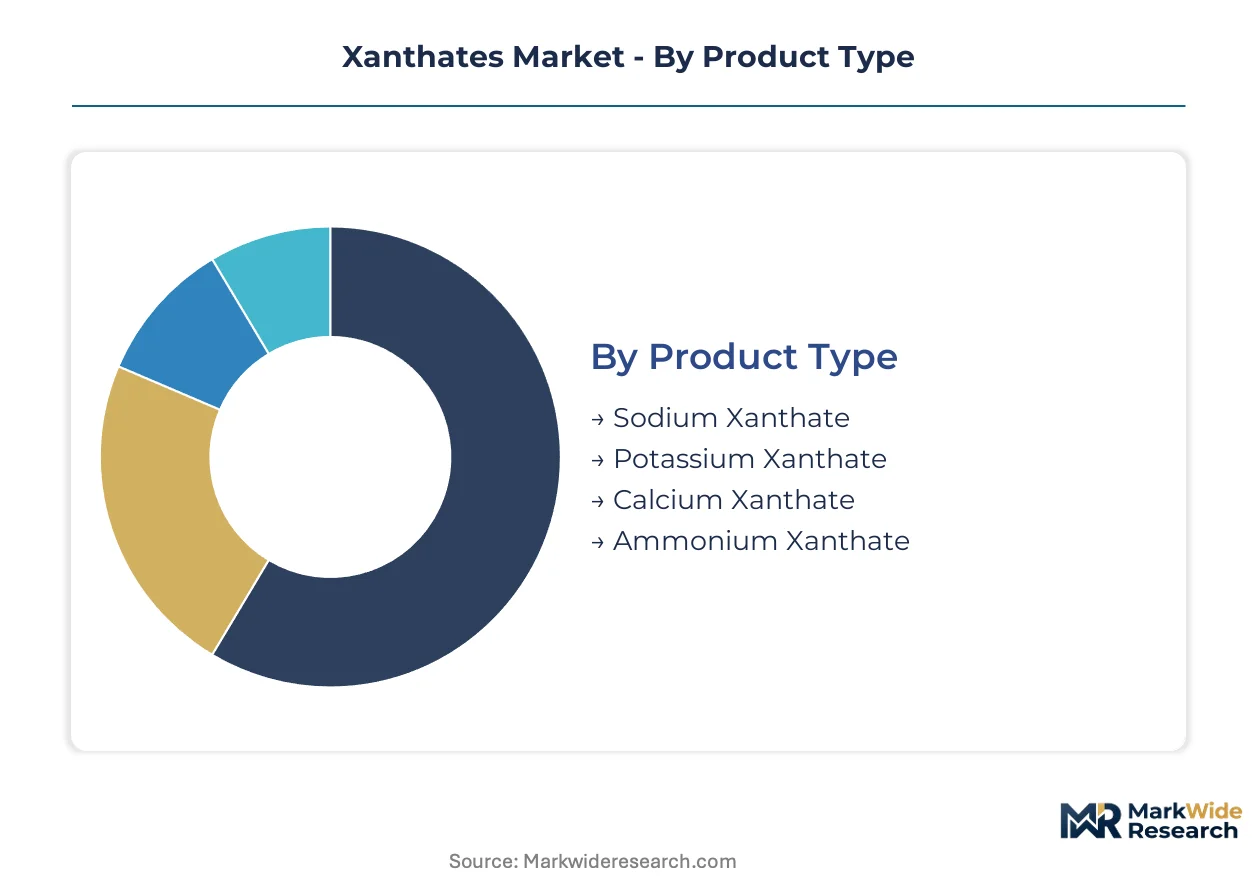
Xanthate selection hinges on collector-mineral affinity matching and water chemistry constraints rather than commodity pricing alone. Procurement teams weight active ingredient purity, dissolution kinetics, and effluent compliance against ore body complexity and altitude conditions.
Product Type:
Cost efficiency and selectivity precision drive the buyer calculus across alkali metal and ammonium salt formulations.
- Sodium Xanthate:Synthesized from sodium hydroxide and carbon disulfide, this formulation delivers 80-90% active ingredient concentration with rapid dissolution kinetics. Bulk base-metal operators in Zambia's copper belt favor sodium xanthate for high-throughput sulfide flotation where cost-per-ton-of-concentrate dominates procurement decisions.
- Potassium Xanthate:Higher molecular weight and slower hydrolysis rates enable finer control over collector adsorption on complex polymetallic surfaces. Peruvian operators in the Andean cordillera deploy potassium xanthate for copper-molybdenum-silver separation where float kinetics must be tuned to depressed boiling points and altered water chemistry.
- Calcium Xanthate:Limited solubility restricts deployment to specialized circuits where controlled release kinetics offset precipitation risks in hard water conditions.
- Ammonium Xanthate:Volatile decomposition products and handling complexity confine usage to niche applications with dedicated emission control infrastructure.
Volume sits with sodium xanthate; growth tilts toward potassium xanthate.
End Use Industry:
Application maturity and regulatory exposure separate high-volume commodity buyers from specialty chemical purchasers.
- Mining:Froth flotation circuits absorb the dominant share of xanthate output, with copper, gold, and platinum group metal operations driving formulation customization. Stricter EPA effluent guidelines in the United States and MEE emission limits in China are pushing miners toward higher-purity formulations that reduce residual thiocarbonate contamination.
- Chemicals:Intermediate synthesis and specialty derivative production command premium margins through technical specification adherence. REACH registration requirements for sulfur-based reagents concentrate procurement among authorized European compounders with validated dossiers.
- Agriculture:Soil treatment applications remain fragmented across regional pesticide formulators with variable purity requirements.
- Pulp & Paper:Niche demand for xanthate derivatives in pulping chemistry lacks scale to attract dedicated supplier investment.
Revenue concentrates in mining; chemicals deliver margin expansion.
Application:
Process intensity and reagent recovery economics determine consumption patterns across industrial uses.
- Froth Flotation:Collector chemistry dominates xanthate demand, with real-time dosing optimization and machine learning mineralogy analysis reducing consumption intensity per ton of concentrate. Chilean copper operators report 15-20% collector reduction through advanced sensor-based control without recovery rate sacrifice.
- Rubber Processing:Vulcanization accelerator demand in East Asian tire manufacturing clusters offers concentrated margin pools for specialty xanthate derivatives with strict purity certifications.
- Chemical Synthesis:Intermediate production for thiocarbamate and other organosulfur compounds requires consistent active ingredient specifications.
- Soil Treatment:Agricultural deployment faces biodegradability testing uncertainty as EU aquatic toxicity protocols evolve.
Throughput scales with froth flotation; margin accrues to rubber processing.
Packaging Type:
Logistics infrastructure and reagent stability requirements shape procurement specifications across delivery formats.
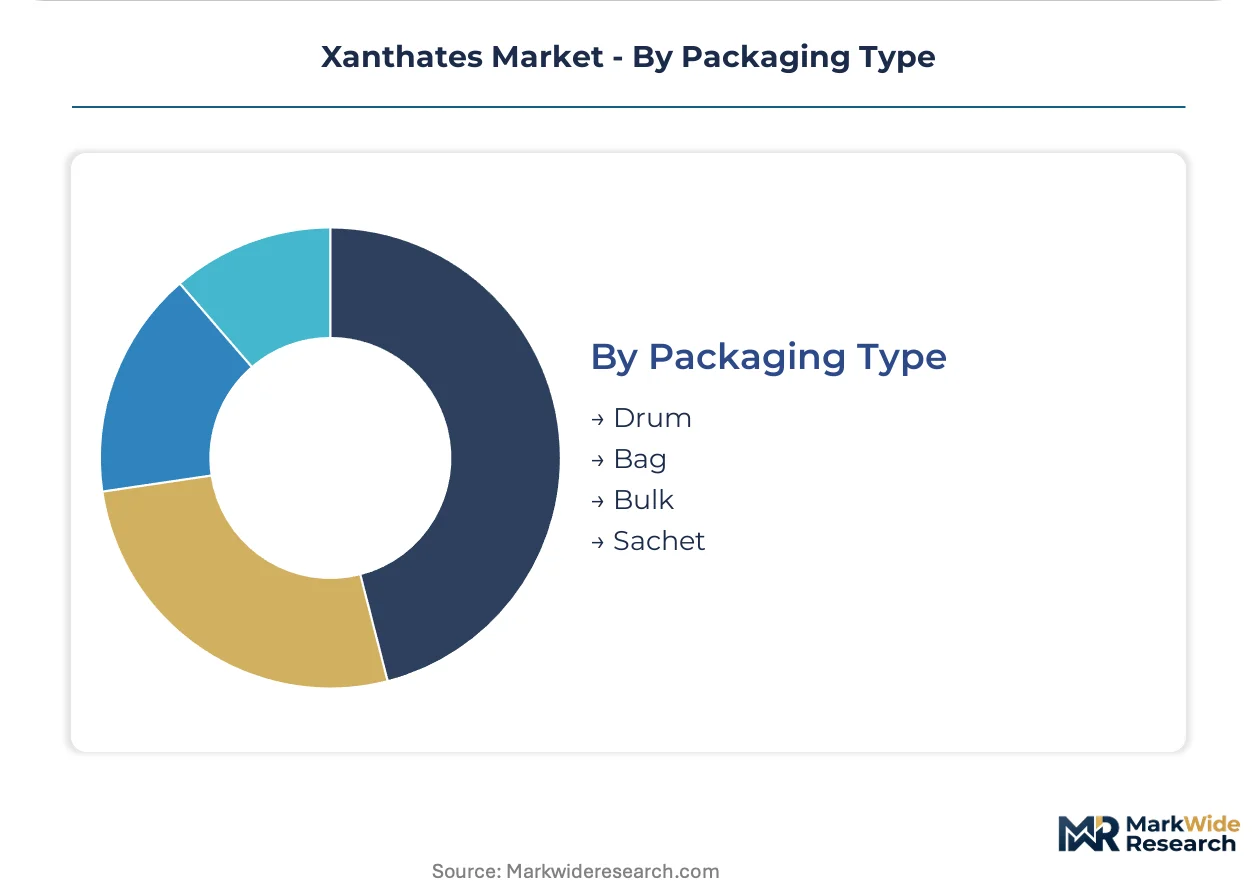
- Drum:Steel containment with nitrogen blanketing preserves xanthate stability during extended storage and multi-modal transport to remote mining sites.
- Bag:Multi-layer laminated sacks balance handling efficiency with moisture protection for high-altitude Andean operations where road access constrains bulk delivery.
- Bulk:Direct pneumatic transfer into automated dosing systems minimizes handling labor and dust exposure at large-scale concentrators with integrated reagent plants.
- Sachet:Pre-measured units serve laboratory-scale flotation testwork and pilot plant campaigns requiring precise reagent accounting.
Procurement shifts toward bulk at major concentrators; drums retain share at remote polymetallic projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate carbon disulfide feedstock infrastructure that anchors xanthate synthesis capacity. Mining investment corridors across Chile, Australia, and South Africa drive collector chemical demand through polymetallic expansion.
Chile
Copper-molybdenum operations in the Atacama Desert deploy selective potassium xanthate blends for complex sulfide separation. The country's environmental regulator enforces strict tailings discharge standards that mandate higher-purity formulations. Antofagasta's mining corridor hosts advanced sensor-based flotation control installations that reduce collector consumption intensity.
Australia
Iron ore and gold producers in Western Australia's Pilbara region sustain bulk sodium xanthate demand through high-throughput flotation circuits. ISO 9001 certification has become mandatory for supply contracts with major mining houses operating across multiple states. Brisbane-based technical service teams support remote site operations with customized formulation adjustments.
China
The Shandong Peninsula and Jiangsu province host integrated carbon disulfide-xanthate production complexes serving domestic and export markets. MEE emission limits on volatile organic compound handling constrain synthesis plant operations and elevate compliance costs. Yantai and Zibo industrial clusters concentrate formulation expertise for rubber processing derivatives.
South Africa
Platinum group metal and gold operations across the Bushveld Complex and Witwatersrand Basin drive collector chemical consumption through deep-level flotation circuits. The country's mineral regulator enforces effluent quality standards that push operators toward biodegradable formulation alternatives. Rustenburg and Johannesburg form the core distribution nodes for southern African supply.
Peru
Polymetallic mining districts in the Andean cordillera above 4,000 meters elevation require custom xanthate blends engineered for altered water chemistry and depressed boiling points. The Ministry of Energy and Mines oversees environmental compliance for tailings management that affects reagent selection. Arequipa and Cusco regions concentrate copper-molybdenum-silver operations demanding selective separation precision.
Xanthates Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a market structure that concentrates procurement power among vertically integrated mining houses. Three to four major suppliers anchor volume contracts with tier-one copper and gold operators, while regional compounders serve fragmented polymetallic projects. Strategic archetypes include backward-integrated feedstock owners, formulation specialists with altitude-specific expertise, and distribution-heavy service providers. Capacity expansion and long-term offtake contracting represent the dominant competitive moves as spot market purchasing declines.
Among the backward-integrated tier, Senmin International exemplifies captive carbon disulfide supply sustaining margin resilience across southern African mining belts. Coogee Chemicals occupies a position as a formulation specialist serving high-altitude Andean operations where standard products fail. Orica Limited anchors the distribution-intensive archetype through dense service networks in Australian iron ore corridors. These three represent distinct strategic positions without implying specific market share or revenue figures.
| Leading Market Players |
|---|
| Senmin International |
| Coogee Chemicals |
| Orica Limited |
| Yantai Humon Chemical |
| China Xanthate International |
| QiXia TongDa Flotation Reagent |
| SNF Group |
| Tieling Flotation Reagent |
| Vanderbilt Chemicals |
| Others |
Value Network & Pricing Analysis
EPA effluent guidelines for mining discharge gate qualified supply and premium-tier pricing access, constraining non-compliant compounders to spot-market tiers while ISO-certified producers capture long-term offtake premiums. Carbon disulfide feedstock volatility and REACH registration barriers compress margin predictability across non-integrated suppliers.
Pricing Analysis
Short lead-time premiums command pricing advantages as tier-one mining houses lock in three-year supply agreements with fixed price collars, displacing spot purchasing. Contract-based long-term offtake dominates, with price differentiation driven by ISO 9001 certification tier and volume scale commitments. Cost compression in standard-grade sodium xanthate intensifies because carbon disulfide price swings erode producer margins. Bulk base-metal operators in Zambia's copper belt exhibit highest price sensitivity, while Peruvian polymetallic specialists accept premiums for altitude-engineered potassium blends.
Supply Chain Analysis
Reverse-logistics flows for drum returns and nitrogen-blanketed container refurbishment sustain reagent stability across multi-modal transport to remote Andean sites. Supply concentrates in China's Shandong Peninsula and Jiangsu province, South Africa's Bushveld Complex corridor, and Australia's Pilbara region. Production draws from carbon disulfide, alkali metal hydroxides, and sulfur feedstocks. Single-source vulnerability from Yangtze River Delta carbon disulfide infrastructure creates chokepoint exposure. Distribution runs through dense technical service networks anchored by regional formulation specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor-based flotation control systems are displacing legacy dosing infrastructure, compressing consumption intensity per ton of concentrate while elevating technical service requirements across supplier relationships.
For Market Incumbents: Extend backward integration into carbon disulfide feedstock to defend margin resilience against raw material volatility. Deepen technical service teams in Chilean copper corridors to embed process engineers directly into customer operations. Address the threat of automated dosing optimization reducing collector throughput by 15-20% through proprietary machine learning mineralogy partnerships.
For New Entrants and Emerging Players: Begin with rubber processing accelerator derivatives in East Asian tire manufacturing clusters, where specialty purity requirements create defensible margin pools outside mining procurement concentration. Target agricultural soil treatment applications facing biodegradability testing uncertainty, as EU protocol delays freeze incumbent formulation pipelines. Pursue ISO 9001 certification arbitrage to unlock tier-one mining house procurement mandates.
For Investors and Strategic Acquirers: REACH authorization timeline extensions beyond 18-24 months are the leading indicator that stranded demand capture opportunities are materializing for compliant European compounders. Frame long-term viability around consolidation of regional formulation specialists with altitude-specific expertise and captive feedstock positions. Monitor EPA effluent guideline enforcement intensity in United States mining jurisdictions as the inflection signal for premium-grade formulation demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Disulfide | Captive feedstock supply insulates margin resilience against natural gas and sulfur market swings. |
| ISO 9001 Certification Investment | De facto mining house procurement mandates create tiered access advantages over uncertified competitors. |
| High-Altitude Formulation Specialization | Custom blends for Andean operations above 4,000 meters command technical premiums from Peruvian polymetallic miners. |
| Long-term Supply Agreement Lock-in | Three-year offtake contracts with fixed price collars displace spot purchasing among tier-one copper operators. |
| Rubber Accelerator Diversification | Specialty derivative production for East Asian tire clusters accesses concentrated margin pools outside mining cyclicality. |
Research Methodology
Independent corroboration across plant managers at xanthate synthesis facilities, procurement leads at major mining houses, distribution channel partners in southern African supply corridors, and technical R&D directors at flotation reagent compounders underwrites the qualitative findings. Secondary validation draws from customs and trade data, SEC filings of diversified chemical conglomerates, EPA effluent guideline documentation, and REACH registration databases. Bottom-up volume modeling triangulates against top-down value estimates across the projection horizon.
Rate-of-change decomposition separates volume growth from price/mix effects across product type segmentation by alkali metal salt formulation, end-use industry concentration in mining versus rubber processing, application intensity in froth flotation circuits, and regional production hub clustering. CAGRs derive from regression analysis of historical consumption patterns against mining capacity expansion pipelines and regulatory compliance cost trajectories. Forecast inputs incorporate carbon disulfide price volatility indices and REACH authorization timeline assumptions.
Underlying measurement precision varies by segment; sodium xanthate volume estimates carry tighter precision than specialty ammonium salt derivatives due to standardized bulk procurement reporting. Forecasts reflect documented assumptions on mining investment cycle timing and environmental regulator enforcement intensity. Practitioners should monitor EPA effluent guideline revision schedules and EU biodegradability protocol finalization for early signals of formulation demand shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
4-Dichlorodiphenyl Sulfone (DCDPS) Market
Chemicals
Ethyl Chloride Market
Chemicals
Lauryl Dimethyl Amine Oxide Market
Chemicals
Muriatic Acid Market
Chemicals
Desalination Chemicals Market
Chemicals
SLS and LABSA Market
Chemicals
Phosphotungstic Acid Market
Chemicals
Fireworks Market
Chemicals
Paint Remover Market
Chemicals
Barbituric Acid Market
Chemicals
Photographic Chemicals Market
Chemicals
Glycerol Carbonate Market
Chemicals
Para Cresol Market
Chemicals
Menadione Market
Chemicals
Global Methylene Chloride Market
Chemicals
Aircraft Cleaning Chemicals Market