
 Global Cysteine Market | 2026-2036
Global Cysteine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cysteine Market Foresight
ISO 22000 certification for food-grade amino acid production is rotating supplier eligibility across the Global Cysteine Market, favoring manufacturers with integrated fermentation and downstream purification capabilities. Wacker Chemie AG leverages its biotechnology platform to sustain captive supply chains for pharmaceutical-grade reduced L-cysteine. Ajinomoto Co. Inc. anchors amino acid expertise through decades of fermentation scale-up in Japan and overseas production nodes. CJ CheilJedang Corp. competes on cost-optimized microbial fermentation, dominating feed-grade volumes across Asian markets.
Cysteine is a sulfur-containing proteinogenic amino acid with the molecular formula C₃H₇NO₂S, manufactured primarily via microbial fermentation of glucose using genetically optimized Escherichia coli or Corynebacterium strains, with hydrolysis and crystallization as downstream steps; it functions as a reducing agent, antioxidant precursor, and structural building block in peptides and proteins. The L-cysteine hydrochloride segment occupies the largest revenue share due to its stability and solubility advantages in pharmaceutical and food applications, while N-acetyl L-cysteine leads growth as clinicians expand its use in acetaminophen overdose protocols and chronic respiratory management. Powder form dominates procurement volumes because of handling efficiency in bulk compounding, though liquid formulations are gaining traction in automated pharmaceutical manufacturing lines.
EMA guidelines on amino acid impurities in parenteral nutrition, China's SAMR food additive safety standards, and FDA GRAS notifications collectively constrain which suppliers can access regulated end-use channels. These frameworks elevate analytical burden and documentation costs, compressing margins for non-integrated traders while rewarding manufacturers with in-house quality laboratories. Stakeholders must monitor regulatory divergence between pharmacopeial-grade and food-grade specifications, as tightening purity thresholds in one jurisdiction often cascade into reformulation requirements across export portfolios.
Market Dynamics
Fermentation capacity concentration in China's Hubei and Zhejiang provinces is redrawing supplier power dynamics, as integrated manufacturers with captive glucose supply chains squeeze non-integrated traders out of pharmaceutical-grade procurement channels.
Growth Catalysts
- Acetaminophen overdose protocols:Emergency medicine departments in Germany and Japan are expanding N-acetyl L-cysteine stocking requirements, pulling volume through hospital procurement systems.
- REACH compliance tightening:ECHA's elevated purity thresholds for sulfur-containing amino acids are disqualifying legacy suppliers, consolidating qualified vendor pools for EU pharmaceutical formulators.
- Fermentation yield improvements:Genetically optimized Corynebacterium strains are reducing glucose-to-cysteine conversion costs at industrial biotech facilities.
Market Restraints
- Feedstock volatility:Corn-derived glucose prices fluctuate with agricultural commodity cycles, compressing margins for non-captive fermentation operators.
- Geographic supply concentration:Over 60 percent of L-cysteine hydrochloride fermentation capacity sits within 200 kilometers of Wuhan, creating single-point-of-failure exposure.
- Substitution pressure:Synthetic methionine-cysteine blends in poultry nutrition are displacing pure L-cysteine in price-sensitive feed applications.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO's accelerated approval pathways for active pharmaceutical ingredients are attracting contract manufacturing investment for mucolytic-grade cysteine derivatives.
- Biologics excipient demand:Monoclonal antibody formulations require reduced L-cysteine as a stabilizer, opening high-margin pharmaceutical channels.
- Green chemistry mandates:China's dual carbon goals are incentivizing microbial fermentation over traditional hair-hydrolysis routes, favoring biotech-based producers.
Industry Challenges
- Pharmacopeial certification timelines:USP and EP compliance documentation for new production batches extends 18-24 months, freezing capacity expansion returns.
- Downstream purification bottlenecks:Crystallization expertise scarcity limits yield recovery rates at scale-up facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cysteine Market |
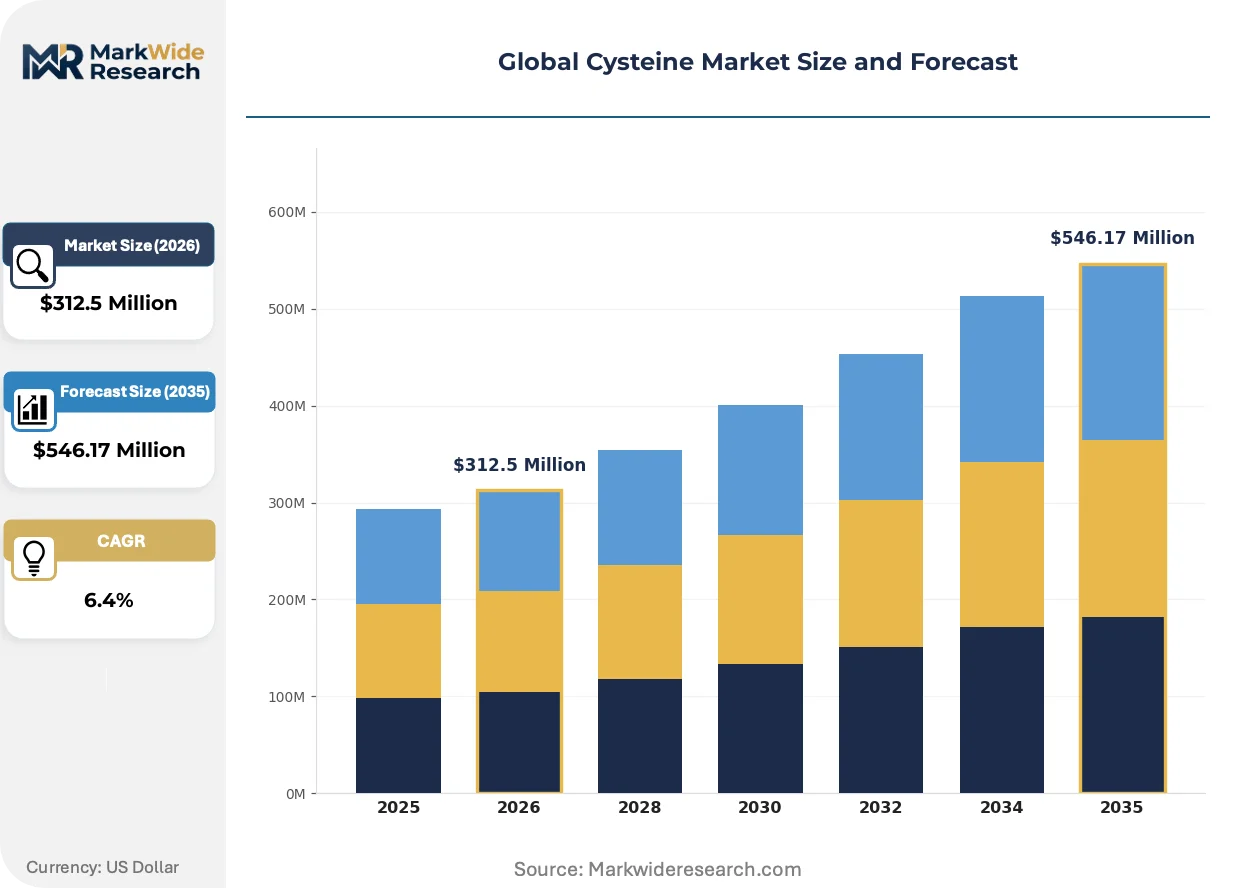
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: L-Cysteine Hydrochloride, L-Cysteine Sulfate, D-Cysteine, N-Acetyl L-Cysteine, Reduced L-Cysteine Form: Powder, Crystals, Liquid, Granules, Flakes Application: Food Additives, Animal Feed, Cosmetics, Pharmaceutical Excipients, Detergents End User Type: Food Processing Firms, Feed Manufacturers, Personal Care Producers, Drug Formulators, Cleaning Product Companies |
| Companies Covered | Wacker Chemie AG, Ajinomoto Co. Inc., CJ CheilJedang Corp., Merck KGaA, Evonik Industries AG, Nippon Rika Co. Ltd., Shine Star (Hubei) Biological Engineering Co. Ltd., Wuhan Grand Hoyo Co. Ltd., Zhejiang NHU Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cysteine Market Shifts & Advancements
Continuous processing technologies and analytical quality-by-design frameworks are displacing batch fermentation paradigms, compressing production cycles and redefining competitive differentiation around real-time release testing capabilities.
Single-use bioreactor systems for amino acid fermentation are miniaturizing capital deployment requirements for mid-scale cysteine production. Contract manufacturers in South Korea and Singapore are adopting 2,000-liter disposable vessels for pharmaceutical-grade campaigns. This distributed production model is compressing lead times for regional pharmaceutical supply chains while reducing cross-border regulatory exposure.
EMA's 2023 revision to amino acid impurity limits in parenteral nutrition products is forcing reformulation of legacy cysteine-containing solutions. Manufacturers serving European hospital networks must now demonstrate sub-10 ppm heavy metal profiles through validated ICP-MS protocols. The pharmaceutical-grade segment is responding by segregating fermentation trains and dedicating purification lines to EU-bound output.
Hospital procurement consortia in Japan and Germany are consolidating amino acid purchasing through centralized tenders, displacing fragmented distributor networks. Pharmaceutical-grade cysteine volumes are migrating toward direct manufacturer relationships with documented GMP audit trails. This concentration is most visible in university hospital systems, where formulary committees now mandate single-source qualification for critical excipients.
Global Cysteine Market Segmentation
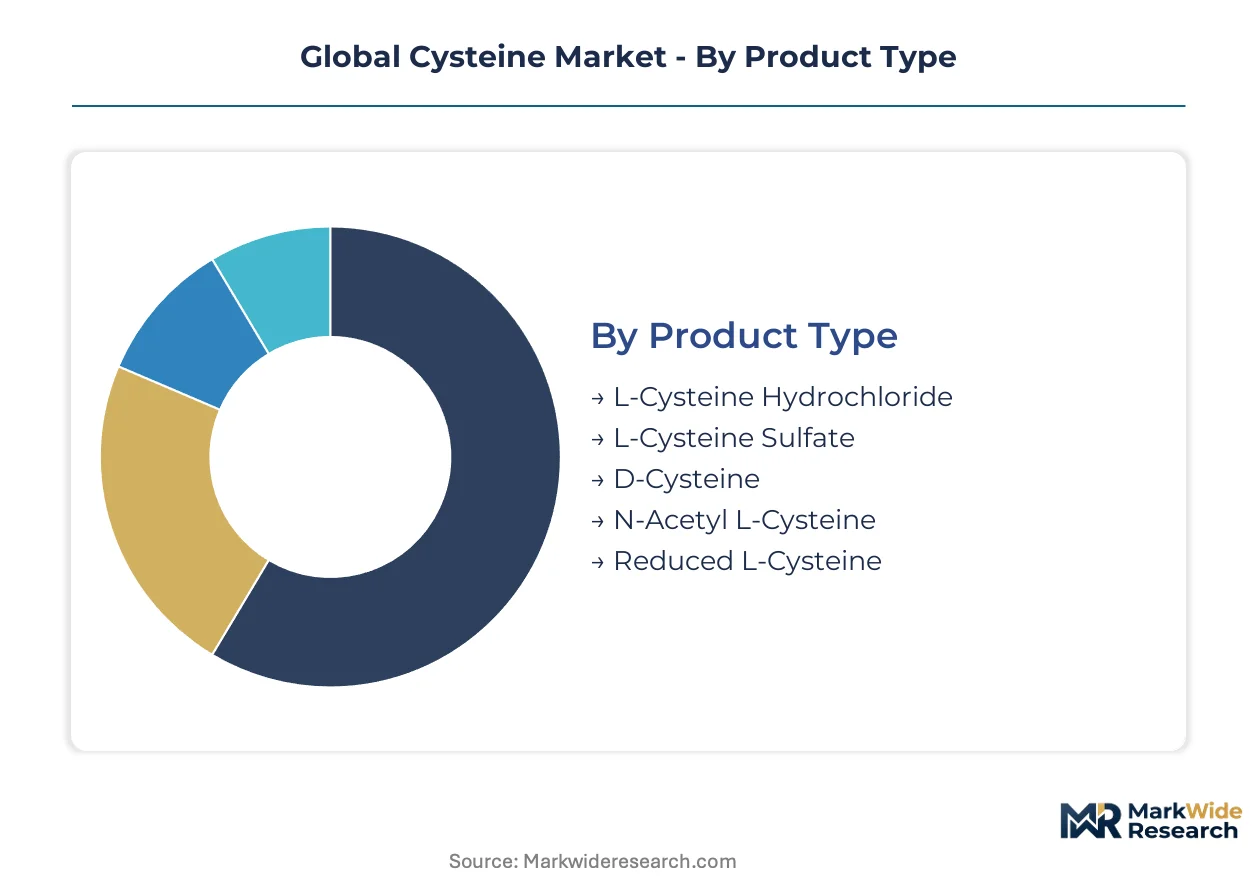
Cysteine derivatives serve divergent purity requirements across pharmaceutical, nutritional, and industrial channels. Segmentation reveals how fermentation economics, regulatory thresholds, and formulation constraints partition procurement behavior between commodity traders and integrated manufacturers.
Product Type:
Export-led pharmaceutical grades dominate cross-border trade flows, while domestic food-grade volumes concentrate near fermentation clusters in China and Japan.
- L-Cysteine Hydrochloride:The hydrochloride salt delivers enhanced stability and aqueous solubility for parenteral nutrition formulations. Hospital procurement systems in Germany and Japan prioritize this grade for compounding pharmacy operations, with EMA and PMDA documentation requirements filtering supplier pools.
- N-Acetyl L-Cysteine:This acetylated derivative crosses cellular membranes more efficiently than native cysteine, supporting acetaminophen overdose protocols and chronic obstructive pulmonary disease management. Emergency medicine departments in university hospital systems are expanding stocking requirements, pulling volume through direct manufacturer contracts.
- L-Cysteine Sulfate:Sulfate salt variant serving niche pharmaceutical applications with specific counterion requirements.
- D-Cysteine:Non-proteinogenic enantiomer employed in specialized research and chiral synthesis applications.
- Reduced L-Cysteine:Free thiol form critical for monoclonal antibody stabilization in biologics manufacturing, commanding premium pharmaceutical-grade pricing.
L-Cysteine Hydrochloride holds the largest share; momentum sits with N-Acetyl L-Cysteine.
Form:
Handling economics and automated manufacturing compatibility drive form selection, with powder and liquid splitting between bulk commodity and precision pharmaceutical channels.
- Powder:Dominates procurement volumes due to handling efficiency in bulk compounding operations and extended shelf stability under controlled humidity. Feed manufacturers and food processing firms in China's Hubei province favor pneumatic conveying systems for powder material flows.
- Liquid:Gaining traction in automated pharmaceutical manufacturing lines requiring direct metered dosing without dissolution steps. Contract manufacturers in South Korea are adopting liquid cysteine for continuous processing campaigns.
- Crystals:High-purity crystalline grades for analytical reference standards and exact-weigh pharmaceutical applications.
- Granules:Free-flowing agglomerated form reducing dust exposure in high-volume feed milling operations.
- Flakes:Compressed solid form for specialized industrial applications requiring controlled dissolution rates.
Powder commands the greatest volume; liquid formulations are climbing the fastest.
Application:
Regulatory stringency stratifies applications, with pharmaceutical and food channels demanding pharmacopeial certification unavailable to industrial users.
- Pharmaceutical Excipients:Reduced L-cysteine functions as an antioxidant stabilizer in parenteral nutrition and biologics formulations. EMA's tightened impurity limits for sulfur-containing amino acids are forcing dedicated fermentation trains for European-bound output.
- Food Additives:Cysteine serves as a dough conditioner and flavor precursor in baked goods manufacturing. China's SAMR food additive safety standards and EU REACH compliance are rotating supplier eligibility toward ISO 22000-certified integrated producers.
- Animal Feed:Synthetic methionine-cysteine blends are displacing pure L-cysteine in price-sensitive poultry nutrition applications.
- Cosmetics:Antioxidant and conditioning properties support hair care and skin care formulations.
- Detergents:Reducing agent functionality in specialized industrial cleaning applications.
Pharmaceutical Excipients generate the highest margins; Food Additives represent the broadest installed base.
End User Type:
Procurement consolidation is compressing distributor networks, with direct manufacturer relationships replacing fragmented purchasing across hospital consortia and feed compounders.
- Drug Formulators:Hospital procurement consortia in Japan and Germany are consolidating amino acid purchasing through centralized tenders, mandating single-source qualification with documented GMP audit trails.
- Feed Manufacturers:Cost-optimized microbial fermentation from CJ CheilJedang and Chinese integrated producers dominates volume procurement, with corn-derived glucose price volatility compressing margins for non-captive operators.
- Food Processing Firms:Processed meat and bakery manufacturers requiring dough conditioning and flavor development functionality.
- Personal Care Producers:Cosmetics formulators seeking antioxidant and conditioning properties for hair and skin applications.
- Cleaning Product Companies:Industrial detergent manufacturers utilizing reducing agent properties.
Drug Formulators drive premium pricing; Feed Manufacturers absorb the greatest absolute volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta's deepwater ports and intermodal freight networks enable efficient export of fermentation-derived amino acids from Shanghai and Ningbo terminals. This infrastructure underwrites China's dominance in cysteine manufacturing capacity.
China
Hubei province hosts concentrated L-cysteine hydrochloride fermentation facilities serving pharmaceutical and food additive channels. GB standards enforced by SAMR mandate progressively stricter purity thresholds for food-grade amino acid exports. Zhejiang's Shaoxing and Taizhou industrial corridors have scaled downstream crystallization capacity to capture value from upstream fermentation.
Germany
University hospital systems in Munich and Heidelberg are expanding N-acetyl L-cysteine procurement for emergency medicine and hepatology departments. REACH compliance administered by ECHA disqualifies non-integrated suppliers lacking documented impurity controls. The Rhine-Main chemical corridor maintains specialized pharmaceutical-grade amino acid formulation capabilities.
Japan
PMDA guidelines on parenteral nutrition excipients are tightening documentation requirements for cysteine derivatives used in biologics stabilization. The Kansai region's Osaka-Kobe pharmaceutical manufacturing cluster sources reduced L-cysteine for monoclonal antibody production. METI's industrial biotechnology initiatives support fermentation yield optimization research.
India
CDSCO's accelerated approval pathways for active pharmaceutical ingredients are attracting contract manufacturing investment for mucolytic-grade cysteine derivatives. Maharashtra's Mumbai-Pune pharmaceutical belt is developing downstream purification capabilities for export-oriented production. Domestic formulators are qualifying new suppliers to reduce import dependency.
South Korea
MFDS regulations on amino acid impurities in injectable formulations are elevating analytical requirements for pharmaceutical-grade procurement. The Busan-Ulsan chemical complex maintains fermentation and downstream processing infrastructure for amino acid derivatives. Contract manufacturers are adopting single-use bioreactor systems for mid-scale pharmaceutical campaigns.
Global Cysteine Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and captive supply chain control. The market exhibits tiered concentration, with integrated fermentation operators commanding pharmaceutical-grade channels while commodity traders compete on feed-grade volumes. Three archetypes dominate: biotechnology platforms with decades of strain optimization, diversified chemical conglomerates leveraging existing infrastructure, and regional specialists concentrating on cost-optimized microbial production. Capacity expansion and pharmacopeial certification acquisition represent the primary competitive vectors.
Within the biotechnology platform tier, Wacker Chemie AG exemplifies integrated fermentation and downstream purification capabilities. Ajinomoto Co. Inc. anchors amino acid expertise through historical fermentation scale-up operations. CJ CheilJedang Corp. occupies the cost-optimized production position, competing on microbial fermentation economics across Asian feed and food markets.
| Leading Market Players |
|---|
| Wacker Chemie AG |
| Ajinomoto Co. Inc. |
| CJ CheilJedang Corp. |
| Merck KGaA |
| Evonik Industries AG |
| Nippon Rika Co. Ltd. |
| Shine Star (Hubei) Biological Engineering Co. Ltd. |
| Wuhan Grand Hoyo Co. Ltd. |
| Zhejiang NHU Co. Ltd. |
| Others |
Supply & Pricing Matrix
EMA and PMDA pharmacopeial certification gates simultaneously filter supplier pools and stratify price tiers, as manufacturers lacking validated impurity controls forfeit pharmaceutical-grade premiums while integrated fermentation operators capture margin premiums through documented GMP audit trails.
Pricing Analysis
Volume-discount tiering separates pharmaceutical-grade reduced L-cysteine from feed-grade hydrochloride salts, with certification depth and captive glucose supply chains driving price differentiation between integrated biotech platforms and non-captive traders. Cost compression in feed-grade channels intensifies as synthetic methionine-cysteine blends displace pure L-cysteine in poultry nutrition. Feed manufacturers exhibit highest price sensitivity due to commoditized procurement, while biologics formulators accept premium pricing for monoclonal antibody-grade reduced L-cysteine with validated heavy metal profiles.
Supply Chain Analysis
Wuhan's 200-kilometer fermentation radius constitutes a chokepoint, as over sixty percent of L-cysteine hydrochloride capacity concentrates in China's Hubei and Zhejiang provinces with limited geographic diversification. Downstream purification draws from crystallization expertise concentrated in Shaoxing and Taizhou industrial corridors, with corn-derived glucose feedstock tethered to agricultural commodity cycles. Single-source vulnerability from this geographic concentration elevates supply chain risk. Distribution runs through Yangtze River Delta deepwater ports at Shanghai and Ningbo terminals for export-oriented pharmaceutical volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic methionine-cysteine blends in animal feed represent the primary substitution threat that cysteine incumbents must navigate through certification depth and captive supply chain control.
For Market Incumbents: Compound fermentation yield advantages through Corynebacterium strain optimization and backward integration into glucose supply chains. Secure pharmacopeial certification renewals ahead of EMA impurity threshold tightening. Defend against methionine-cysteine blend displacement by anchoring pharmaceutical-grade relationships with documented GMP audit trails. For New Entrants and Emerging Players: CDSCO's accelerated API approval pathways offer fast-track qualification for mucolytic-grade N-acetyl L-cysteine production targeting India's Mumbai-Pune pharmaceutical belt. Target underpenetrated liquid formulation channels in South Korean contract manufacturing. Pursue single-use bioreactor deployment for mid-scale campaigns with reduced capital requirements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Chinese fermentation specialists lacking downstream crystallization capabilities. Five-to-ten year viability hinges on pharmacopeial certification breadth rather than commodity volume scale. Watch for EMA and PMDA impurity threshold harmonization as inflection signal for consolidation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glucose Supply | Captive corn-derived feedstock insulates margins from agricultural commodity volatility in Hubei province. |
| Pharmacopeial Certification Investment | USP and EP compliance documentation unlocks hospital procurement consortia in Germany and Japan. |
| Single-Use Bioreactor Deployment | Disposable 2,000-liter vessels compress capital requirements for mid-scale pharmaceutical campaigns in South Korea. |
| Crystallization Expertise Acquisition | Downstream purification capabilities determine yield recovery rates at scale-up facilities in Zhejiang corridor. |
| Green Fermentation Transition | Microbial routes over hair-hydrolysis align with China's dual carbon goals and EU REACH compliance. |
Research Methodology
Desk research of customs trade flows, EMA submission databases, and SAMR food additive registrations preceded structured interviews with fermentation plant managers, pharmaceutical procurement leads at German university hospital systems, CDSCO regulatory affairs officers, and amino acid distribution channel partners. Primary fieldwork combined with secondary validation from SEC filings of listed biotechnology platforms and ACC industrial reports. Bottom-up capacity modeling triangulated against top-down demand estimates from parenteral nutrition and biologics formulation channels.
Variance-decomposition across the projection horizon isolates volume drivers by product type, application channel, and regional regulatory cluster. Segmentation dimensions modeled include pharmaceutical grade tier, end-use industry, and fermentation geography. CAGRs derive from iterative reconciliation of capacity expansion announcements, pharmacopeial certification timelines, and substitution elasticity estimates for methionine-cysteine blends in feed applications. Industry-specific inputs encompass glucose-to-cysteine conversion yield improvements and EMA impurity threshold revision schedules.
Decision-makers should treat outputs as directional under assumptions of sustained REACH compliance stringency and stable corn-derived glucose feedstock pricing; material deviation in regulatory harmonization or agricultural commodity cycles would warrant model refresh. Practitioners should keep alternative scenarios live as CDSCO approval pathway efficiency and China's dual carbon policy implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Ethylenediamine (EDA) Market
Chemicals
Global Monochloroacetic Acid Market
Chemicals
Bronopol Market
Chemicals
Hydrazine Market
Chemicals
Anhydrides Market
Chemicals
Methyldiisopropanolamine Market
Chemicals
Benzalkonium Bromide Market
Chemicals
3,5-Dinitroaniline Market
Chemicals
Non-Halogenated Flame Retardant Chemicals Market
Chemicals
Global Aldehyde Market
Chemicals
Dimethyldichlorosilane Market
Chemicals
Global Methyl Methacrylate (MMA) Monomer Market
Chemicals
N-Propanol Market
Chemicals
Flatting Agents Market
Chemicals
Europe Flame Retardant Chemicals Market
Chemicals
Fungicide Active Ingredients Market