
 Cesium Hydroxide Market | 2026-2036
Cesium Hydroxide Market Size, Share, and Industry Trends Forecast 2026-2036
Cesium Hydroxide Market Analysis
The divergence between premium and commodity tiers is hardening as high-purity grades command widening price premiums over technical and industrial grades. Albemarle Corporation leverages its integrated cesium resource base to secure upstream supply stability for specialty chemical customers. American Elements sustains a broad catalog spanning reagent through high-purity grades, serving research institutions and electronics fabricators. Merck KGaA anchors its position through stringent quality protocols that align with pharmaceutical and nuclear application requirements.
Cesium hydroxide (CsOH) is a strongly basic alkali metal hydroxide, typically supplied as a hygroscopic solid or aqueous solution with purity grades ranging from industrial to 99.9%+ high-purity specifications; it functions primarily as a precursor in cesium salt synthesis, specialty glass manufacturing, and drilling fluid formulations. High-purity grades capture the strongest margin pools due to exacting trace-metal limits demanded by electronics and nuclear end users. Oilfield chemicals and catalyst applications represent volume anchors, though nuclear applications and chemical synthesis segments are expanding fastest as advanced reactor designs and pharmaceutical intermediates drive specification upgrades.
EPA hazardous waste regulations and OSHA workplace exposure limits shape domestic manufacturing and handling protocols, while REACH and RoHS frameworks in Europe restrict contaminant thresholds in downstream electronics applications. These regulatory layers elevate compliance costs for commodity producers while creating protected niches for certified high-purity suppliers. Stakeholders must monitor evolving nuclear safety standards and battery electrolyte research directions, as these vectors will determine which purity grades and packaging formats capture future value.
Market Dynamics
Purity-grade stratification now dominates cesium hydroxide commercial dynamics as electronics and nuclear end-users impose sub-ppm trace-metal specifications that commodity producers cannot meet. This technical bifurcation concentrates margin capture among certified high-purity suppliers while relegating industrial-grade volumes to price-competitive drilling and catalyst applications.
Growth Catalysts
- Specialty glass expansion:Precision optics manufacturers in Germany and Japan are scaling high-purity CsOH procurement for refractive index tuning in advanced lens systems. Fiber optic cable production for data center interconnects drives additional volume.
- REACH Article 33 compliance:Electronics fabricators across the European Union now mandate documented contaminant thresholds below 100 ppm for cesium compounds used in semiconductor cleaning formulations, forcing specification upgrades across the supply base.
- Advanced reactor R&D:Molten salt reactor developers in the United States and Canada require ultra-high-purity cesium hydroxide for coolant salt synthesis, creating demand insulated from commodity pricing cycles.
Market Restraints
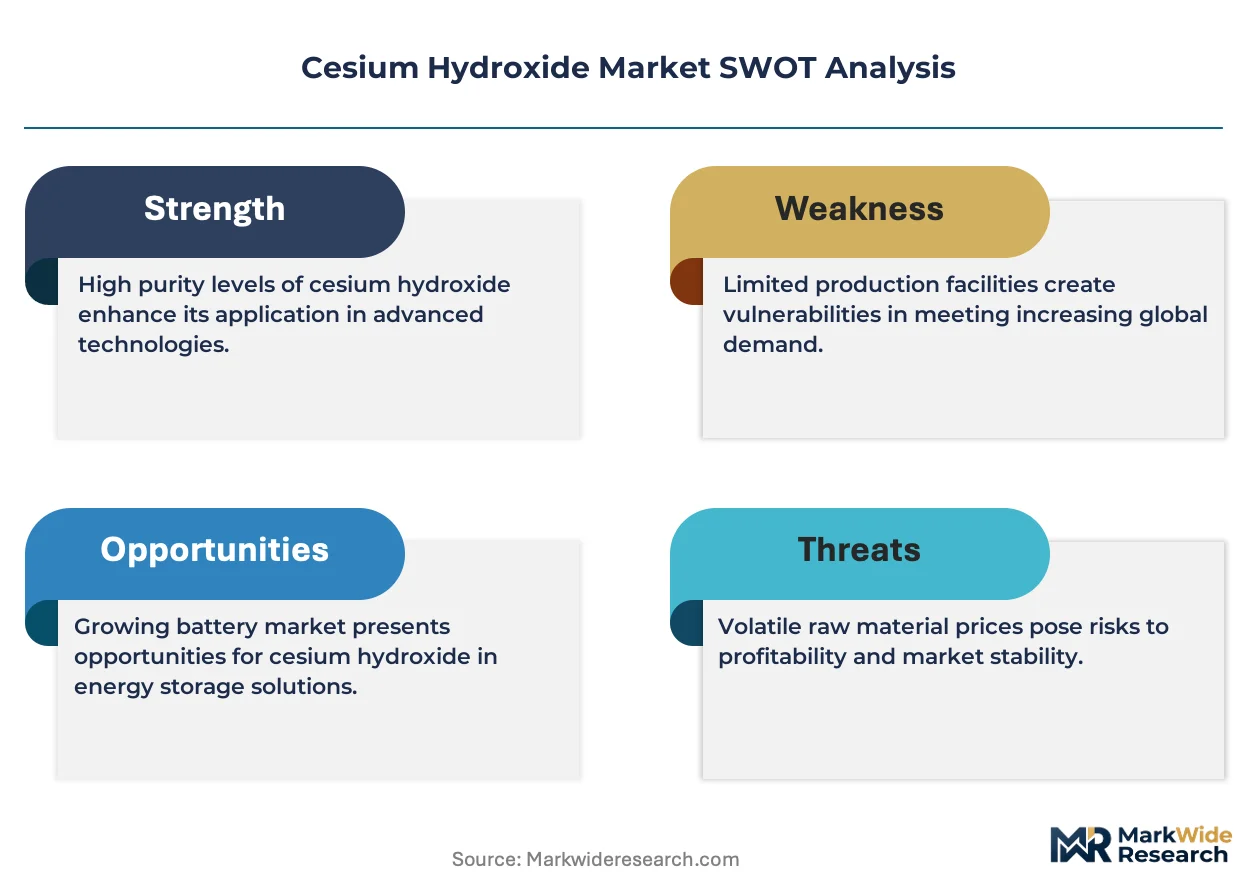
- Upstream resource concentration:Economically viable pollucite ore deposits concentrate in Canada and Zimbabwe, creating geopolitical exposure for processors dependent on single-source concentrate supply.
- Caustic soda substitution:Industrial cleaning and some catalyst applications tolerate potassium hydroxide or sodium hydroxide where trace-metal sensitivity permits, capping volume growth in technical-grade segments.
- EPA RCRA hazardous waste classification:Spent cesium hydroxide solutions carry cradle-to-grave tracking requirements that elevate disposal costs and deter small-volume users from adoption.
Strategic Opportunities
- Solid-state battery electrolyte research:Cesium hydroxide-derived salts are emerging as candidate dopants for sulfide-based solid electrolytes, with South Korean and Japanese materials institutes accelerating evaluation timelines.
- India BIS certification pathway:Domestic specialty chemical manufacturers can capture import substitution value by achieving Bureau of Indian Standards certification for pharmaceutical-grade material ahead of formal purity mandates.
- Direct-to-lab distribution:Research institutions and university chemistry departments are migrating from distributor networks to manufacturer-direct procurement portals, compressing channel margins and improving lot traceability.
Industry Challenges
- Analytical chemistry talent scarcity:ICP-MS operators capable of certifying sub-ppm impurity profiles command premium compensation, constraining quality control throughput at expansion-stage producers.
- Multi-jurisdiction certification timelines:Simultaneous pursuit of USP, ACS Reagent, and ISO 17025 accreditations extends product launch cycles by 18-24 months for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cesium Hydroxide Market |
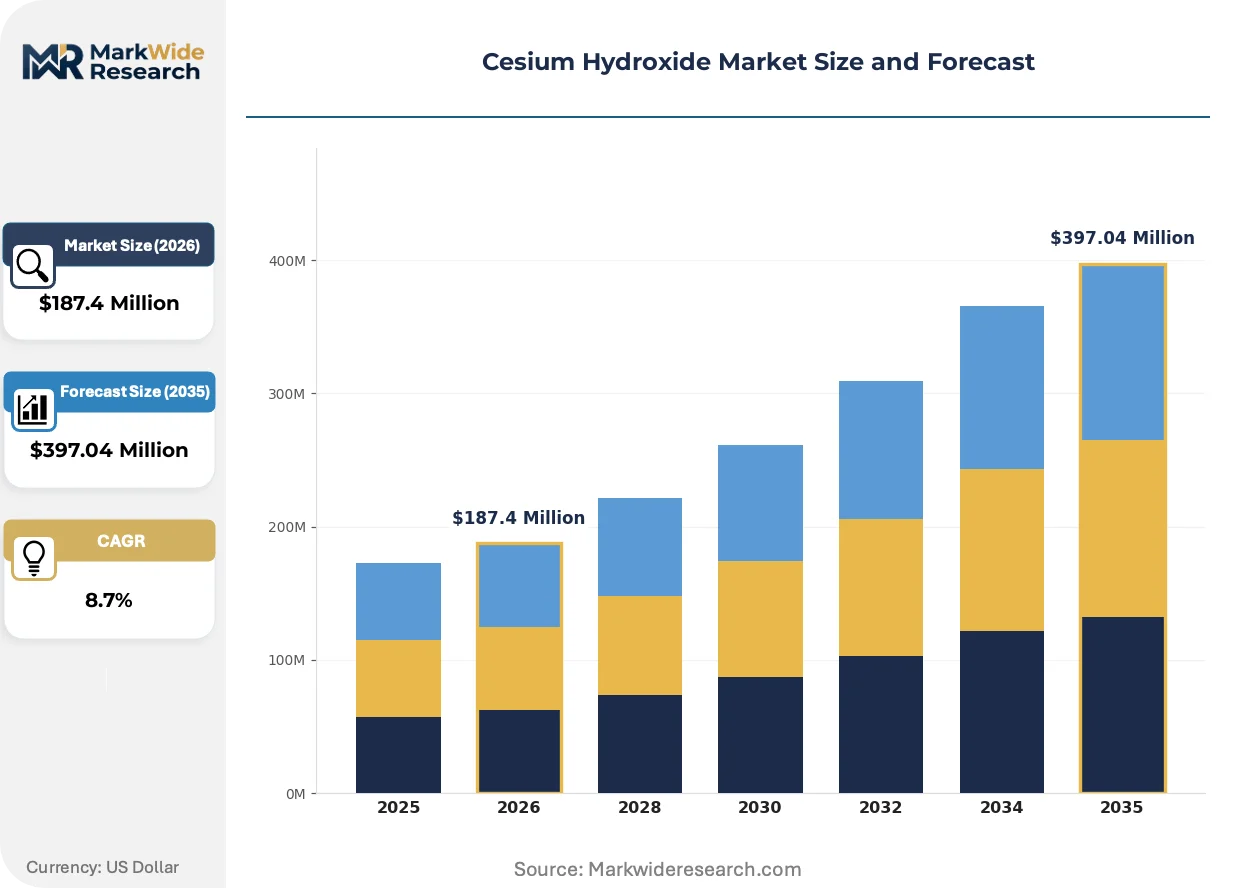
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Purity, Technical Grade, Reagent Grade, Industrial Grade Application: Oilfield Chemicals, Catalyst, Nuclear Applications, Chemical Synthesis End User: Pharmaceuticals, Electronics, Energy, Research Institutions Packaging Type: Drums, Bags, Bulk Containers, Cylinders |
| Companies Covered | ProChem, Inc., Cabot Corporation, American Elements, ESPICorp Inc., Power Metals Corp., Merck KGaA, Albemarle Corporation, Fluorochem Ltd., Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cesium Hydroxide Market Emerging Trajectories
Continuous crystallization technology is rewriting process economics for high-purity cesium hydroxide production, enabling real-time impurity rejection that batch precipitation cannot match. This shift favors capital-intensive producers capable of integrating upstream ore processing with downstream purification.
Membrane electrodialysis is rewriting the technical baseline for aqueous cesium hydroxide concentration, replacing energy-intensive evaporative steps with selective ion transport. Specialty glass manufacturers in Germany and Japan are qualifying electrodialysis-produced material for critical optical applications within compressed validation cycles. The technology is rewriting competitive positioning by decoupling purity achievement from thermal history constraints that compromise optical-grade specifications.
REACH SVHC candidate list expansion is rewriting compliance obligations for cesium compound importers, with ECHA evaluations of cesium-containing substances triggering downstream notification requirements. Electronics chemical distributors in the Netherlands and France are pre-emptively securing full material disclosure documentation from Asian suppliers. The regulation is rewriting procurement protocols as original equipment manufacturers demand third-party-verified contaminant data prior to contract renewal.
Consolidated procurement by integrated specialty materials conglomerates is rewriting vendor relationship structures, with multi-year offtake agreements replacing spot-market transactions for high-purity grades. North American nuclear research facilities and Asian battery electrolyte developers are centralizing CsOH sourcing through single-supplier frameworks with embedded technical service provisions. This concentration is rewriting pricing transparency as negotiated contract terms displace published price references.
Cesium Hydroxide Market Segmentation
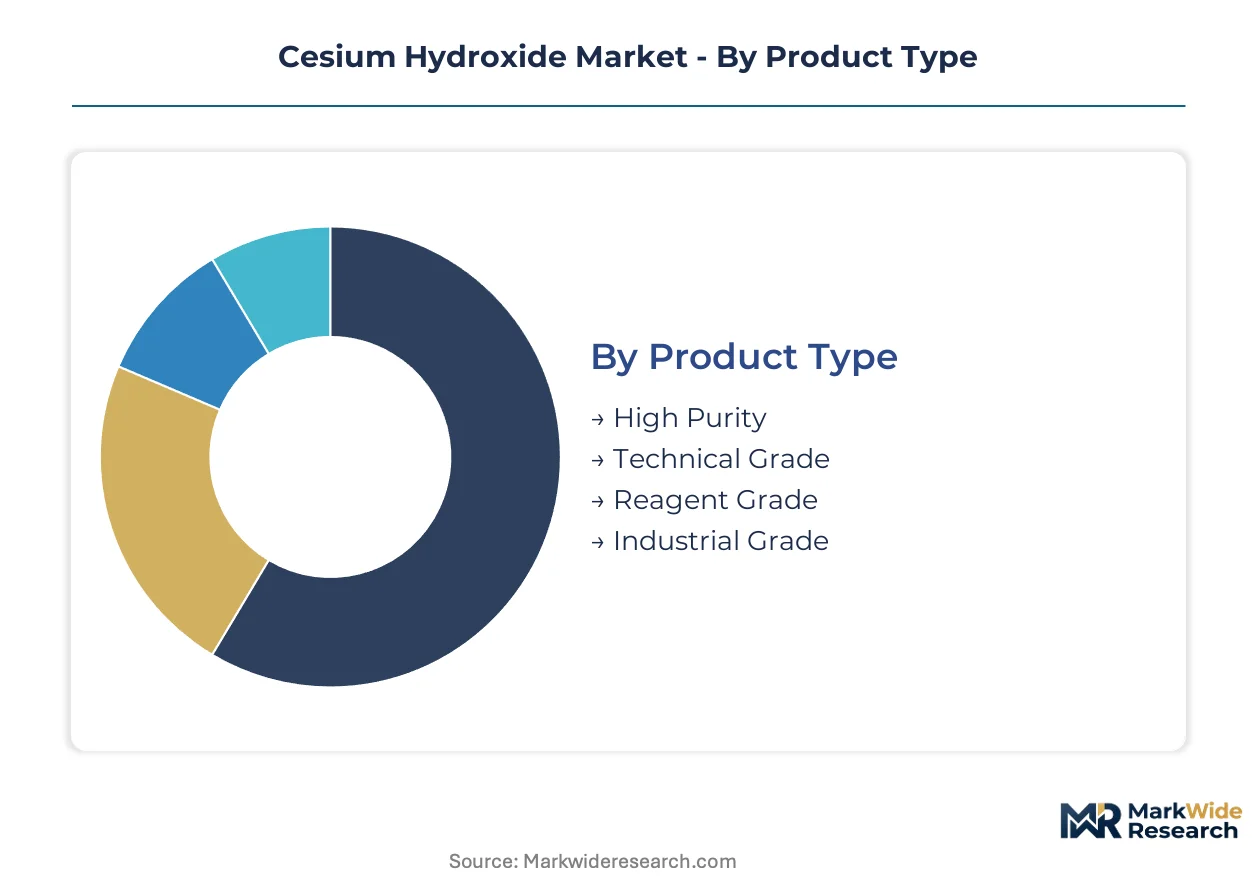
Cesium hydroxide procurement patterns diverge sharply across purity thresholds and end-use sensitivity. Electronics fabricators and nuclear facilities impose sub-ppm specifications that industrial drilling operations do not require, fragmenting supplier strategies and margin structures.
Product Type:
Customization intensity scales inversely with volume throughput across this category.
- High Purity:Material meeting 99.9%+ specifications with strict trace-metal ceilings. Demand concentrates in German and Japanese precision optics manufacturers where refractive index tuning requires contaminant control below 100 ppm.
- Technical Grade:Intermediate purity suitable for catalyst substrates and industrial chemical synthesis. Specifications tolerate higher alkali metal contamination where reaction chemistry rather than optical performance governs outcomes.
- Reagent Grade:ACS or equivalent certified material for analytical laboratories and pharmaceutical intermediates. Procurement runs through distributor networks with lot-specific certificates of analysis.
- Industrial Grade:Bulk volumes for drilling fluid density adjustment and commodity chemical processing. Price sensitivity drives substitution toward potassium hydroxide where process tolerance permits.
Leading the category by volume: Industrial Grade. Expanding most quickly: High Purity.
Application:
End-use maturity determines specification stringency and contract duration across this category.
- Nuclear Applications:Ultra-high-purity CsOH for molten salt reactor coolant synthesis. United States and Canadian advanced reactor developers specify material with documented thermal stability across repeated freeze-thaw cycles.
- Chemical Synthesis:Precursor for cesium salts used in pharmaceutical intermediates and specialty organic reactions. European REACH compliance mandates full material disclosure for downstream notification.
- Oilfield Chemicals:Density-modifying additive for high-pressure drilling fluids. Demand tracks North American shale activity and offshore exploration budgets in the Gulf of Mexico.
- Catalyst:Support material for petroleum refining and emissions control systems. Refiners in Texas and Louisiana specify technical-grade material with consistent particle size distribution.
Volume leadership: Oilfield Chemicals. Steepest expansion trajectory: Nuclear Applications.
End User:
Customer sophistication determines packaging, documentation, and technical service requirements across this category.
- Electronics:Semiconductor cleaning formulations and display manufacturing. South Korean and Japanese fabricators mandate REACH Article 33 compliance with third-party-verified contaminant thresholds.
- Research Institutions:University chemistry departments and national laboratories. Procurement is shifting toward manufacturer-direct portals with embedded lot traceability and certificate archival.
- Pharmaceuticals:Active pharmaceutical ingredient synthesis and analytical reference standards. USP and EP compliance requires extended stability data and accelerated degradation studies.
- Energy:Battery electrolyte research and grid-scale storage development. Solid-state battery programs in Japan evaluate cesium hydroxide-derived dopants for sulfide electrolyte conductivity enhancement.
Fastest-growing demand: Electronics. Highest specification barriers: Pharmaceuticals.
Packaging Type:
Scale economies and handling safety dictate format selection across this category.
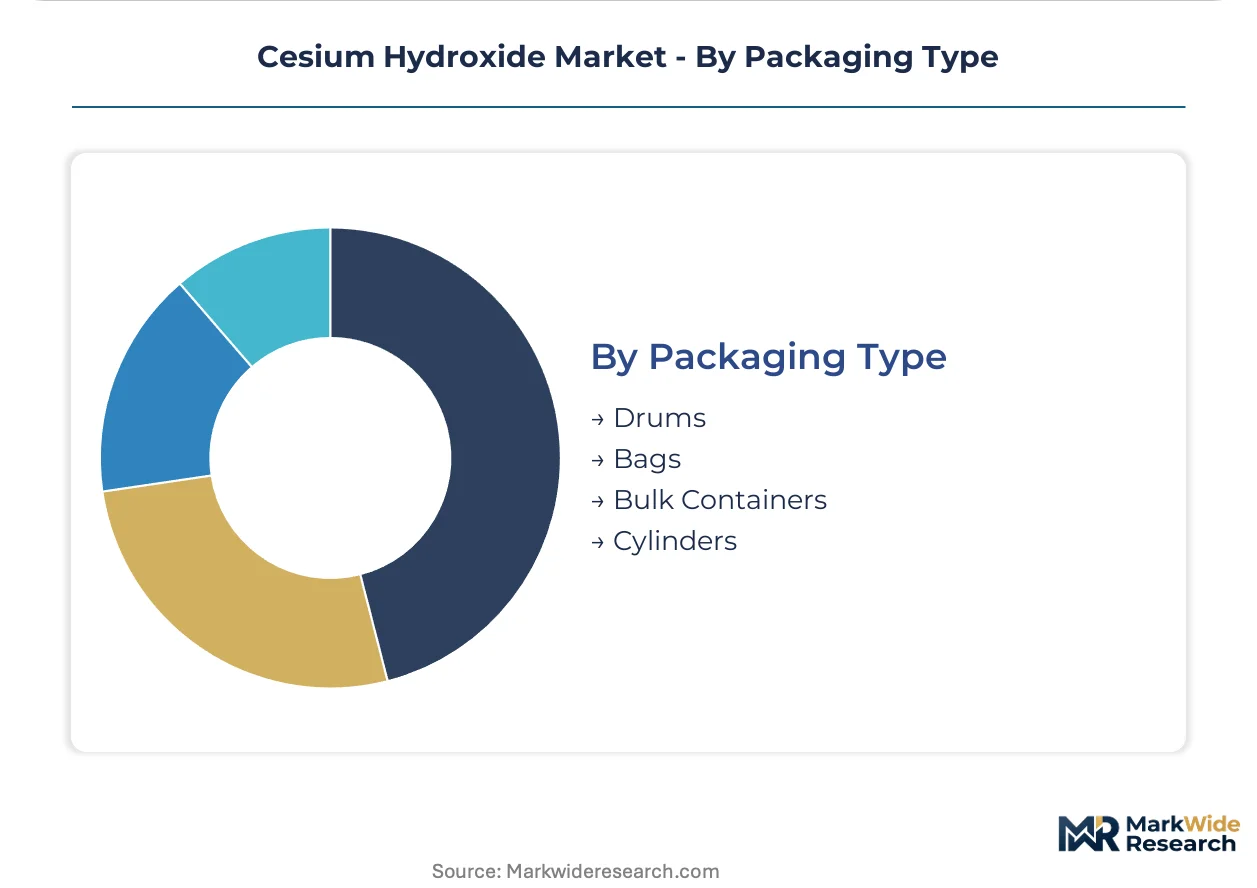
- Drums:Standard 200-liter steel or polyethylene containers for liquid solutions and hygroscopic solids. Electronics chemical distributors in the Netherlands prefer drum formats with integrated nitrogen padding for moisture exclusion.
- Bulk Containers:Intermediate bulk containers and tote tanks for high-volume catalyst and oilfield chemical customers. Refillable formats reduce per-kilogram packaging waste compliance costs under EPA regulations.
- Bags:Multi-layer laminated sacks for free-flowing technical-grade powder. Indian pharmaceutical manufacturers specify bag formats with heat-sealed inner liners to prevent moisture ingress during monsoon season transport.
- Cylinders:Pressurized or sealed metal cylinders for ultra-high-purity material requiring inert atmosphere preservation. Nuclear research facilities in Canada mandate cylinder delivery with pressure integrity certification.
Dominant format by volume: Drums. Gaining share fastest: Bulk Containers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty glass and precision optics manufacturers in Germany and Japan anchor high-purity cesium hydroxide procurement. Molten salt reactor developers in the United States and Canada are scaling ultra-high-purity material sourcing. Electronics fabricators across South Korea and Taiwan impose sub-ppm contaminant thresholds that reshape supplier qualification protocols.
United States
Advanced reactor developers in Idaho National Laboratory and Oak Ridge National Laboratory specify ultra-high-purity CsOH for molten salt coolant synthesis. EPA RCRA hazardous waste classification elevates disposal compliance costs for spent solutions. Texas and Louisiana refiners anchor technical-grade demand through catalyst support applications in petroleum processing.
Germany
Precision optics manufacturers in Jena and Mainz scale high-purity procurement for refractive index tuning in advanced lens systems. REACH Article 33 compliance mandates documented contaminant thresholds below 100 ppm for semiconductor cleaning formulations. The Rhine-Main industrial corridor concentrates specialty glass R&D facilities qualifying electrodialysis-produced material.
China
Domestic pollucite processing capacity in Jiangxi and Hunan provinces underpins upstream concentrate supply for specialty chemical synthesis. MIIT industrial standards for electronic-grade chemicals tighten trace-metal specifications for display manufacturing inputs. The Yangtze River Delta cluster hosts expanding fiber optic cable production driving additional high-purity volume.
Japan
Solid-state battery research programs at national materials institutes evaluate cesium hydroxide-derived dopants for sulfide electrolyte conductivity enhancement. METI technology roadmaps prioritize domestic sourcing security for critical battery materials. Osaka-based specialty glass fabricators maintain stringent optical-grade qualification cycles for electrodialysis-produced material.
Canada
Pollucite ore extraction in Bernic Lake, Manitoba supplies concentrated cesium feedstock to North American processors. Canadian Nuclear Safety Commission licensing frameworks govern ultra-high-purity material handling for advanced reactor R&D partnerships. Ontario-based nuclear research facilities centralize CsOH sourcing through single-supplier frameworks with embedded technical service provisions.
Cesium Hydroxide Market Vendor Landscape
Premium-margin players sit above commodity-margin players across purity-grade stratification. High-purity certification capabilities concentrate margin capture among integrated resource holders and specialty chemical houses, while industrial-grade volumes fragment across regional processors. Three archetypes dominate: upstream-integrated miners with captive concentrate supply, diversified specialty chemical houses with multi-grade portfolios, and research-focused distributors serving laboratory end-users. Competitive moves center on backward integration into pollucite processing and multi-year offtake agreements that displace spot-market transactions.
Among North American resource-integrated players, Albemarle Corporation and Power Metals Corp. exemplify upstream-anchored positioning. American Elements occupies a position within the multi-grade specialty chemical tier, spanning reagent through high-purity specifications. Merck KGaA anchors the stringent quality protocol segment, aligning with pharmaceutical and nuclear application requirements. These three represent the structural spectrum from raw material control through distribution reach.
| Leading Market Players |
|---|
| ProChem, Inc. |
| Cabot Corporation |
| American Elements |
| ESPICorp Inc. |
| Power Metals Corp. |
| Merck KGaA |
| Albemarle Corporation |
| Fluorochem Ltd. |
| Thermo Fisher Scientific |
| Others |
Supply Flow & Price Mechanics
Integrated nuclear research facilities and advanced reactor developers in the United States and Canada command multi-year offtake agreements that displace spot-market transactions, anchoring value-based pricing for ultra-high-purity grades while industrial drilling operators negotiate commodity-indexed contracts.
Pricing Analysis
Yield-guaranteed pricing for semiconductor cleaning formulations anchors the premium tier, with South Korean and Japanese fabricators paying substantial markups for documented sub-ppm trace-metal certification under REACH Article 33. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade material with USP compliance from technical-grade catalyst substrates and bulk industrial drilling additives. Cost compression in the industrial tier intensifies because potassium hydroxide substitution tolerances cap volume growth, while nuclear and electronics buyers show minimal price sensitivity due to non-substitutable specification requirements.
Supply Chain Analysis
Regional distribution centers in the Netherlands and Germany manage electrodialysis-produced material qualification for specialty glass manufacturers, feeding hub-and-spoke patterns that concentrate high-purity inventory near Jena and Mainz optics clusters. Upstream pollucite extraction centers on Canada and Zimbabwe, with Jiangxi and Hunan provinces in China adding downstream processing capacity for electronic-grade chemicals. Single-source vulnerability from Bernic Lake concentrate dependence elevates geopolitical exposure, while distribution runs through specialty chemical distributors with embedded nitrogen-padding capabilities for moisture-sensitive drum formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH SVHC candidate list expansion and EPA hazardous waste reclassification have erected compliance moats that reward certified high-purity suppliers with protected margin pools inaccessible to commodity processors.
For Market Incumbents: Hedge against caustic soda substitution threats in industrial tiers by securing captive pollucite supply through backward integration into Canadian or Zimbabwean ore assets. Defend nuclear and electronics franchise value by accelerating ICP-MS quality control capacity expansion ahead of analytical chemistry talent scarcity constraints. For New Entrants and Emerging Players: Launch via direct-to-lab distribution portals targeting research institutions migrating from distributor networks, capturing compressed channel margins while building lot traceability credentials. Target India's pharmaceutical-grade segment ahead of formal BIS purity mandates, leveraging import substitution windows before domestic certification requirements harden. For Investors and Strategic Acquirers: Distressed-cycle entries favor upstream-integrated miners with captive concentrate supply in Canada during periods of pollucite price softness, as downstream purification capabilities command persistent scarcity premiums. Watch solid-state battery electrolyte research milestones at Japanese and South Korean materials institutes as the critical demand inflection signal for high-purity grade viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pollucite Processing | Captive ore supply from Bernic Lake insulates Albemarle and Power Metals from Zimbabwe geopolitical exposure. |
| Membrane Electrodialysis Capacity Buildout | German and Japanese specialty glass manufacturers qualify electrodialysis-produced material within compressed validation cycles. |
| Multi-year Offtake Agreements with Nuclear Facilities | Idaho National Laboratory and Oak Ridge National Laboratory centralize sourcing through single-supplier frameworks with embedded technical service. |
| Direct-to-Lab Distribution Portal Launch | University chemistry departments migrate from distributor networks to manufacturer-direct procurement with certificate archival. |
| REACH Article 33 Compliance Certification Investment | Electronics fabricators in the Netherlands and France demand third-party-verified contaminant data prior to contract renewal. |
Methodological Framework
Independent corroboration across specialty chemical procurement managers, ICP-MS quality control directors, and nuclear research facility supply officers underwrites the qualitative findings, validated against customs trade data, SEC 10-K filings from integrated resource holders, ECHA SVHC candidate list documentation, and MIIT electronic-grade chemical standards. Bottom-up segmentation modeling triangulates with top-down macroeconomic anchors across the analysis window.
Rate-of-change decomposition separates volume drivers by purity grade tier, end-use industry sensitivity, packaging format economics, and regional production hub concentration throughout the forecast period. CAGRs derive from segment-level growth rate blending weighted by current revenue contribution, with nuclear application R&D timelines and solid-state battery electrolyte evaluation milestones serving as industry-specific forecast inputs.
Upstream resource nationalization, REACH SVHC list expansion velocity, and solid-state battery research discontinuation are the dominant revision risks that could alter trajectory assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Chlorotoluenes Market
Bulk Chemicals
Lithium Nitrate Market
Bulk Chemicals
Precipitated Fine Hydrate Market
Bulk Chemicals
Oxalic Acid Market
Bulk Chemicals
Nickel Nitrate Hexahydrate Market
Bulk Chemicals
North America Copper Sulphate Market
Bulk Chemicals
Barite Market
Bulk Chemicals
Di-Isobutylene Market
Bulk Chemicals
Global Ferrous Sulfate Market
Bulk Chemicals
Global Ground and Precipitated Calcium Carbonate Market
Bulk Chemicals
Aluminum Chloride Hexahydrate Market
Bulk Chemicals
Calcium Carbonate Market
Bulk Chemicals
North America and Europe Palm Derivatives Market
Bulk Chemicals
Zinc Acetate Market
Bulk Chemicals
Cresylic Acid Market
Bulk Chemicals
Para Nitrophenol Market