
 Isooctyl Alcohol Market | 2026-2036
Isooctyl Alcohol Market Size, Share, and Industry Trends Forecast 2026-2036
Isooctyl Alcohol Market Foresight
Multi-sourced feedstock procurement is realigning as producers hedge against propylene price volatility. BASF SE leverages integrated oxo-alcohol complexes across European sites to sustain captive supply of high-purity isooctanol. Evonik Industries AG anchors its specialty alcohol position through controlled hydrogenation technology. ExxonMobil Chemical competes on Gulf Coast feedstock access and pipeline-linked distribution.
Isooctyl alcohol denotes a branched-chain C8 fatty alcohol produced via oxo synthesis or hydroformylation of heptene, typically exhibiting a boiling point near 183°C and serving primarily as a chemical intermediate for plasticizers, surfactants, and solvent formulations. The plasticizer application segment leads value generation due to phthalate and non-phthalate ester demand in flexible PVC compounding, while solvent applications in coatings and inks represent the fastest-growing end-use trajectory as waterborne formulations expand. Catalytic distillation technology dominates commercial production routes for isooctanol, though hydrocracking variants gain traction where refiners seek co-product flexibility from mixed olefin streams.
REACH registration requirements in Europe mandate full substance dossiers for isooctanol imports above one tonne annually, elevating compliance costs for non-EU producers. EPA Toxic Substances Control Act oversight in the United States imposes pre-manufacture notification burdens on novel isooctyl alcohol derivatives. China's MEE enforces volatile organic compound emission limits that constrain solvent-grade alcohol usage in coastal manufacturing zones. Stakeholders must weigh regulatory divergence against regional demand pull when siting new oxo-alcohol capacity or reformulating downstream product lines.
Market Dynamics
Oxo-alcohol capacity concentration in China's coastal provinces is redrawing procurement geography for downstream plasticizer manufacturers, while REACH dossier requirements in Europe elevate compliance barriers for import-dependent compounders.
Growth Catalysts
- Plasticizer demand in flexible PVC:Construction and automotive wire coating sectors in China and India consume isooctyl alcohol-derived phthalate and non-phthalate esters at accelerating rates.
- REACH registration thresholds:Full substance dossier mandates above one tonne annually create captive demand for EU-registered supply chains, favoring established oxo-alcohol producers.
- Hydroformylation efficiency gains:Cobalt-catalyzed oxo synthesis refinements are lowering unit production costs for C8 branched alcohols in integrated petrochemical complexes.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracking margins and shale-gas propylene output swings directly compress oxo-alcohol producer margins.
- Supplier concentration in East Asia:Over 60% of merchant isooctanol capacity sits in China, creating geographic supply risk for Atlantic basin buyers.
- 2-Ethylhexanol substitution:Competing C8 plasticizer alcohols with established supply chains constrain isooctyl alcohol pricing power in standard-grade applications.
Strategic Opportunities
- Waterborne coatings expansion:Solvent-grade isooctanol demand in low-VOC architectural and industrial coatings is accelerating in Germany and the Netherlands.
- India's specialty chemicals push:PLI scheme incentives for domestic chemical manufacturing are attracting oxo-alcohol investment toward Mumbai-Pune and Gujarat chemical corridors.
- Surfactant formulation innovation:Alkoxylated isooctyl alcohol derivatives for hard-surface cleaners represent an underdeveloped application segment with formulation flexibility advantages.
Industry Challenges
- Process safety certification timelines:Seveso III compliance and pressure equipment directives in Europe extend commissioning schedules for new hydrogenation units.
- Legacy esterification asset compatibility:Older plasticizer plants require reactor modifications to handle higher-purity isooctanol feedstocks without catalyst poisoning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isooctyl Alcohol Market |
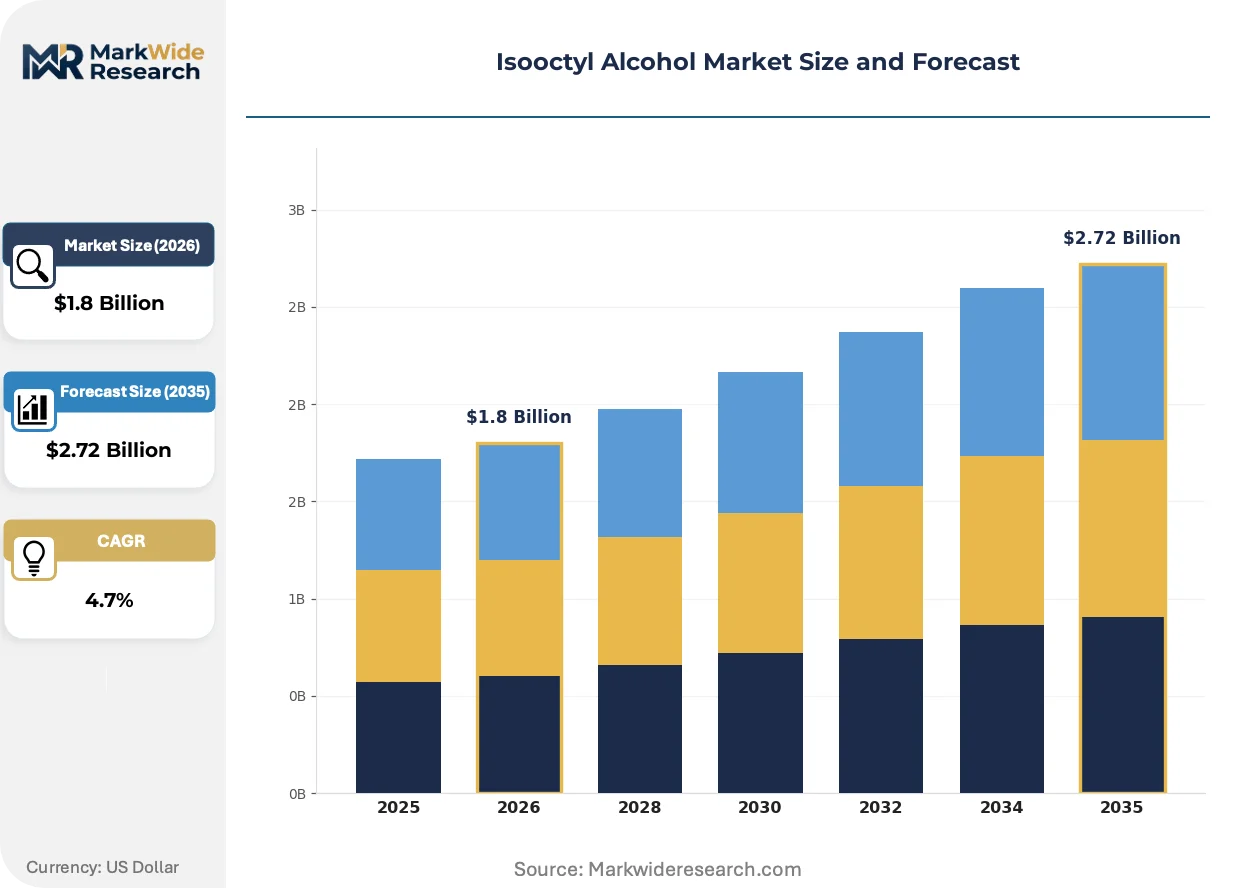
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isooctanol, Hexanol, Decanol, Ethanol End User: Cosmetics, Pharmaceuticals, Coatings, Plastics Application: Solvent, Plasticizer, Emulsifier, Fuel Additive Technology: Catalytic Distillation, Hydration, Fermentation, Hydrocracking |
| Companies Covered | BASF SE, Evonik Industries AG, ExxonMobil Chemical, OXEA GmbH, LG Chem Ltd, Perstorp Holding AB, Eastman Chemical Company, Sinopec Limited, INEOS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isooctyl Alcohol Market Shifts & Advancements
Catalytic process intensification and regulatory chemistry disclosure requirements are forcing simultaneous investment in production efficiency and supply chain transparency across the oxo-alcohol value chain.
Hydroformylation catalyst systems are converging with membrane separation technology to enable continuous isooctanol production with reduced cobalt catalyst losses. Specialty chemical producers in the Ruhr region and US Gulf Coast are piloting these integrated units. This convergence is compressing capital intensity thresholds for mid-scale oxo-alcohol entrants.
REACH substance identification and sameness protocols now require full analytical characterization of isooctanol isomer distributions in imported batches. The European Chemicals Agency's enforcement of substance identity requirements is elevating analytical costs for non-EU suppliers. German and Dutch downstream registrants are consolidating supplier bases to reduce dossier maintenance burdens.
Compounders in the coatings sector are consolidating annual isooctanol volumes into fewer, larger supply agreements with fixed-price escalators. This behavior is displacing spot-market procurement that dominated the 2015-2020 period. The shift is most visible in Benelux and northern Italy, where paint manufacturers seek supply security amid feedstock volatility.
Isooctyl Alcohol Market Segmentation
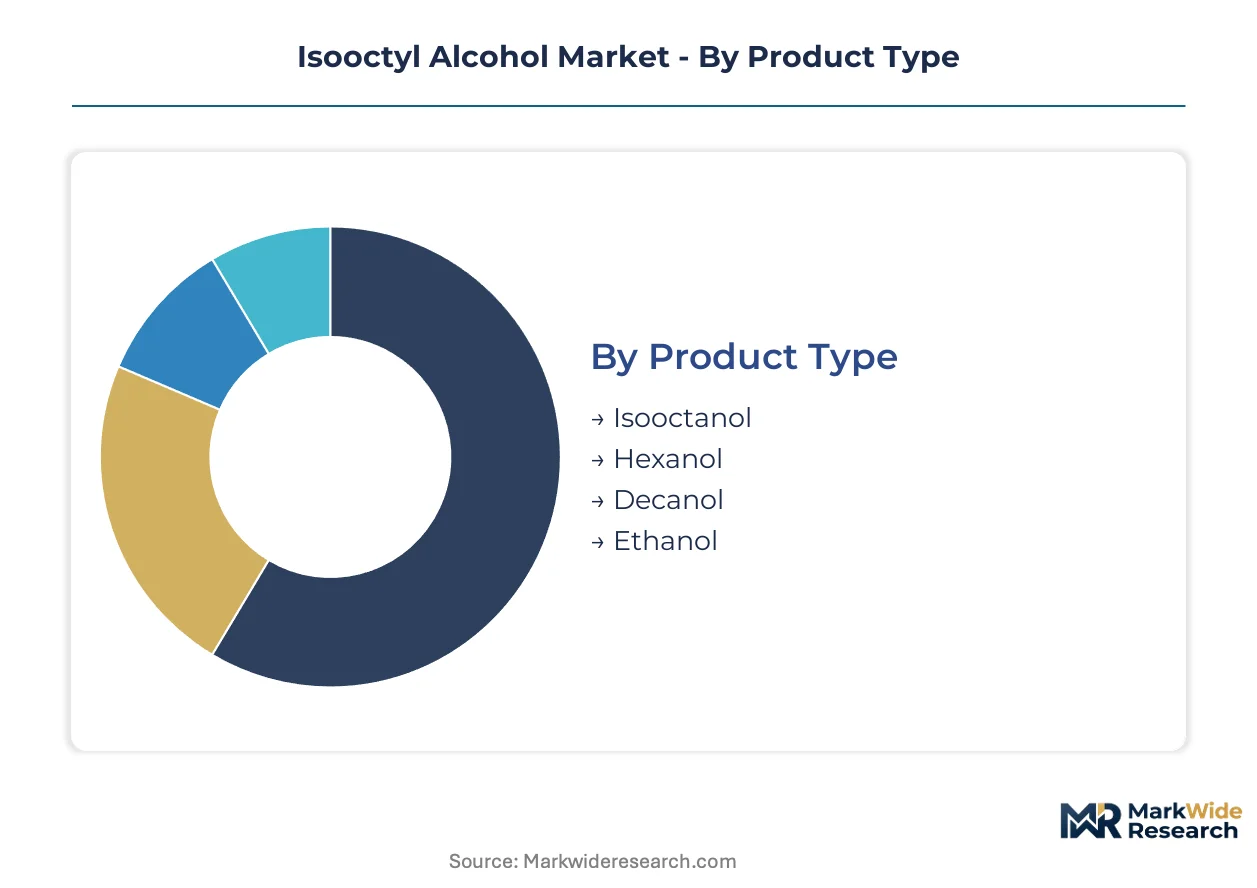
Segmentation in the isooctyl alcohol market reveals divergent margin structures across product grades and end-use applications. Manufacturers configure production assets around specific technology routes that lock in feedstock flexibility and downstream purity specifications.
Product Type:
Integration depth varies sharply across alcohol carbon chains, with C8 branched products serving as embedded intermediates while lighter fractions often reach end-users directly.
- Isooctanol:Branched-chain C8 alcohol produced via oxo synthesis of heptene, exhibiting a boiling point near 183°C and high purity requirements for plasticizer esterification. Demand concentrates in China's coastal provinces where flexible PVC compounding for construction wire coating consumes merchant volumes; REACH registration mandates above one tonne annually elevate compliance costs for non-EU supply chains.
- Hexanol:Straight-chain C6 alcohol serving solvent and extractant applications with lower purity thresholds than C8 branched variants. Procurement is shifting toward integrated petrochemical complexes in the US Gulf Coast and Rotterdam-Antwerp corridor as naphtha-cracking margins compress merchant producer economics.
- Decanol:C10 fatty alcohol for surfactant and lubricant base stock formulations, typically sourced from natural oil hydrolysis or petrochemical routes.
- Ethanol:C2 alcohol with established fermentation and ethylene hydration supply chains, rarely competing directly with higher carbon oxo-alcohols.
Isooctanol leads volumes today; hexanol is gaining share fastest as solvent applications in waterborne coatings expand.
End User:
Customer concentration patterns separate formulation-intensive sectors requiring technical service from commodity buyers prioritizing delivered cost.
- Plastics:Flexible PVC compounders represent the dominant volume sink for isooctyl alcohol-derived phthalate and non-phthalate plasticizers, with formulation specifications tightening around migration limits in automotive wire insulation.
- Coatings:Architectural and industrial paint manufacturers in Germany and the Netherlands are consolidating annual volumes into fewer supply agreements with fixed-price escalators as low-VOC regulations constrain solvent selection.
- Cosmetics:Personal care formulators demand cosmetic-grade alcohol certifications with full analytical characterization of isomer distributions.
- Pharmaceuticals:Excipient and active pharmaceutical ingredient manufacturers require GMP-compliant supply chains with documented batch consistency.
Plastics leads volumes today; coatings is gaining share fastest on waterborne formulation conversion.
Application:
Functional role in downstream formulations determines pricing power, with intermediate applications commanding technical premiums over commodity solvent uses.
- Plasticizer:Esterification with phthalic anhydride or adipic acid yields flexible PVC additives; construction and automotive wire coating sectors in China and India consume at accelerating rates.
- Solvent:Coatings and inks represent the steepest expansion trajectory as waterborne formulations displace higher-VOC alternatives in Germany and the Netherlands.
- Emulsifier:Alkoxylated derivatives for hard-surface cleaners offer formulation flexibility advantages in underdeveloped specialty segments.
- Fuel Additive:Cetane improver and lubricity agent applications compete with established petroleum-derived additives on cost-performance metrics.
Plasticizer leads volumes today; solvent is gaining share fastest.
Technology:
Process selection locks in feedstock flexibility, catalyst recovery economics, and product slate breadth for multi-alcohol producers.
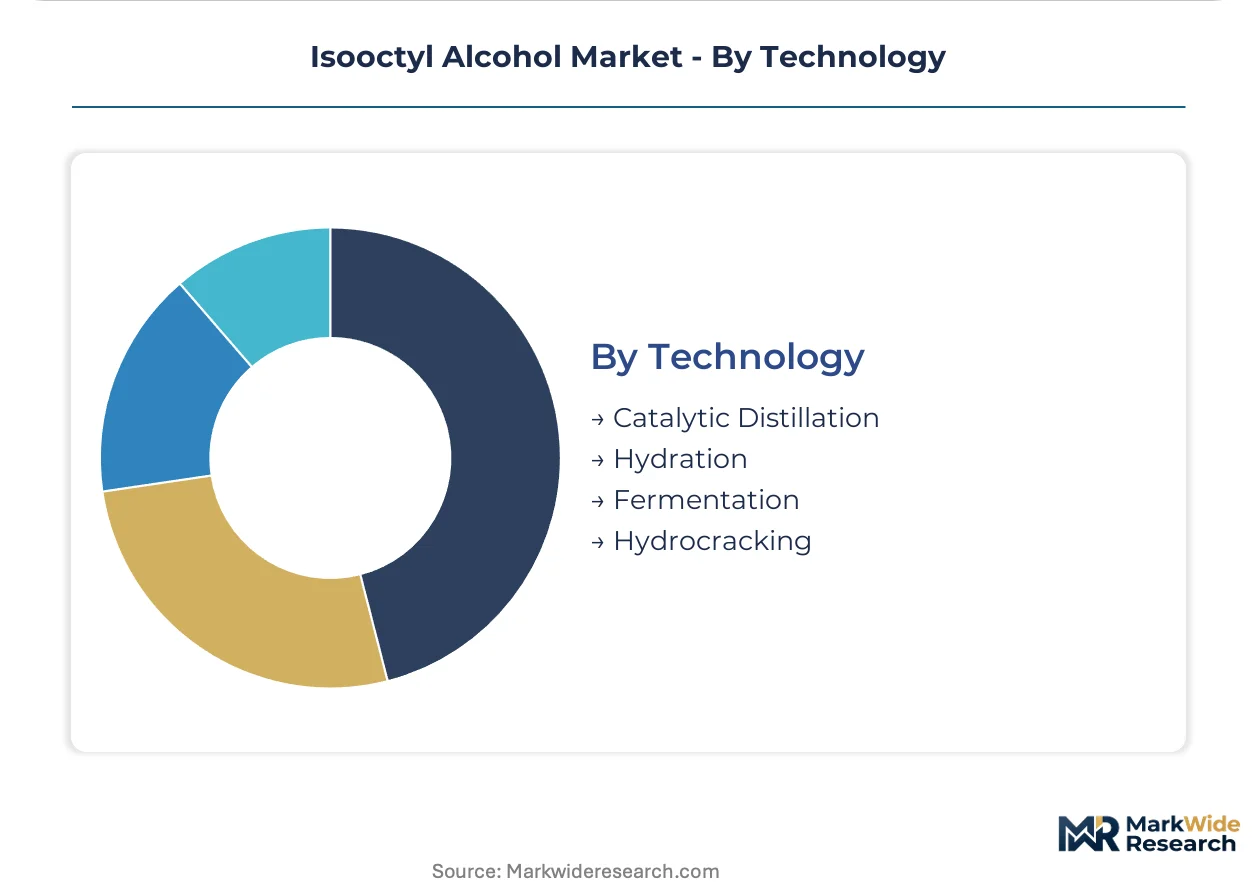
- Catalytic Distillation:Cobalt-catalyzed oxo synthesis with integrated hydrogenation dominates commercial isooctanol production, with refinements lowering unit costs in integrated petrochemical complexes.
- Hydrocracking:Mixed olefin stream processing gains traction where refiners seek co-product flexibility from FCC or steam-cracker outputs.
- Hydration:Ethylene hydration for ethanol production operates on separate economics from oxo-alcohol routes.
- Fermentation:Bio-based ethanol and higher alcohol pathways remain cost-disadvantaged against petrochemical C8 branched alcohols for plasticizer applications.
Catalytic distillation leads volumes today; hydrocracking is gaining share fastest as refiners prioritize feedstock flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping oxo-alcohol production geography as REACH compliance costs in Europe widen cost-of-compliance gaps with Asian manufacturing jurisdictions. Producers are siting new capacity where environmental enforcement remains less stringent while maintaining EU-registered supply chains for registered tonnage.
China
Flexible PVC compounding for construction wire coating and automotive harnesses absorbs the majority of merchant isooctanol volumes. MEE volatile organic compound emission limits constrain solvent-grade alcohol usage in coastal manufacturing zones. Yangtze River Delta chemical clusters around Shanghai and Ningbo host integrated oxo-alcohol complexes serving domestic coatings and adhesives sectors.
Germany
Waterborne coatings conversion in architectural and industrial paint formulations is accelerating solvent-grade isooctanol demand. ECHA REACH substance identification protocols require full analytical characterization of isooctanol isomer distributions in imported batches. Ruhr region specialty chemical producers pilot membrane-integrated hydroformylation units to reduce cobalt catalyst losses.
United States
Gulf Coast feedstock access and pipeline-linked distribution networks sustain competitive positioning for oxo-alcohol producers. EPA Toxic Substances Control Act oversight imposes pre-manufacture notification burdens on novel isooctyl alcohol derivatives. Texas and Louisiana petrochemical corridors concentrate catalytic distillation capacity serving domestic plasticizer compounders.
India
Construction and automotive wire coating sectors consume phthalate and non-phthalate plasticizer esters at accelerating rates. PLI scheme incentives for domestic chemical manufacturing attract oxo-alcohol investment toward Mumbai-Pune and Gujarat chemical corridors. Dahej and Mundra port zones emerge as preferred sites for import substitution capacity.
Netherlands
Paint manufacturers in Benelux consolidate annual isooctanol volumes into fewer supply agreements with fixed-price escalators. EU Green Deal carbon border adjustment mechanisms elevate cost scrutiny for imported alcohol batches. Rotterdam-Antwerp corridor refiners evaluate hydrocracking flexibility for mixed olefin stream processing.
Isooctyl Alcohol Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty-grade positioning through certification arbitrage. The vendor base separates into three functional tiers: integrated petrochemical majors with captive olefin feedstock, merchant alcohol specialists with hydrogenation technology control, and regional compounders with backward integration into esterification. Consolidation pressure concentrates among mid-scale European registrants facing dossier maintenance cost escalation. Capacity expansion and strategic partnerships dominate competitive moves as firms secure registered supply chains.
Among German-integrated chemical majors, BASF SE and Evonik Industries AG exemplify archetypes of captive supply chain control and specialty alcohol positioning respectively. ExxonMobil Chemical occupies a position among Gulf Coast feedstock-advantaged producers. These three entities anchor the competitive structure without exhausting its diversity.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| ExxonMobil Chemical |
| OXEA GmbH |
| LG Chem Ltd |
| Perstorp Holding AB |
| Eastman Chemical Company |
| Sinopec Limited |
| INEOS |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap hydrogenation specialists in Europe anchor pricing discipline through REACH-registered supply chains that command technical premiums over Asian merchant volumes. Their ownership structure enables patient capital allocation toward dossier maintenance and cobalt catalyst recovery systems that integrated majors often underinvest in.
Pricing Analysis
Distributor margin layering separates plasticizer compounders in China's Yangtze Delta from spot-market buyers in Southeast Asia. Three-tier pricing structure across REACH-registered, technical-grade, and solvent-economy levels reflects certification burden and isomer purity. Pricing pressure stems from 2-ethylhexanol substitution in standard PVC applications. Volume-contracted automotive wire coaters exhibit lowest price sensitivity; spot-buying coatings formulators face acute cost compression.
Supply Chain Analysis
REACH substance identification protocols gate EU market access for non-registered Asian producers, forcing analytical characterization investments before shipment. Supply concentrates in China, Germany, and the United States, with over sixty percent of merchant capacity anchored in coastal Chinese provinces. Raw material flows draw from propylene via naphtha cracking or shale gas, with cobalt catalyst and hydrogen feedstocks sourced from integrated petrochemical complexes. Single-source vulnerability runs through Yangtze River Delta port congestion. Distribution runs through pipeline-linked integrated complexes and bulk tanker networks serving downstream compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The isooctyl alcohol market compounds steadily as construction wire coating and automotive harness demand in Asia-Pacific industrial hubs sustains volume growth. Regulatory chemistry disclosure requirements in Europe create durable competitive moats for registered suppliers.
For Market Incumbents: Cement REACH registration maintenance as the priority defensive lever against emerging Indian producers leveraging PLI scheme incentives. Deepen backward integration into propylene feedstock through pipeline-linked Gulf Coast or Rotterdam-Antwerp corridor positions. Counter 2-ethylhexanol substitution threat by expanding high-purity grades for migration-sensitive automotive specifications. For New Entrants and Emerging Players: Specialty coatings distributors in Germany and the Netherlands offer the most penetrable channel anchor for solvent-grade volumes displaced by waterborne formulation conversion. Target alkoxylated derivative white space in hard-surface cleaner formulations where formulation flexibility advantages remain underexploited. Pursue toll-manufacturing arrangements with idled European hydrogenation assets to bypass Seveso III compliance timelines. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale European registrants facing dossier maintenance cost escalation without captive olefin supply. Long-term viability favors integrated petrochemical majors with backward control over C7 olefin feedstock and hydrogenation technology. Watch cobalt catalyst recovery efficiency gains as the inflection signal for margin expansion in membrane-integrated hydroformylation units.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene | Pipeline-linked Gulf Coast access insulates BASF and ExxonMobil from naphtha-cracking margin volatility. |
| REACH Dossier Consolidation | German and Dutch downstream registrants reduce supplier bases to cut ECHA sameness protocol compliance burdens. |
| Membrane-Integrated Hydroformylation | Ruhr region pilots compress capital intensity thresholds for mid-scale oxo-alcohol entrants via continuous production. |
| Long-term Supply Agreement Structuring | Benelux paint manufacturers lock in fixed-price escalators to secure volumes amid feedstock volatility. |
| Specialty Alcohol Certification Arbitrage | Cosmetic-grade and GMP-compliant positioning commands technical premiums over standard plasticizer grades. |
Research Methodology
Direct dialogue with oxo-alcohol plant managers, procurement leads at downstream PVC compounders, distribution channel partners, and ECHA regulatory affairs specialists grounded qualitative findings. Secondary validation drew from customs and trade flow databases, Cefic sector reports, SEC 10-K chemical segment disclosures, and REACH registration dossiers. Bottom-up volume builds across plasticizer, solvent, and surfactant applications triangulated against top-down petrochemical capacity assessments.
Segment-level projections across product grade tiers, end-use industries, and regional production hubs fed into the analytical framework over the projection horizon. CAGRs derived from elasticity-adjusted demand modeling incorporating construction wire coating intensity, automotive harness specifications, and waterborne coatings conversion rates. Cobalt catalyst efficiency trends and propylene feedstock cost trajectories served as key sensitivity inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH authorization list amendments, MEE emission limit tightening in Chinese coastal zones, and shale-gas propylene output swings. Forecasts reflect documented assumptions around oxo-alcohol capacity commissioning schedules and downstream formulation substitution elasticities. A model refresh is warranted upon material change in ECHA substance identification enforcement intensity or PLI scheme incentive structures in India.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Ethylenediaminetetraacetic Acid Market
Chemicals
Lanthanum Nitrate Market
Chemicals
Global Amines Market
Chemicals
Methyl Ethyl Ketone Peroxide (MEKP) Market
Chemicals
1,3-Dibromoadamantane Market
Chemicals
Global Methylene Chloride Market
Chemicals
1-Methylimidazole Market
Chemicals
Welding Chemicals Market
Chemicals
Allyl Chloride Market
Chemicals
Sodium Cyanide Market
Chemicals
Benzoyl Alcohol Market
Chemicals
Scouring Agents Market
Chemicals
3,5-Dinitroaniline Market
Chemicals
Hydrophobing Agents Market
Chemicals
Spirodiclofen Market
Chemicals
Carcinogenic Chemical Alternatives Market