
 Phosphate Chemical Reagents Market | 2026-2036
Phosphate Chemical Reagents Market Size, Share, and Industry Trends Forecast 2026-2036
Phosphate Chemical Reagents Market Analytics
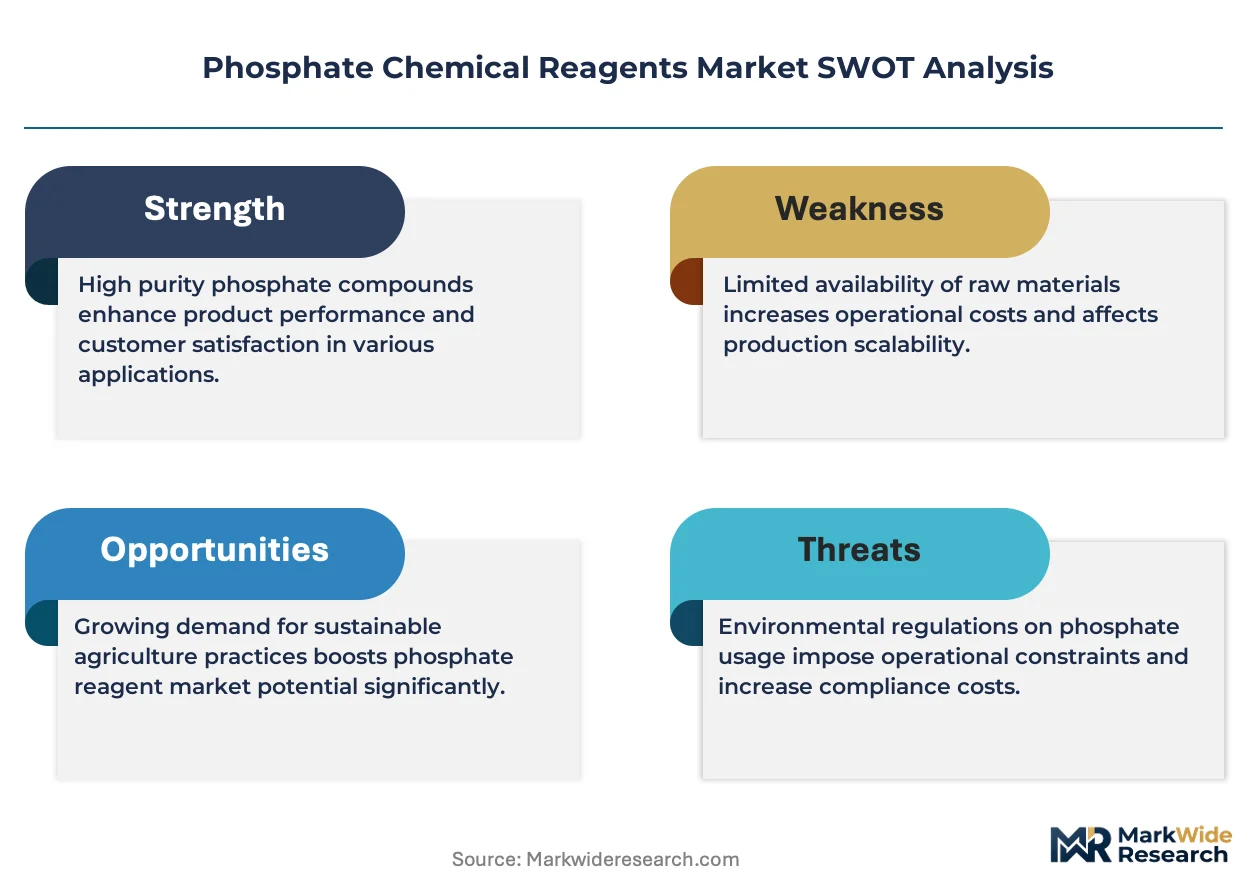
Project finance for greenfield phosphate purification facilities is narrowing the competitive field to players with balance-sheet depth or sovereign-backed credit lines. Solvay SA leverages its integrated phosphorus derivatives platform across European and North American production sites. Innophos Holdings Inc. anchors its position through specialty phosphate blends for food and pharmaceutical grade applications. Merck KGaA differentiates via stringent quality certifications that command premium positioning in life-science channels.
Phosphate chemical reagents comprise purified inorganic phosphate salts and derivatives manufactured through wet-process acid purification or thermal reduction routes, with specifications typically requiring 85-99% purity depending on end-use. These compounds function primarily as buffering agents, nutrient sources, precipitating agents, and chemical intermediates across industrial and laboratory settings. Sodium phosphate variants lead volume demand in water treatment and food processing applications where pH stabilization drives recurring consumption. Calcium phosphate grades command margin concentration in pharmaceutical excipients and biomedical applications due to biocompatibility requirements and regulatory filing burdens. Potassium phosphate forms represent the fastest-growing product class in hydroponic agriculture and specialized fertilizer formulations.
EPA phosphorus discharge standards under the Clean Water Act shape product formulation requirements for water treatment reagents in the United States. REACH registration obligations and the EU F-Gas Regulation indirectly influence phosphate fluorine derivative processing economics across European manufacturing. China's MEE enforces dual carbon goals that constrain energy-intensive thermal phosphate production in key industrial provinces. Stakeholders must monitor evolving fertilizer efficiency mandates and laboratory reagent purity standards as regulatory fragmentation intensifies between agricultural and life-science application channels.
Market Dynamics
Phosphate rock reserve concentration in China, Morocco, and Russia is concentrating upstream supply power among sovereign-controlled mining complexes, forcing downstream reagent manufacturers to secure long-term offtake agreements or accept feedstock price volatility.
Growth Catalysts
- REACH registration tiering:ECHA's differentiated registration deadlines for low-volume phosphate derivatives are accelerating specialty-grade capacity investments in European manufacturing clusters.
- Precision agriculture expansion:Variable-rate fertilizer application systems are driving demand for high-purity potassium phosphate forms in controlled-release formulations across North American and European farming operations.
- Wet-process acid purification:Advanced solvent extraction technologies are enabling food-grade phosphate production from lower-quality rock reserves, expanding addressable ore sources.
Market Restraints
- Phosphate rock supply concentration:OCP Group in Morocco and Chinese state-owned mining entities control over 70% of exportable phosphate rock, creating geopolitical supply risk for non-integrated reagent producers.
- Energy cost volatility:Thermal reduction routes for elemental phosphorus production remain exposed to natural gas price swings, compressing margins for European and North American thermal process operators.
- Fluorine derivative regulatory friction:EU F-Gas Regulation and EPA fluorine emission standards are constraining capacity expansion for phosphate fluorine coproduct streams.
Strategic Opportunities
- Brazilian agricultural demand:ANVISA's streamlined fertilizer registration pathways and expanding soy cultivation are creating import substitution opportunities for purified phosphate reagent suppliers.
- Biomedical-grade calcium phosphates:ISO 10993 biocompatibility certification requirements for synthetic bone graft materials are opening premium positioning for GMP-certified manufacturers.
- Water treatment reagent bundling:Municipal procurement consolidation is favoring integrated chemical service providers capable of delivering phosphate-based precipitants alongside coagulant portfolios.
Industry Challenges
- Analytical chemist scarcity:ICP-MS and ion chromatography expertise required for ultra-high-purity phosphate certification is concentrated among aging technical workforces in Western Europe and Japan.
- Multi-jurisdictional filing complexity:Food-grade phosphate approvals require parallel FSSAI, FDA, and EFSA submissions with divergent purity specification thresholds, extending commercialization timelines.
- Legacy thermal asset stranding:China's MEE carbon intensity mandates are forcing capacity retirements at coal-fired elemental phosphorus furnaces without clear replacement technology economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phosphate Chemical Reagents Market |
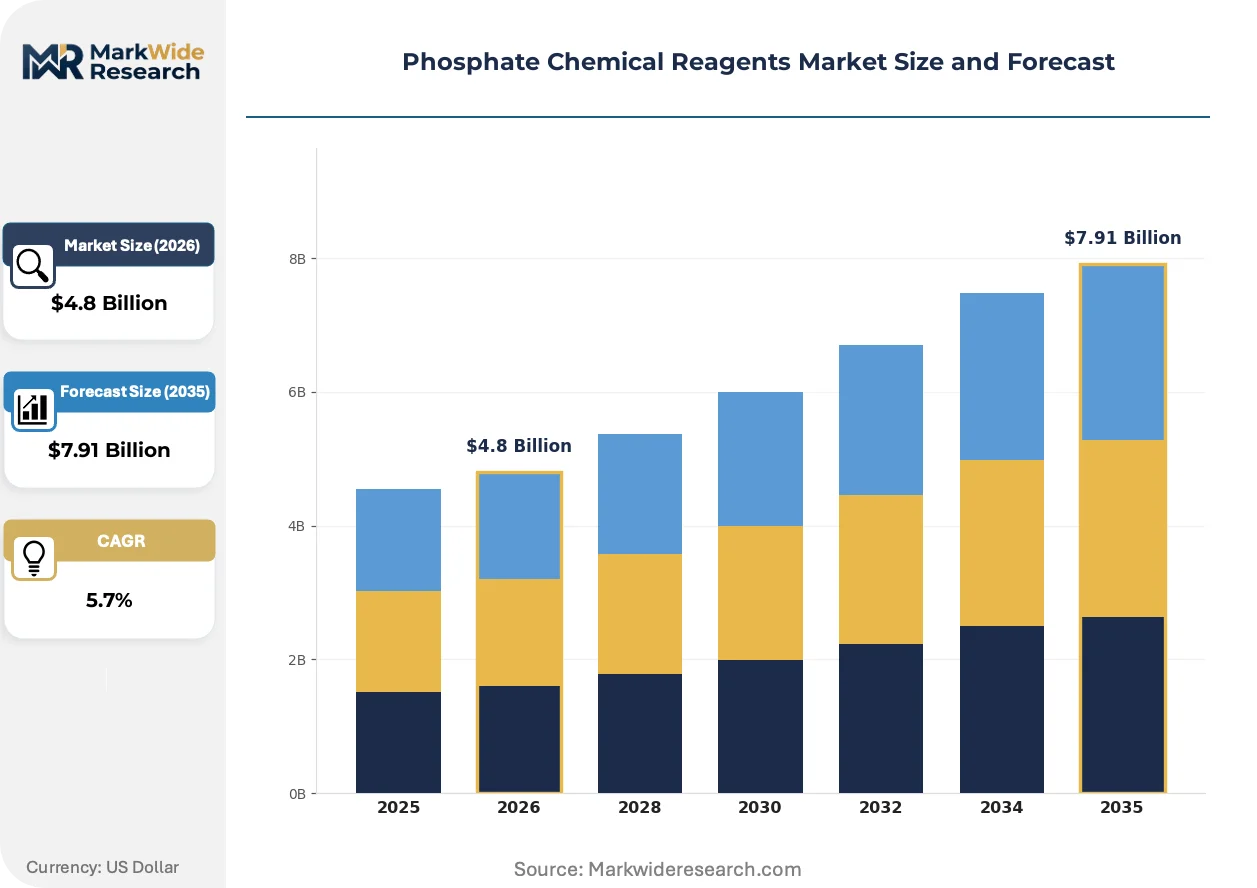
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Phosphate, Potassium Phosphate, Ammonium Phosphate, Calcium Phosphate Application: Fertilizers, Food Additives, Pharmaceuticals, Water Treatment End User: Agriculture, Food Industry, Chemical Manufacturing, Healthcare Delivery Mode: Bulk Supply, Packaged Supply, Online Retail, Direct Sales |
| Companies Covered | Alfa Aesar, Thermo Fisher Scientific, Solvay SA, AAT Bioquest, Inc., Avantor Inc., Innophos Holdings Inc., Tintometer GmbH, HiMedia Laboratories, Merck KGaA, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phosphate Chemical Reagents Market Evolving Landscape
Wet-process purification advances and regulatory chemistry mandates are compressing traditional thermal process economics while opening specialty-grade opportunities for integrated manufacturers with quality certification depth.
Membrane-based selective electrodialysis is collapsing the cost gap between wet-process and thermal-route food-grade phosphate production. European and North American specialty chemical producers are retrofitting existing acid plants with electrodialysis stacks to capture pharmaceutical-grade margins without greenfield thermal investments. This technology is collapsing the historical purity premium that thermal reduction routes commanded in life-science applications.
EPA phosphorus discharge standards under the Clean Water Act are tightening total maximum daily load allocations for municipal wastewater treatment facilities. Nutrient removal mandates are expanding precipitating agent consumption volumes while favoring ferric and aluminum phosphate co-precipitation chemistries over biological phosphorus removal in cold-climate installations. Water treatment operators in the Great Lakes and Chesapeake Bay watersheds are responding with dual-chemical feed systems optimized for seasonal temperature variation.
Consolidated procurement by multi-national fertilizer distributors is compressing spot-market volumes and lengthening contract durations for phosphate reagent suppliers. Bayer CropScience and Nutrien are centralizing global phosphate additive purchasing through Singapore and Switzerland trading desks, displacing regional distributor networks in Southeast Asian and Latin American markets. This concentration is most visible in Indonesian and Vietnamese hydroponic nutrient markets where direct manufacturer relationships are replacing layered distribution.
Phosphate Chemical Reagents Market Segmentation
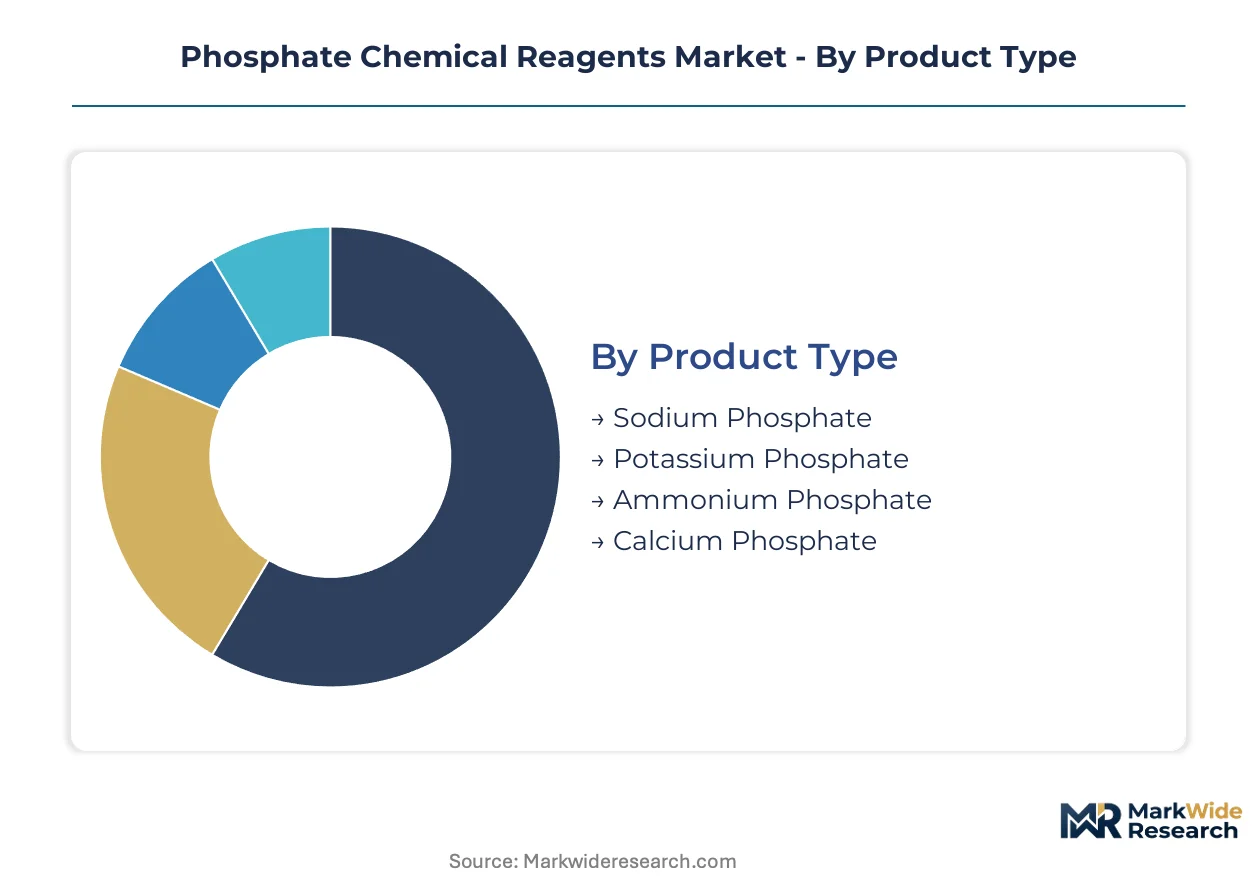
Phosphate chemical reagents fragment across purity grades and delivery formats that command radically different margin structures. Segmentation discipline separates commodity buffer salts from certified life-science grades where regulatory filing burdens create pricing power.
Product Type:
Inventory velocity varies dramatically across phosphate salt categories, with fertilizer-grade bulk salts turning monthly while pharmaceutical-grade calcium phosphates sit in validation queues for quarters.
- Sodium Phosphate:Comprises mono-, di-, and tribasic sodium salts manufactured through wet-process acid neutralization, typically specified at 85-98% purity depending on food-grade or technical-grade designation. Municipal water treatment plants in the United States consume massive volumes for pH buffering and boiler water conditioning, with EPA discharge standards driving recurring precipitation chemistry demand.
- Potassium Phosphate:Exists as monobasic and dibasic forms with hygroscopic properties requiring moisture-controlled packaging for hydroponic nutrient applications. Controlled-release fertilizer formulators in the Netherlands and Spain specify high-purity grades for precision agriculture systems where nutrient dosing accuracy directly impacts crop yield metrics.
- Ammonium Phosphate:Dual-nutrient compound serving as both nitrogen and phosphorus source in compound fertilizer manufacturing.
- Calcium Phosphate:Biocompatible ceramic precursor for synthetic bone grafts and dental cements requiring ISO 10993 certification.
Sodium phosphate dominates installed base tonnage. Potassium phosphate is where expansion concentrates.
Application:
Margin architecture separates agricultural commodities from certified life-science grades where regulatory filing costs create barrier-to-entry premiums.
- Fertilizers:Compound fertilizer and straight fertilizer applications consuming technical-grade phosphates with tolerance for minor metal contaminants. Brazilian soy cultivation and Indonesian palm oil estates drive import demand for bulk ammonium phosphate and potassium phosphate blends, with ANVISA registration pathways streamlining market access for purified reagent suppliers.
- Food Additives:pH buffering agents, emulsifiers, and leavening acids subject to FSSAI, FDA, and EFSA parallel approval requirements with divergent purity thresholds. Bakery and processed meat manufacturers in Germany and Italy specify food-grade sodium phosphates where EFSA additive re-evaluations periodically restrict acceptable daily intake levels.
- Pharmaceuticals:Excipient and active pharmaceutical ingredient applications demanding USP-NF or EP monograph compliance.
- Water Treatment:Precipitating agents for phosphorus removal in municipal wastewater facilities.
Fertilizers anchor volume demand. Food additives command the steepest certification premiums.
End User:
Procurement sophistication varies from spot-market agricultural purchasing to multi-year pharmaceutical supply agreements with audit rights.
- Agriculture:Fertilizer manufacturers and large-scale farming operations purchasing technical-grade phosphates through consolidated distributor networks. Bayer CropScience and Nutrien centralize global phosphate additive procurement through Singapore trading desks, displacing regional distributors in Southeast Asian hydroponic markets.
- Food Industry:Processed food manufacturers and beverage companies requiring batch-certified food-grade phosphates with full traceability documentation.
- Chemical Manufacturing:Industrial phosphate derivative producers and specialty chemical formulators.
- Healthcare:Pharmaceutical companies and medical device manufacturers specifying GMP-certified calcium phosphates for implantable applications.
Agriculture generates the highest absolute tonnage. Healthcare delivers the most attractive unit economics.
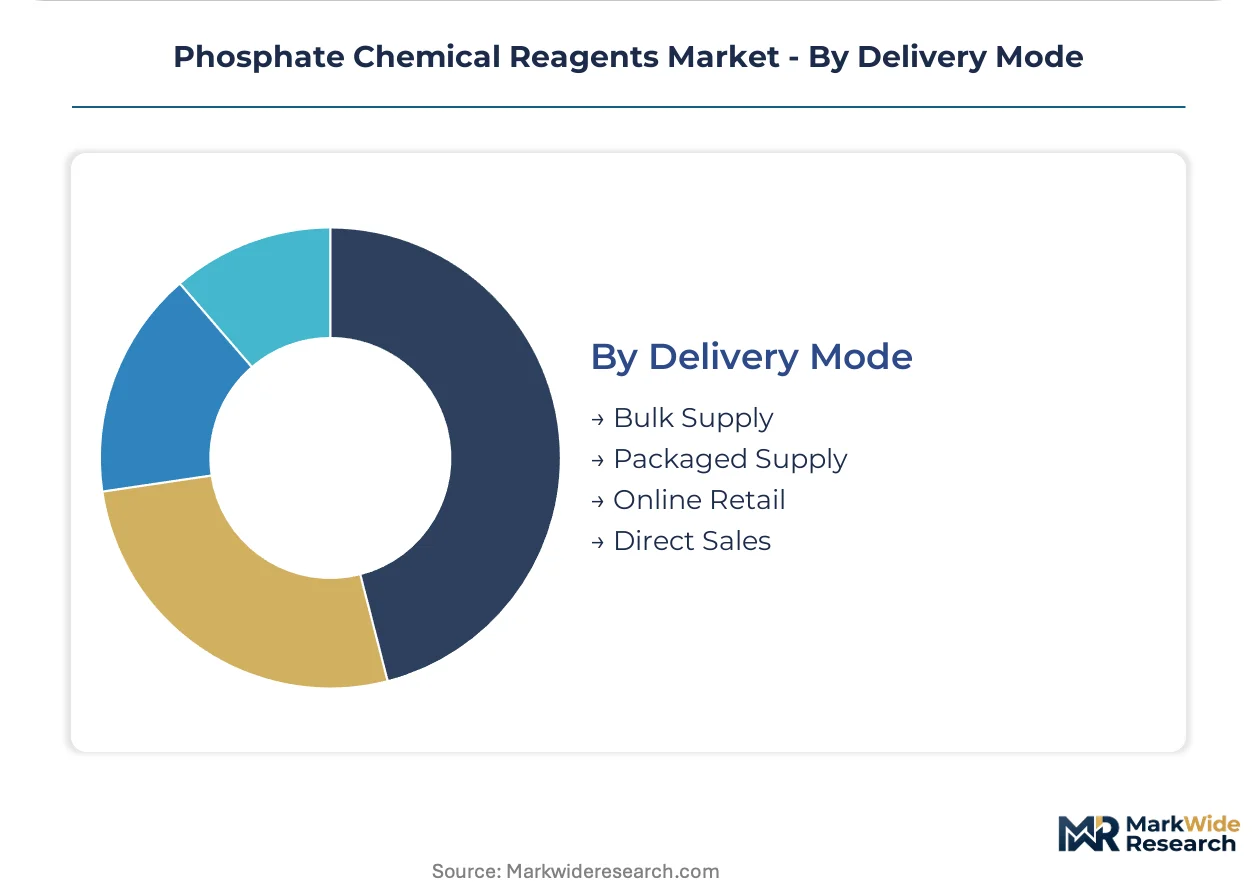
Delivery Mode:
Logistics configuration directly determines working capital intensity and customer intimacy depth across the value chain.
- Bulk Supply:Railcar and vessel deliveries of unbagged phosphate salts to integrated fertilizer producers and large water treatment facilities. OCP Group in Morocco and Chinese state-owned mining entities leverage captive port infrastructure for exportable phosphate rock and downstream reagent distribution.
- Packaged Supply:25-50 kg bags and supersacks for mid-scale food processors and regional chemical distributors.
- Online Retail:Laboratory-scale containers and reagent-grade quantities for research institutions and small manufacturers.
- Direct Sales:Manufacturer-to-customer relationships for pharmaceutical and biomedical-grade certified phosphates with dedicated technical service support.
Bulk supply moves the greatest mass. Direct sales captures the highest margin per kilogram.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in phosphate chemical reagents tilts heavily toward Chinese state-controlled mining complexes, while European and North American manufacturers absorb feedstock volatility through long-term offtake premiums. This asymmetry reshapes regional competitive positioning and investment priorities across the value chain.
China
Yunnan and Guizhou provinces host thermal reduction furnaces producing elemental phosphorus for high-purity derivatives. MEE dual carbon goals are forcing capacity retirements at coal-fired installations in these industrial heartlands. Manufacturers in the Yangtze River Delta are retrofitting wet-process acid plants with electrodialysis stacks to capture pharmaceutical-grade margins without thermal investments.
United States
Florida's phosphate mining belt supplies feedstock to Gulf Coast purification facilities serving water treatment and food additive channels. EPA phosphorus discharge standards under the Clean Water Act tighten total maximum daily load allocations for municipal wastewater facilities in the Great Lakes and Chesapeake Bay watersheds. Texas and Louisiana chemical corridors concentrate ferric and aluminum phosphate co-precipitation reagent production for cold-climate nutrient removal.
Germany
Rhine-Ruhr industrial clusters integrate phosphate derivative production with specialty chemical manufacturing for life-science applications. ECHA REACH registration tiering accelerates specialty-grade capacity investments in European manufacturing hubs. Bavarian chemical parks host GMP-certified calcium phosphate operations targeting ISO 10993 biocompatibility certification for synthetic bone graft materials.
Brazil
São Paulo and Mato Grosso soy cultivation drives import demand for potassium phosphate blends in controlled-release fertilizer formulations. ANVISA streamlined fertilizer registration pathways reduce commercialization timelines for purified reagent suppliers. Port infrastructure in Santos and Paranaguá handles bulk ammonium phosphate deliveries displacing regional distributor networks with direct manufacturer relationships.
Morocco
OCP Group's Khouribga and Gantour mining complexes control exportable phosphate rock reserves supplying European and Asian reagent manufacturers. Casablanca-Jorf Lasfar industrial zone concentrates downstream phosphoric acid and purified salt production. Sovereign-controlled vertical integration enables captive supply of technical-grade phosphates to fertilizer compounders across West African markets.
Phosphate Chemical Reagents Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with certification depth as their primary defense. The vendor base organizes around three archetypes: integrated mining-to-derivatives conglomerates with sovereign backing, specialty chemical houses with quality certification platforms, and laboratory reagent distributors with geographic density. Consolidated procurement by multinational fertilizer distributors and pharmaceutical manufacturers compresses spot-market volumes while lengthening contract durations. Competitive moves concentrate on backward integration into phosphate rock offtake and electrodialysis technology licensing to collapse wet-process purity premiums.
Within the quality-certification tier, Merck KGaA and Solvay SA exemplify European manufacturers leveraging stringent quality certifications for premium positioning in life-science channels. Innophos Holdings Inc. anchors North American specialty phosphate production through food and pharmaceutical grade applications. These three entities represent the dominant pattern of mid-cap specialists defending margin position through regulatory filing depth rather than scale economies.
| Leading Market Players |
|---|
| Alfa Aesar, Thermo Fisher Scientific |
| Solvay SA |
| AAT Bioquest, Inc. |
| Avantor Inc. |
| Innophos Holdings Inc. |
| Tintometer GmbH |
| HiMedia Laboratories |
| Merck KGaA |
| Honeywell International Inc. |
| Others |
Value Network & Pricing Analysis
Phosphate rock supply concentration in Morocco and China determines both the spread between technical-grade and pharmaceutical-grade pricing tiers and the geographic shape of downstream distribution networks. Sovereign-controlled mining complexes capture upstream rent, forcing non-integrated reagent manufacturers to absorb feedstock volatility through long-term offtake premiums or accept margin compression.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing across bulk fertilizer-grade phosphates, while life-science channels command premium-mid-economy pricing differentiation based on USP-NF certification depth and ISO 10993 biocompatibility status. Cost compression in technical-grade sodium phosphates is intensifying because wet-process electrodialysis investments are collapsing historical purity premiums. Agricultural compounders exhibit highest price sensitivity due to consolidated procurement through Singapore trading desks, whereas pharmaceutical excipient buyers prioritize audit-ready documentation over unit cost.
Supply Chain Analysis
Export-control restrictions on advanced electrodialysis membrane technology limit capacity expansion outside established manufacturing clusters, constraining supply growth for pharmaceutical-grade derivatives. Production gravity centers on China, Morocco, and Russia for phosphate rock extraction, with wet-process acid purification drawing from sulfuric acid and energy inputs. Single-source vulnerability runs through OCP Group's Khouribga mining complex, which feeds European thermal reduction furnaces. Distribution runs through sovereign-controlled port infrastructure at Jorf Lasfar and Yangtze River Delta chemical parks, with packaged supply displacing bulk in hydroponic nutrient channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Phosphate chemical reagents function as a regulatory entrenchment market where REACH registration depth and FDA master file status create switching-cost moats that protect incumbent positioning against commodity substitution.
For Market Incumbents: Pre-empt capacity stranding by retrofitting wet-process acid plants with electrodialysis stacks before China's MEE carbon mandates force thermal furnace retirements. Secure backward integration into Moroccan or Russian phosphate rock offtake to neutralize feedstock volatility that erodes margin in European manufacturing. Certification investment in ISO 10993 biocompatibility pathways defends premium positioning against emerging electrodialysis-enabled competitors. For New Entrants and Emerging Players: Build out Brazilian potassium phosphate formulation capacity to capture ANVISA-streamlined registration benefits in soy cultivation regions. Target hydroponic nutrient direct-sales relationships in Indonesia and Vietnam where Bayer CropScience and Nutrien procurement consolidation has displaced regional distributors. White-space exists in GMP-certified calcium phosphate production for synthetic bone graft applications where aging analytical workforces in Western Europe constrain incumbent expansion. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors wet-process purification specialists with electrodialysis licensing access over legacy thermal operators facing carbon-intensity mandates. Long-term viability hinges on quality-certification platform depth rather than scale economies, making mid-cap European and North American specialty phosphate houses attractive acquisition targets. Watch for MEE enforcement actions in Yunnan and Guizhou provinces as inflection indicators for thermal capacity retirement timelines and feedstock price spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Electrodialysis Technology Licensing | Enables food-grade phosphate production from lower-quality rock reserves without thermal investment. |
| Backward Integration into Phosphate Rock | Neutralizes OCP Group and Chinese state-owned mining entity pricing power for non-integrated producers. |
| ISO 10993 Biocompatibility Certification | Opens premium positioning in synthetic bone graft materials where regulatory filing burdens limit competition. |
| Direct Sales Channel Development | Captures margin from Bayer CropScience and Nutrien procurement consolidation in Southeast Asian hydroponic markets. |
| Long-term Supply Agreement with Municipal Water Treatment | Locks in recurring precipitating agent demand under EPA Clean Water Act phosphorus discharge standards. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across phosphate reagent manufacturing, with primary interviews conducted among plant managers at wet-process and thermal facilities, procurement leads at fertilizer compounders and pharmaceutical excipient buyers, distribution channel partners in European chemical parks, and technical R&D directors developing electrodialysis purification. Secondary validation drew from customs and trade data, SEC filings of listed specialty chemical producers, ECHA REACH registration databases, and EPA discharge standard enforcement records. Bottom-up capacity and consumption estimates were triangulated against top-down macroeconomic drivers.
Calibration of volume and value outputs employed analytical framework segmentation across purity grade tiers, end-use industries spanning agriculture to life-science applications, packaging formats from bulk railcar to laboratory-scale containers, and regional production hubs in China, Morocco, and the United States. CAGRs were derived from modeled demand elasticity against fertilizer efficiency mandates and laboratory reagent purity standards. Industry-specific forecast inputs included MEE carbon intensity enforcement timelines and ANVISA registration pathway throughput rates.
Stress conditions across phosphate rock export restrictions, natural gas price volatility for thermal reduction economics, and electrodialysis membrane supply constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology diffusion rates. Material shifts in China's dual carbon goal implementation pace or OCP Group production quota decisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Triisobutyl Phosphate Market
Chemical Intermediates
9-Decanoic Acid Methyl Ester Market
Chemical Intermediates
Hydroxyisobutyric Acid Market
Chemical Intermediates
Tetrahydrocurcumin Reagent Market
Chemical Intermediates
Grignard Reagents Market
Chemical Intermediates
Ethylene Diamine Tetra Acetic Acid (EDTA) Market
Chemical Intermediates
Montelukast Intermediate Market
Chemical Intermediates
Myristoyl Chloride Market
Chemical Intermediates
Nickel Acetate Market
Chemical Intermediates
Iodoacetonitrile Market
Chemical Intermediates
Glycidyl Methacrylate Market
Chemical Intermediates
Refinery Process Chemicals Market
Chemical Intermediates
Global Aniline Derivative Market
Chemical Intermediates
Isosafrole Market
Chemical Intermediates
Global Glycinates Market
Chemical Intermediates
Reagent Bottle Market